Latest from BCA Research
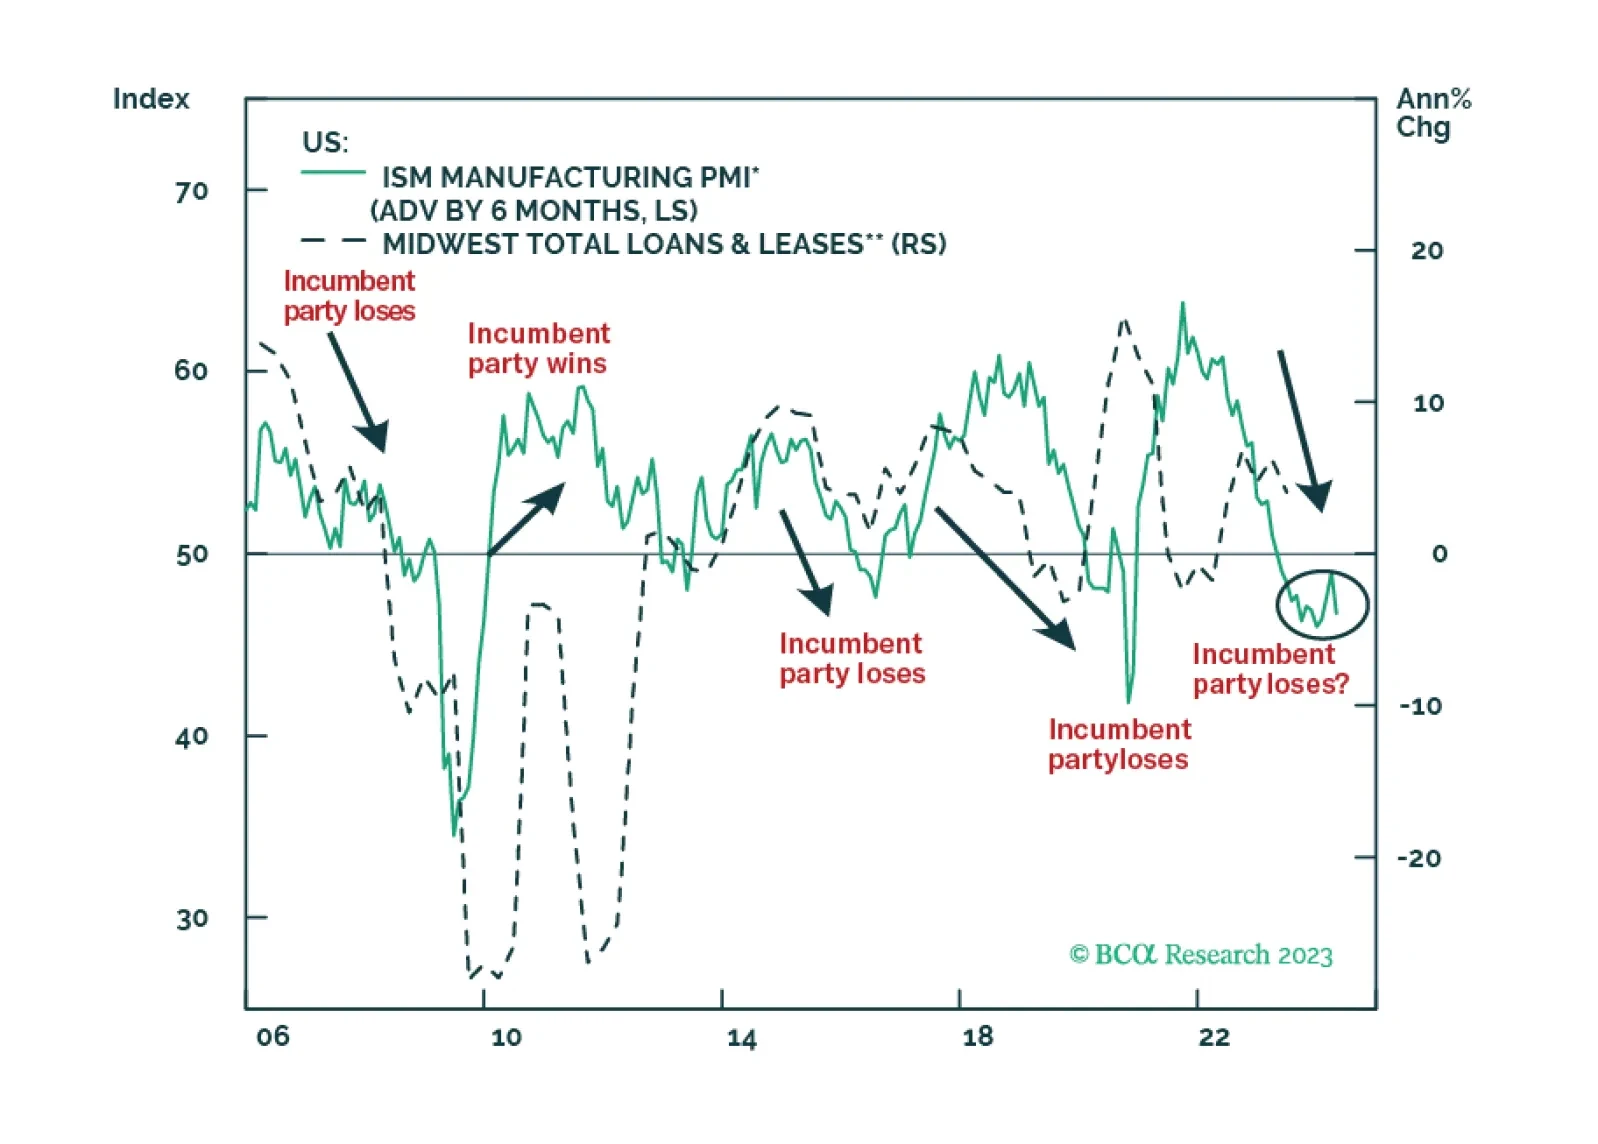
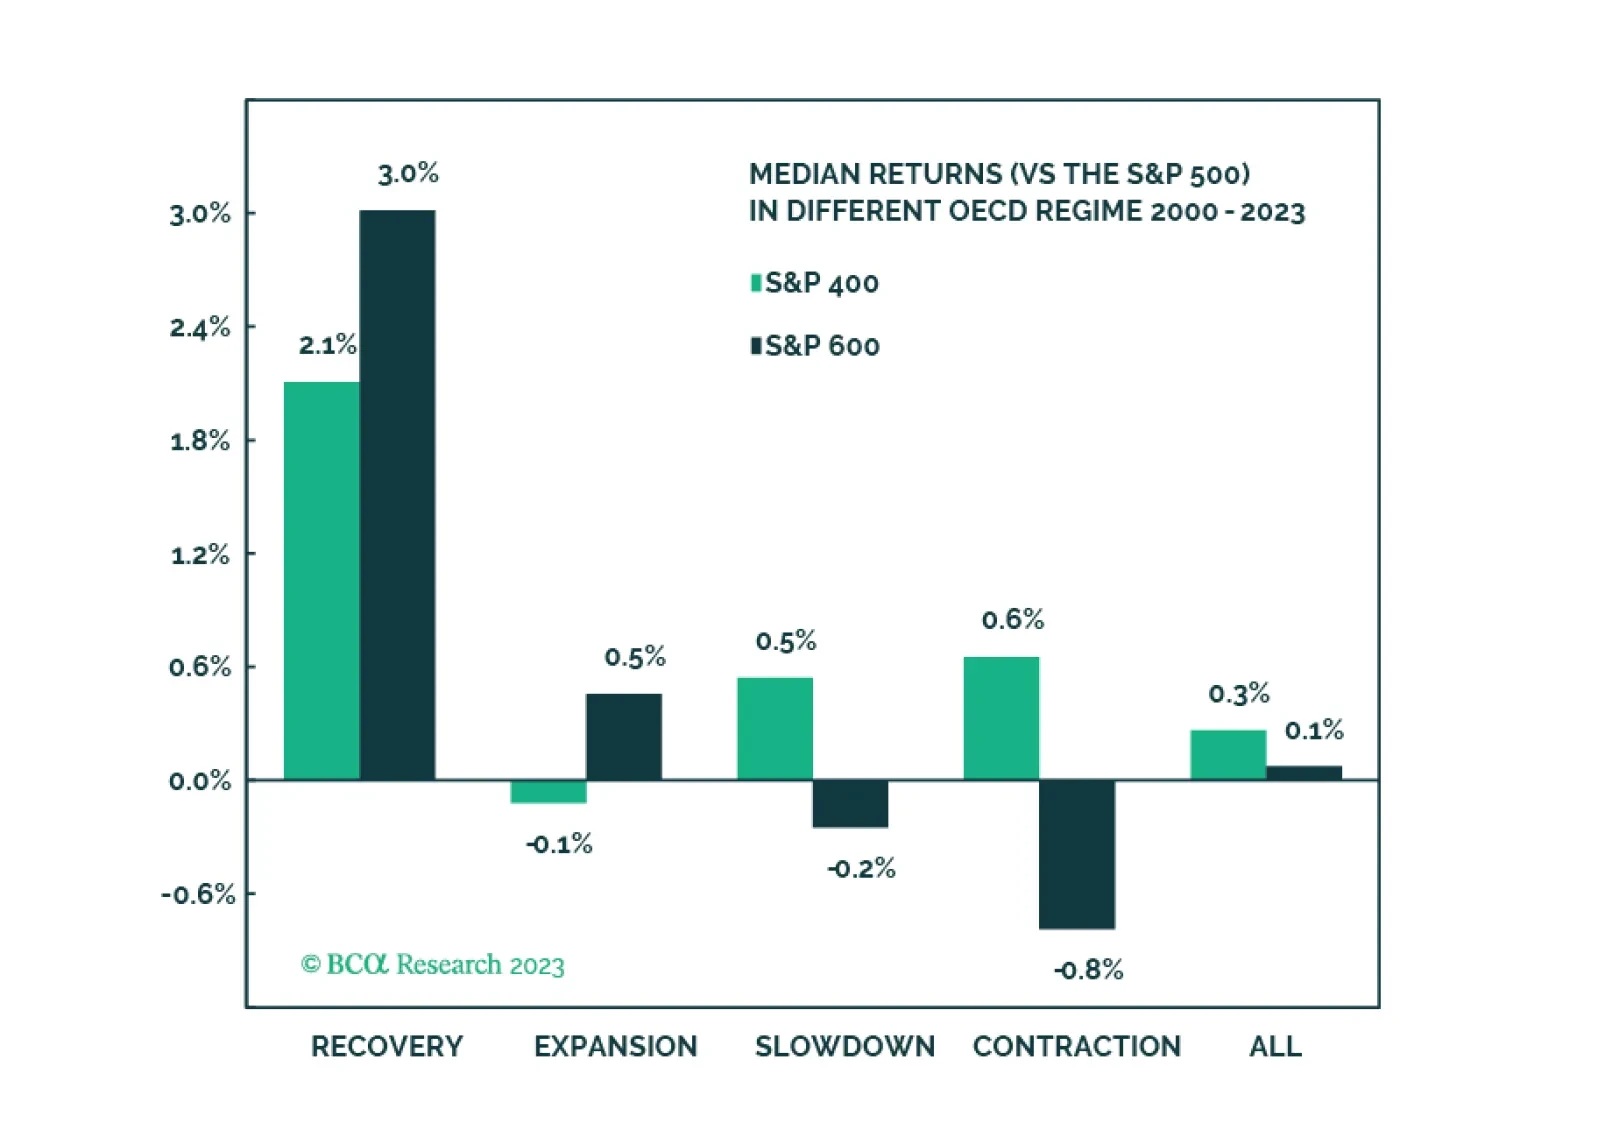
Mid-caps are the best of both worlds and are an excellent strategic overweight thanks to their size premium, but also better financial quality and higher dividend yield than Small. We are bullish on Mid near term and believe that this may be a great trade. We will initiate a position in the S&P 400 as a tactical overweight but will monitor it very closely.
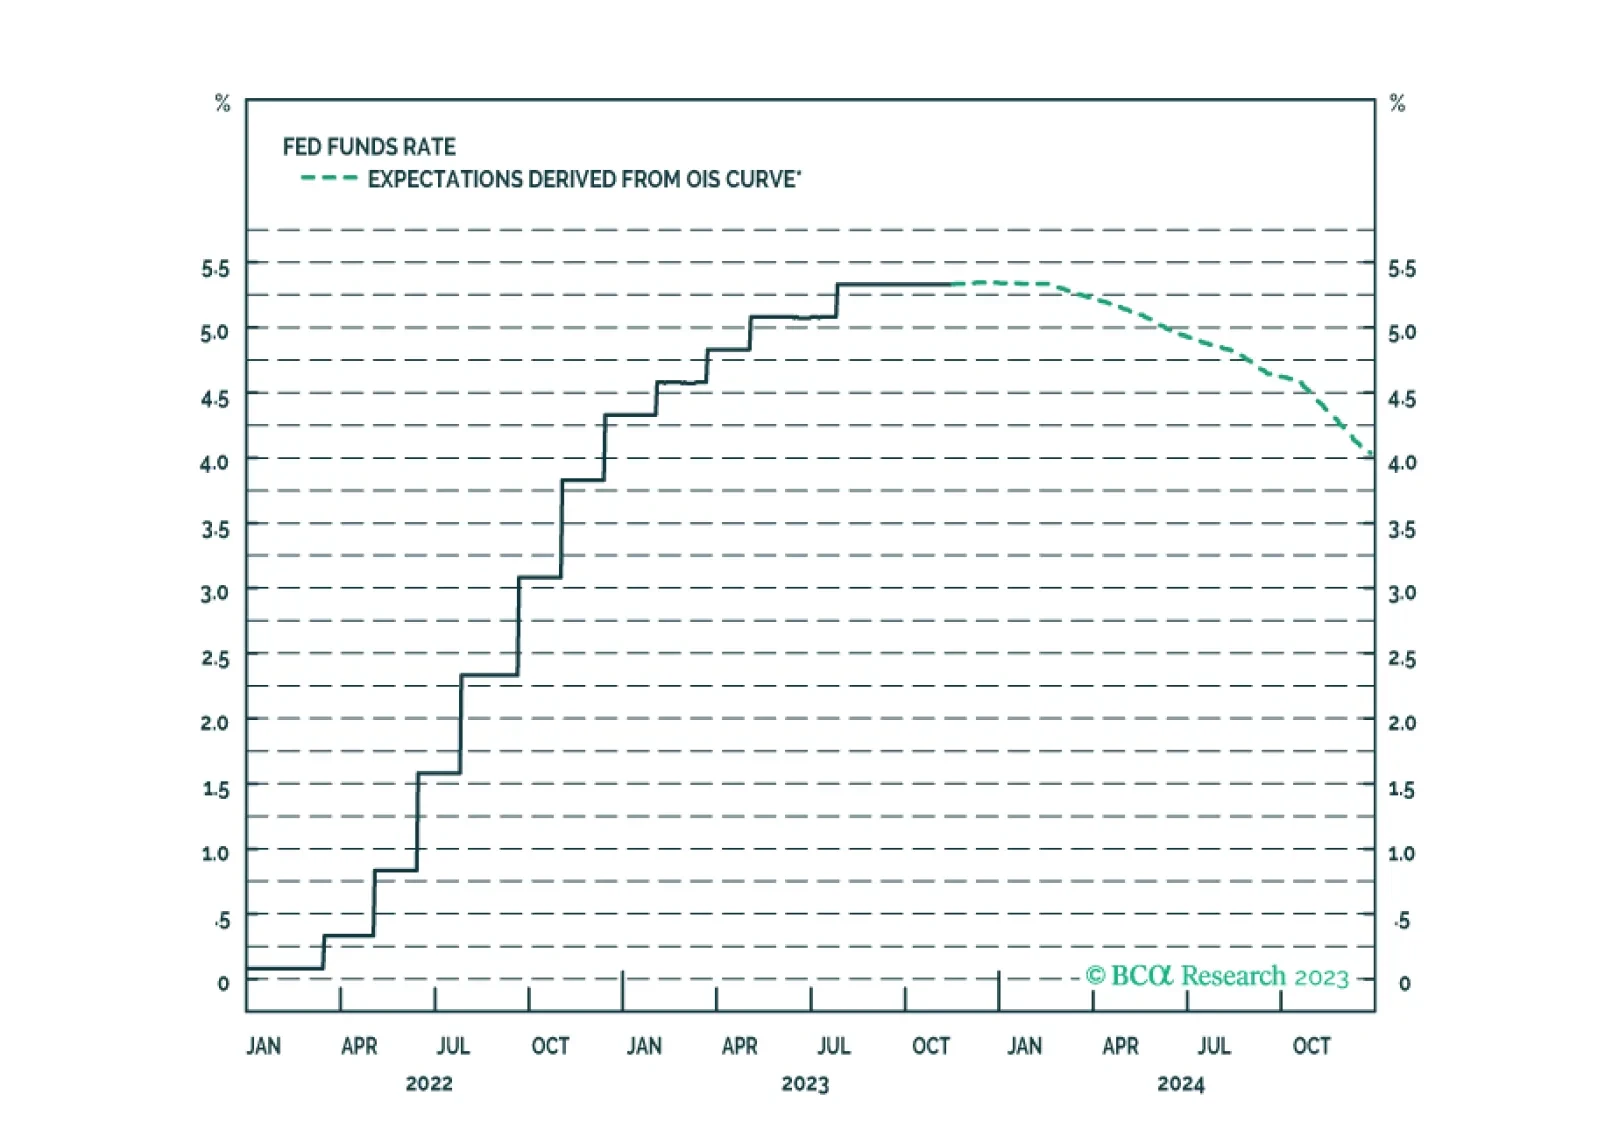
The soft-landing narrative has gotten nowhere at BCA but appears to be making some headway with broker-dealers and investors. We are preparing to lean against it once it pushes equity prices a little higher.
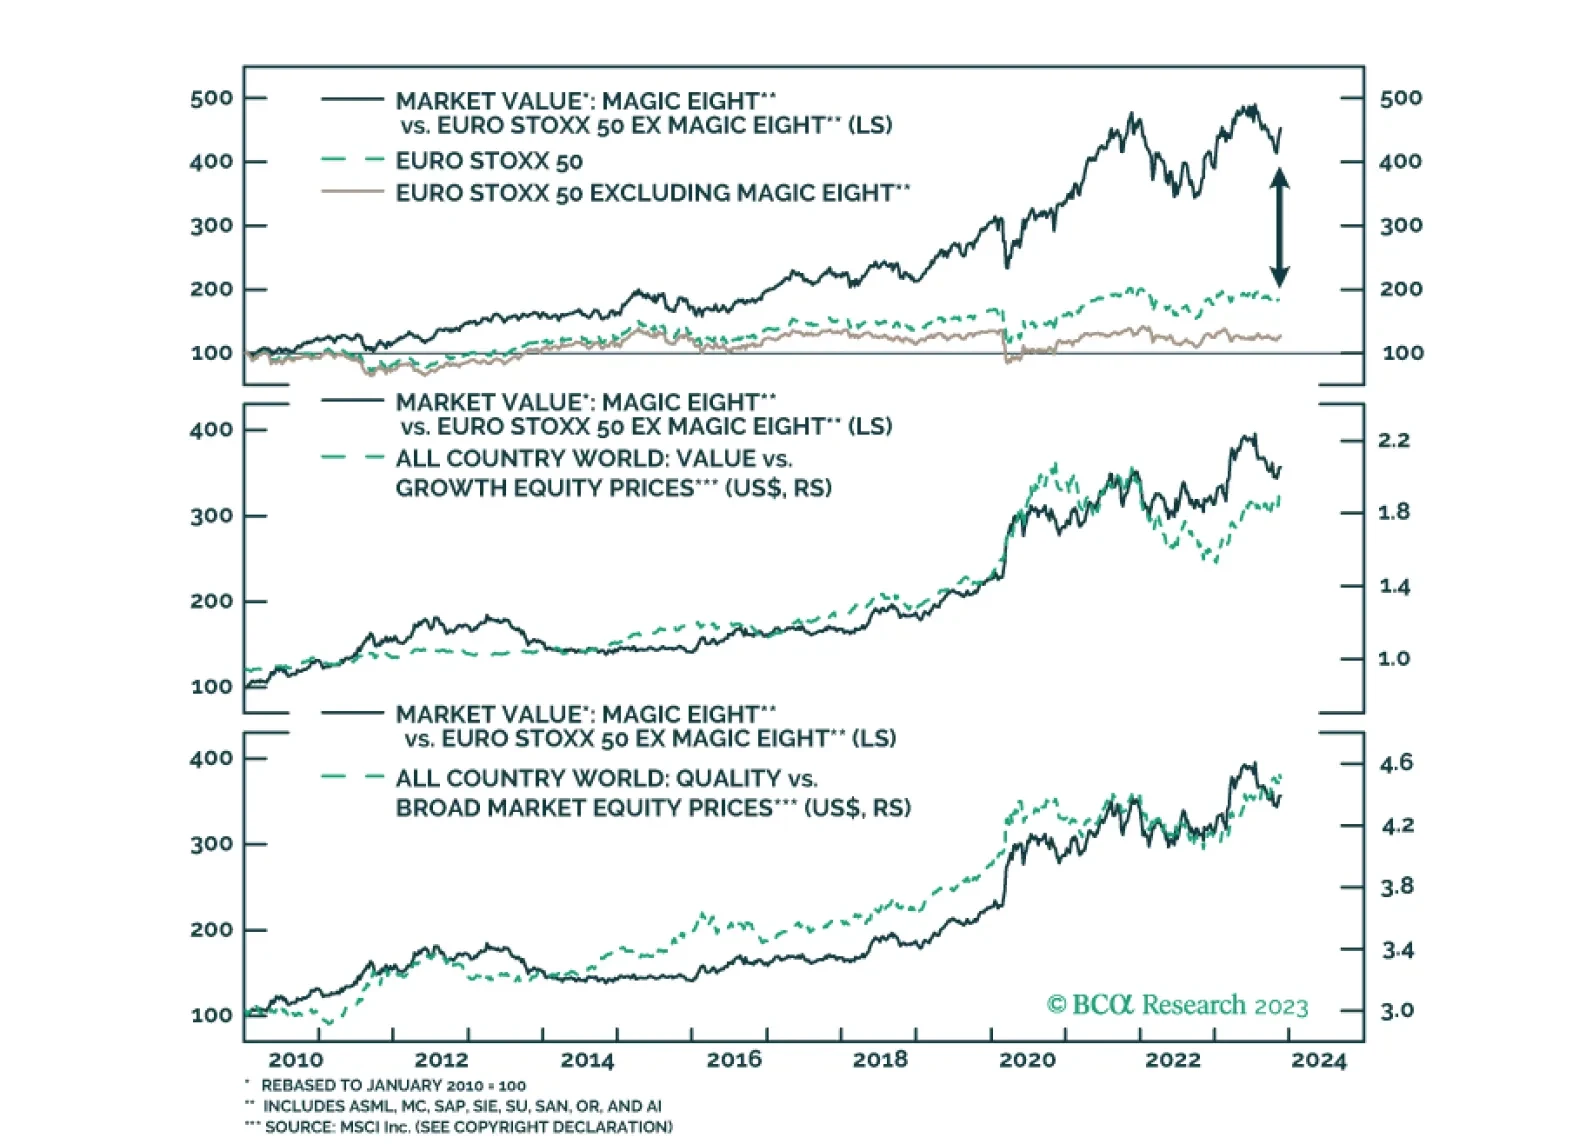
The US has the Magnificent Seven, Europe has the Magic Eight. What drives the performance of those eight stocks crucial to the European market?
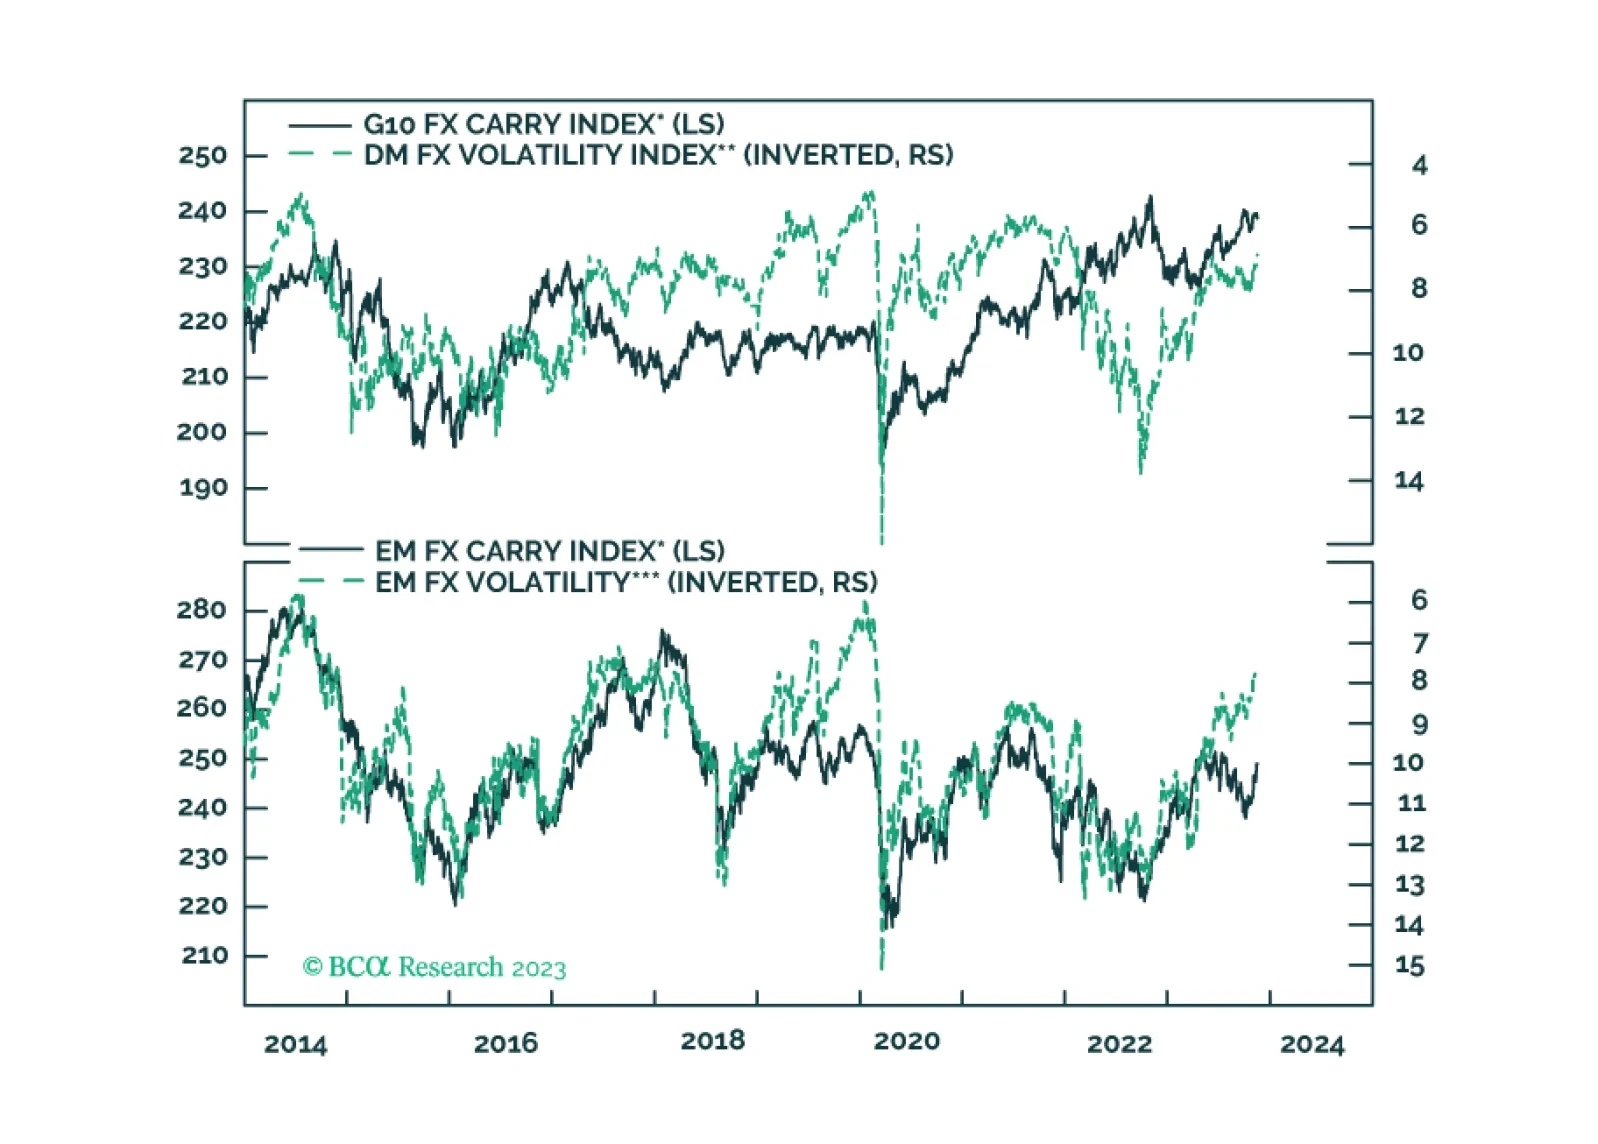
In this report, we evaluate the risk to carry trades in the coming months.
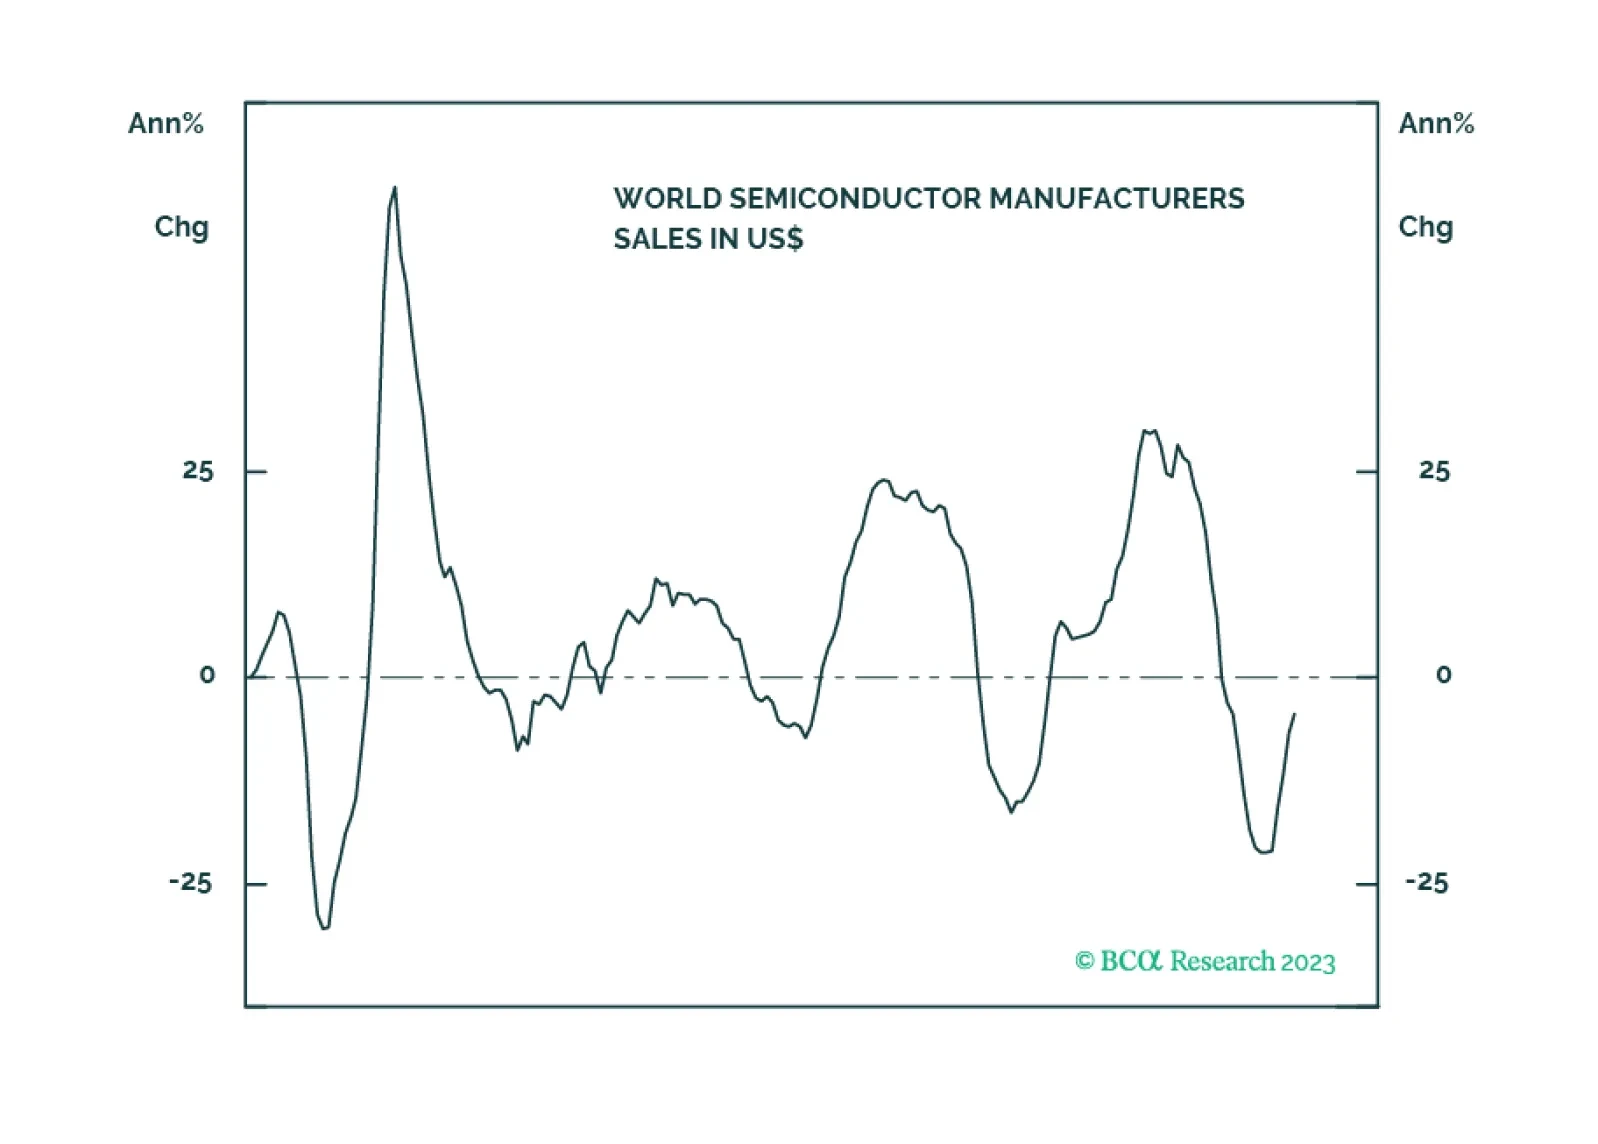
After a prolonged slump, there are early signs that demand for chips has bottomed and is showing signs of life. Meanwhile, corporate demand for future GAI chips is still a significant industry tailwind. In line with our call for an overweight of the Magnificent Seven, upgrade Semis to equal weight from underweight on a tactical basis. Longer-term outlook is neutral to negative as we expect the economy to slow in 2024, while growth expectations may be too high.
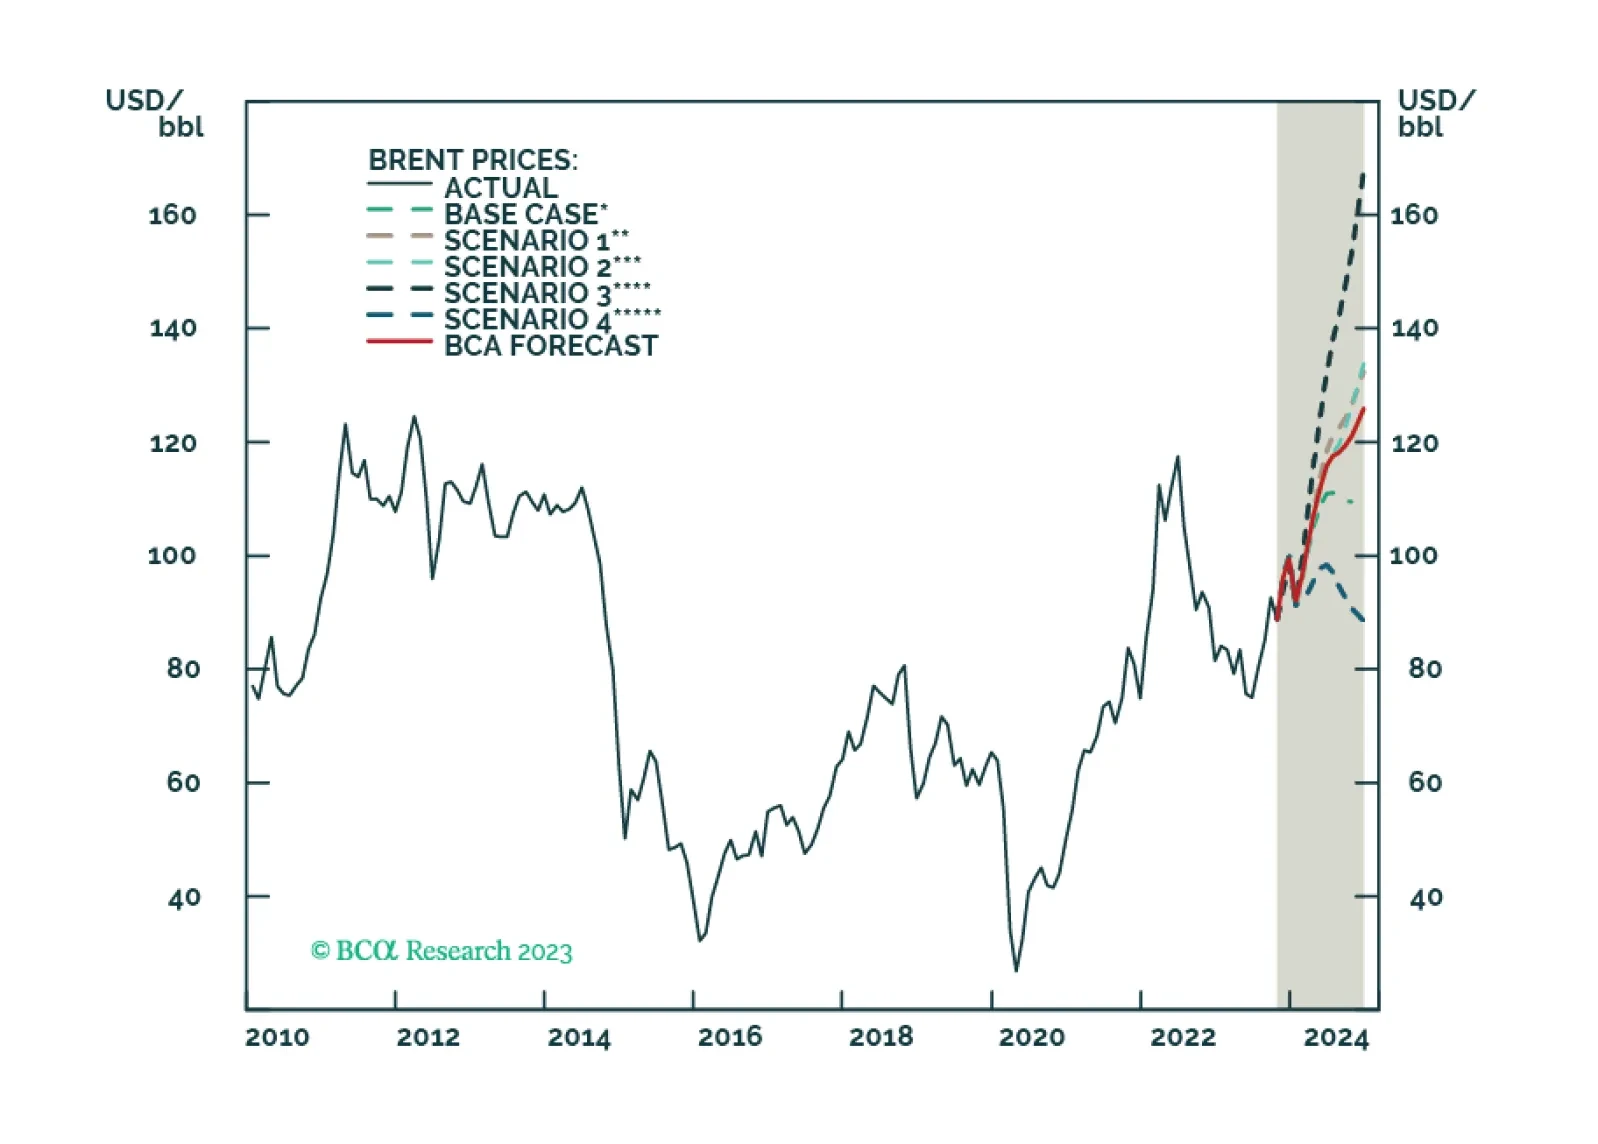
US and Chinese oil-demand strength will offset EU weakness next year. Incremental supply growth from non-OPEC 2.0 producers, coupled with a lower risk of the US enforcing its sanctions on Iranian oil exports, reduces our 2024 Brent price forecast by $6/bbl, and takes it to $112/bbl.
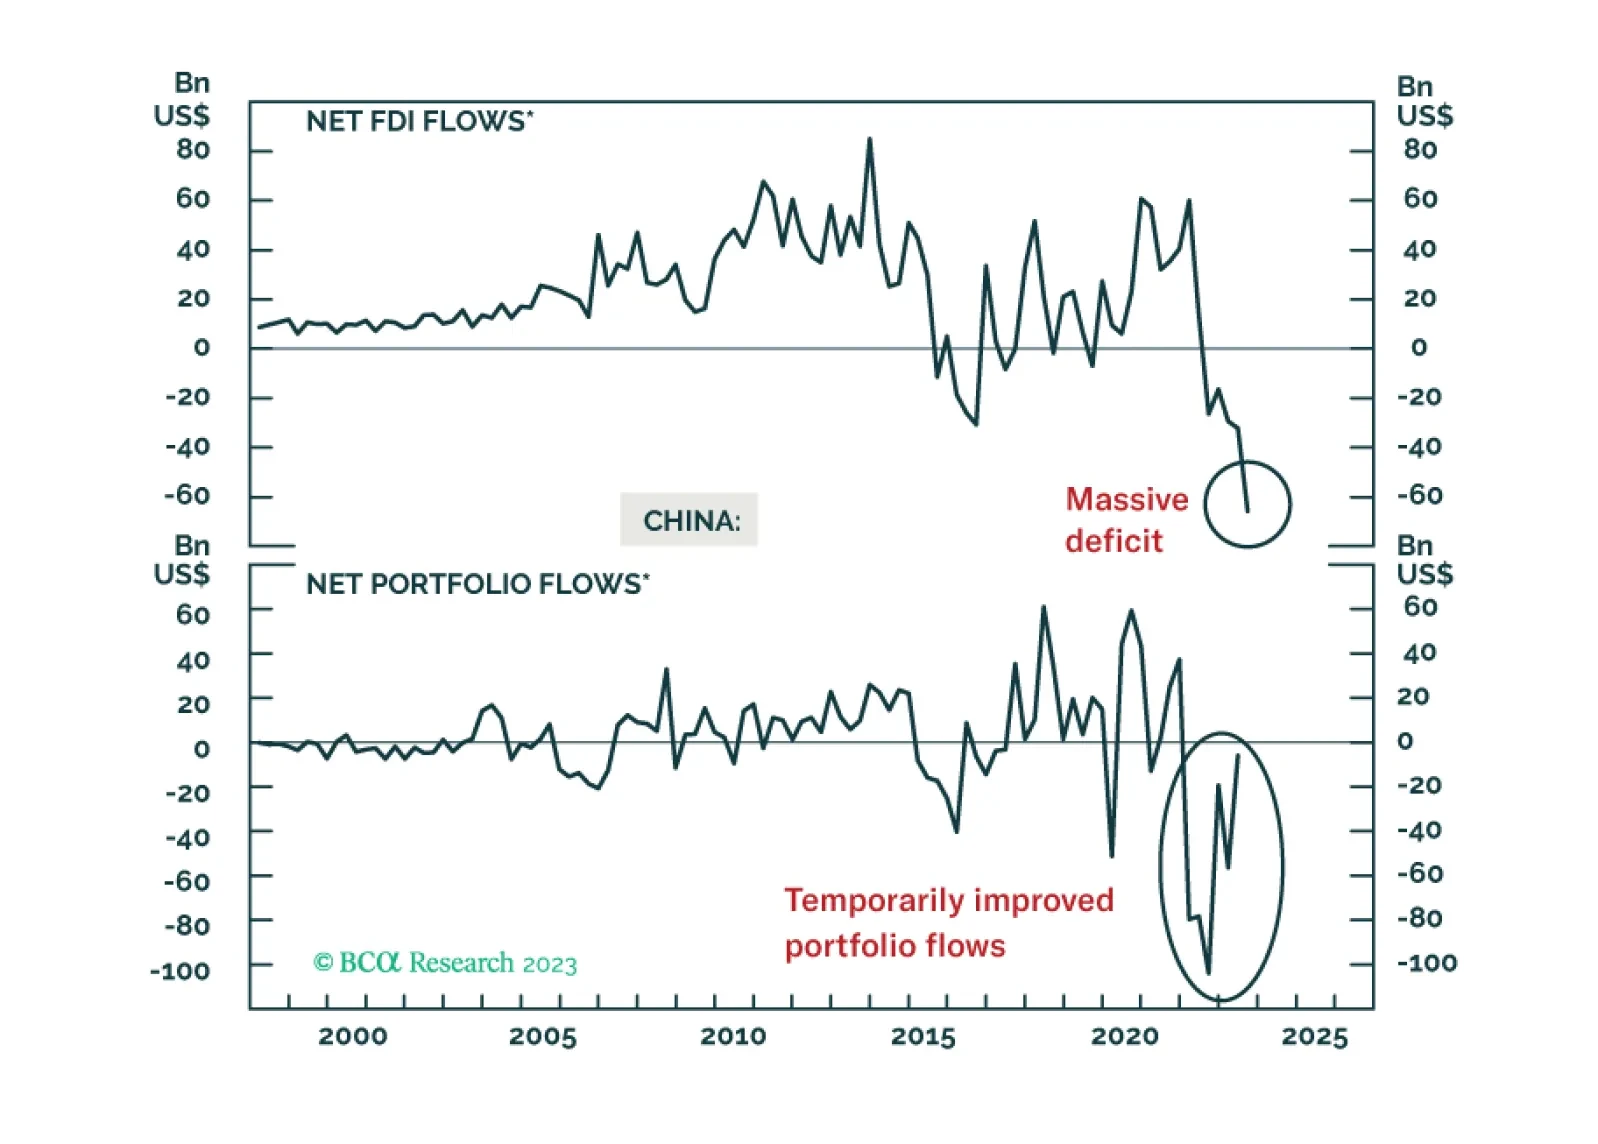
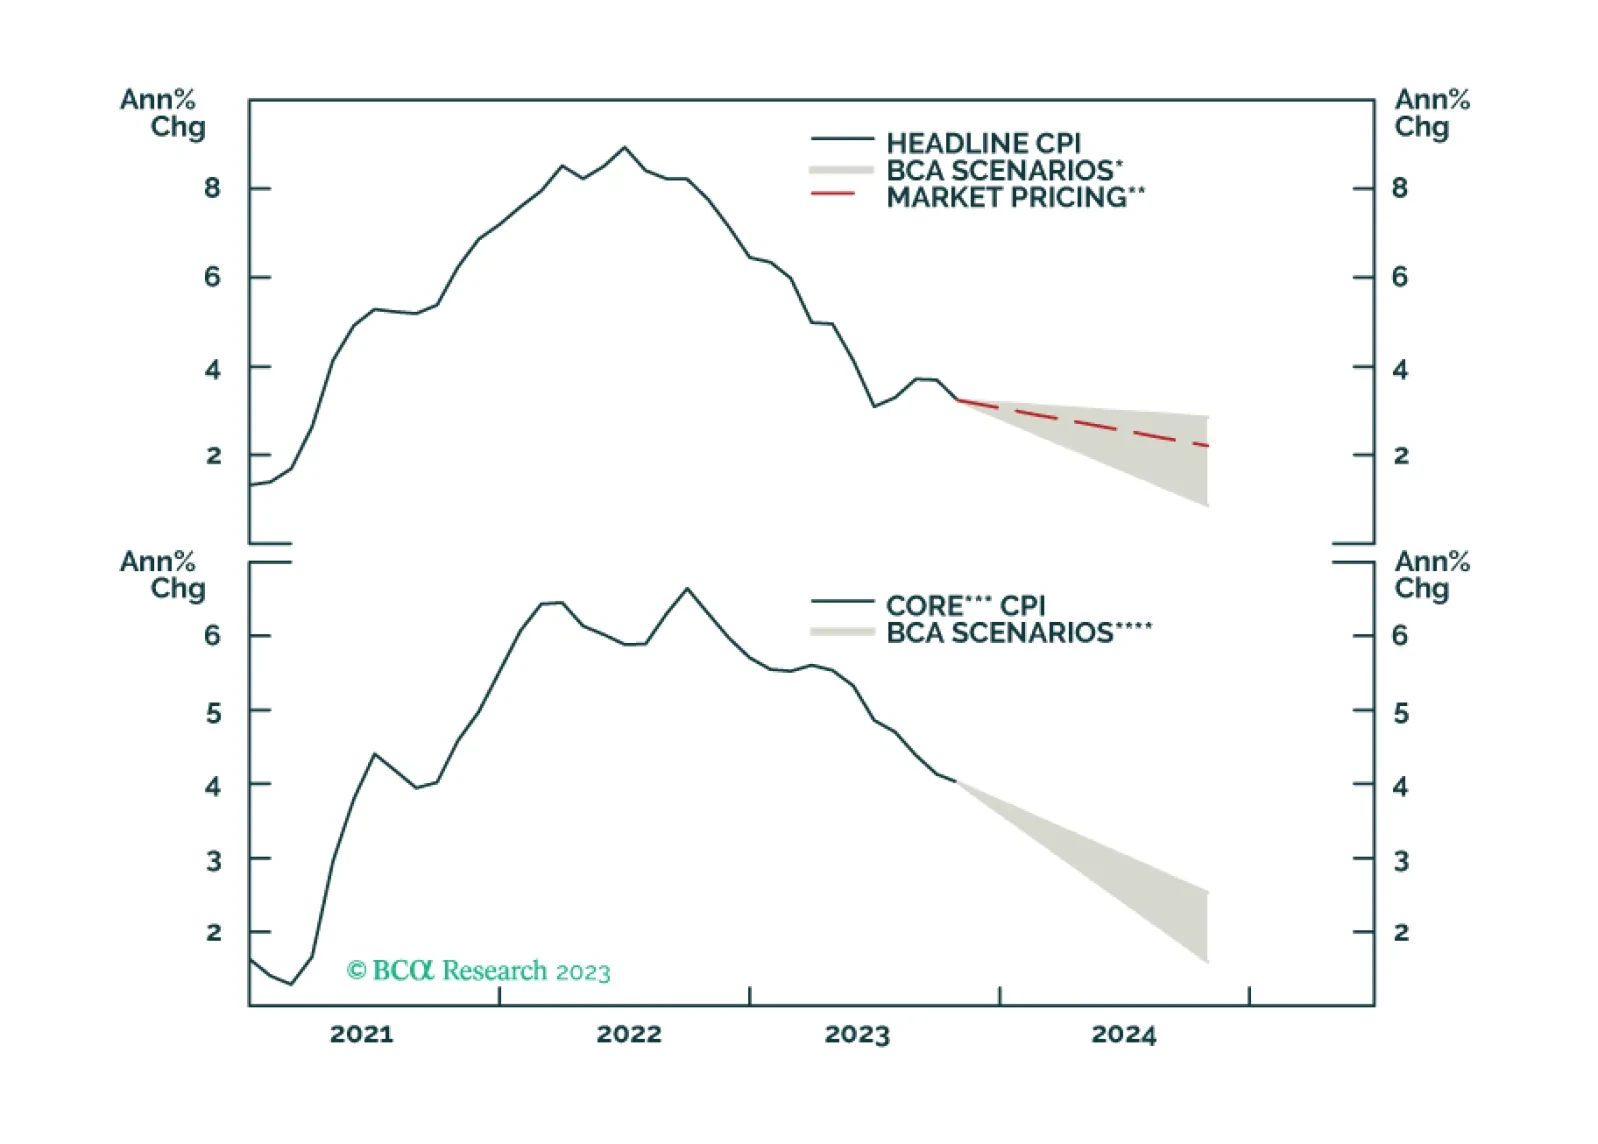
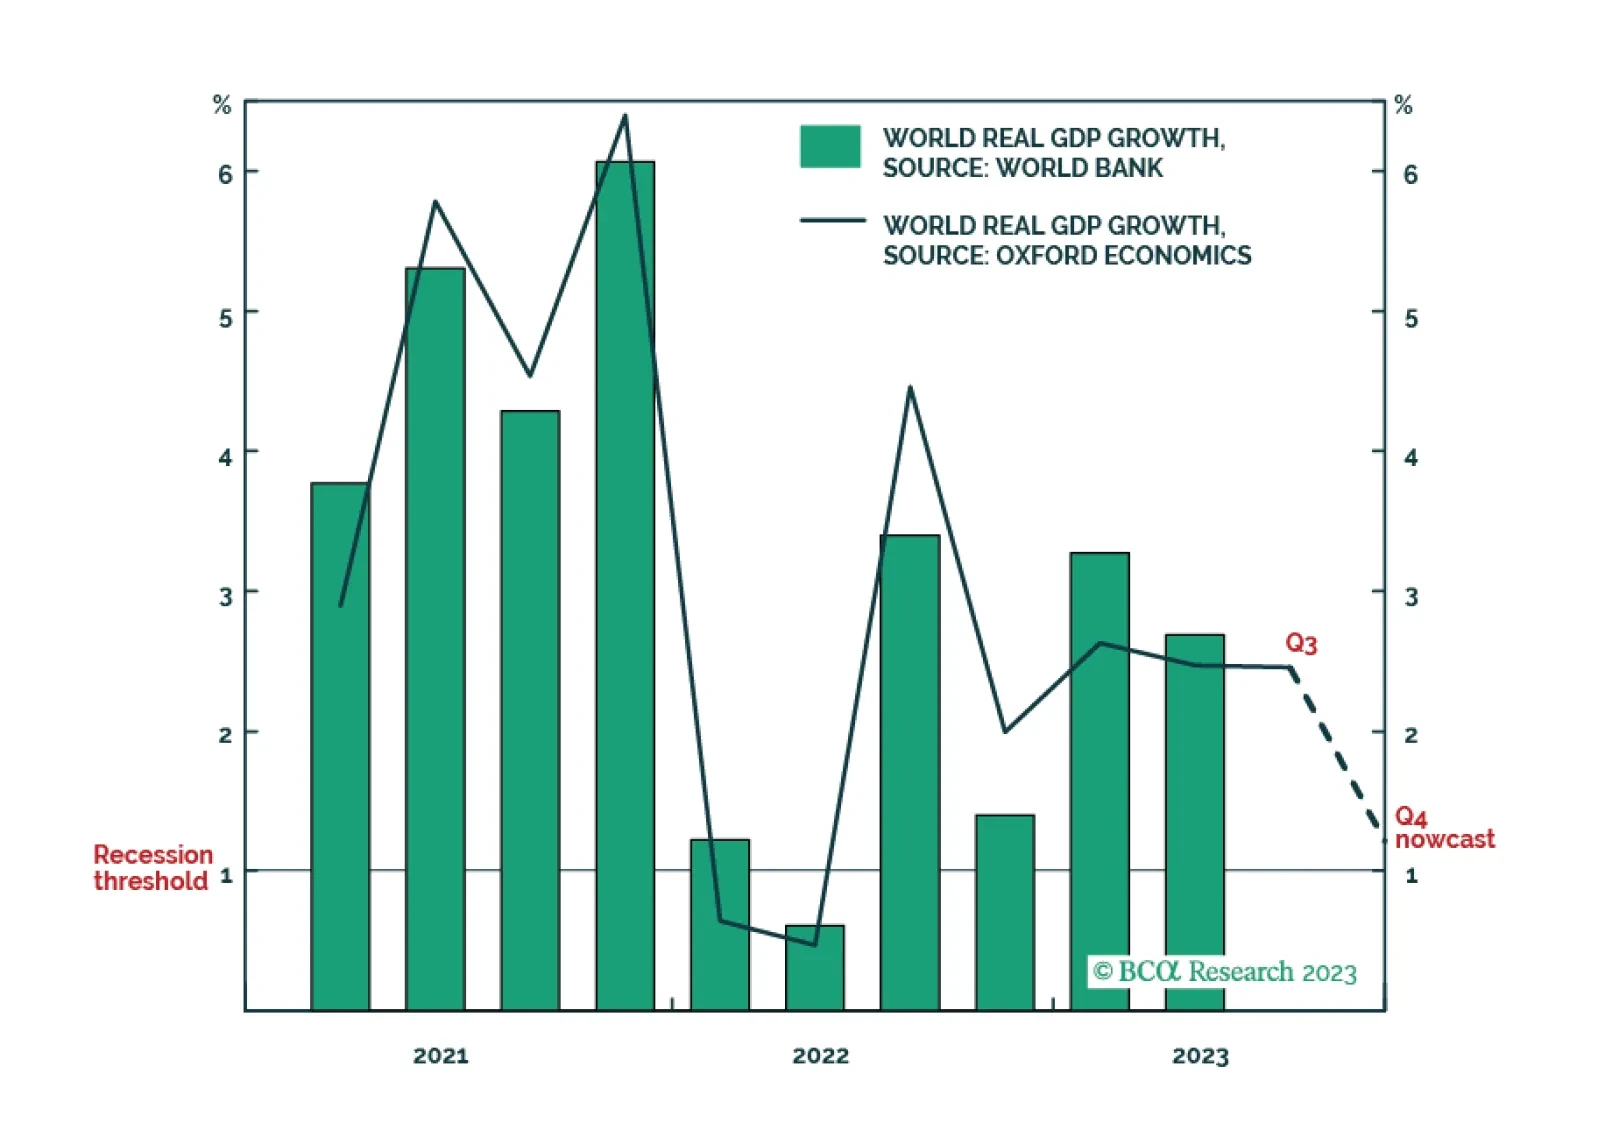
The latest ‘nowcast’ for world economic growth in the fourth quarter has plunged to just 1.2 percent, marking the cusp of another world recession. One important implication is that expectations for oil demand growth and industrial metal demand growth are way too optimistic.