Skip to main content

Latest from BCA Research
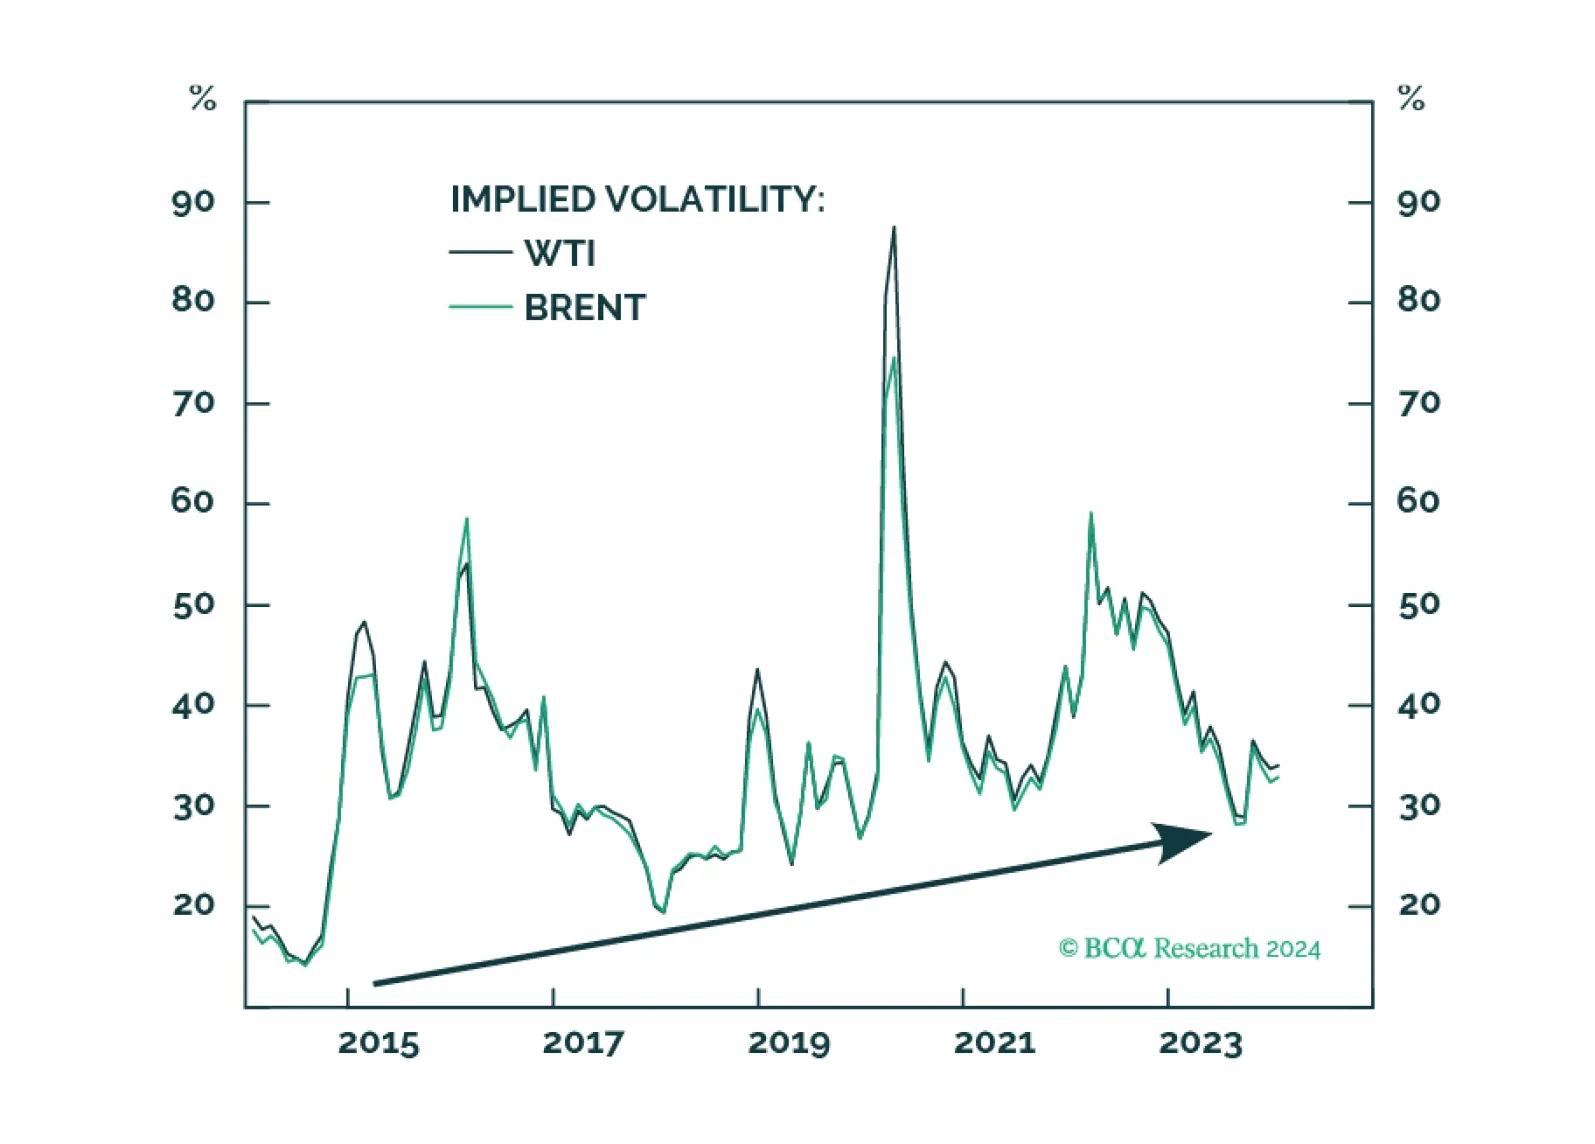
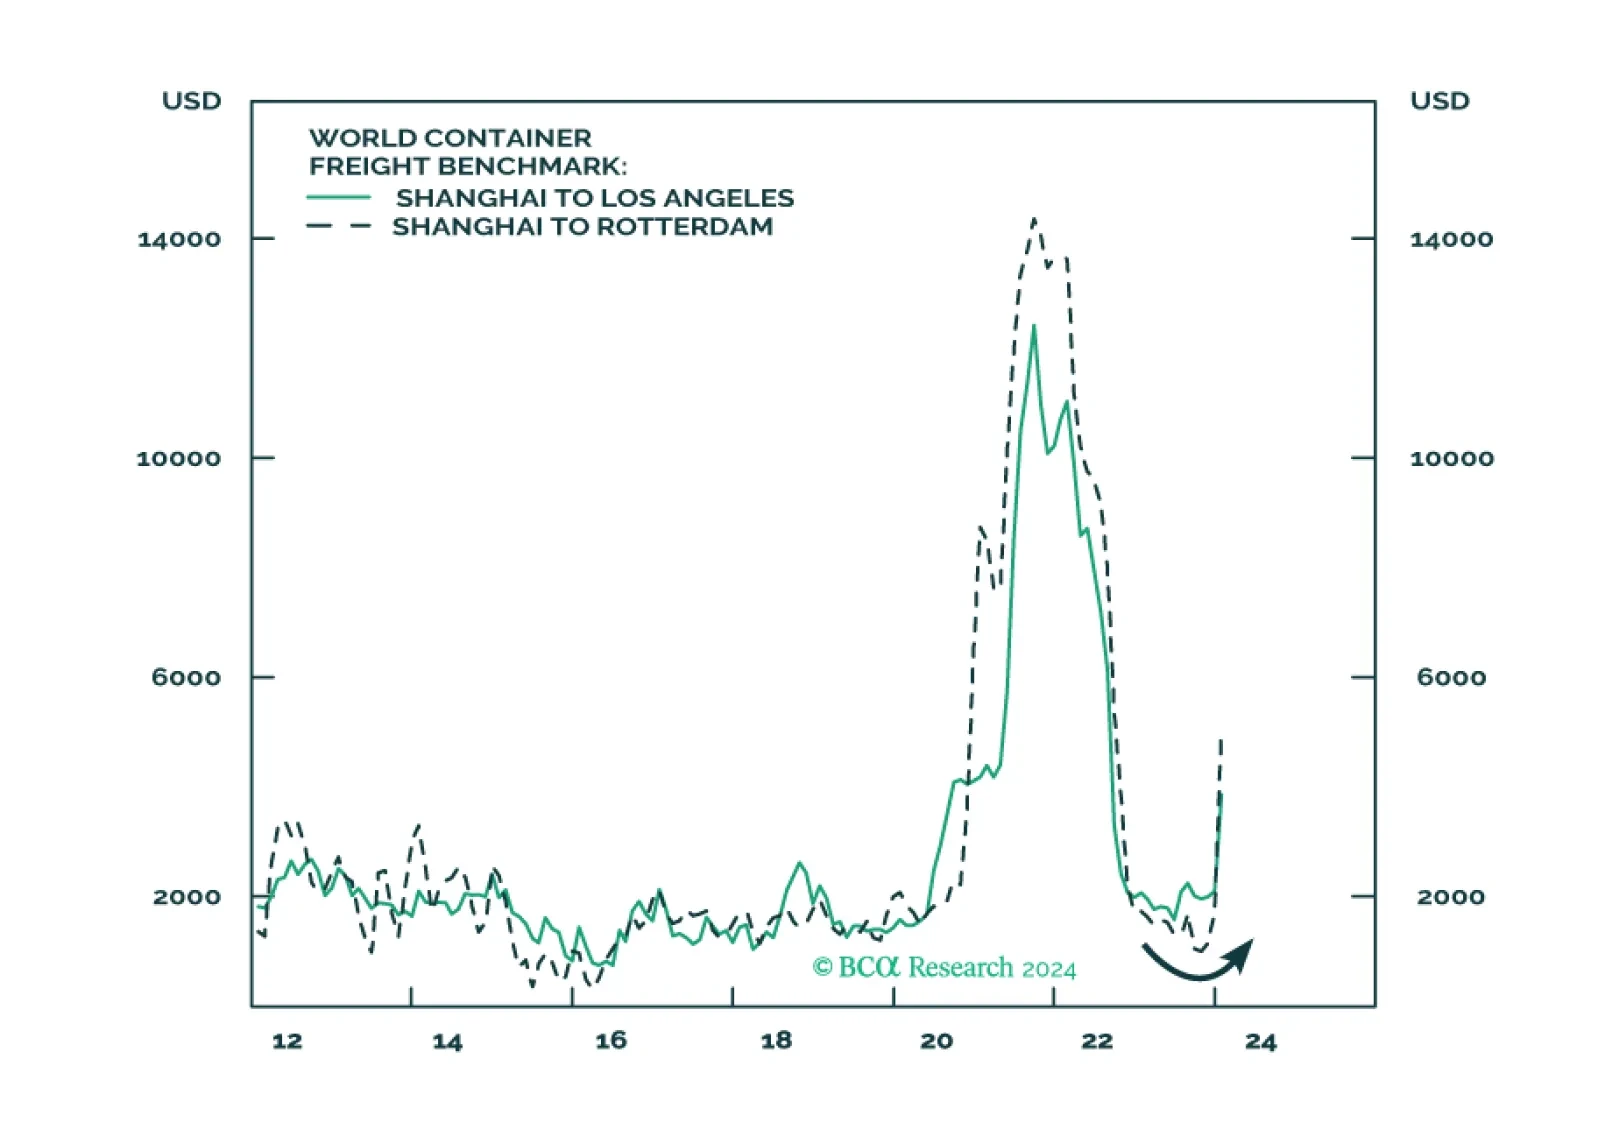
Special Report Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.
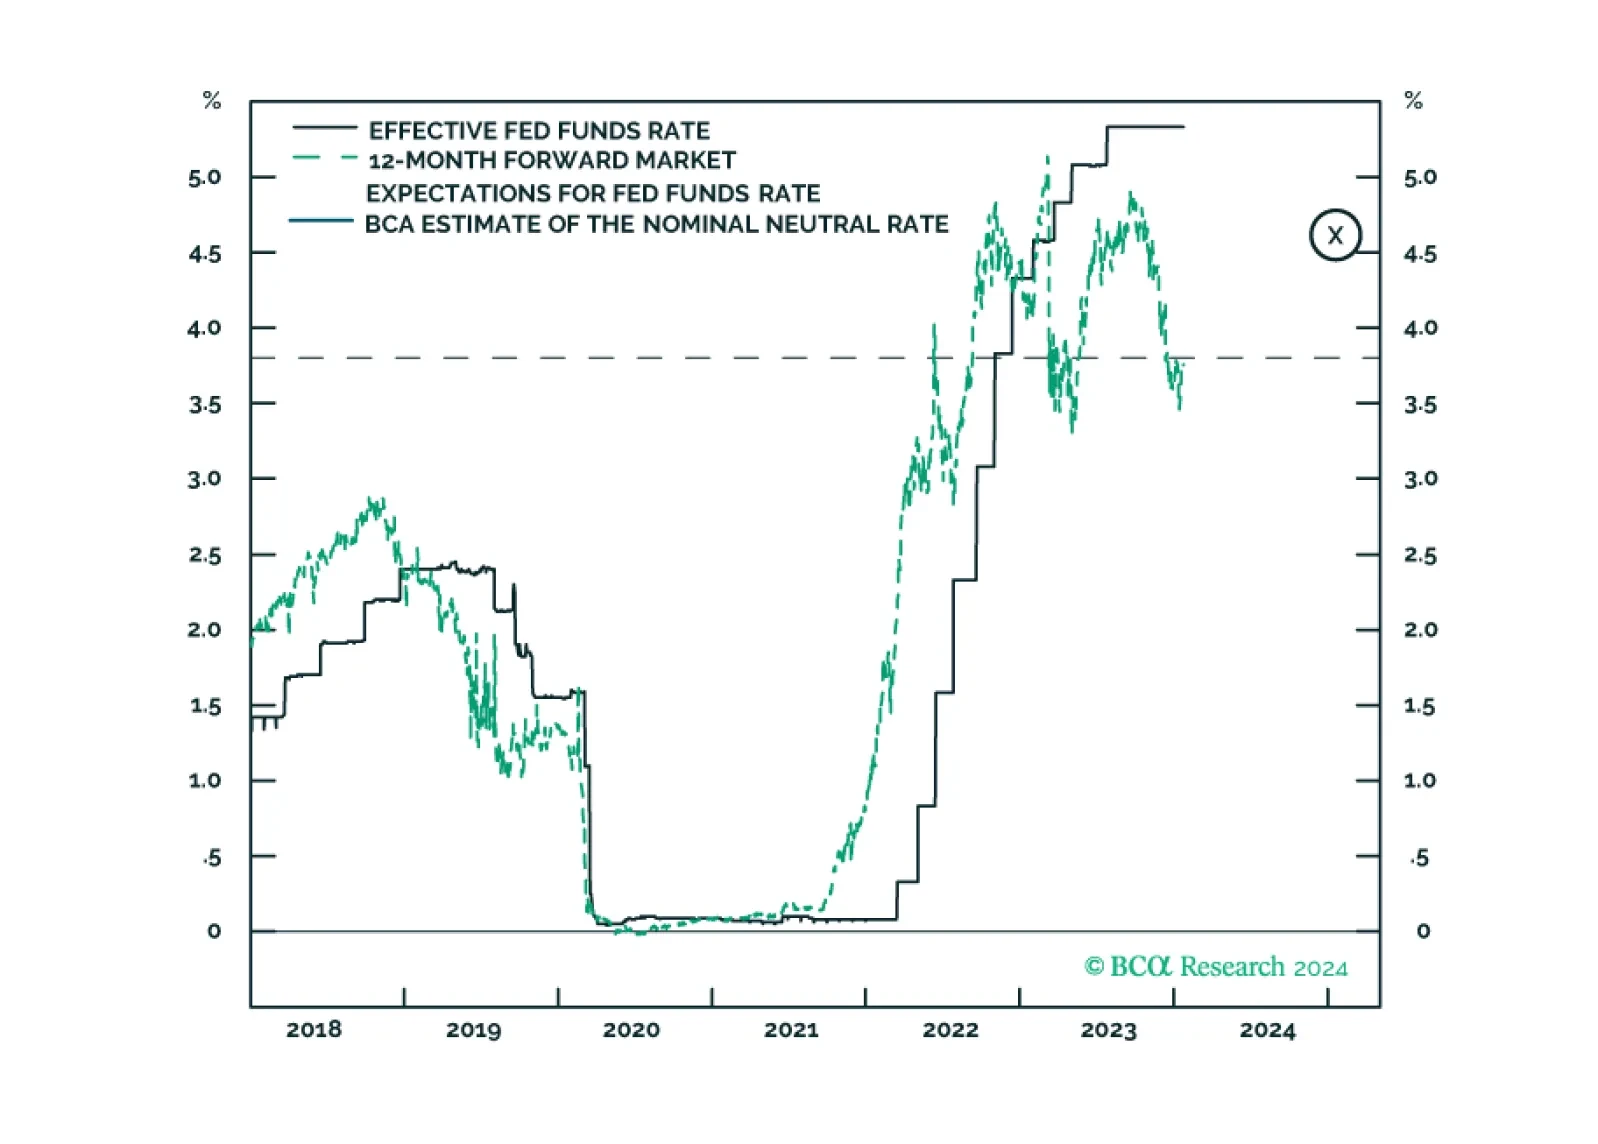
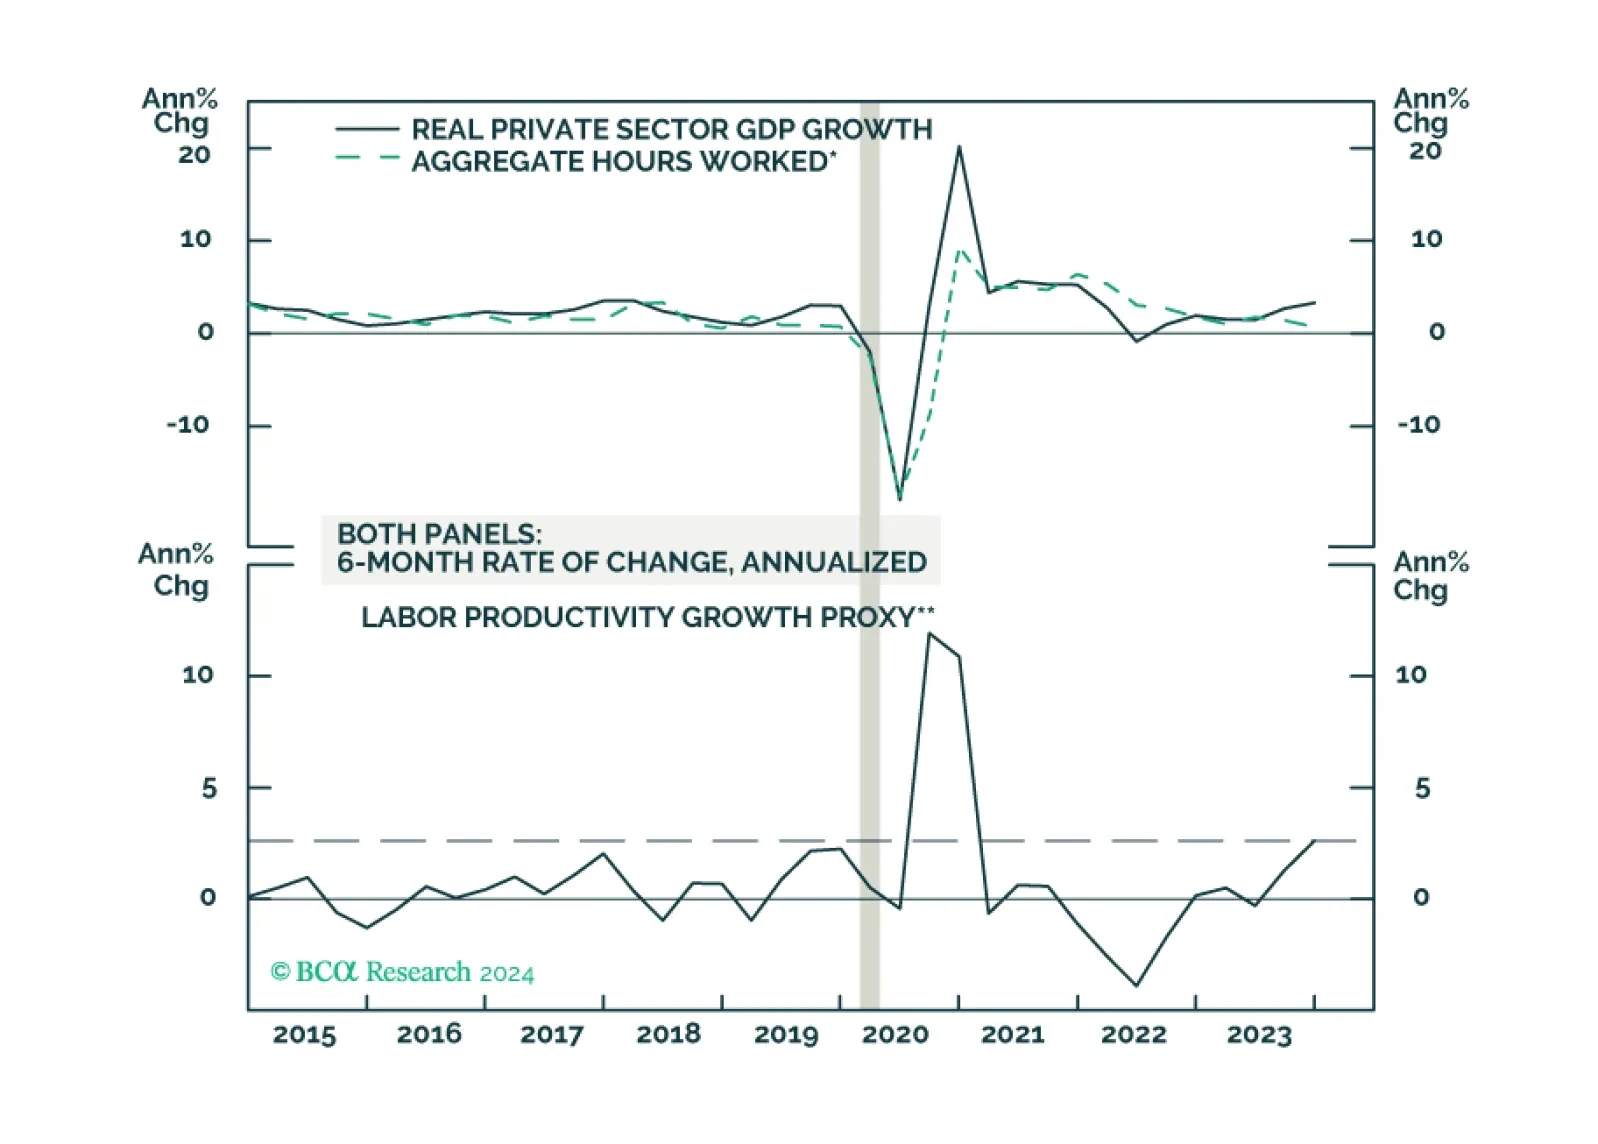
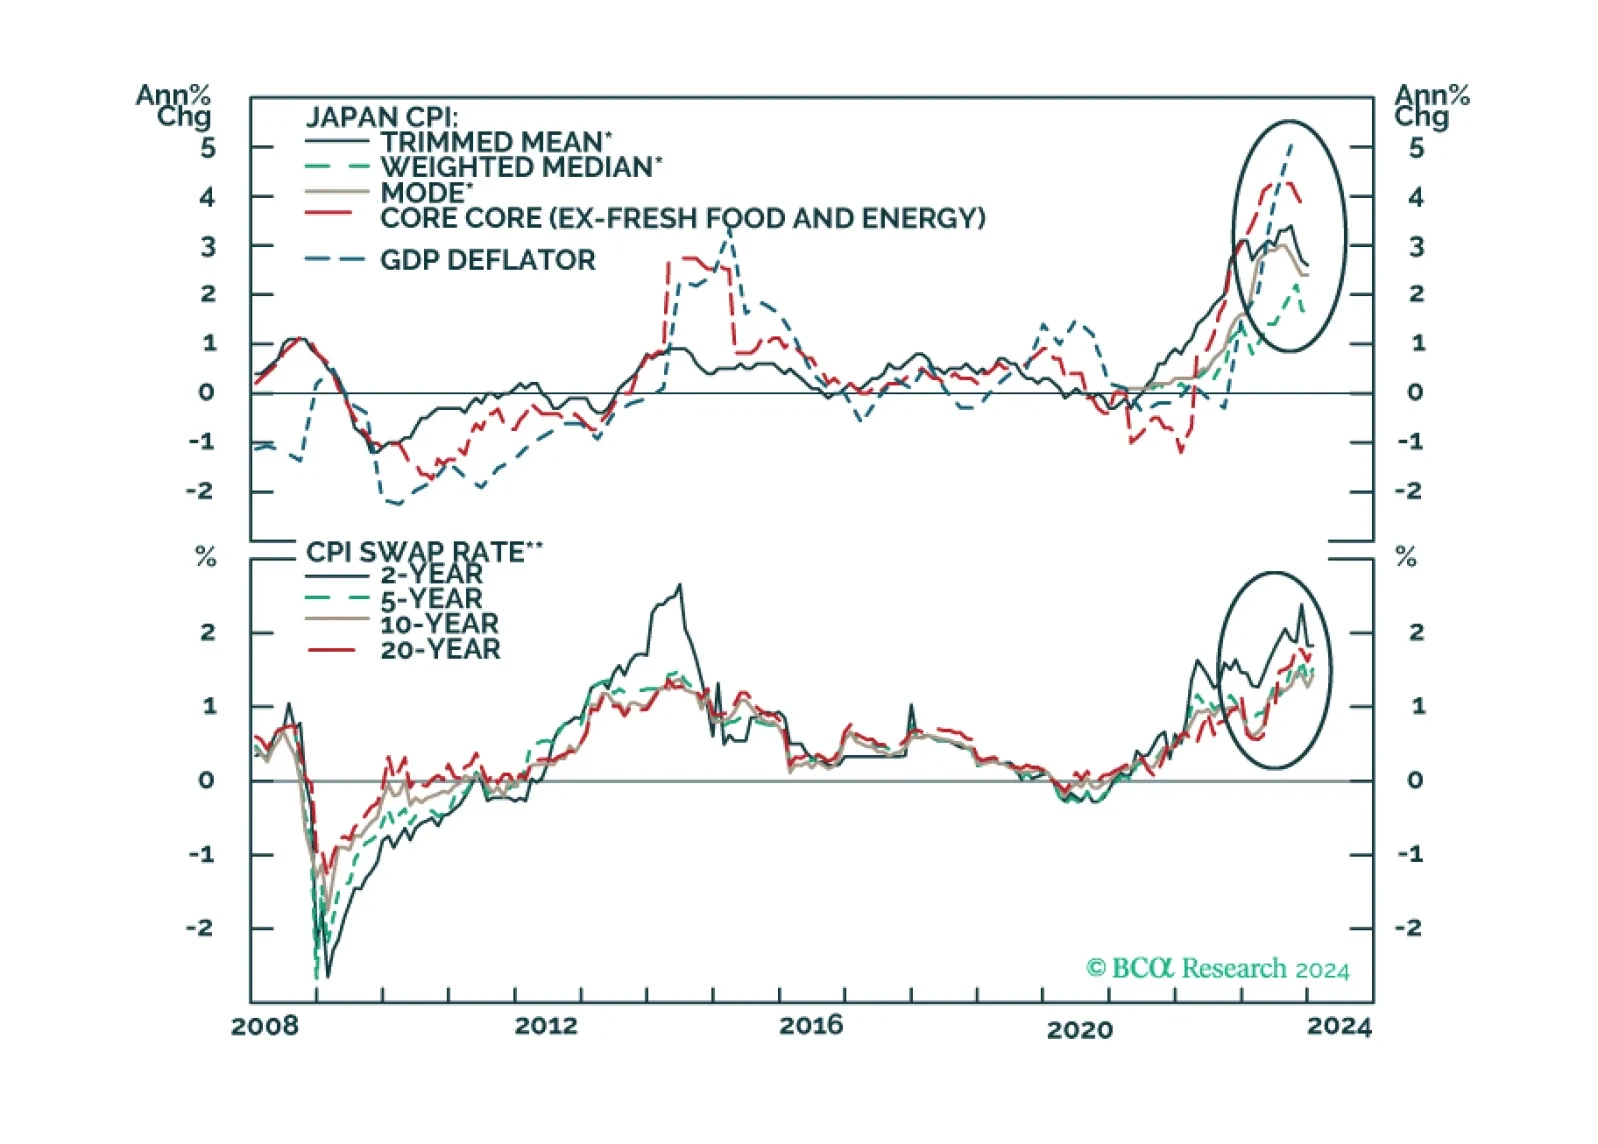
Low inflation argues for the Fed to move relatively quickly toward rate cuts. Continued above-trend GDP growth poses a risk to this view, but leading indicators point to slower growth in the coming quarters.
We look at the implications for FX from the slew of central bank meetings this week.
Bank Credit Analyst
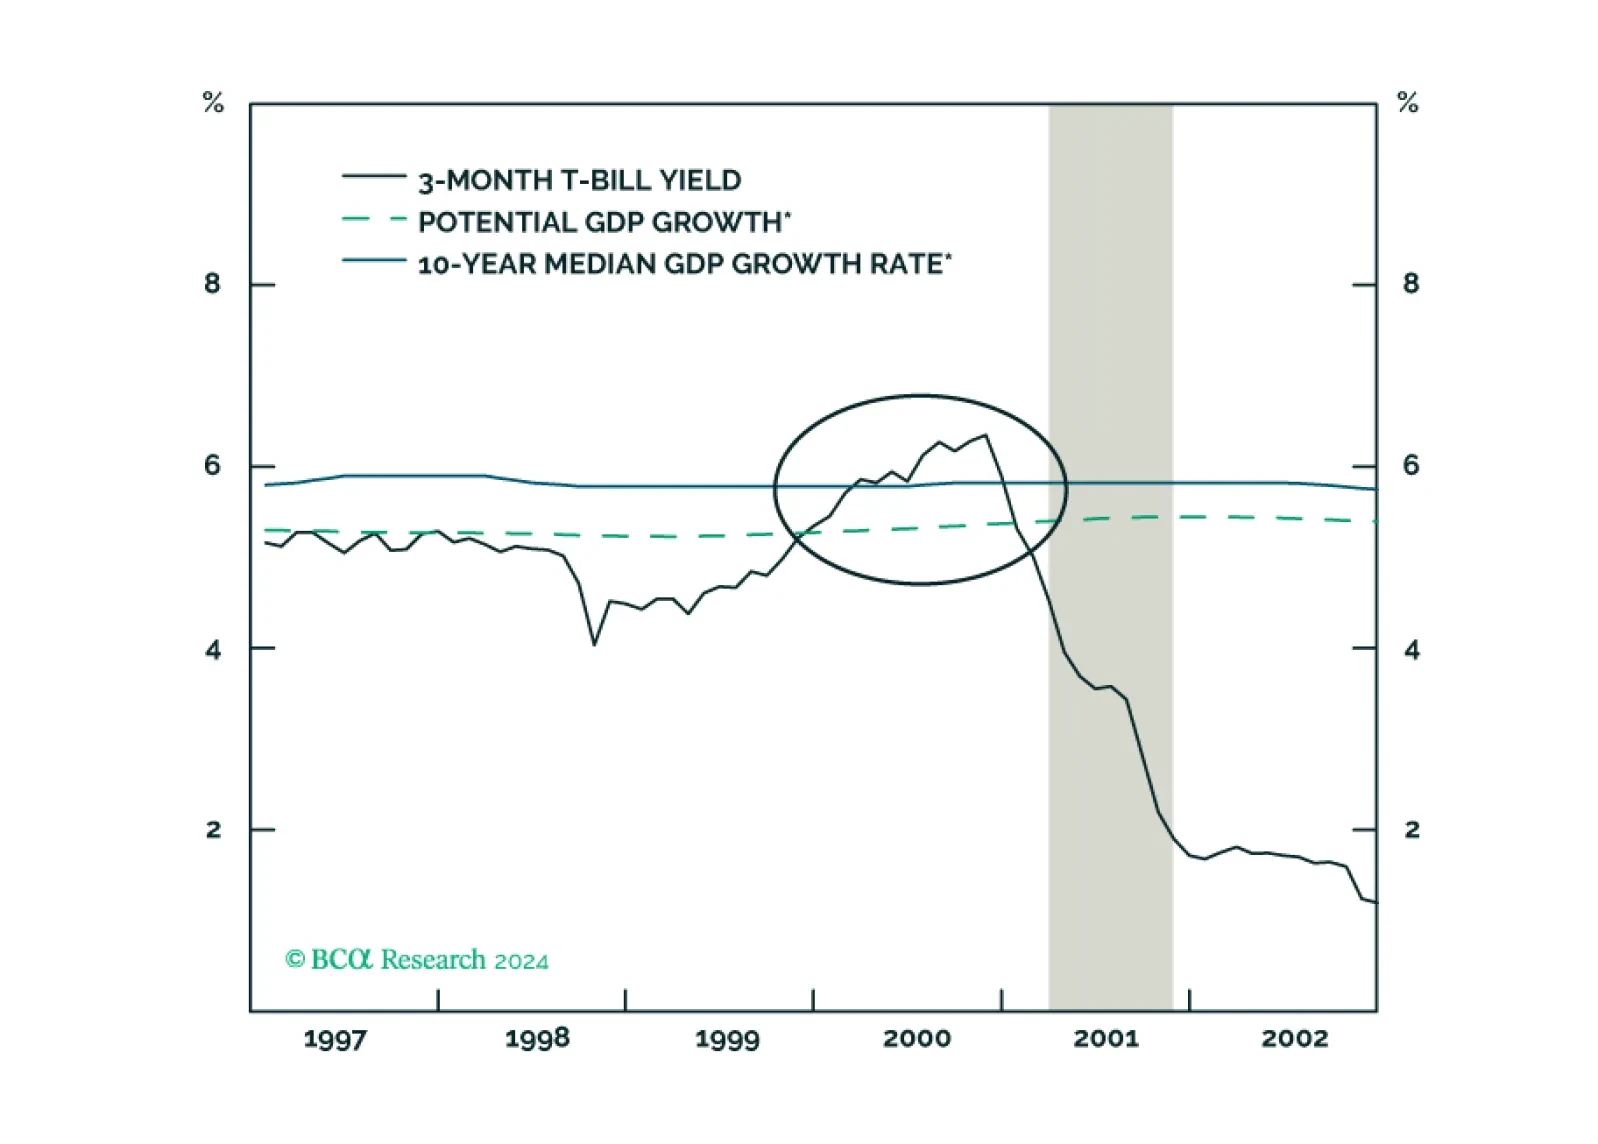
Bank Credit Analyst In Section I, we discuss the important flaws in the market’s “Goldilocks” economic narrative. Forward-looking measures of labor demand are heralding an eventual rise in the unemployment rate, and it is unlikely that this will occur in a benign fashion. This underscores that the US economy remains on a recessionary trajectory so long as monetary policy remains tight. Over the very near term, the Fed's December policy shift will remain a bullish factor for risky asset prices. But over a 6-12 month time horizon, investors should still be underweight risky assets and long fixed-income duration. In Section II, we review the post-World War II recessions to understand their causes and to see what indicators have been the most successful at signaling the end of recessionary selloffs in equity markets. We present an early draft “economic recovery checklist” for investors to monitor as a guide to determining when to increase one’s allocation to equities and other risky assets in the middle of a recession.
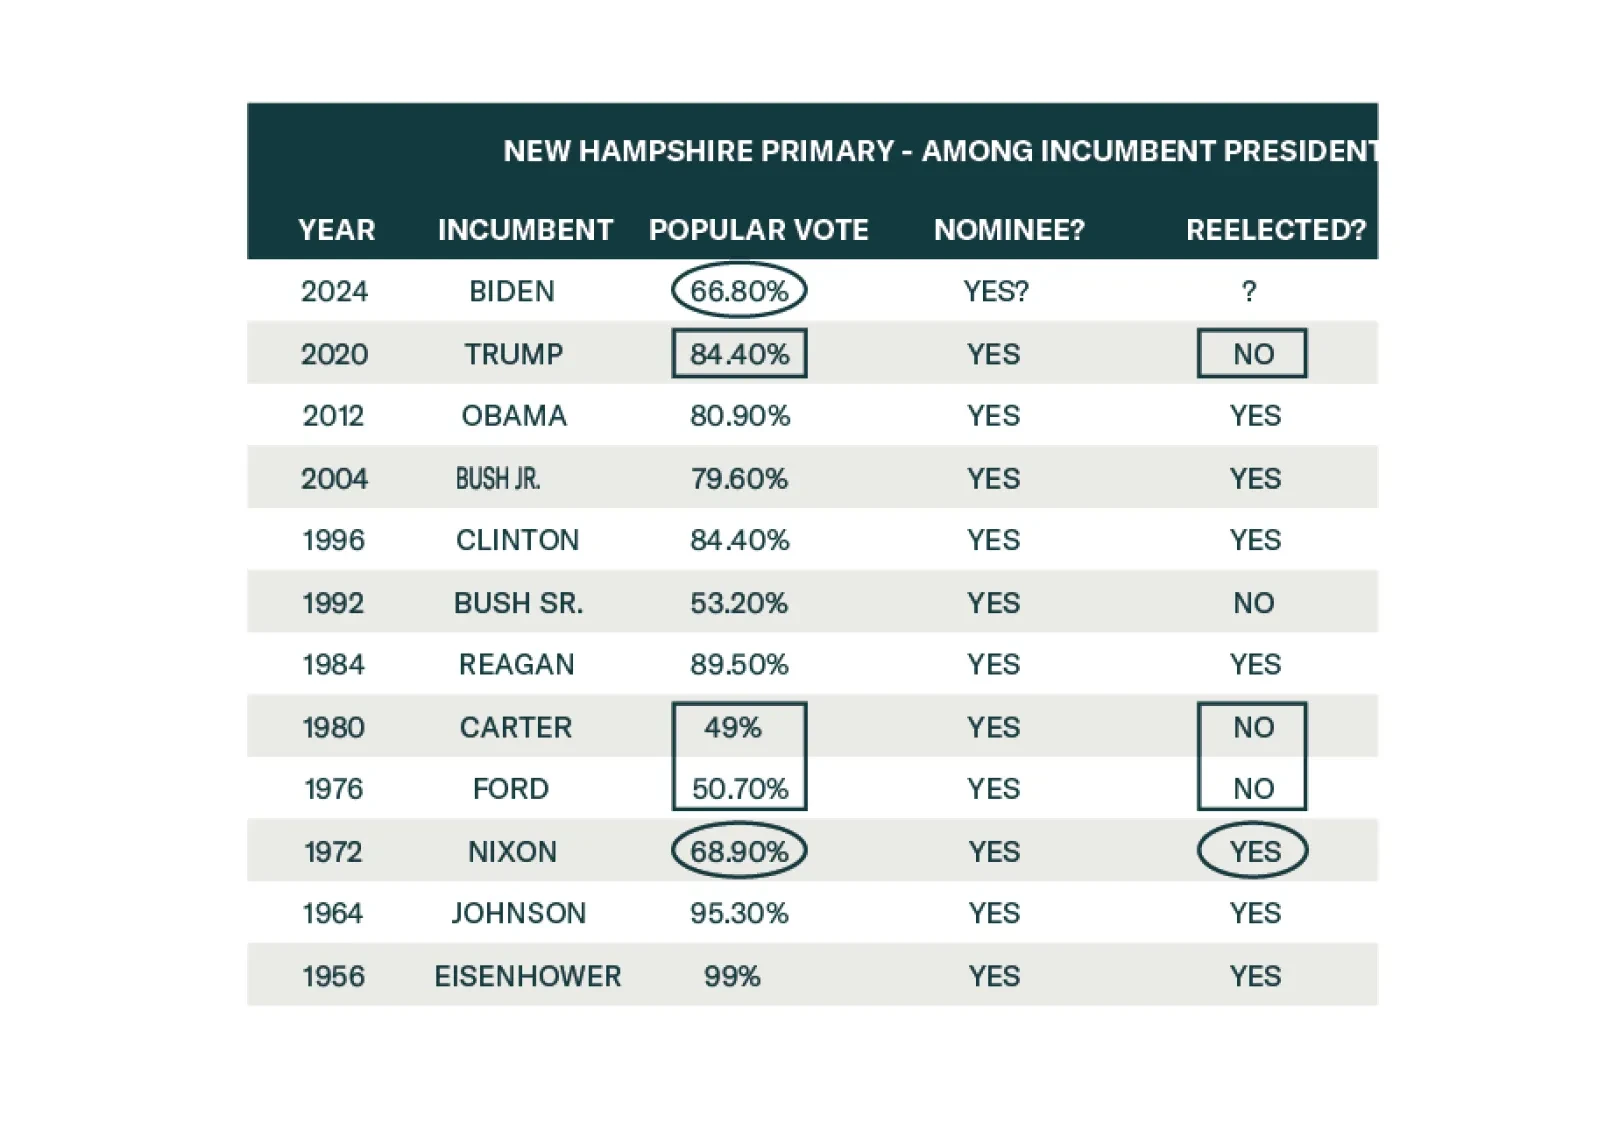
The US primary election is effectively over. The Biden-Trump rematch – our base case since 2022 – is all but set in stone. Only a health issue or freak incident could change that now.
Middle East conflict, extreme US policy uncertainty, Chinese economic slowdown, US-Russian proxy war, and Asian military conflicts do not create a stable investment backdrop for 2024. Our top five “black swan” risks may be highly improbable, but they stem from these underlying trends.
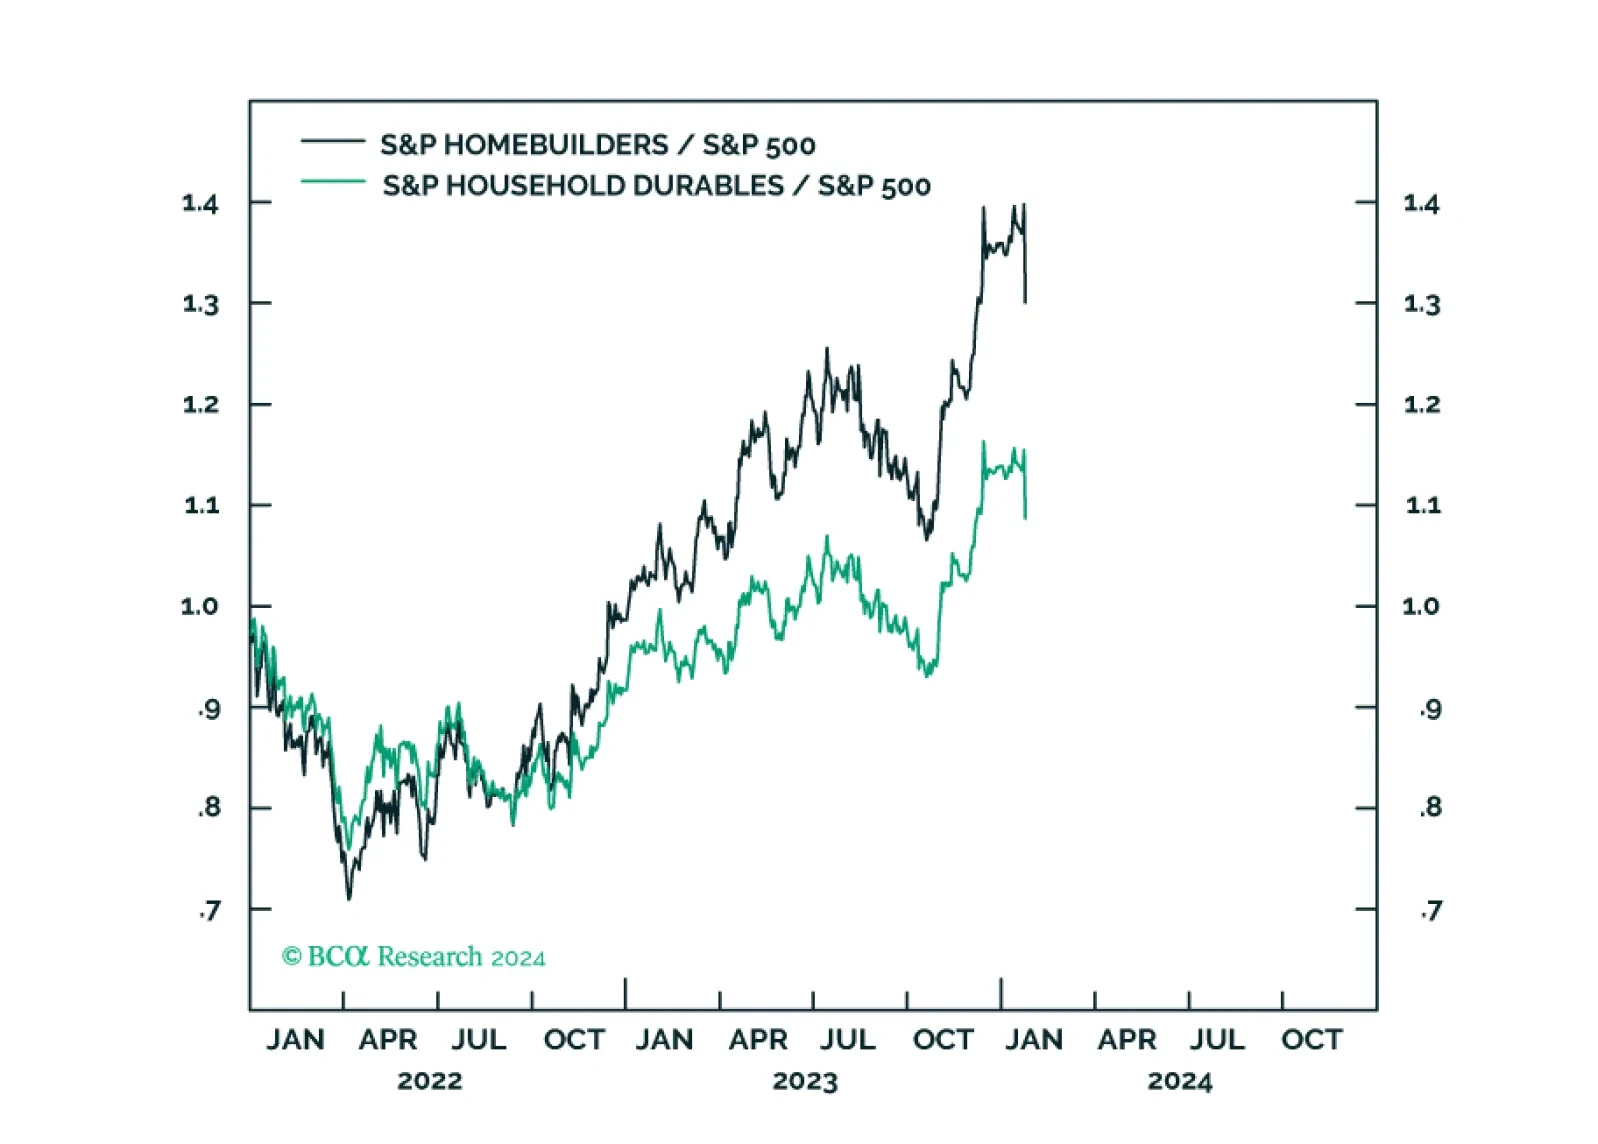
After months of strong performance, Homebuilders and Durable Goods have become crowded trades and are prone to disappointment. We are booking profits and downshifting to a neutral position.
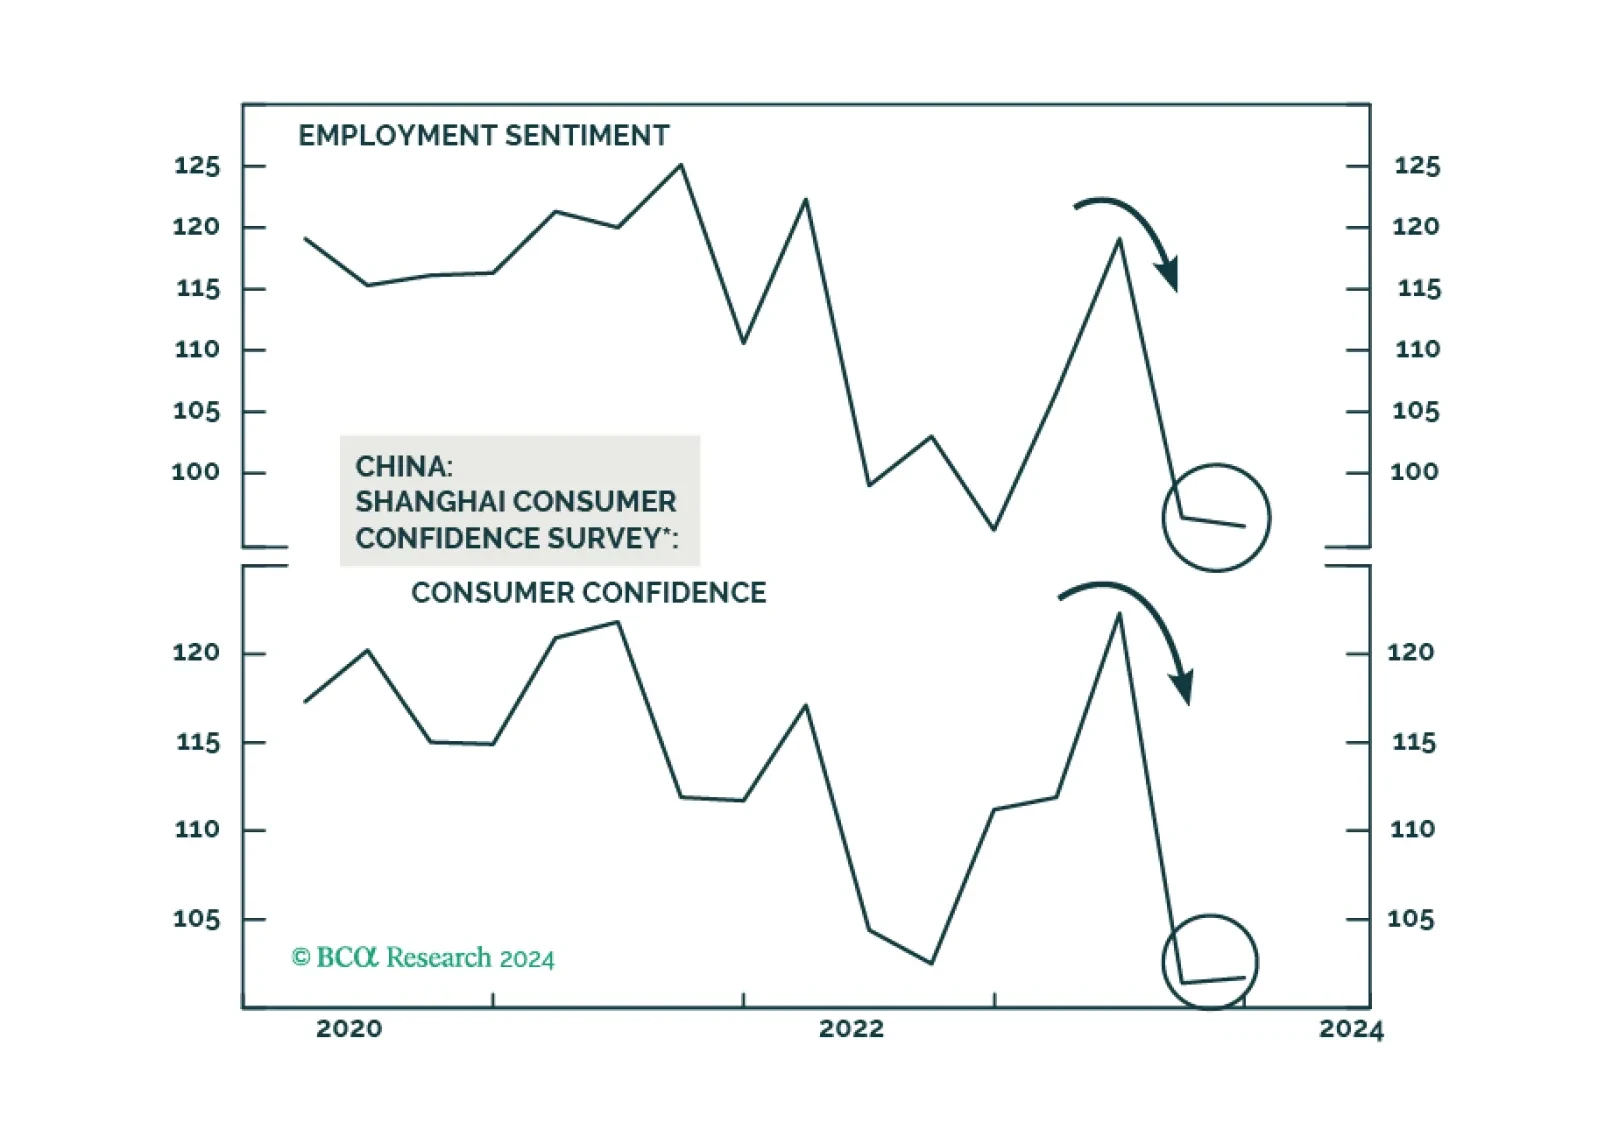
There is no easy way for China to forestall deflation. Provided policymakers are still reluctant to unleash large-size stimulus, more economic disappointments are likely in the coming months, and Chinese stocks will continue to sell off. The yuan is at risk of further depreciation versus the US dollar.
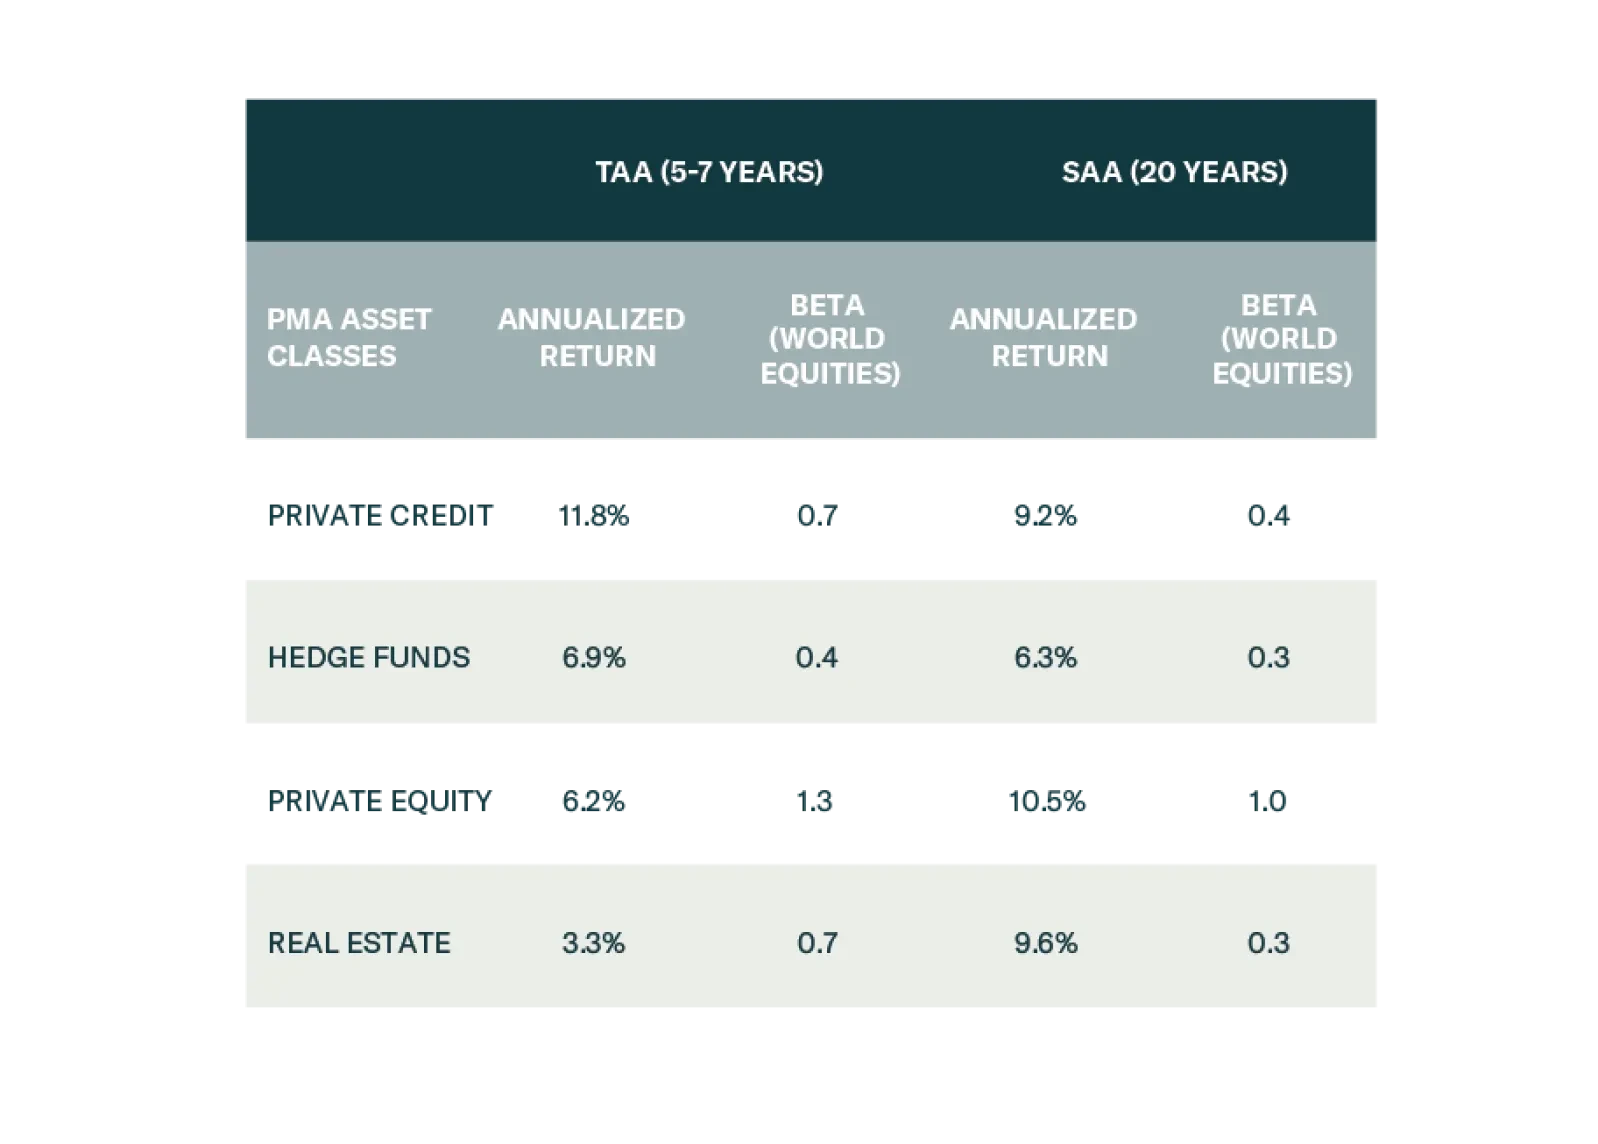
Investors should be tactically tilting allocations towards Direct Lending, Distressed Debt, and Directional Hedge Fund strategies at the expense of Real Estate, Private Equity, and Diversifier Hedge Funds. Structural opportunities are emerging in Real Estate and Venture Capital.