Latest from BCA Research

Fears of a hard landing are abating as growth has been surprising to the upside. New worries are emerging, such as the trajectory of disinflation, and the pace and timing of rate cuts. In this environment, it is important to build a resilient all-weather portfolio, which protects against a correction, rising rates, or stubborn inflation but also has exposure to the AI theme.
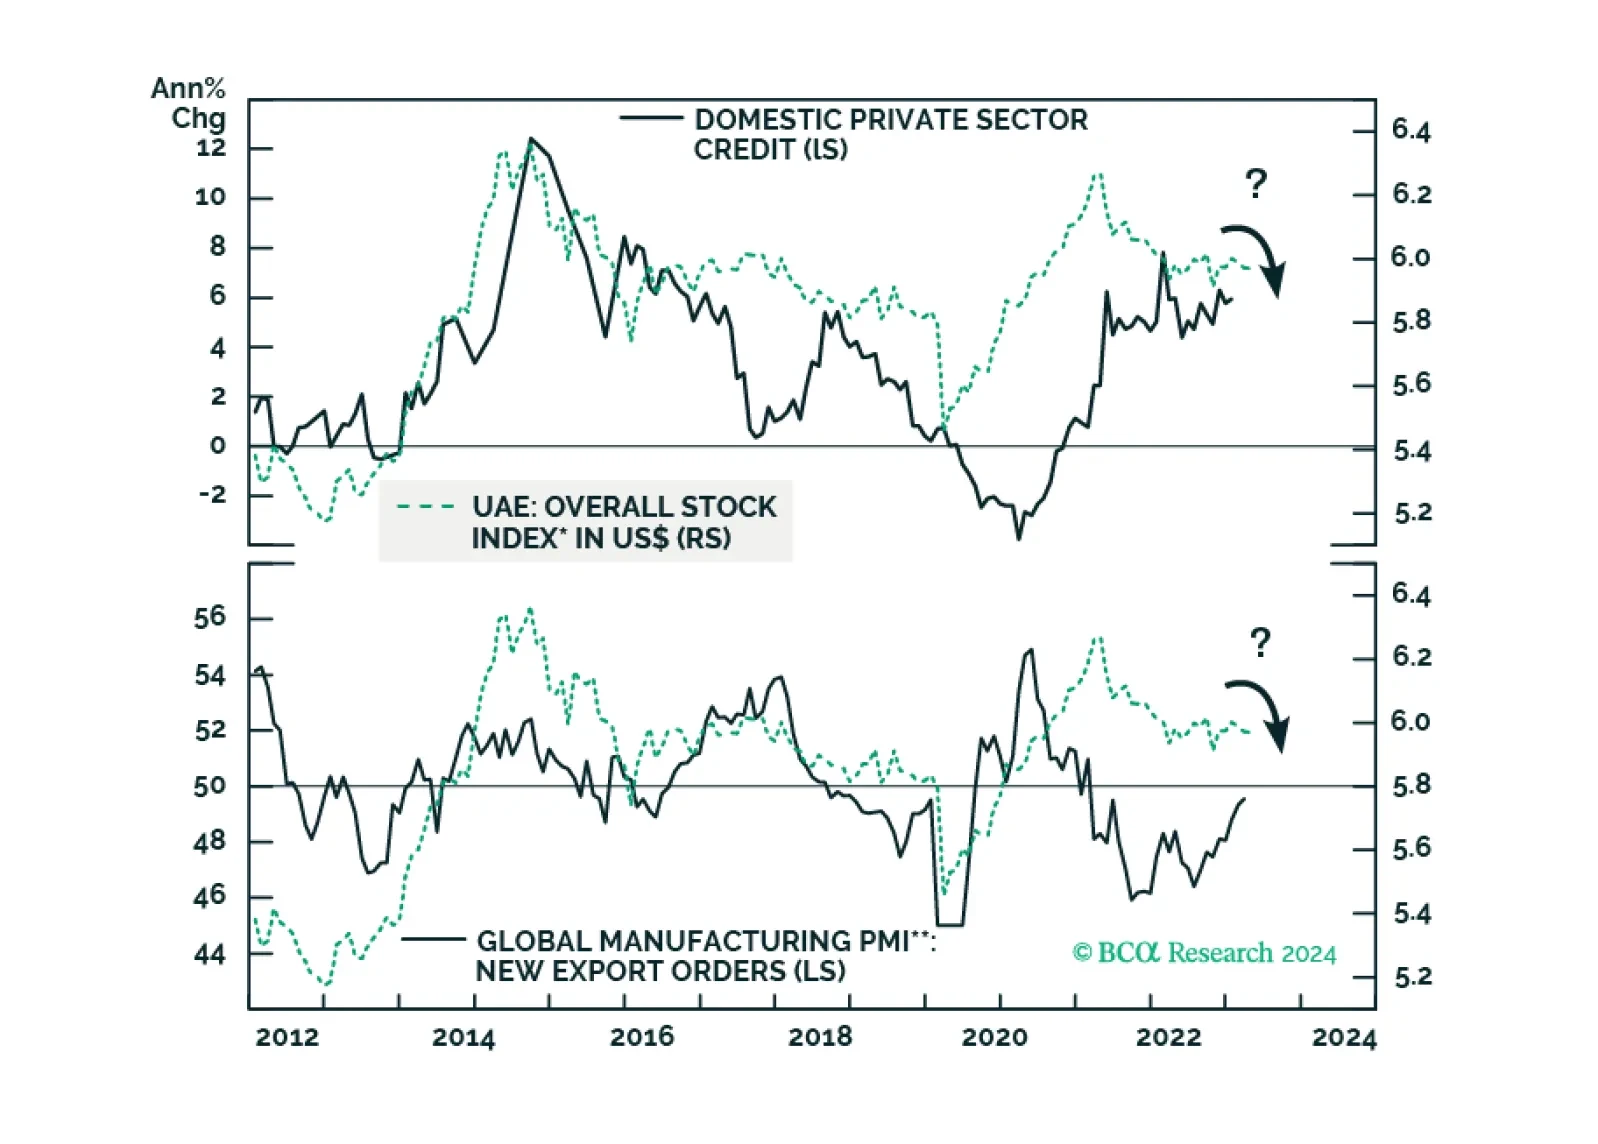
Subdued credit growth and weak global trade will remain headwinds for Emirati stocks. Surging property prices, which have led to a boom in real estate stocks, will also peak soon. Stay neutral on this bourse. Sovereign credit investors, however, should stay overweight UAE in EM credit portfolios.
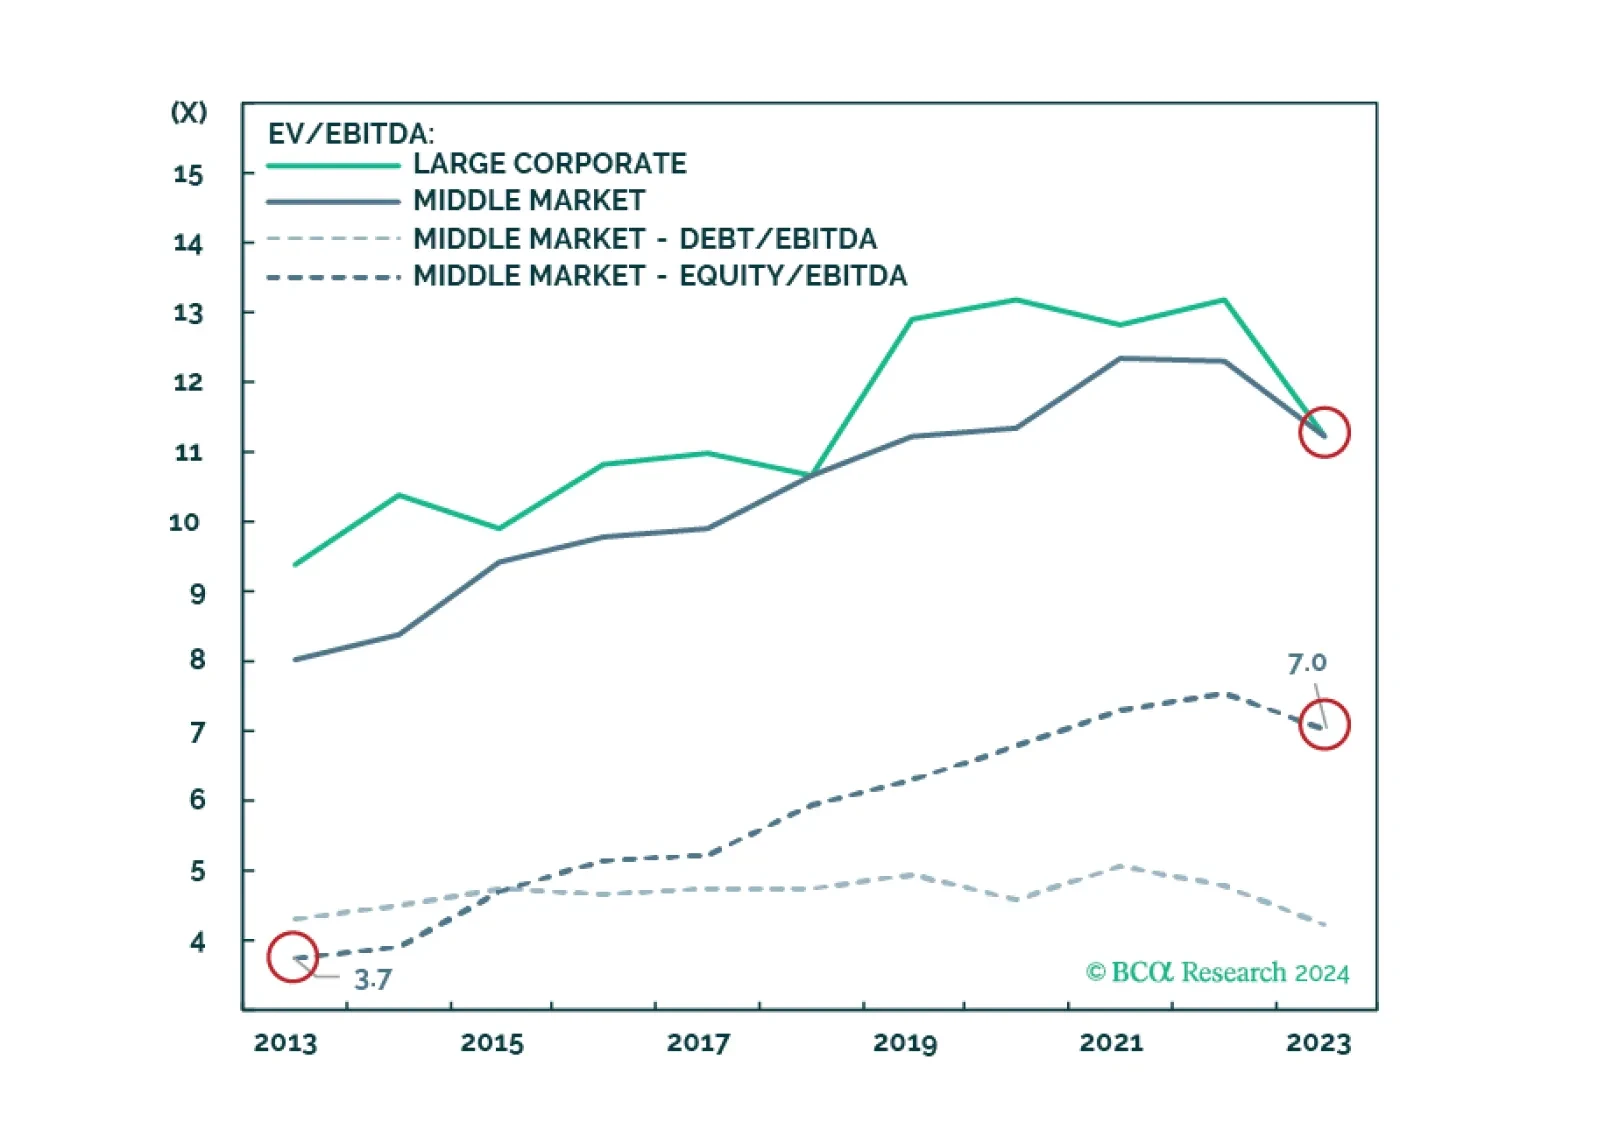
Valuation metrics in Private Equity and Venture Capital vary widely by source, stage, location, and other factors. They are prone to imprecision, which is why investors should monitor a diverse set. This report offers a series of charts comparing valuation ratios. Focusing solely on valuations reveals that North America Middle Market Buyouts appear less attractive and geographical selection will be more important going forward.
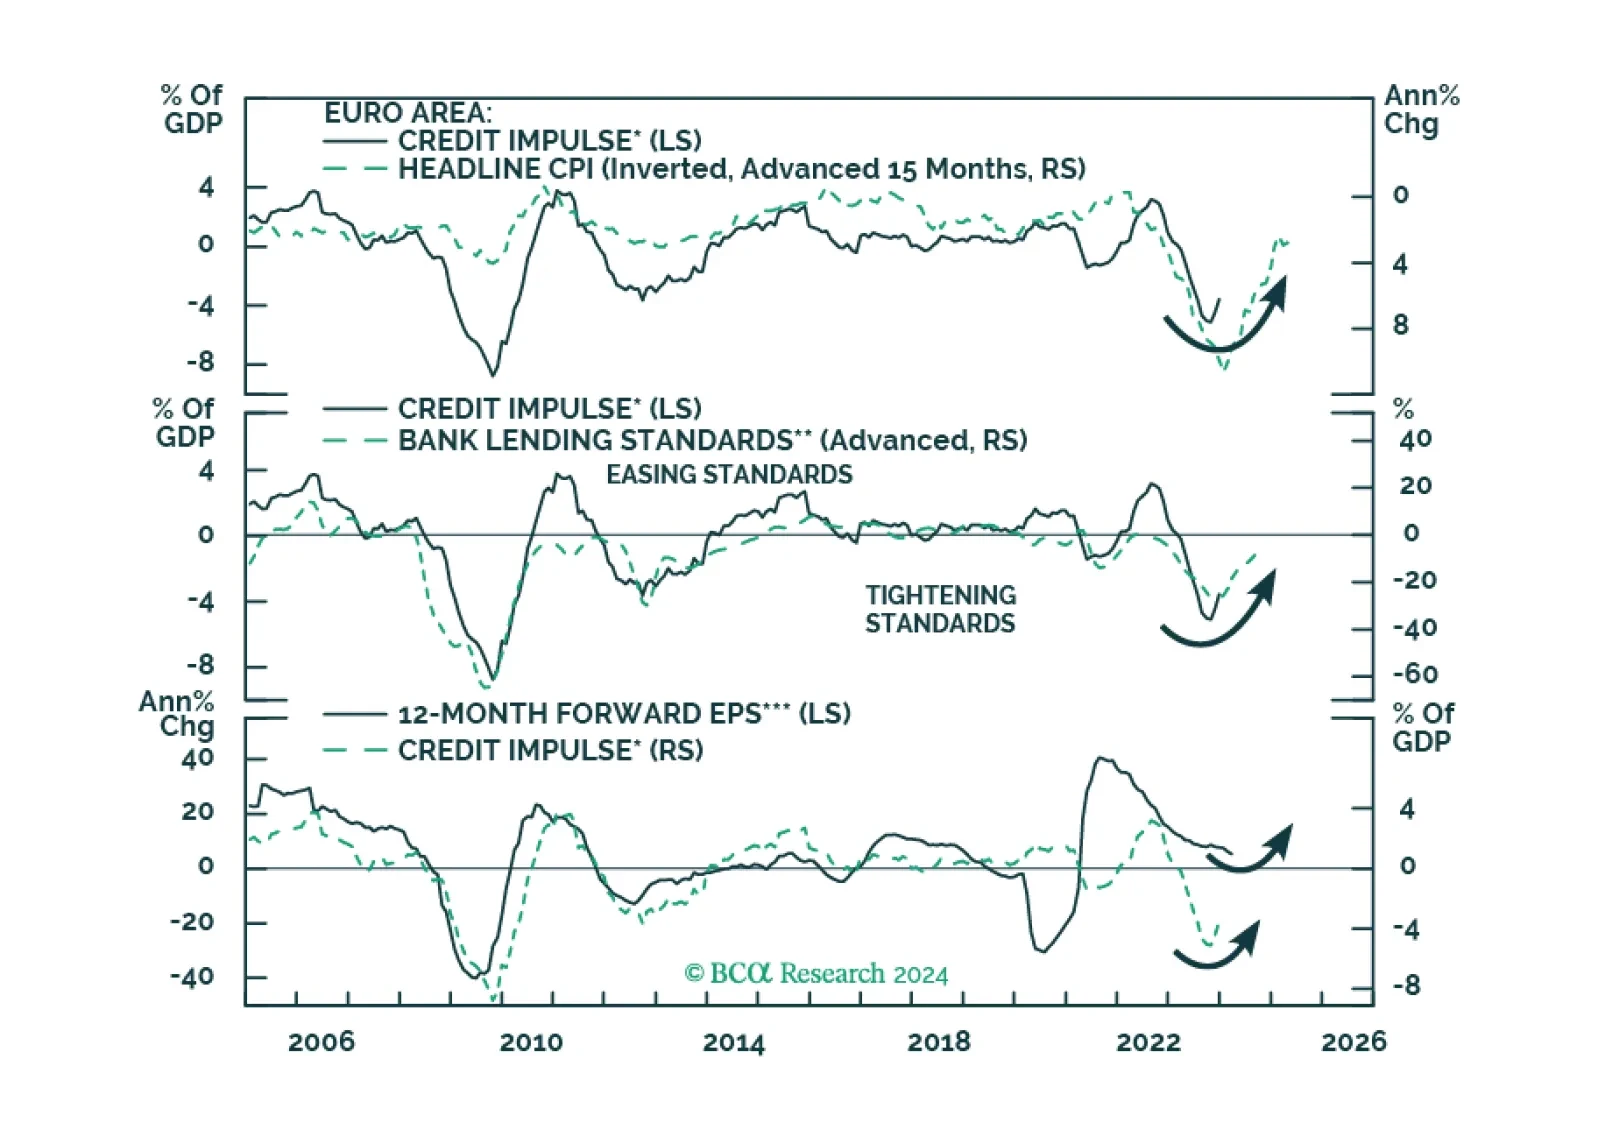
Europe credit flows are stabilizing, hence a major drag on the region’s growth will dissipate. What does this development imply for European equities?
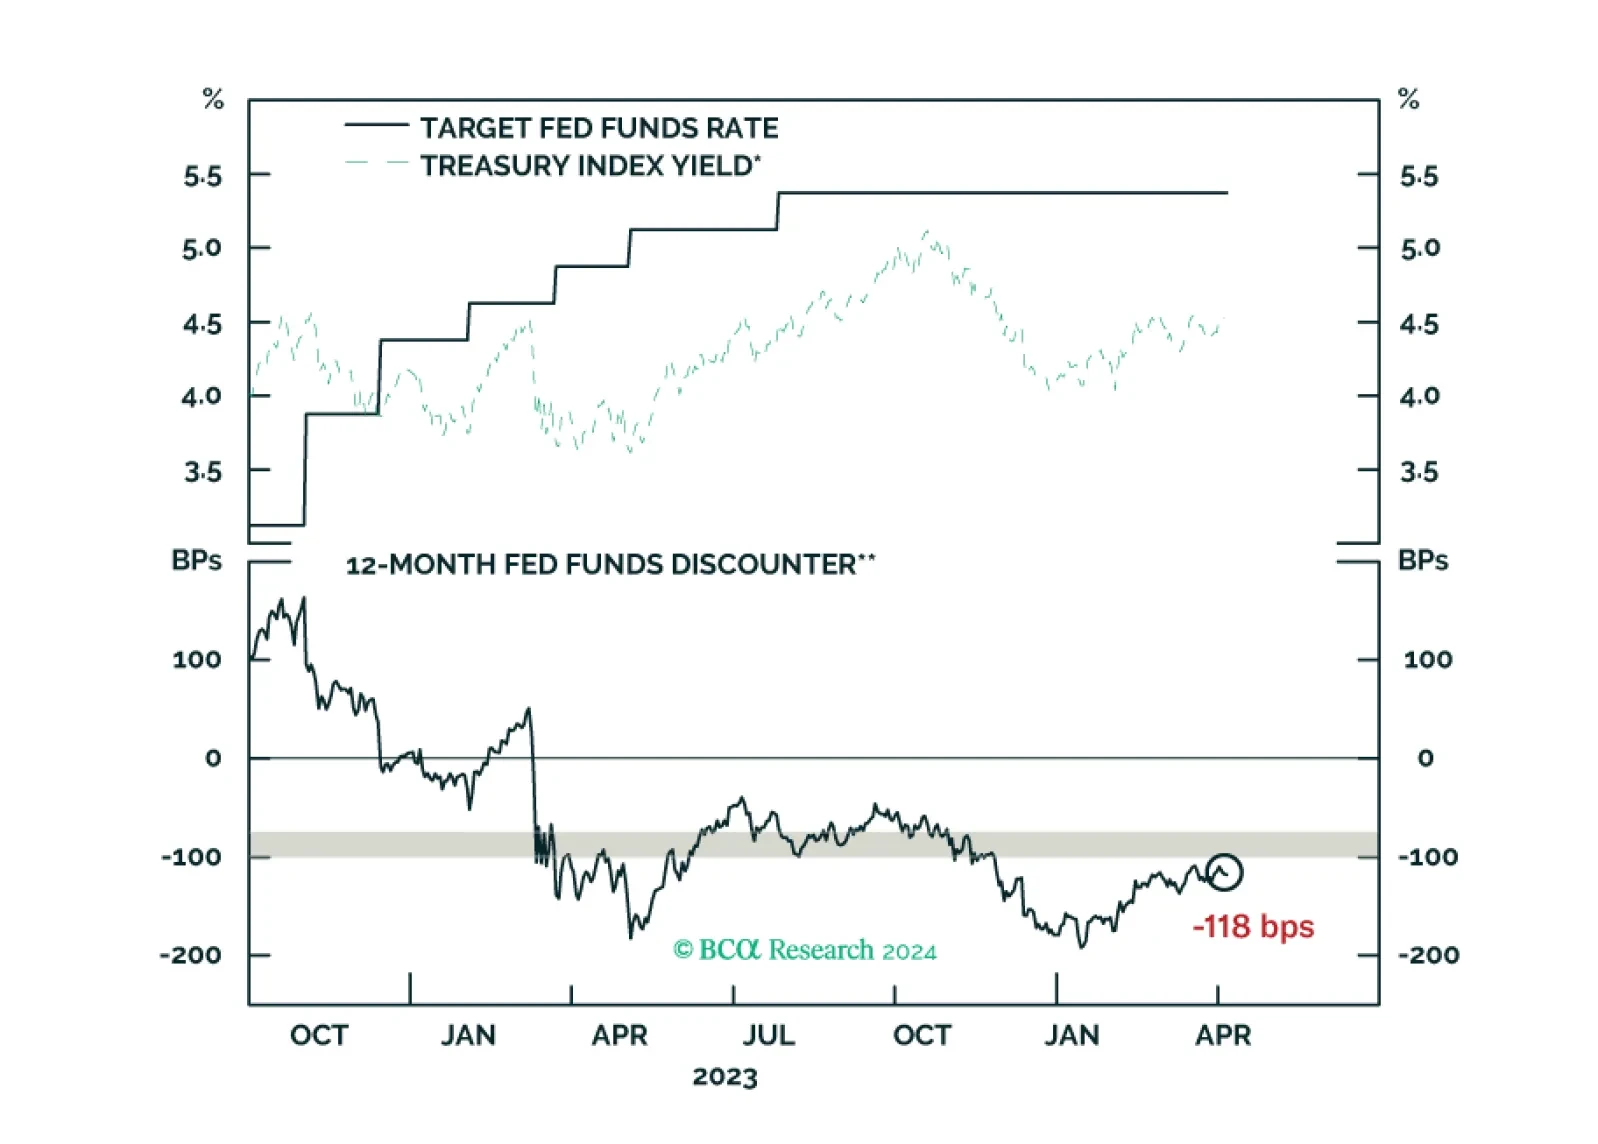
Our reaction to this morning’s employment report and bond market moves.
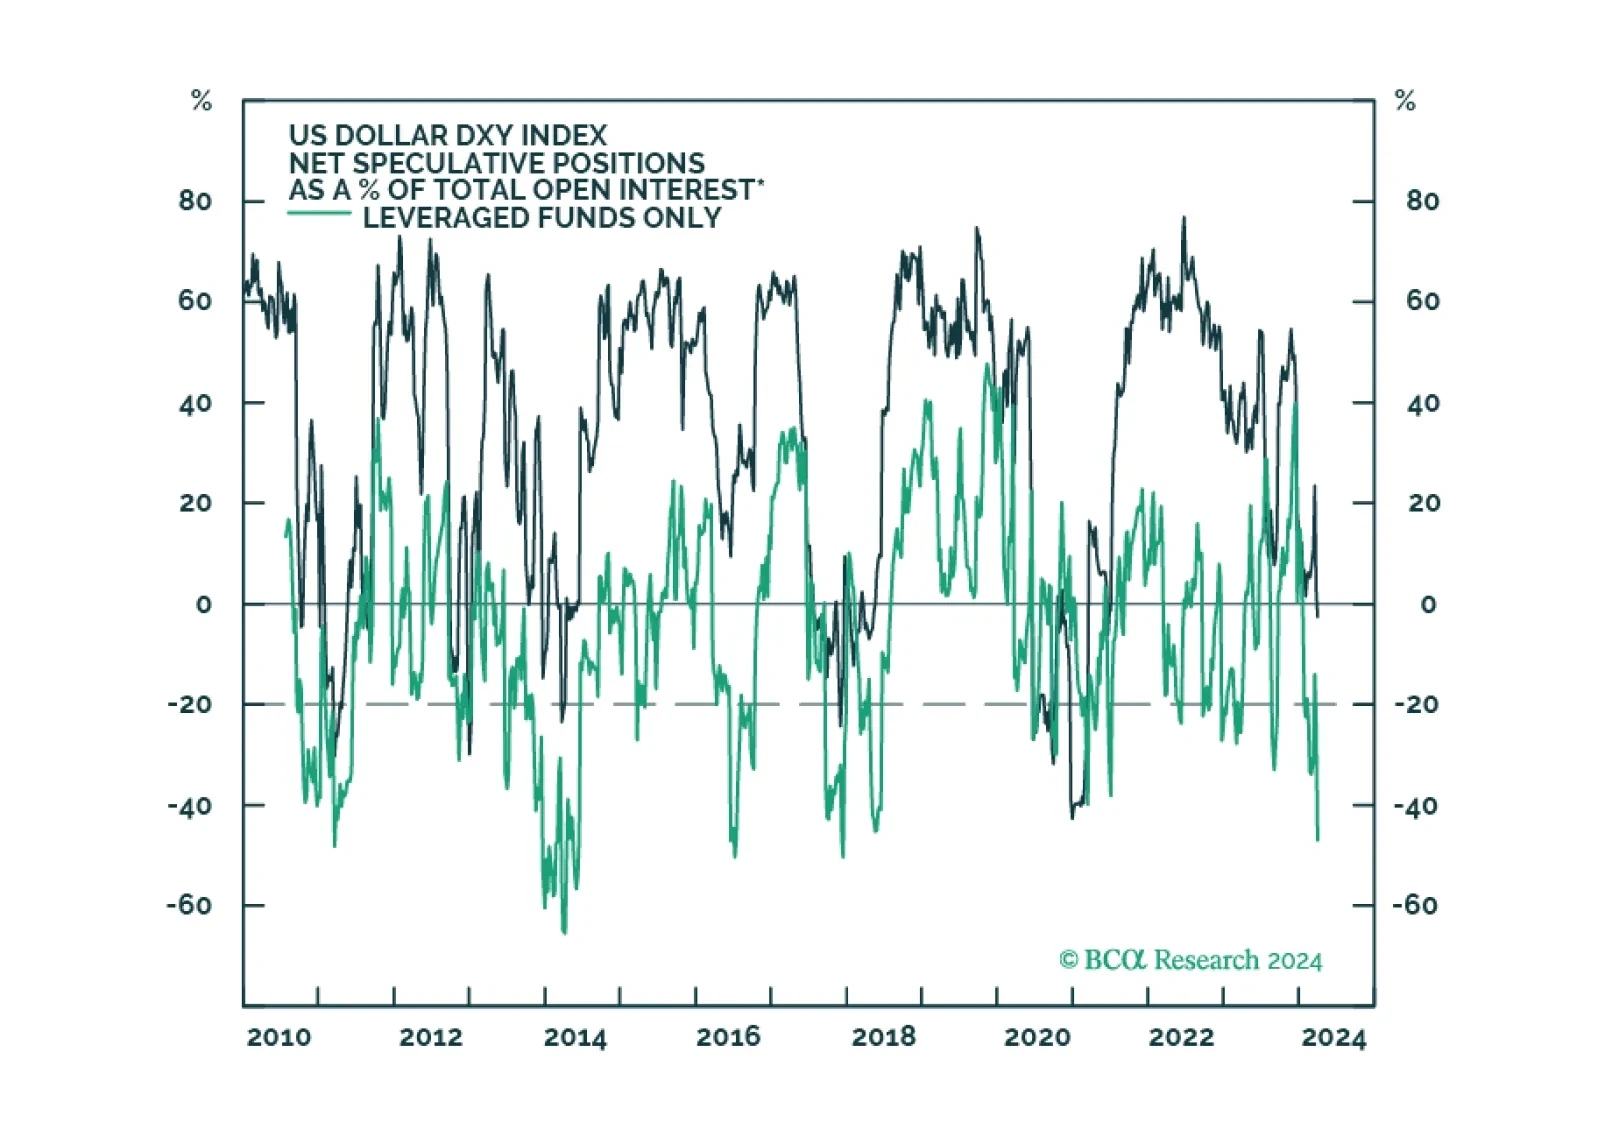
In this report, we review our trade recommendations based on incoming data in the last month.
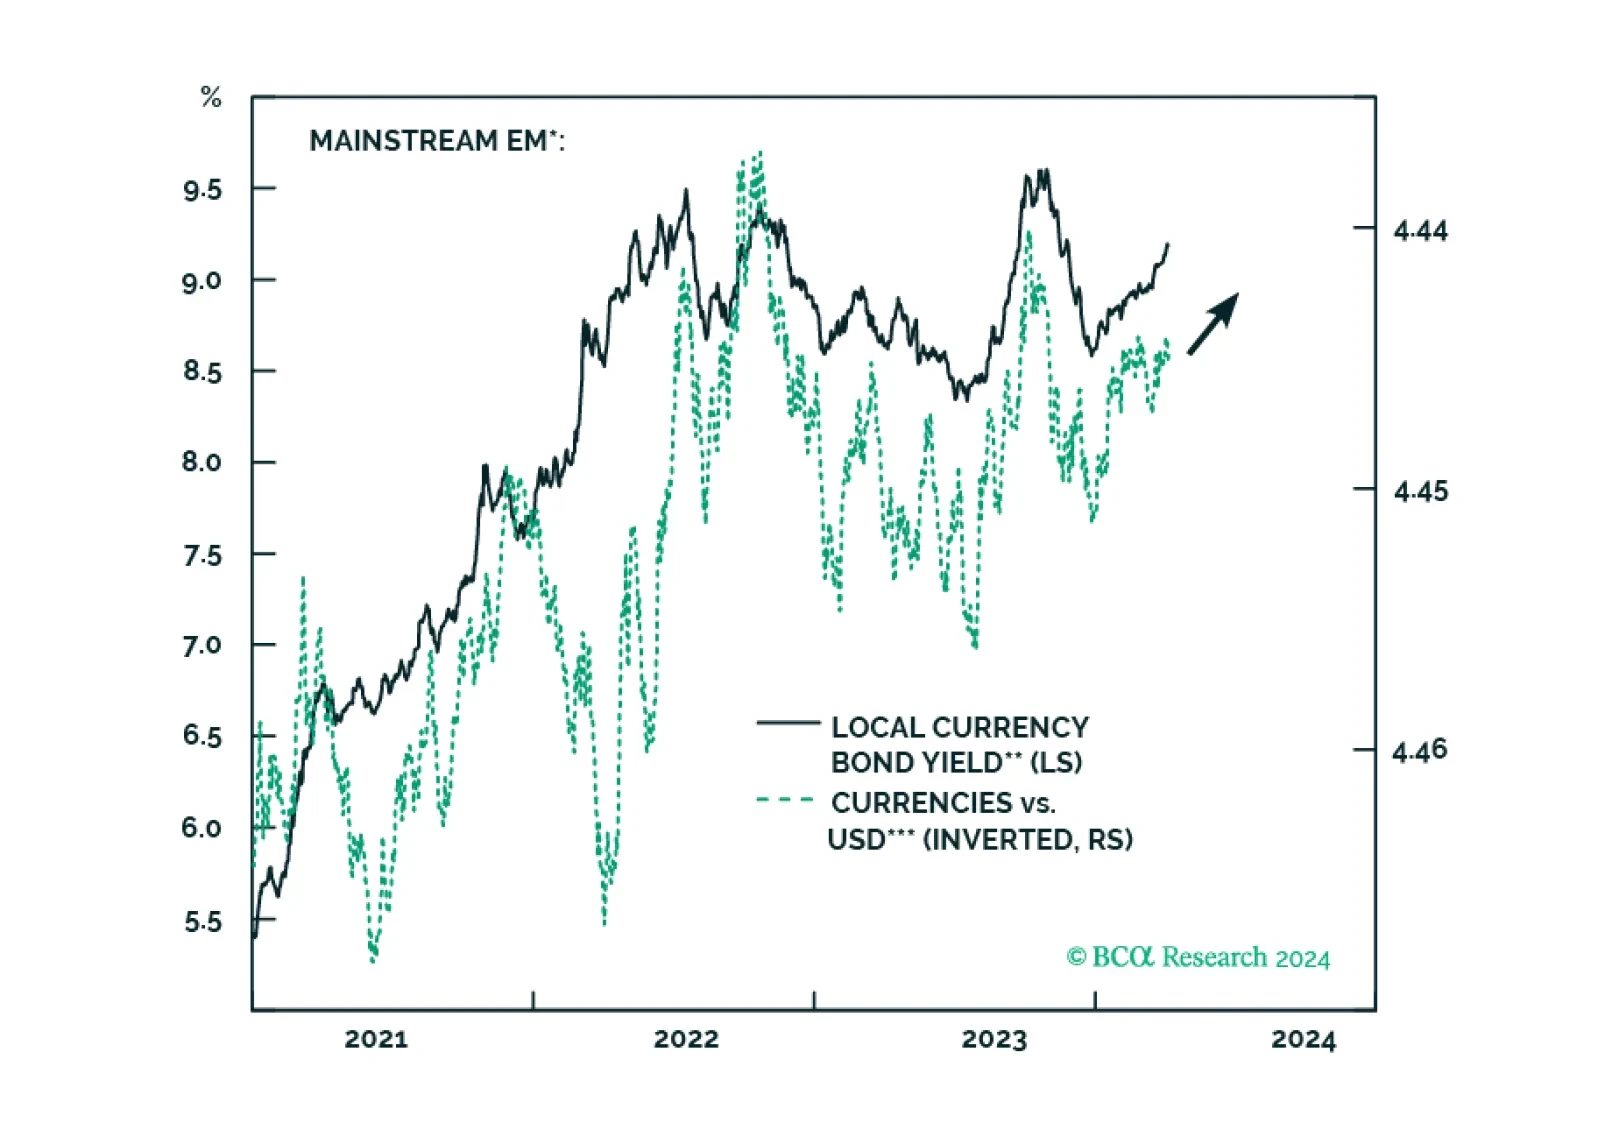
Climbing US bond yields, alongside higher oil prices, might spoil the party for global risk assets. There are budding cracks in EM domestic bonds, and even though we like this asset class in the long run, investors exposed to it should reduce their positions for now.
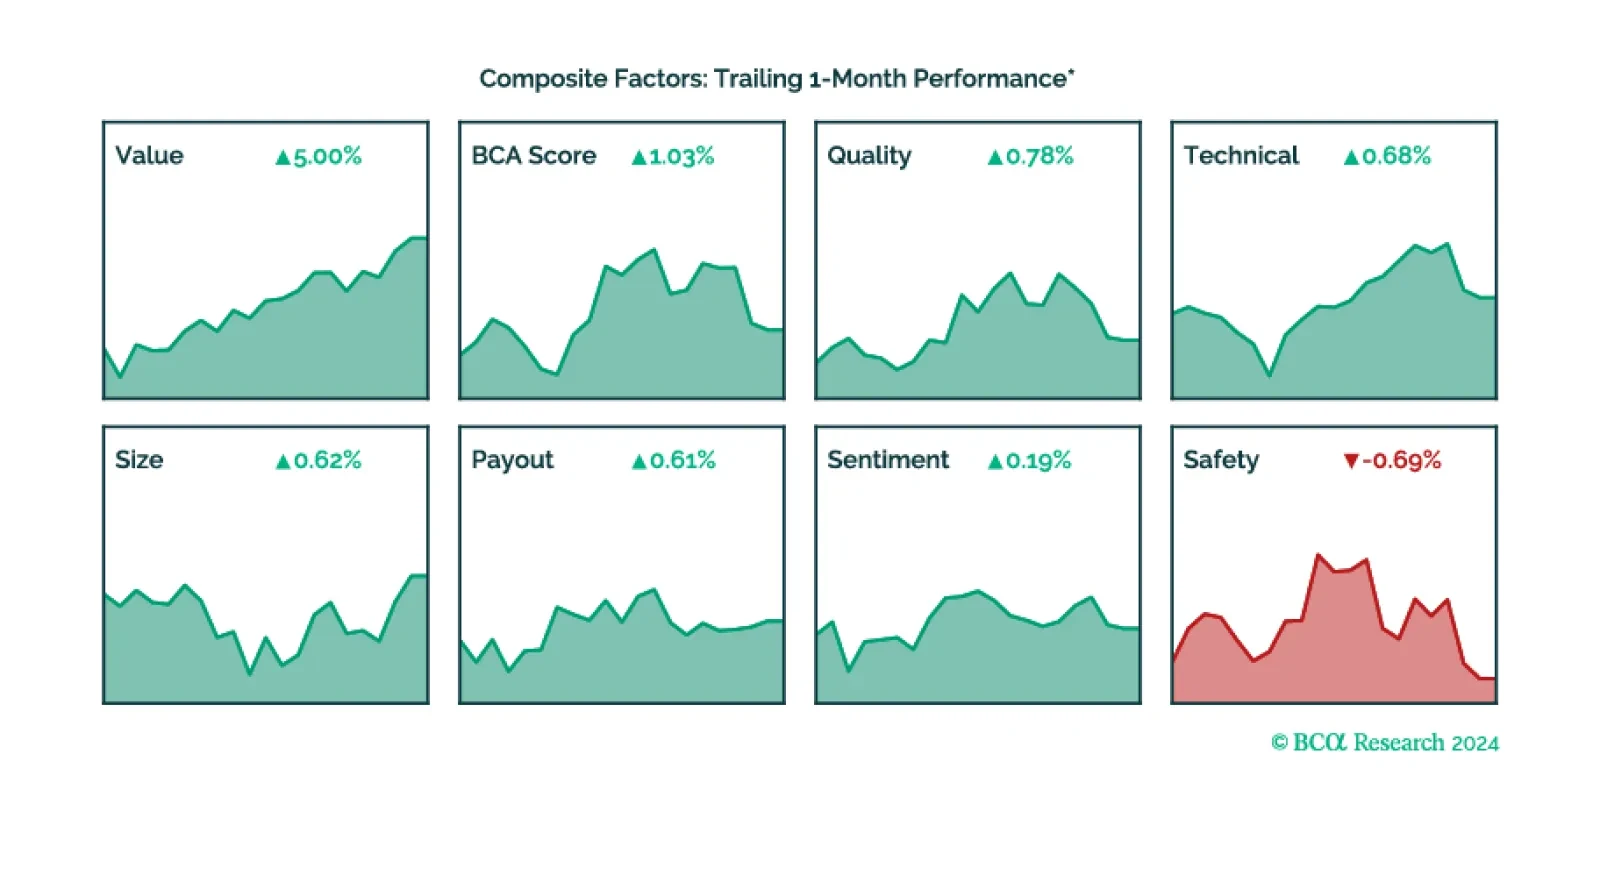
The BCA Score L/S posted a positive return in March with the Value factor leading the way.
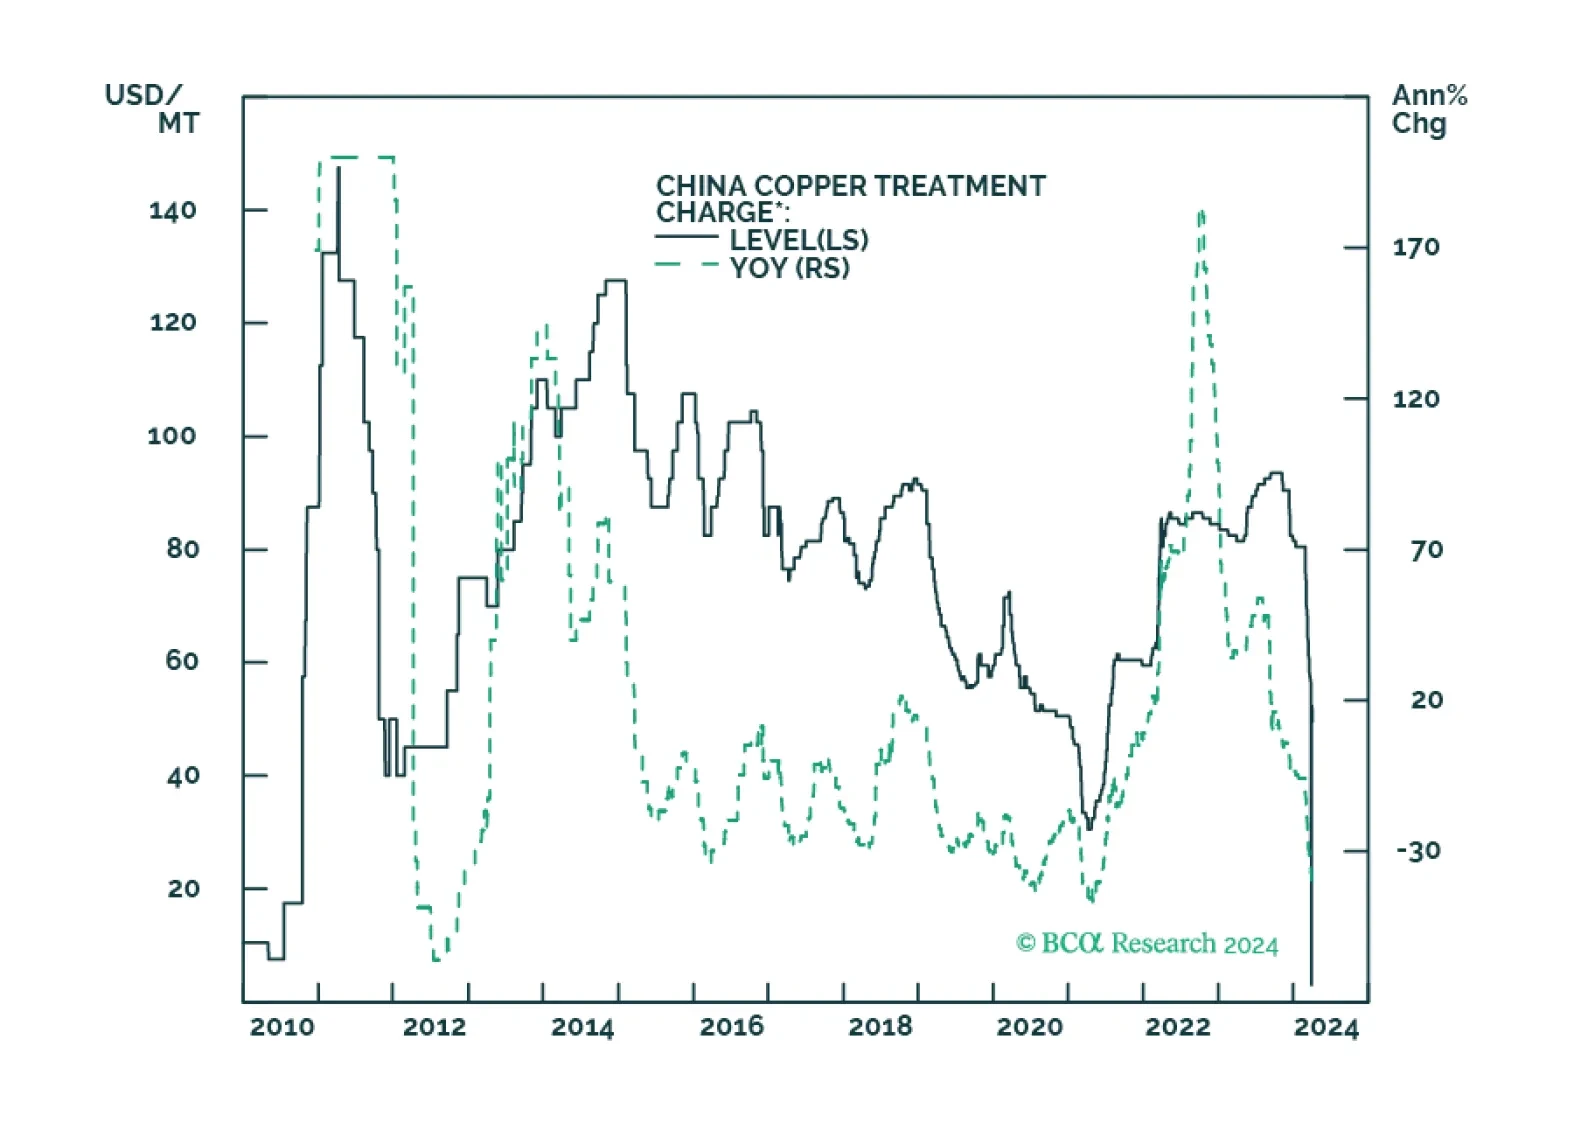
Copper markets are fast approaching a price breakout, as Chinese smelters scramble to find ore to meet increasing refined-copper demand in the wake of a global manufacturing rebound. We are holding fast to our expectation of $4.50/lb (COMEX) this year. We remain long the XME ETF to retain exposure to copper miners and refiners, and the COMT ETF to retain exposure to commodity flat price and the copper backwardation we expect.
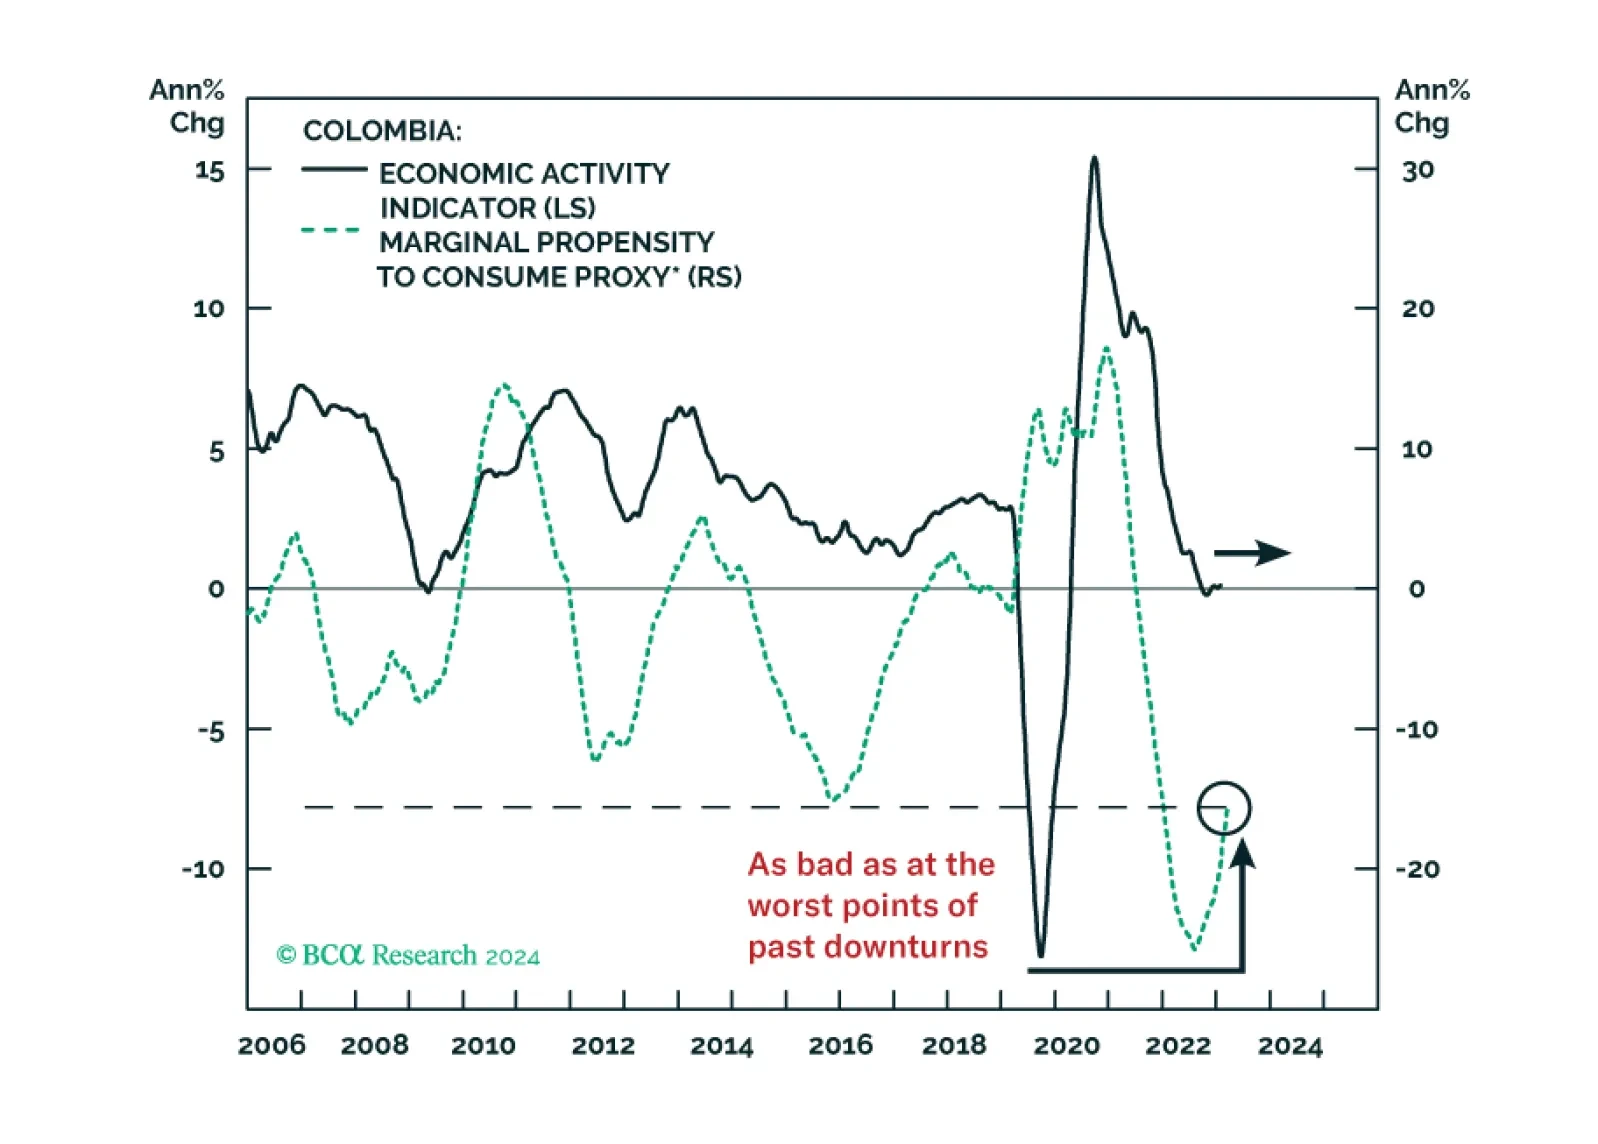
Colombia has fallen from grace in terms of its healthy macroeconomic fundamentals, business-friendly government policies, and conservative fiscal stances. The economy is experiencing stagflation, public finances are deteriorating rapidly, and political uncertainty will persist. Underweight Colombia across all financial markets relative to their EM benchmarks, and short Colombian bank stocks and the currency versus their Chilean counterparts.