Latest from BCA Research
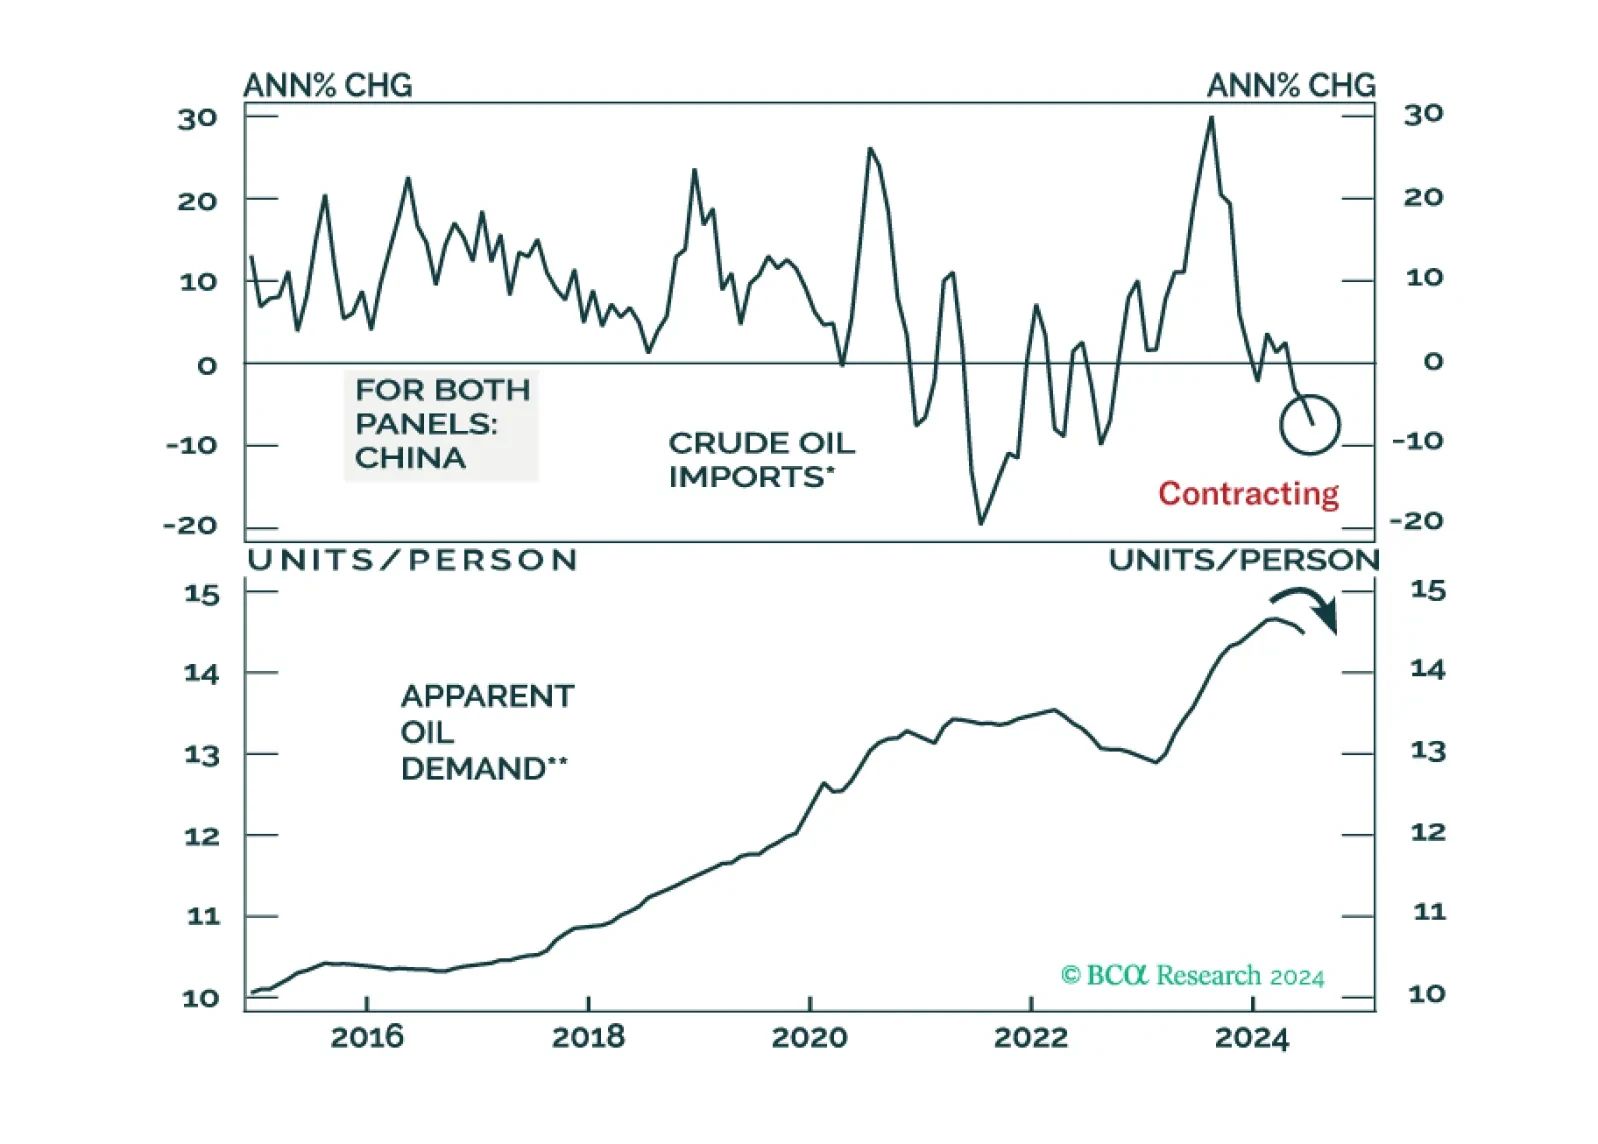
Oil prices are caught in a tug-of-war. Concerns about the demand outlook are acting as a price ceiling while the risk of a geopolitically induced supply shock is providing a floor. Prices are likely to remain rangebound over the near term. Yet the path of least resistance over a 6-to-12-month horizon is to the downside.
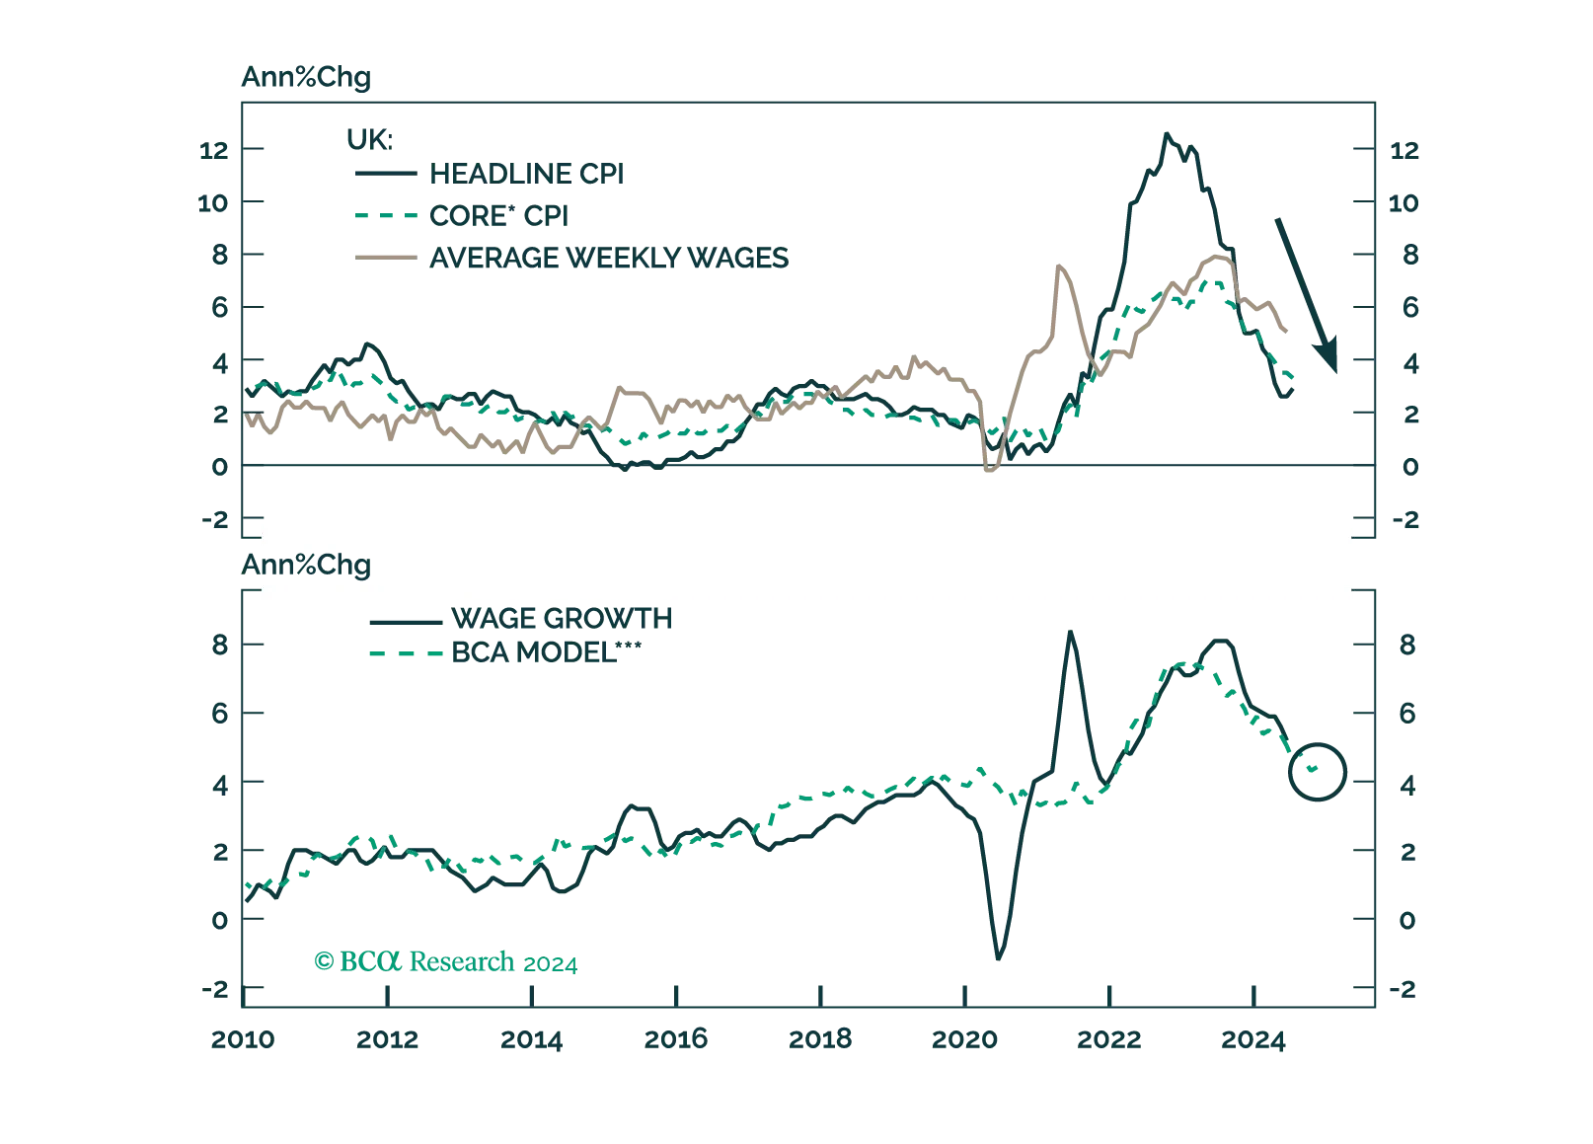
What do the mixed signals sent by the UK economy mean for the Bank of England, and what are the implications for Gilts and the British pound?
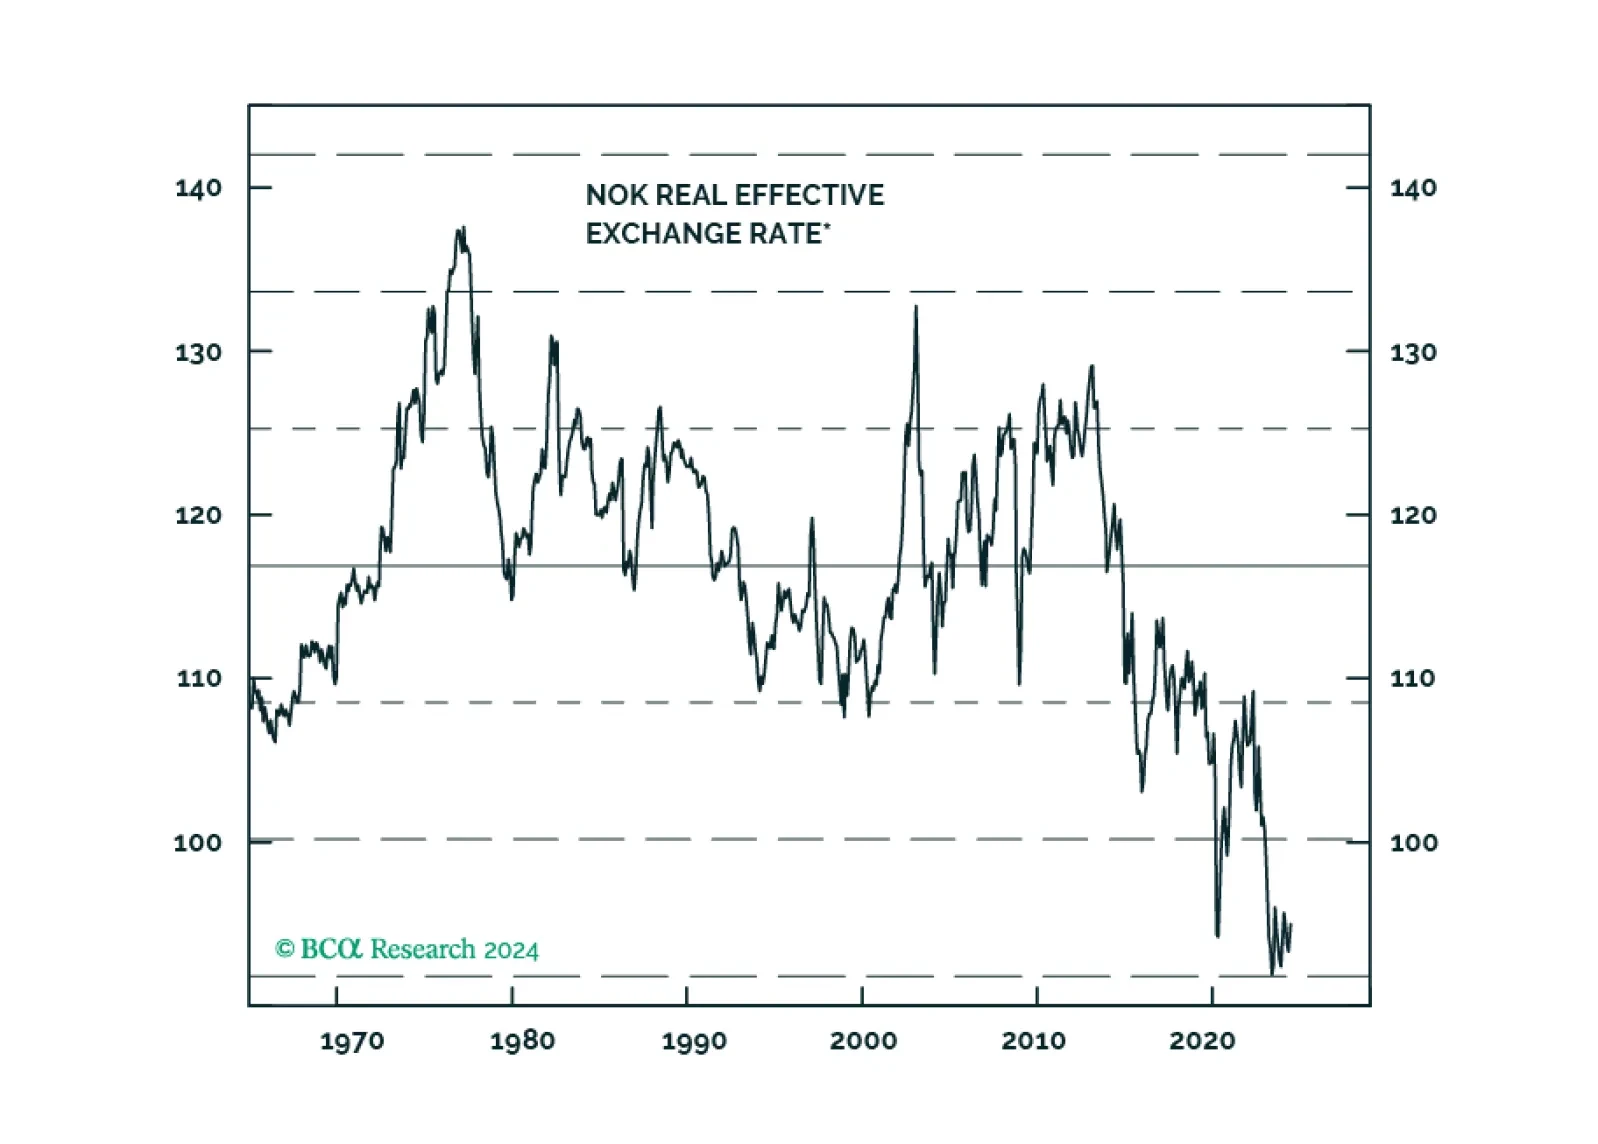
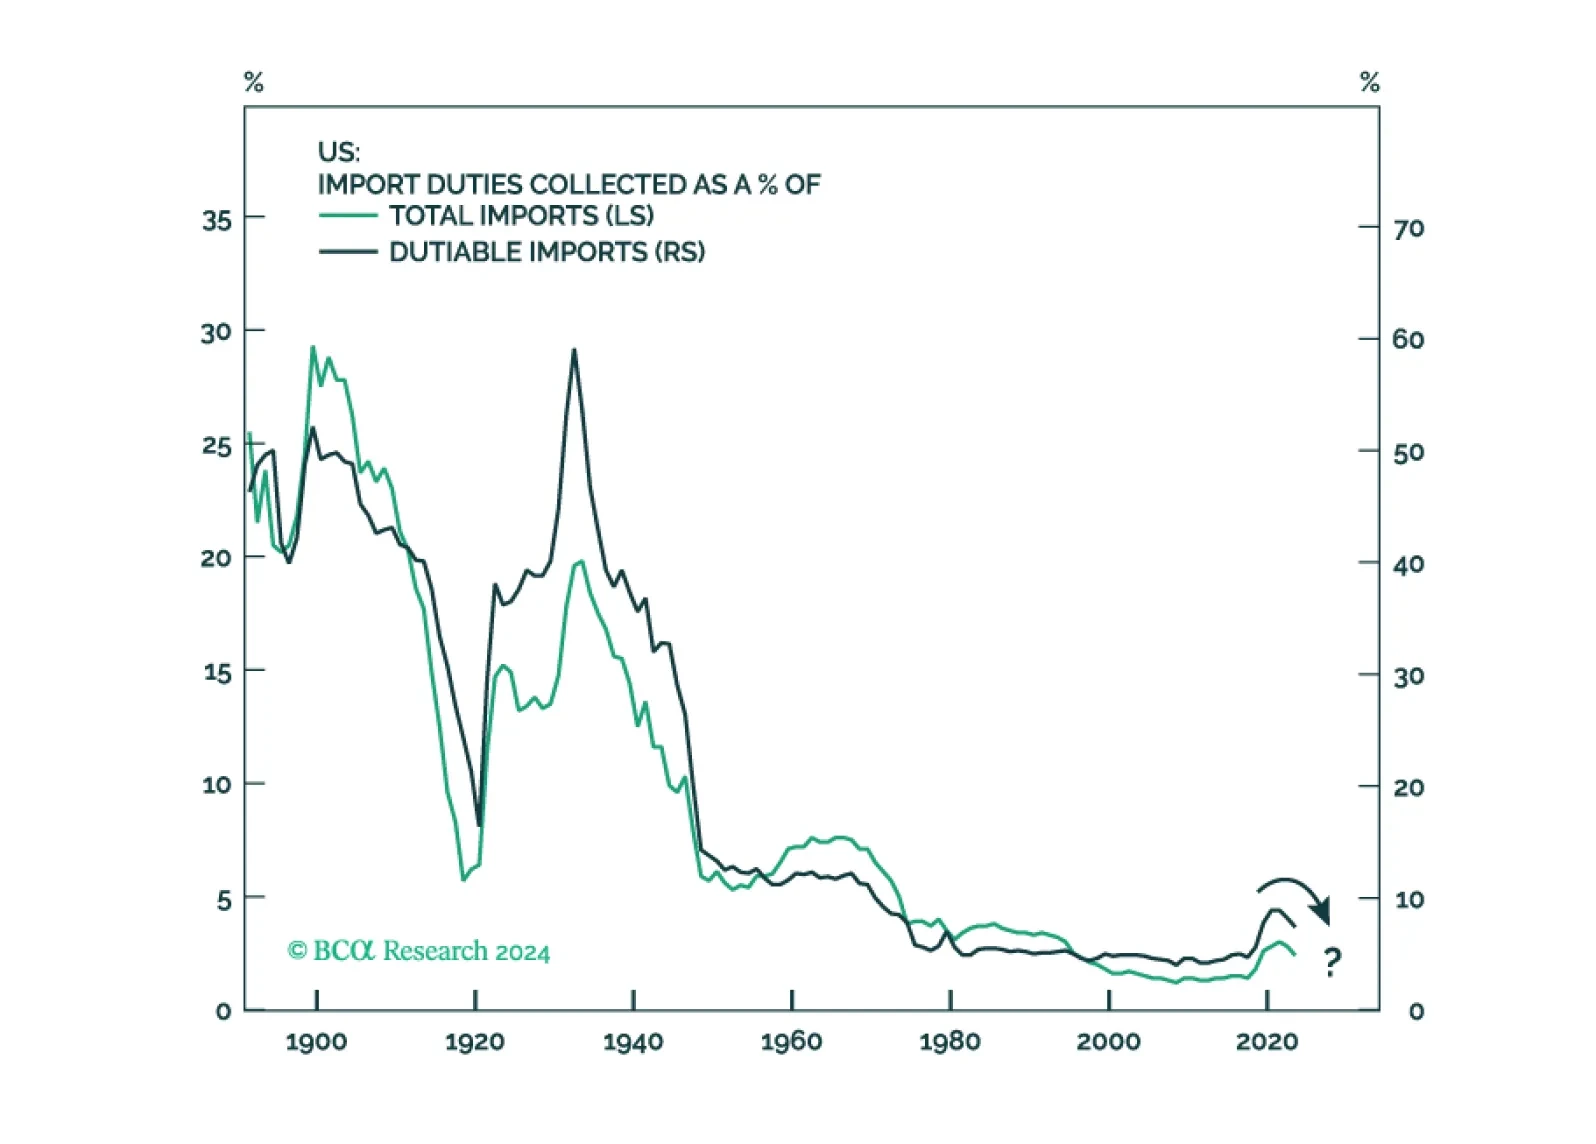

The current Fed easing cycle will likely be a “buy the rumor, sell the news” phenomenon. The basis is our expectation that the US economy is heading into a rough landing. The primary driver of EM currencies is not US interest rates but the global manufacturing cycle.
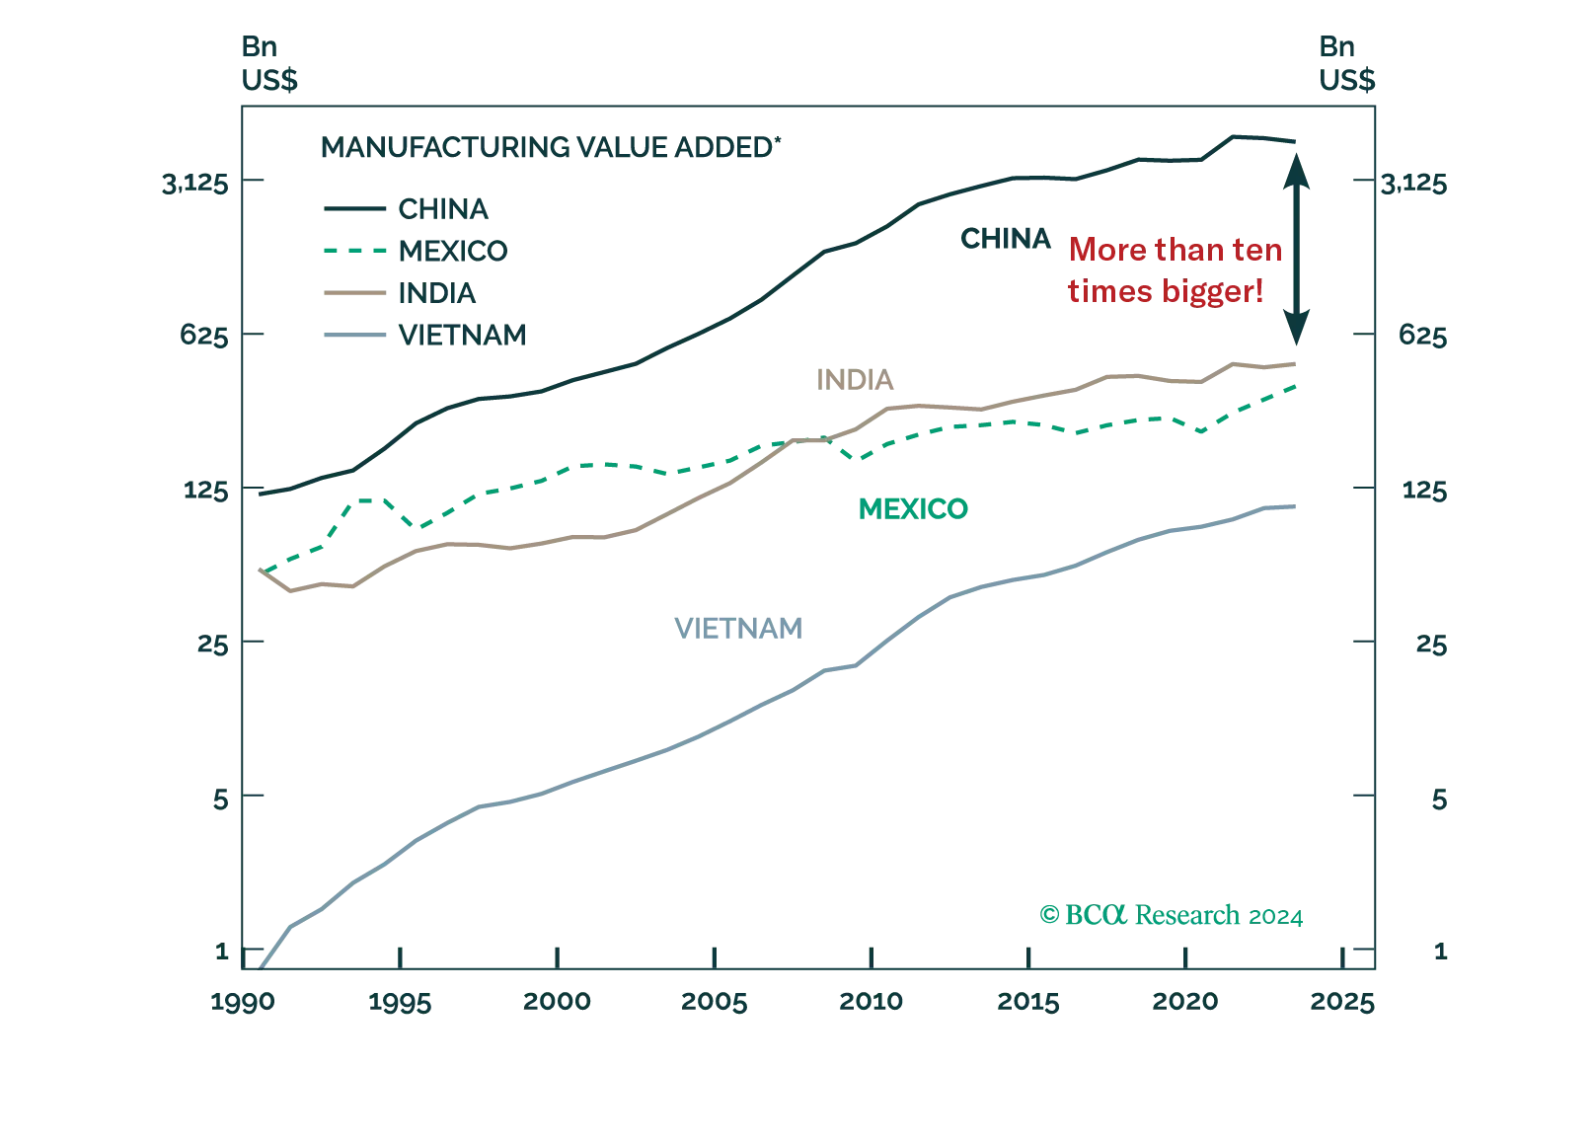
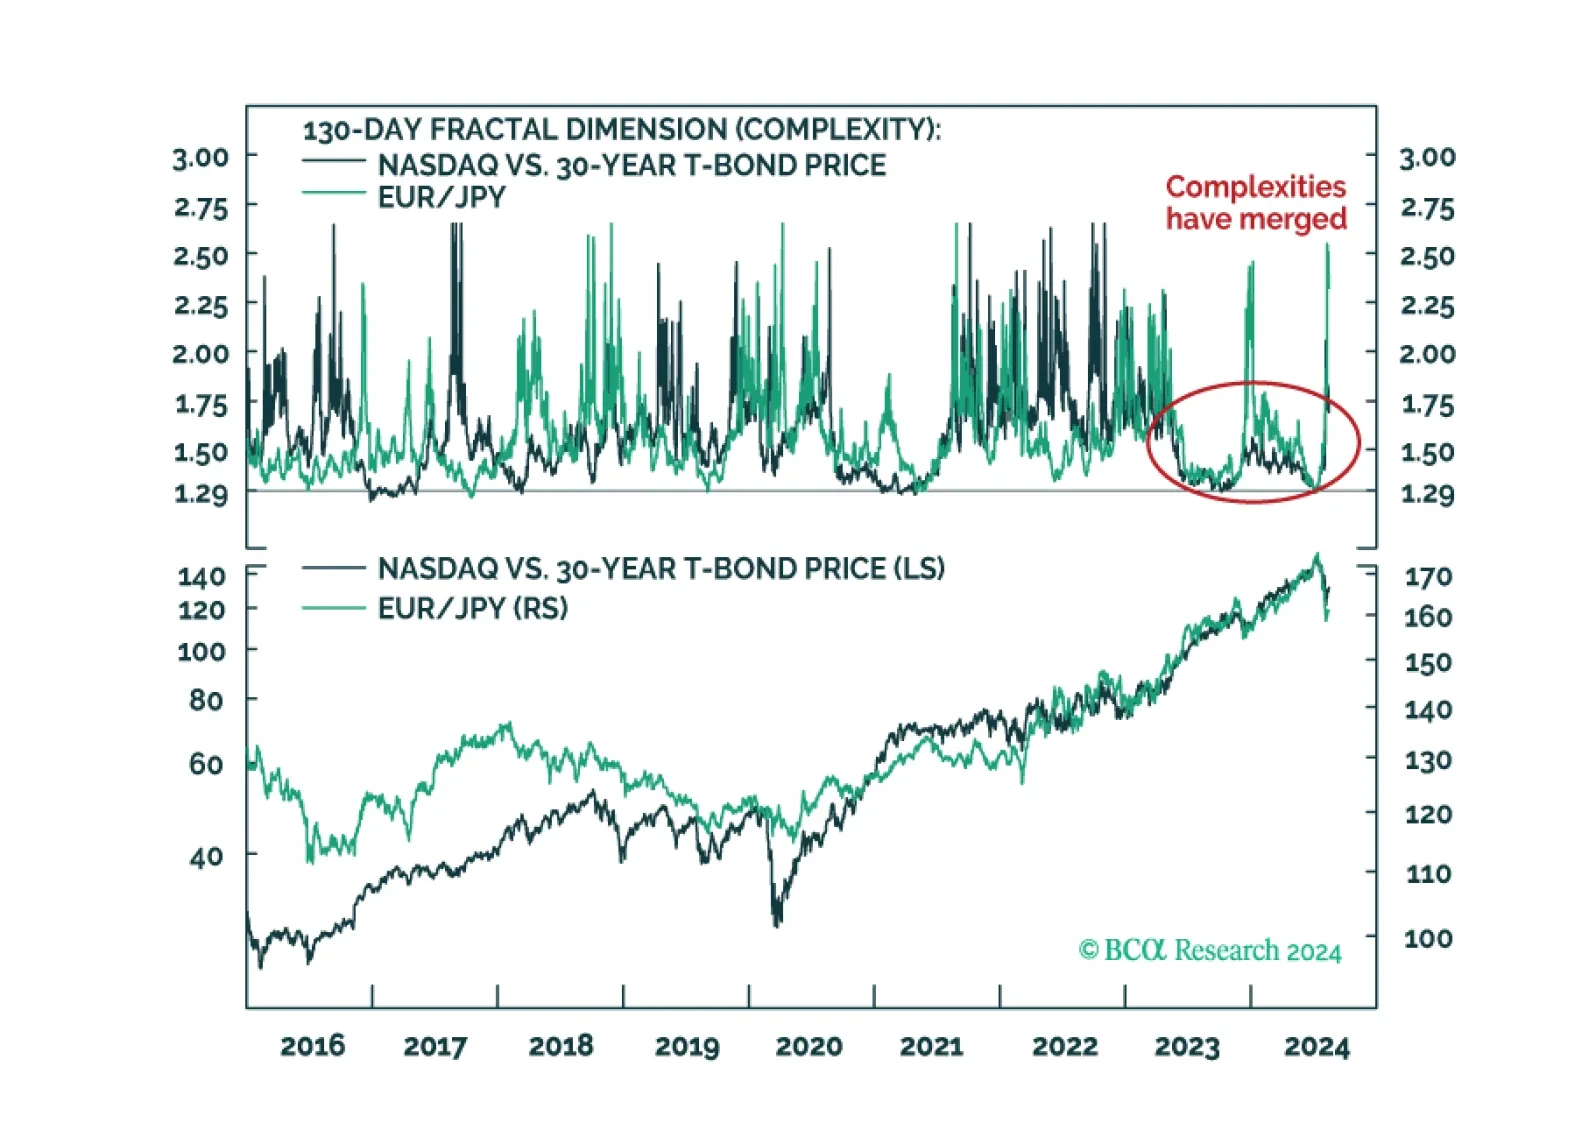
The analysis of price complexity strongly suggests that the ‘yen carry trade’ and the AI bubble are one and the same trade, and that the trade has further to unwind. Plus, go tactically overweight China (CHIQ).
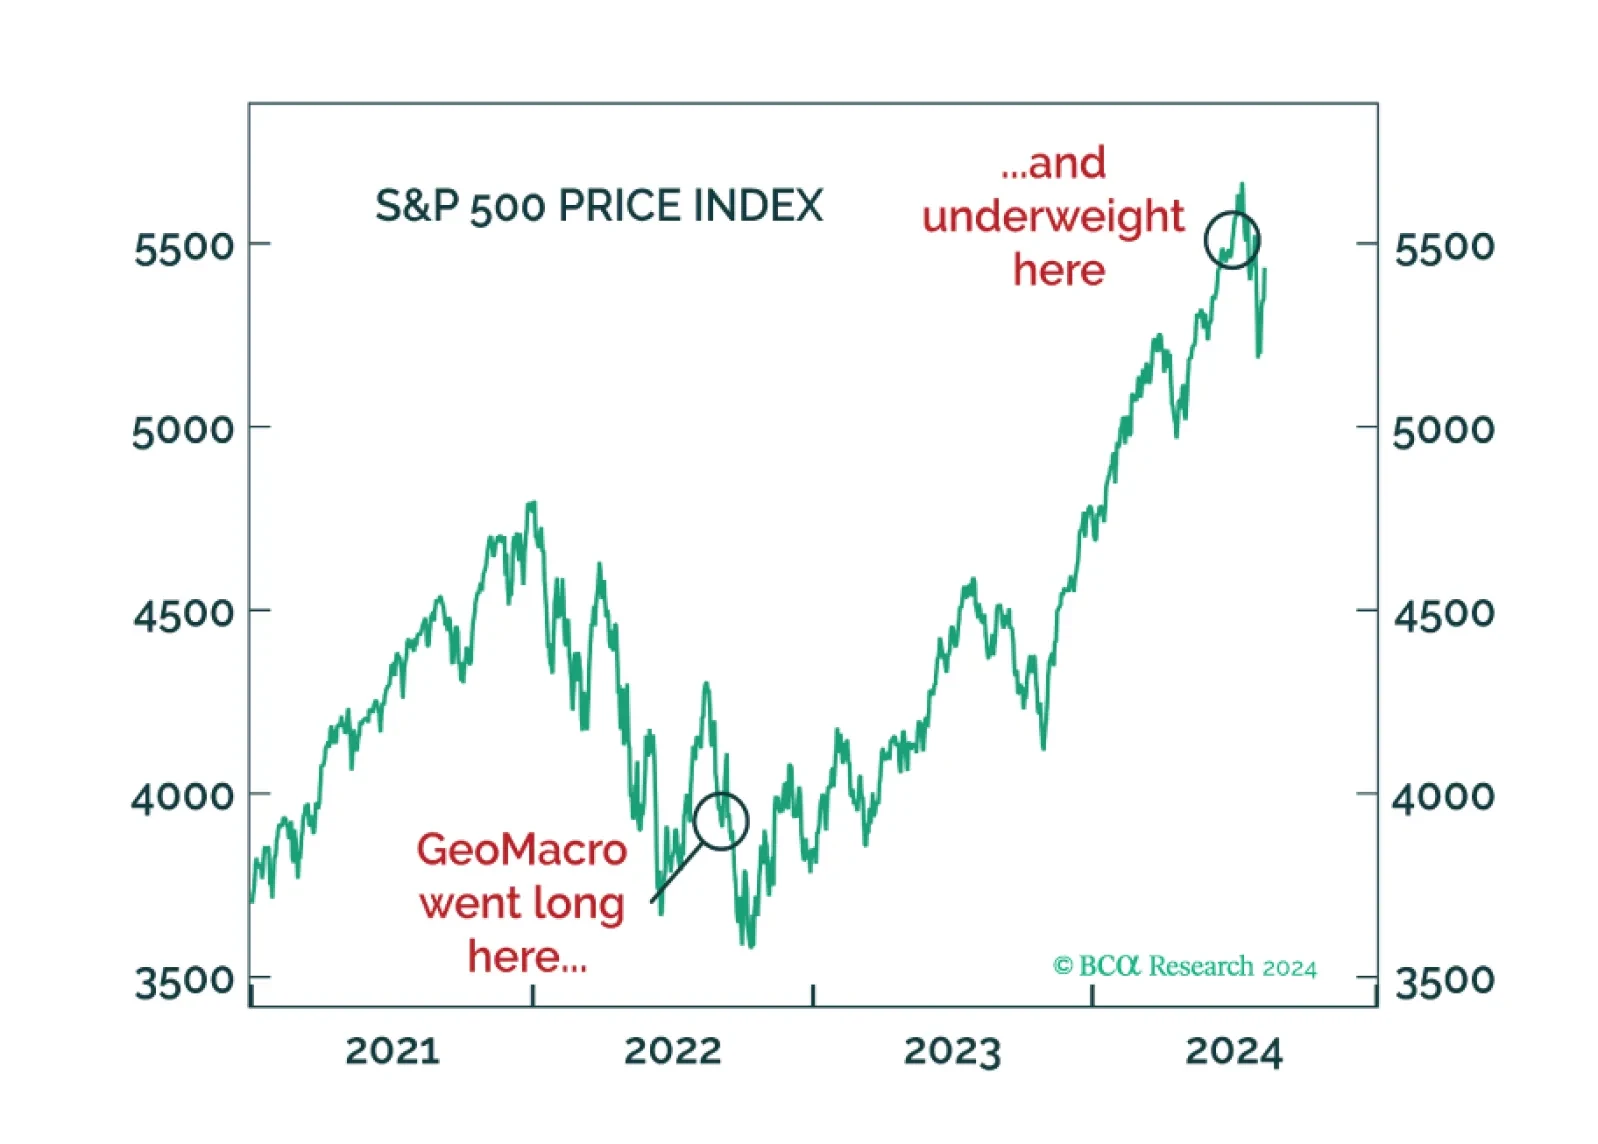
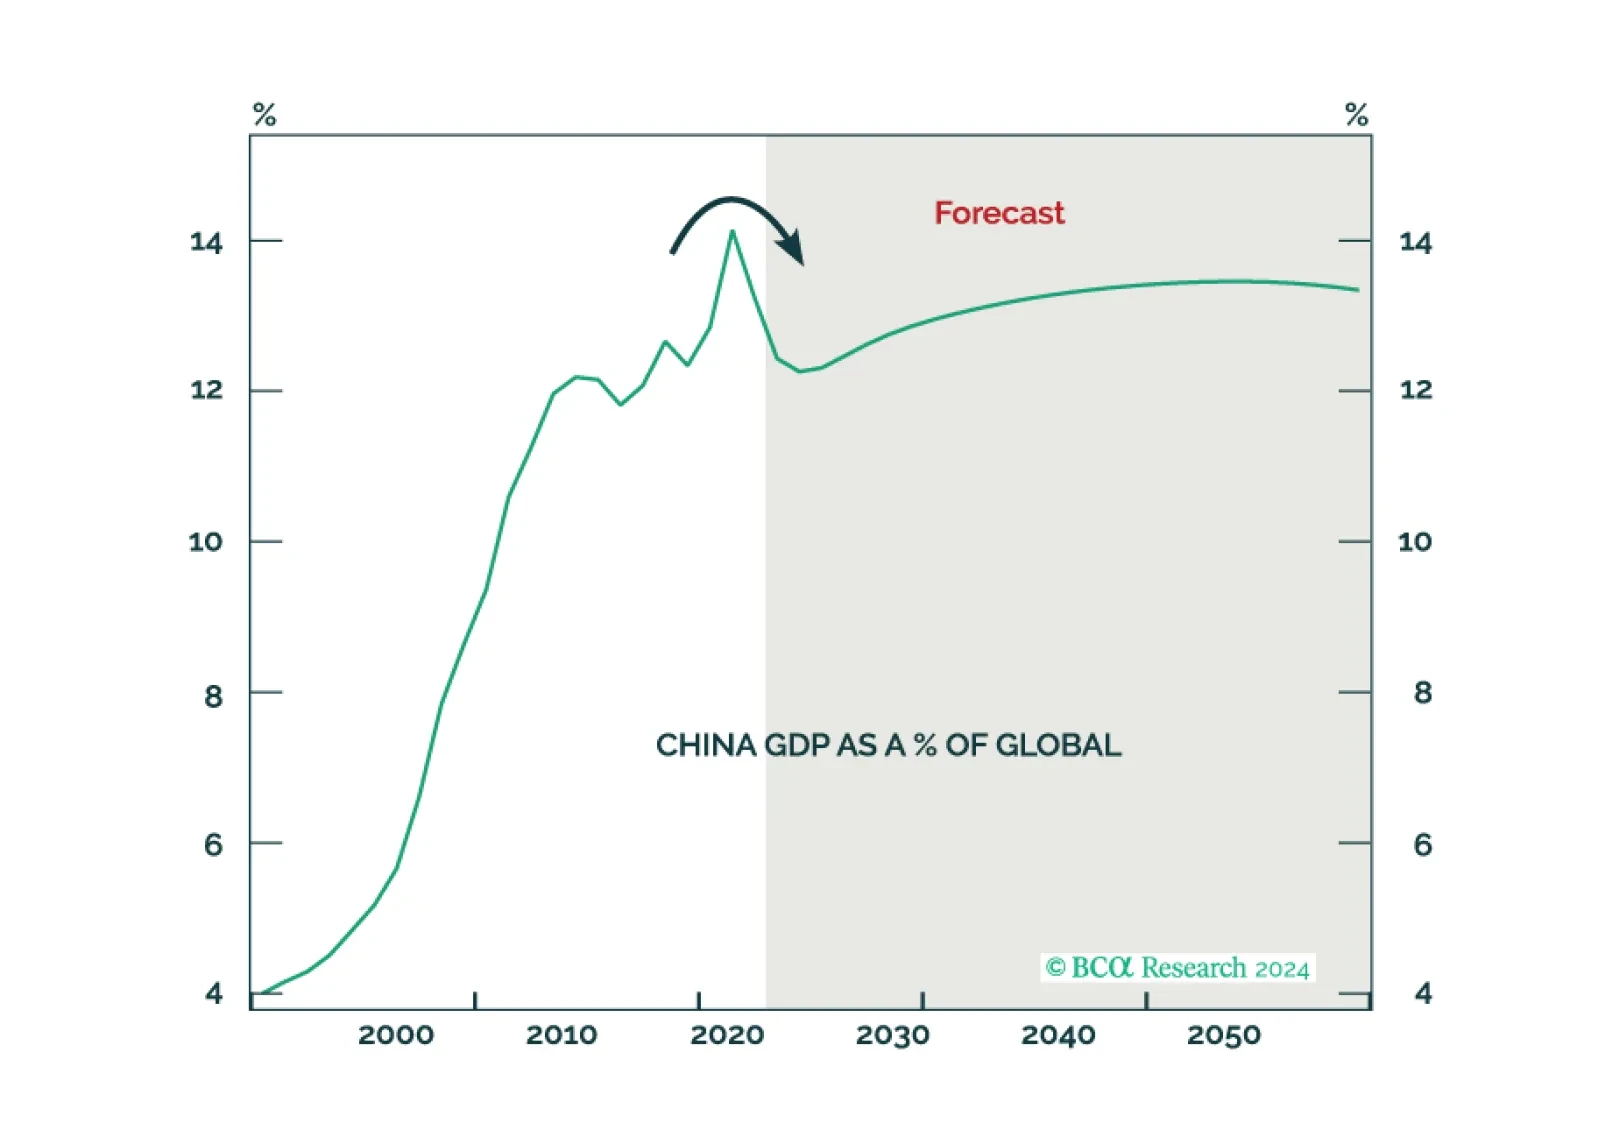
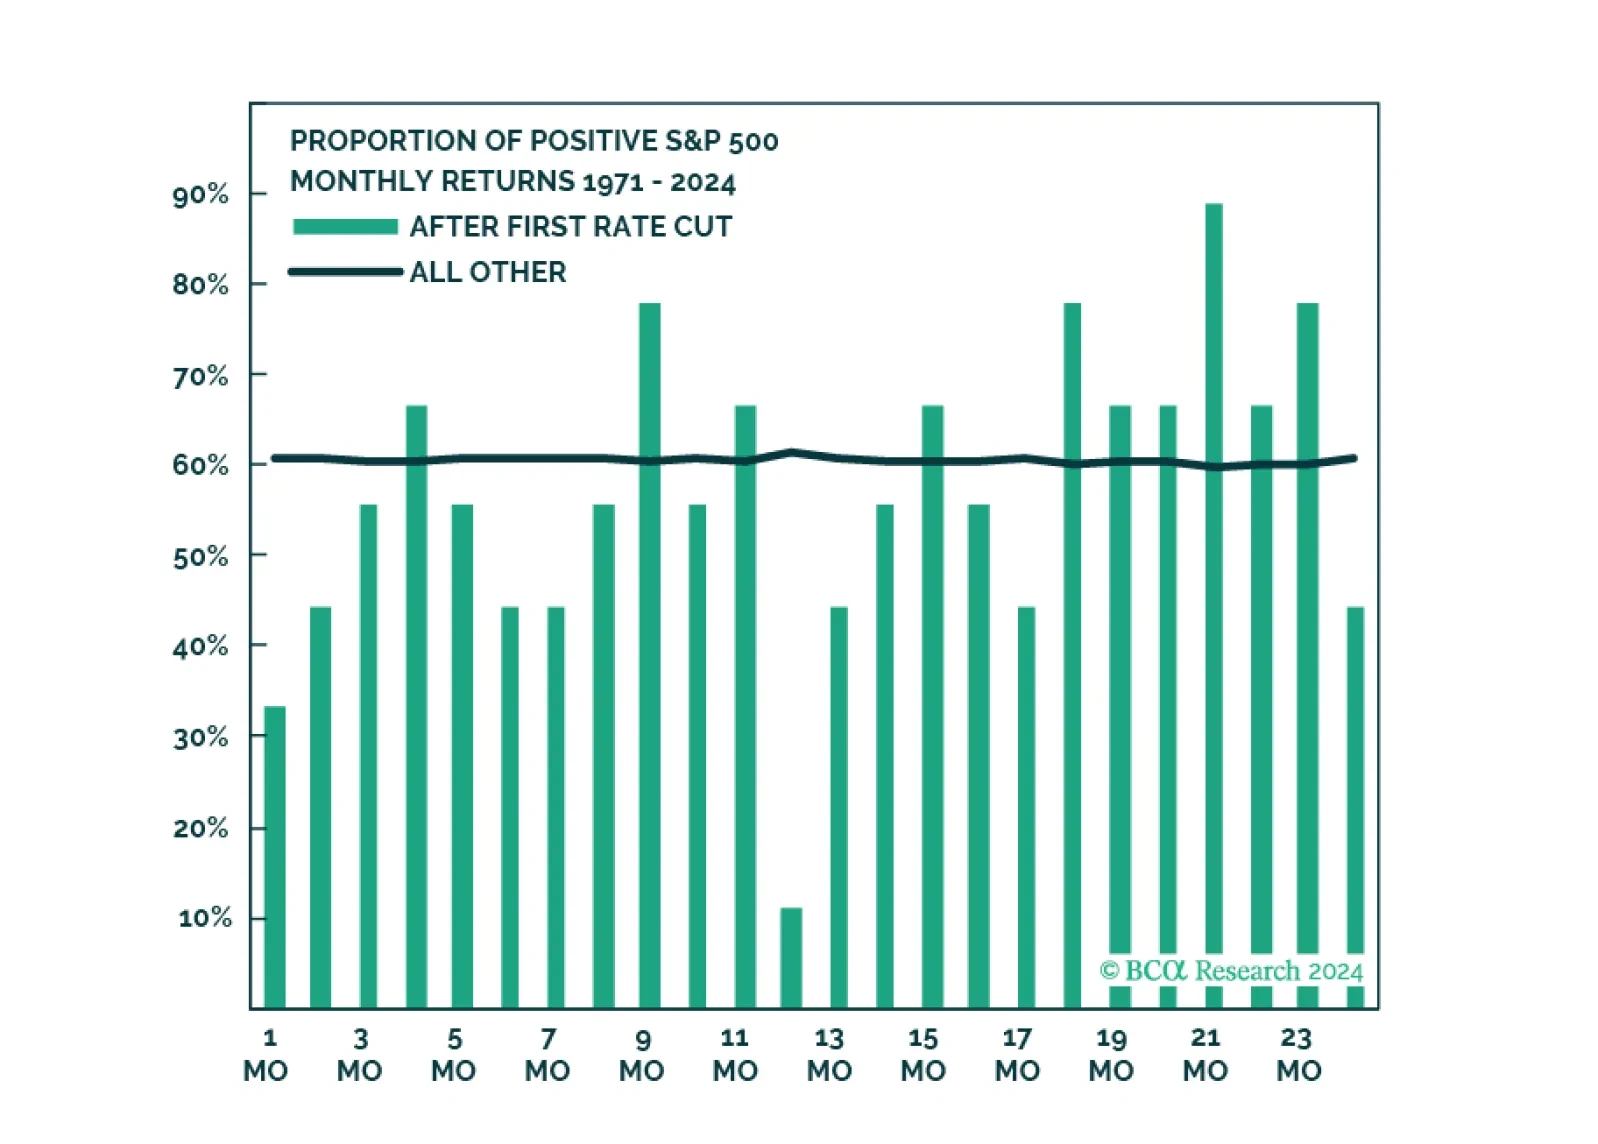
Over the next three months, US equity investors face slowing economic growth, the unwinding of carry trades, skepticism about GAI, uncertainty about the Fed easing campaign, and a run-up to the Presidential election. Empirically, each event has led to lower returns and heightened volatility. A combination of them all is bound to be toxic. It is not too late to take profits and lower portfolio beta.