Latest from BCA Research
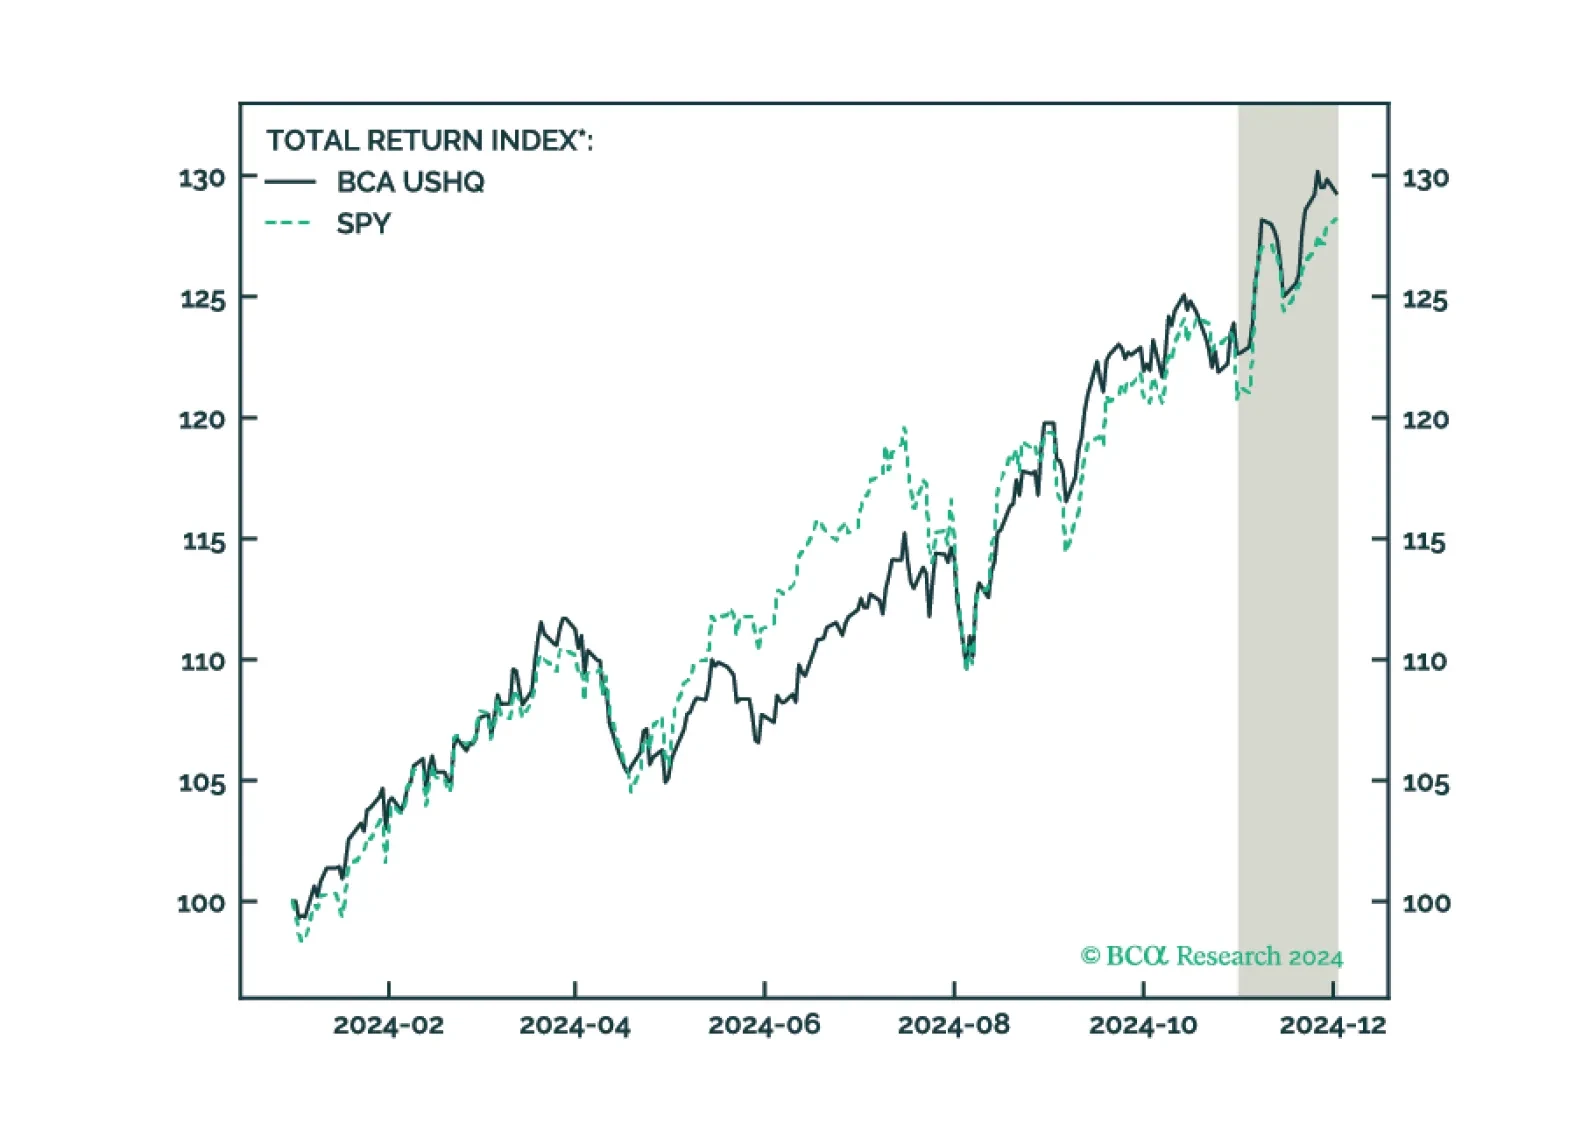
The US High Quality (USHQ) portfolio has performed mostly on par versus its SPY benchmark YTD. However, USHQ still exhibits lower drawdown and volatility versus the SPY. Heading into year end, we are confident that USHQ's performance will remain intact, with out-performance on a risk adjusted basis versus the SPY.
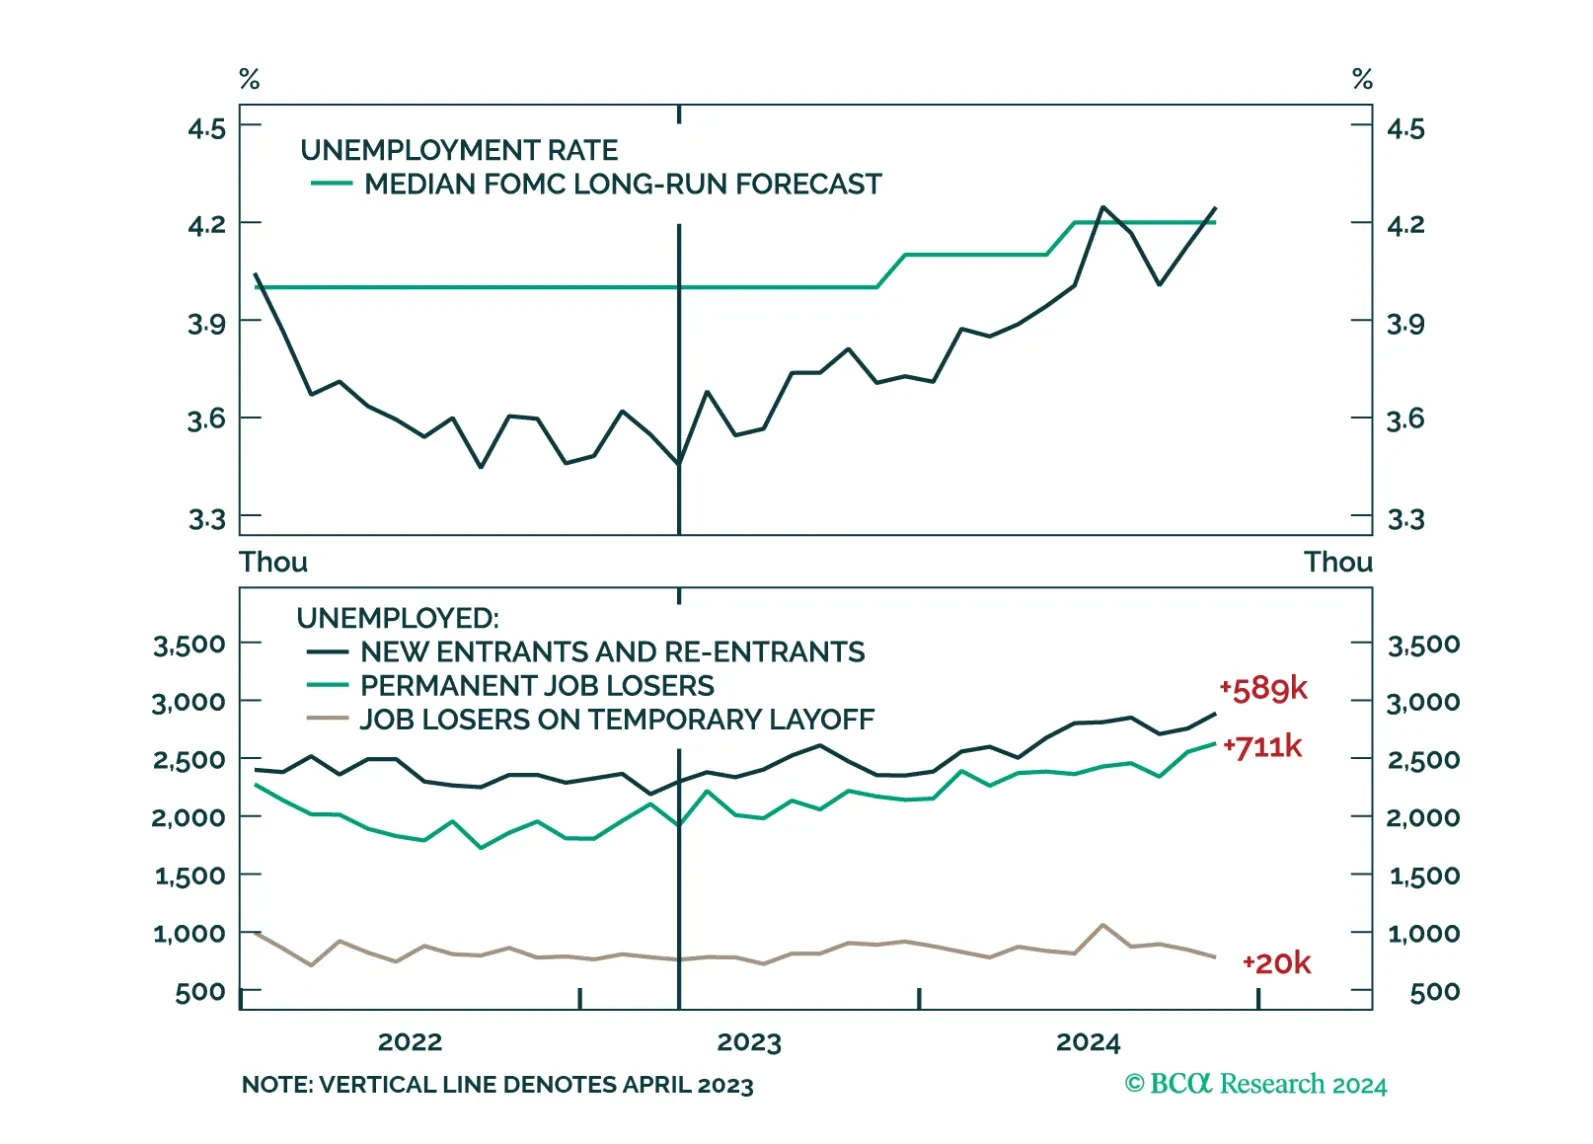
Updated views on trends in labor supply and demand in light of this morning’s employment report.
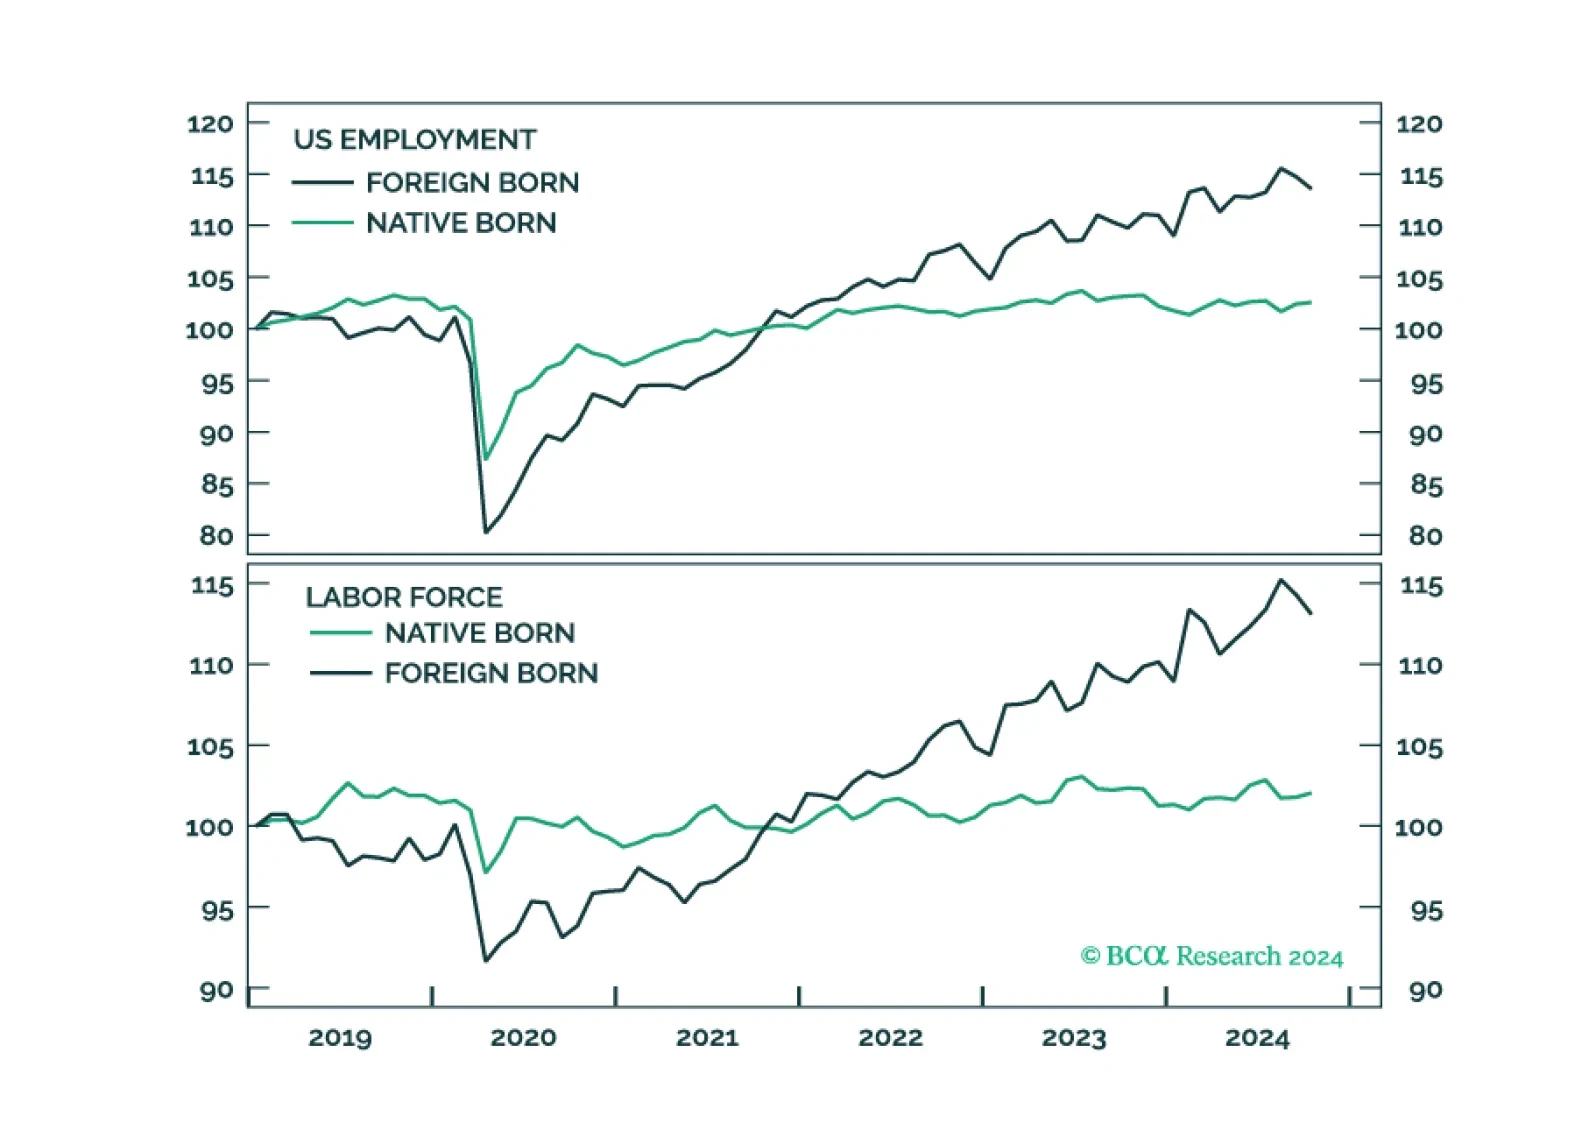
I have been generally sceptical of the reflationary aspects of the so-called Trump trade. If Trump's first term is any guide, lower tax rates will have little impact on business spending while higher tariffs are unlikely to trigger much reshoring of manufacturing activity. Meanwhile, rising debt-service costs could force the Trump administration to cut social spending under the guise of reducing government waste. One open question surrounds immigration. The market consensus seems to be that decreased immigration will lead to a tighter labour market, stoking inflationary pressures in the process.
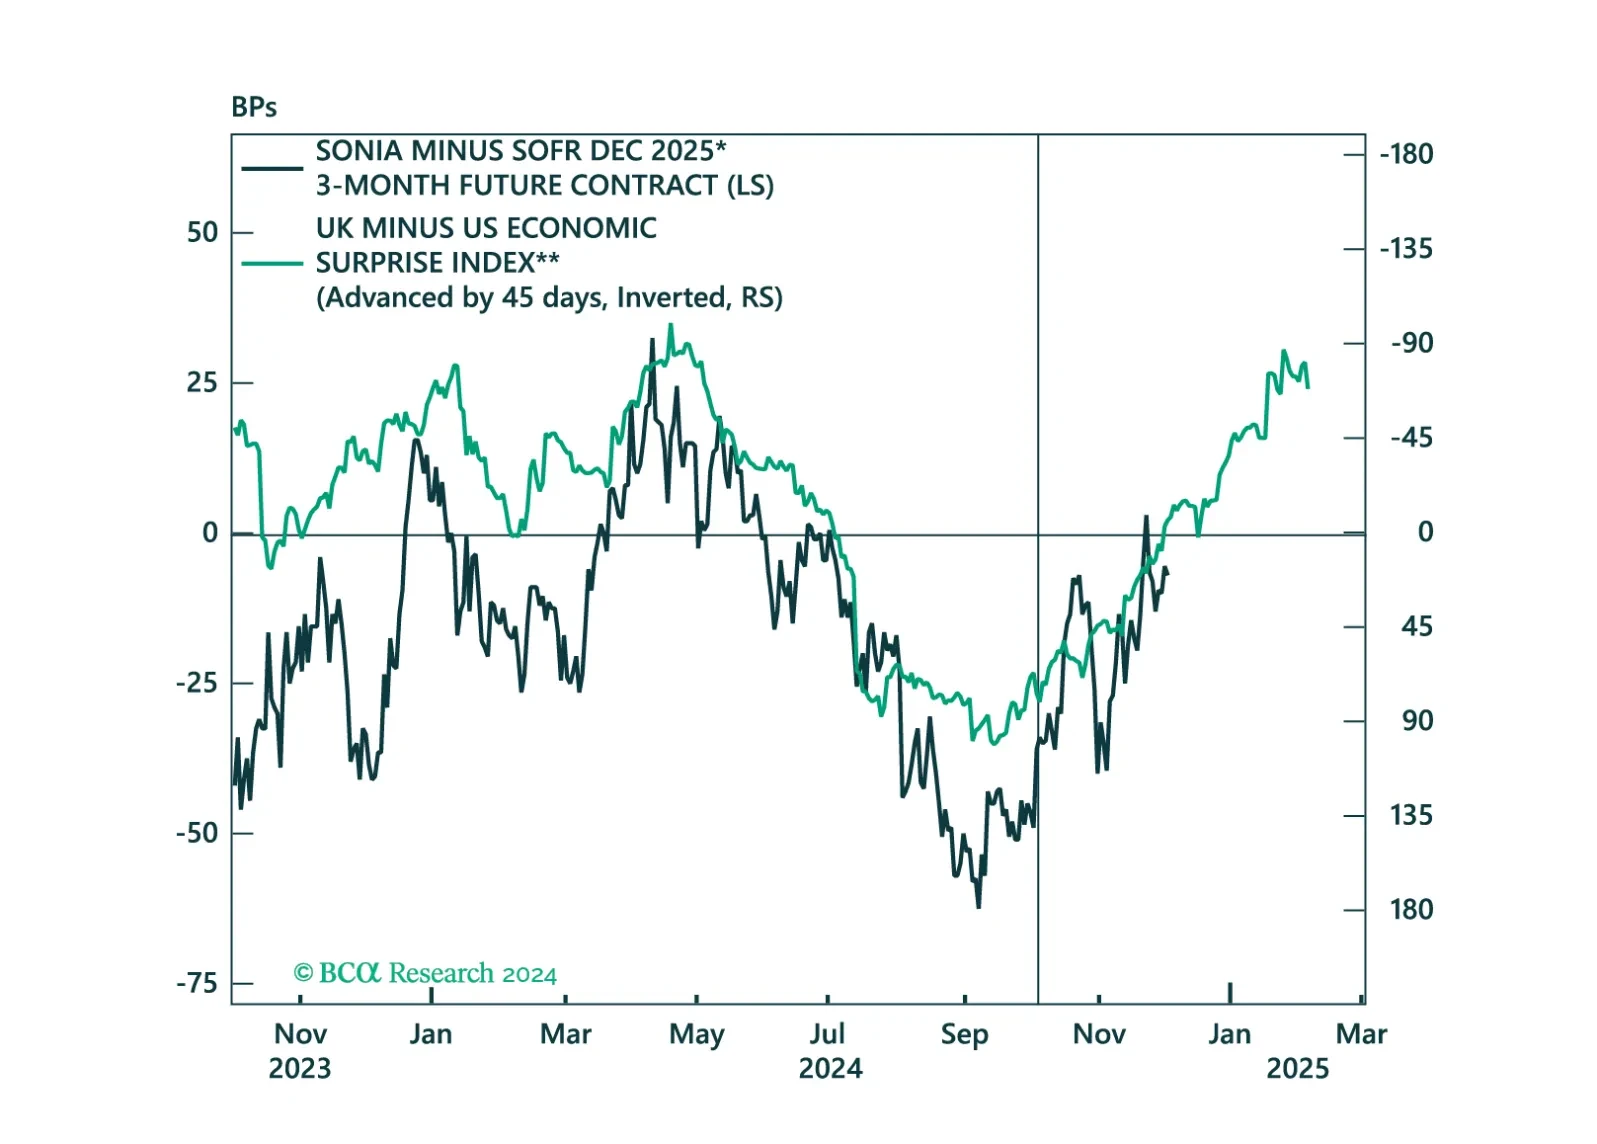
This report reviews our FX and Fixed Income trades over the last year. We look forward to sharing our thoughts for 2025 next week.
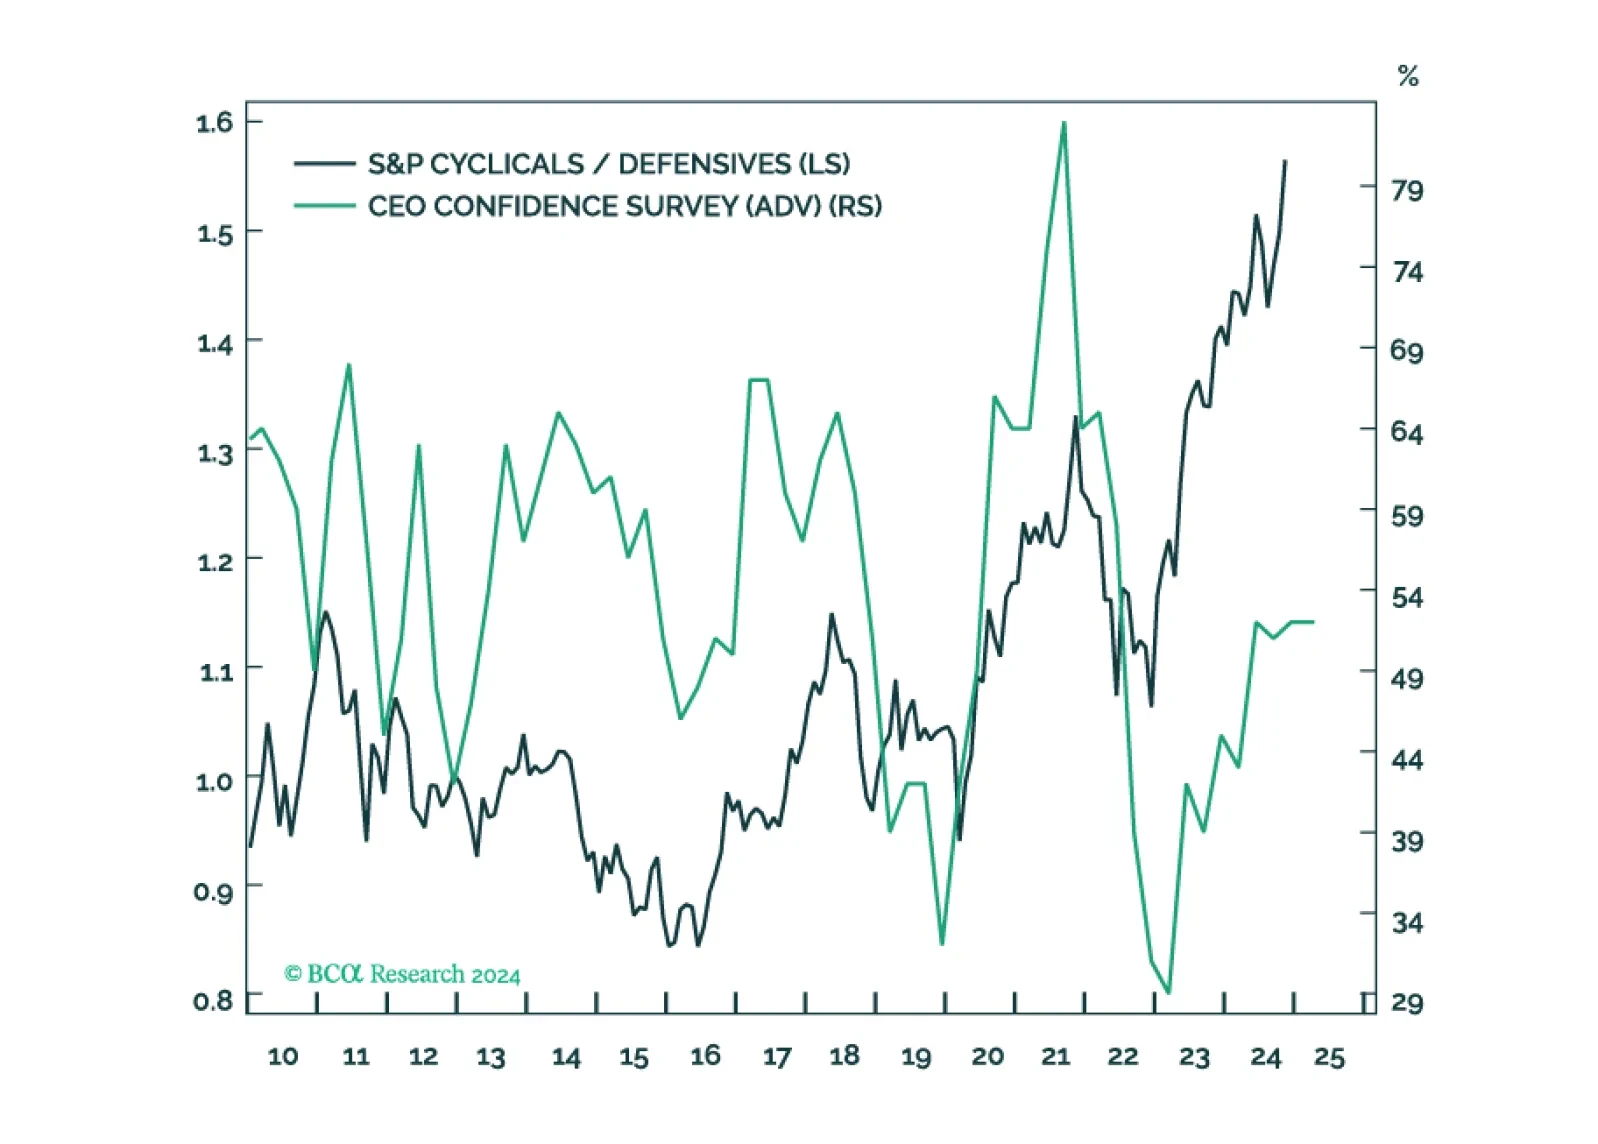
This week, we send you a Style Chart Pack without a front section. We are currently working on the 2025 outlook, which will be released on December 9.
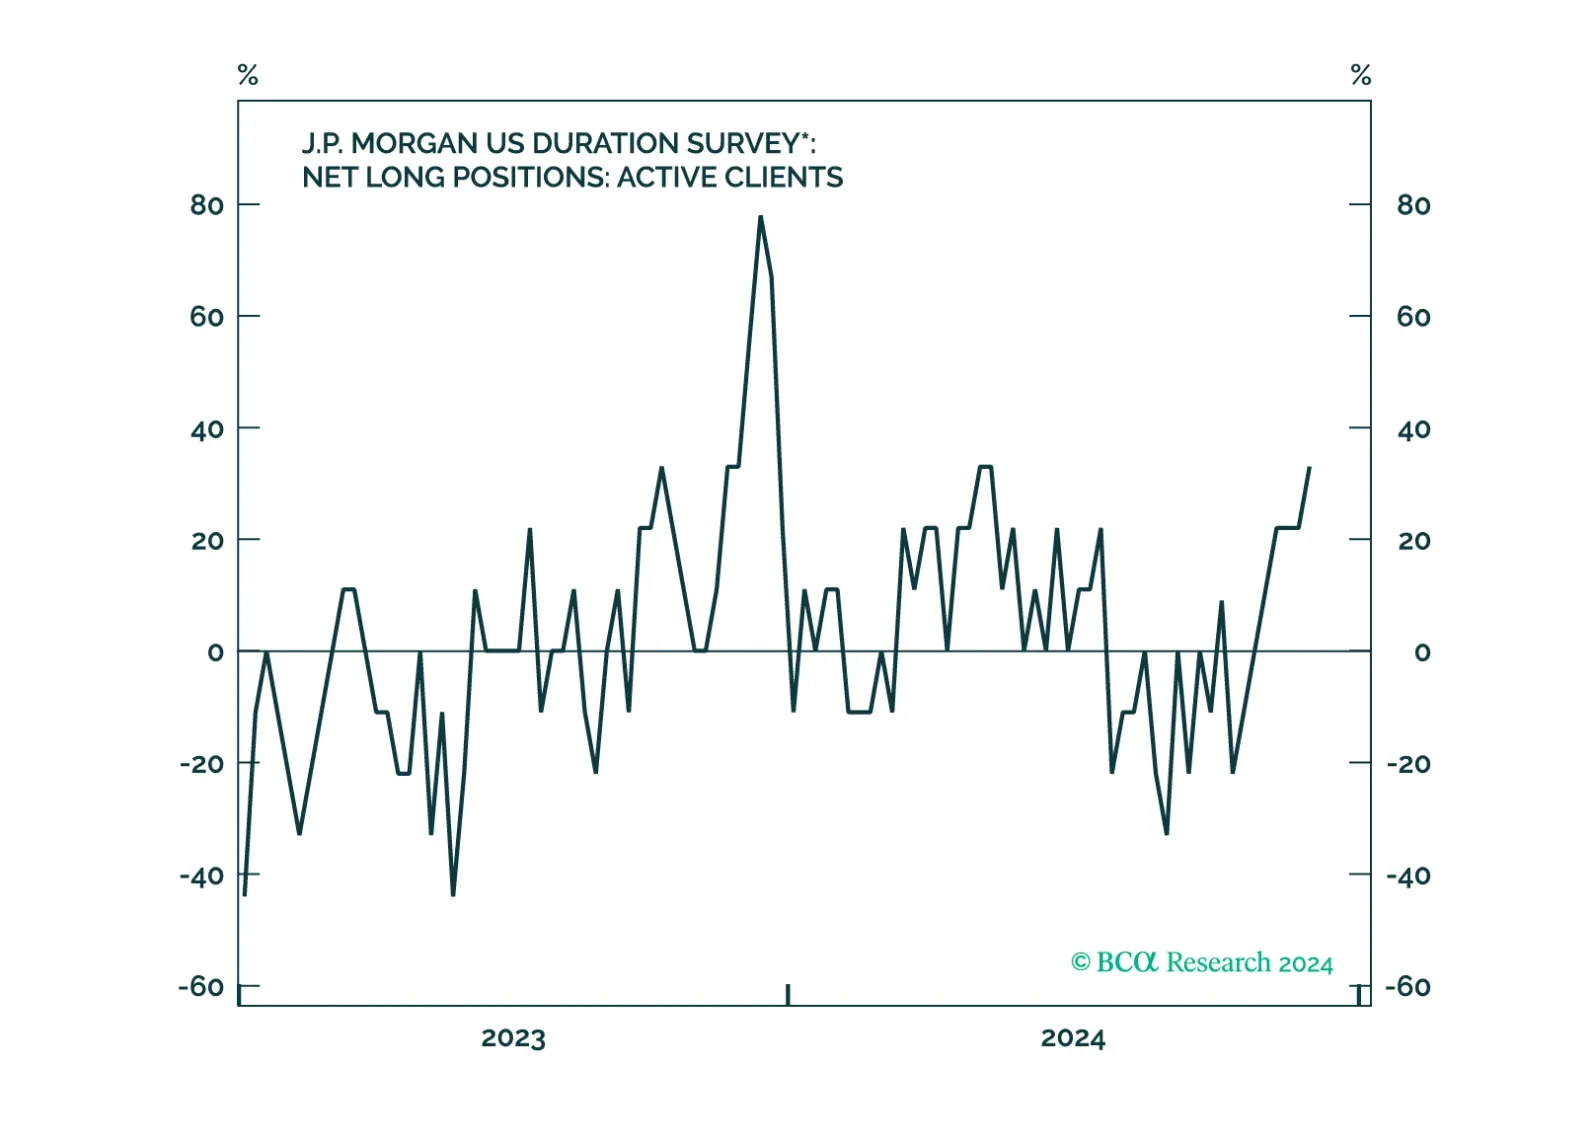
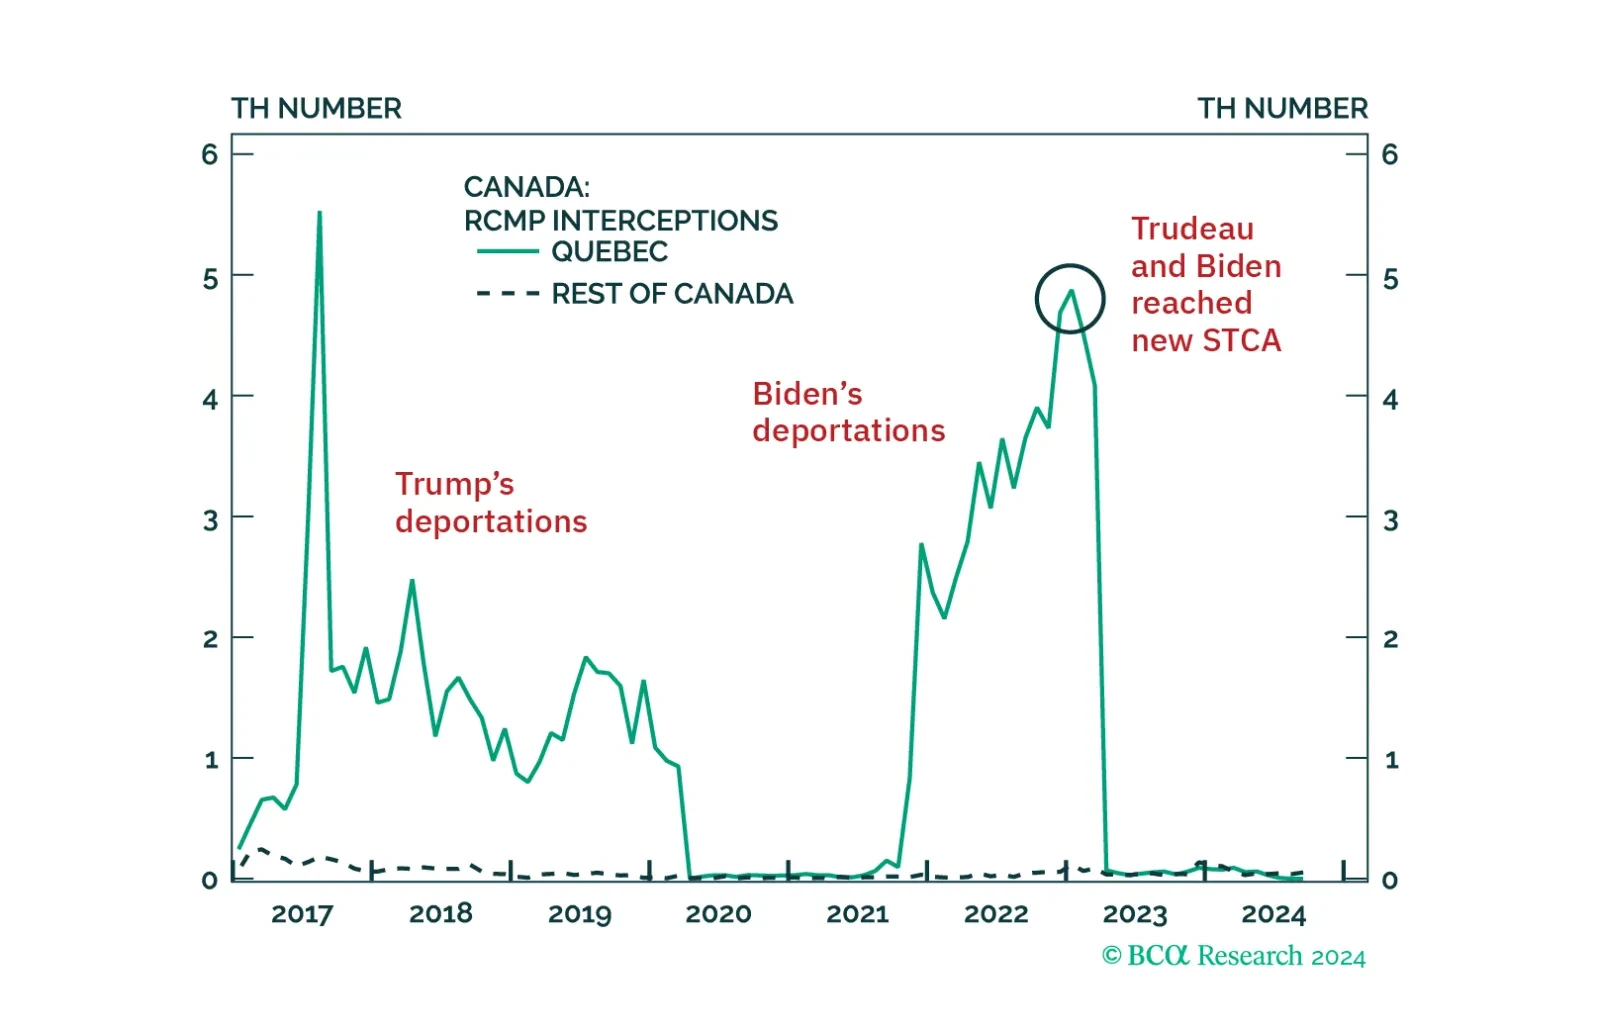
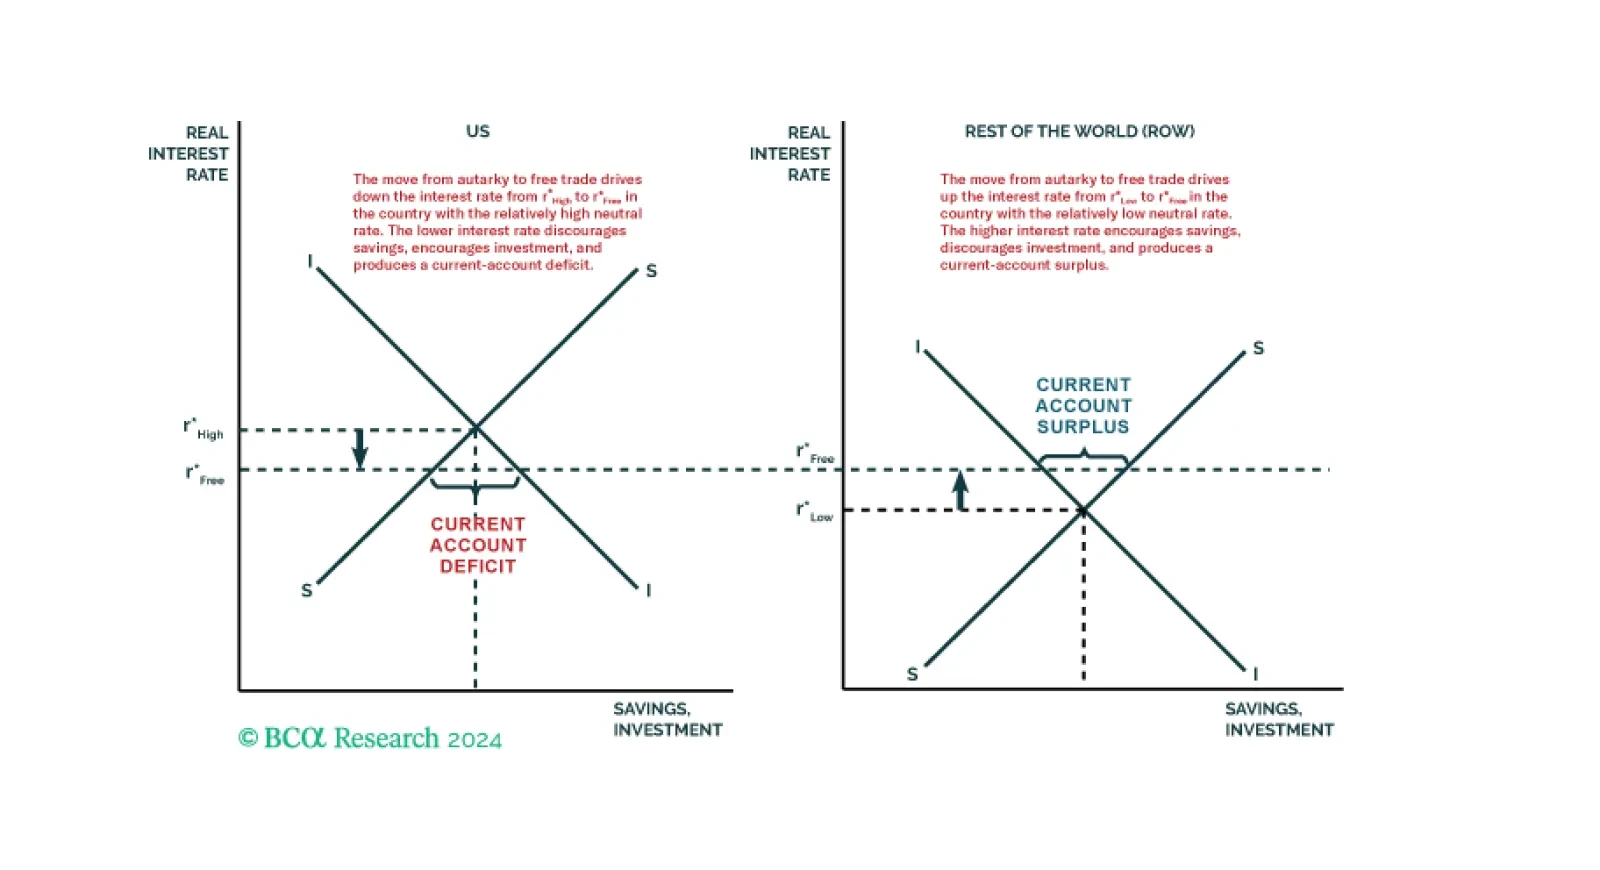
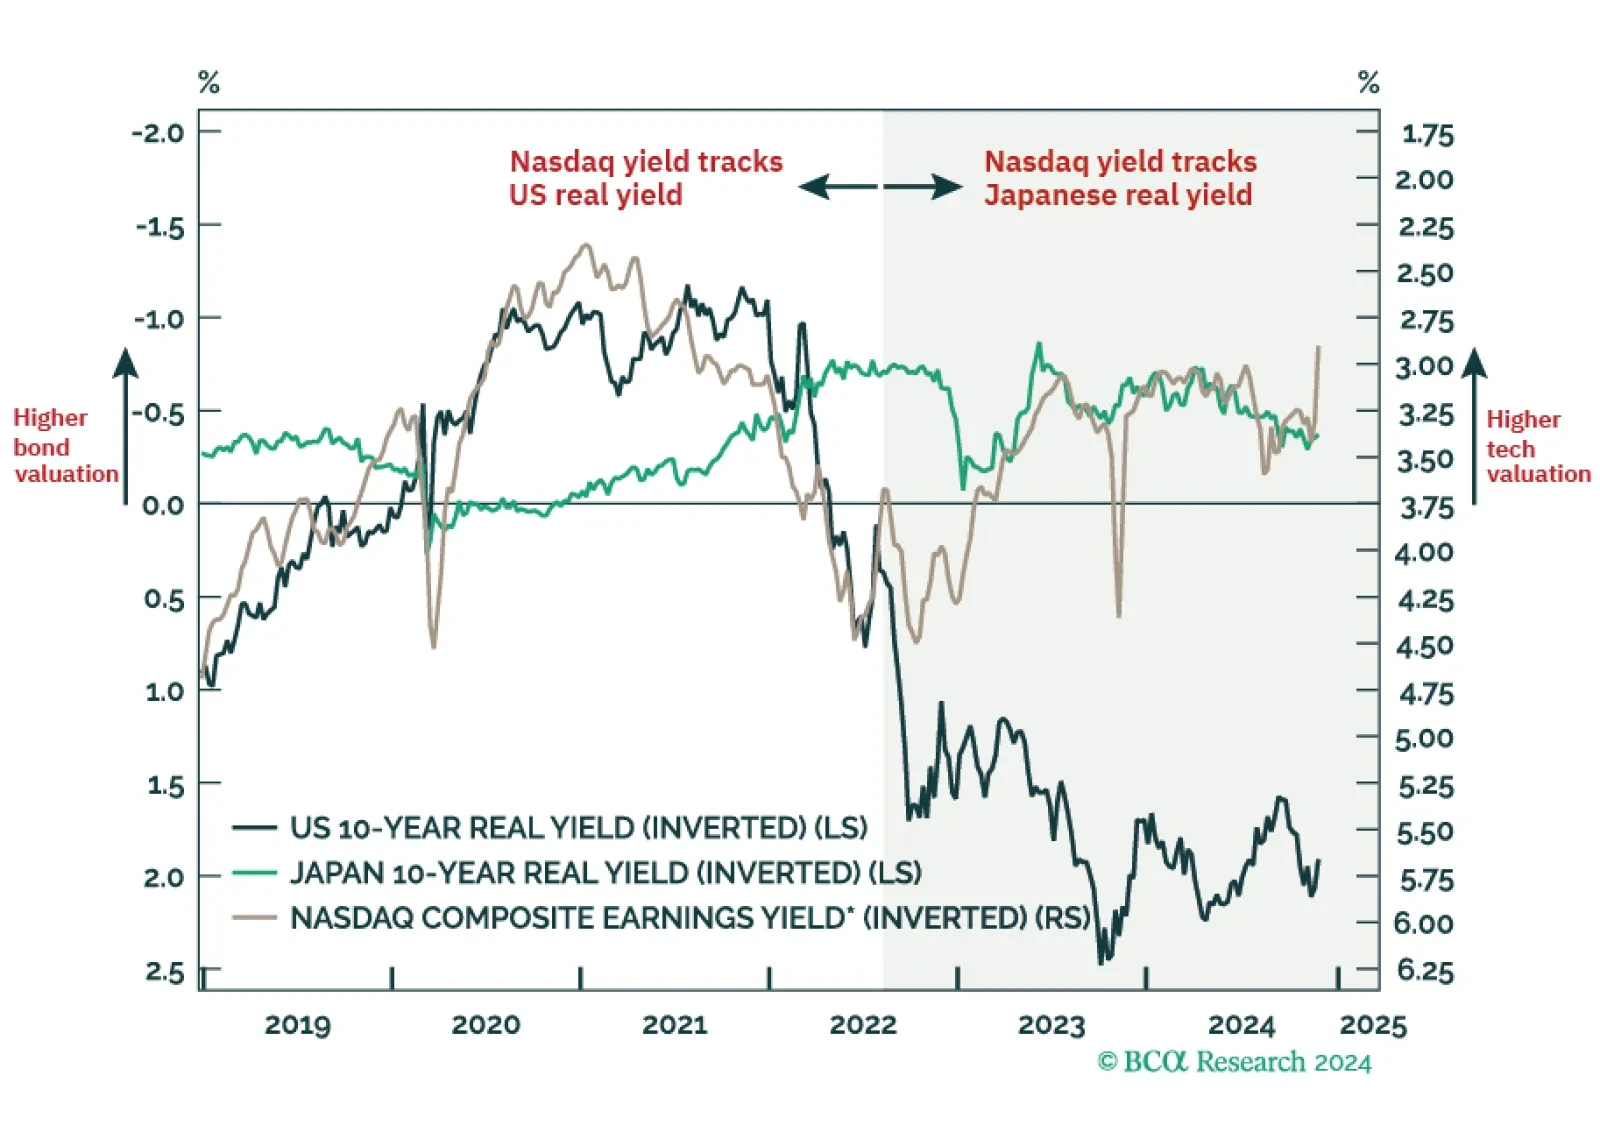
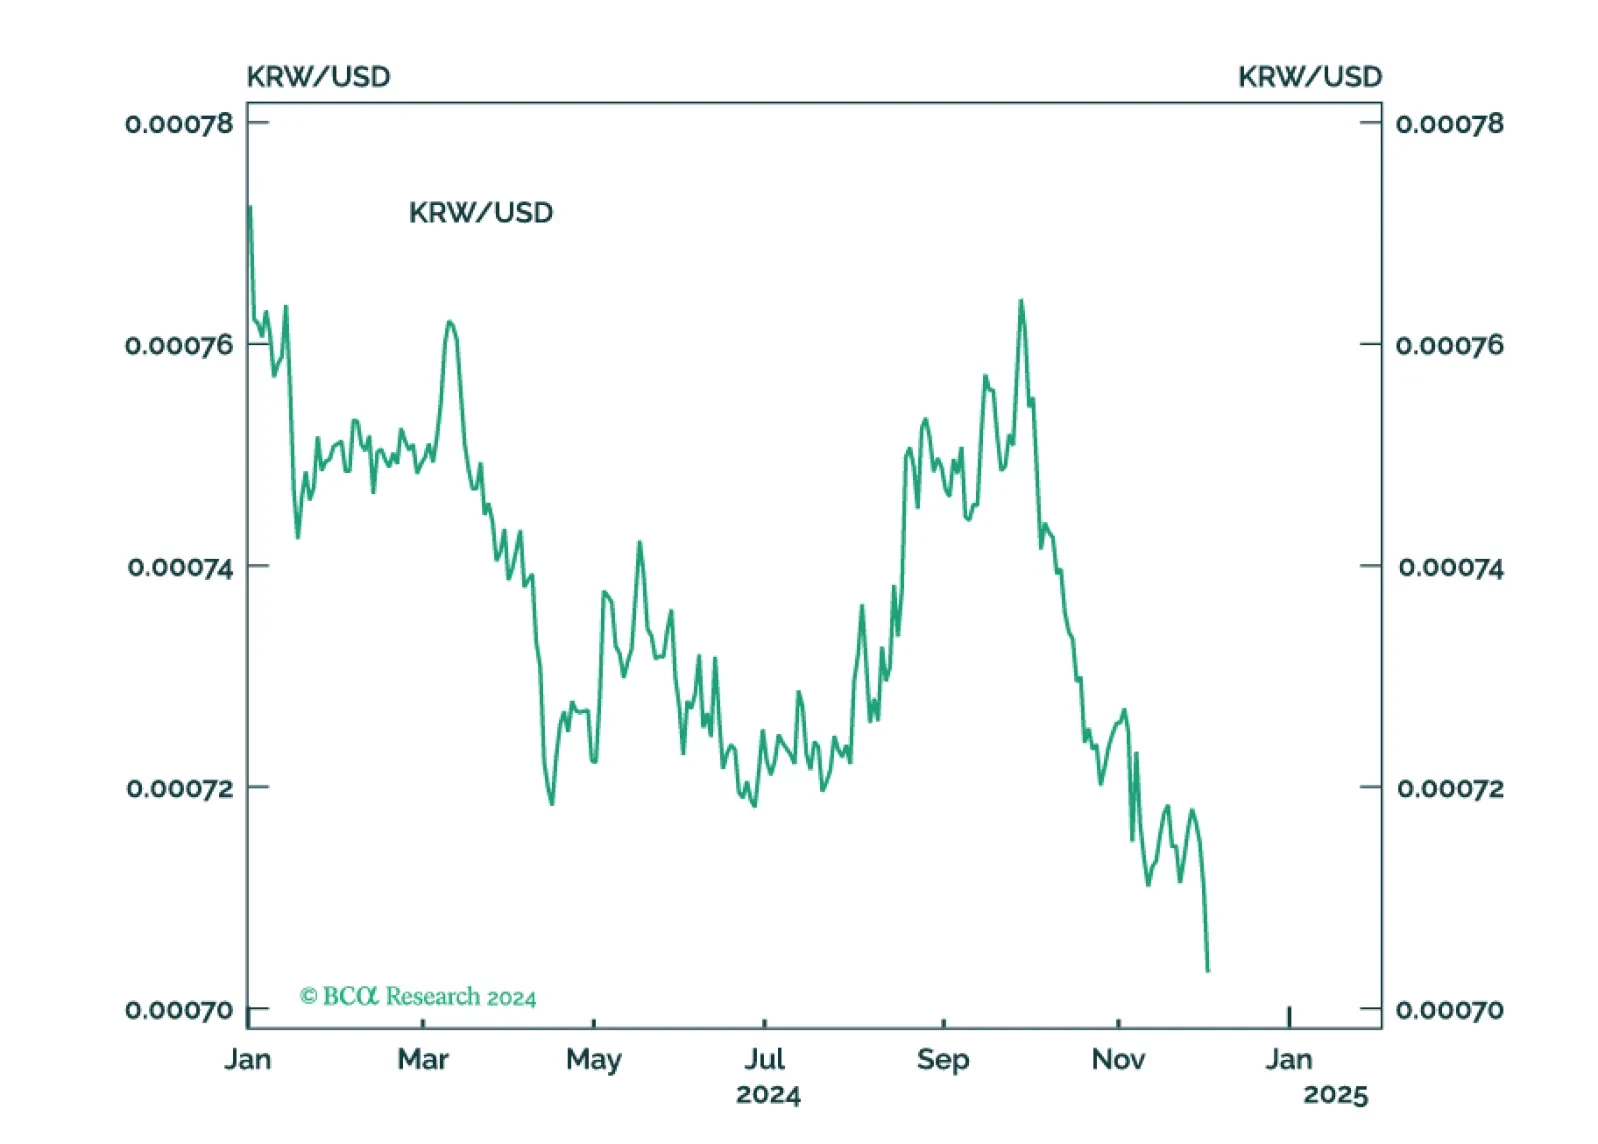
The flurry of global political instability that we expected after the US election is coming to pass. Investors should de-risk in the near term as stocks are flying high but face the turmoil of Biden's last months and then Trump tariffs.