Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
The economy is not in a recession, and the Fed is not behind the curve. A 50 bp rate cut at the September meeting is unlikely, but 25 bp is certain. However, economic growth is slowing, and a recession at the end of the year is still the most likely outcome. The S&P 500 earnings are projected to grow, but our model predicts that the growth rate will roll over. The S&P 500 remains expensive and crowded, but the most extreme technical positioning across sectors has unwound. We recommend lowering portfolio beta with defensive sectors, and under-weighing Tech, and Consumer Discretionary.
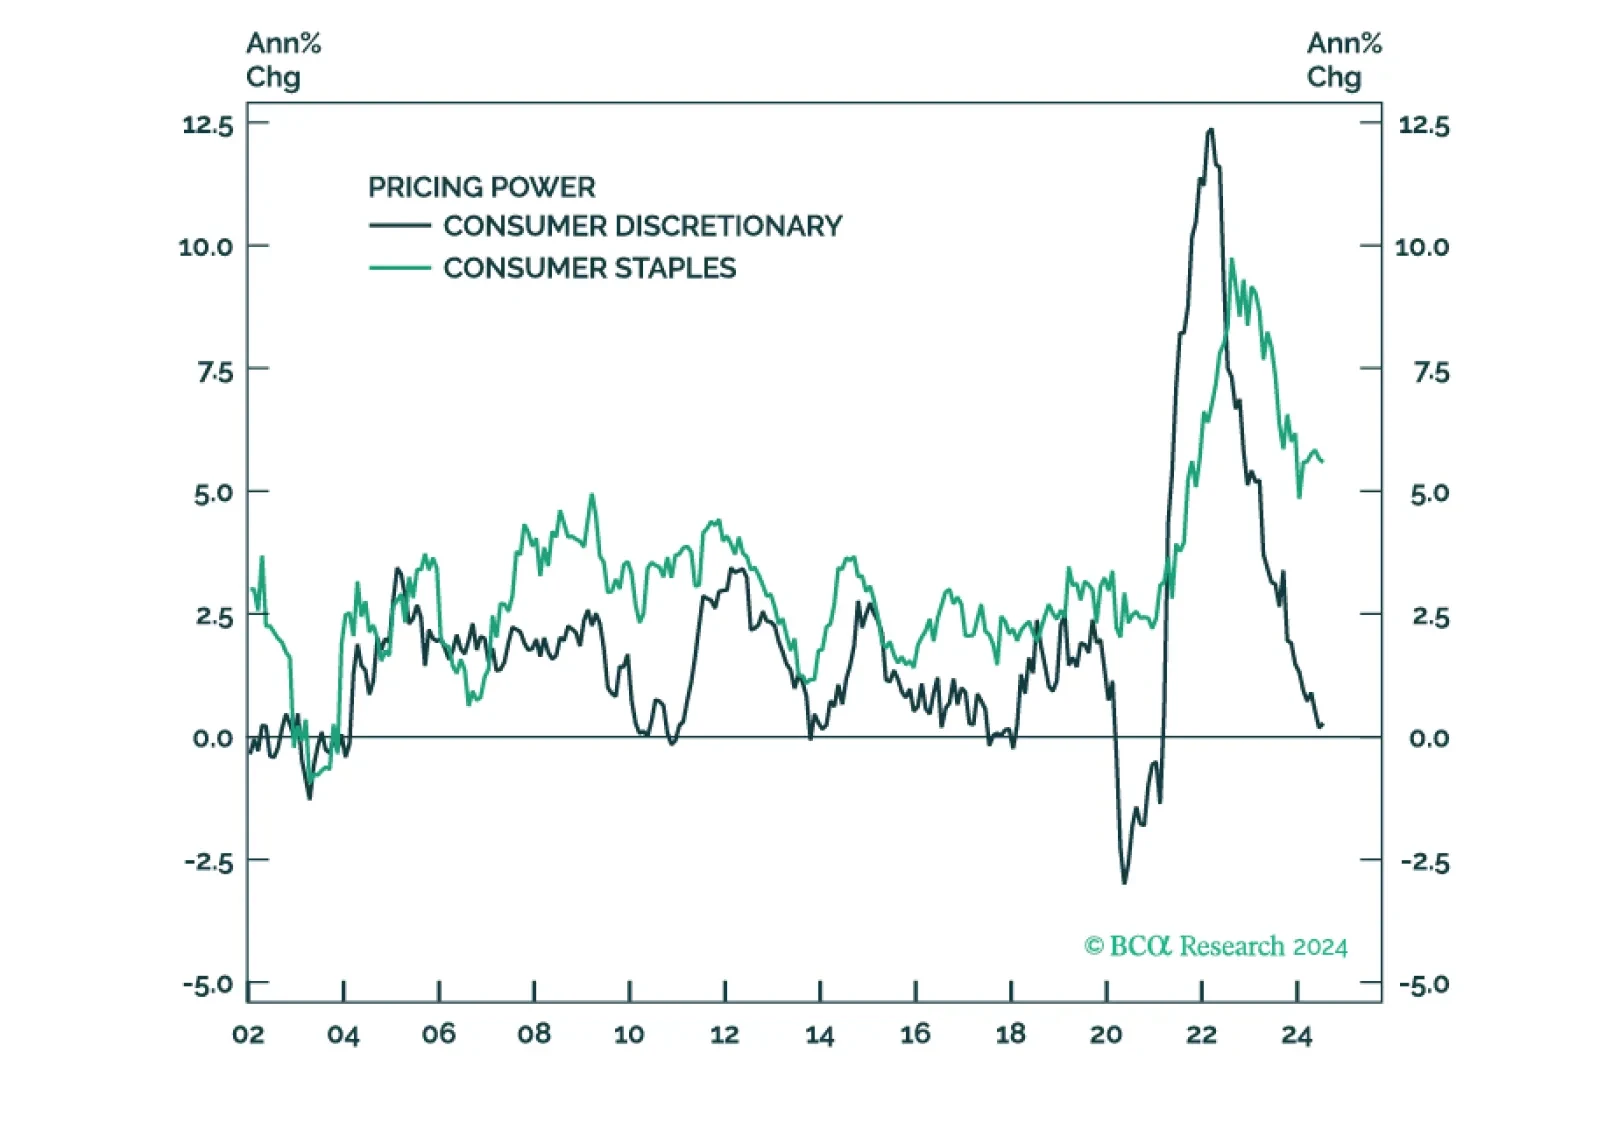
Q2 Earnings season has been strong, with sales and earnings growth accelerating and broadening across sectors. However, companies' results and commentaries are stoking some concerns. GAI monetization will take longer than most investors expect. Companies are also reporting that lower- and middle-income US consumers are strapped. We recommend defensive positioning, as solid earnings growth is insufficient to rule out a recession later this year.
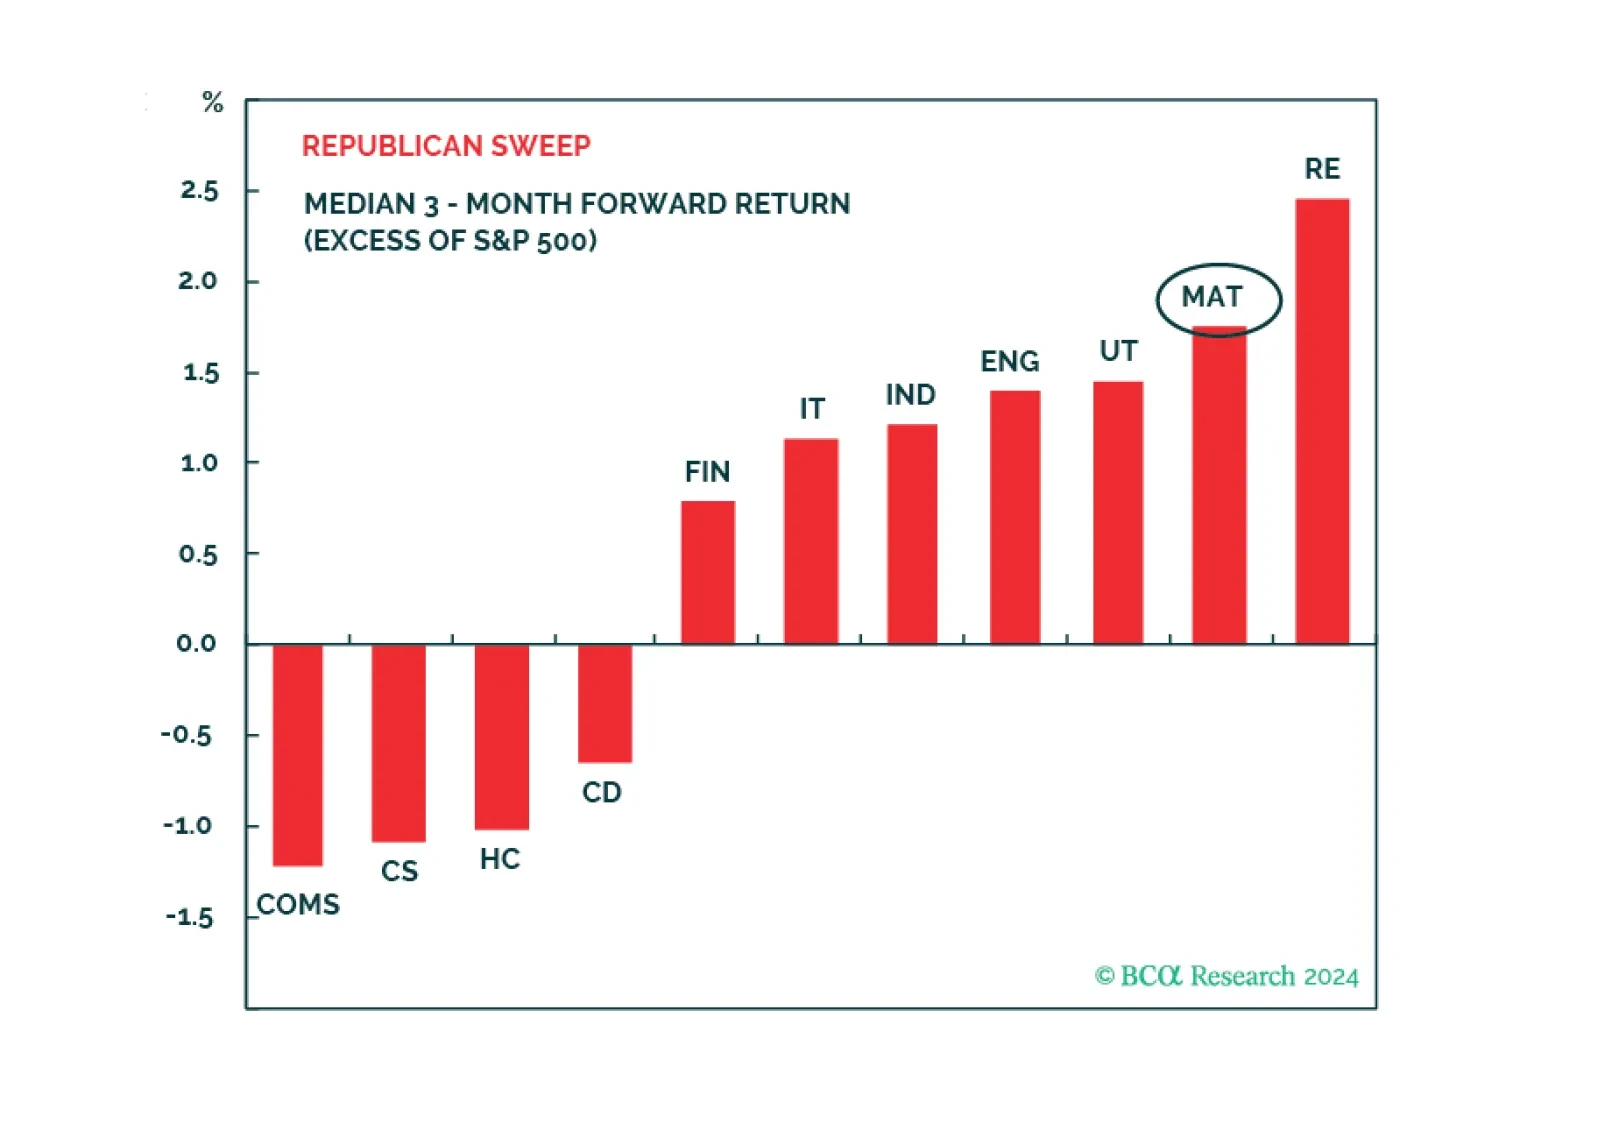
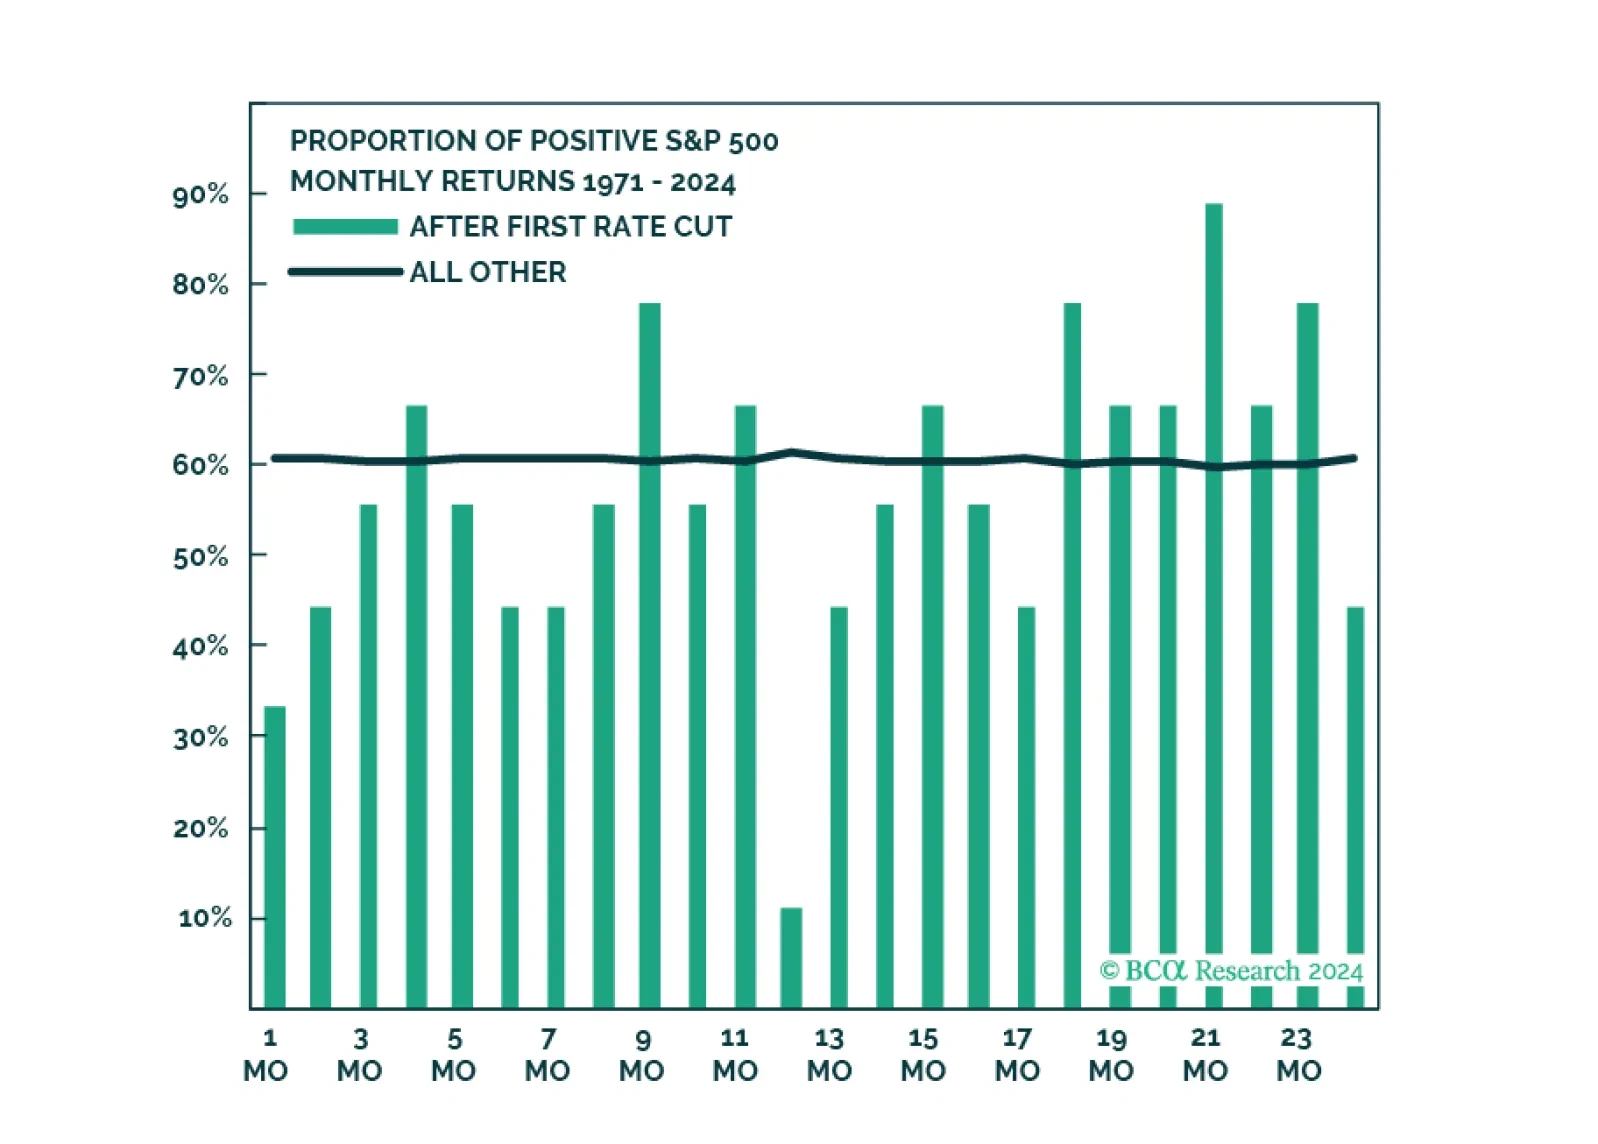
Over the next three months, US equity investors face slowing economic growth, the unwinding of carry trades, skepticism about GAI, uncertainty about the Fed easing campaign, and a run-up to the Presidential election. Empirically, each event has led to lower returns and heightened volatility. A combination of them all is bound to be toxic. It is not too late to take profits and lower portfolio beta.
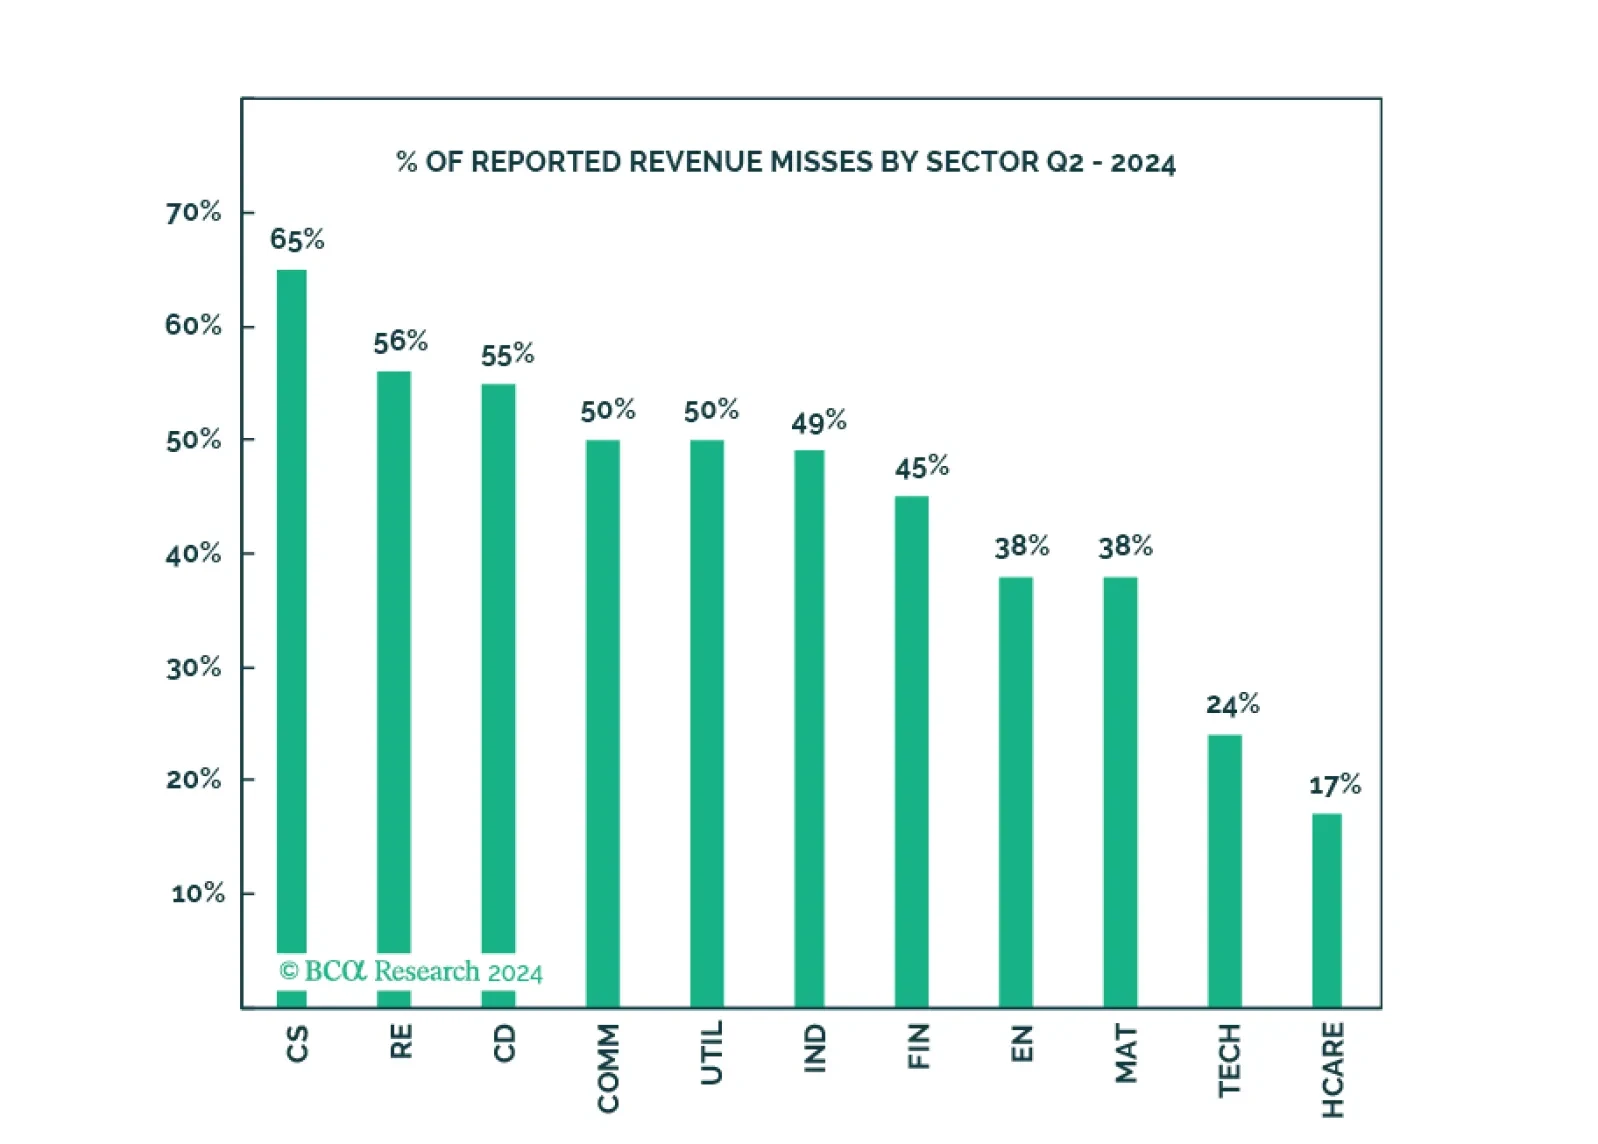
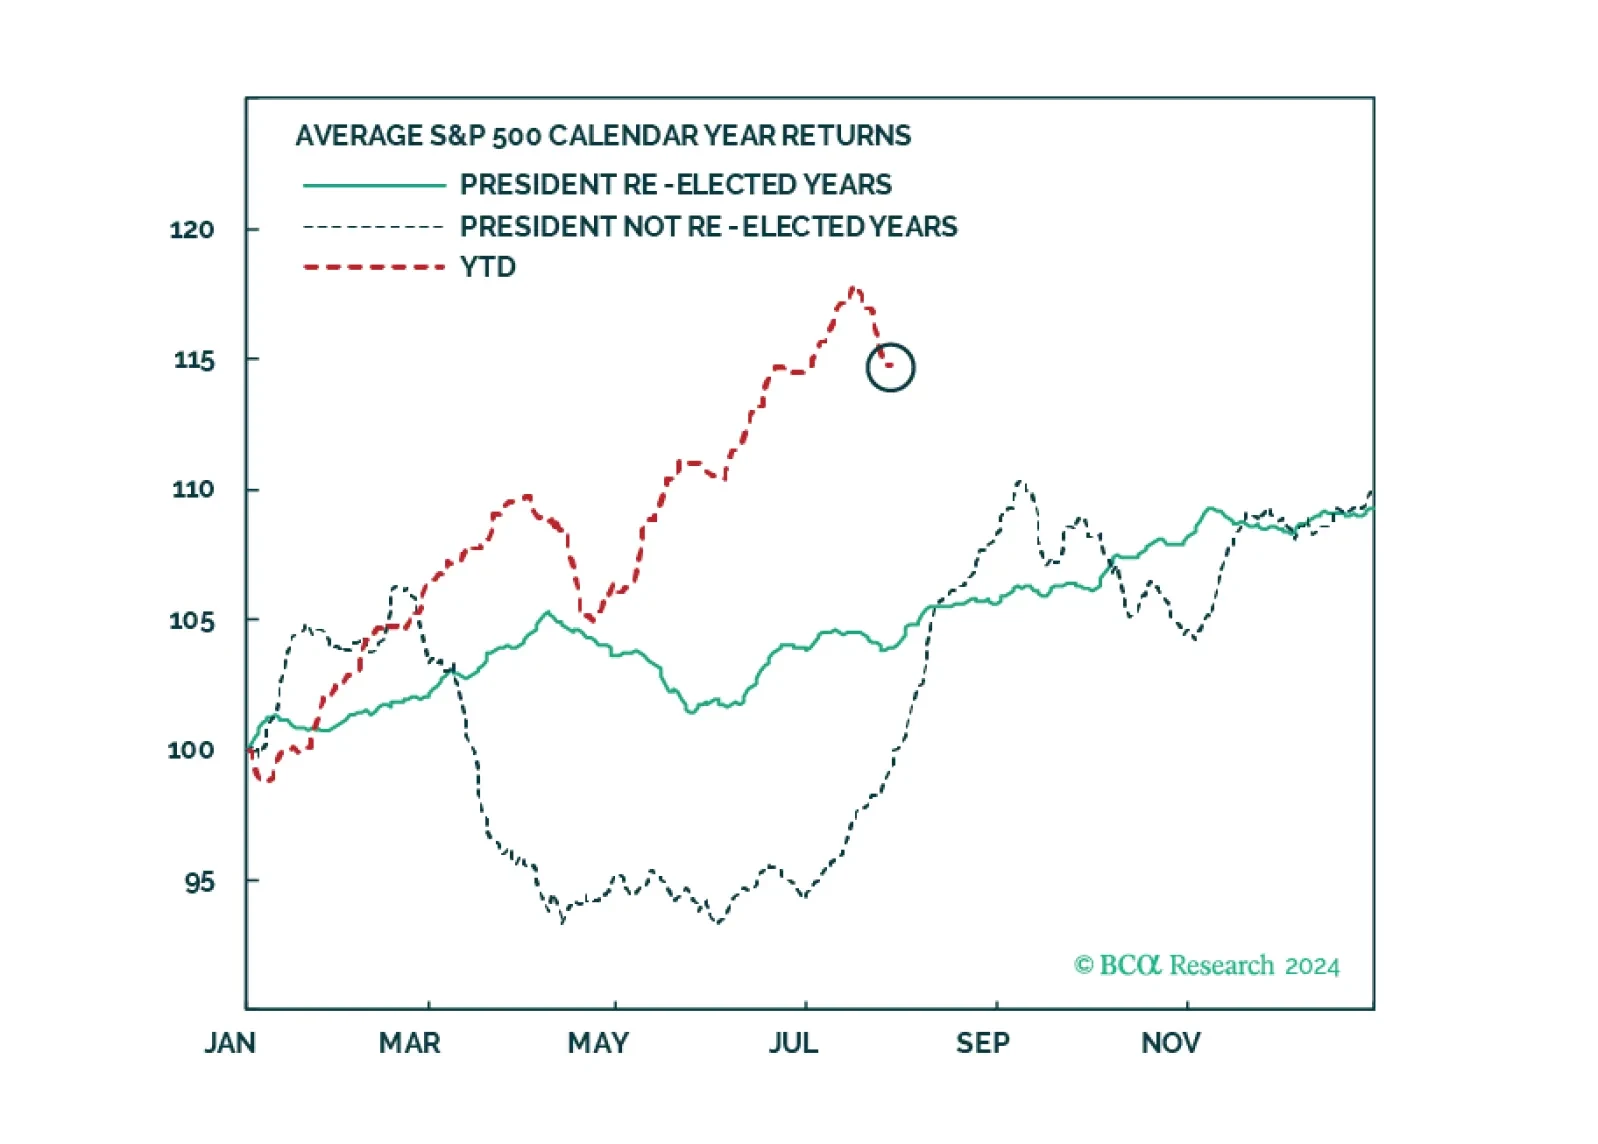
The second half of the year will be challenging for equity investors because economic growth is clearly deteriorating. Election uncertainty is adding to volatility. Bad news is now bad news, and equity markets will likely pull back, anticipating a hard landing. The GAI trade has run its course and now attracts more scrutiny. Take profits from recent winners. Don’t buy on a dip (at least not yet). Defensive and other laggards offer downside protection and will deliver positive relative returns. Close overweights or even go underweight in the Magnificent Seven sectors.
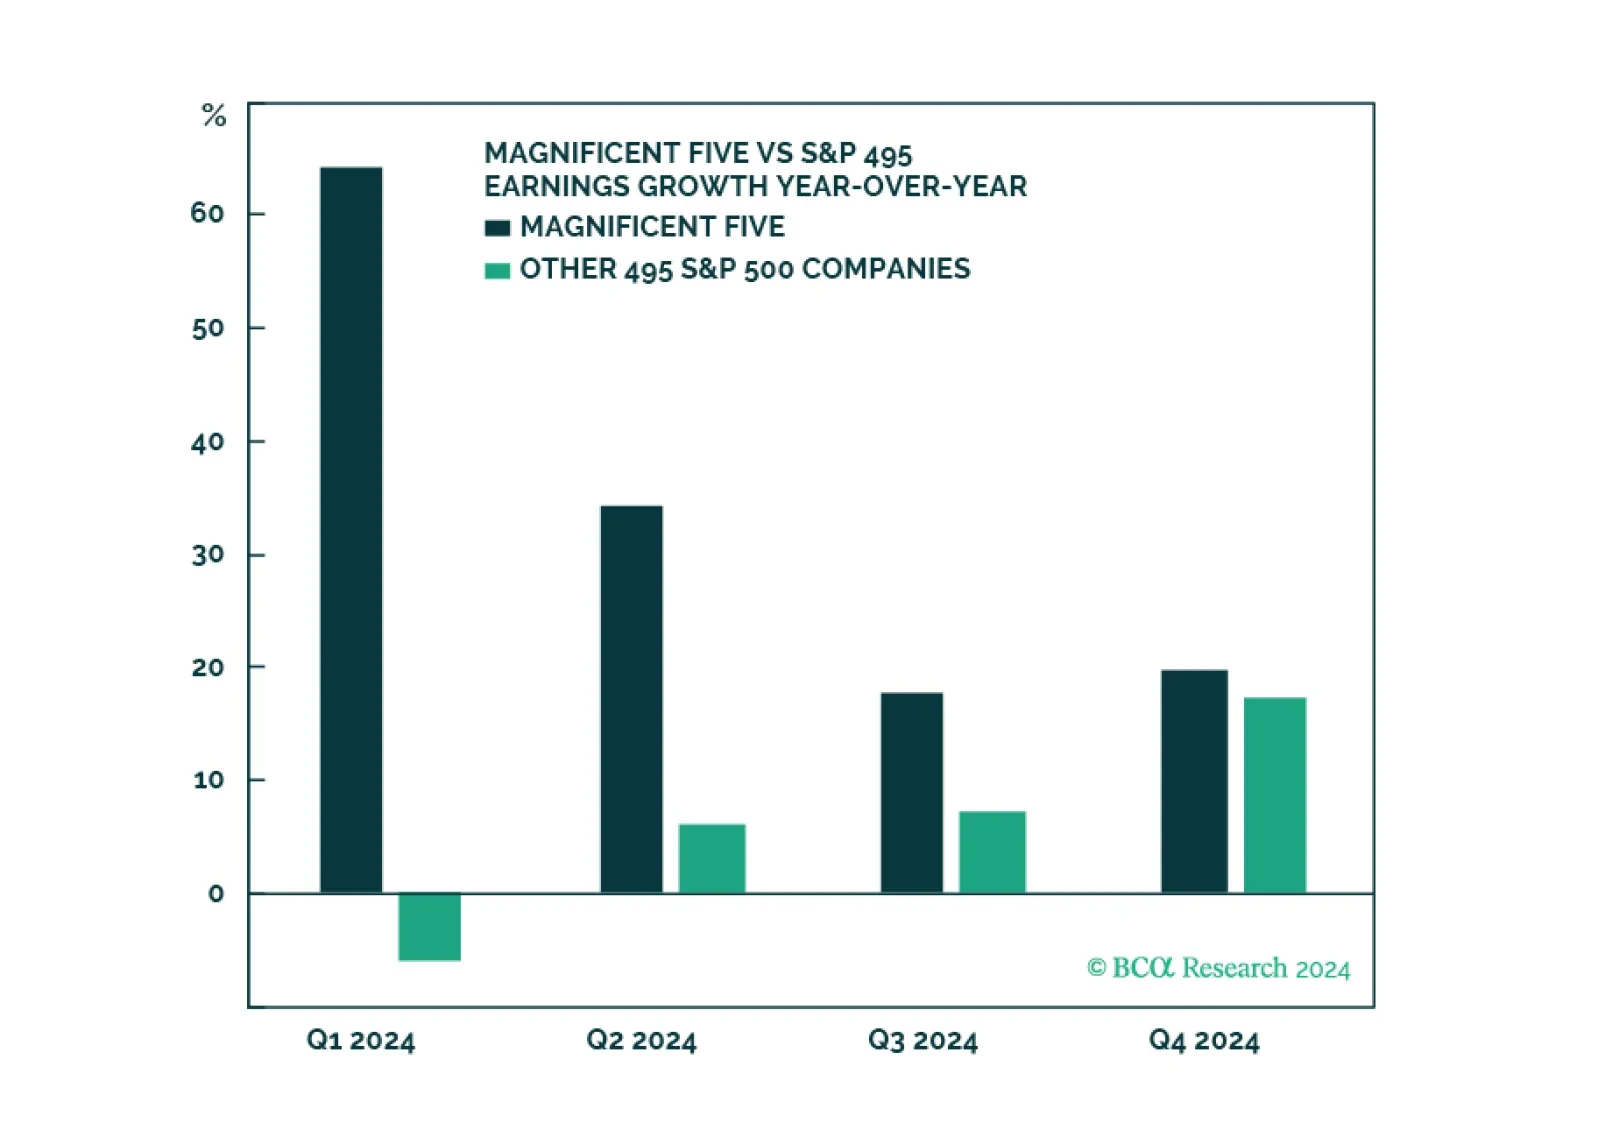
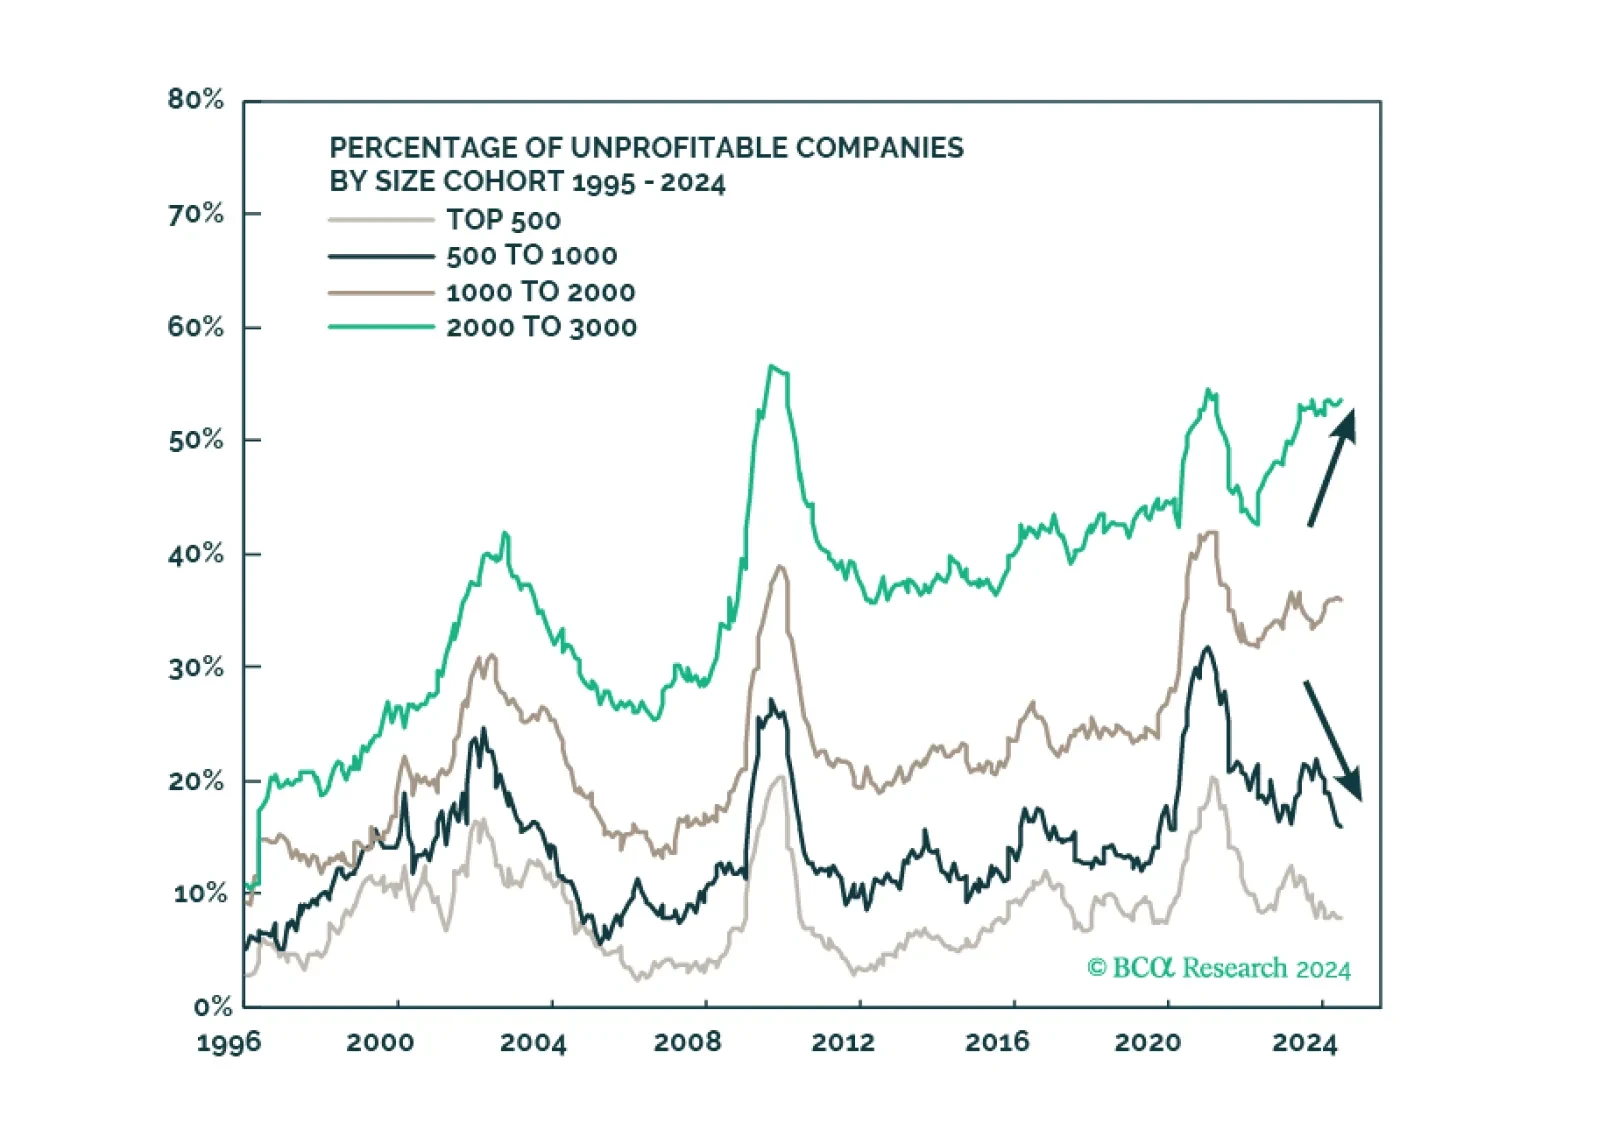
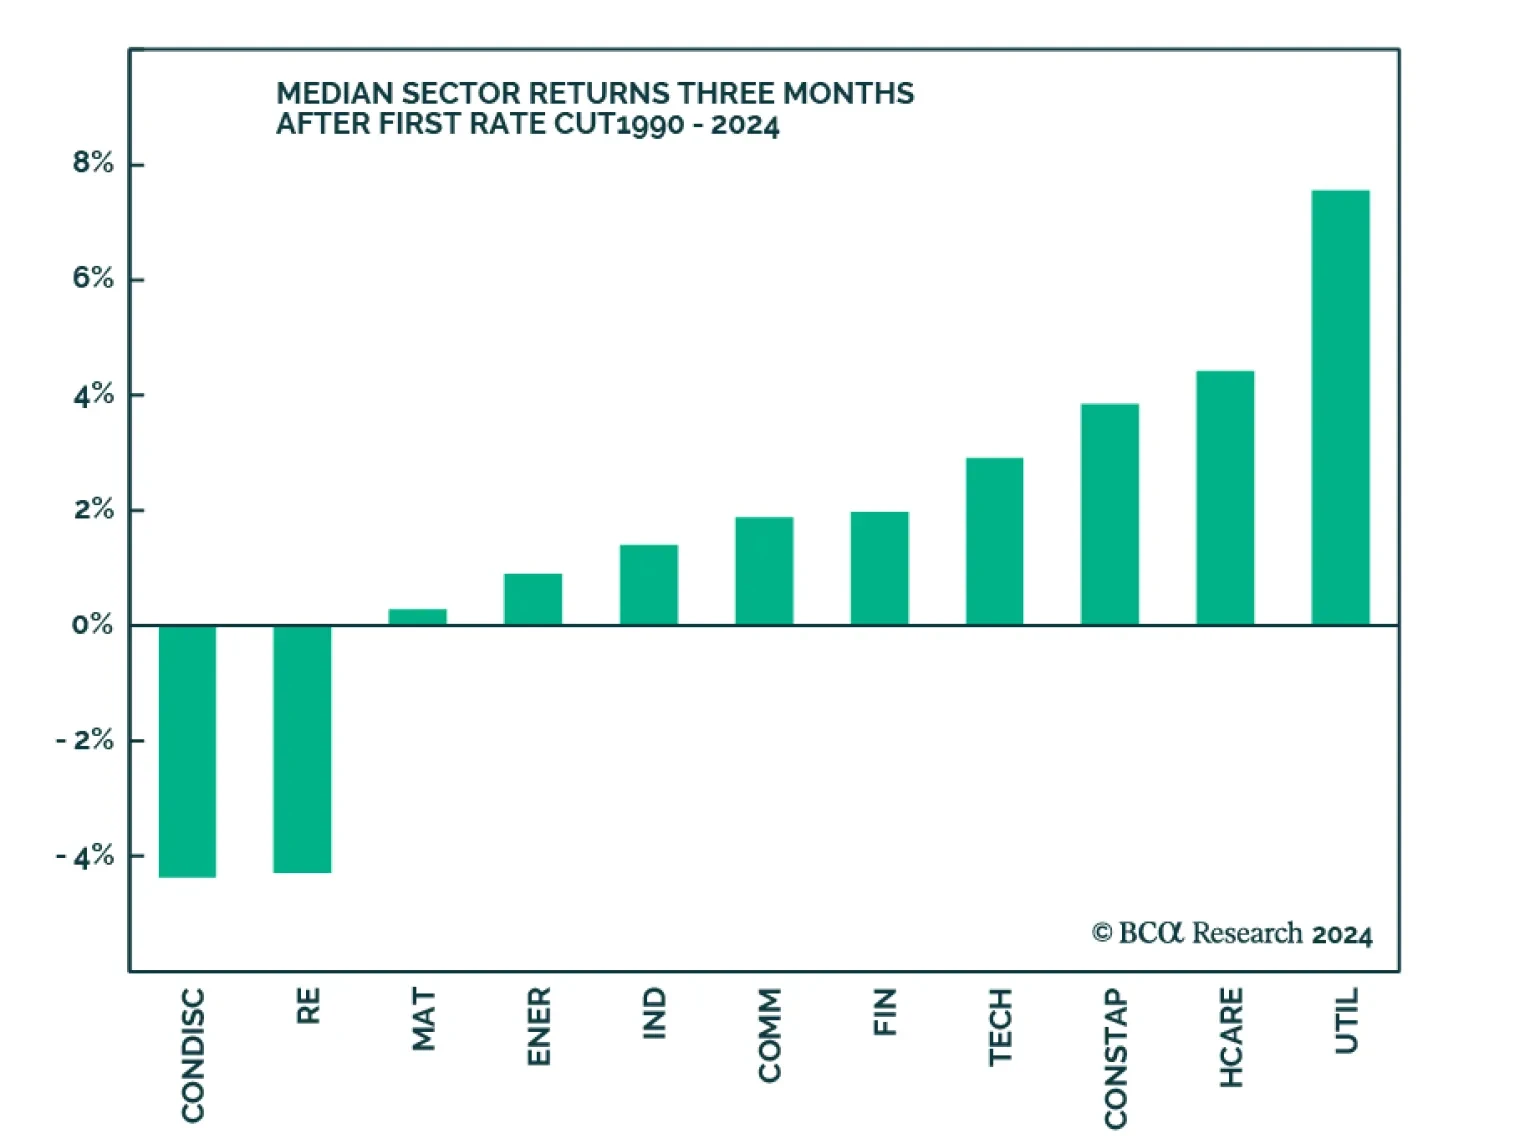
There is a broad-based deterioration of the economic data and a slowdown in consumer spending. On the bright side, inflation prints are better behaved. Rate cuts appear increasingly likely, but they won't stave off a recession. It is time to take profits from the GAI-related industries and bolster the defensive properties of the portfolios. Position for rate cuts.
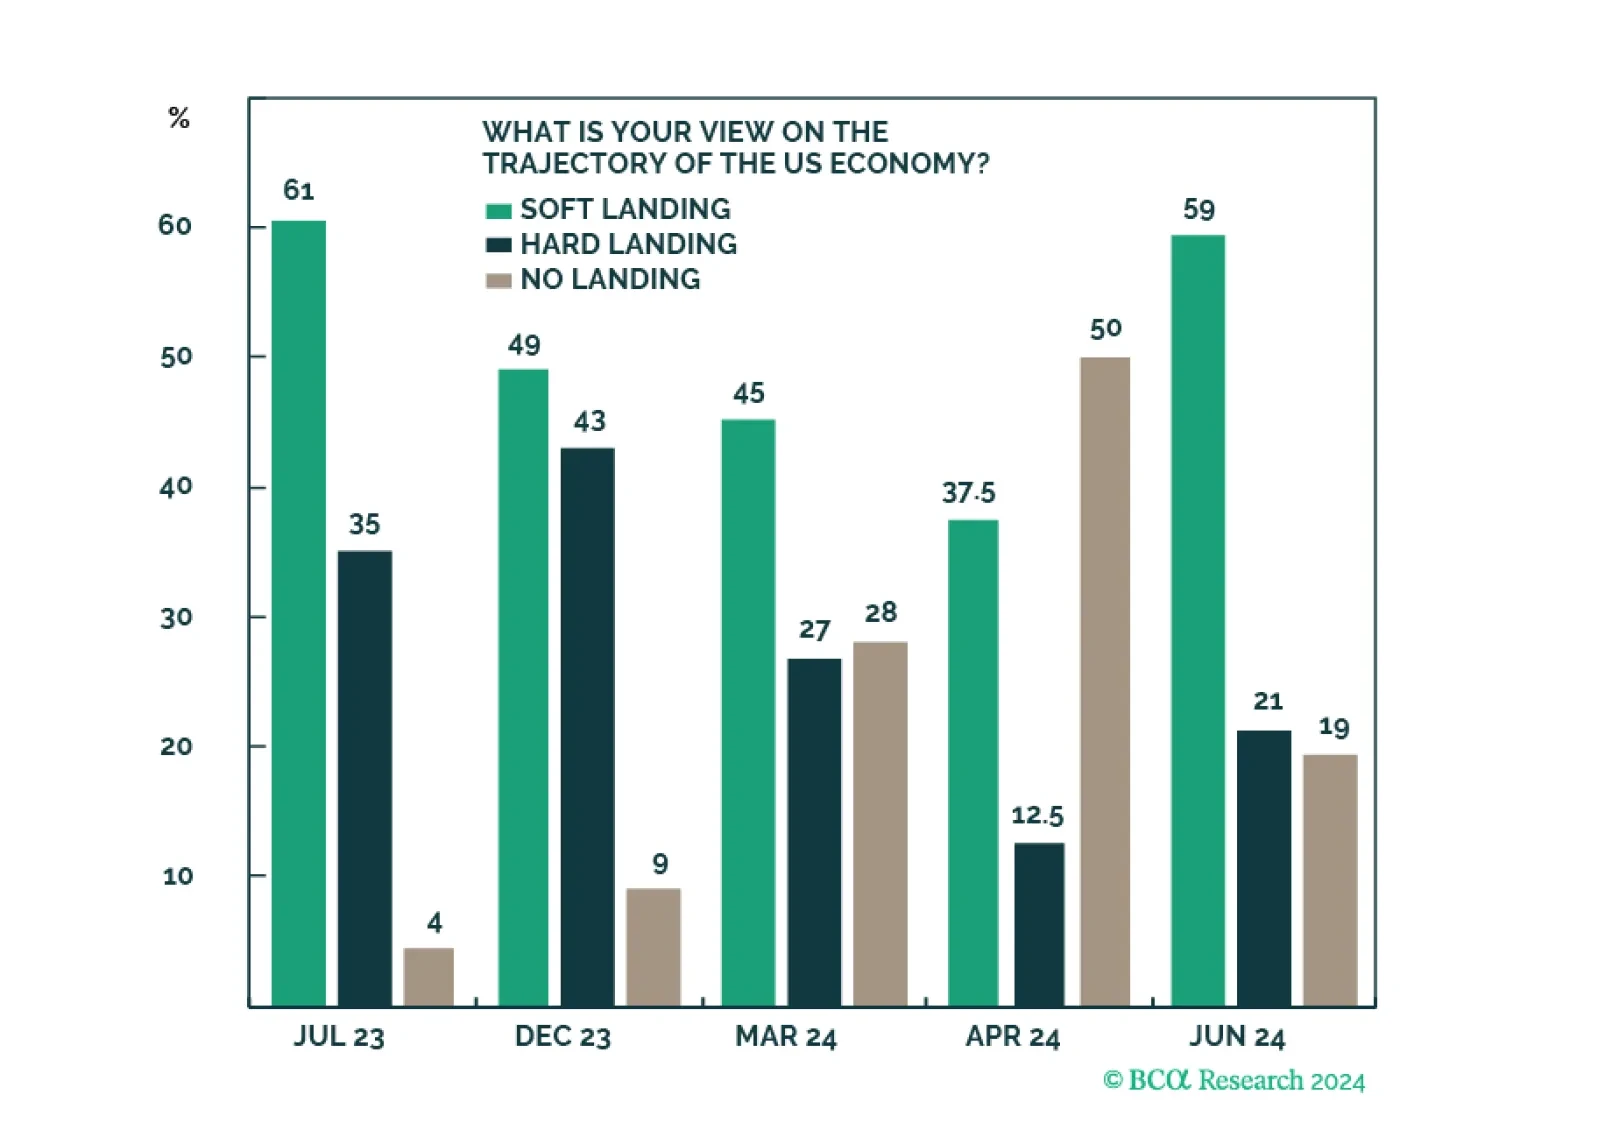
Investors are increasingly more optimistic about the trajectory of the US economy and believe that the “Fed put” is in play limiting the downside. While the majority still have cash to put to work, many are waiting to see if the rally broadens thanks to earnings rebound across non-GenAI sectors. Fairly conservative positioning and expectations of the rangebound markets point to a consensus view that the market may be fully valued, and a soft-landing outcome along with rate cuts, are priced in.