Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Zona Euro

Informe especial

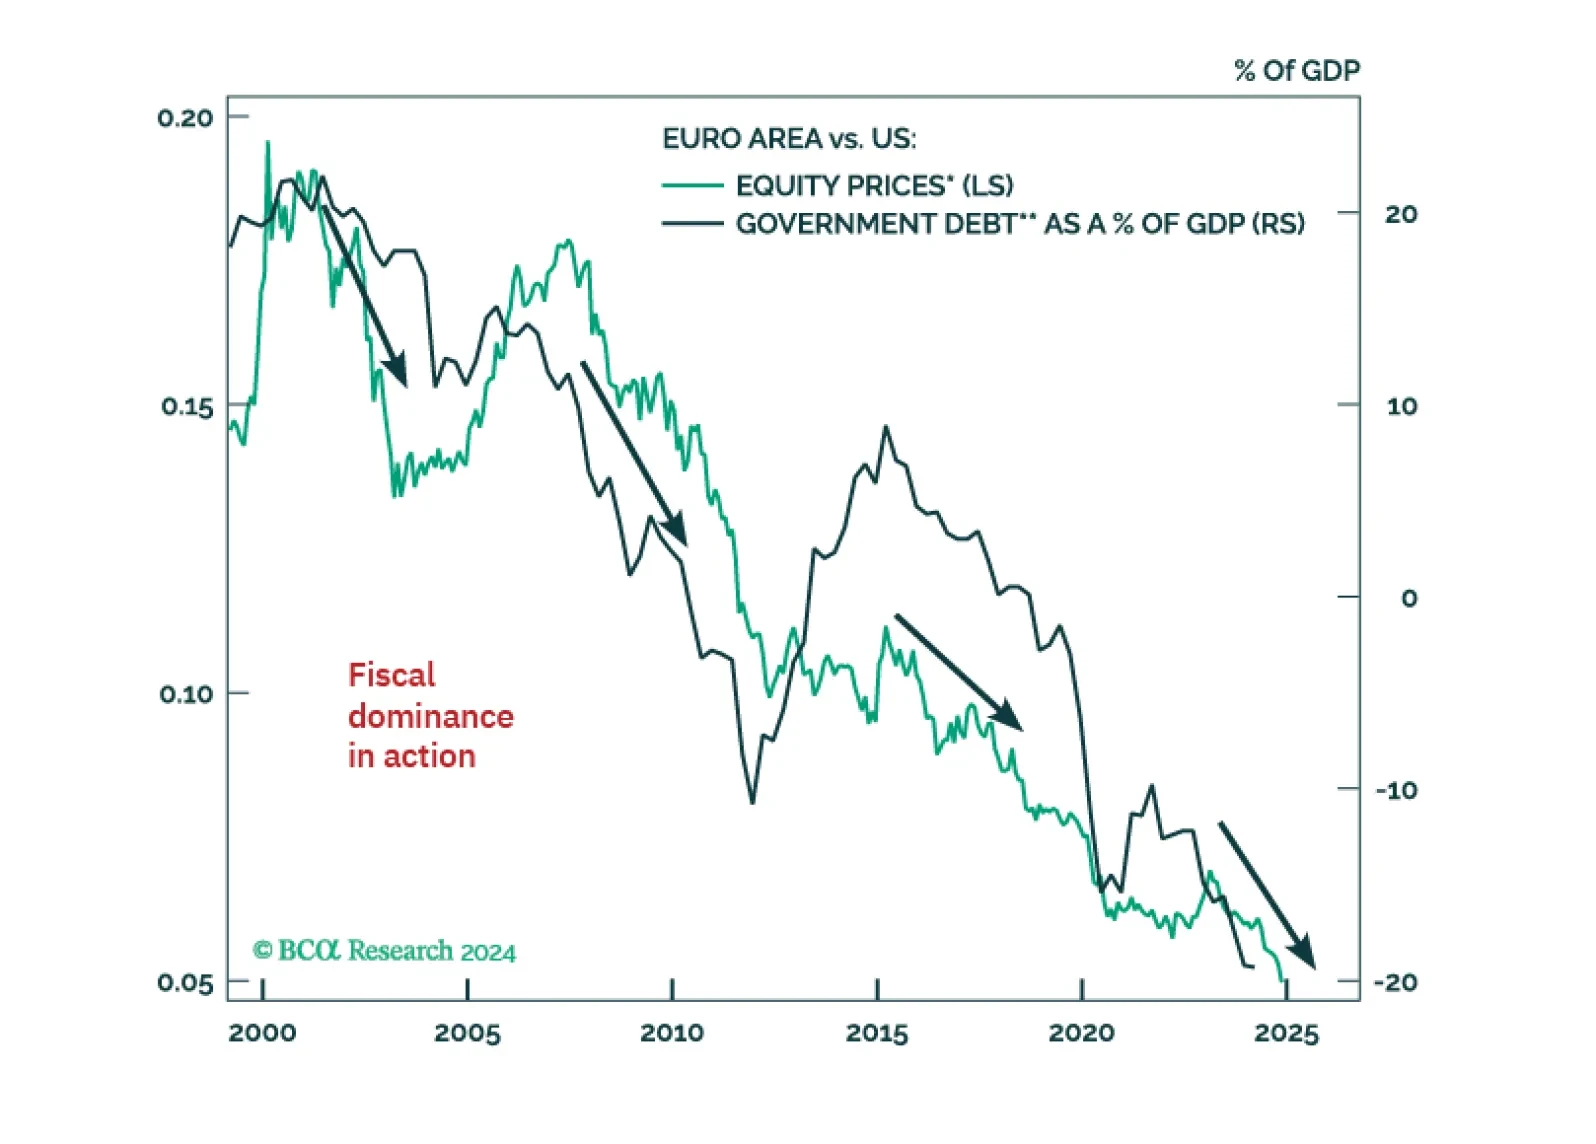
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.

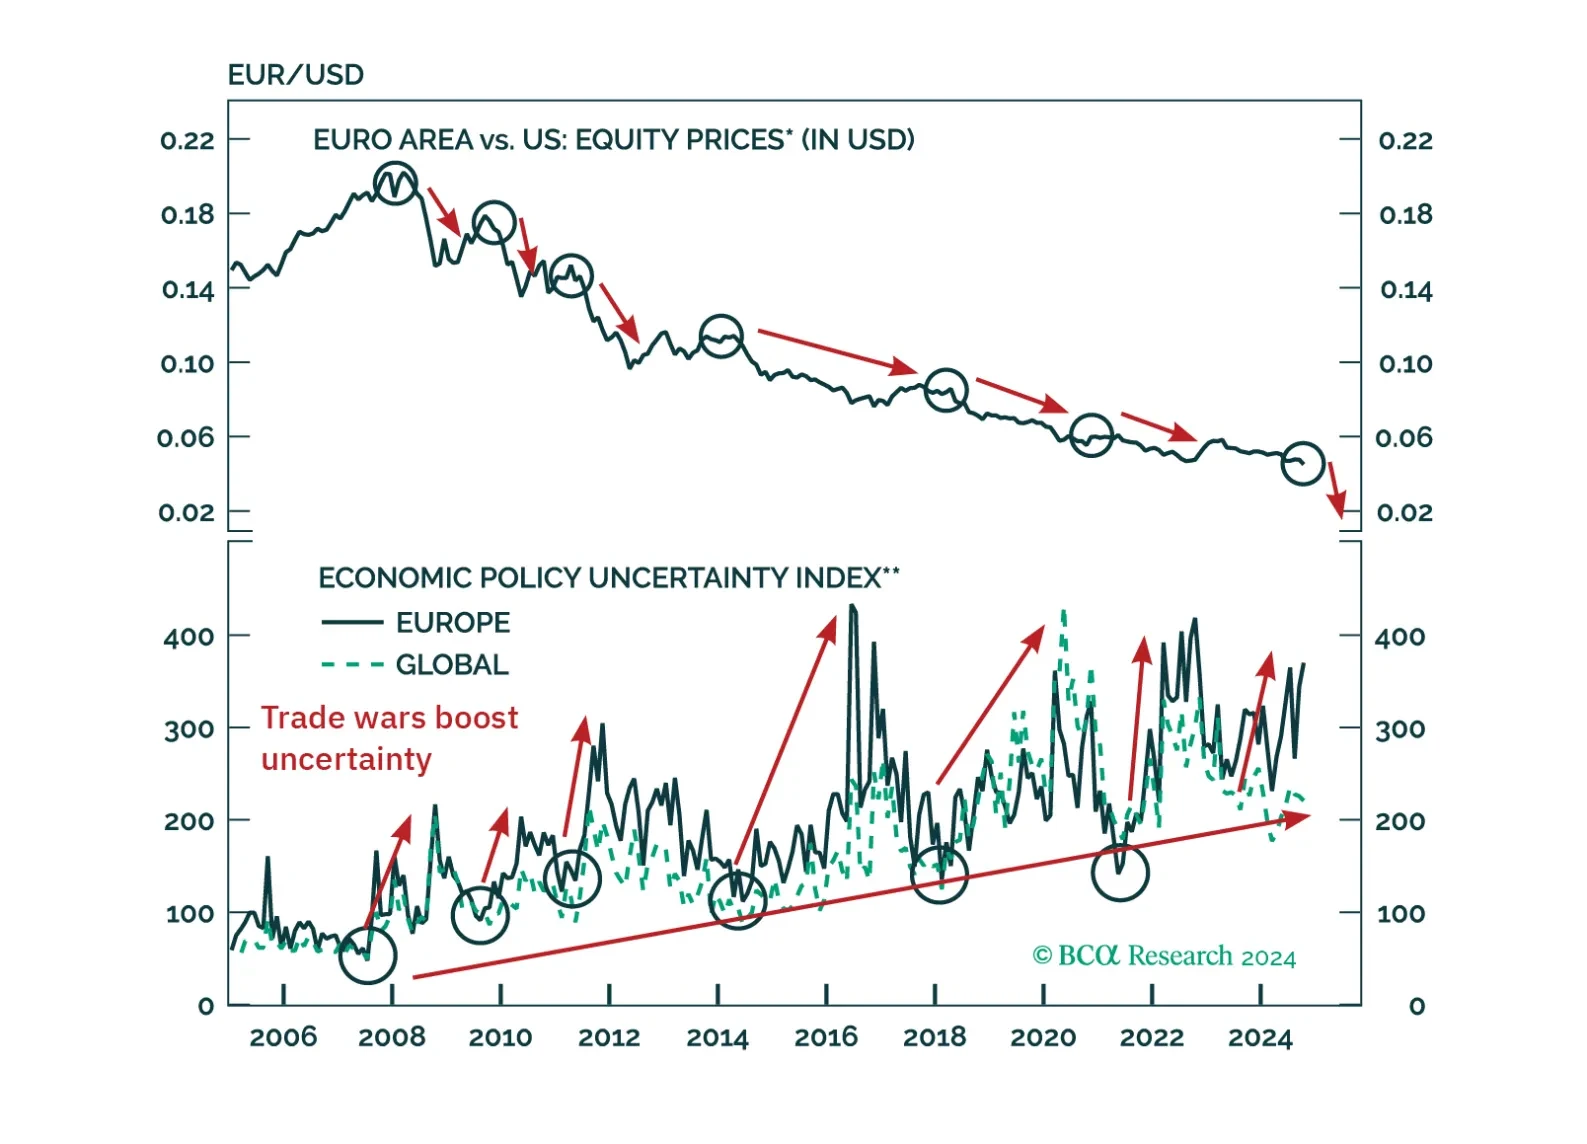
Investors focused on the flurry of cabinet nominations in the aftermath of the US election, but the US does not have a monopoly on political drama. France is going through turmoil of its own. This summer’s snap election left France’s government weakened, and…

European assets and the euro have become oversold and are likely to rebound. Will this move be nothing more than a dead cat bounce leading to more weakness? 

Economic expectations for Germany and the Eurozone disappointed, with the November ZEW decreasing to 12.5 from 20.1. The assessment of current conditions also worsened, implying the sentiment rebound from September will not be sustained. The outlook remains…
Esta semana actualizamos nuestros Monitores de Bancos Centrales (CBMs), que nos ayudan a calibrar cómo debe ajustarse la política monetaria en las economías de mercados desarrollados. Nuestra conclusión es que, si bien en términos generales se requieren condiciones monetarias más acomodaticias, surgen algunas ideas de trading a partir de las divergencias en las señales entre los países del G10.
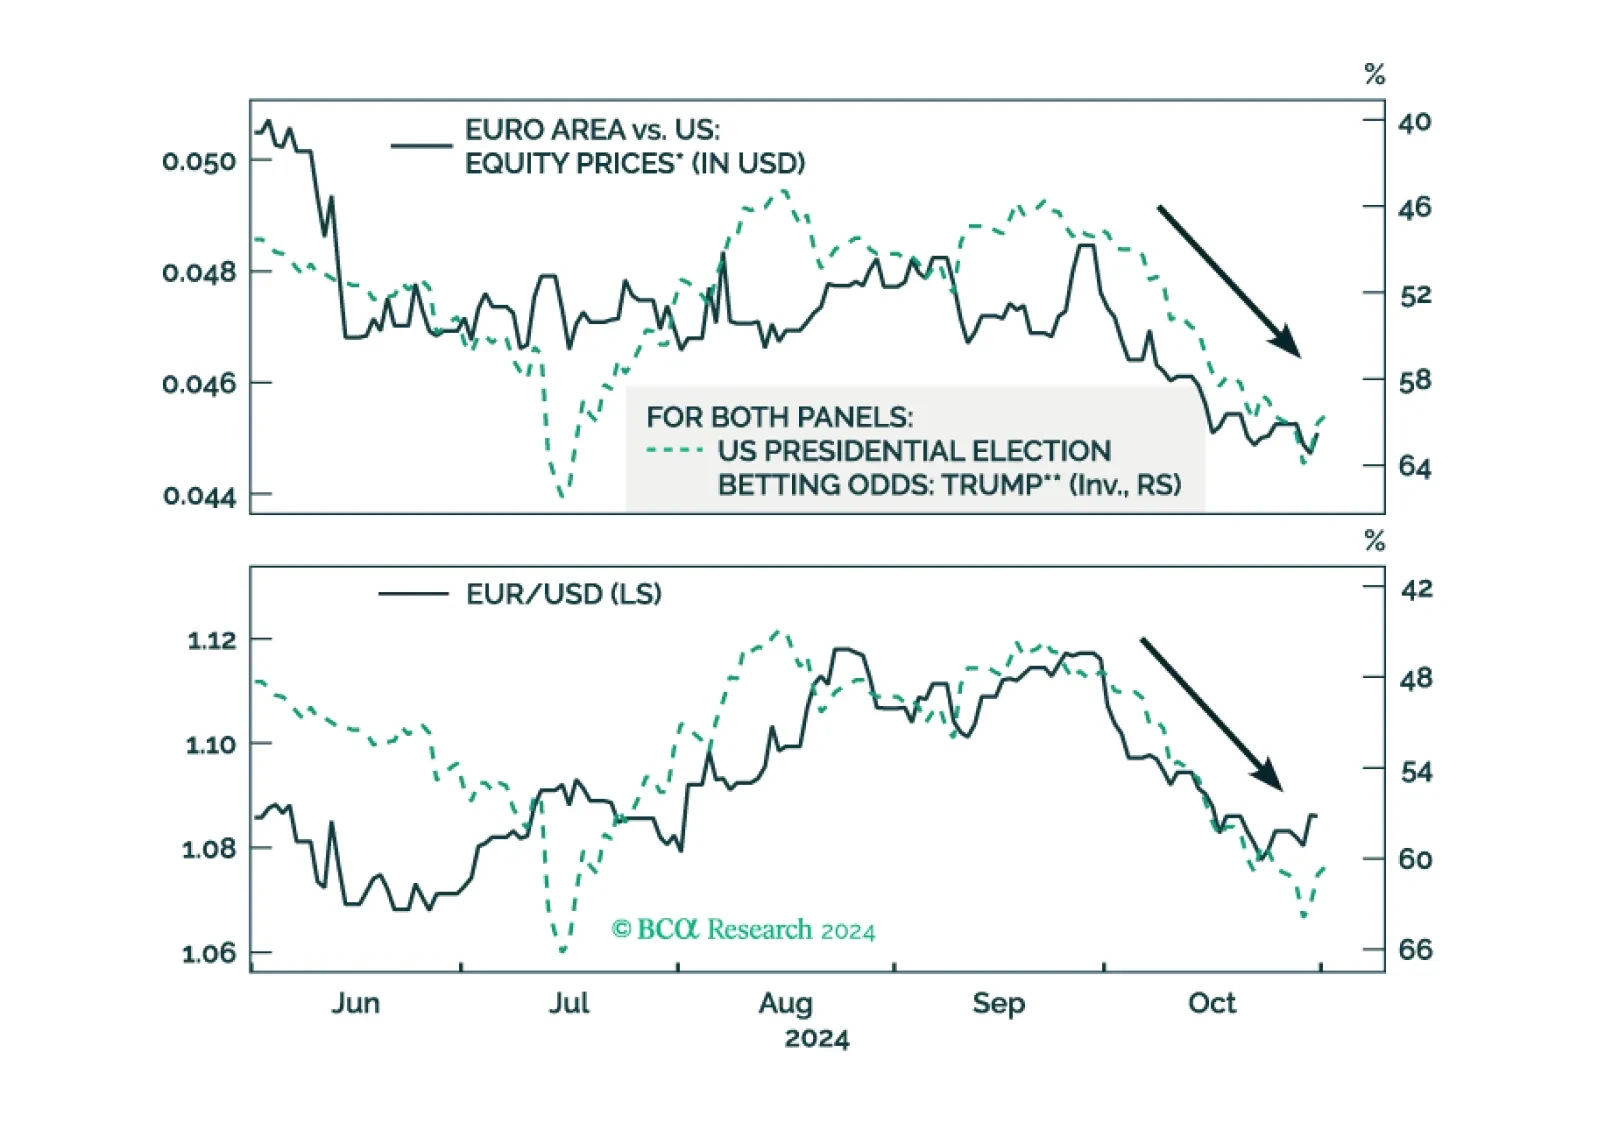
A medida que aumentan las probabilidades de una victoria de Trump, los activos europeos rinden menos que los estadounidenses. ¿Cuál sería el impacto inmediato de una victoria de Trump en las acciones europeas?
Informe especial

Germany’s economy has lagged that of the rest of Europe for nearly 10 years. So have German stocks. Investors are extrapolating these trends to bet on the country’s deindustrialization. Could Germany manage to beat dismal expectations?
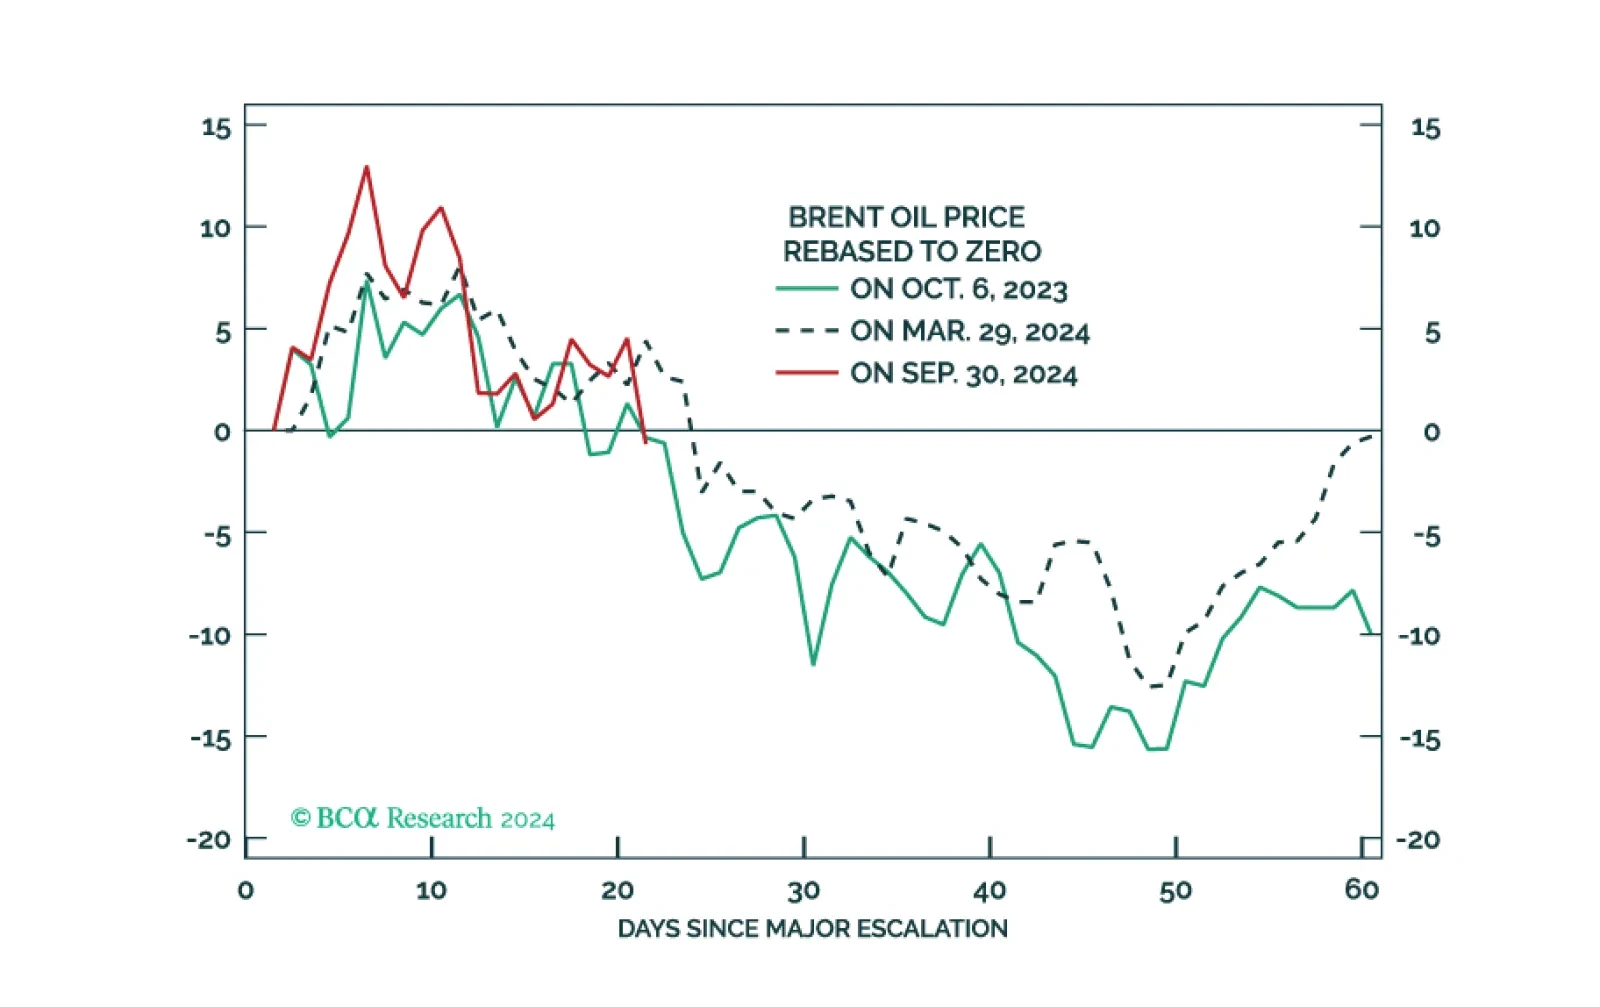
El sistema político mundial se está desestabilizando y Estados Unidos adoptará una postura más agresiva en política exterior, política comercial o en ambas, independientemente del resultado electoral. Tácticamente, apueste por el dólar.
Germany’s problems are well known: Demographics, Chinese competition, underinvestment, energy dependence, and constrained fiscal policy. Our European Investment Strategy colleagues believe this bad news is priced in. More optimism is warranted as cyclical…

Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?