Chile
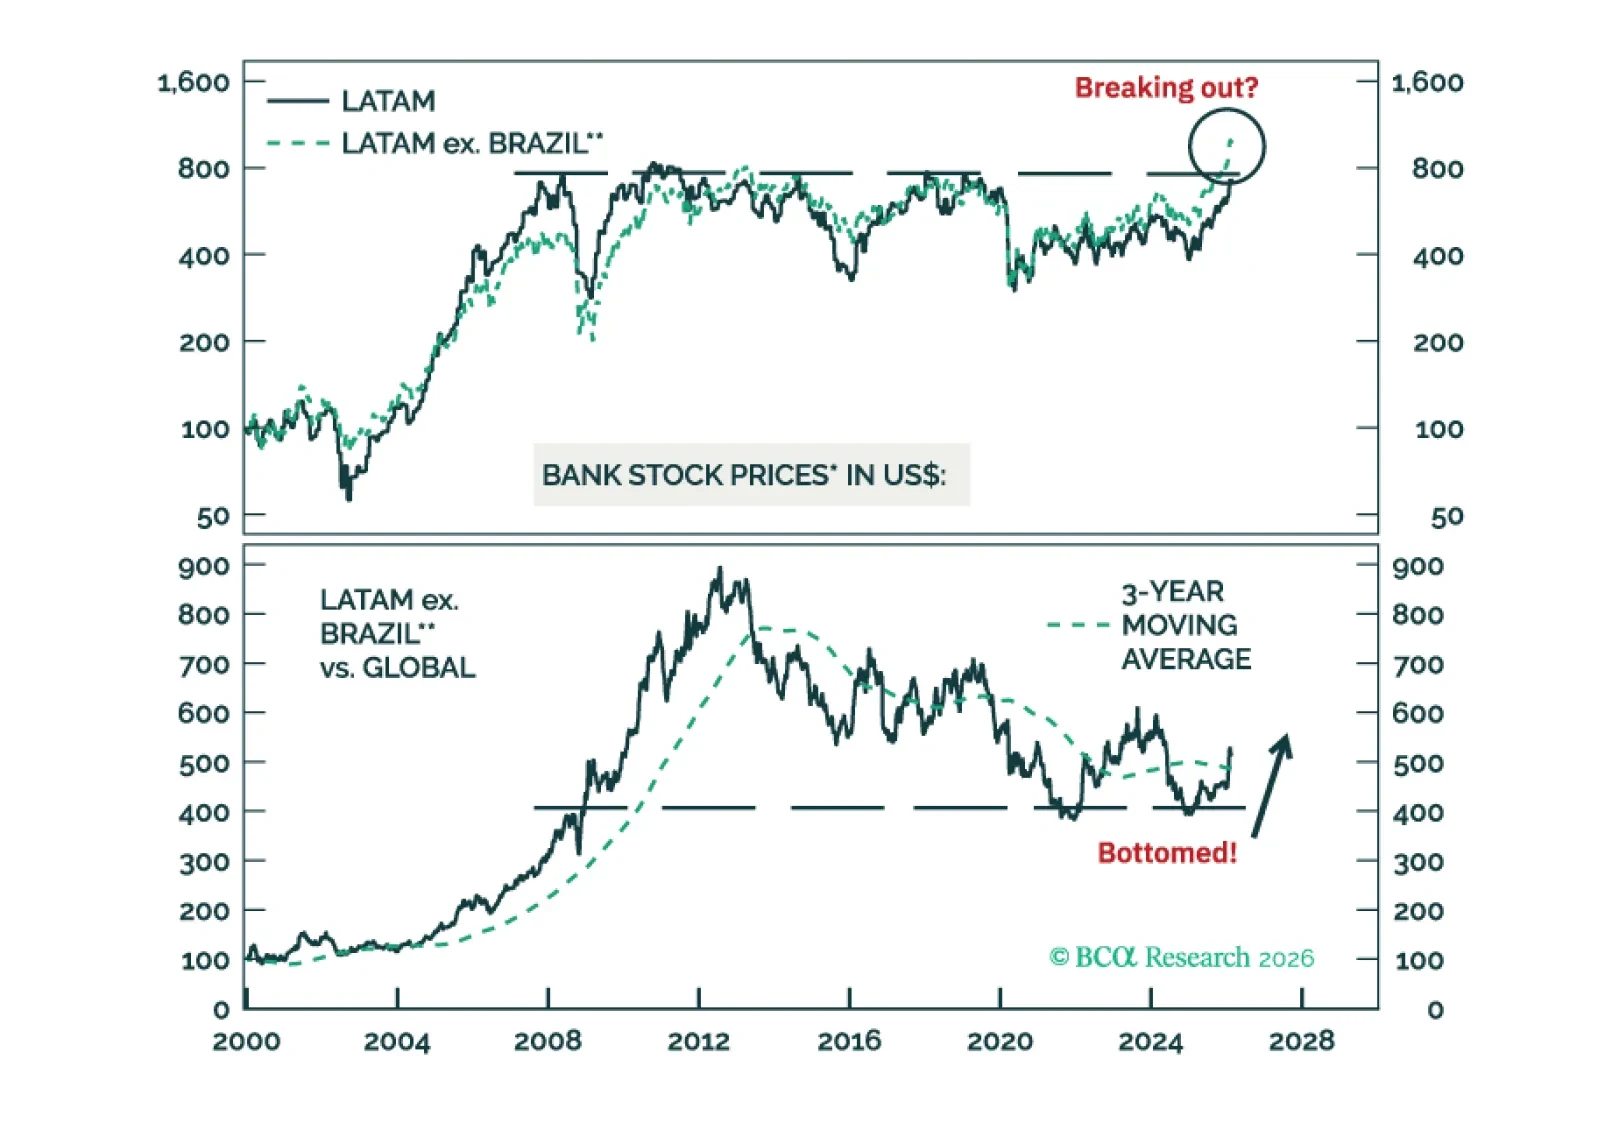
Ir largo en bancos de LATAM ex. Brasil / ir corto en acciones bancarias globales. Las acciones de los bancos brasileños tendrán un desempeño inferior debido a macro fundamentos pobres y en deterioro.


Following this weekend's election, we reiterate an overweight stance across Chilean risk assets relative to EM benchmarks and advise buying local currency government bonds (currency unhedged).

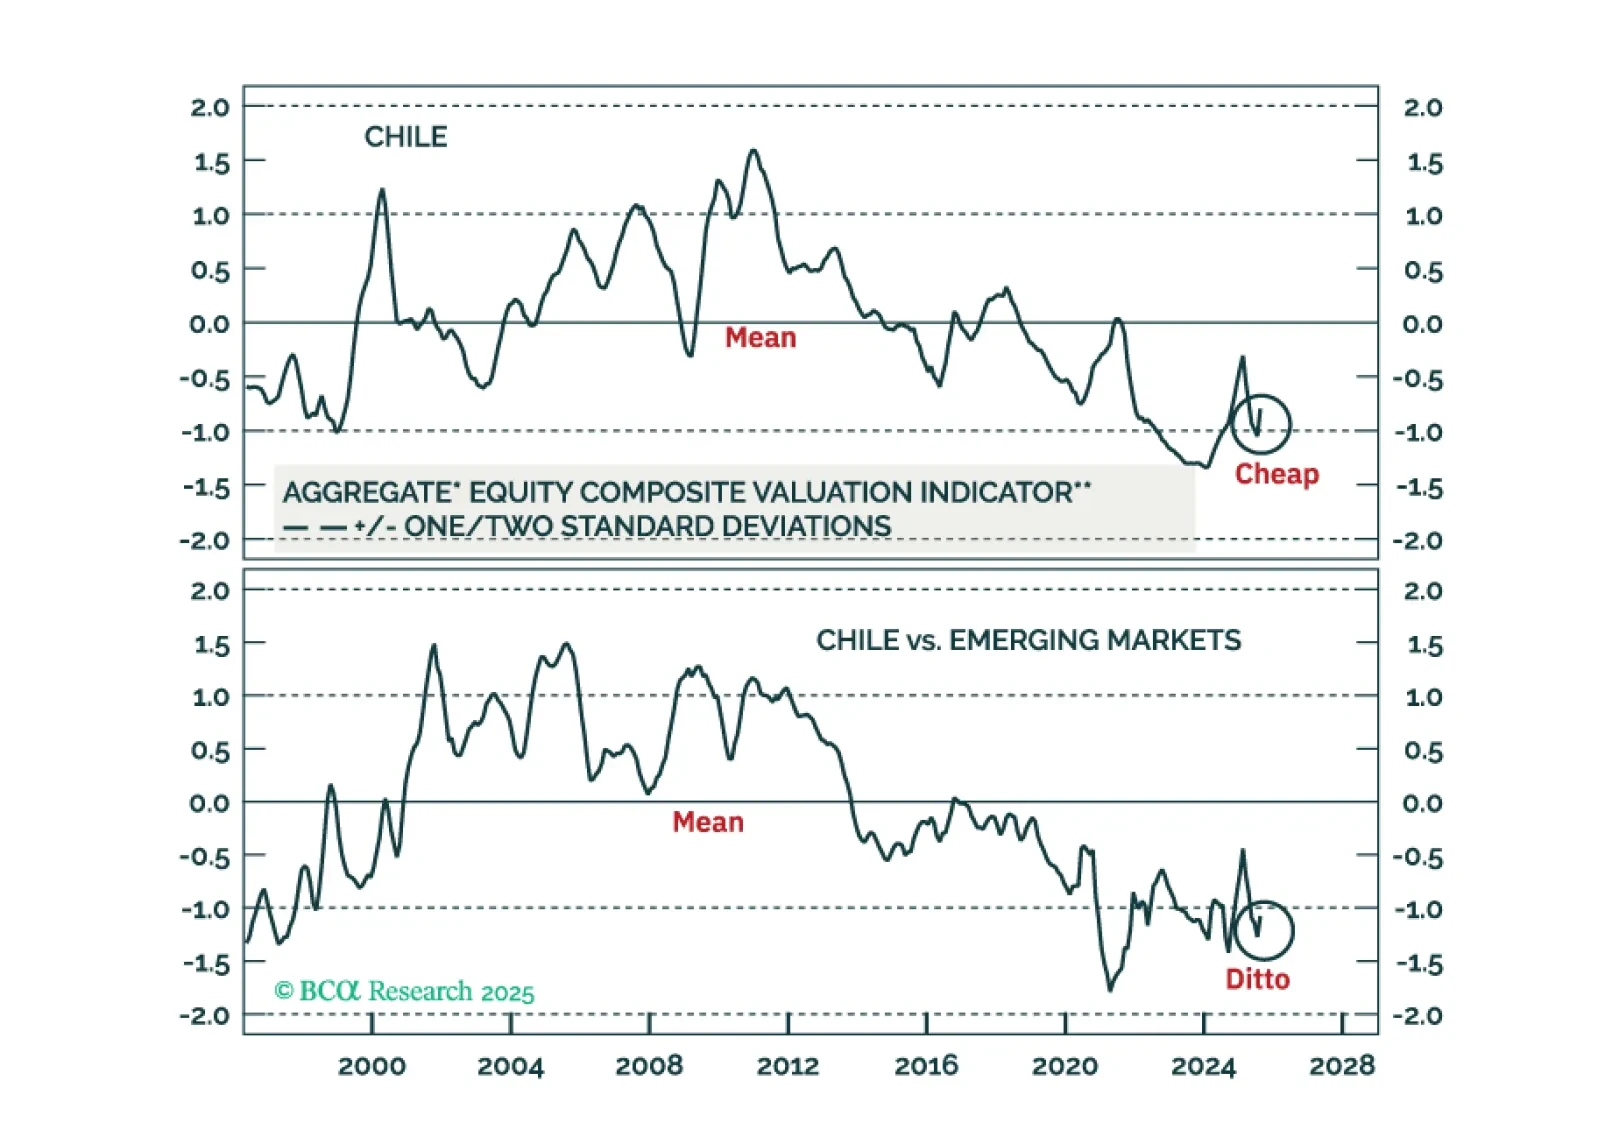
Las acciones chilenas están experimentando una reevaluación estructural. Un giro político hacia una administración proempresarial, un entorno macroeconómico favorable y un tipo de cambio resistente impulsarán el rendimiento superior de los mercados chilenos frente a sus pares de mercados emergentes.
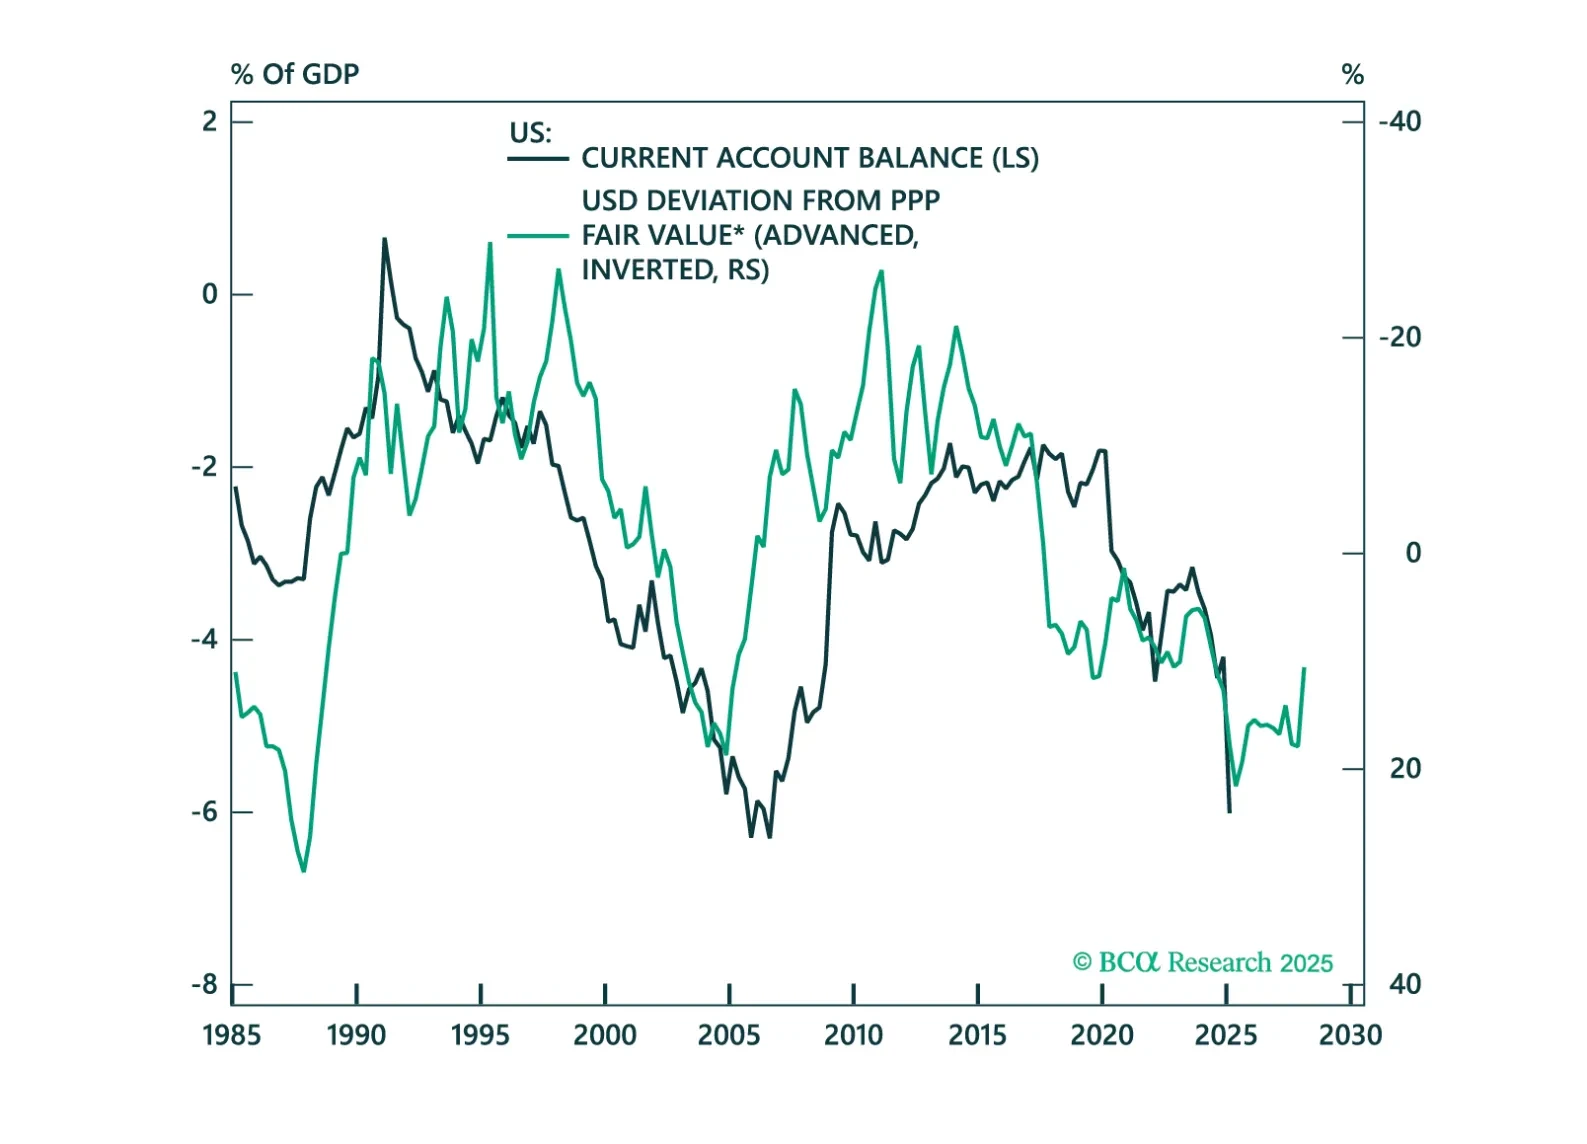
En este libro de gráficos, analizamos la balanza de pagos en países desarrollados (DM) y mercados emergentes (EM). A Estados Unidos no le va bien, pero a algunos otros países tampoco.
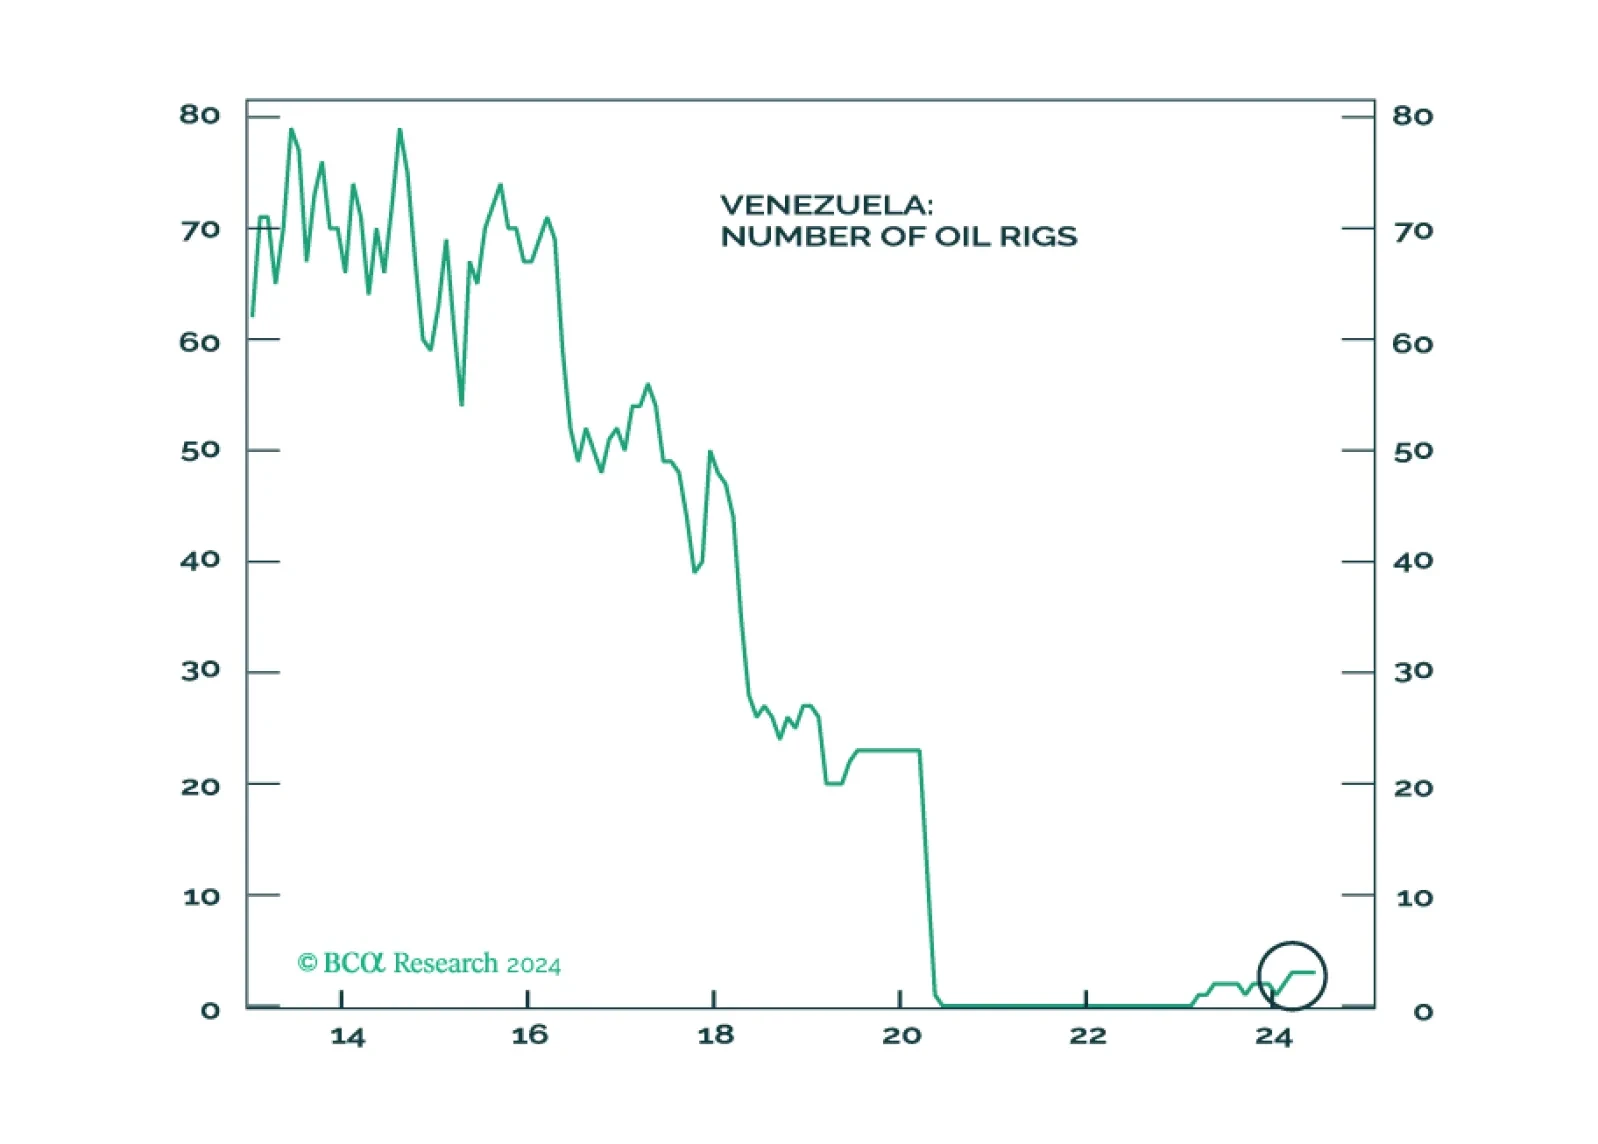
Oil markets will not be impacted by Venezuela in the near term, but by shocks from the Middle East. Maduro’s ability to stay in power in the short-term removes an avenue of oil supply relief. The same avenue is cut off if Trump is reelected. Geopolitical shocks in Venezuela could present tactical buying opportunities for Chile, Peru, and Colombia.
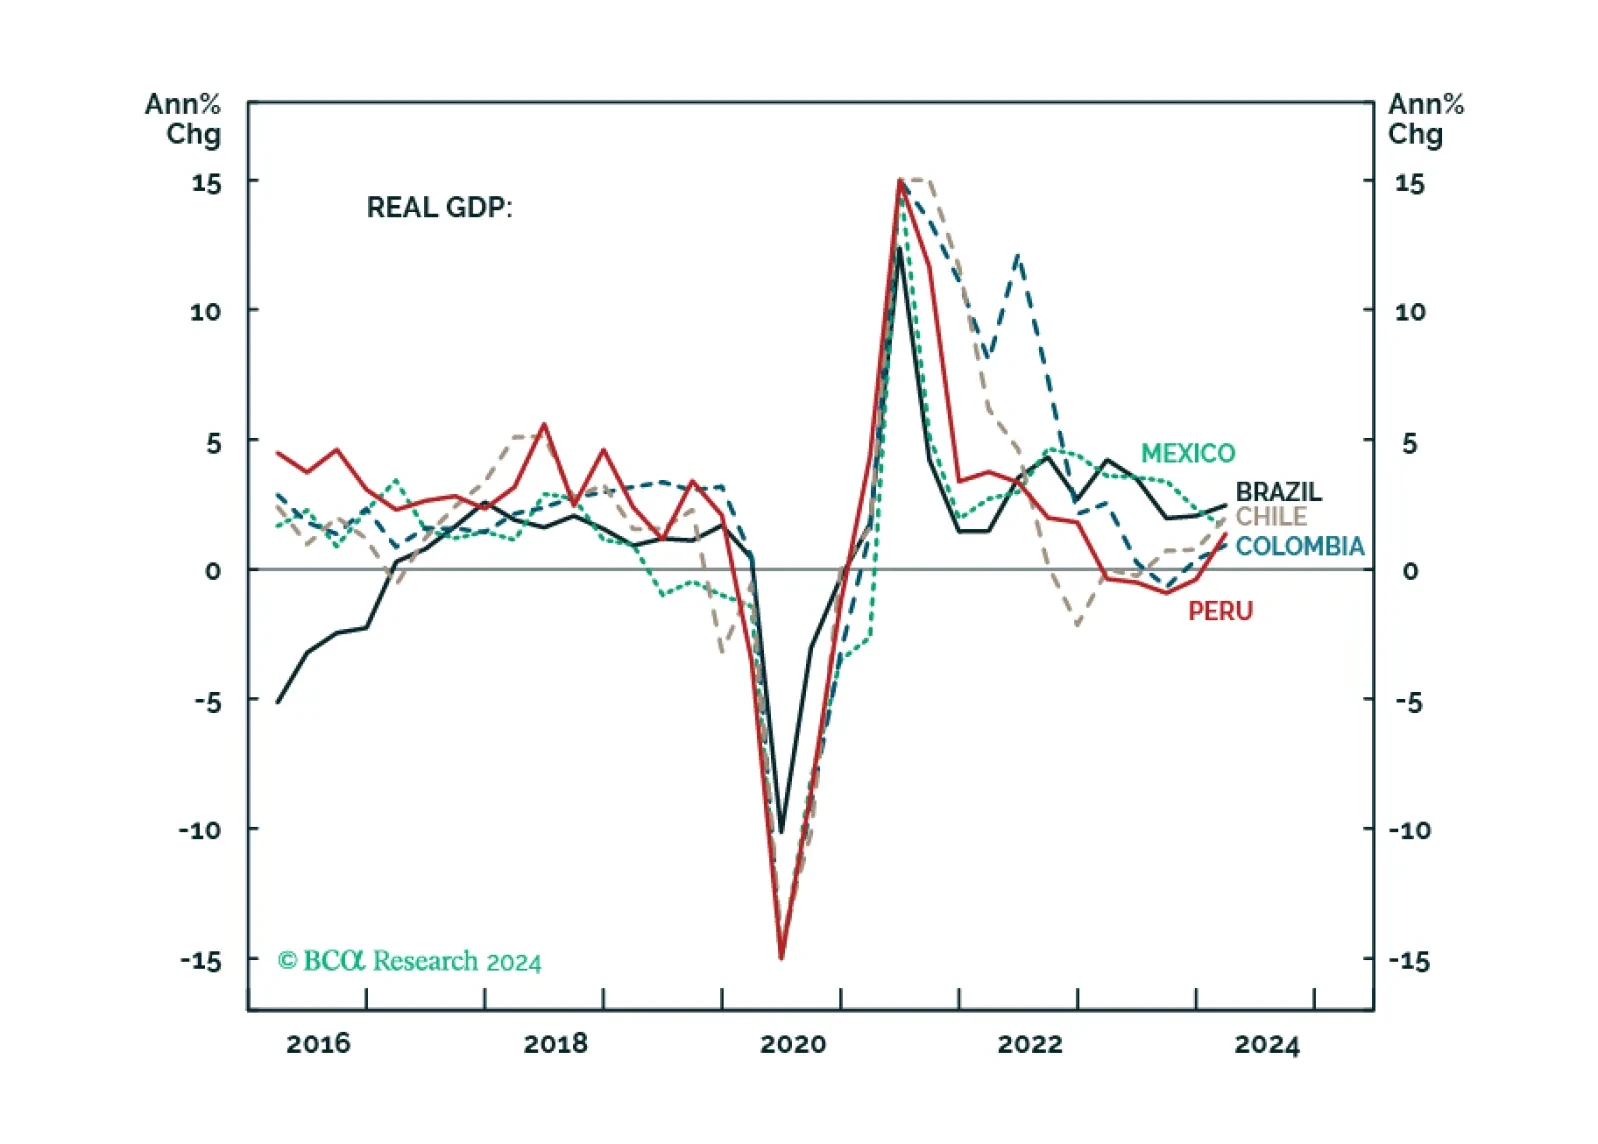
Non-trivial macro divergences have emerged between mainstream LATAM economies. This report compares and ranks Brazil, Mexico, Colombia, Chile, and Peru based on their business cycle outlook, macro policy stance, external accounts, and structural fundamentals. All in all, LATAM risk assets will fall in absolute terms given a strengthening US dollar and a global risk-off move in the coming months. Within LATAM, we favor Mexico, Chile and Peru, are neutral on Brazil, and bearish on Colombia.
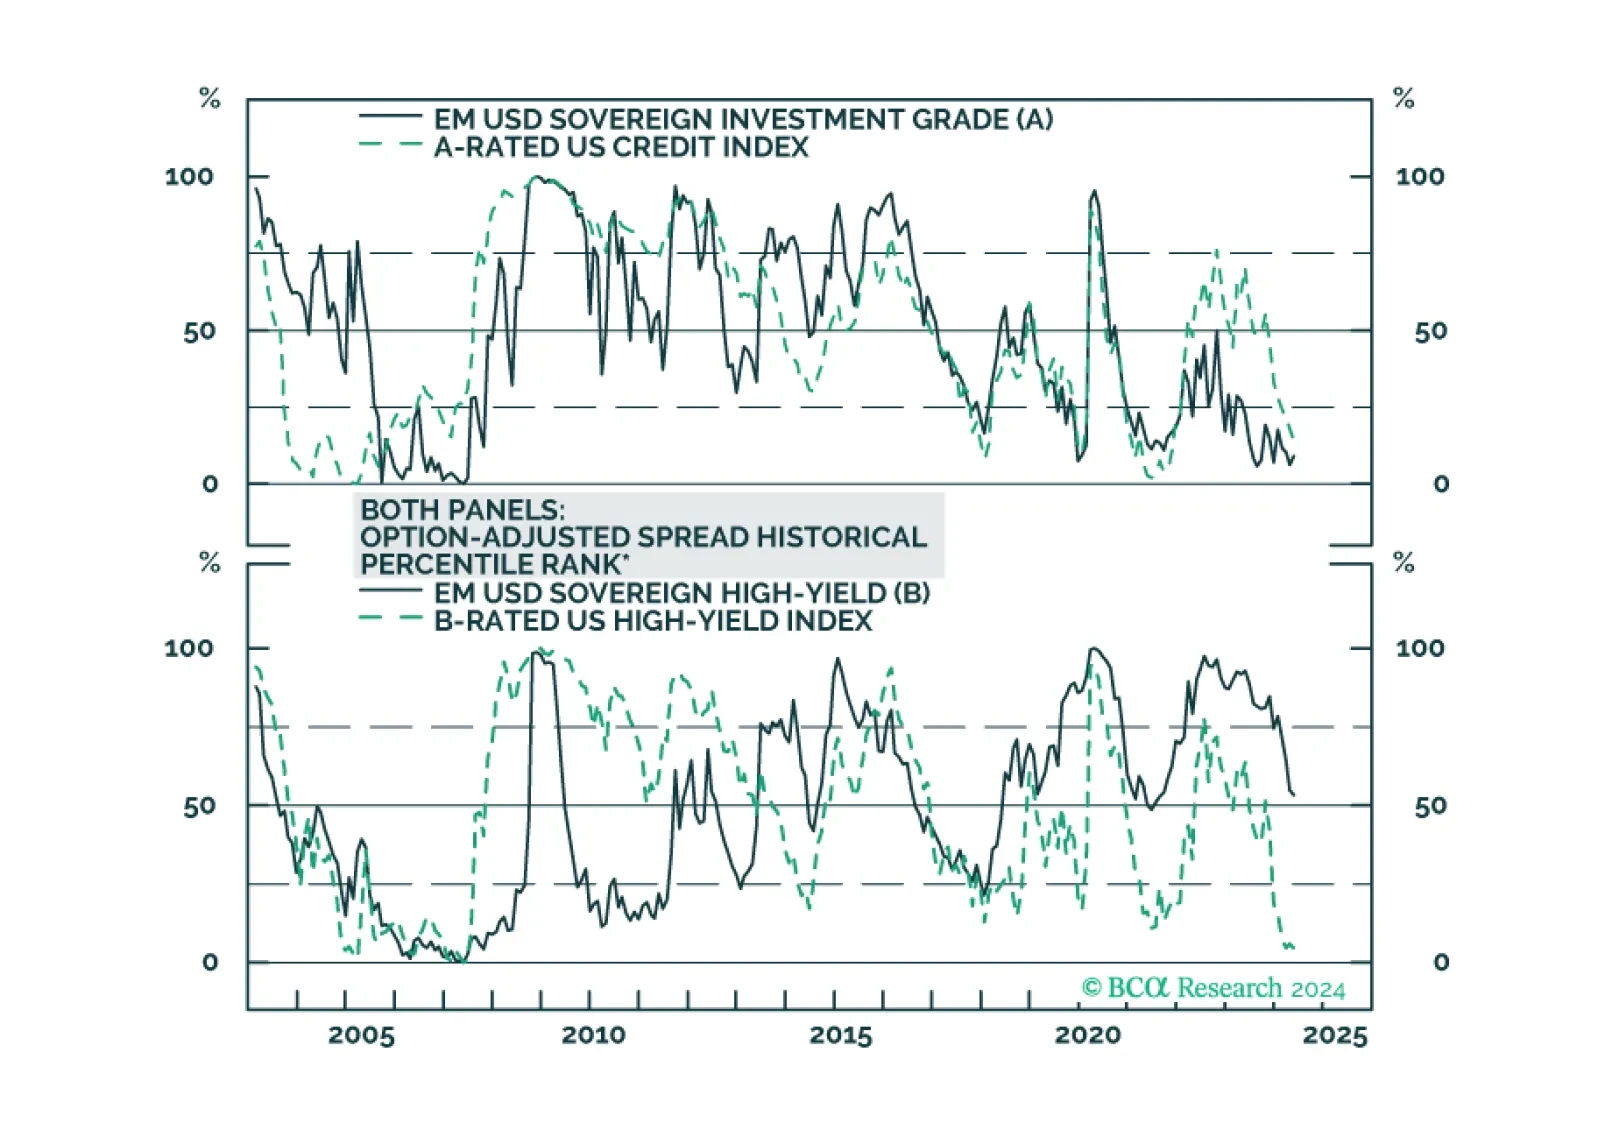
We dig into the USD-denominated Emerging Market Sovereign Index to see which credit tiers and countries offer value relative to US Credit.