Skip to main content

Economy

Special Report

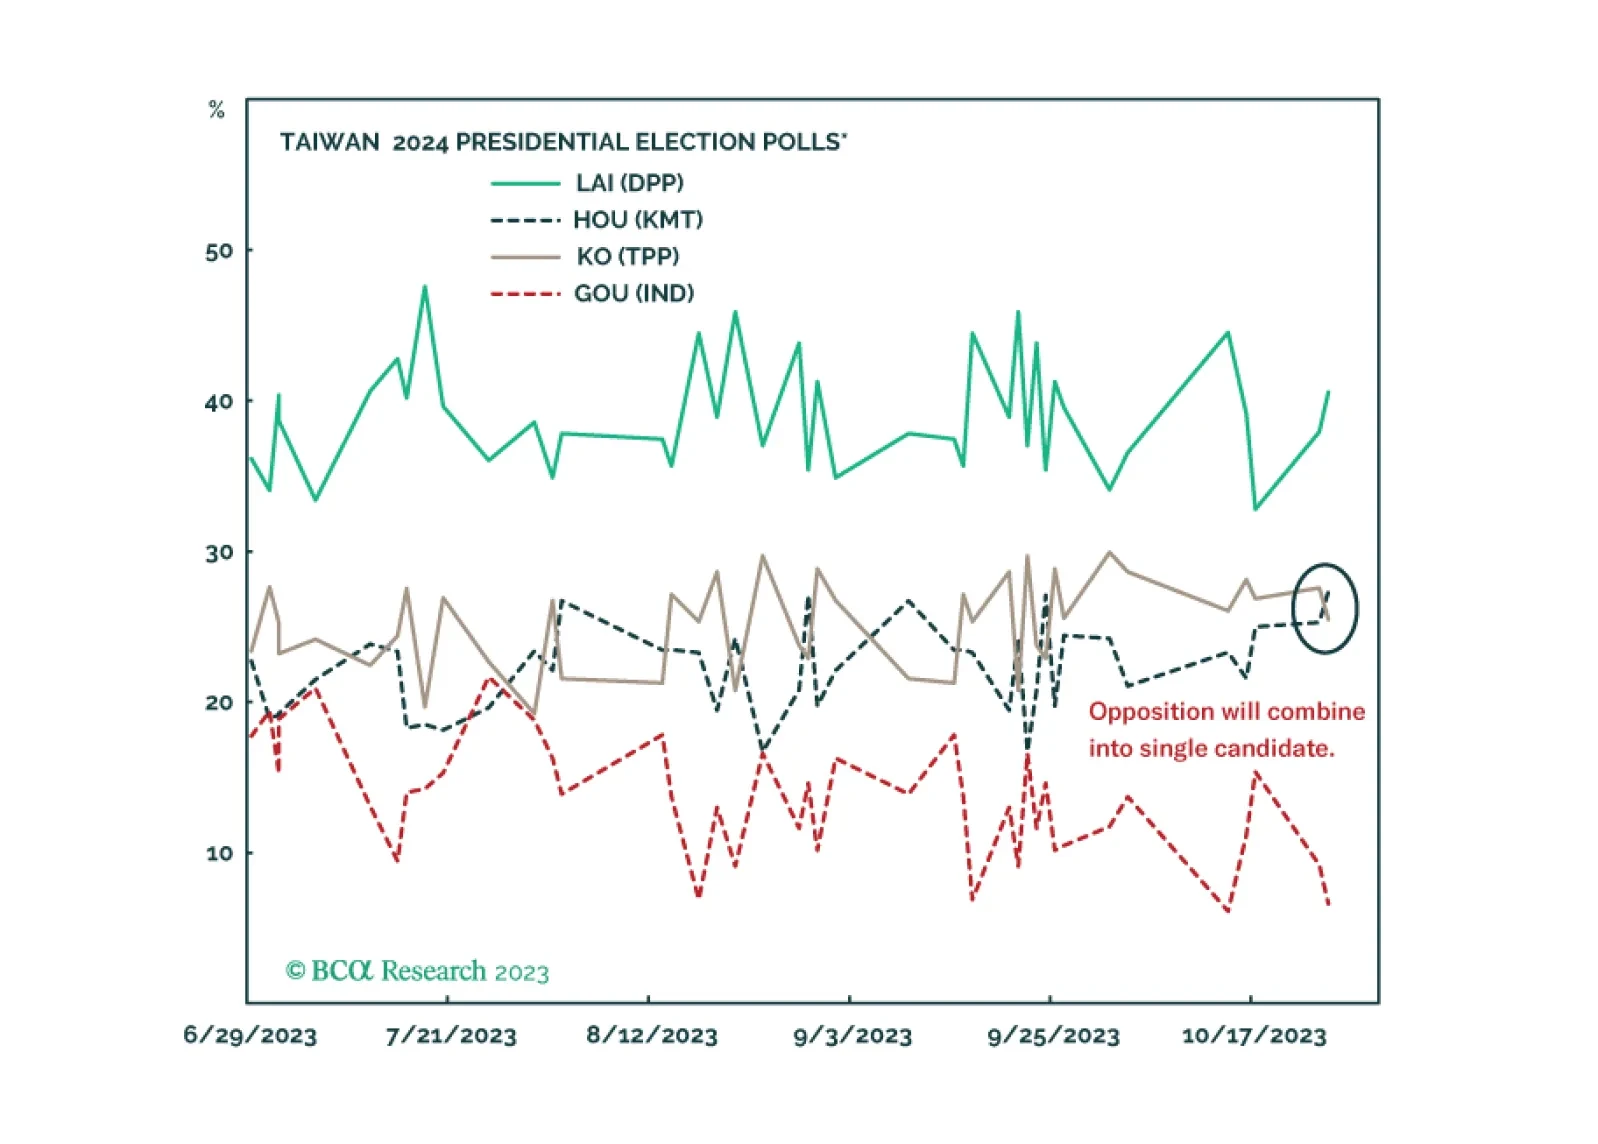
Investors should not get their hopes up about the Biden-Xi summit. Wait to see if a new ruling party is elected in Taiwan before downgrading geopolitical risk in the Taiwan Strait. US-China strategic détente is possible but neither the geopolitics nor the macro backdrop warrant a risk-on position next year.

The latest house price data indicate that China's housing market remains weak. The prices of newly built homes across 70 medium and large Chinese cities declined by 0.4% m/m in October – a faster pace of decline than the 0.3% m/m drop registered in September…
US jobless claims have been trending higher in recent weeks, confirming that labor market conditions are deteriorating. Initial claims came in slightly above consensus estimates on Thursday, increasing by 231 thousand versus expectations of a 220 thousand…
Special Report

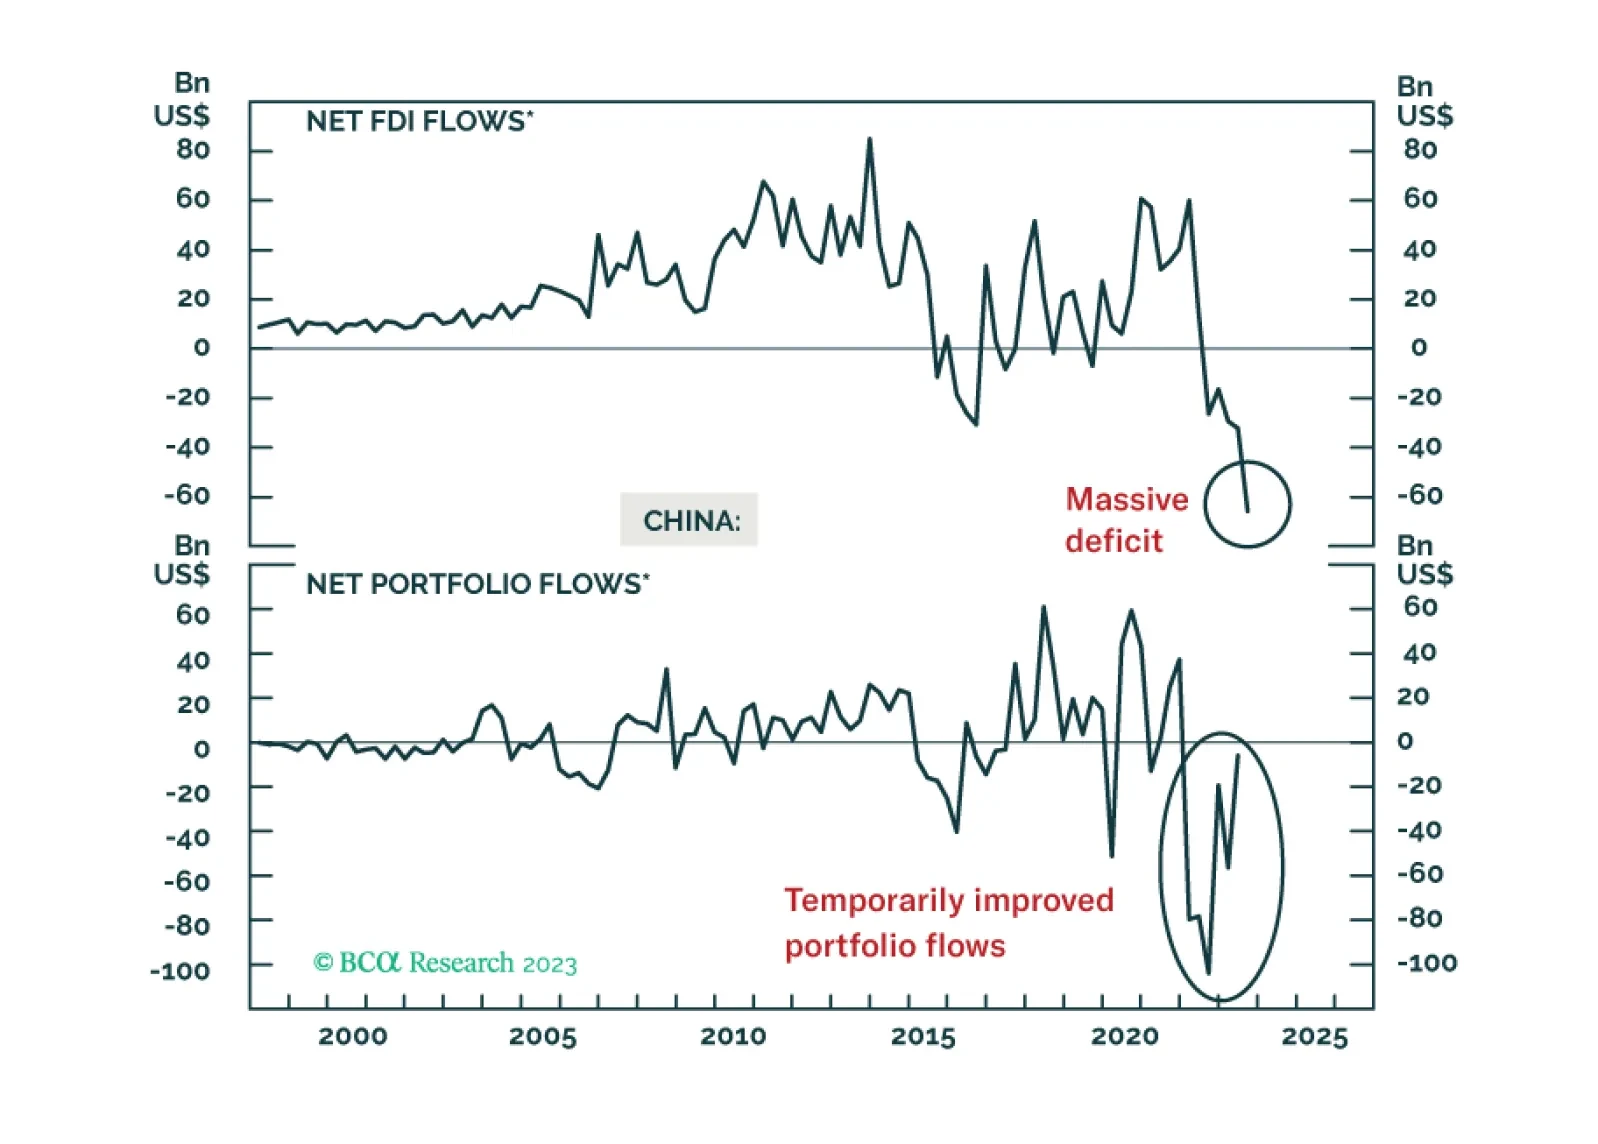
China’s capital outflows will likely remain substantial at least through the next few quarters. This wave of capital outflows will likely be more chronic, albeit less acute than the 2015-16 episode. Persistent capital outflows will exert downward pressure on the RMB.
The US retail sales release delivered a mixed signal about US consumption. Although the headline figure contracted by 0.1% m/m in October, it was better than expectations of a 0.3% m/m decline. Moreover, the September increase was revised up from 0.7% m/m to…
On the surface, the acceleration in Chinese retail sales and industrial production growth in October suggests that the economy is holding up. Retail sales expanded by 7.6% y/y last month – beating expectations of 7.0% y/y following a 5.5% y/y increase in…
The New York Fed's Empire Manufacturing Index unexpectedly returned to positive territory in November, climbing 14 points to its highest level since April. The headline index suggests that manufacturing activity is expanding in New York State – a positive…
According to BCA Research’s China Investment Strategy service, Chinese policymakers are facing the Impossible Trinity. When faced with rapid currency depreciation in August-September, the PBoC deliberately tightened liquidity and steered interest rates…
Special Report

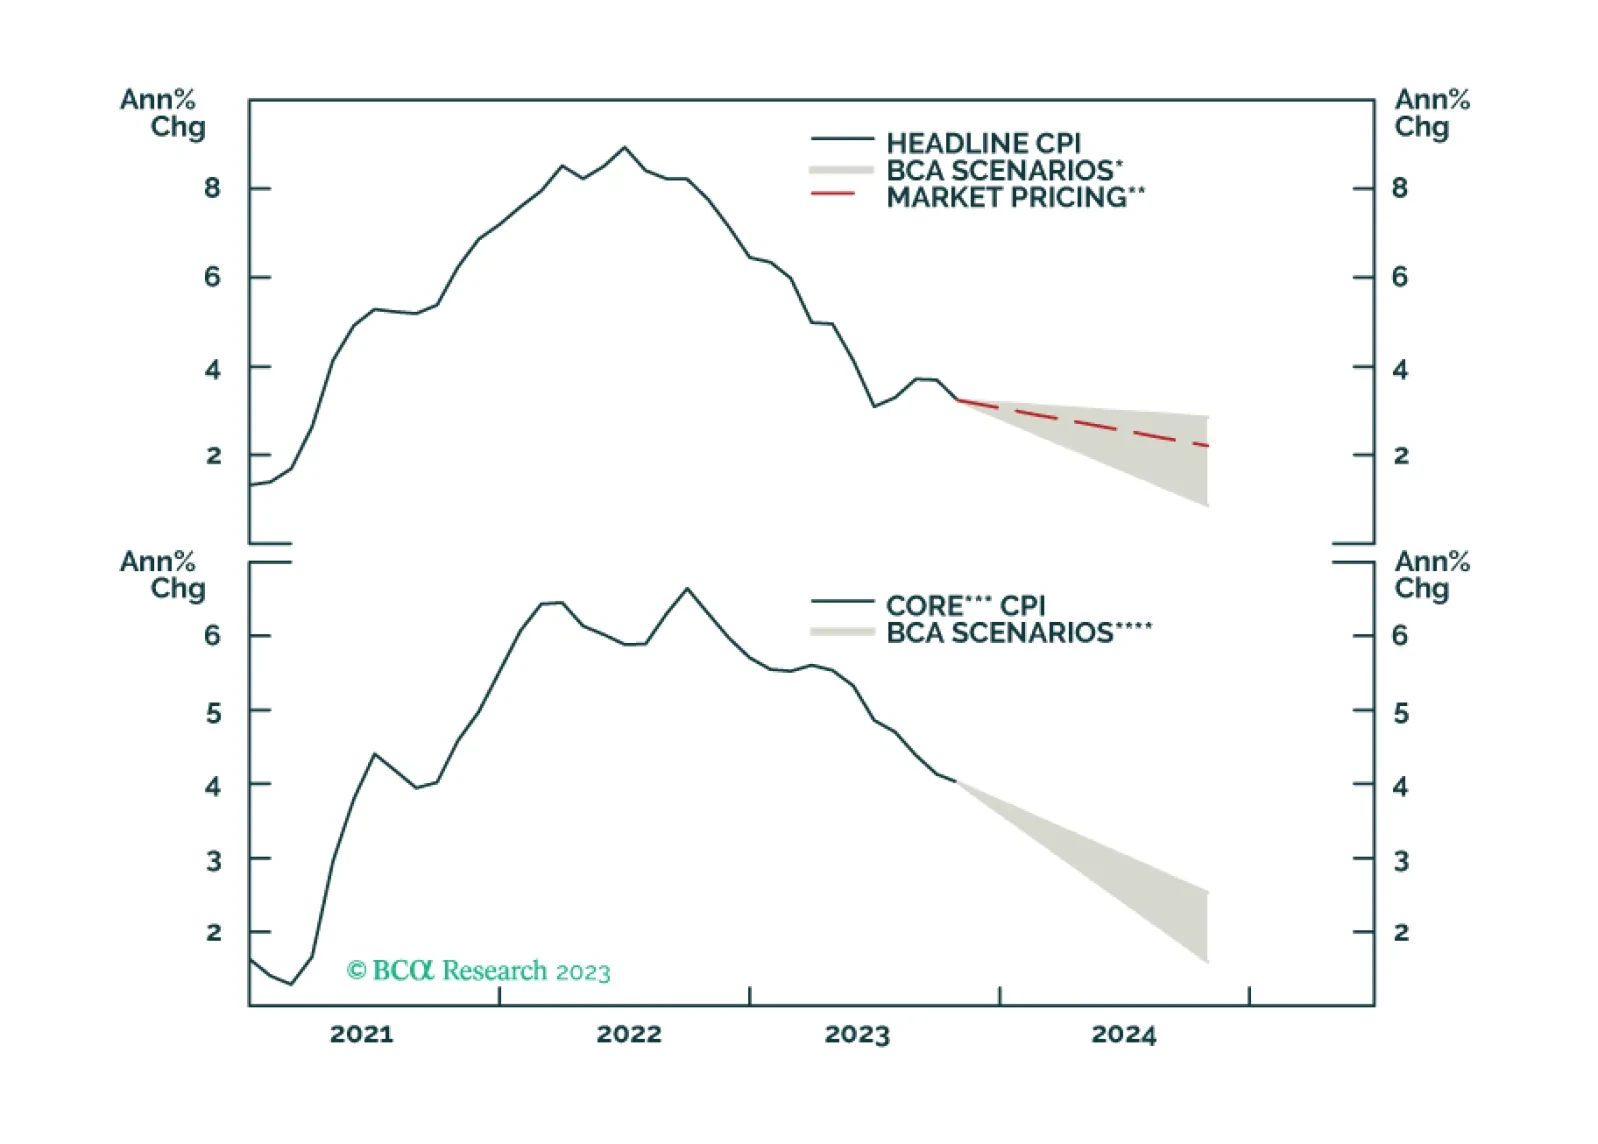
This week’s Special report revisits our TIPS Golden Rule. We provide a 12-month inflation forecast and discuss how it impacts our TIPS view.
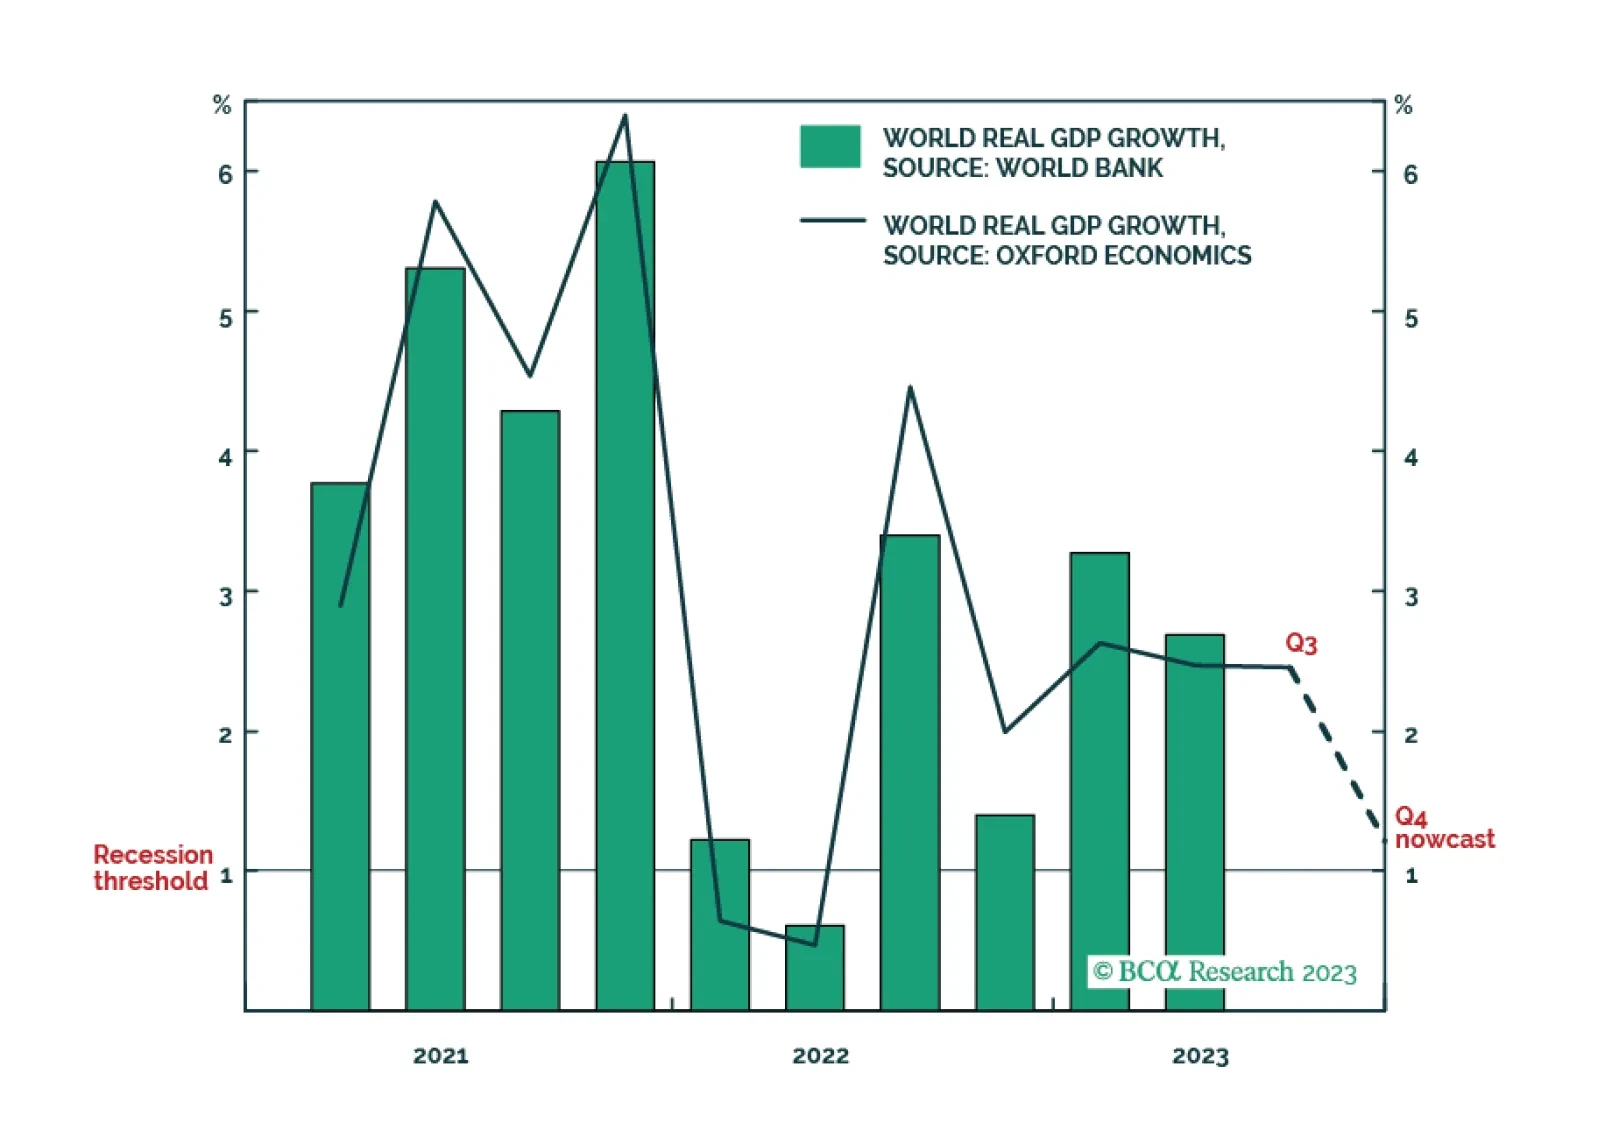
The latest ‘nowcast’ for world economic growth in the fourth quarter has plunged to just 1.2 percent, marking the cusp of another world recession. One important implication is that expectations for oil demand growth and industrial metal demand growth are way too optimistic.