Skip to main content

Economy

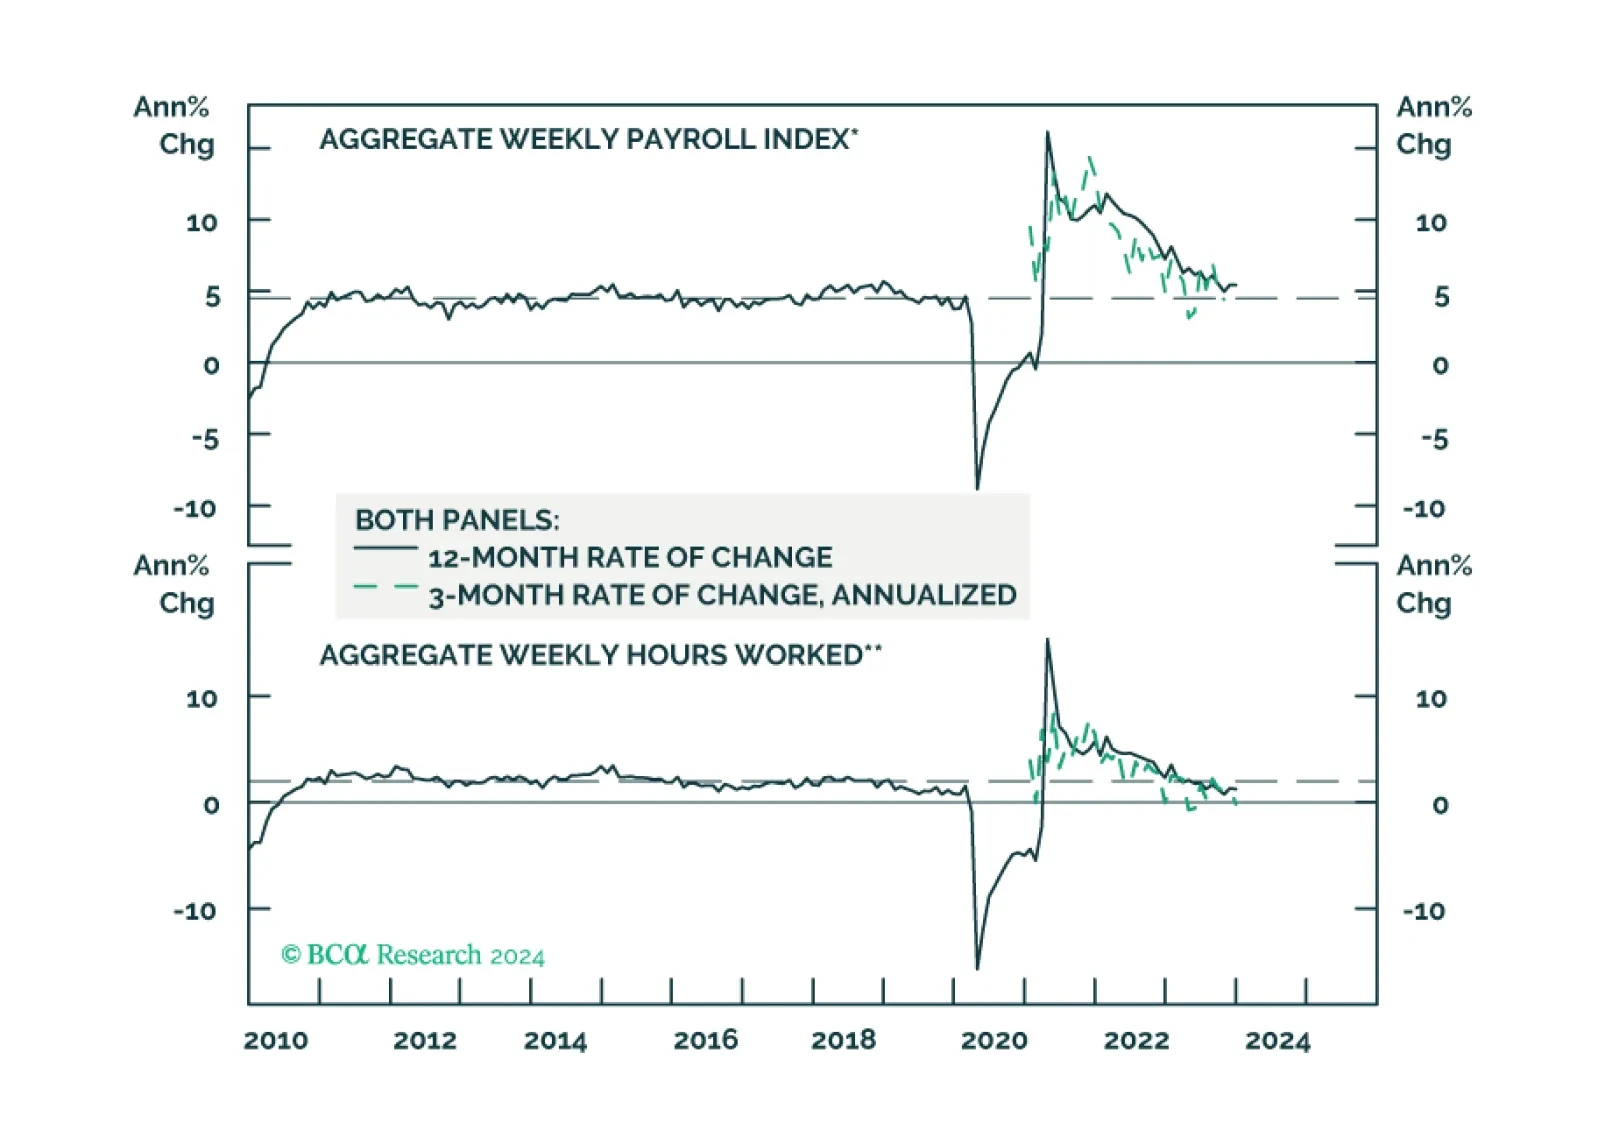
BCA Research’s US Bond Strategy service recommends investors keep portfolio duration close to benchmark for now. They will increase rate exposure as the labor market downturn worsens. Treasury yields are up slightly to start the year, but last Friday’s…

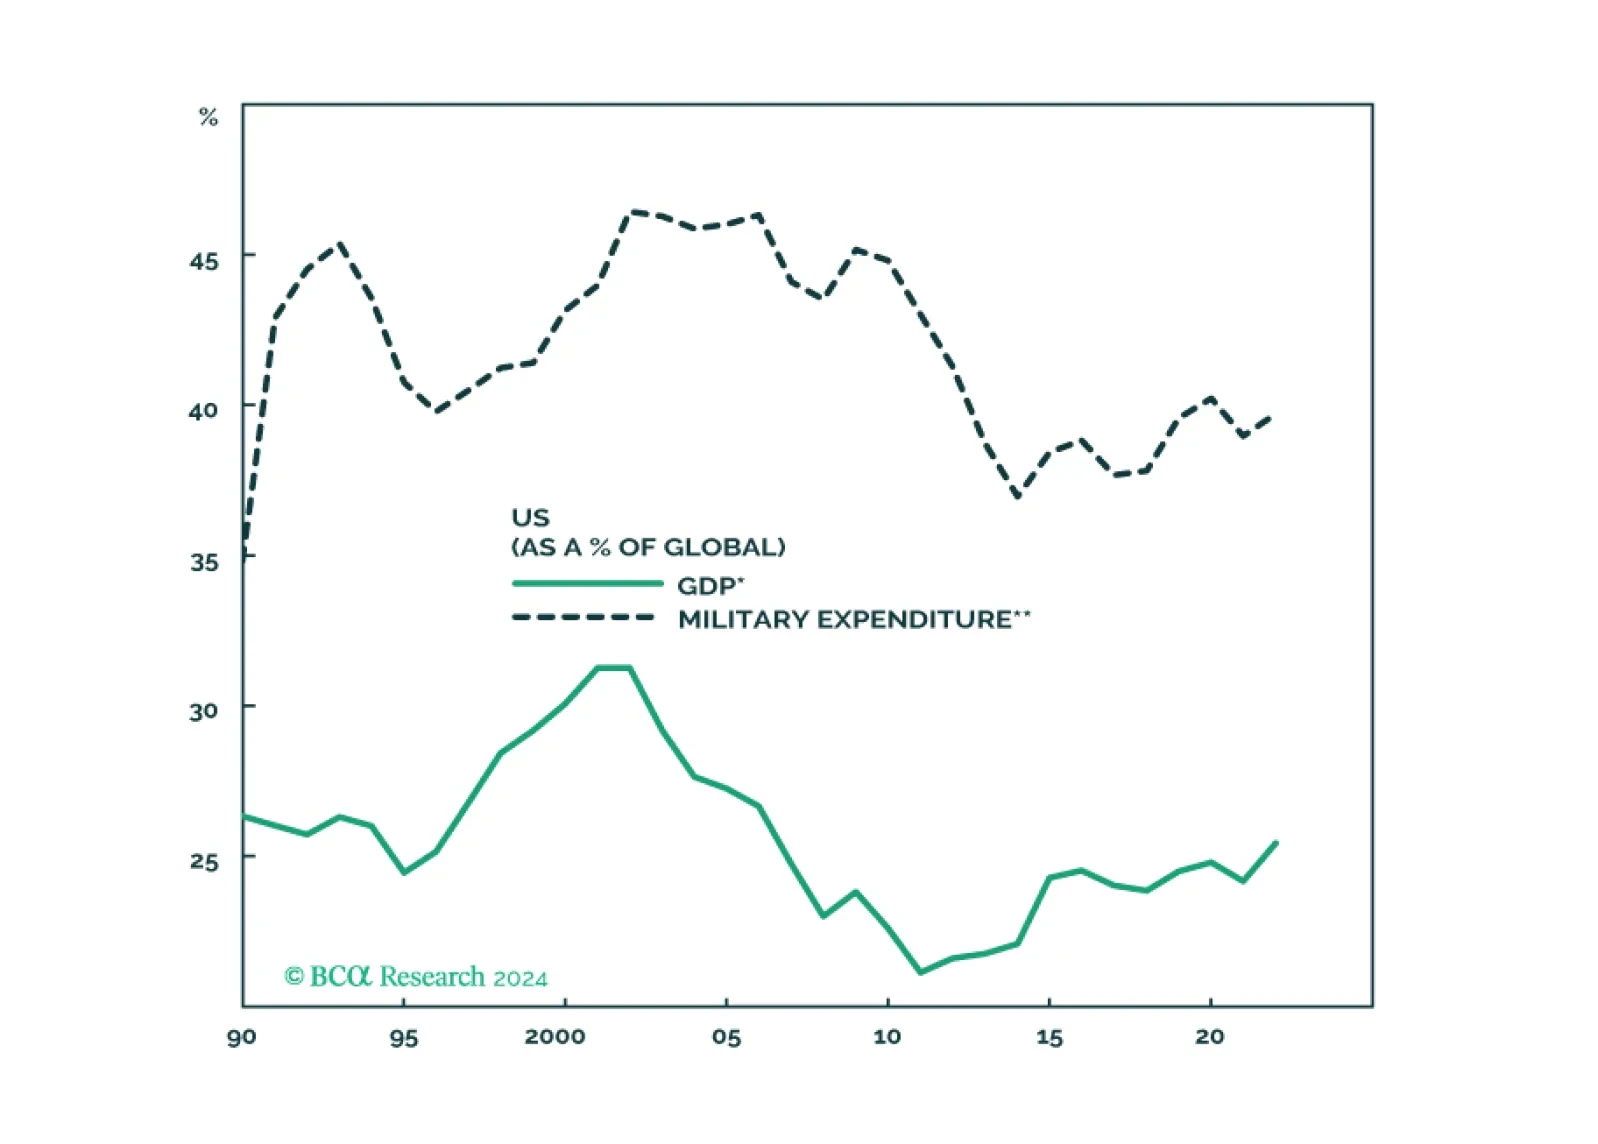
The market’s pricing of a soft landing means that geopolitical risks are becoming more, not less, relevant in 2024. US domestic divisions will invite challenges as foreign powers rightly fear that US policy will turn more hawkish after the election.
Optimism among investors and economic agents continues to improve in the Eurozone. The Sentix Economic Index for the Eurozone rose from -16.8 to -15.8 in January – in line with consensus expectations and marking the third consecutive increase. The current…
Growth in US disposable income has outpaced inflation nearly every month since mid-2022. Consumption is principally driven by income, but in the US it has gotten a meaningful assist the last two years from the drawdown of excess savings accumulated over the…
The S&P 500 has started off the new year on a weak footing, dropping by 1.5% in the first week of January. Indeed, by the end of 2023, several indicators were warning that conditions were becoming bearish. In particular, investors have tuned increasingly more…
Following a strong rally in the prior two years, the performance of the US dollar was significantly weaker in 2023. The DXY index ended last year down 0.9%, after gaining 3.3% and 6.4% in 2021 and 2022, respectively. Importantly, the USD weakness was…
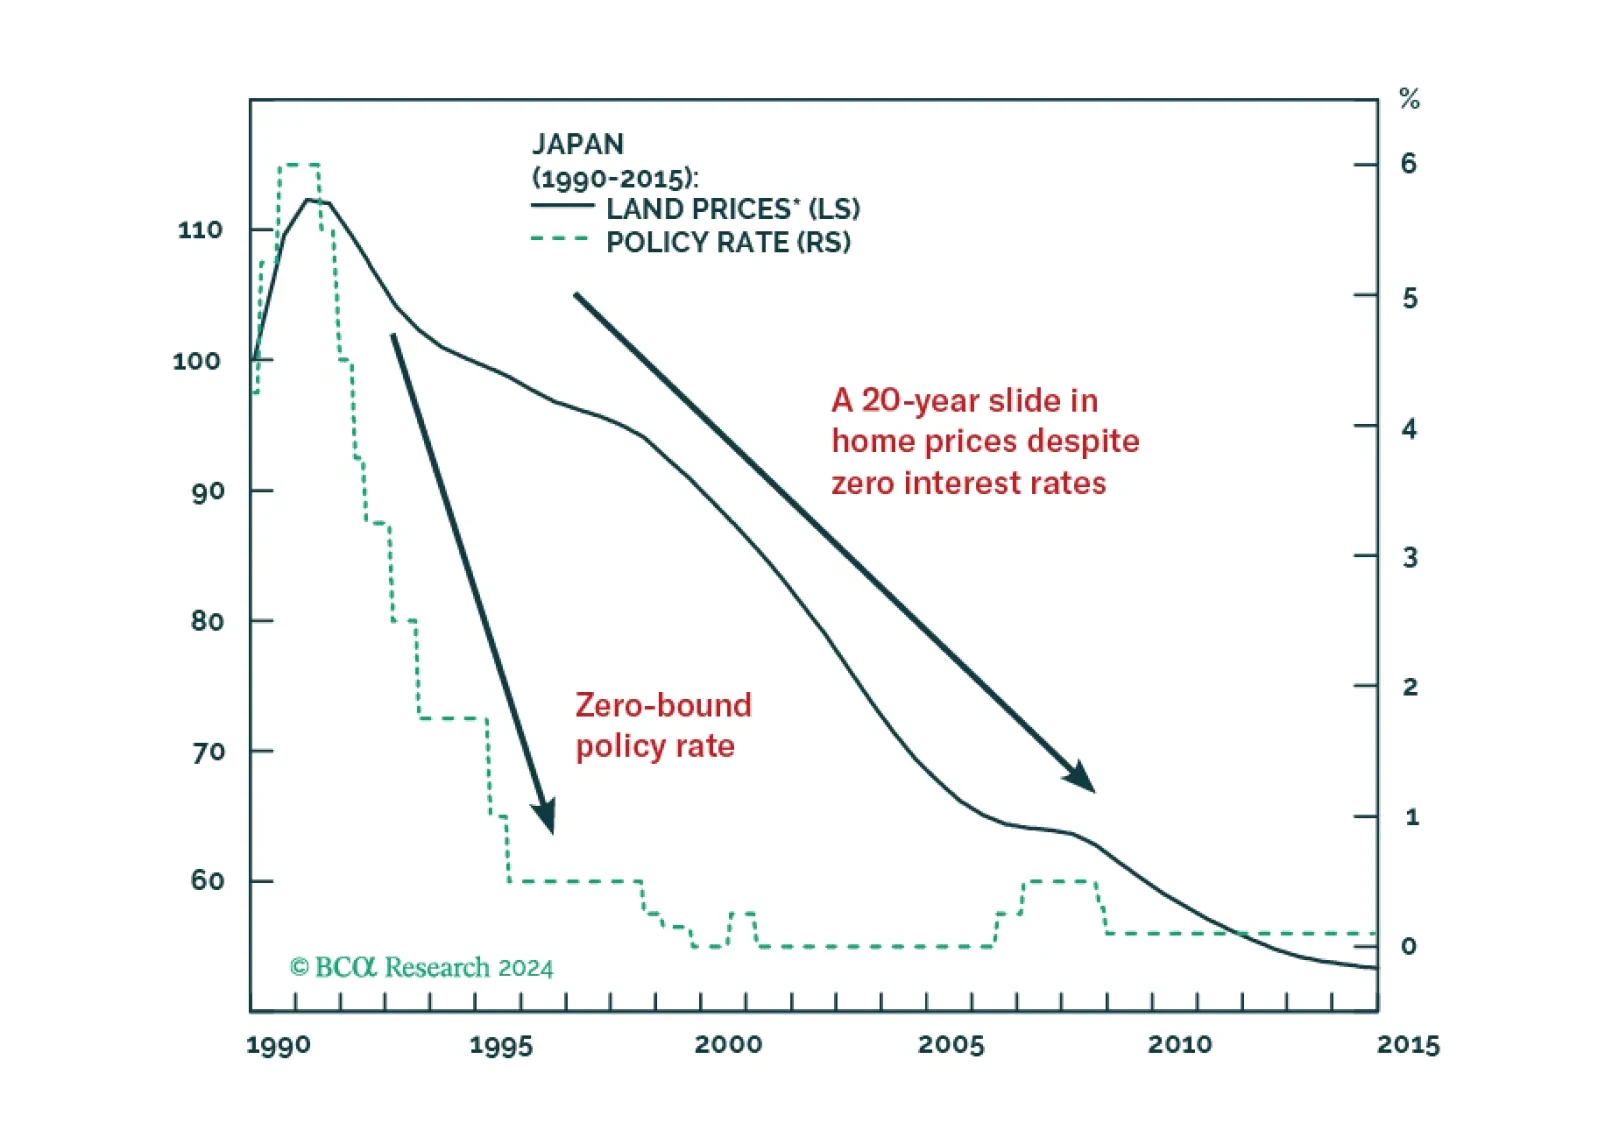
According to BCA Research’s China Investment Strategy service, the structural landscape of China's property market today is, in many aspects, more challenging than the real estate markets in Japan and the US at the peak of their housing bubbles: The…

Our Portfolio Allocation Summary for January 2024.

A low multiplier effect of stimulus will reduce the magnitude of the rebound in China's business activities in 2024. The housing market downturn will likely persist, and the ongoing household deleveraging also poses a significant challenge to China’s economic recovery.
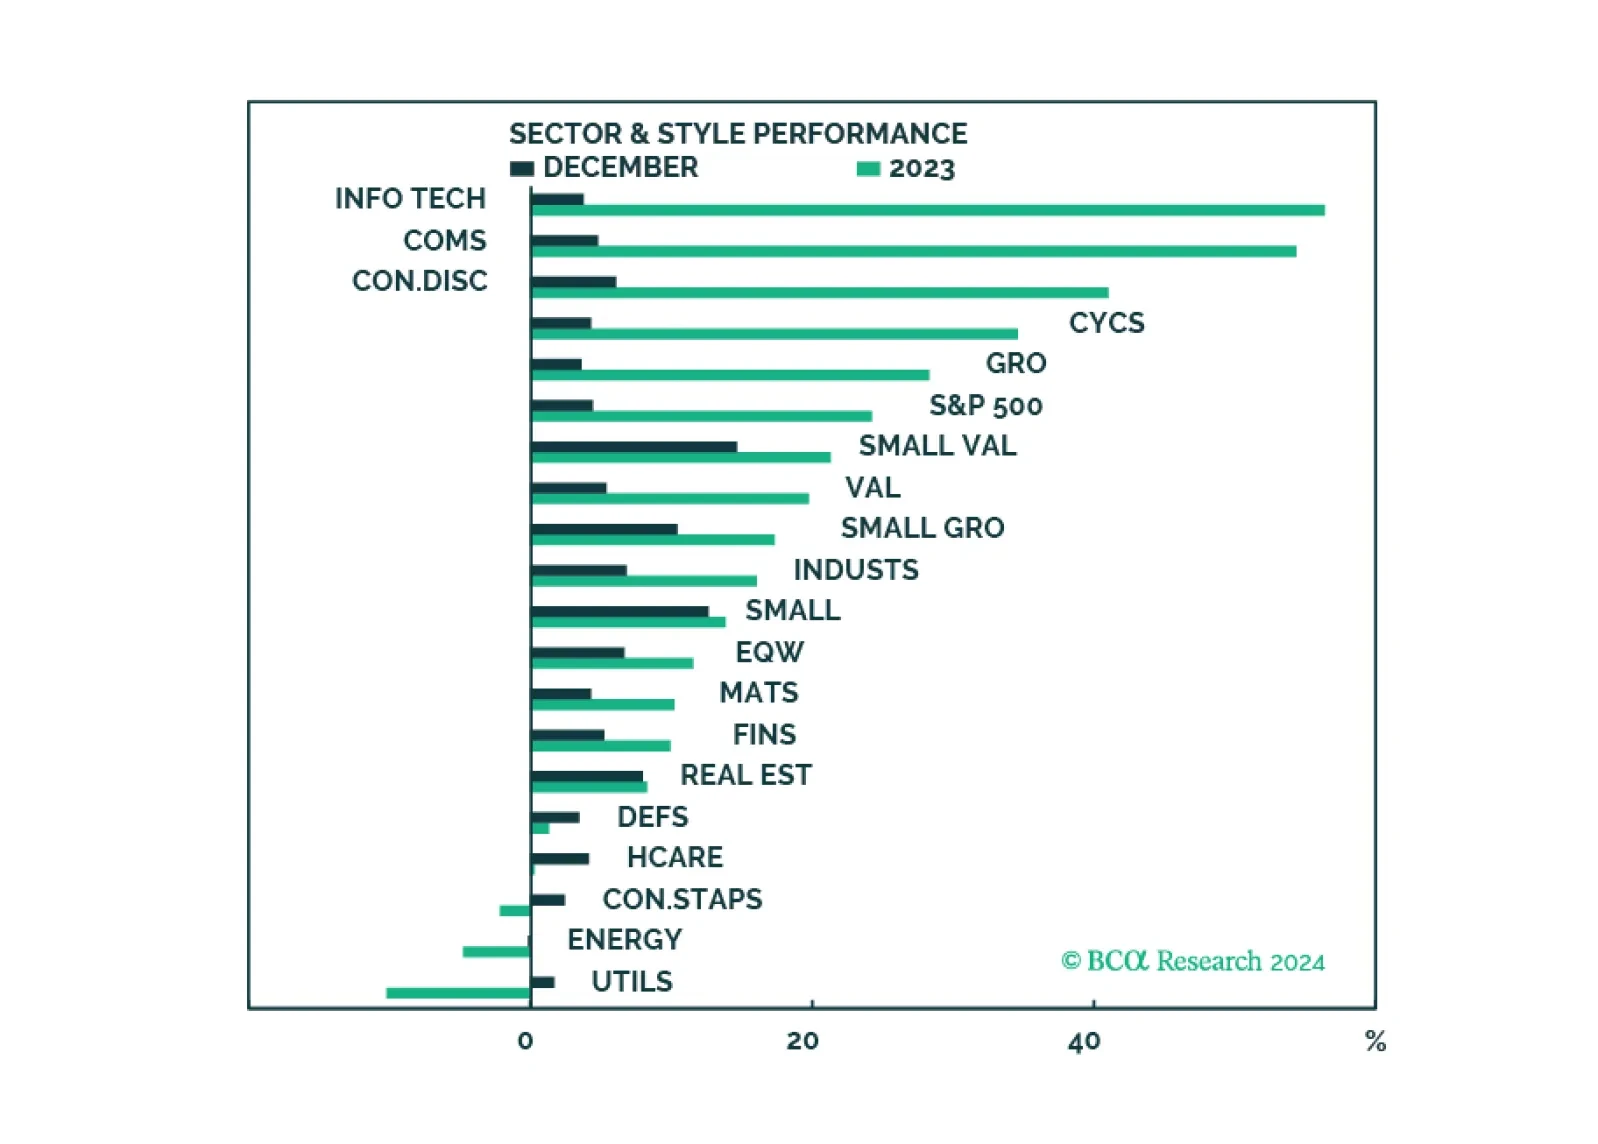
The Santa Claus rally has been fueled by investors optimism about a soft landing which is the least likely macro outcome in 2024. A pullback in the market is imminent as the probability of "too hot" or "too cold" will get priced in. We are downgrading Software and Services on a tactical basis to take profits but maintaining a strategic overweight in the same trade.