Skip to main content

Currencies

Special Report

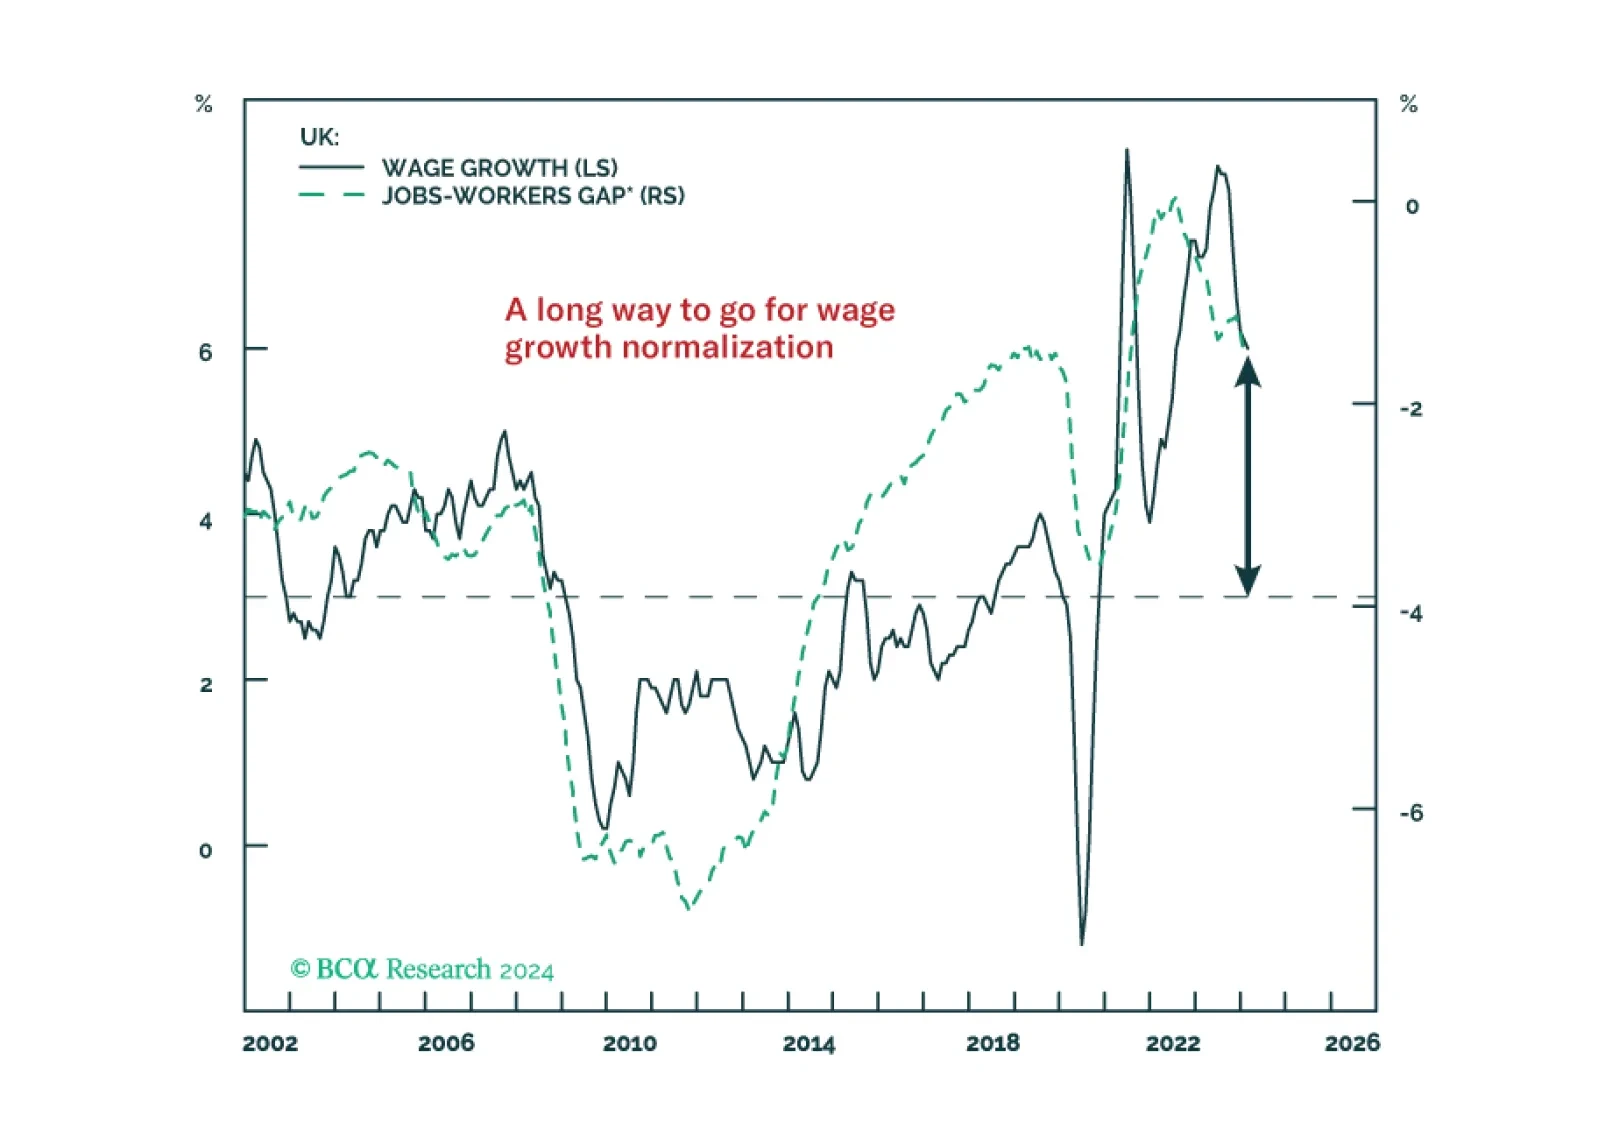
The UK labor market remains far too tight to expect wage growth to slow to levels consistent with the Bank of England inflation target. A true recession with rising unemployment is needed to finally slay the UK inflation beast. 2024 rate cuts are off the table, with the central bank having to keep monetary policy tighter for longer than markets expect and the UK economy now rebounding. We recommend downgrading UK gilts to underweight in global bond portfolios, while also looking for opportunities to buy the British pound on pullbacks versus the euro, Canadian dollar and Swedish krona.

USD/JPY has appreciated by over 10% so far in 2024, making the yen the worst performing G10 currency year-to-date. This cross has also surpassed the 150 threshold which historically is the level at which the Bank of Japan begins to intervene. Today, it stands…
BCA Research’s Emerging Markets Strategy service concludes that among the CE3 currencies, the zloty and the koruna will be the relative winners, while the forint will likely be the worst performer of the three. That said, all three CE3 currencies will weaken…

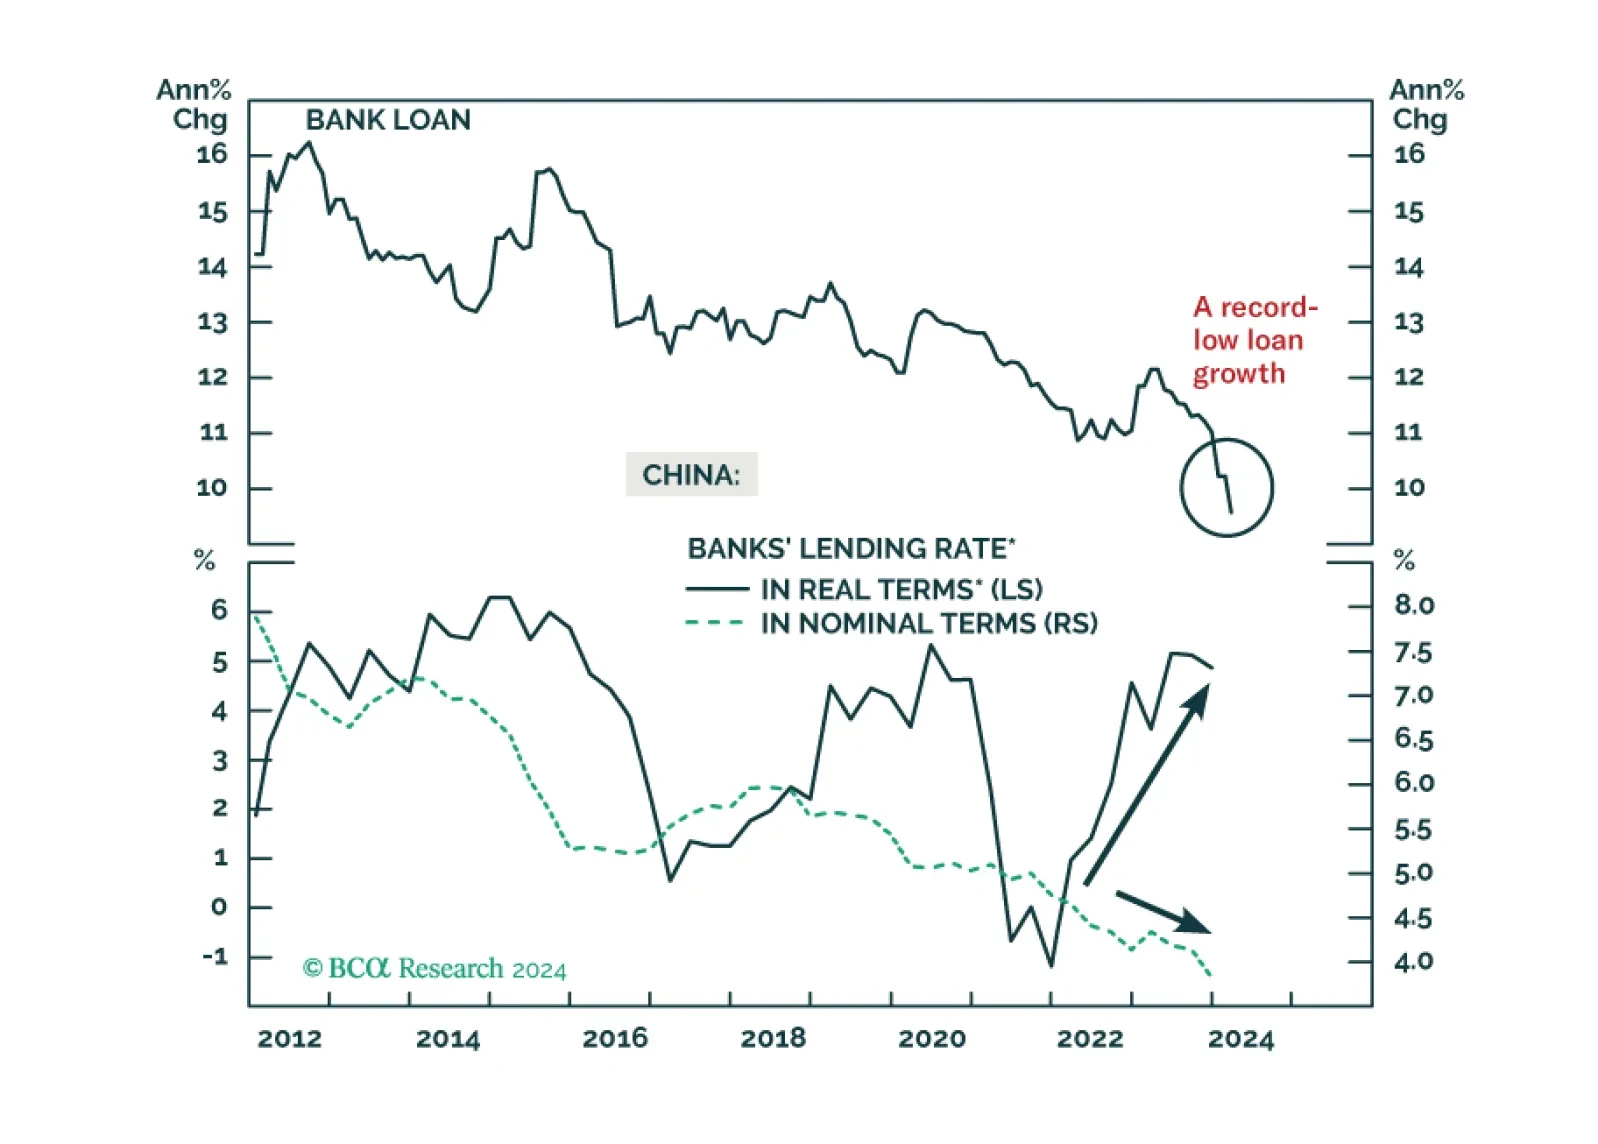
China’s economy is cruising at a very low altitude. The odds are that China’s equity rebound is running out of time. The RMB will continue to depreciate versus the US dollar in the coming months, albeit the pace may be modest.
Flash estimates for several European PMIs were released Tuesday. The results for manufacturing activity were somewhat disappointing. The German manufacturing PMI increased from 41.9 to 42.2, but underperformed expectations of 42.7. France’s manufacturing PMI…
Euro Area small caps typically outperform large caps whenever the trade weighted euro appreciates and underperform whenever it depreciates. The rationale is simple. Most European large cap companies are large multinationals that export their products outside…

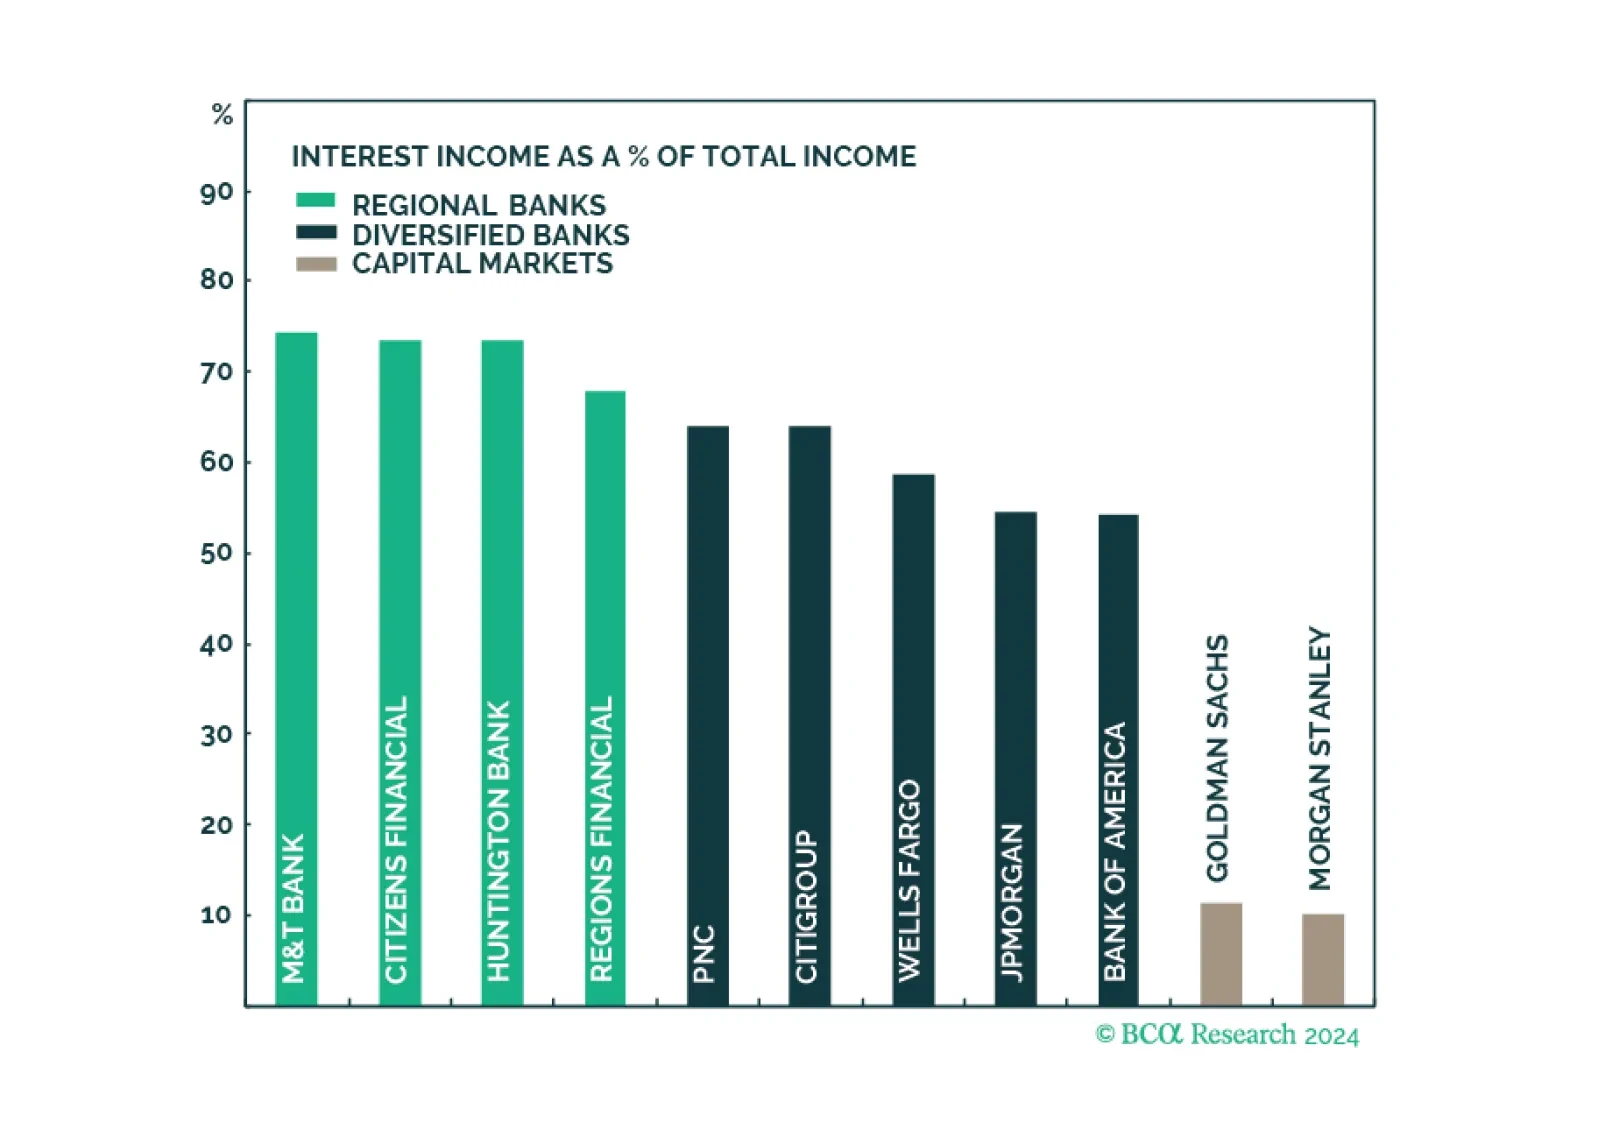
Q1 earnings results of the largest US banks have demonstrated that the engine of recent growth in profitability, NII, has faltered as funding costs are rising fast. However, the resurgence in non-NII thanks to a revival in corporate activity has been a saving grace. Earnings growth appears to have bottomed, while valuations are attractive. To play up portfolio exposure to an upcoming surge in capital markets activity, and minimize exposure to declining profitability in traditional banking services, overweight Diversified Banks and Capital Markets, and underweight Regional Banks.

According to BCA Research’s Foreign Exchange Strategy service, an ensemble of technical indicators reveals that the dollar is overbought in the near term. The list of indicators they have compiled for this analysis is simple but potent: How are speculators…
Japan’s national CPI inflation unexpectedly cooled in March, falling to 2.7% y/y versus consensus estimates it would remain at 2.8% y/y. Notably, measures of underlying inflation such as core CPI (ex-fresh food) and “core-core” CPI (ex-fresh food and energy)…
The IMF’s latest fiscal monitor report highlighted the dangers that rising sovereign debt alongside rising deficits pose to advanced economies. The United States, in particular, is at risk. The IMF projects that fiscal deficits in the US will stay above 3% of…