Saltar al contenido principal

Portfolio

Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
Explore Portfolio Construction
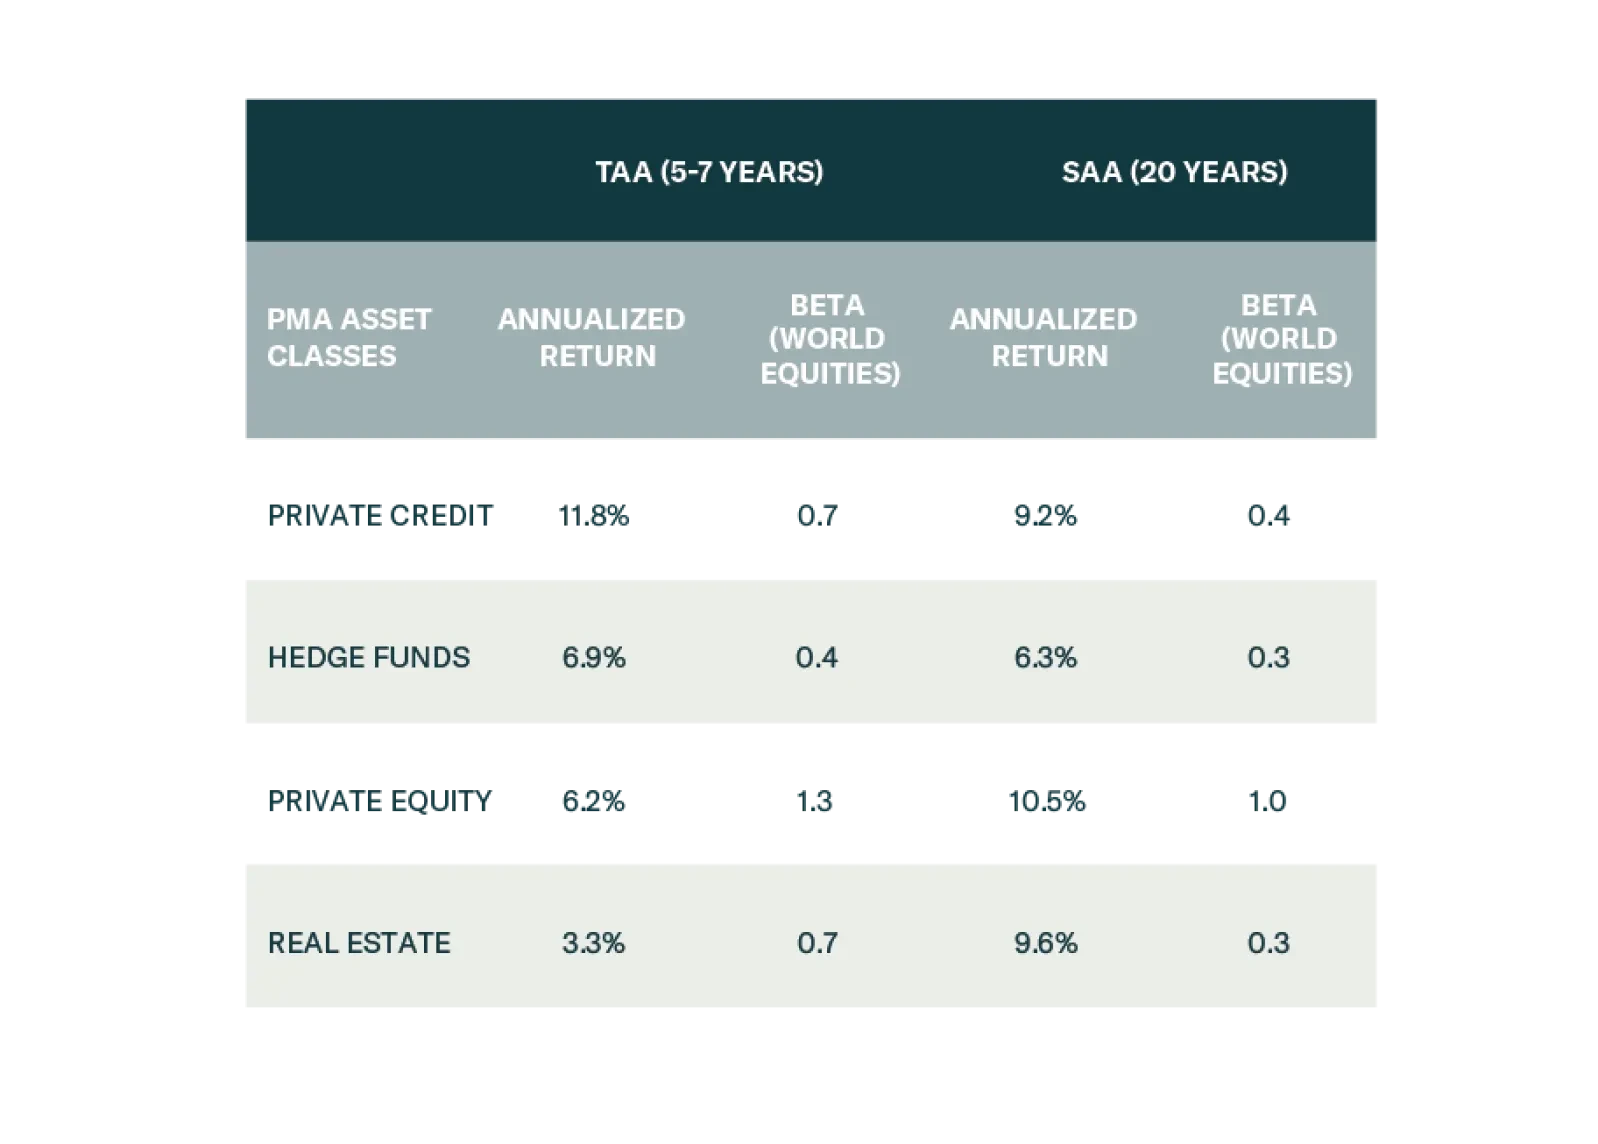
Investors should be tactically tilting allocations towards Direct Lending, Distressed Debt, and Directional Hedge Fund strategies at the expense of Real Estate, Private Equity, and Diversifier Hedge Funds. Structural opportunities are emerging in Real Estate and Venture Capital.
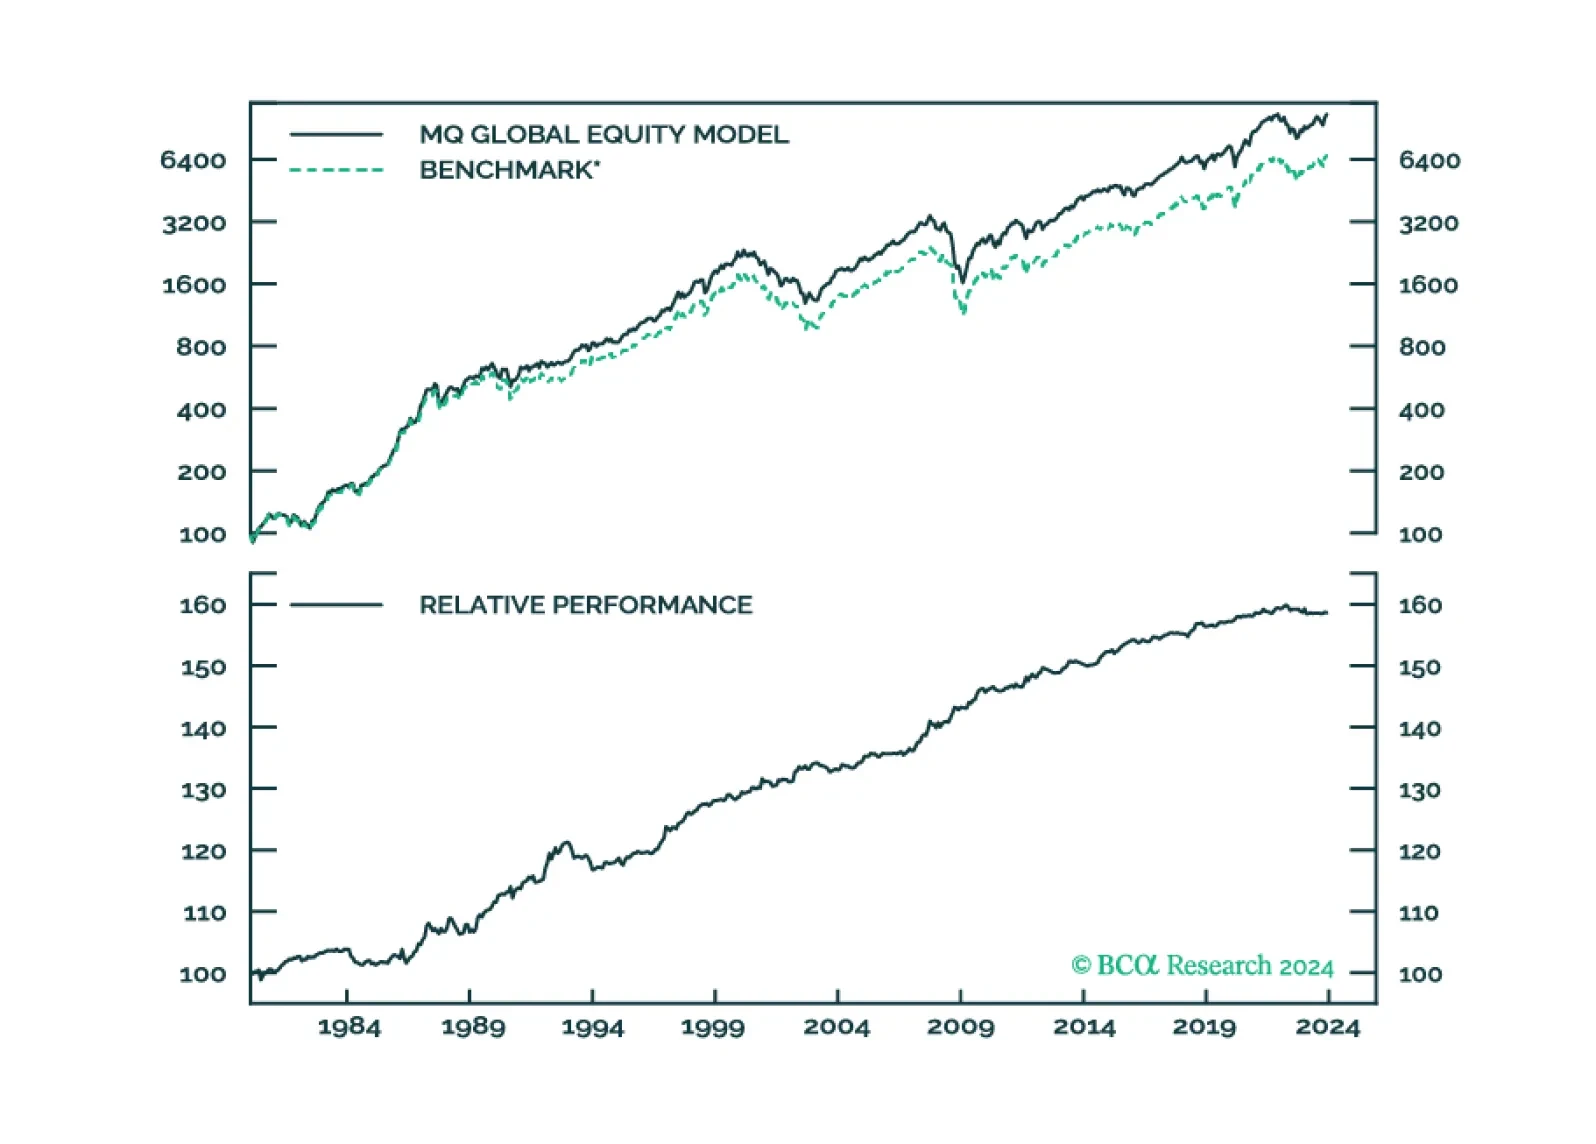
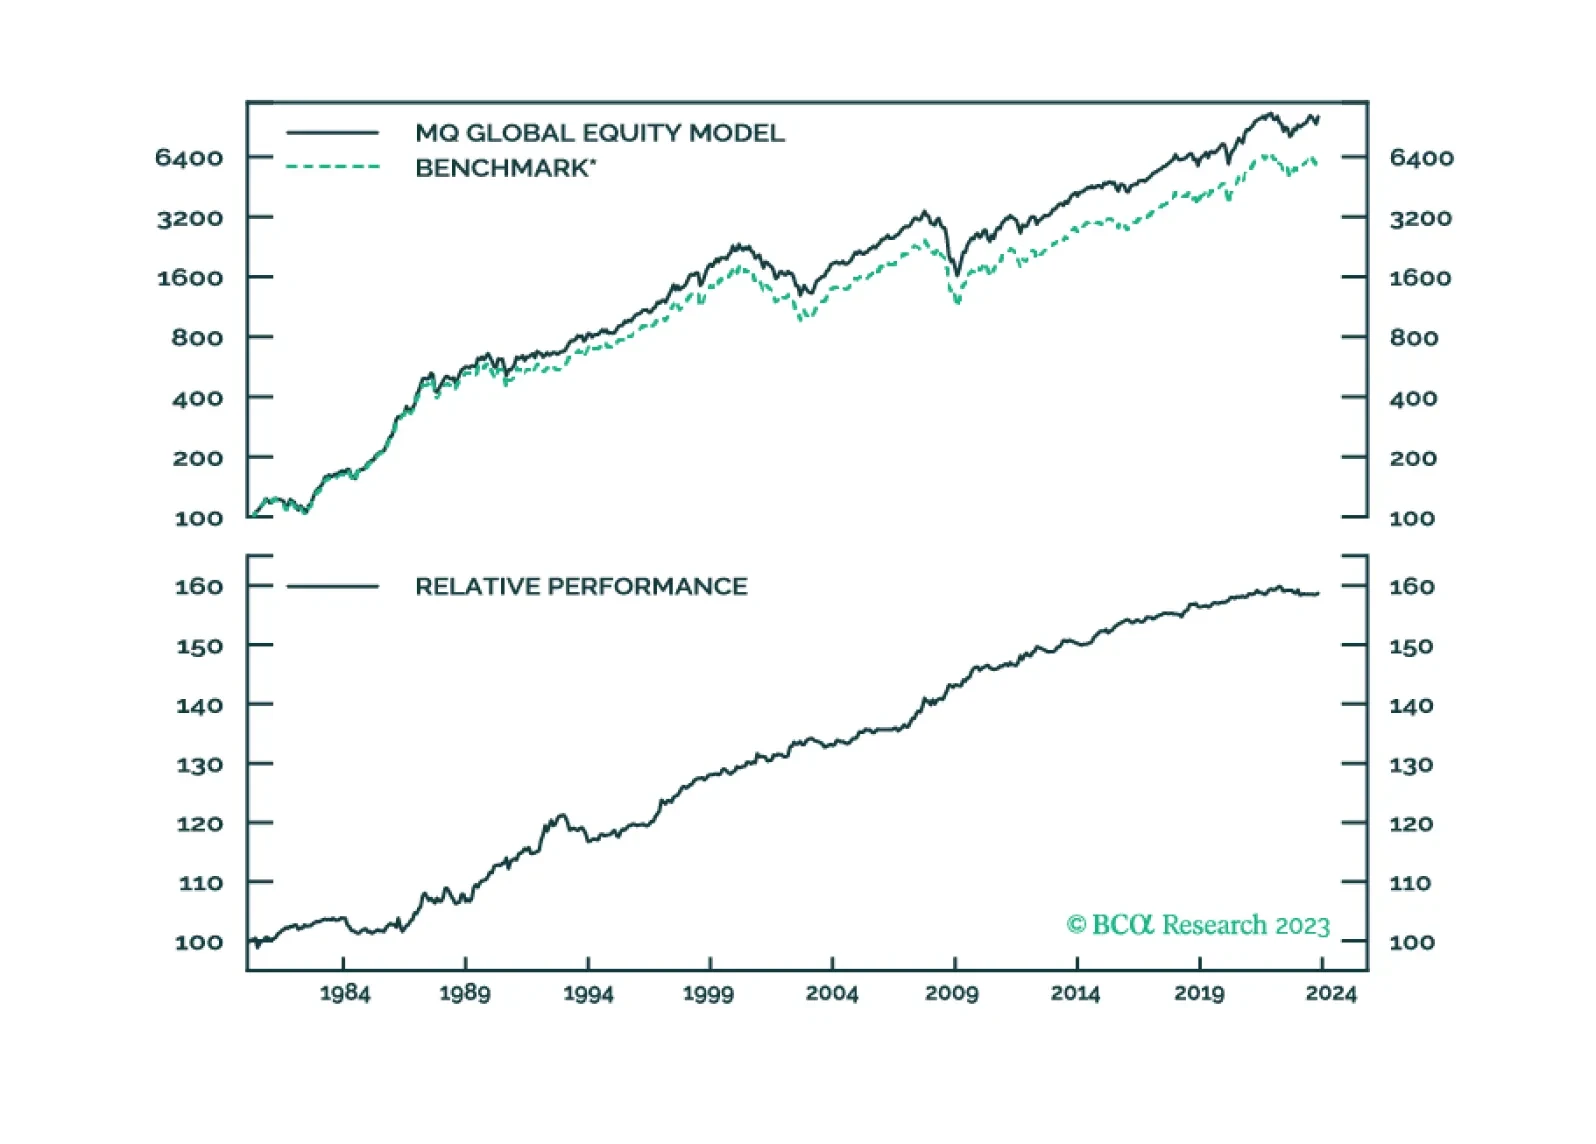
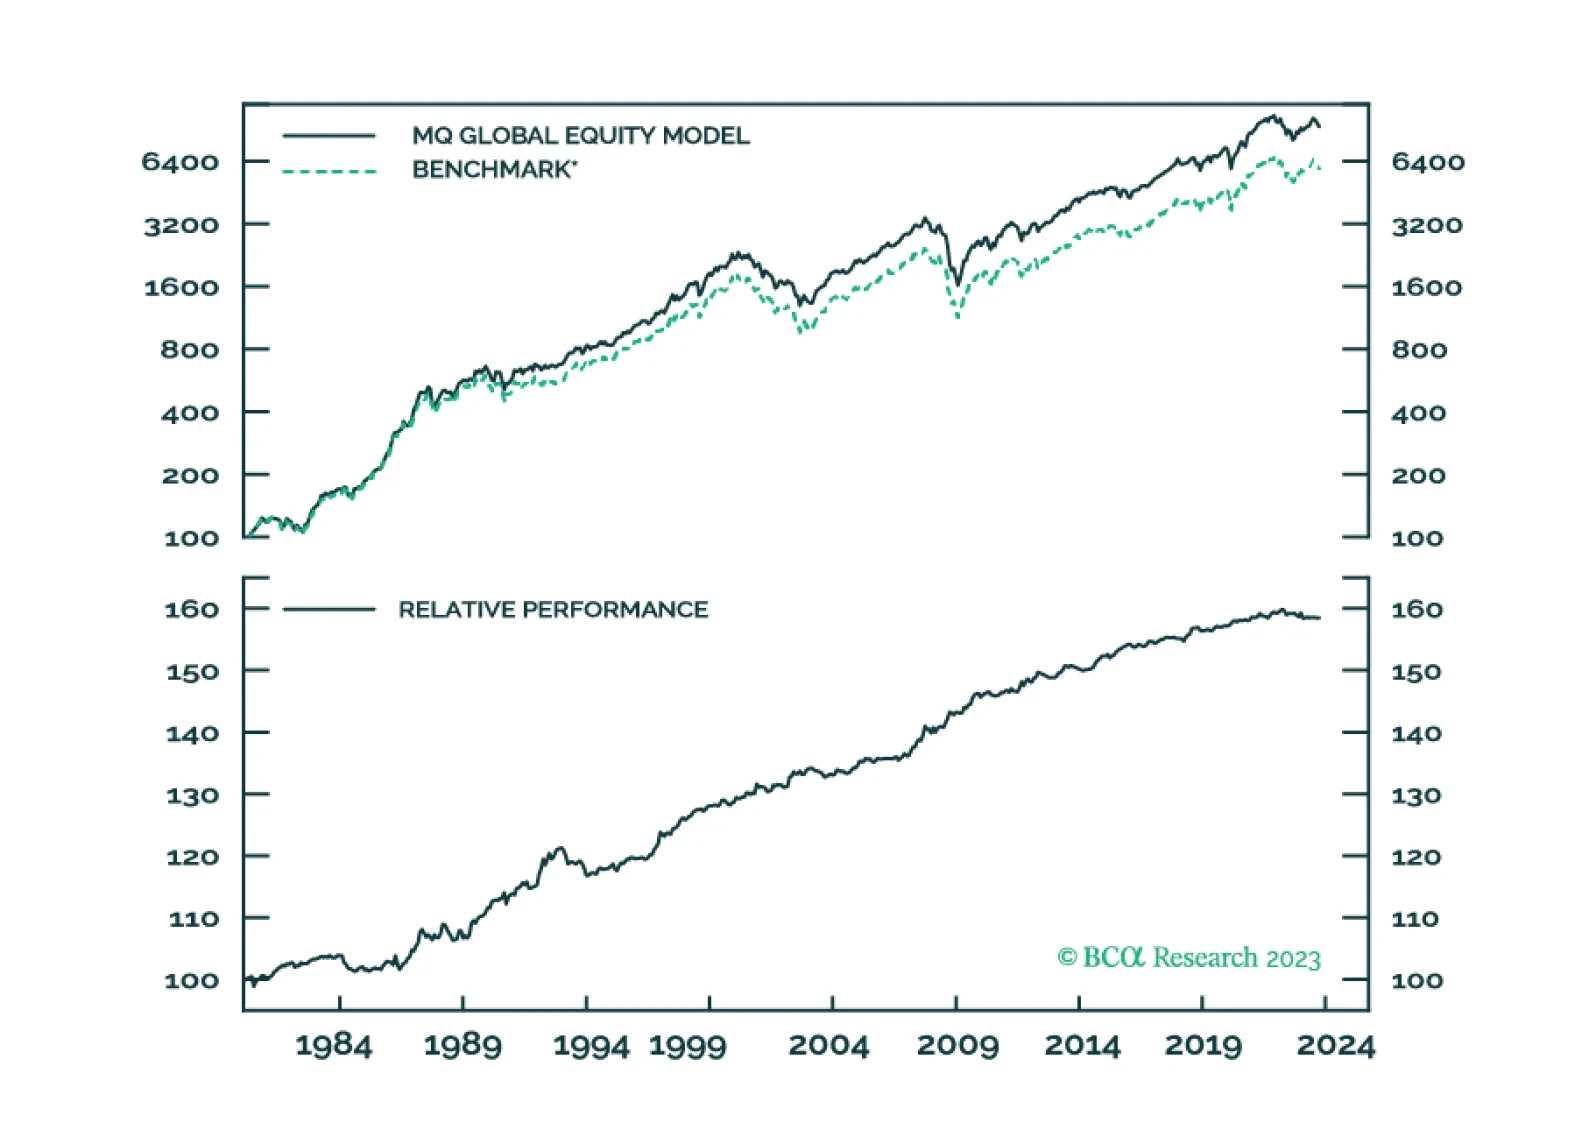
MacroQuant has upgraded equities to overweight at the expense of bonds. Cash remains neutral.
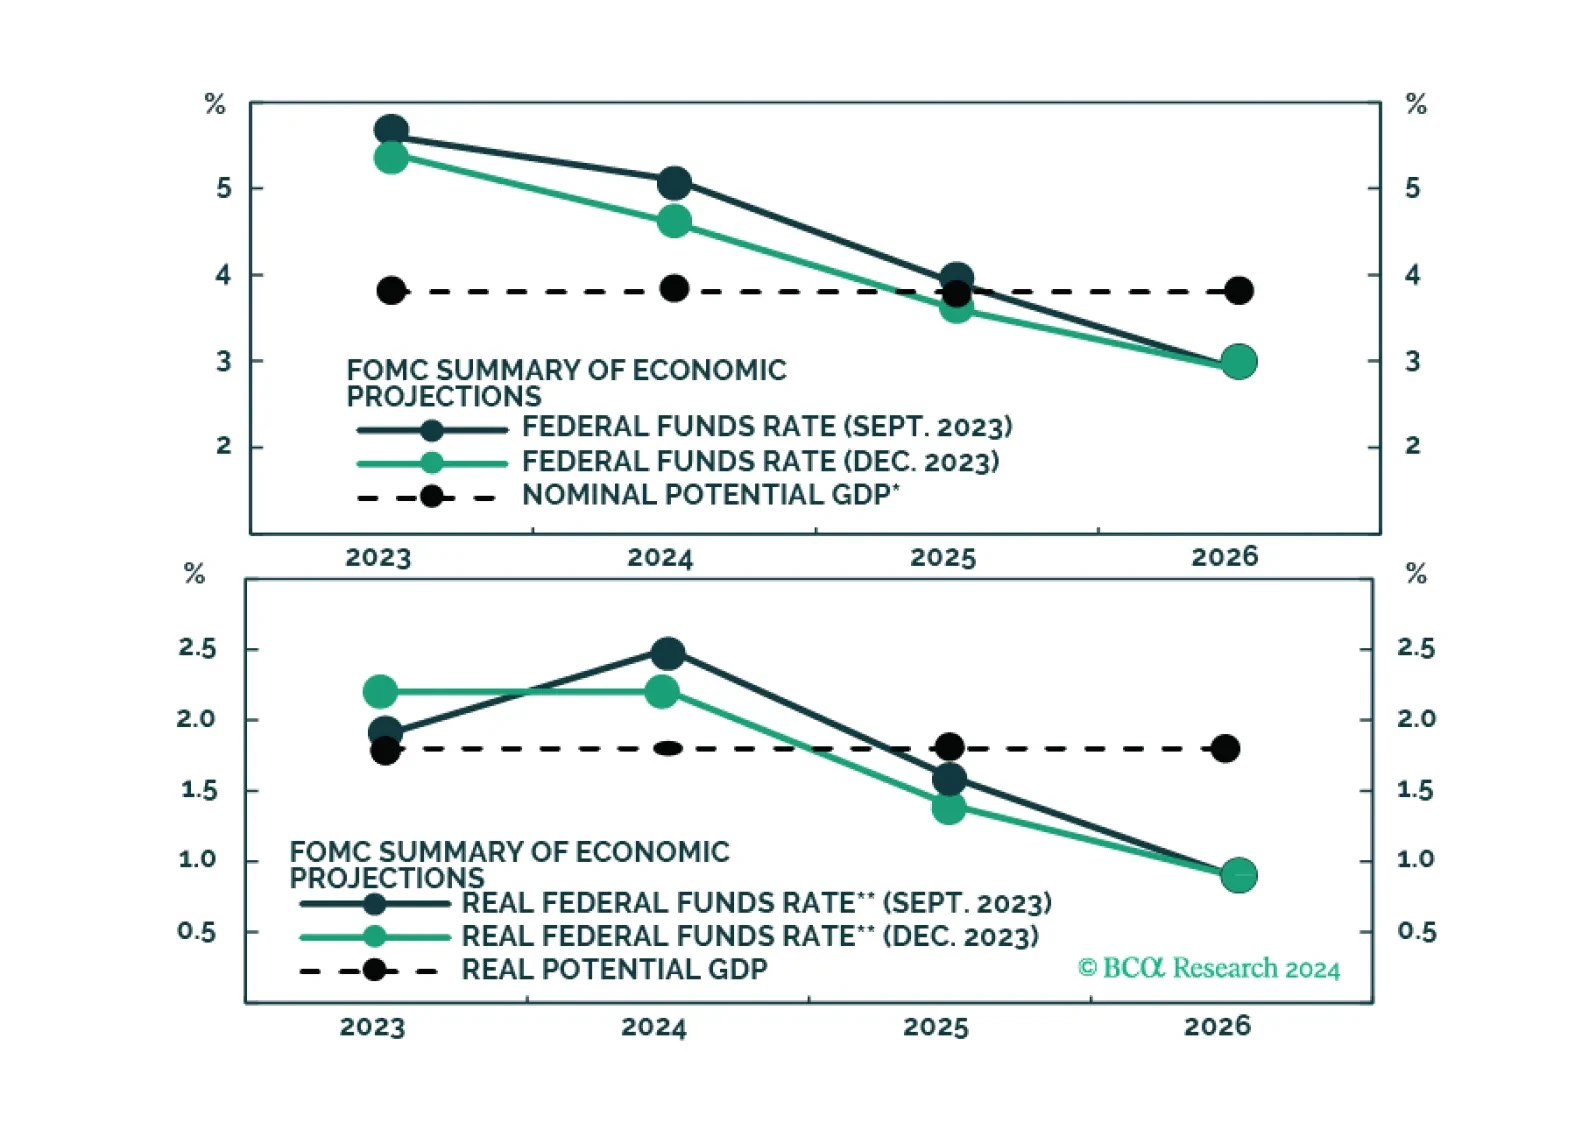
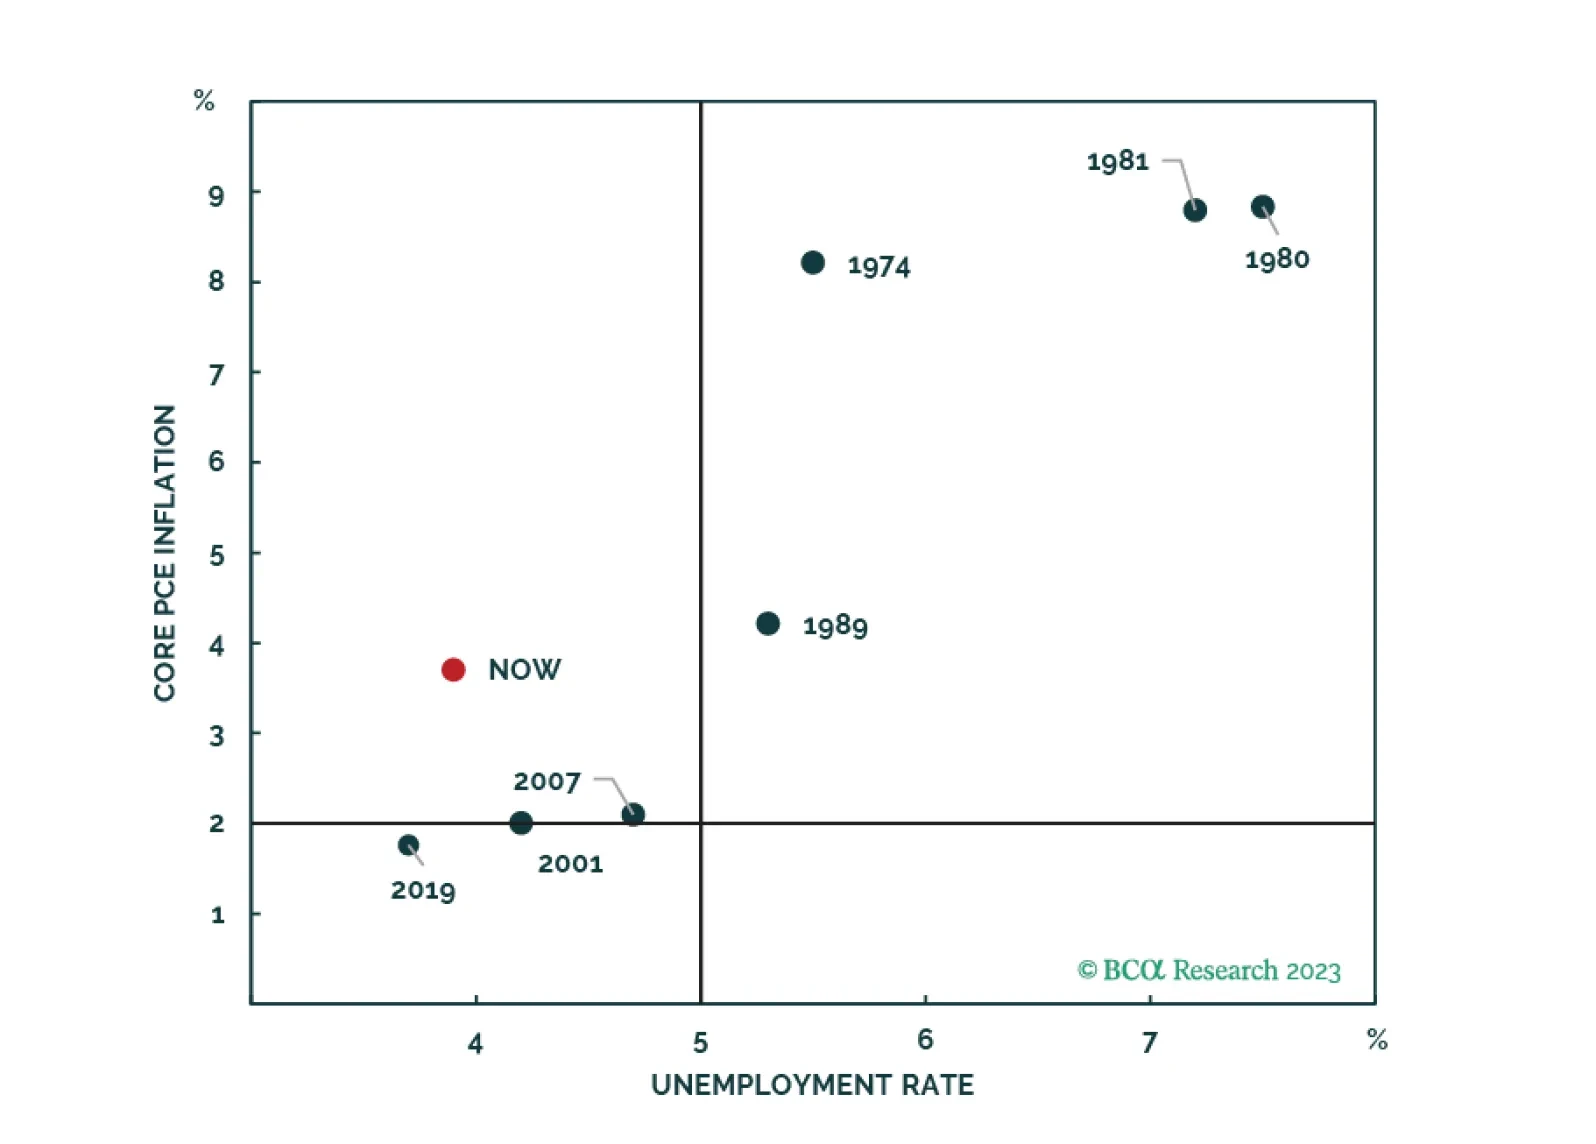
The market is excited by the idea that the Fed will cut rates early this year, even without a recession. But is that likely, with inflation still set to be around 2.8% mid-year?
Informe especial Our recommendations for blogs and X’s (on the economy, financial markets, asset allocation, bonds, quants, energy, real estate, geopolitics, and specific countries and regions) to try over the holidays.
MacroQuant is overweight bonds and cash and underweight equities.
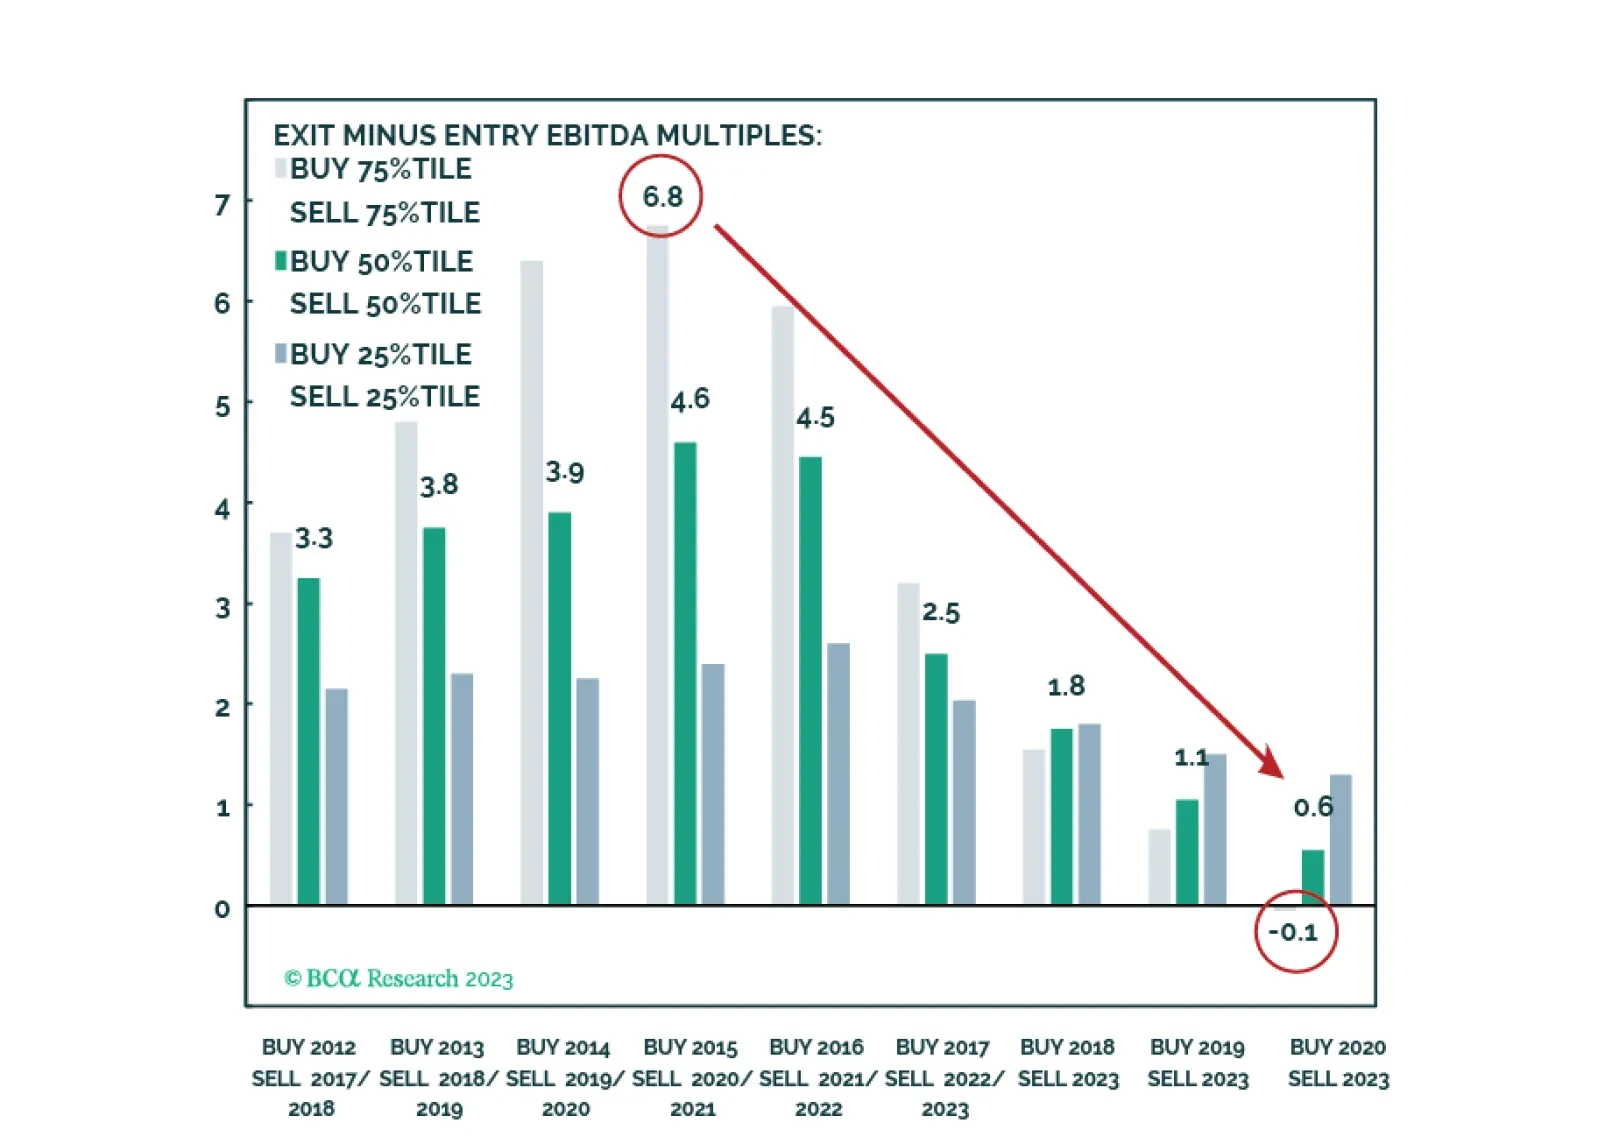
Informe especial The next dollar into Private Equity carries more time and opportunity cost risk. We do not see a high risk of permanent capital loss for the next vintages; existing vintages we do. While our primary focus revolves around the next dollar, it is valuable to comprehend the risks associated with current investments made through yesterday's allocations. In this report we delve into risks pertaining to dollars invested in the past and those earmarked for the future, with a special emphasis on Buyouts.
Inflation won’t fall fast enough for the Fed to cut rates preemptively before recession arrives. The risk/rewards balance is unfavorable for risk assets. Stay overweight bonds versus equities.
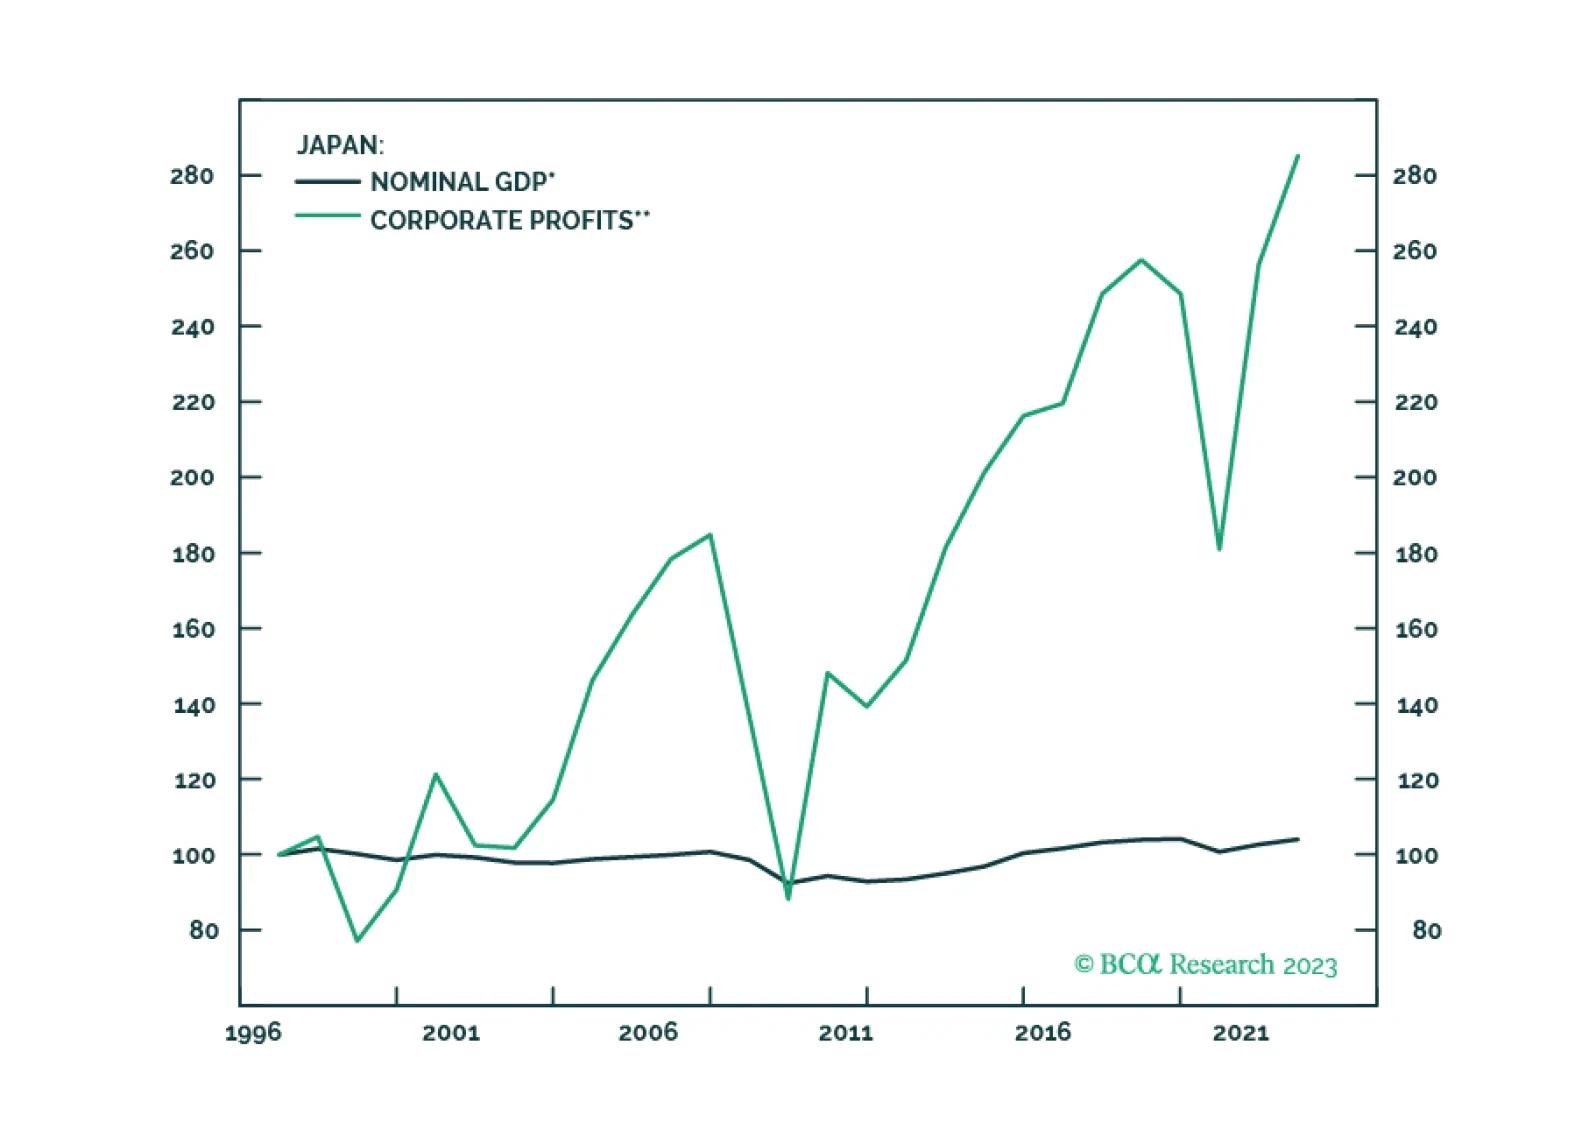
Informe especial Economic growth has little to no relationship with long-term country returns. But if GDP doesn’t drive long-term equity returns, then what does? To find out, we break down equity total returns of 33 countries from 1997 to 2022 into seven components. In line with other academic research, we find that, over our sample, net buybacks were a crucial factor for long-term country performance. Our research suggests that equity issuance is an underestimated driver of returns that investors should pay more attention to.
MacroQuant is holding a near neutral positioning with a slight tilt towards equities and bonds and away from cash.
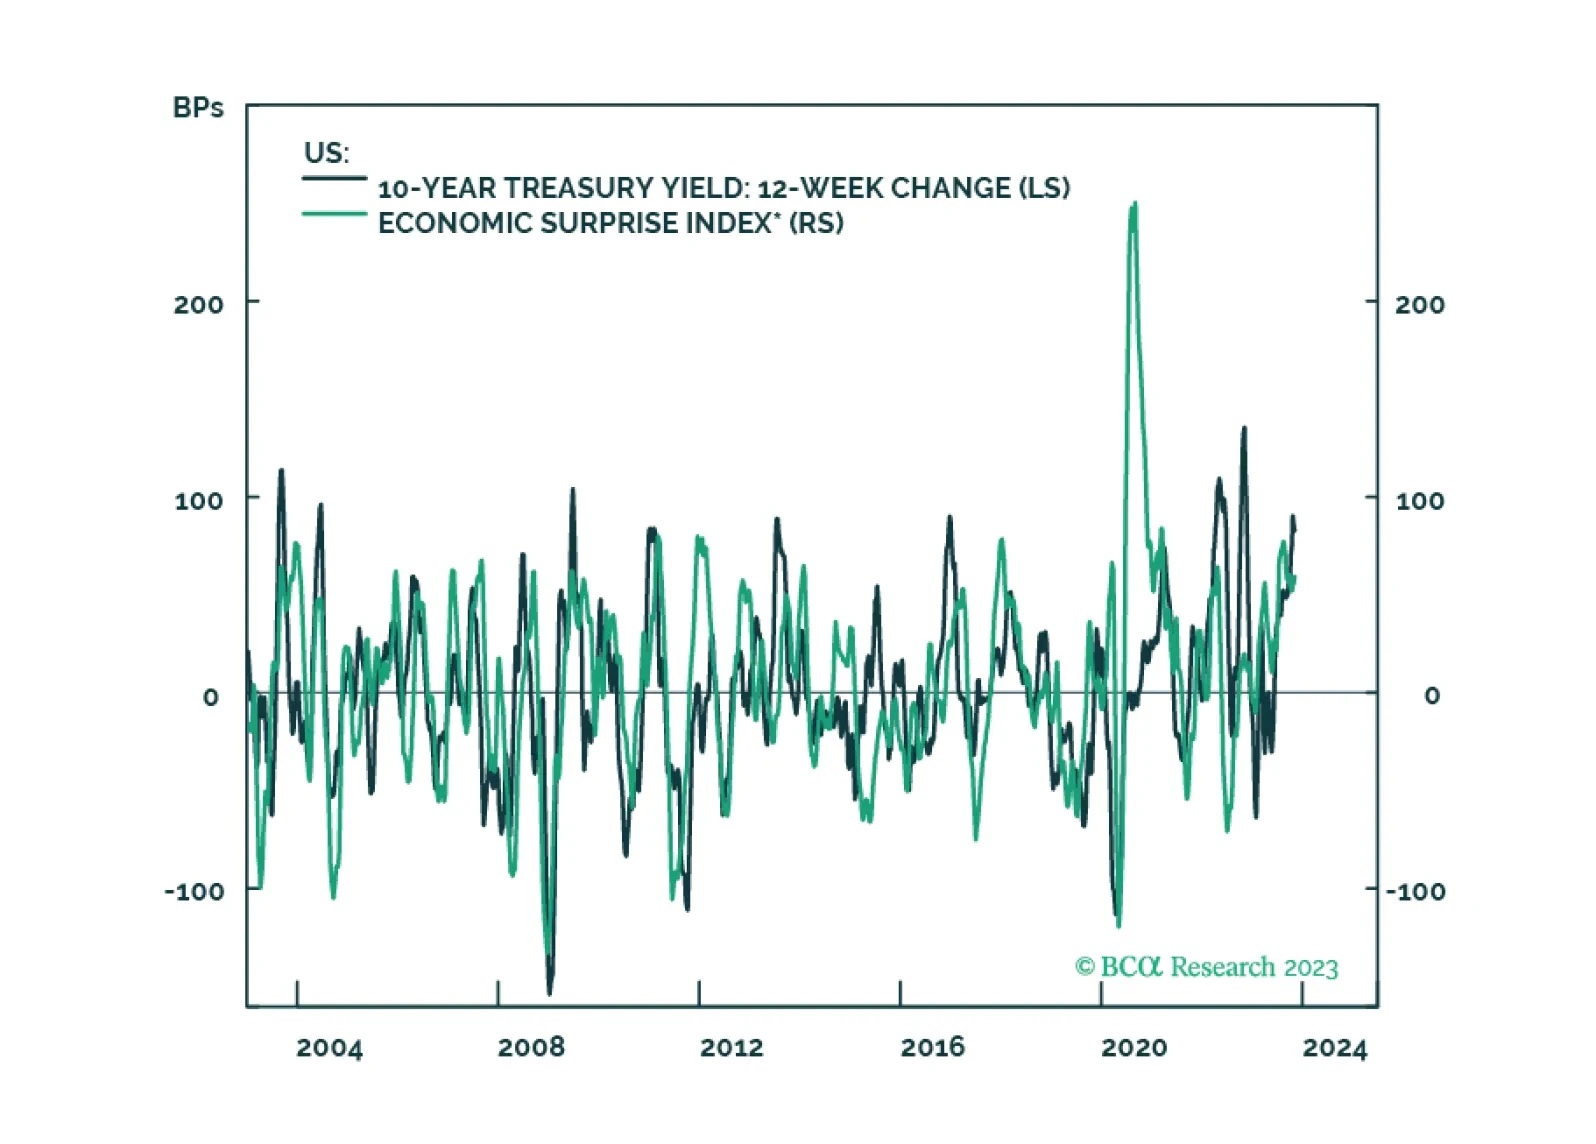
High interest rates will eventually cause growth to slow. Signs of stress are already starting to show. Stay cautiously positioned.