 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
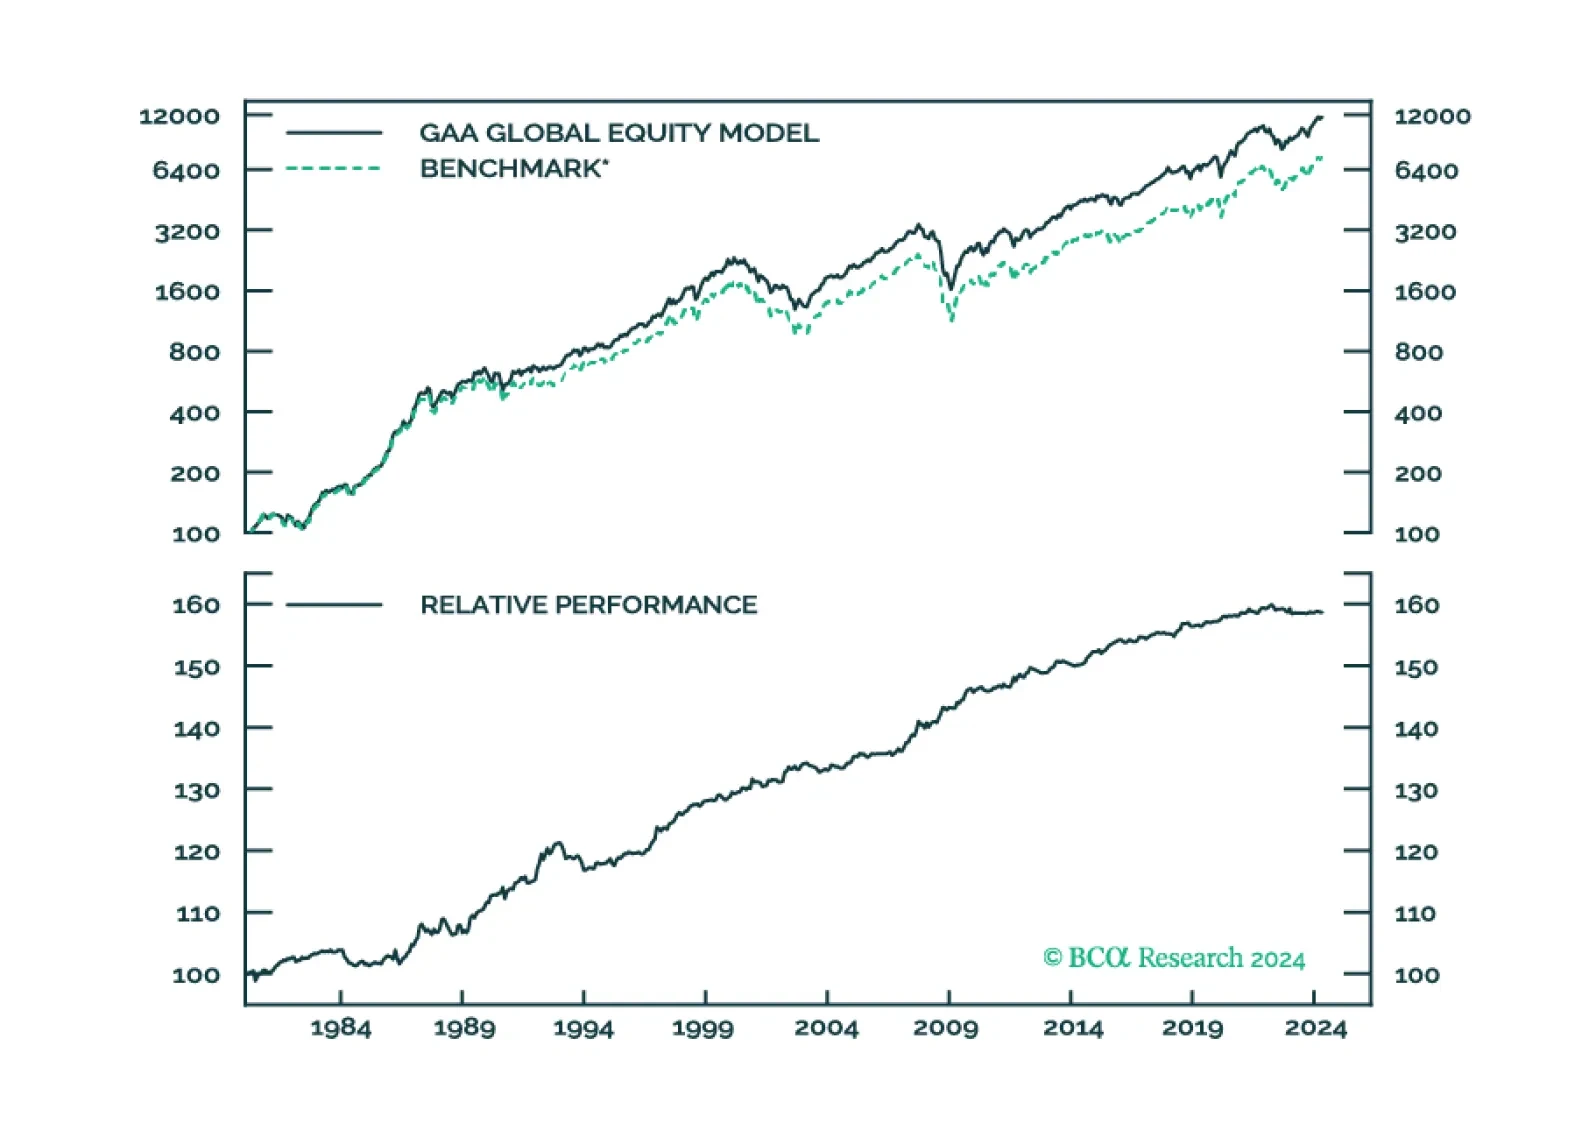
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
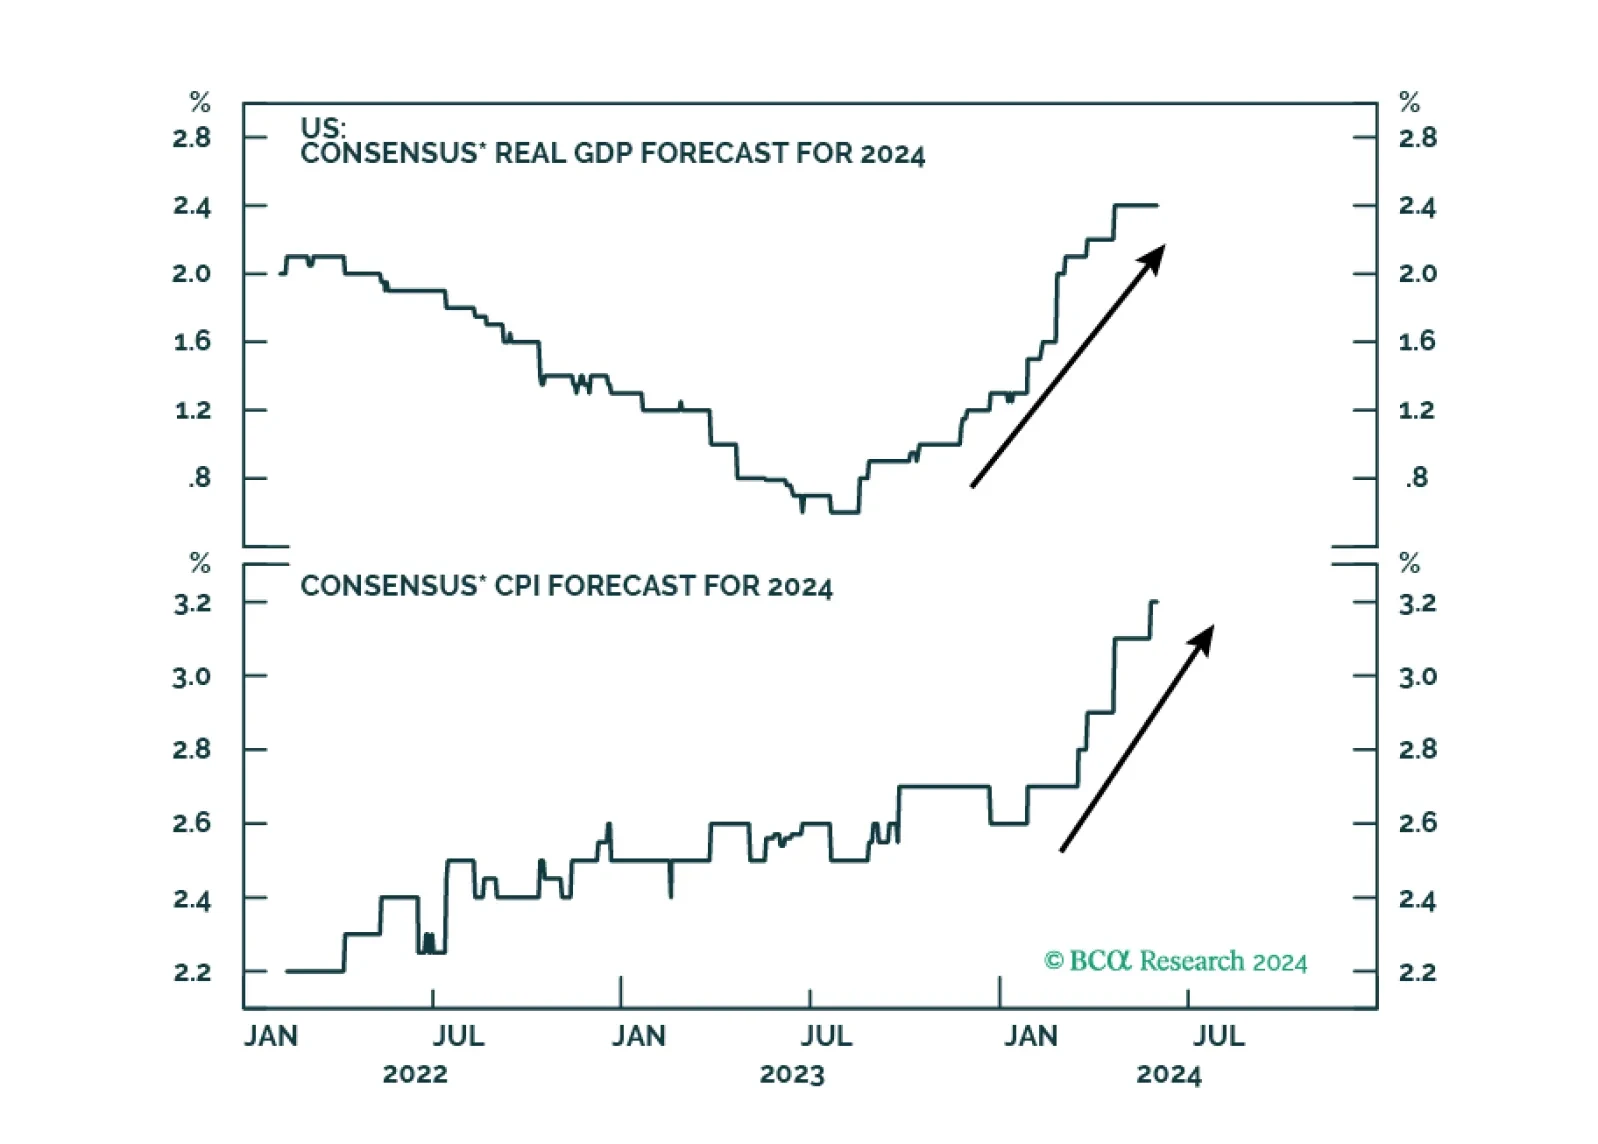
The US economy is in the “Overheating” phase, so stronger growth brings higher inflation. Tight monetary policy means recession is still likely over the next 12 months. Stay defensive.

We are positive Private Credit but currently underweight Public BDCs. Today’s market pricing and sentiment in BDCs are excessively optimistic. Long-term investors should await a better entry point. Traders may find an attractive short. This report also peels back the Public BDC onion and presents over/underweights across individual BDCs via our filtering methodology. Also included at the end of this report is an updated presentation titled 'Private Credit: Drivers Of The Boom And Understanding Risks On The Horizon,' recently presented at GII’s Private Credit Roundtable in Australia. It features updated charts and additional analysis.
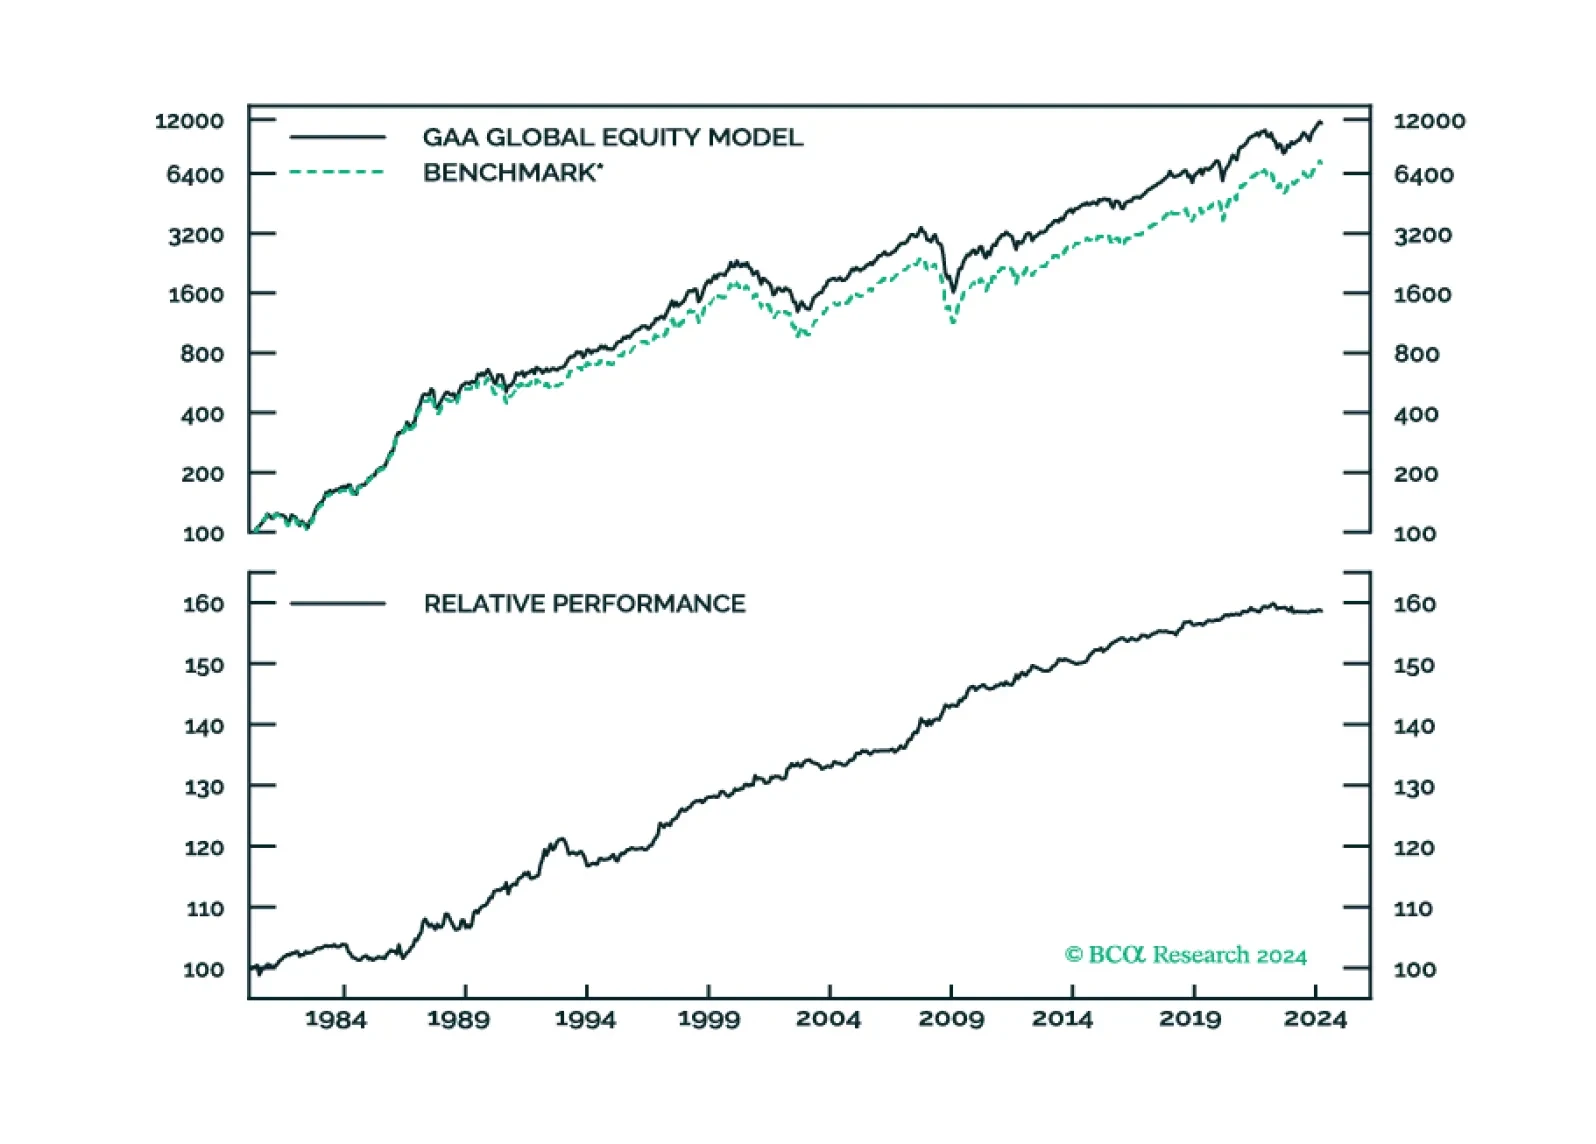
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
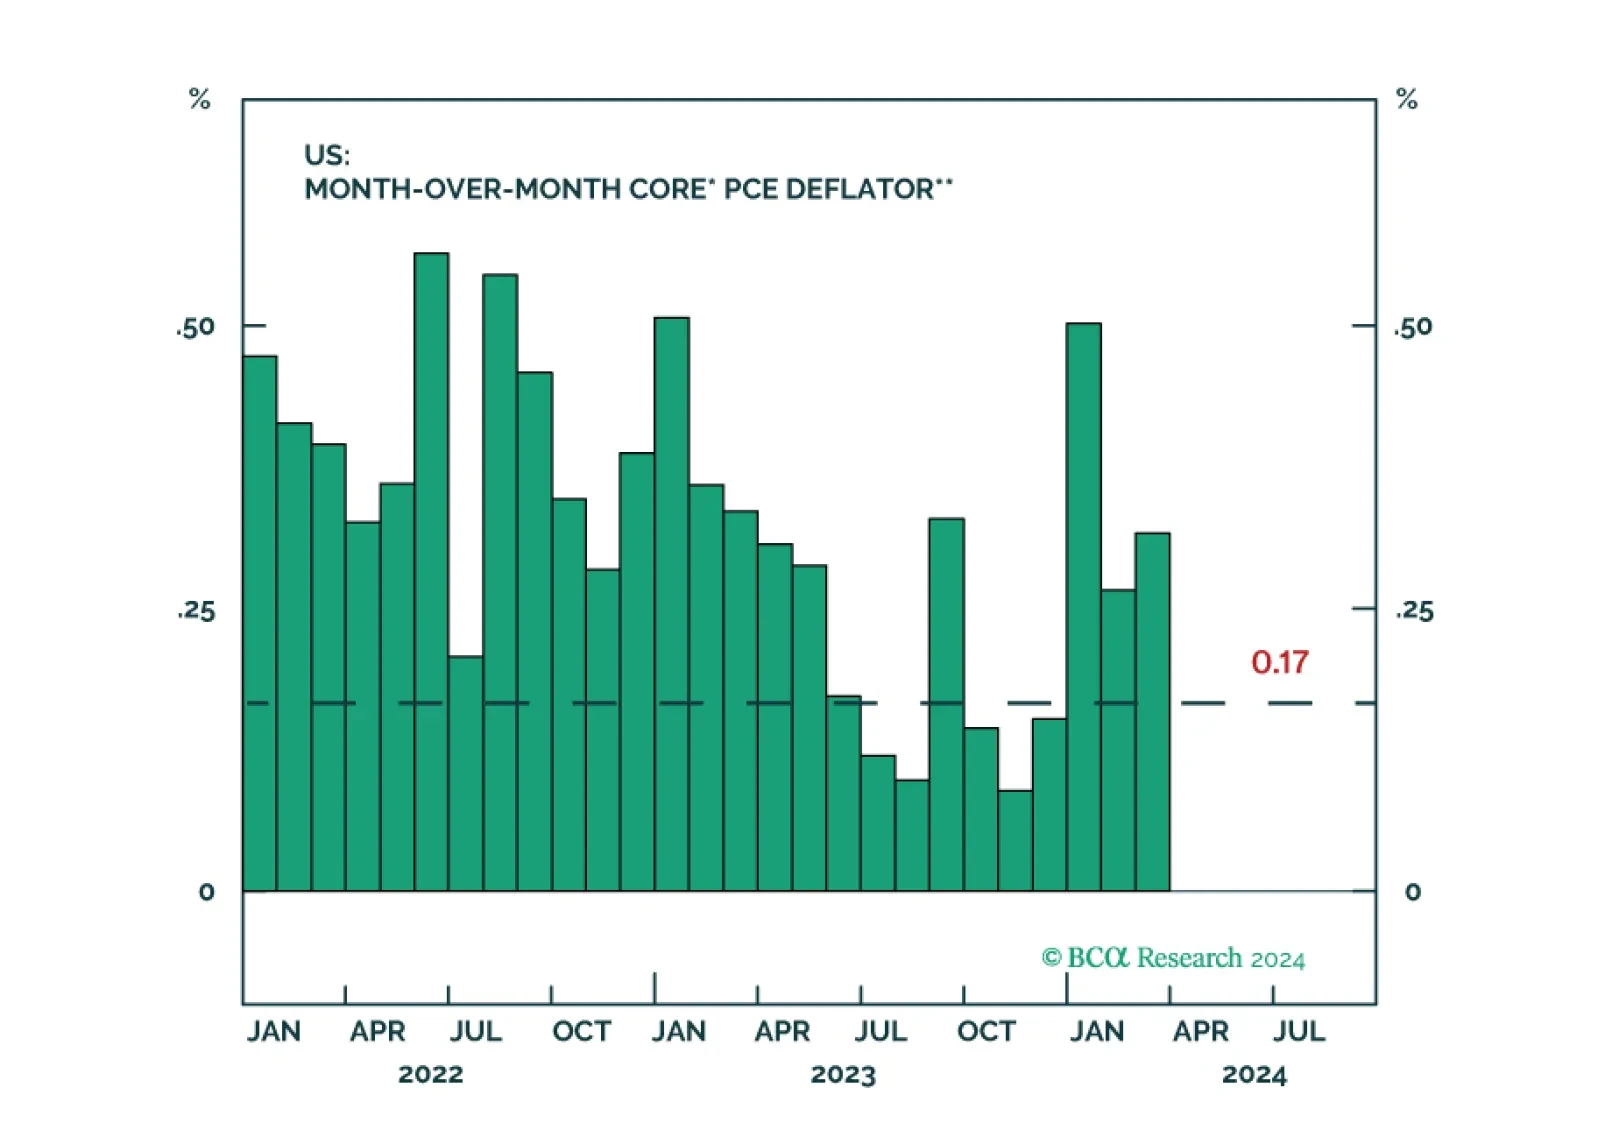
Central banks are in a dilemma whether to prioritize supporting growth or bringing inflation back to target. This is unlikely to end well. Investors should be defensively positioned.
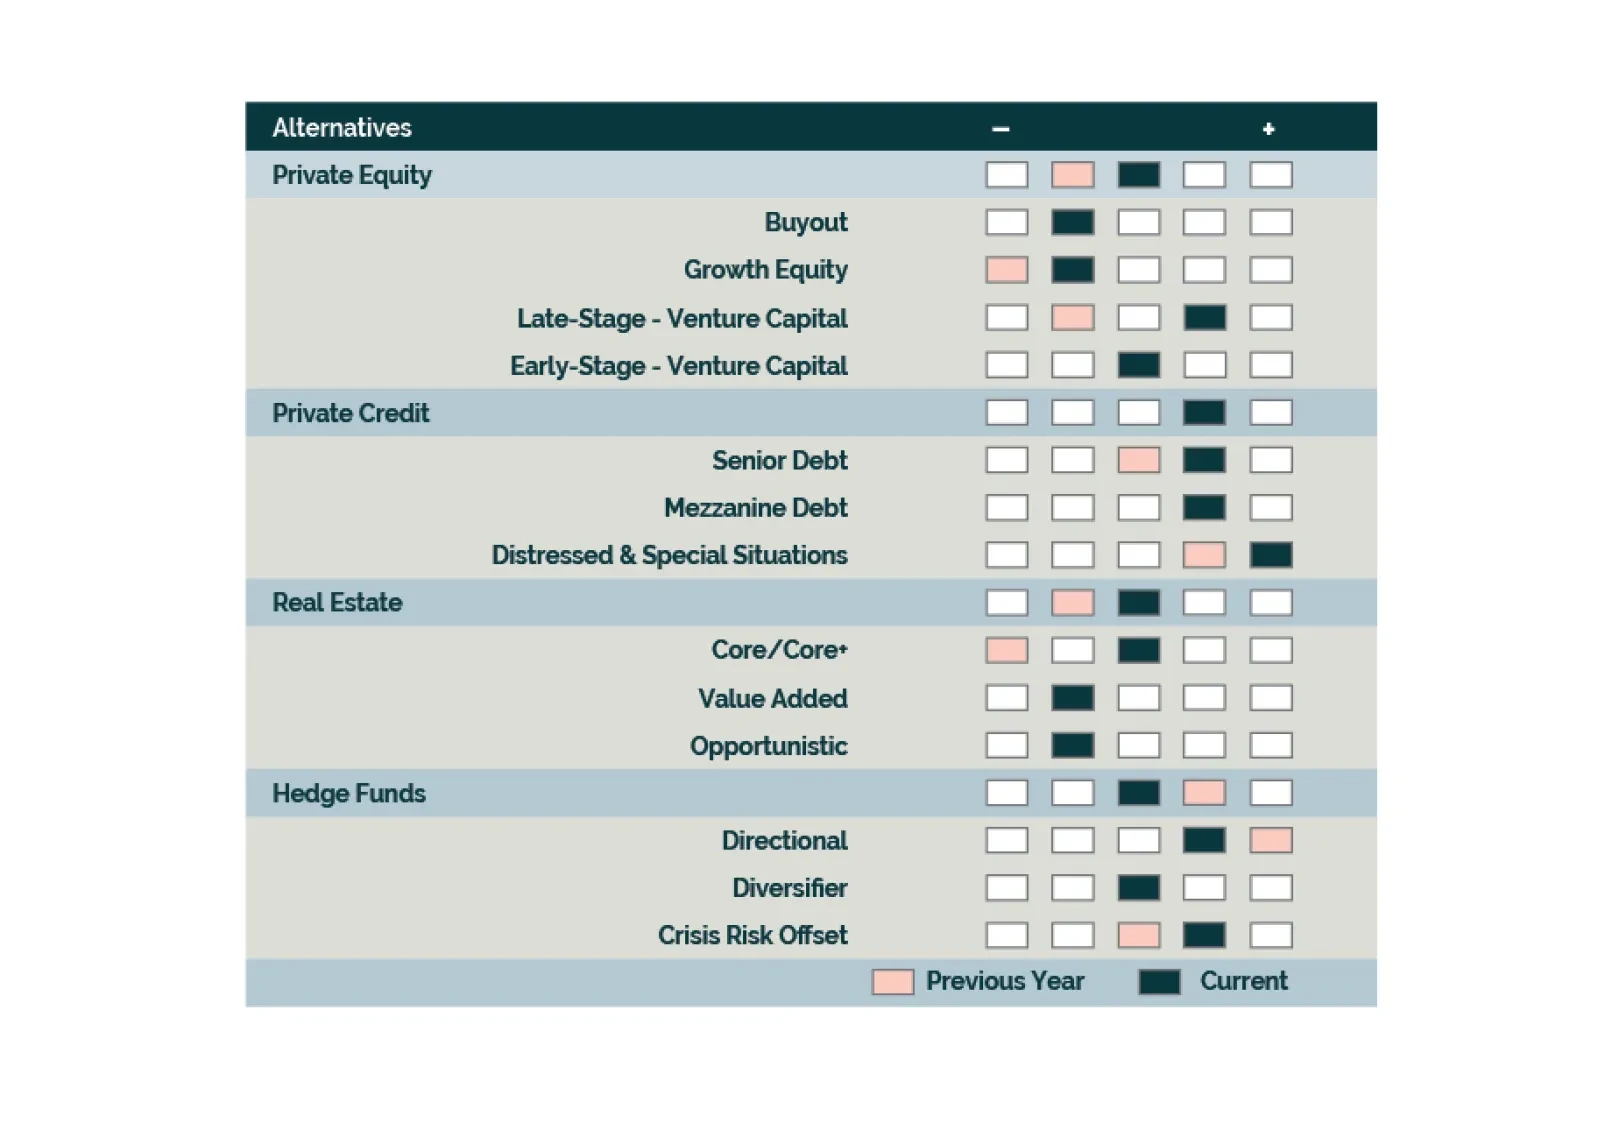
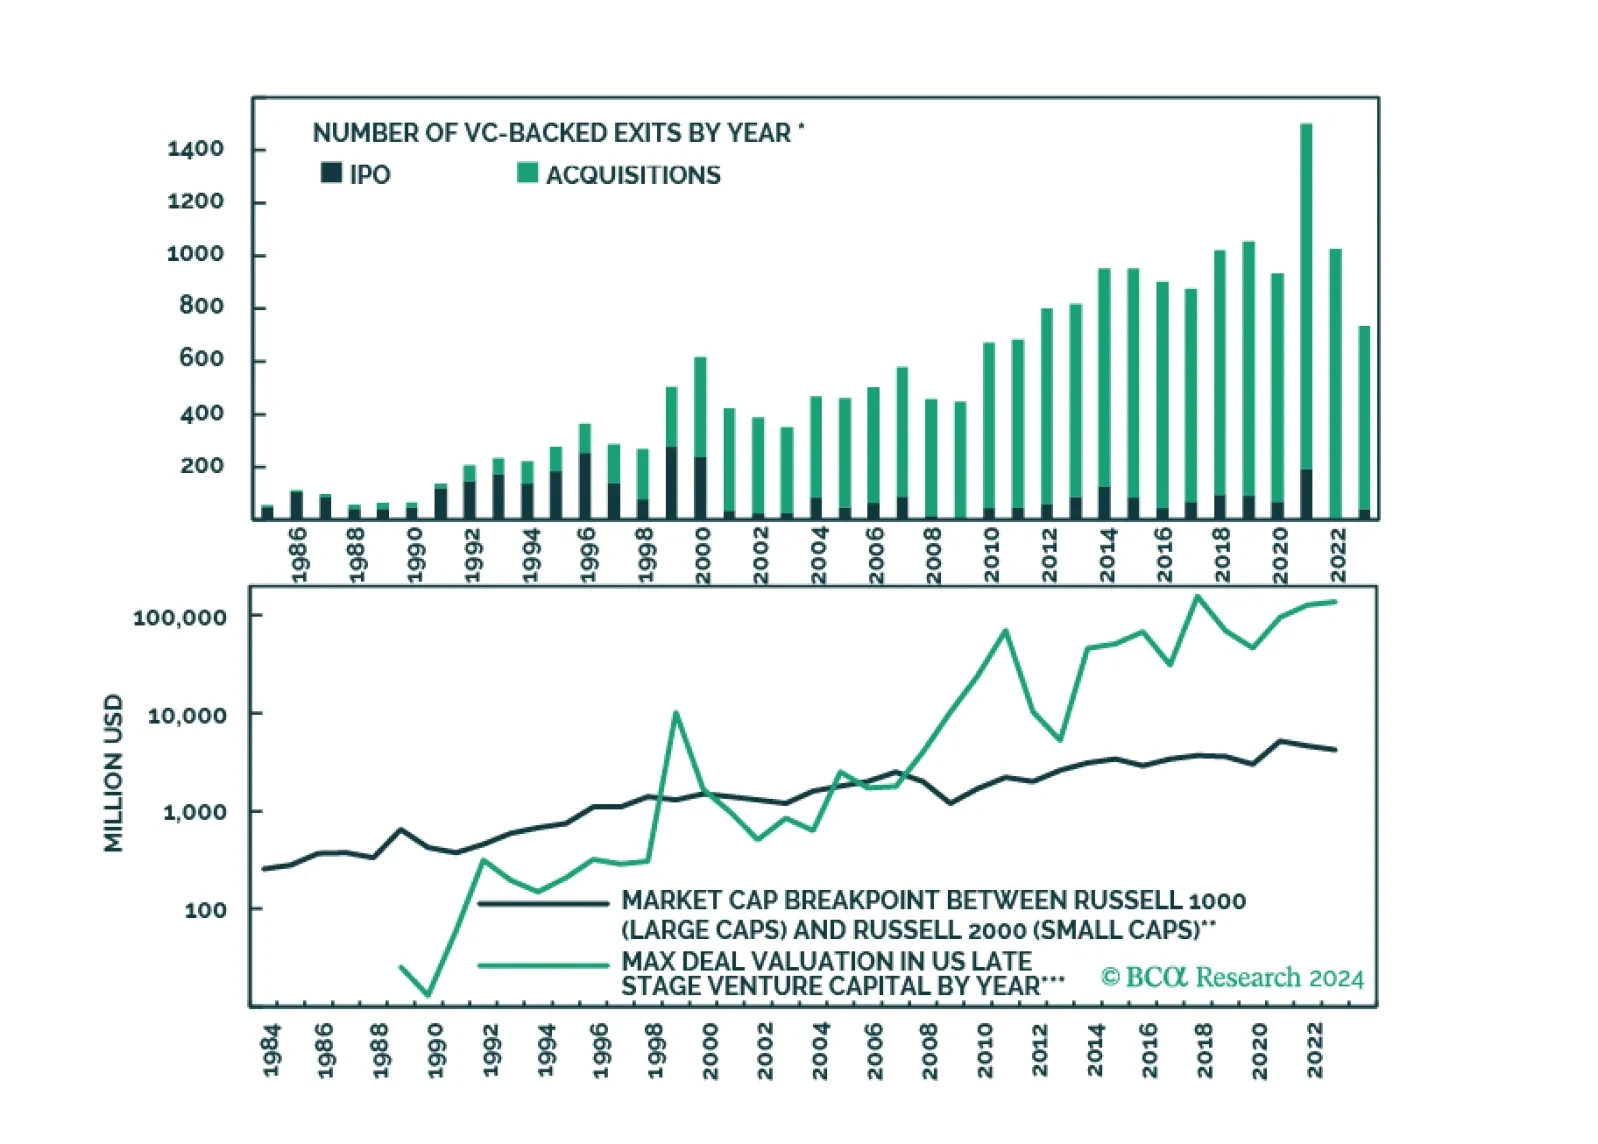
We go overweight Late-Stage Venture Capital and APAC Private Equity but remain underweight North America Buyouts. We maintain our neutral outlook towards Hedge Funds and are positive on Long-Short Equity, Event Driven, and CRO strategies. We are cooling towards Direct Lending strategies as competition and relative opportunities increase. CRE’s downturn continues to unfold; we are starting to be buyers.
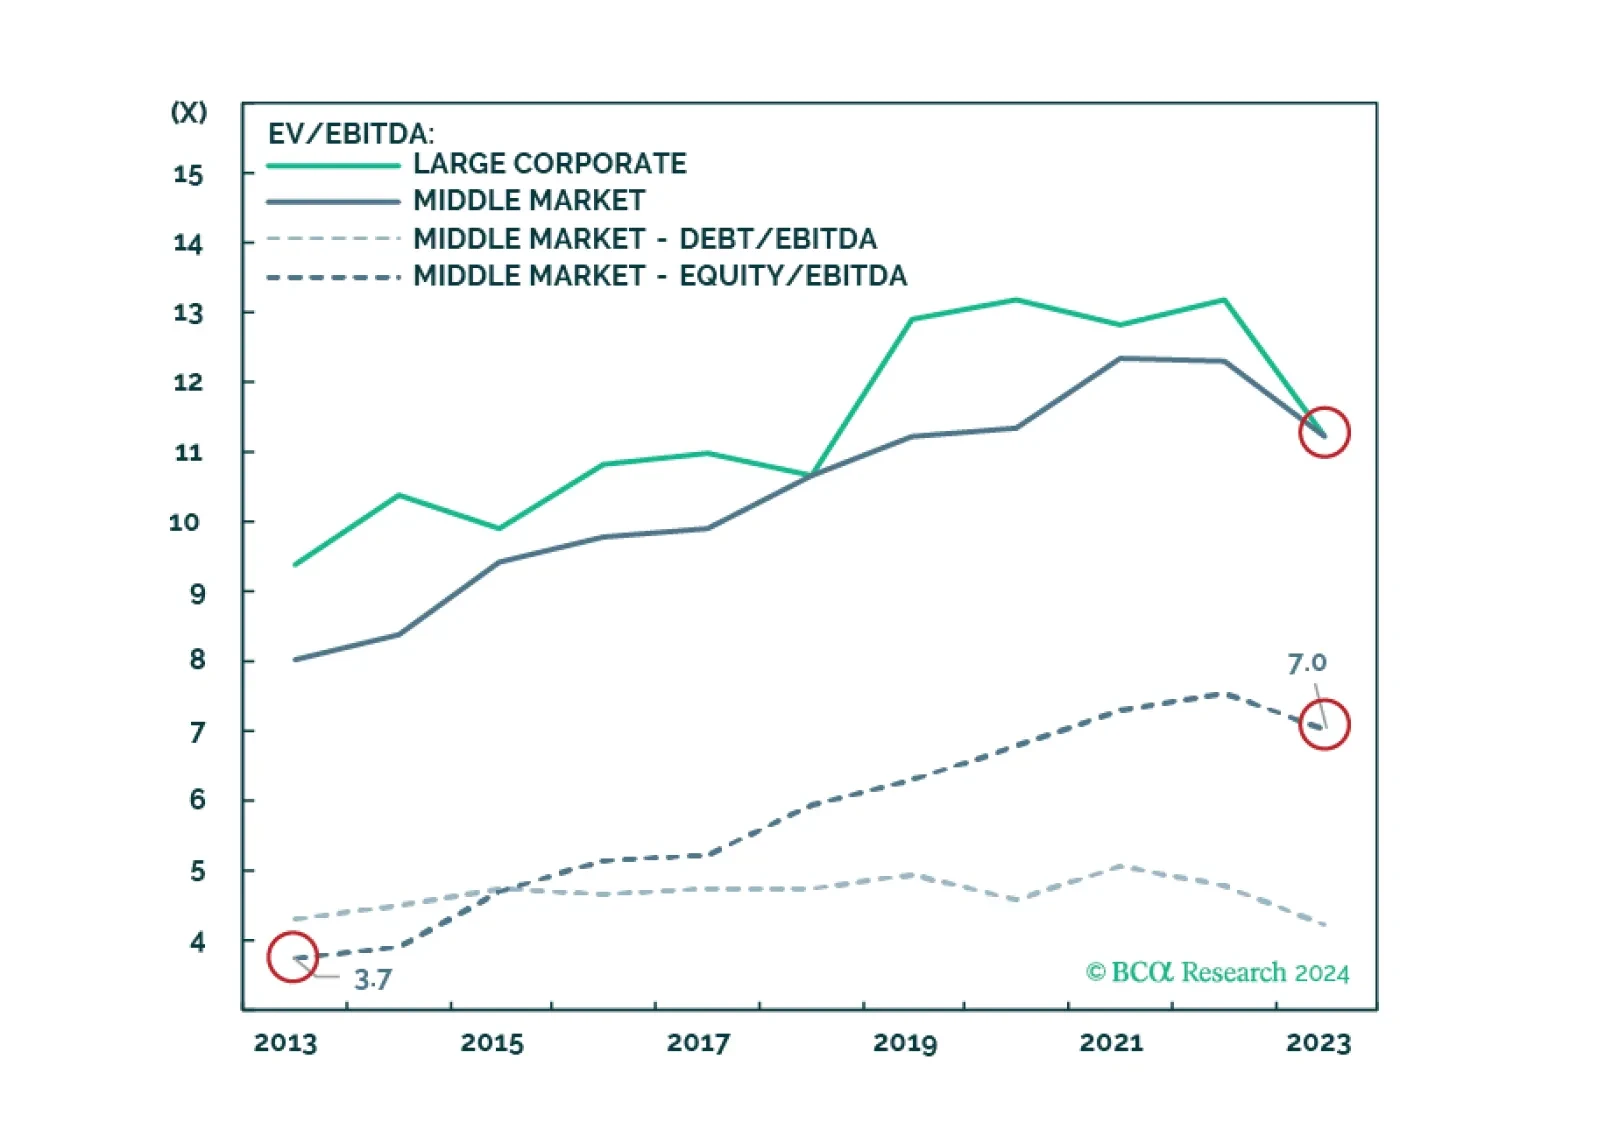
Valuation metrics in Private Equity and Venture Capital vary widely by source, stage, location, and other factors. They are prone to imprecision, which is why investors should monitor a diverse set. This report offers a series of charts comparing valuation ratios. Focusing solely on valuations reveals that North America Middle Market Buyouts appear less attractive and geographical selection will be more important going forward.
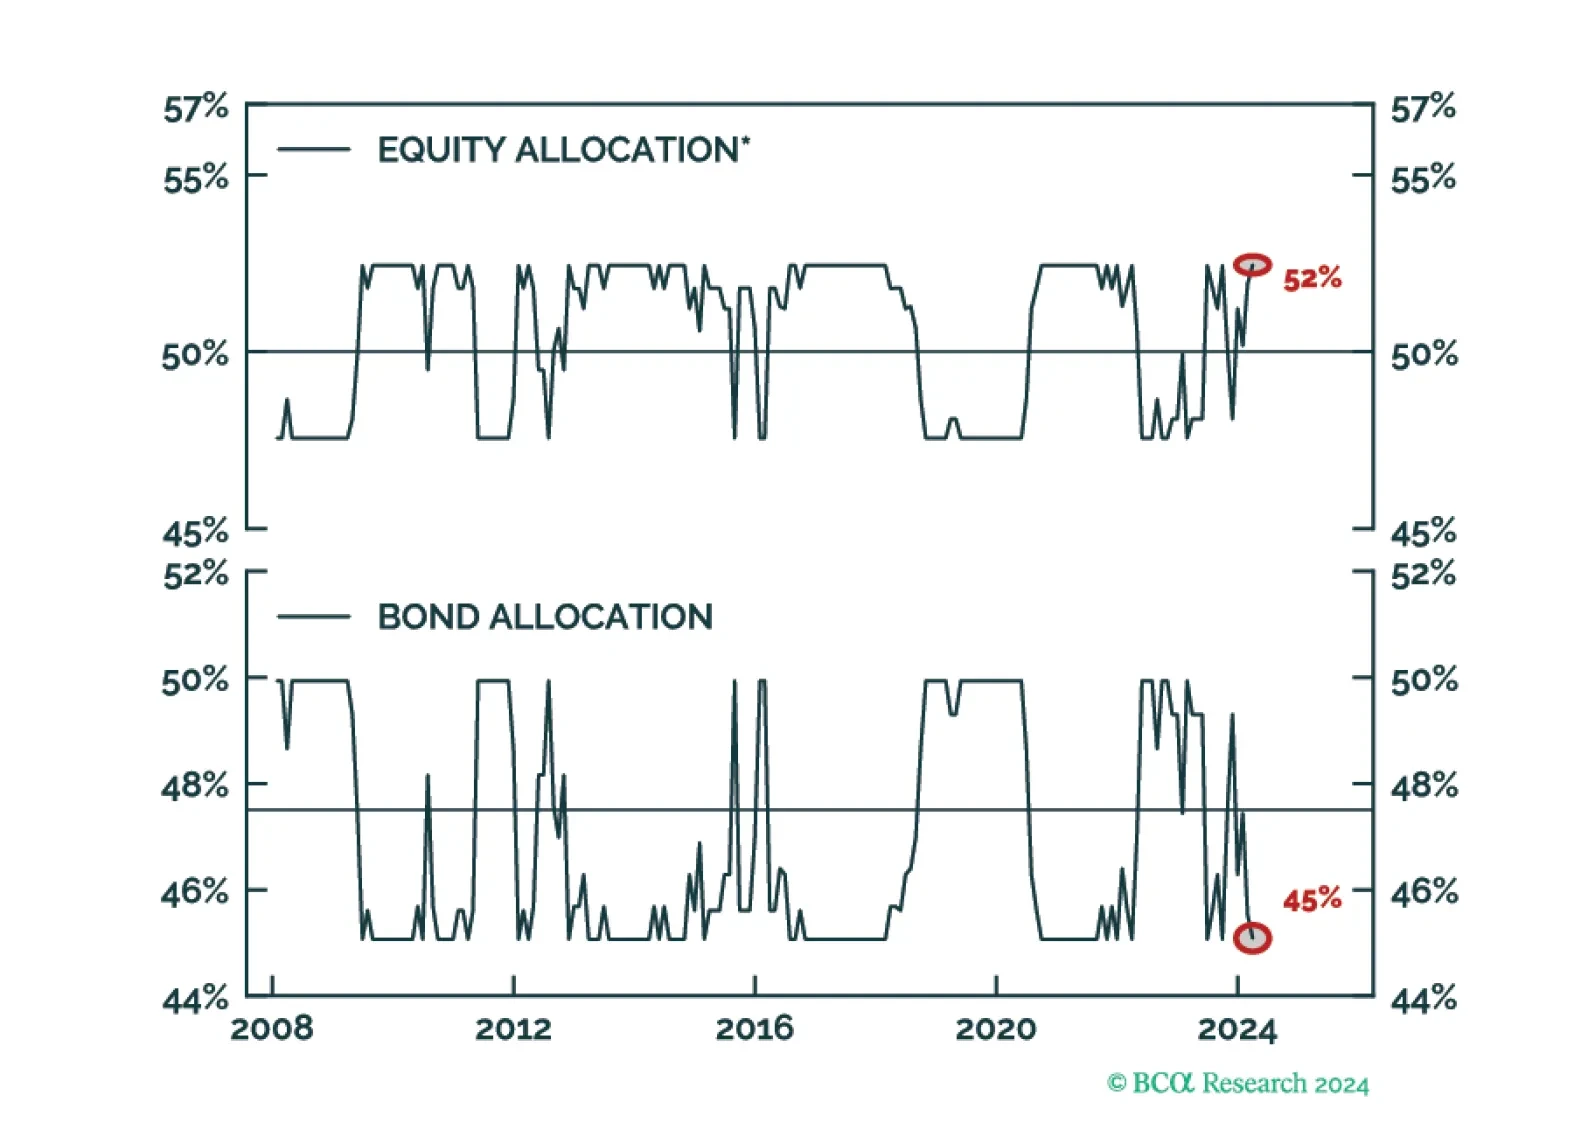
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
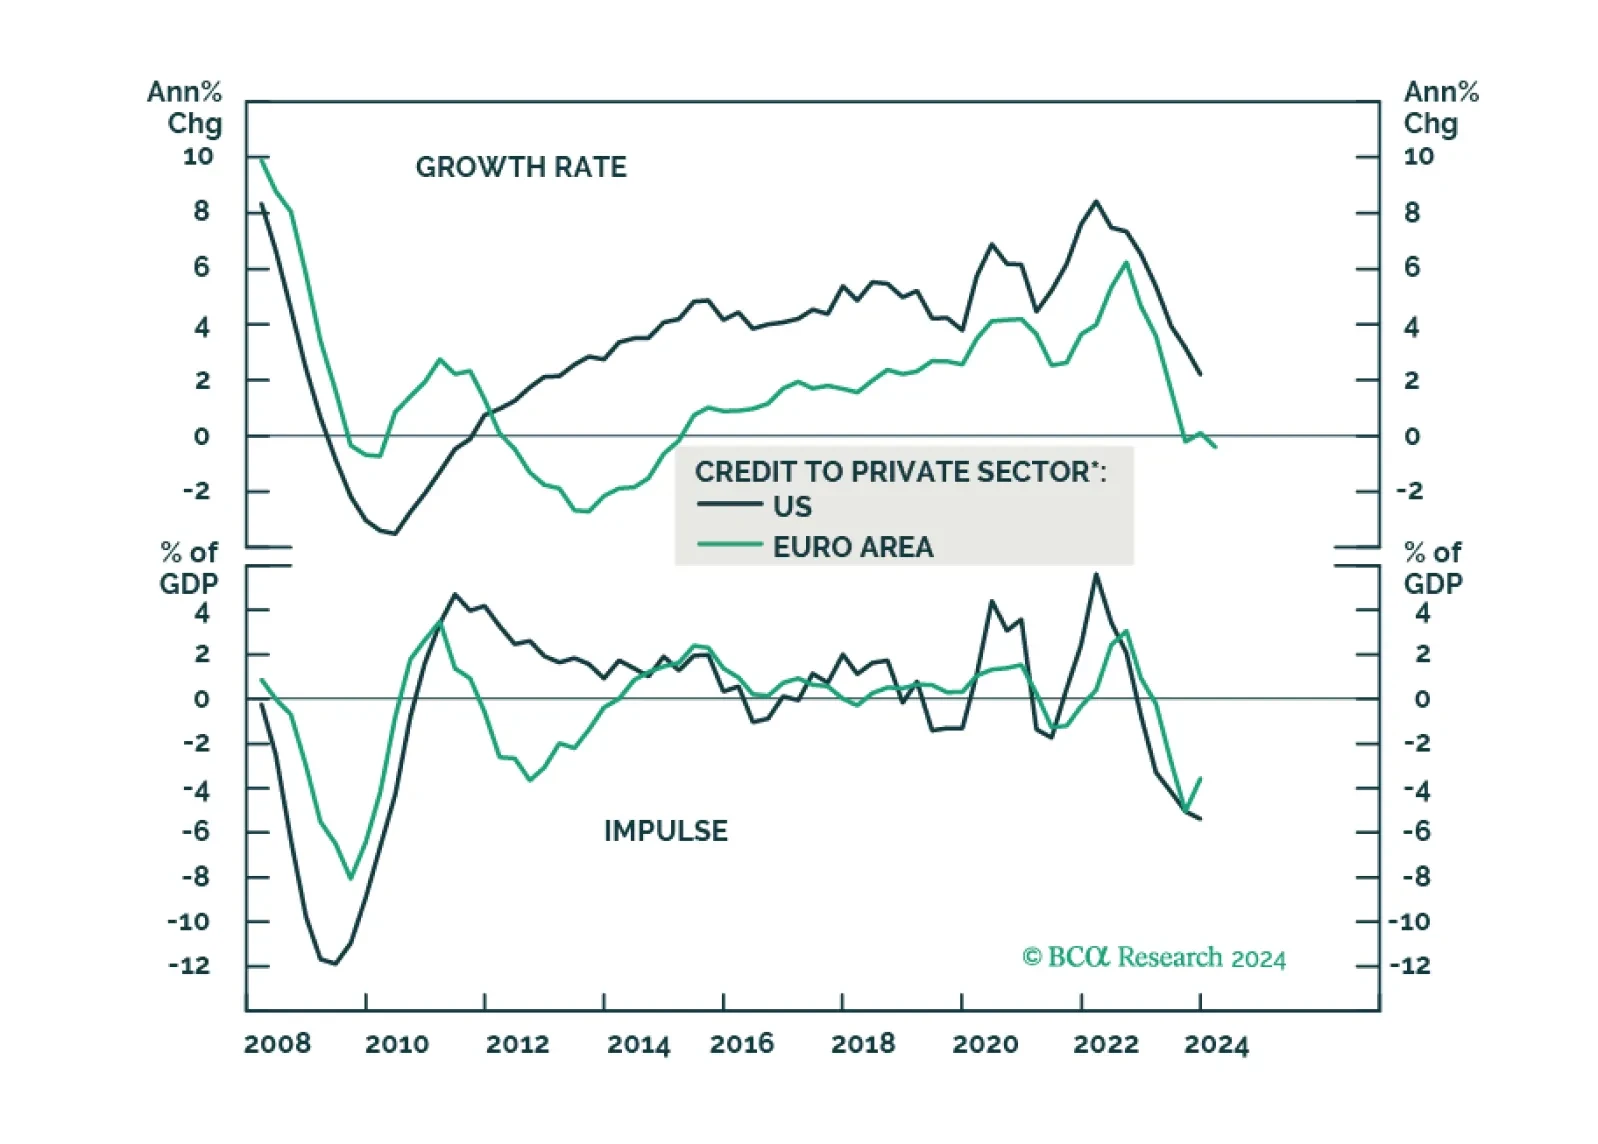
The global economy is wobbling precariously between slowing growth and reaccelerating inflation. This is unlikely to end well. Stay cautious, and hedge against both recession and inflation.