Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
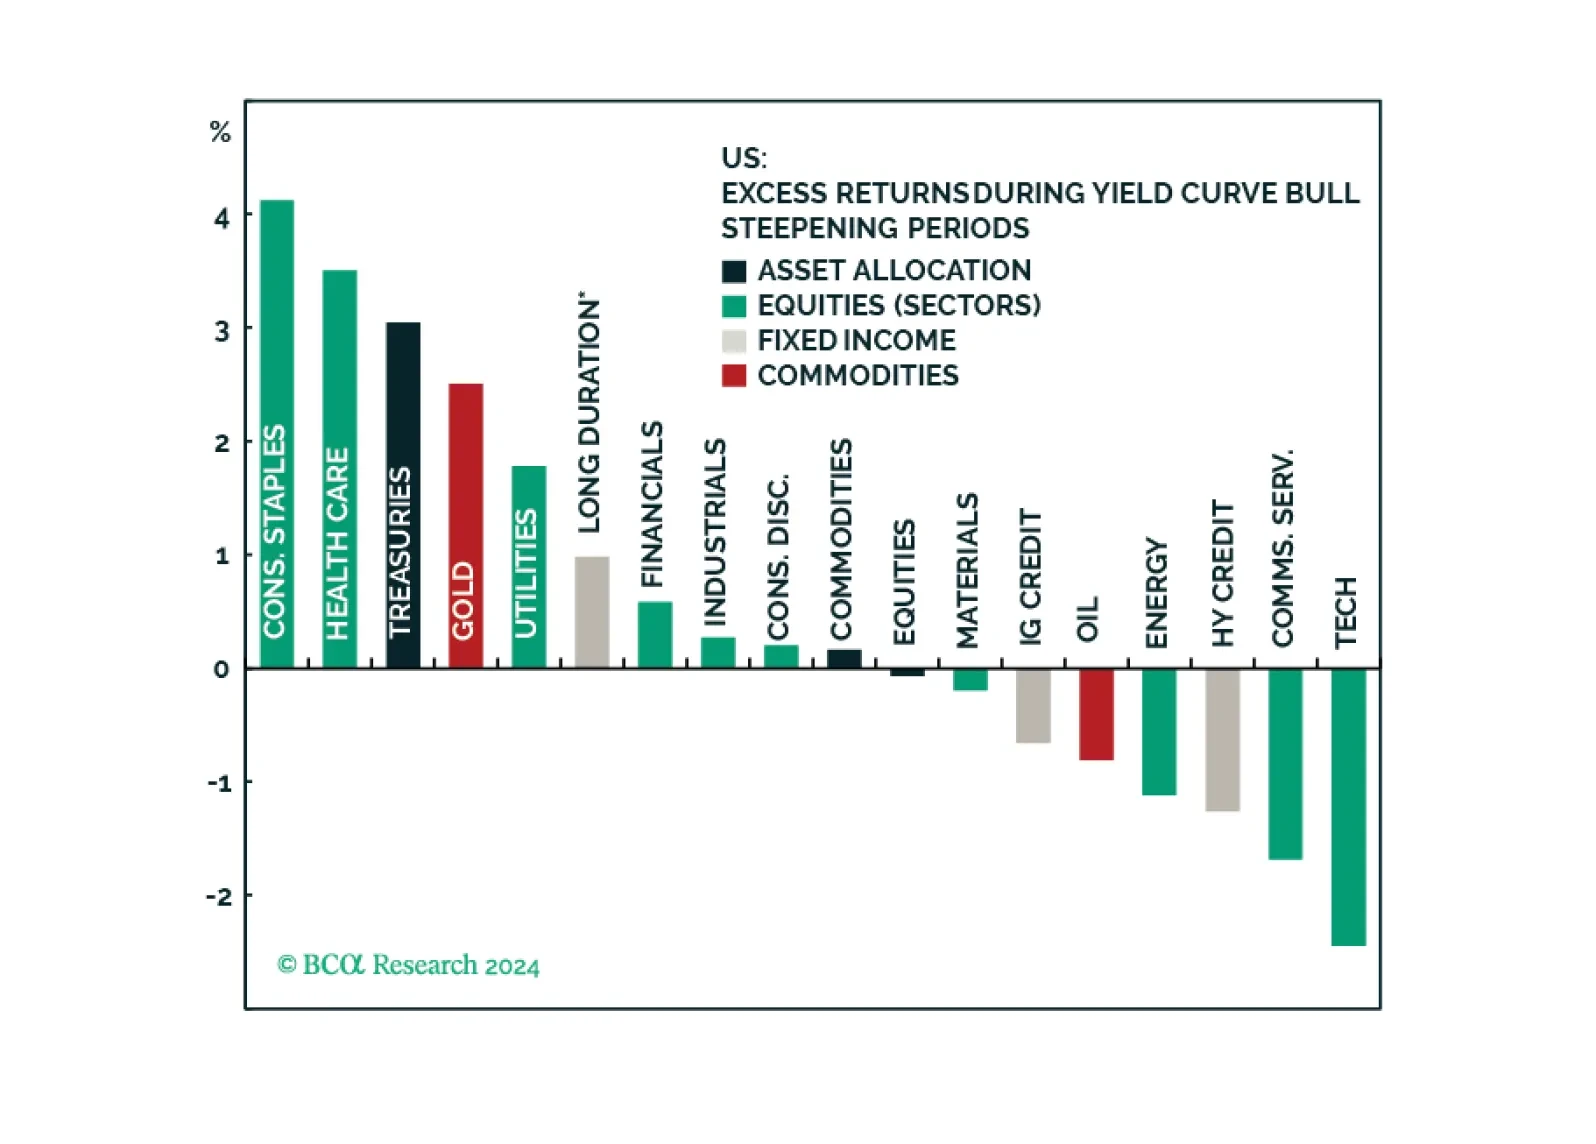
As the first Fed cut of this cycle approaches, this Strategy Insight looks at the cross-asset implications of a Treasury curve bull steepening. Investors should maintain a defensive positioning.
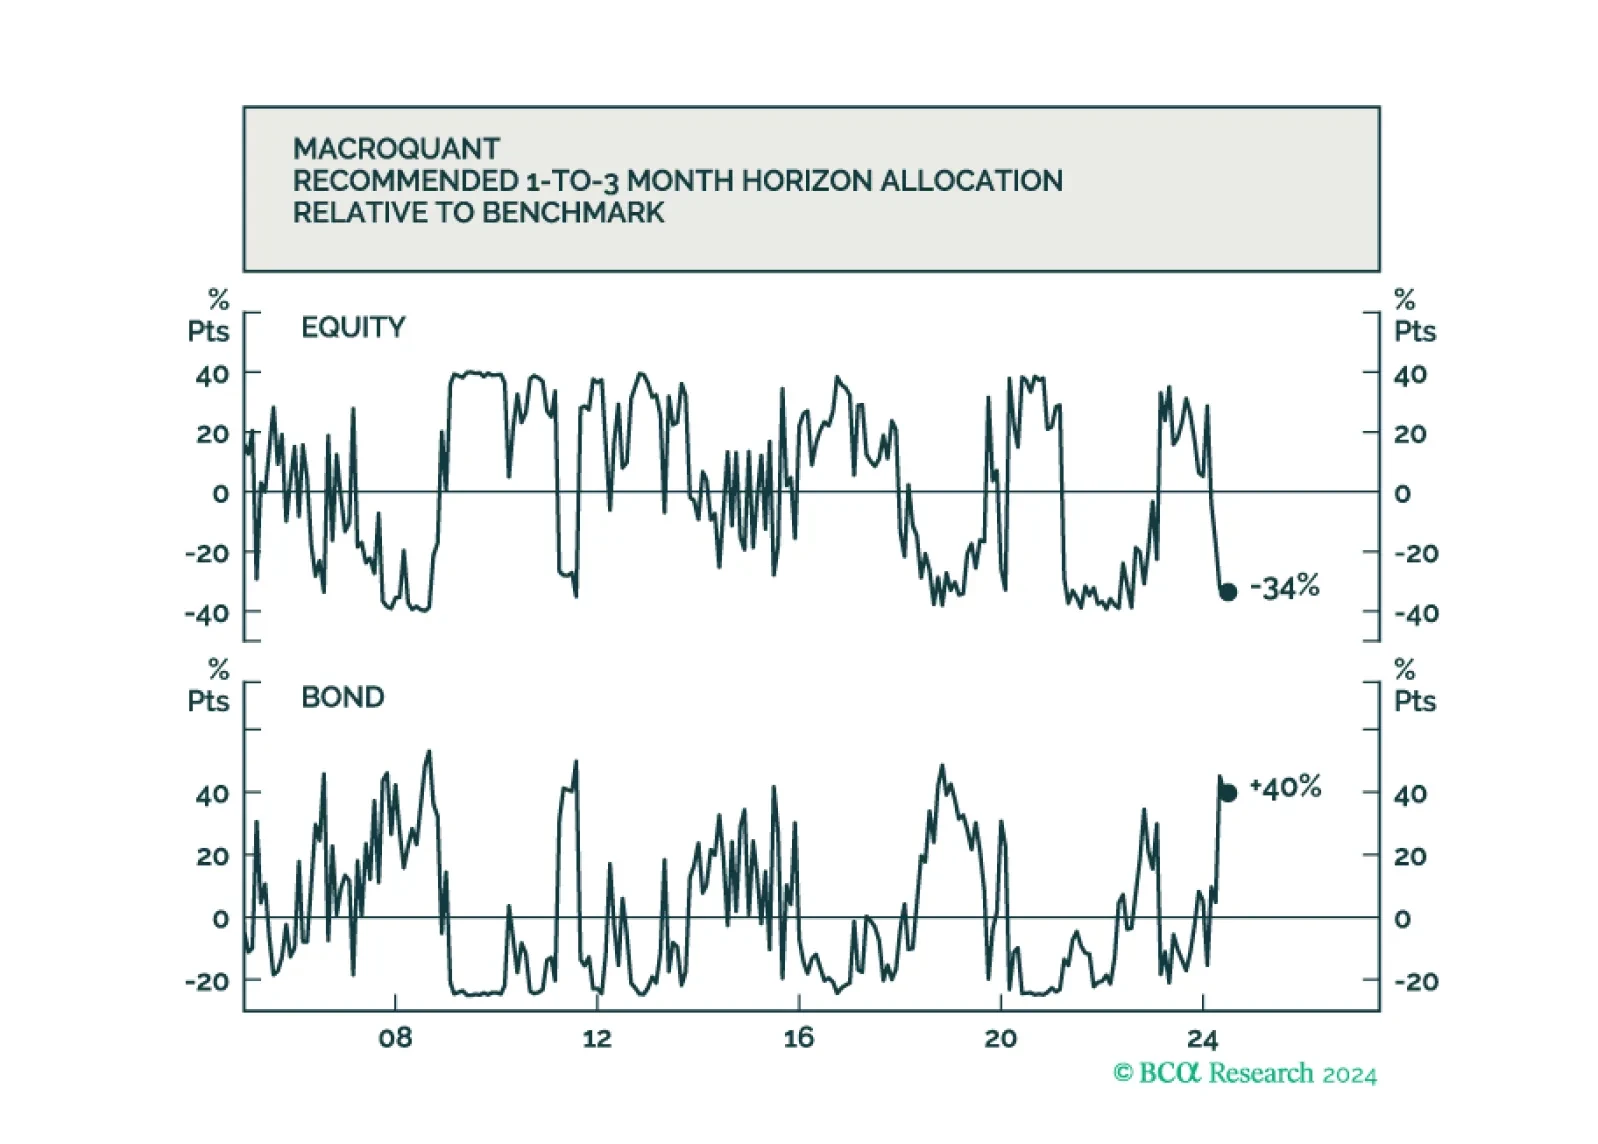
The Global Investment Strategy team downgraded global equities to underweight in late June. The latest reading from our MacroQuant model is consistent with this decision.
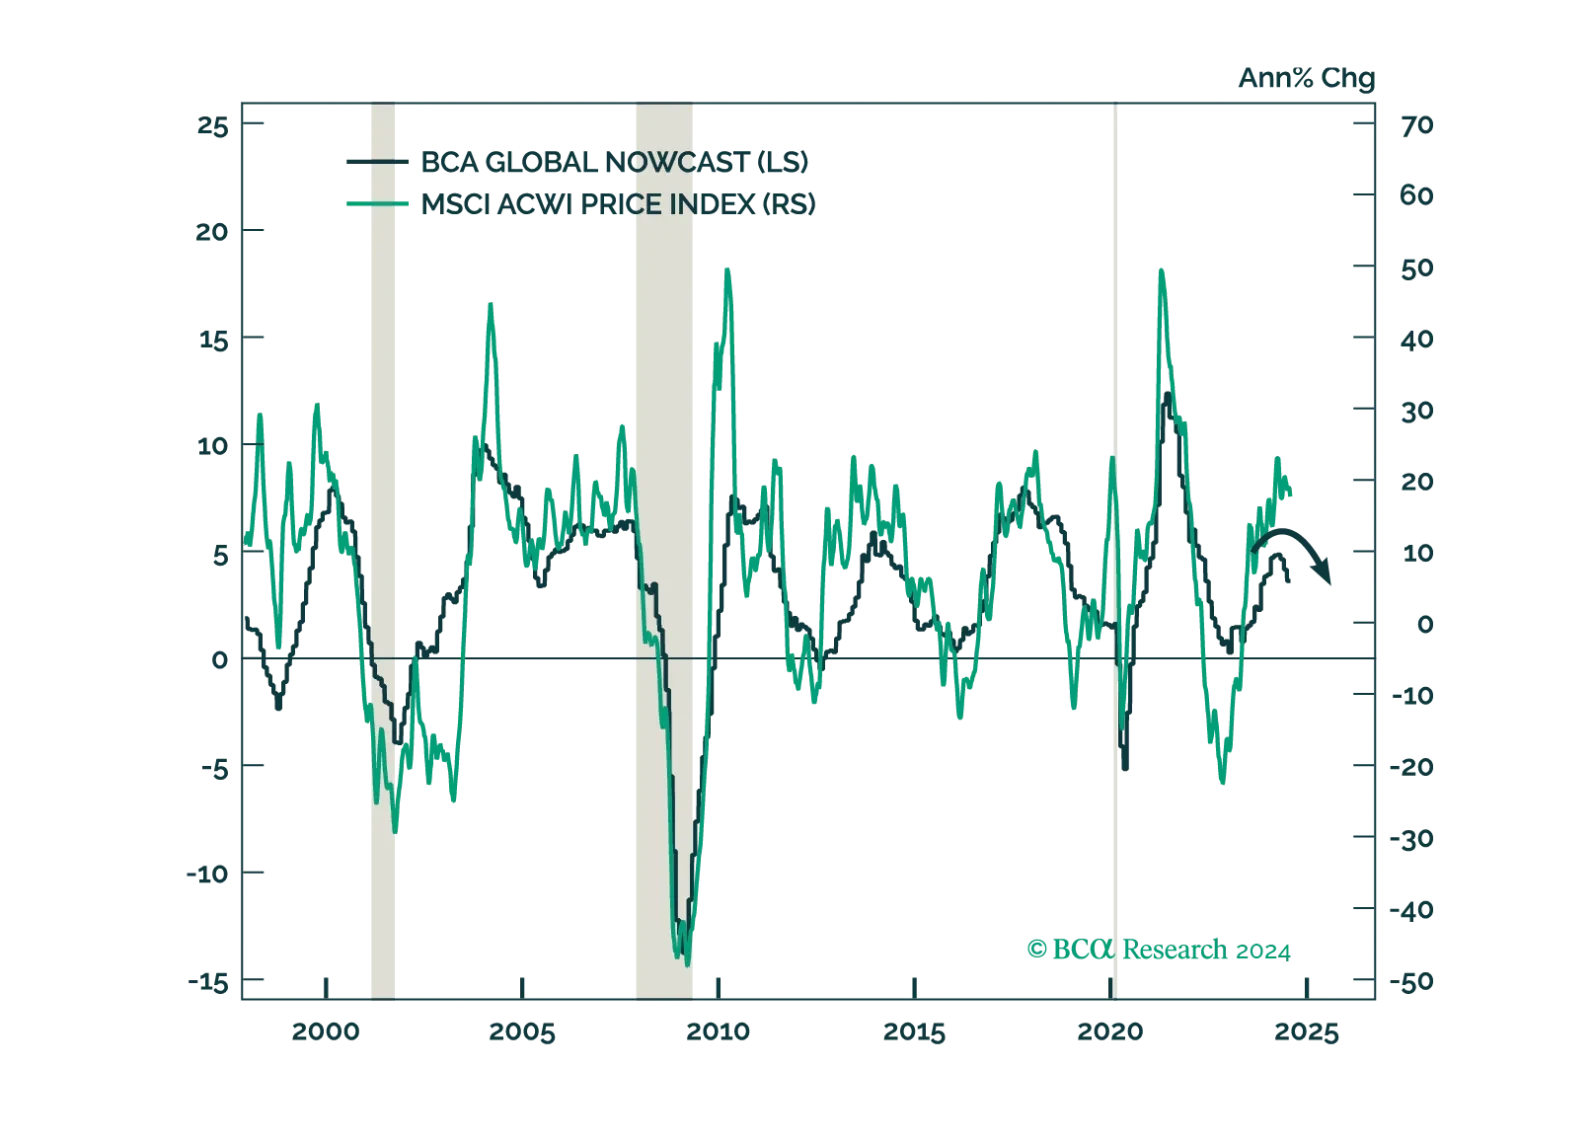
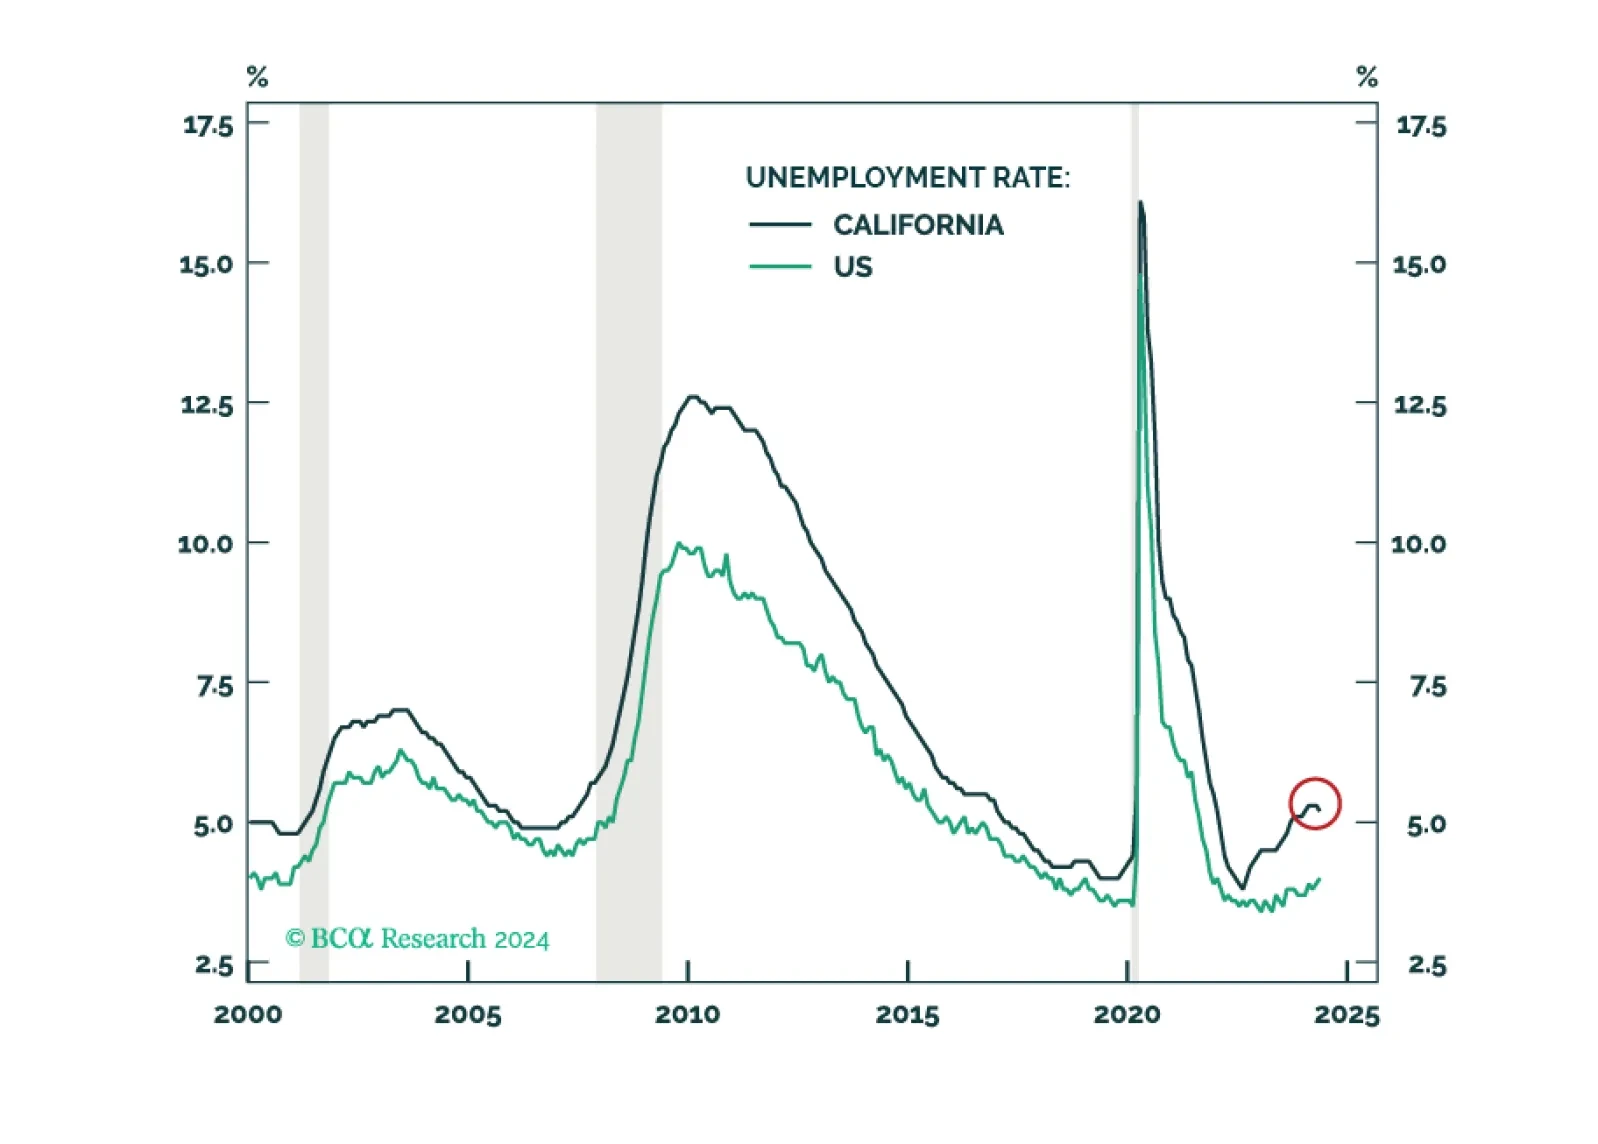
The market is pricing in a soft landing, but we see growing signs that the global economy is faltering. Investors should be defensively positioned.
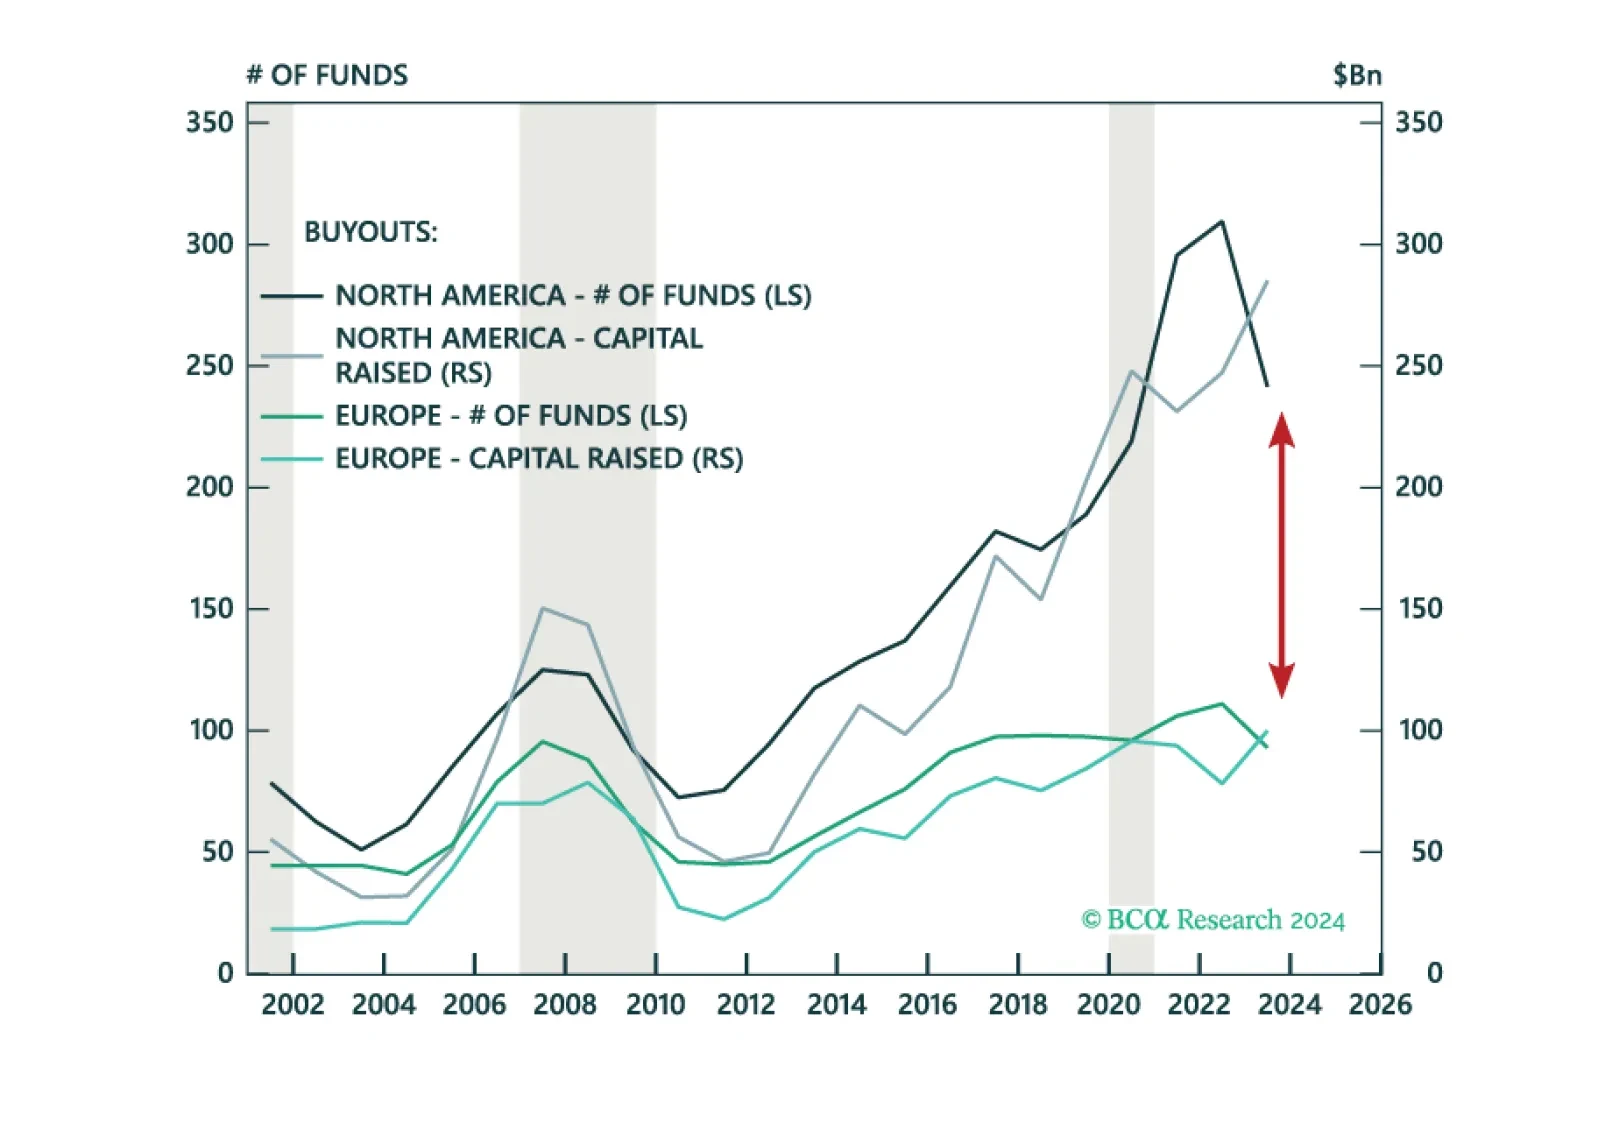
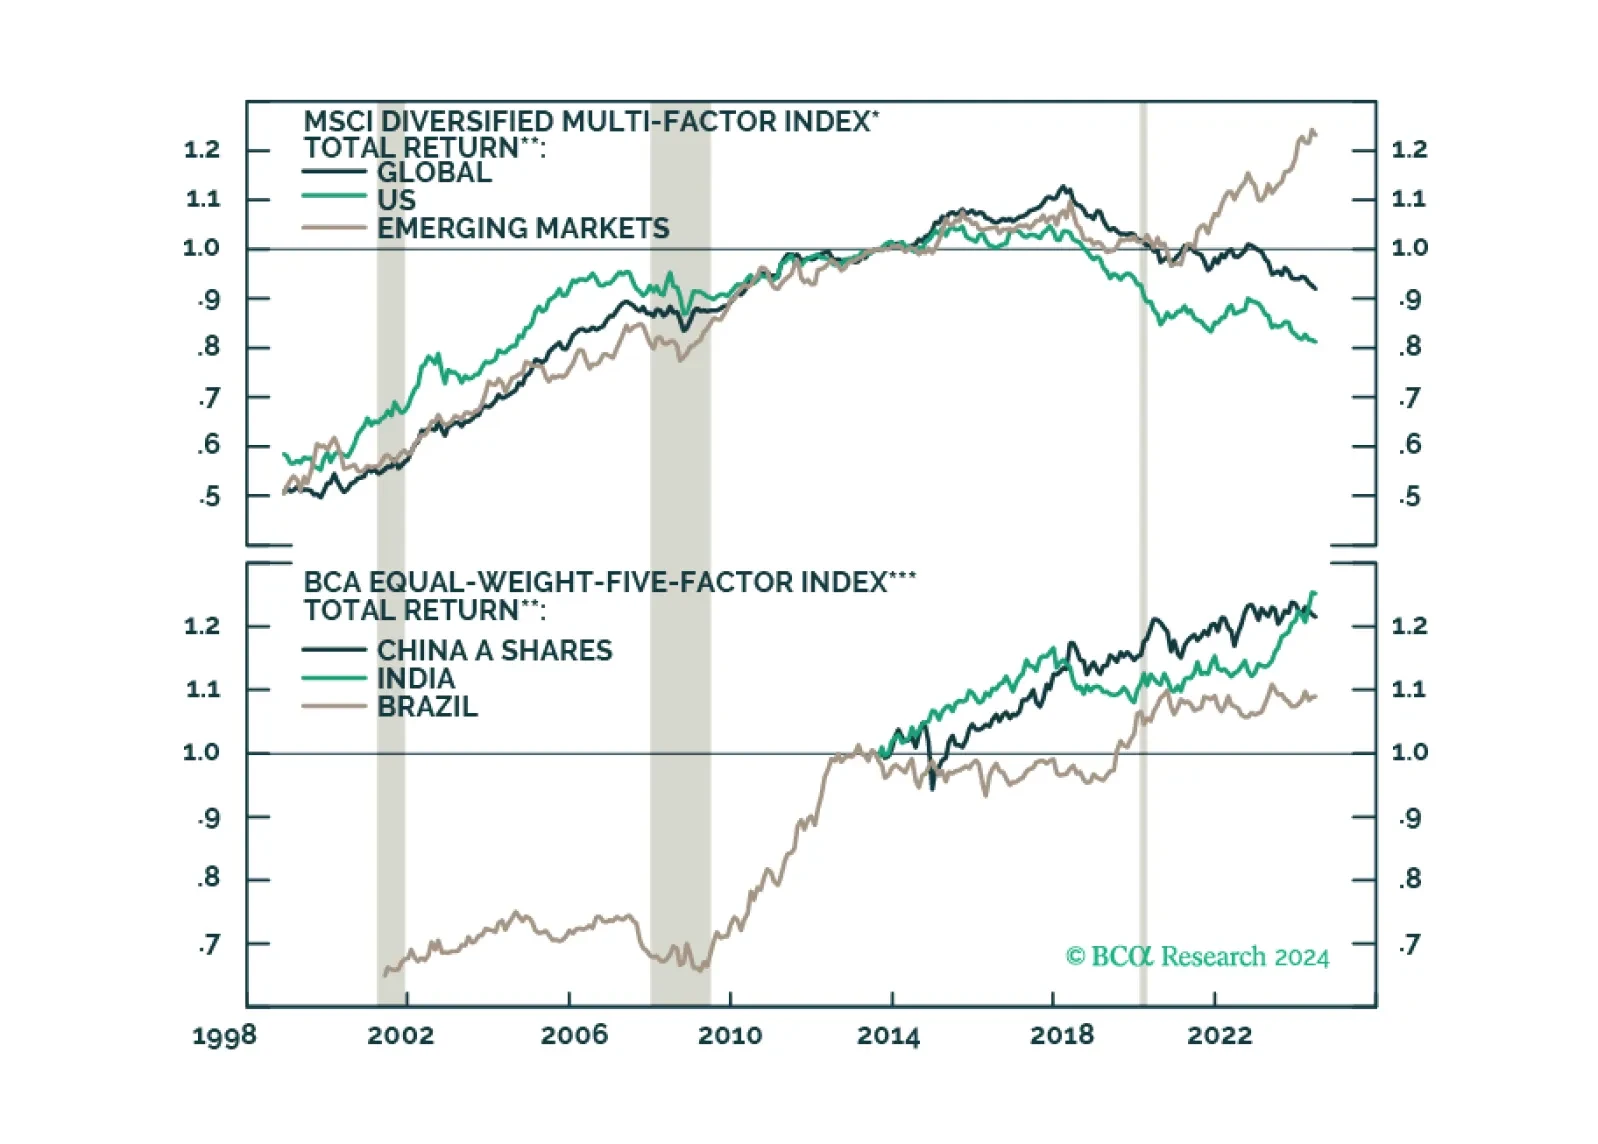
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are underweight Multi-Strategy amongst Hedge Funds. We maintain an overweight to Senior Direct Lending for Income with a preference for North America.
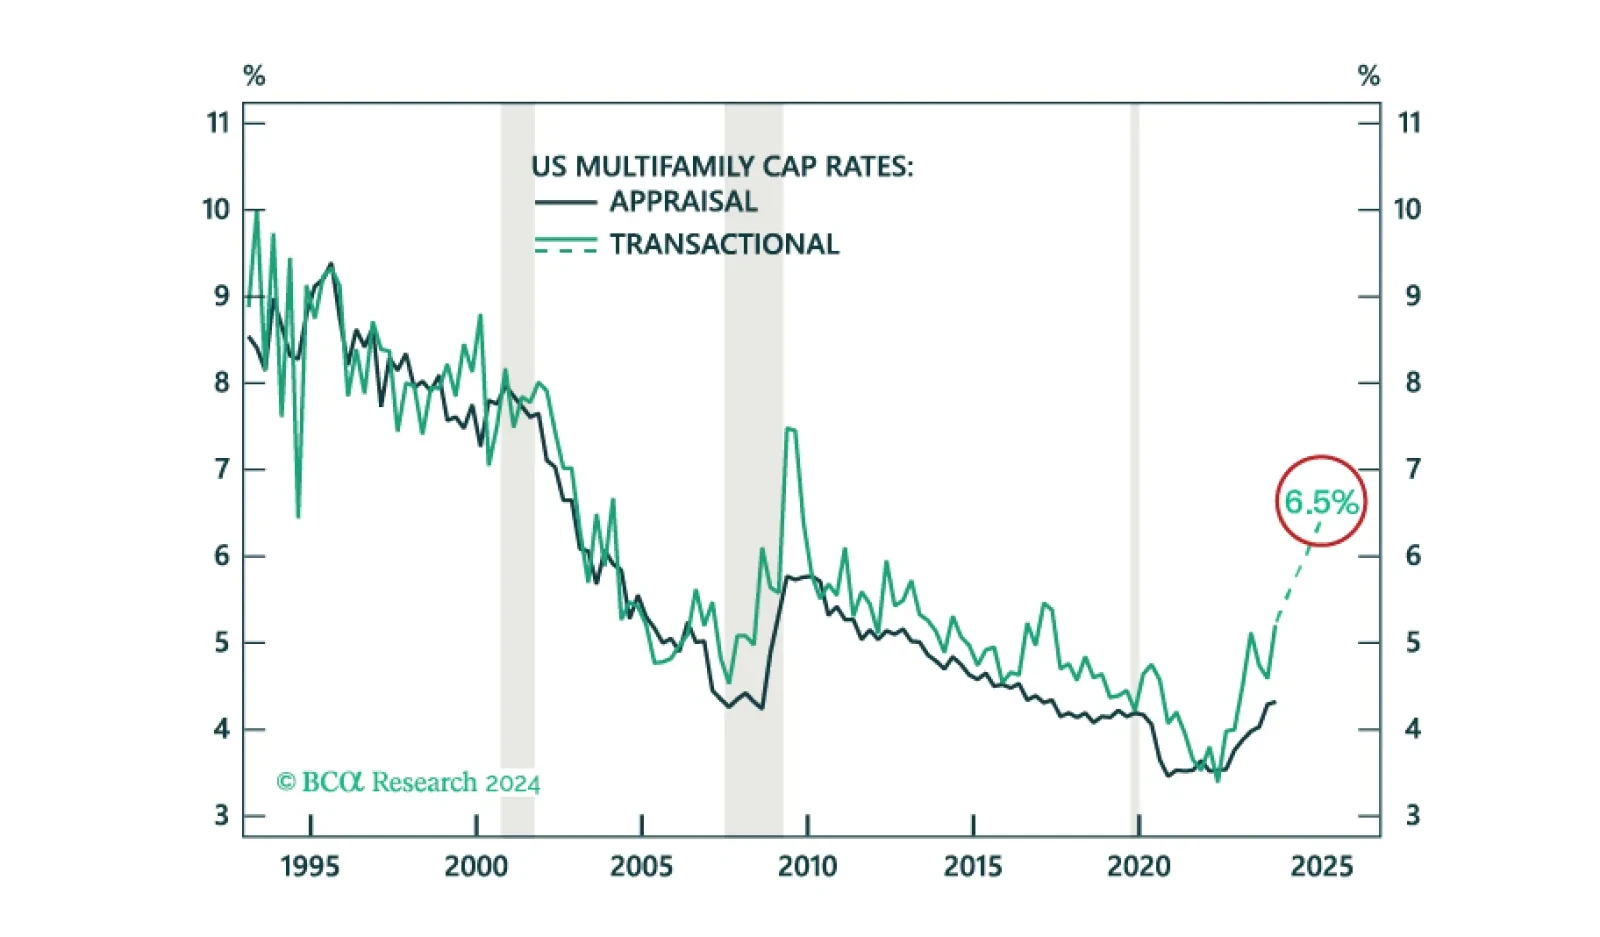
We project US Multifamily cap rates to increase from 5.2% to 6.5%. While we find an unfavorable risk-adjusted return on the asset, especially relative to other opportunities in CRE, cap rates are moving closer to peak.
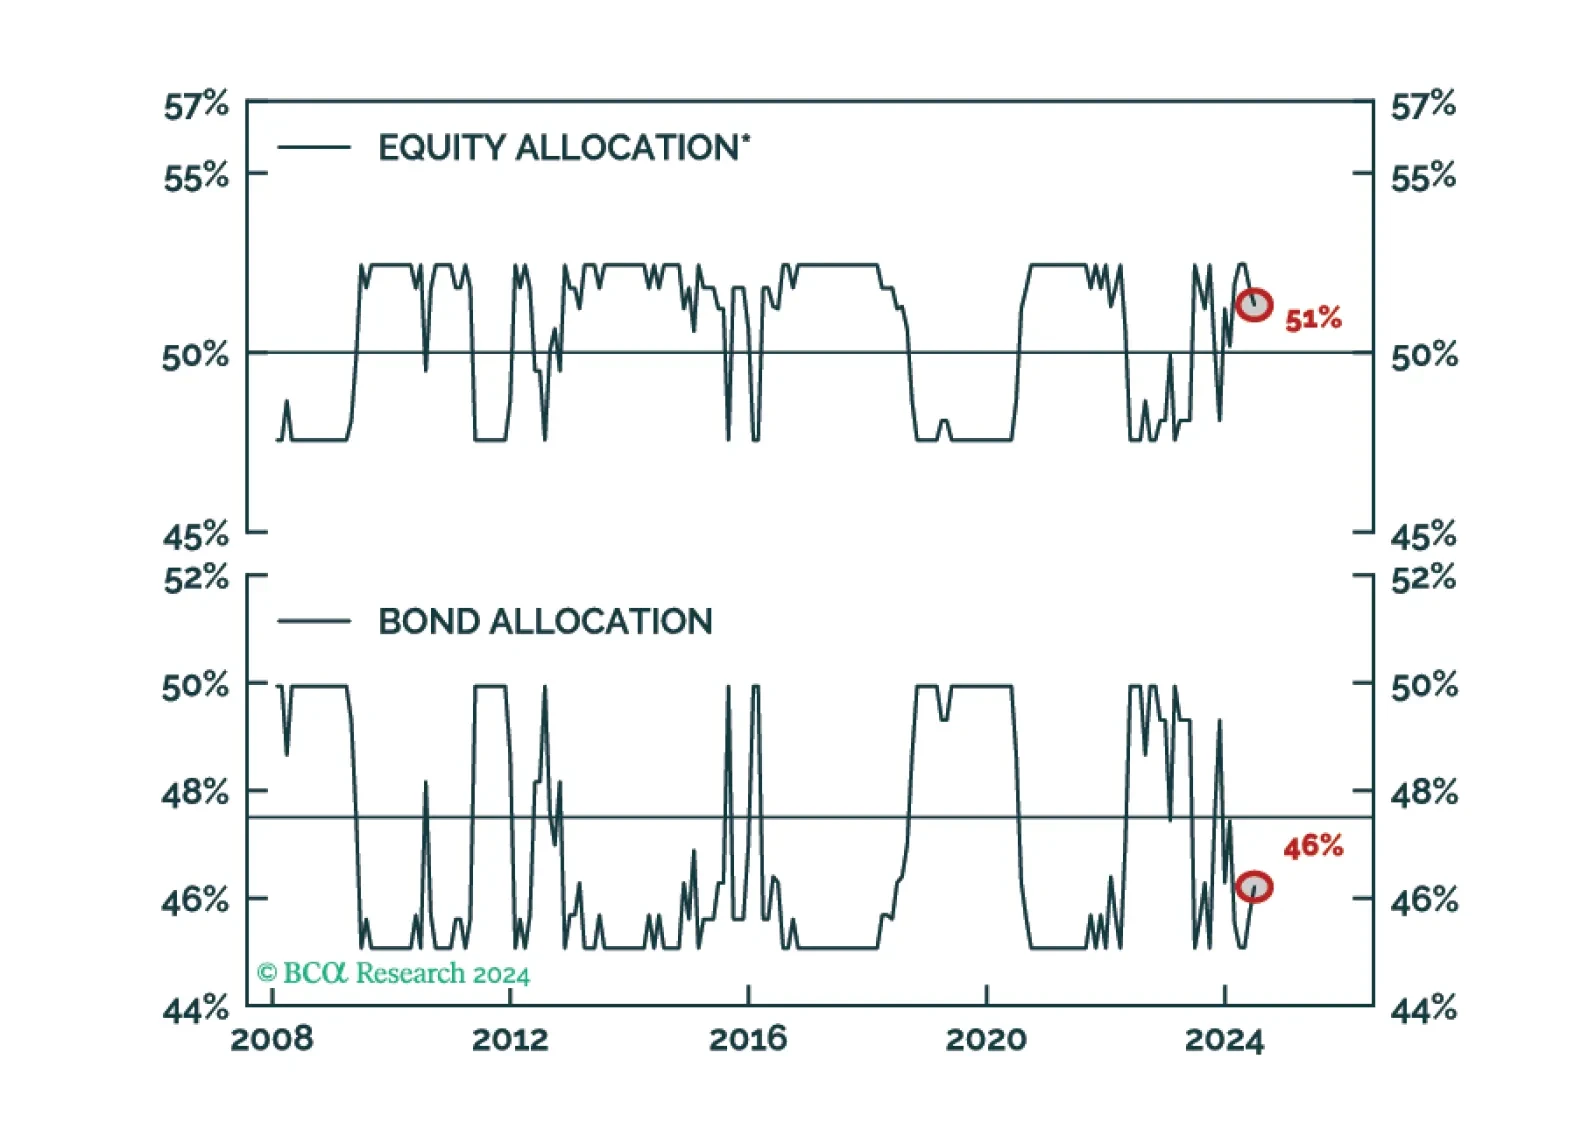
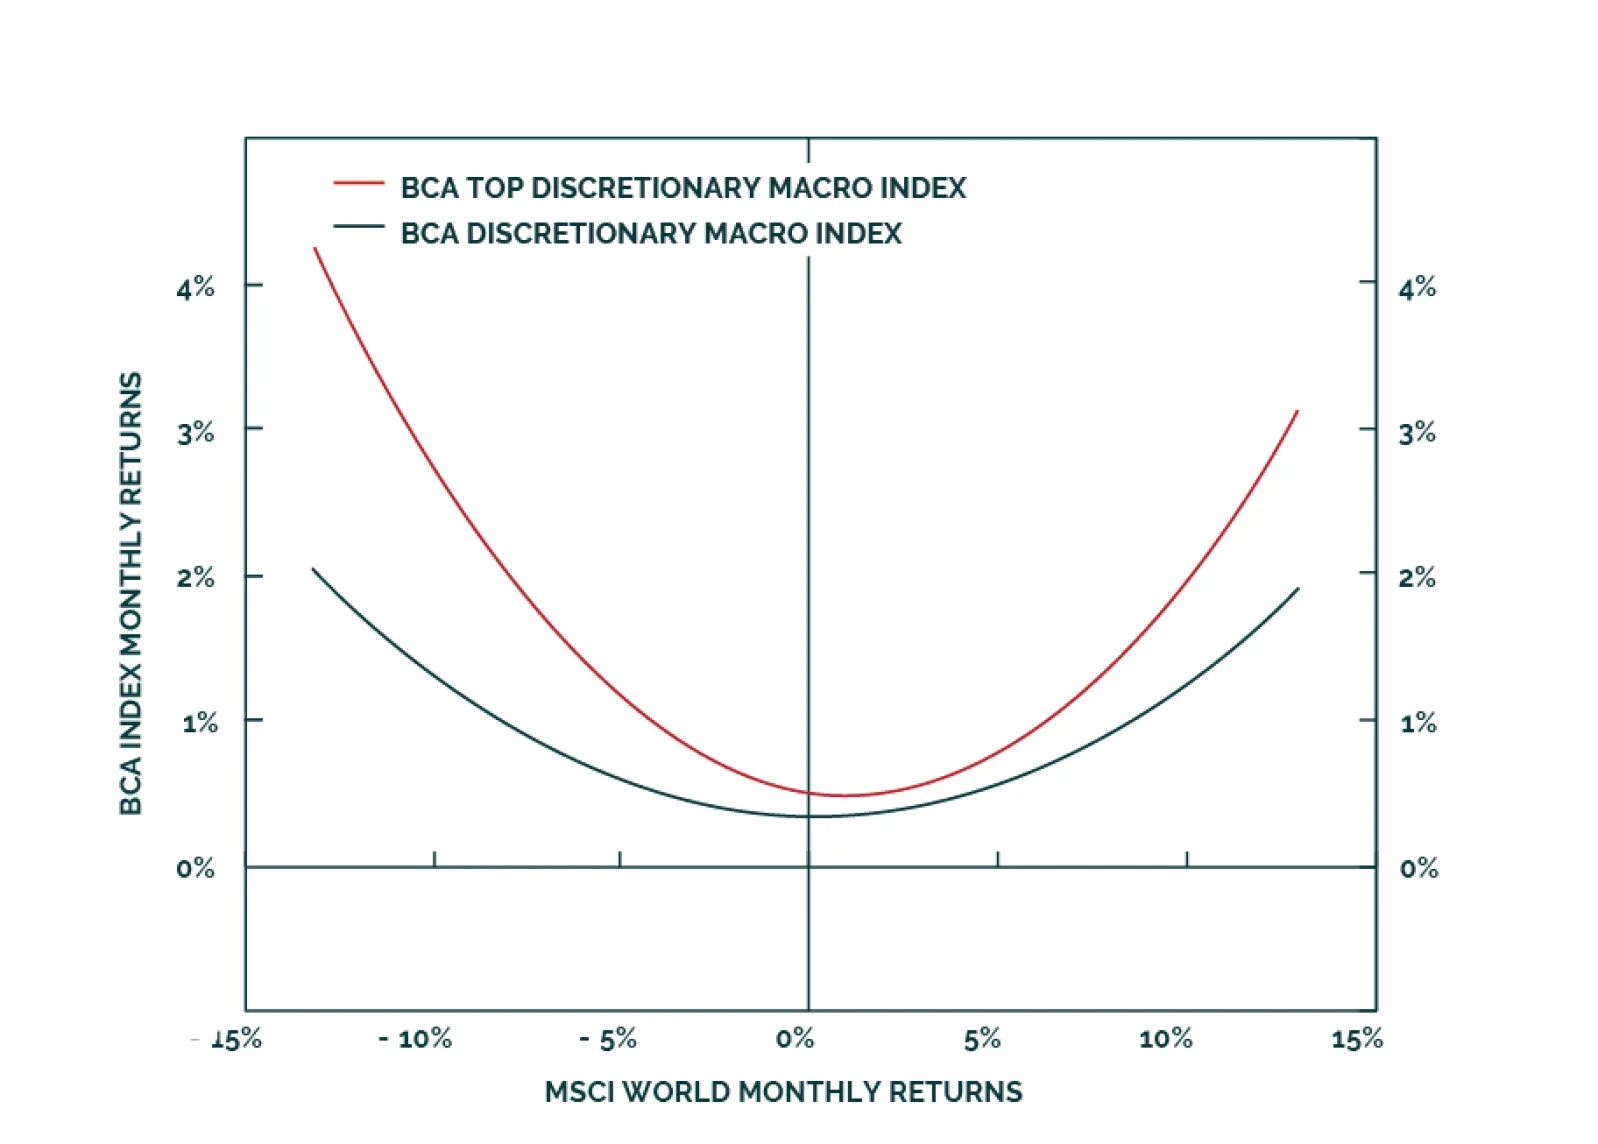
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
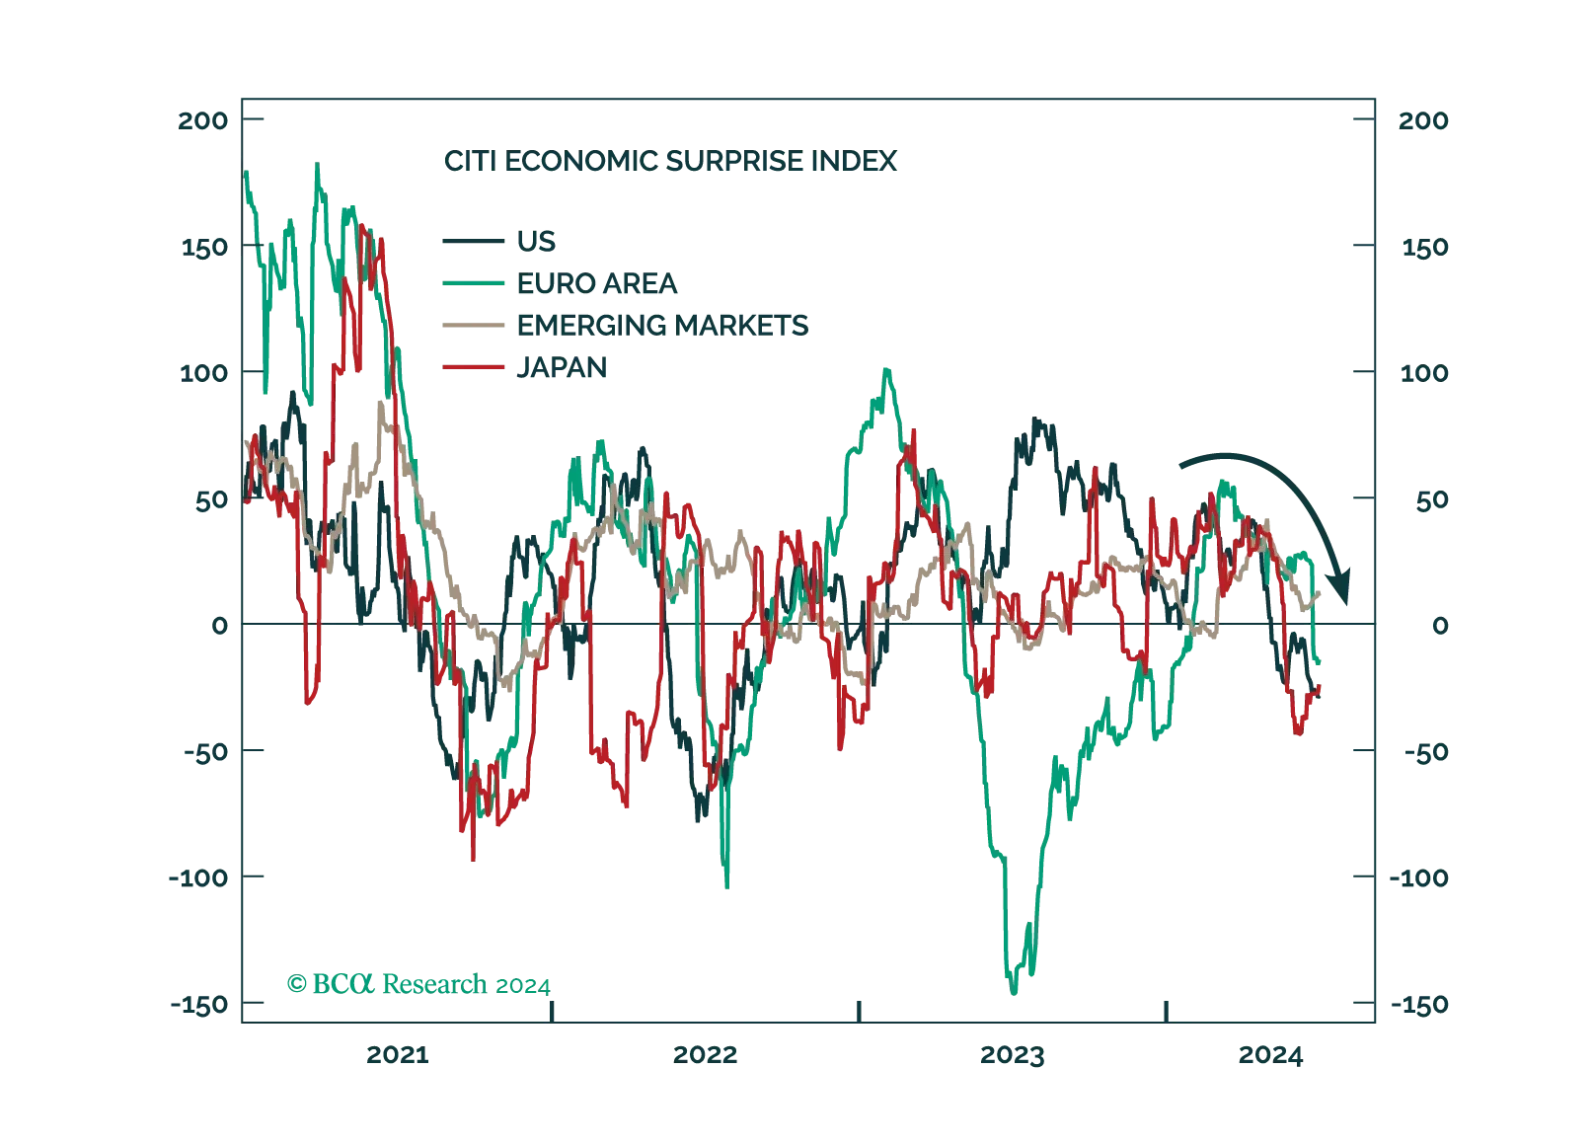
Concerns about the global economy have shifted from sticky inflation to faltering growth. Tight monetary policy is finally starting to bite. We suggest increasing portfolio defensiveness.