 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
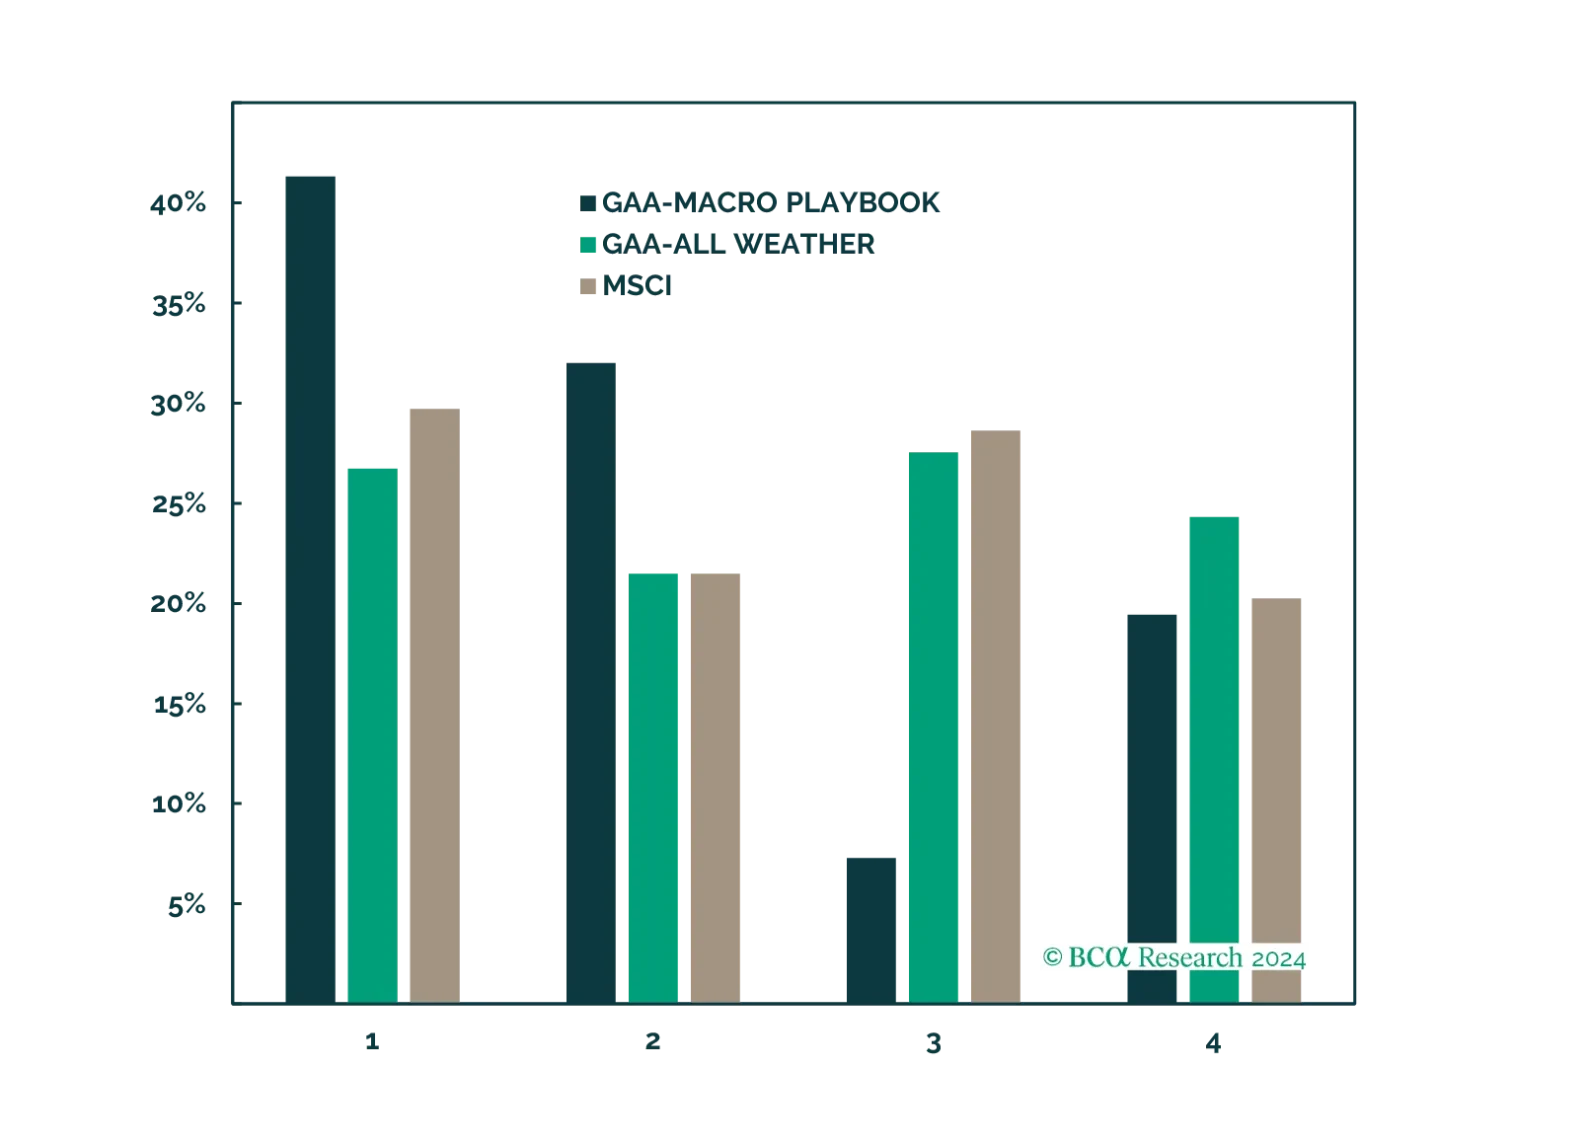
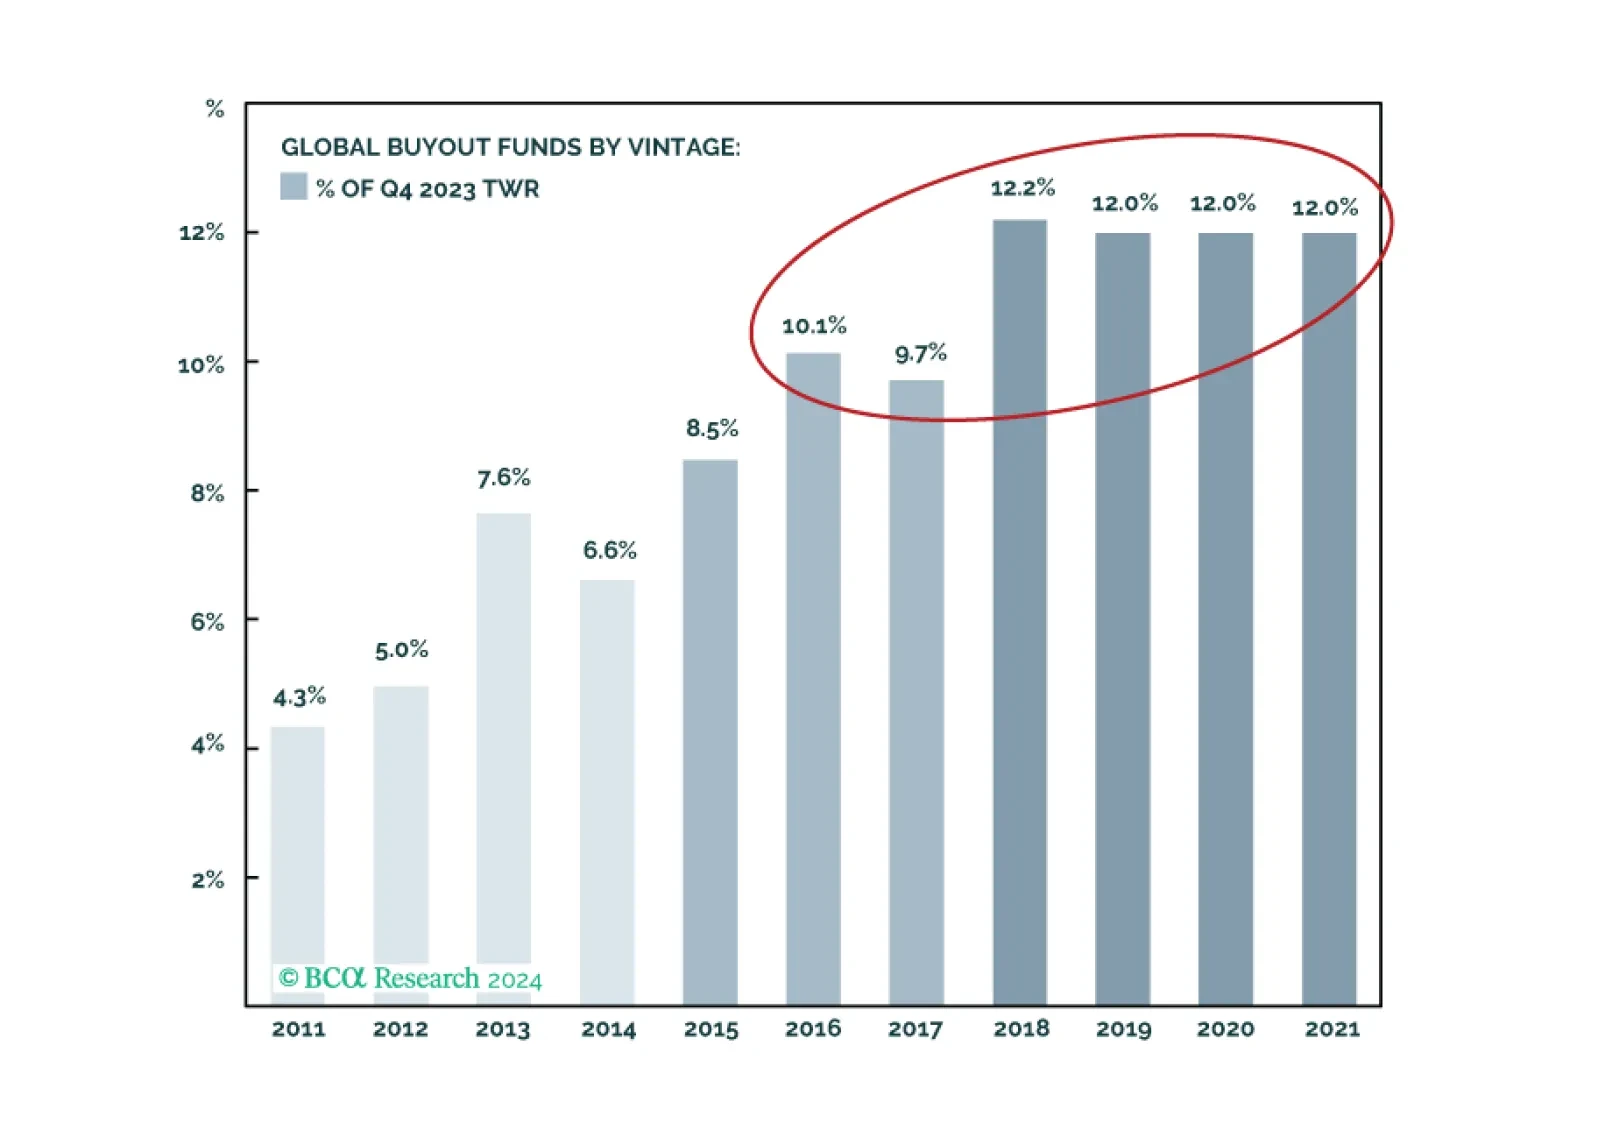
Unlike public markets, performance in private markets is complex and multifaceted. In this report we present multiple metrics across time and sources, offering investors a comprehensive range of benchmarks to assess their relative performance. Differences across sources will surprise.
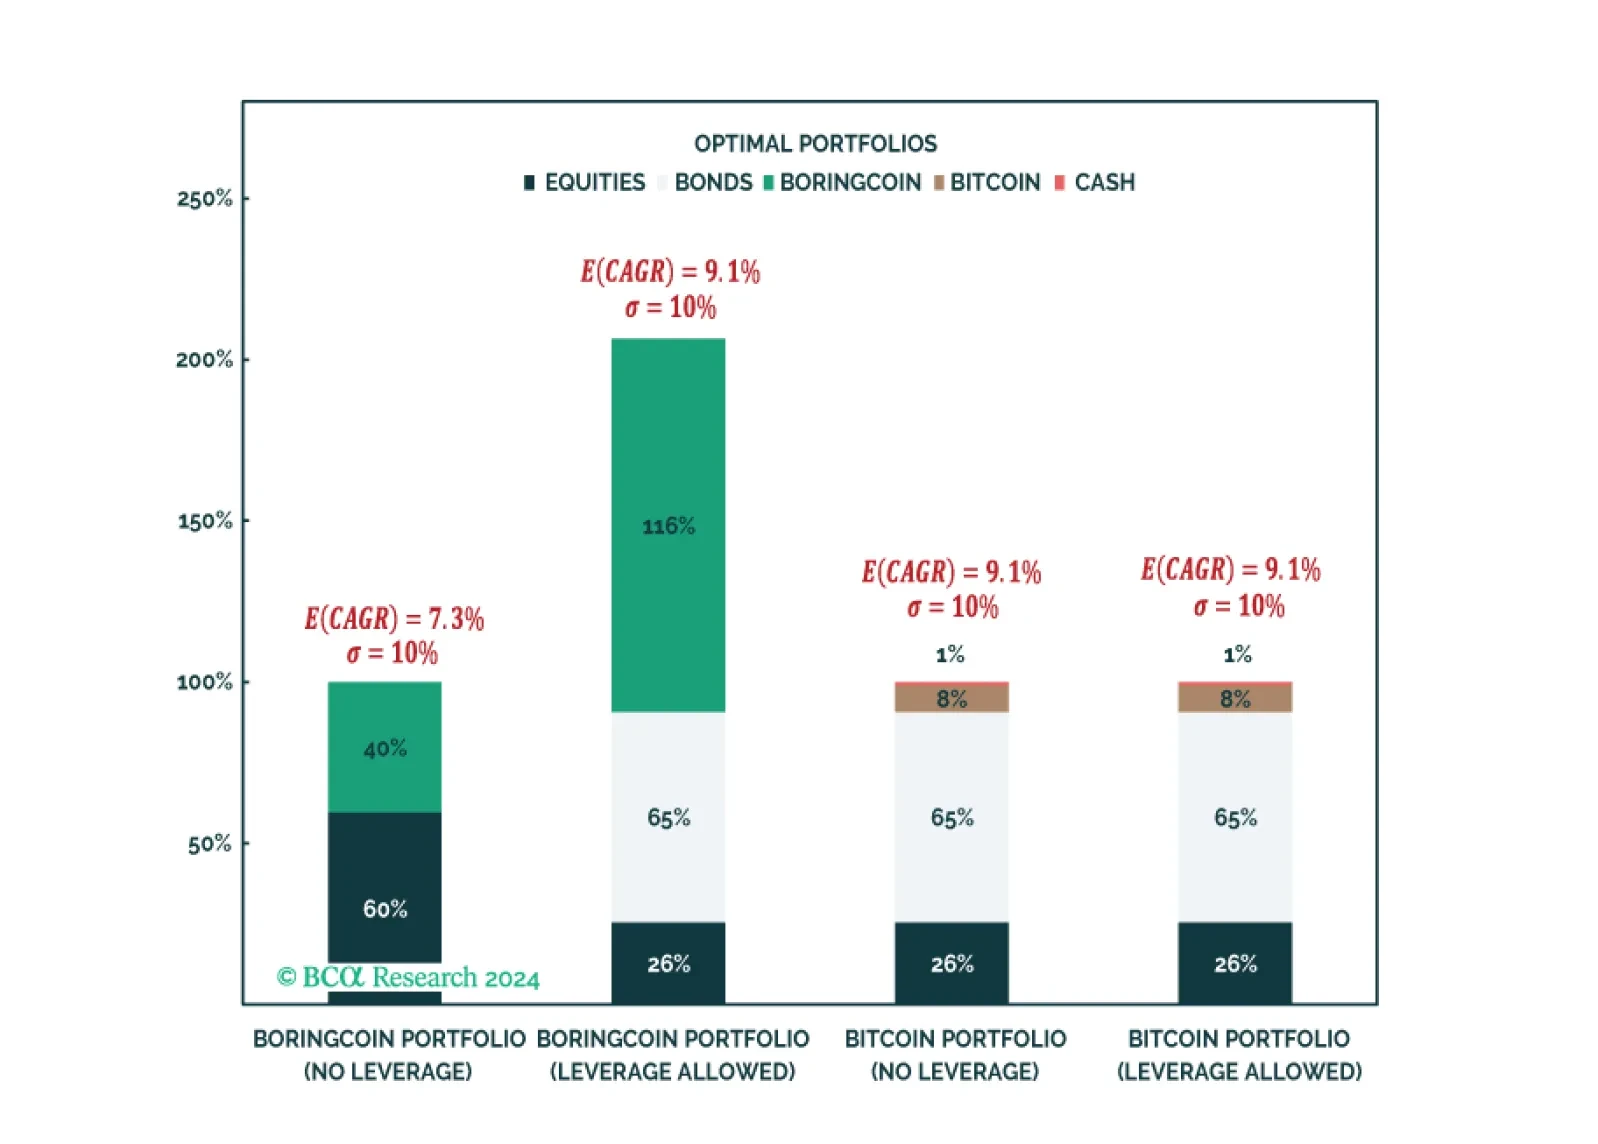
Conservative investors usually shy away from very volatile assets. But is this the right approach? By comparing Bitcoin with a hypothetical asset called “Boringcoin” we show that, all else being equal, high volatility assets are preferable as diversifiers due to better capital efficiency. Asset allocators should remember to think about their portfolio holistically and avoid looking at assets in isolation, particularly when they are very volatile.
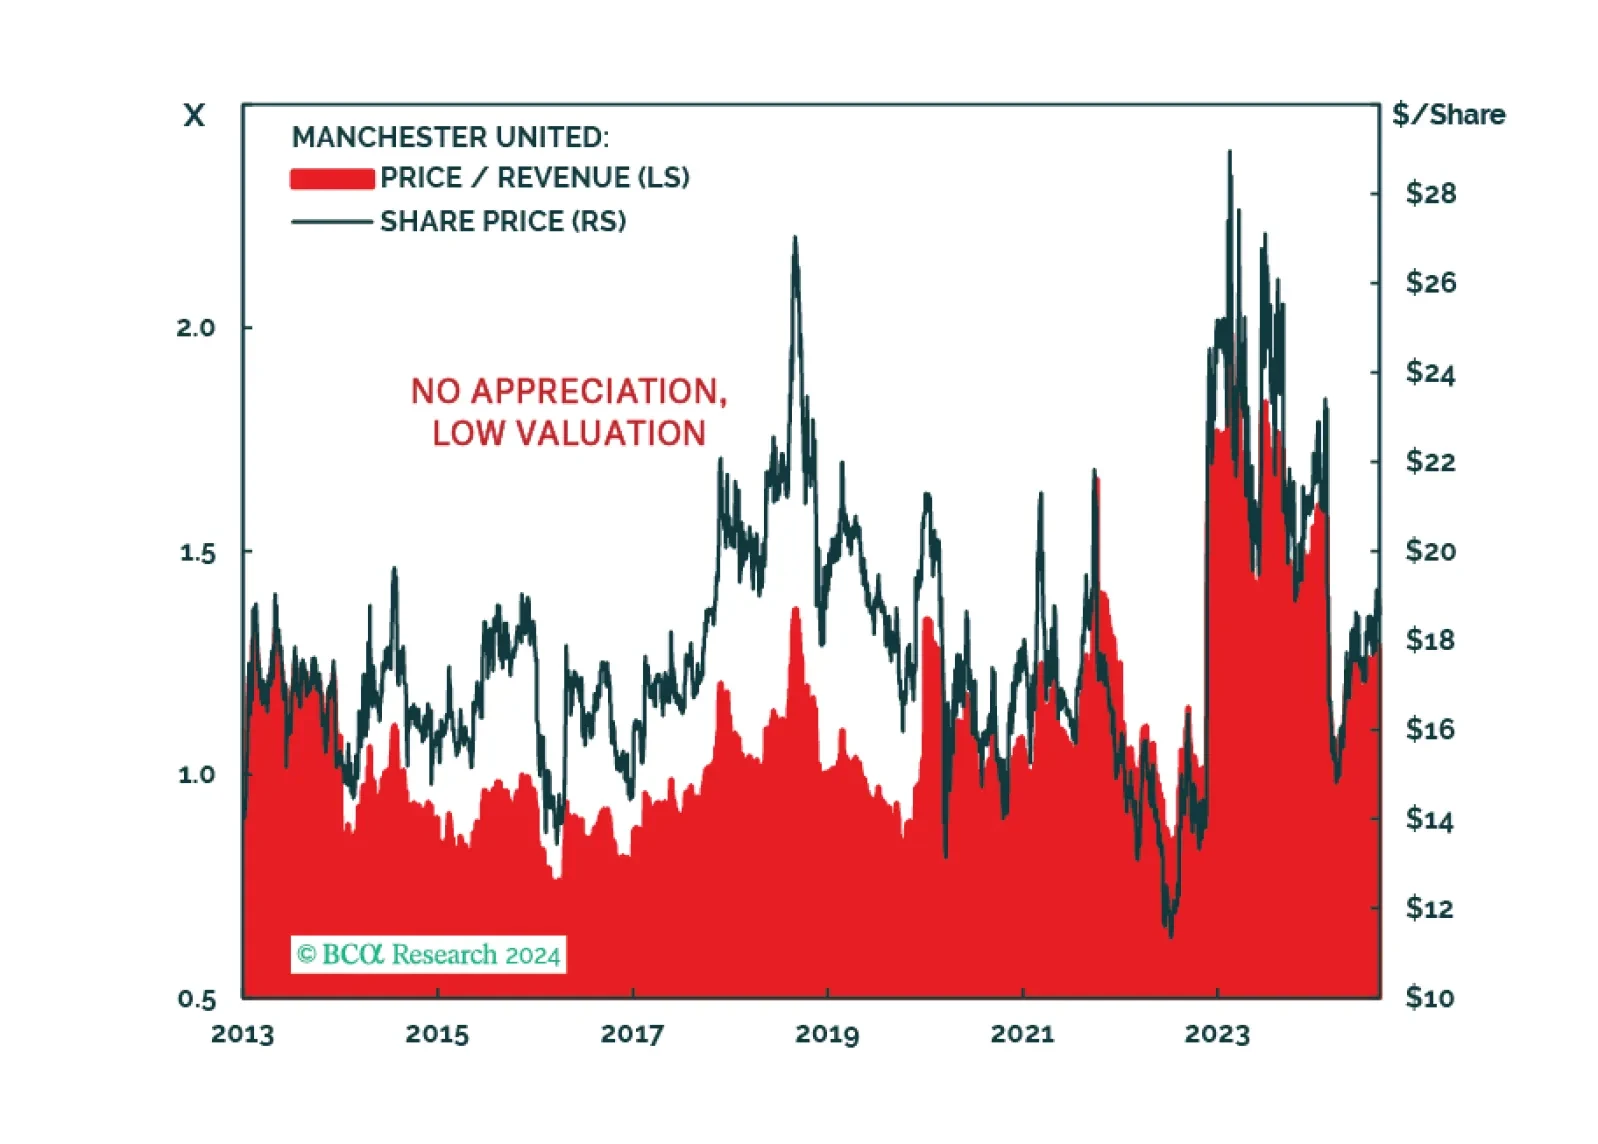
The NFL is opening the gates to the barbarians. No majority ownership is allowed...yet. However, that will not limit the upside in Growth Equity investments. Investors should cheer, so should fans.
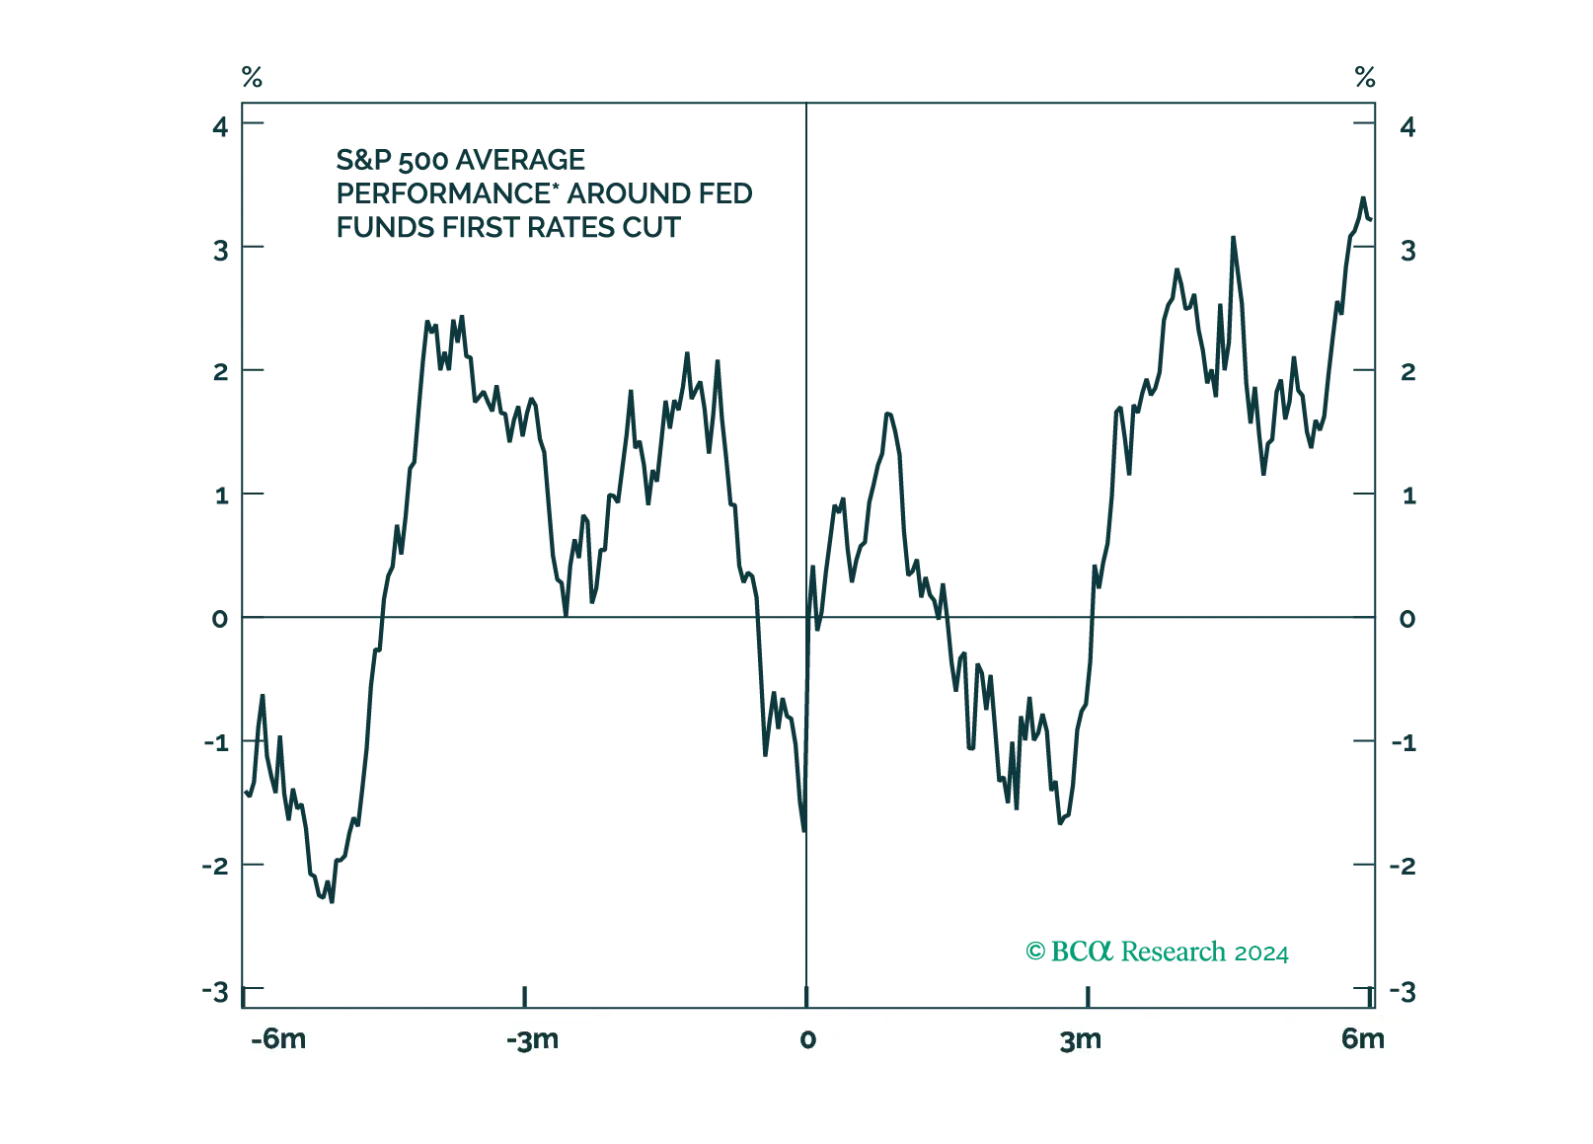
Even after the Fed cuts rates, policy will remain restrictive for some time. Moreover, in history, stocks have tended to fall around the first rate cut. We remain cautious on the outlook for the economy and risk assets.
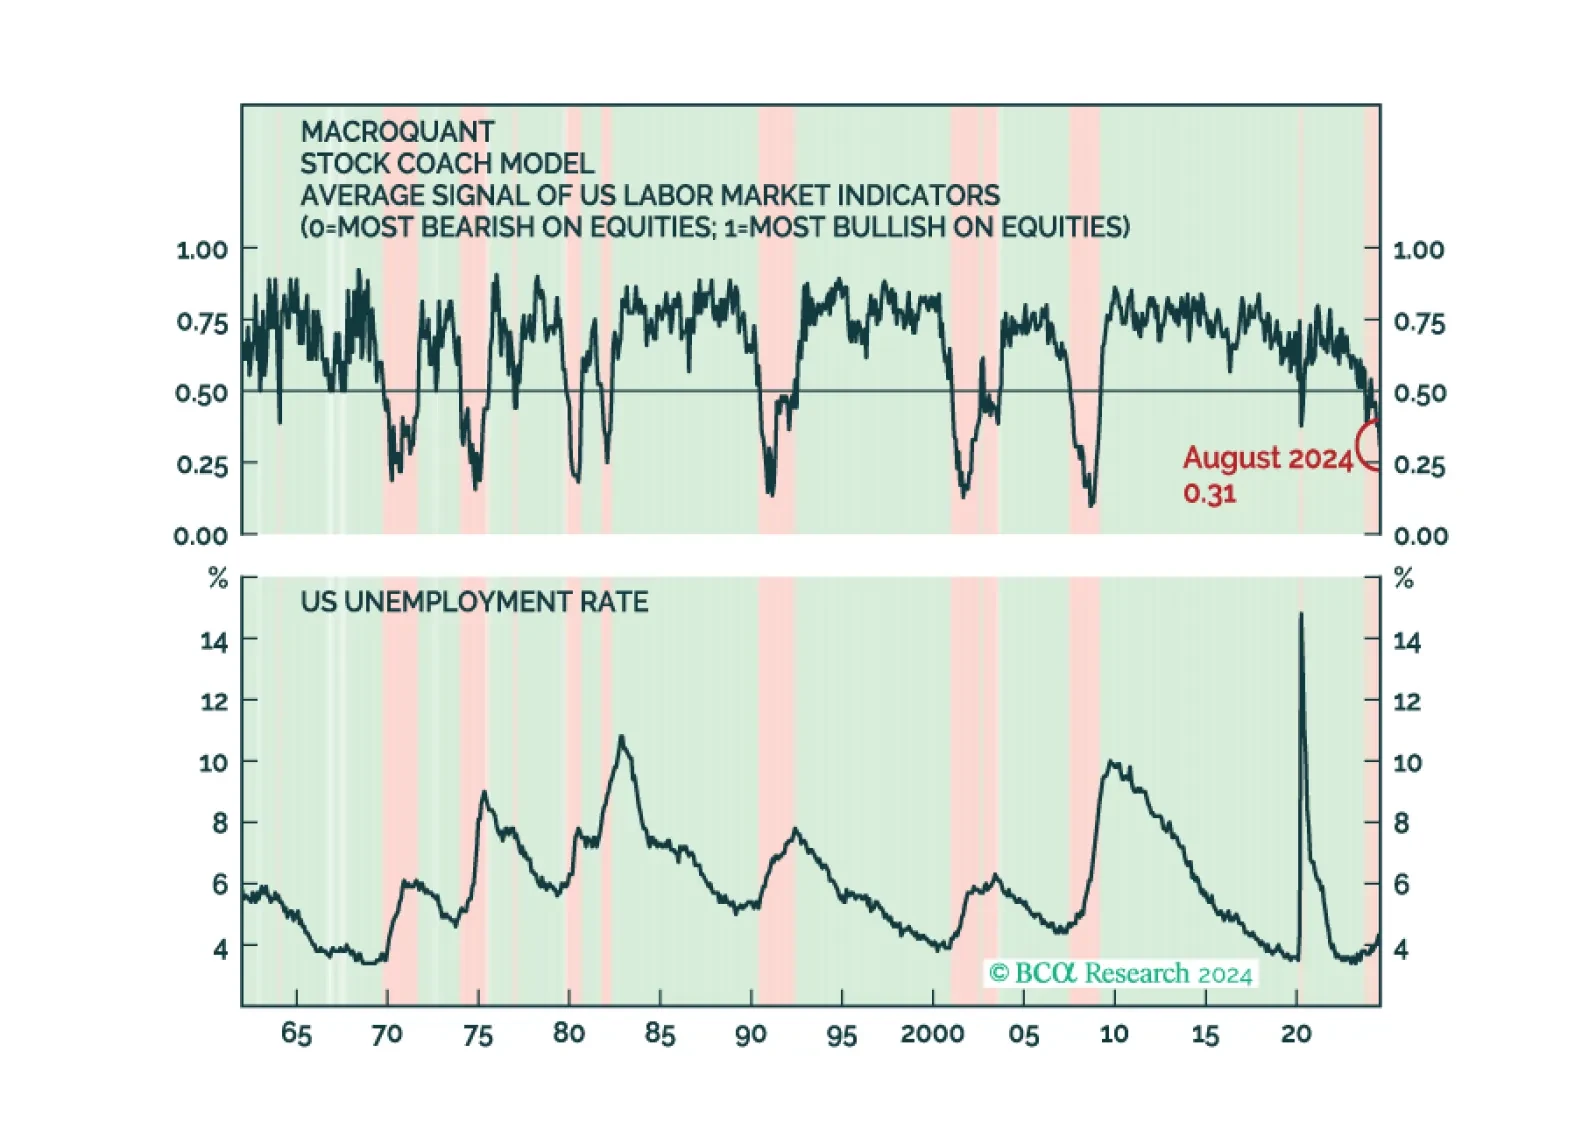
MacroQuant continues to recommend underweighting equities and overweighting bonds. This is consistent with the Global Investment Strategy Team's decision to downgrade global equities to underweight in late June.
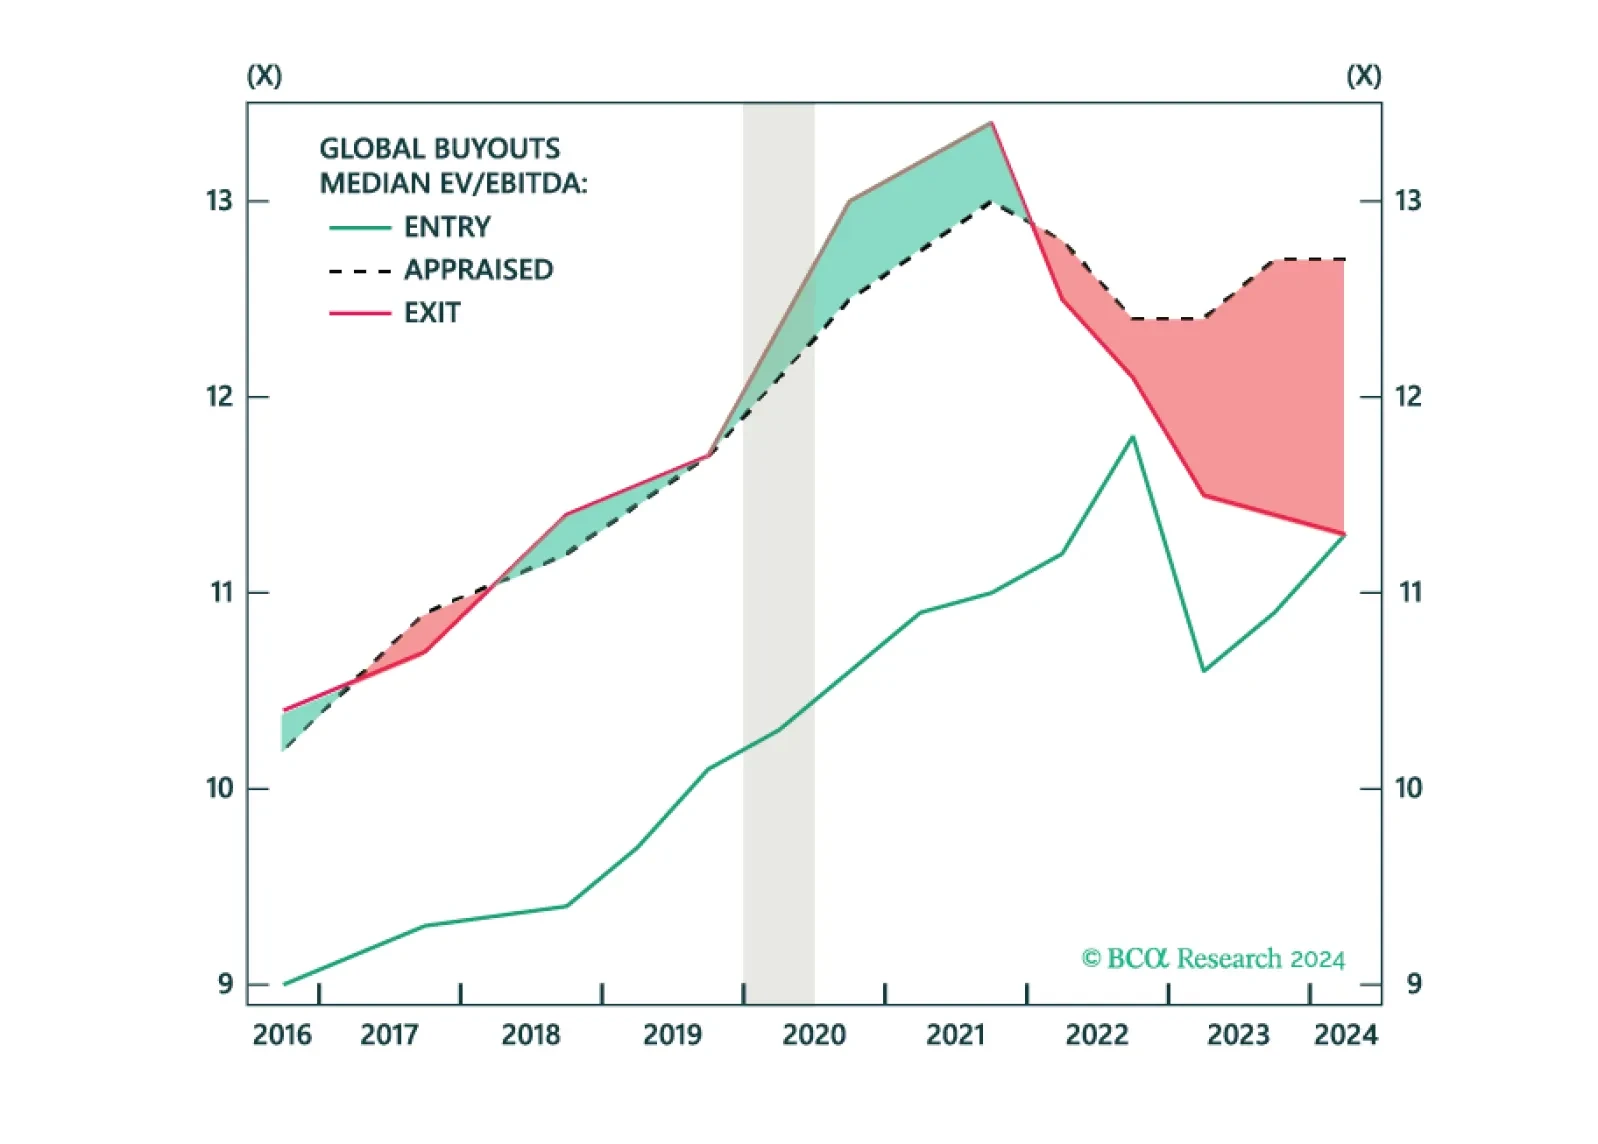
Private Equity Secondaries have grown but so have their opportunities. Near-term opportunities will be fertile while underlying trends will sustain the asset class in the long-term. Private Equity investors should be greedy.
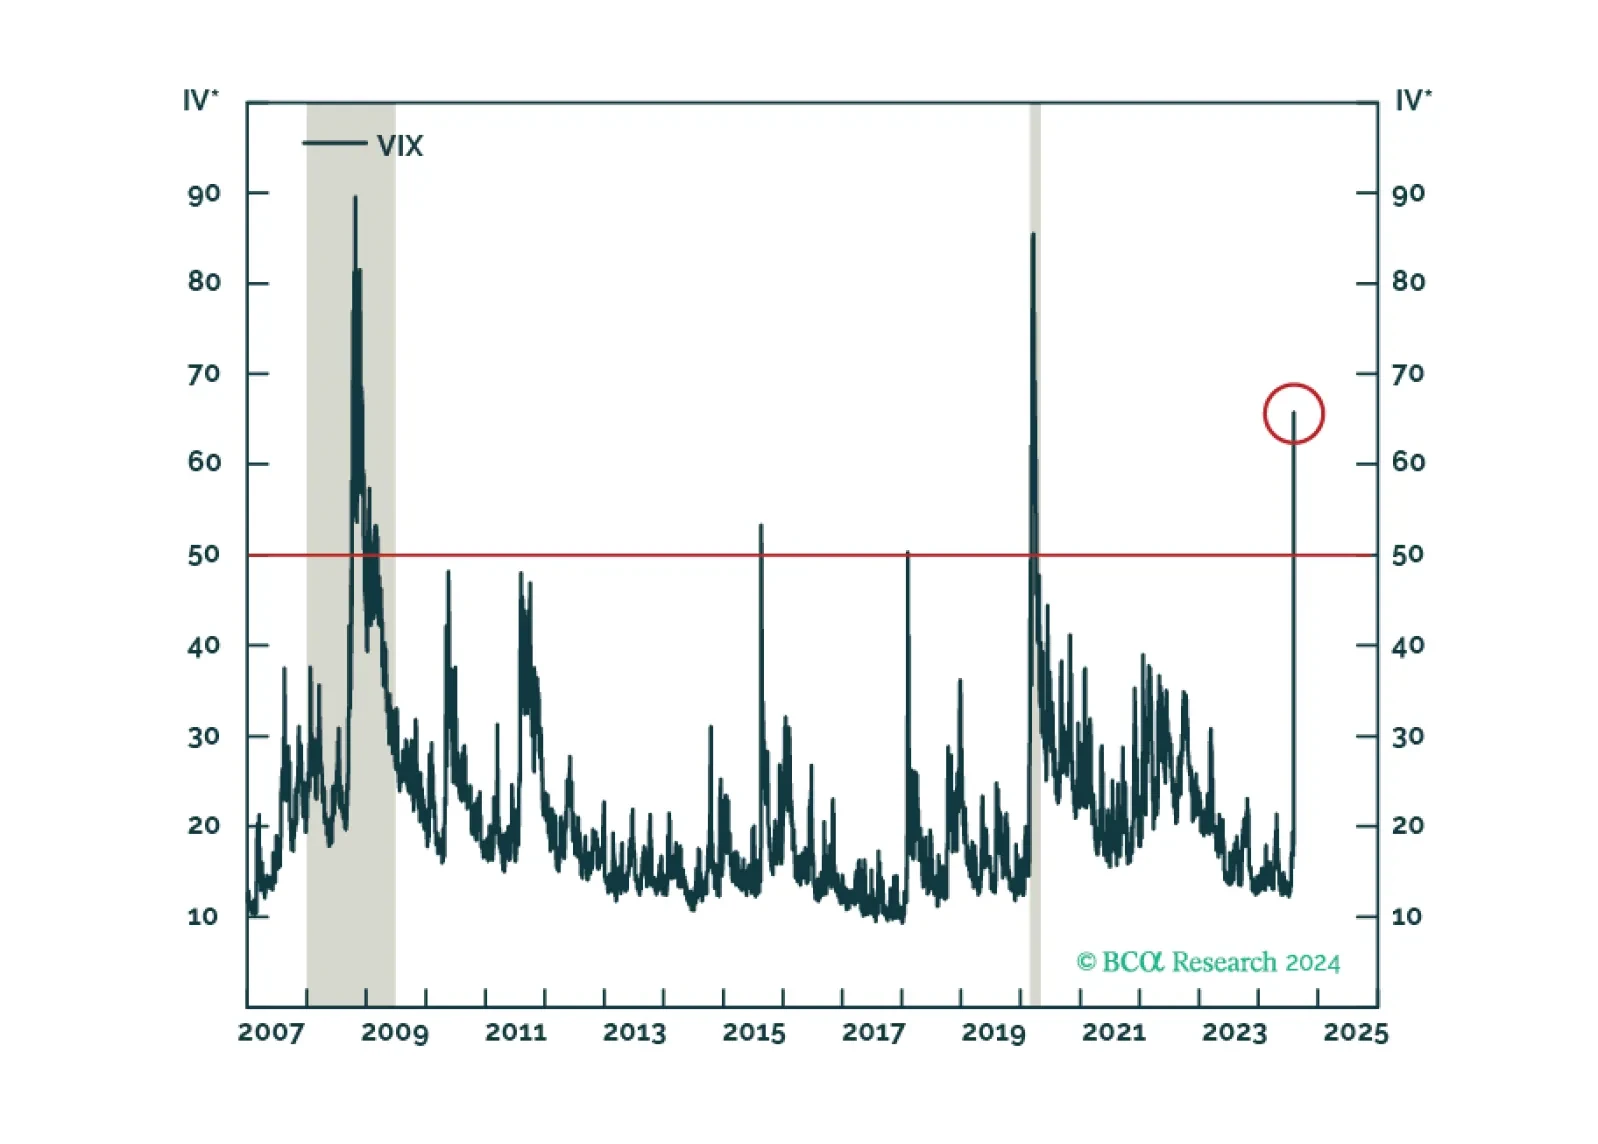
Market volatility has surged. Investors should no longer be allocating into Tail Risk structures. For those invested, start monetizing gains and let CTAs and Developed Market Fixed Income take the wheel from here.