 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
After the election, investors have begun to price in a repeat of the first Trump presidency. The market is expecting Trump to enact a flurry of policies that will unleash a year of growth like 2017. But we believe the consensus is wrong. Investors are playing the man and not the macro. The economic outlook and the political situation today are the polar opposite to late 2016. We are fading the small cap rally and recommending above-benchmark duration. We also recommend a defensive stance.

Can Powell achieve a soft landing? There are some indications he is doing it. We examine why our negative stance was wrong and analyze the four growth engines that kept recession at bay. Half of these forces remain while the other half have run out of juice. While this might be enough to keep the economy going, we maintain our defensive positioning. Equities have priced a very benign outcome. Meanwhile, rising rates in anticipation of a Trump win are pushing the economy away from the soft-landing path. We hedge the possibility of further upside in yields in case Trump gets elected by downgrading duration to neutral.
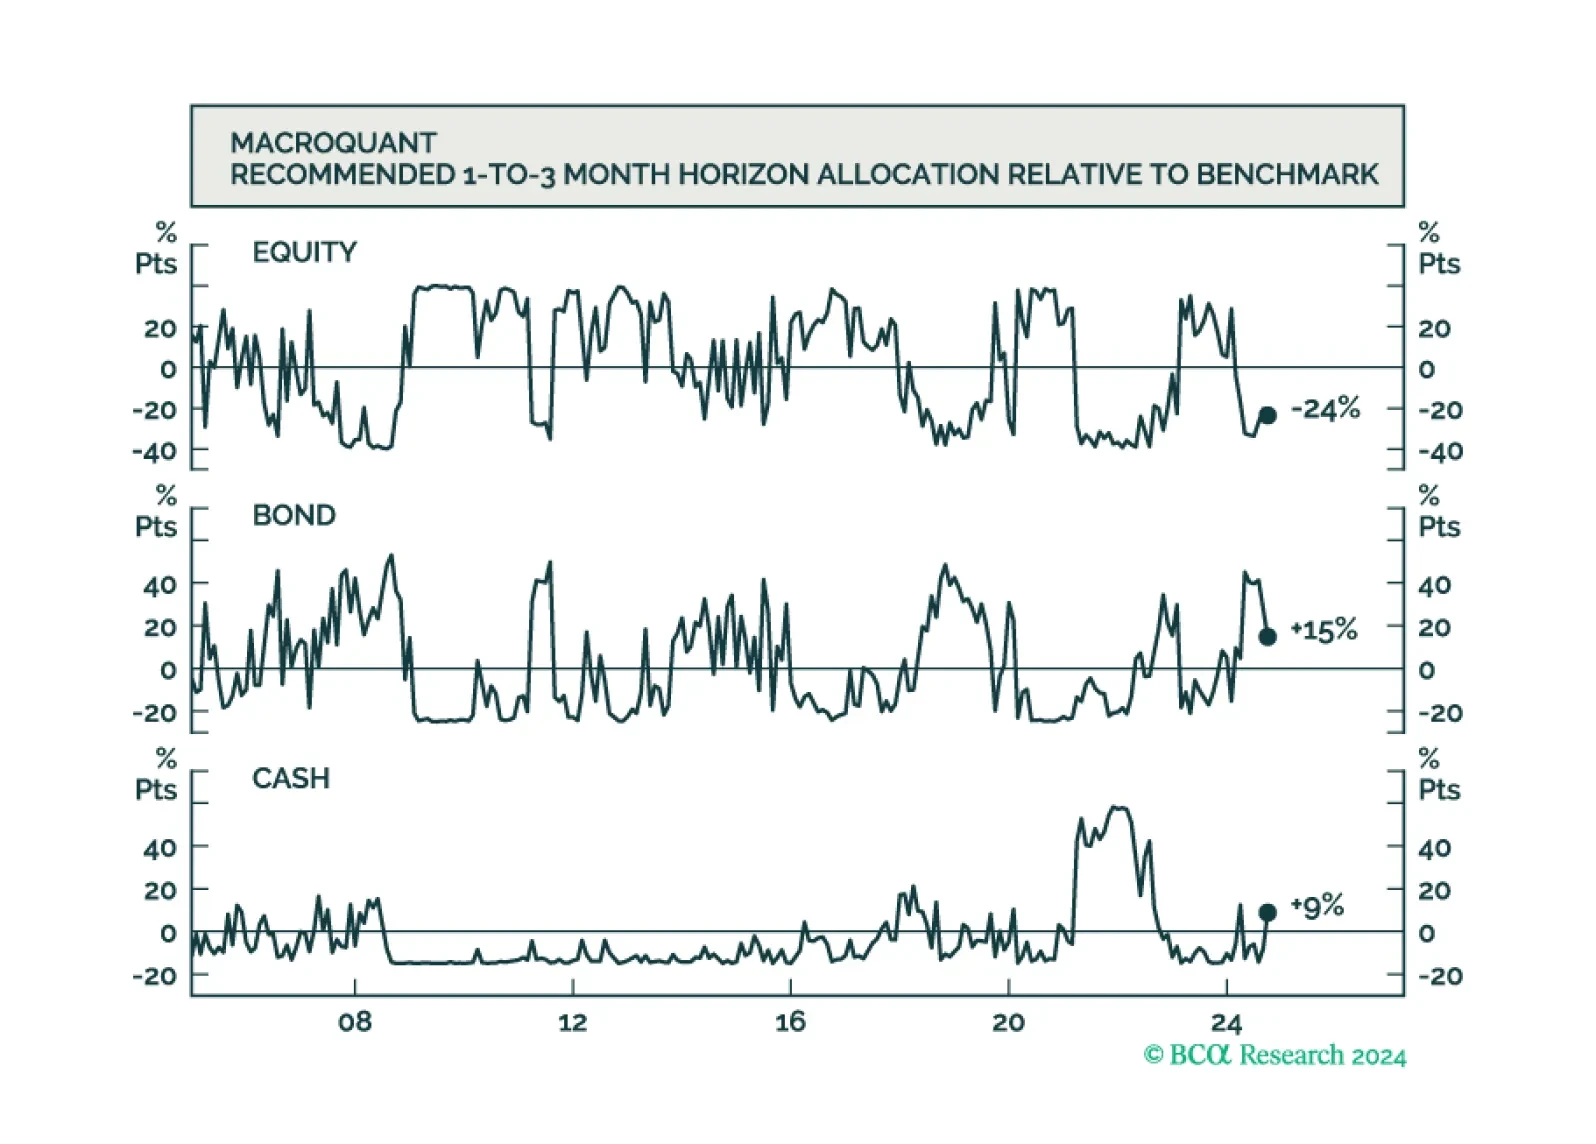
MacroQuant expects global equities to weaken in November. As such, the model recommends underweighting equities and overweighting bonds and cash.
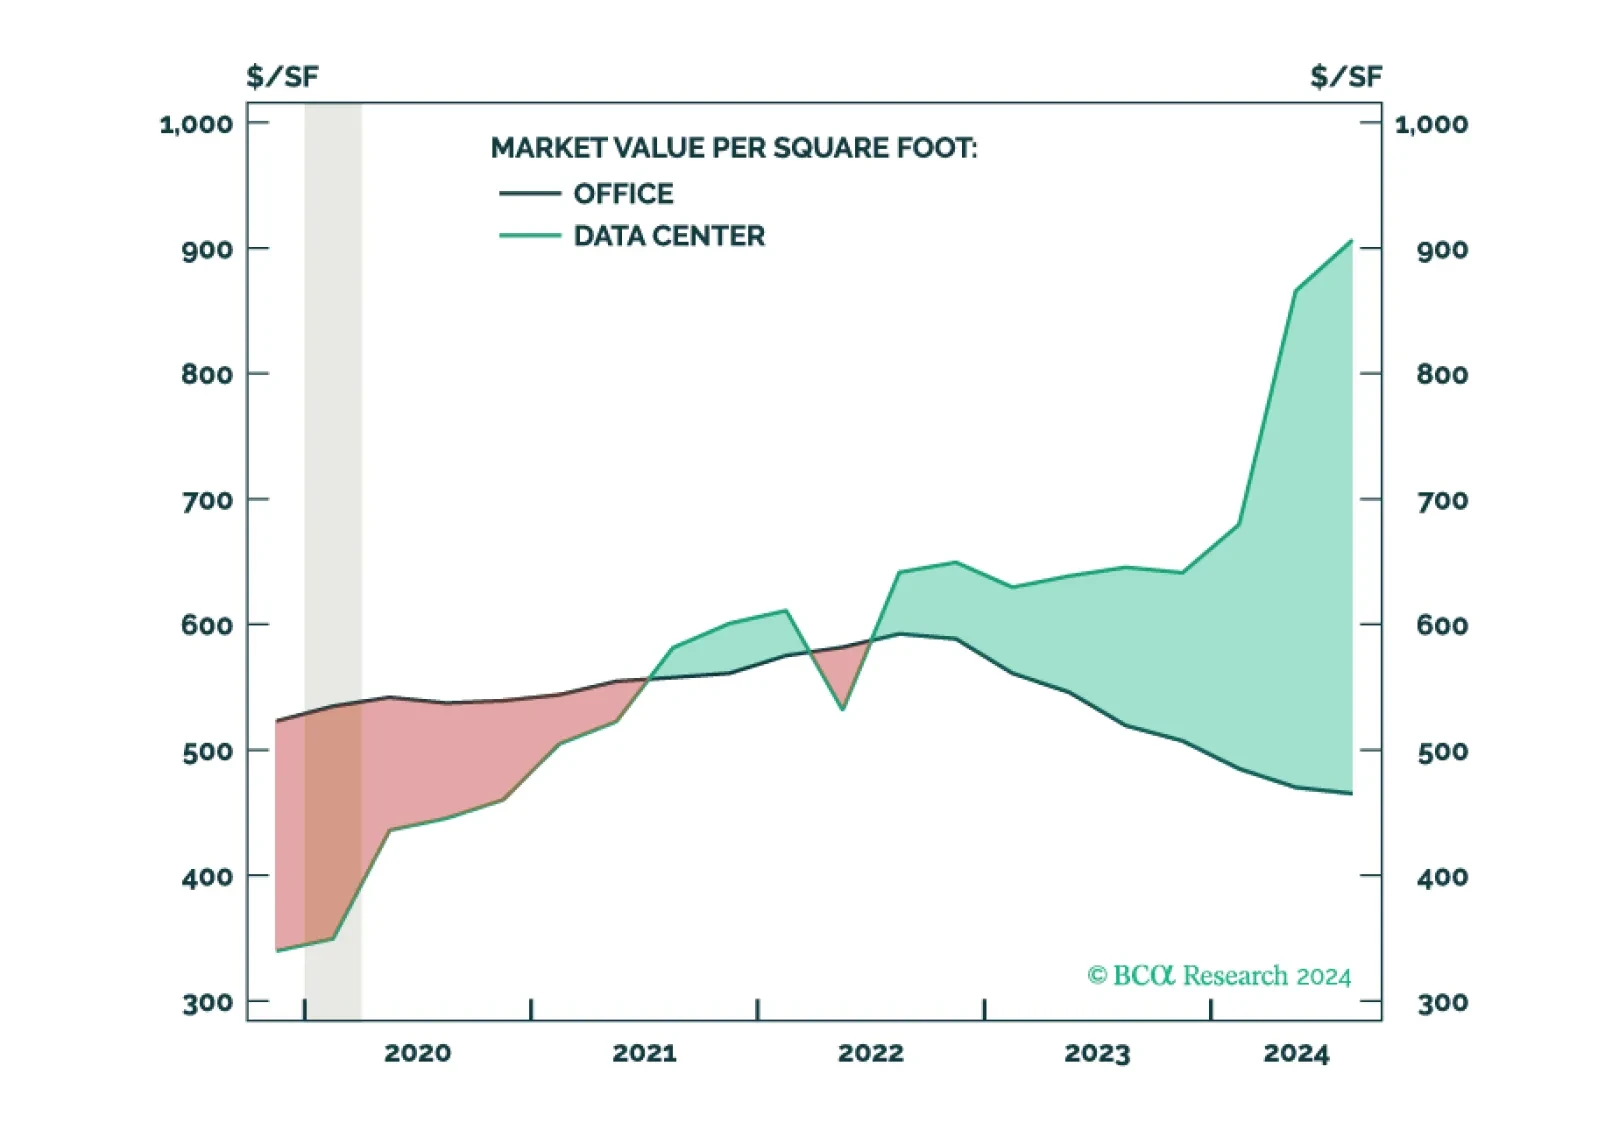
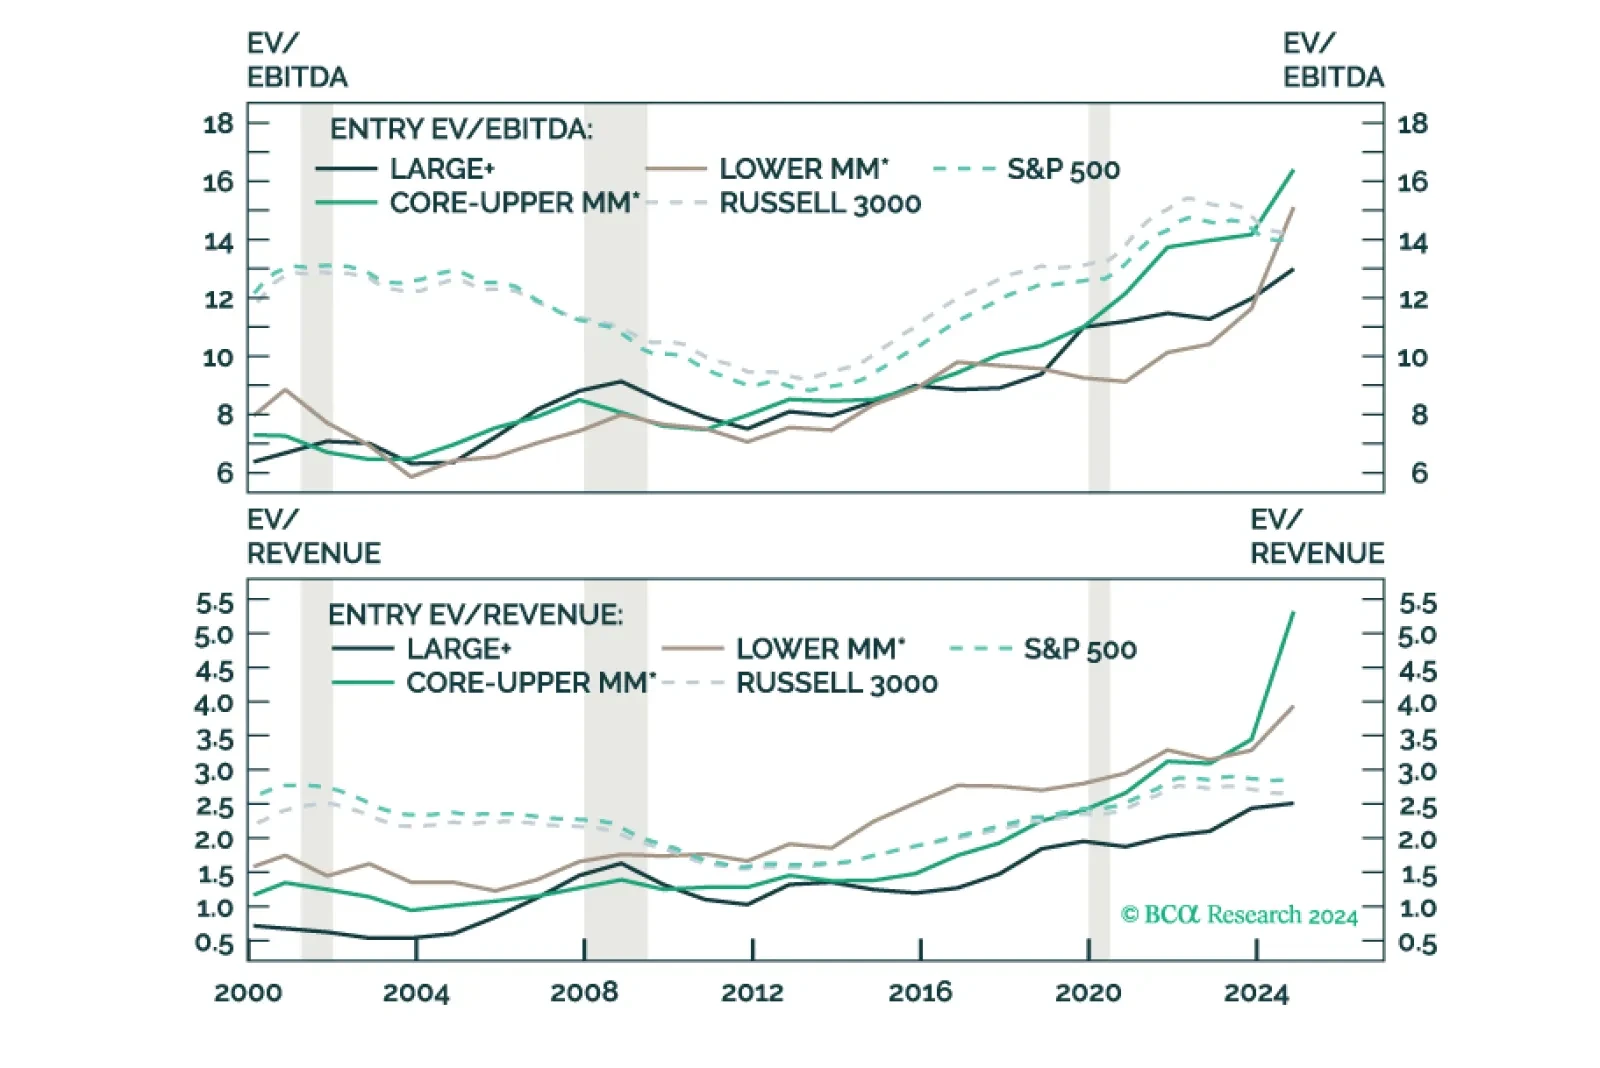
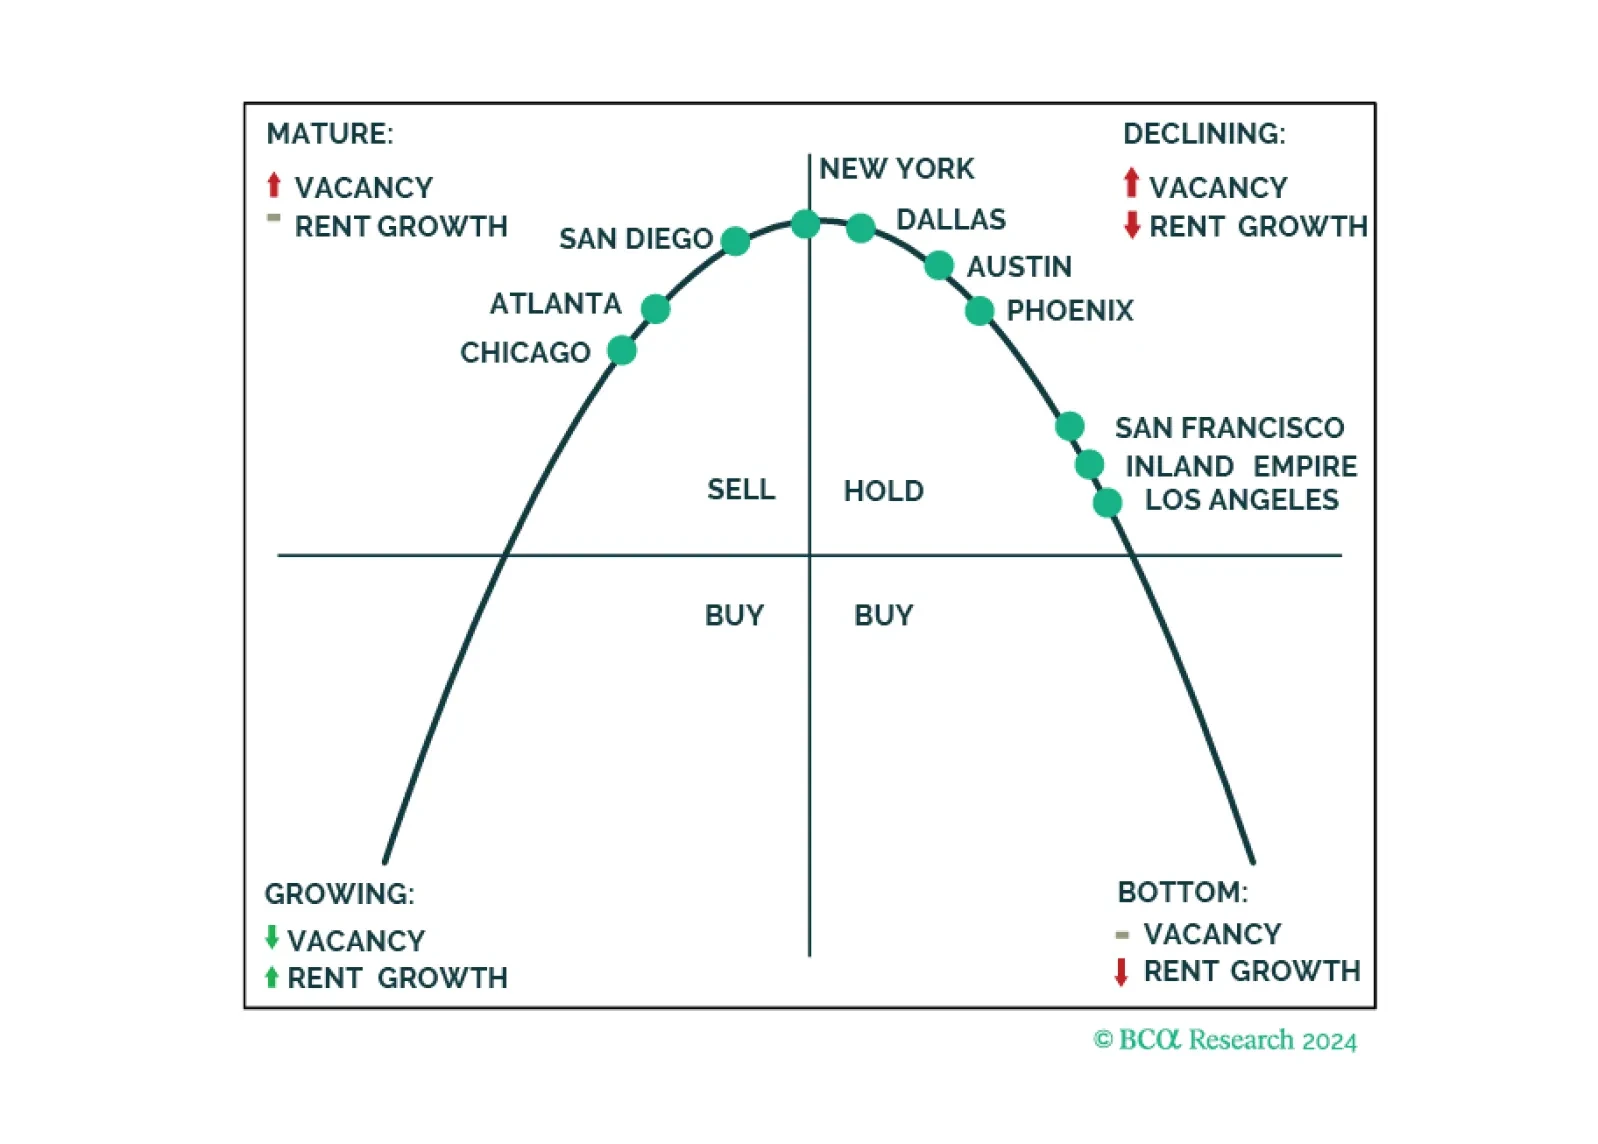
We prefer Non-Core Infrastructure and Venture Capital over Buyouts and Multi-Strategy Hedge Funds. We are now overweight Core/+ Real Estate. Investors need to recheck the bank regulation tailwind for their long-term assumptions on Private Credit.
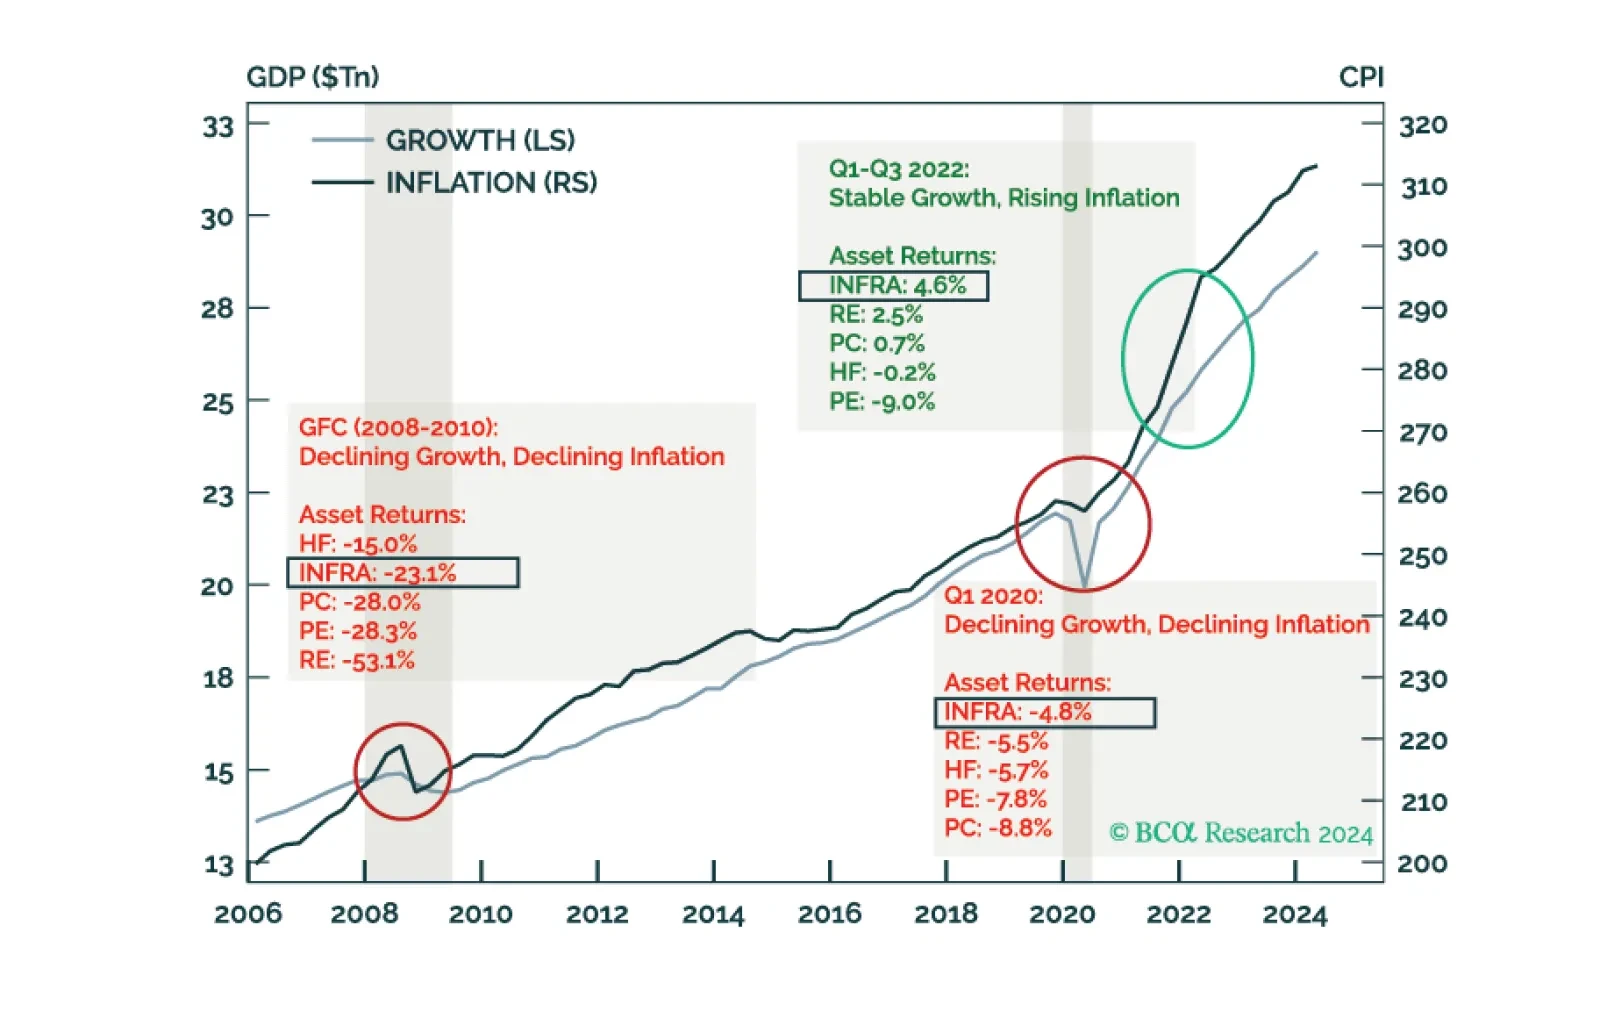
Institutional investing is not as straightforward as picking the fastest horse. Infrastructure’s attraction as an investment stems from its diversification, specifically its feature as an inflation-hedge, cash flow stability, and scalability. This Primer lays the groundwork for integrating Infrastructure into the PMA framework.
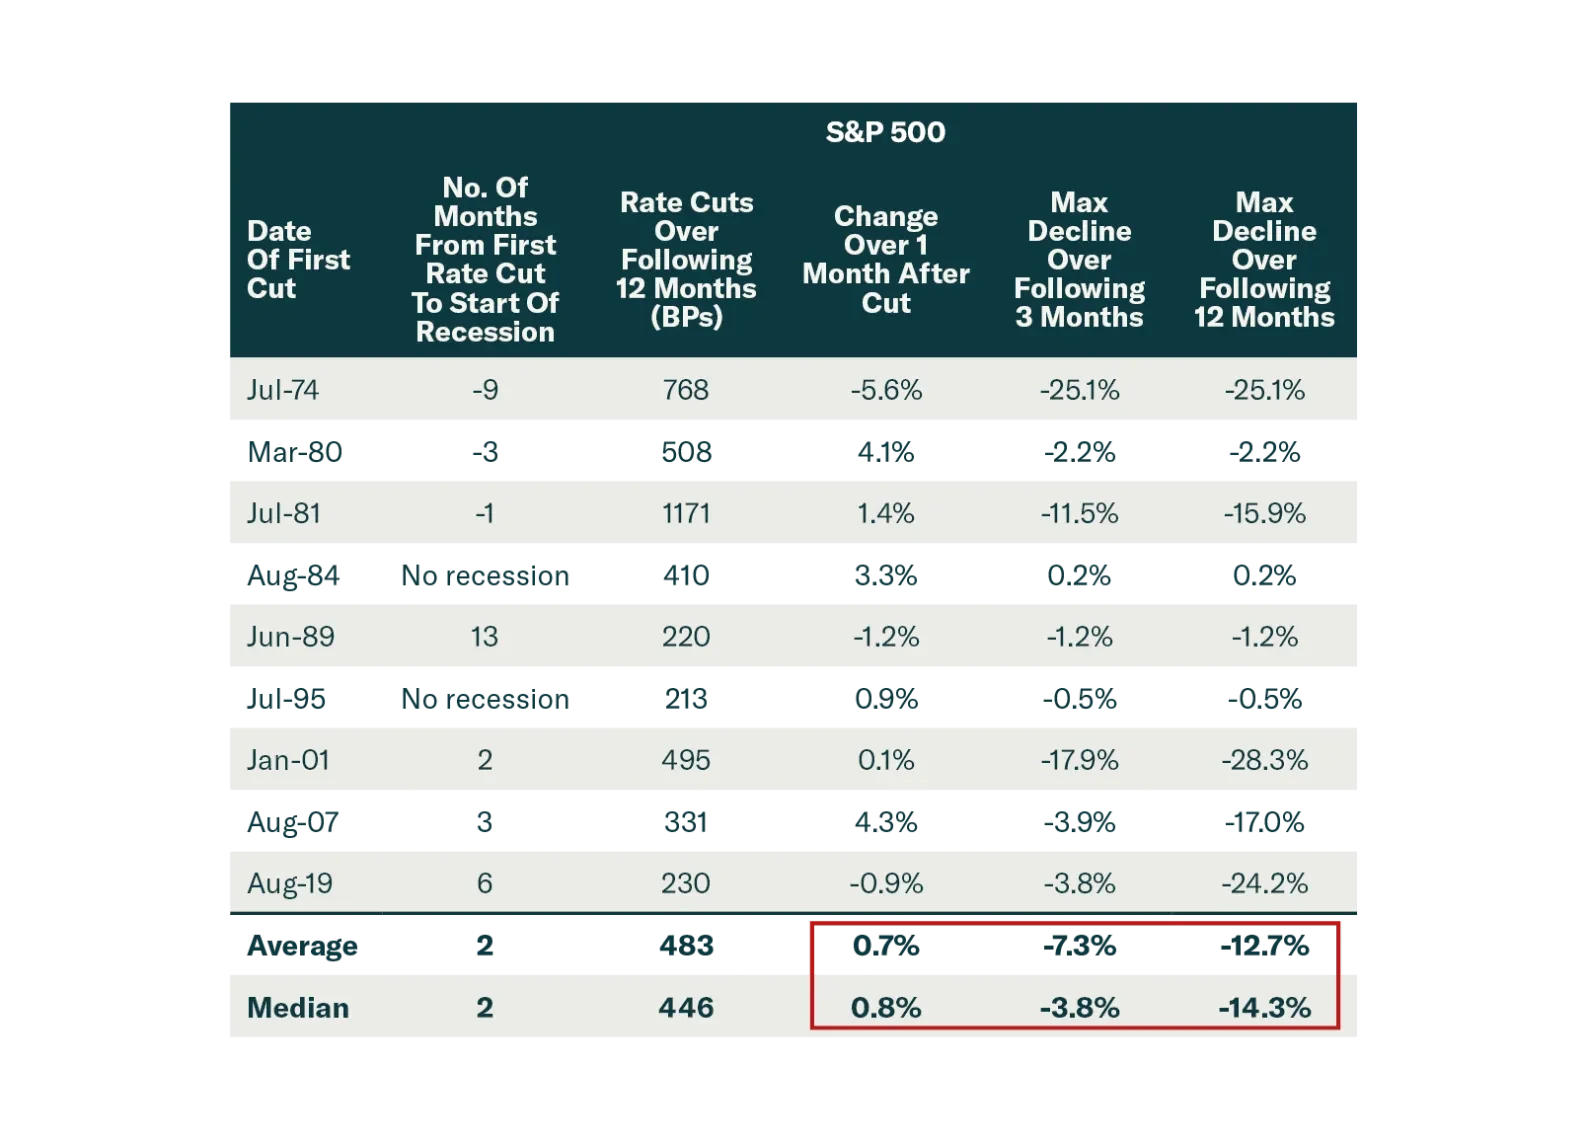
The market got excited by the 50 bps Fed cut and China stimulus. But these are a recognition that economies are slowing significantly. Stocks often rally after the first Fed cut, before falling sharply. Investors should stay defensive.
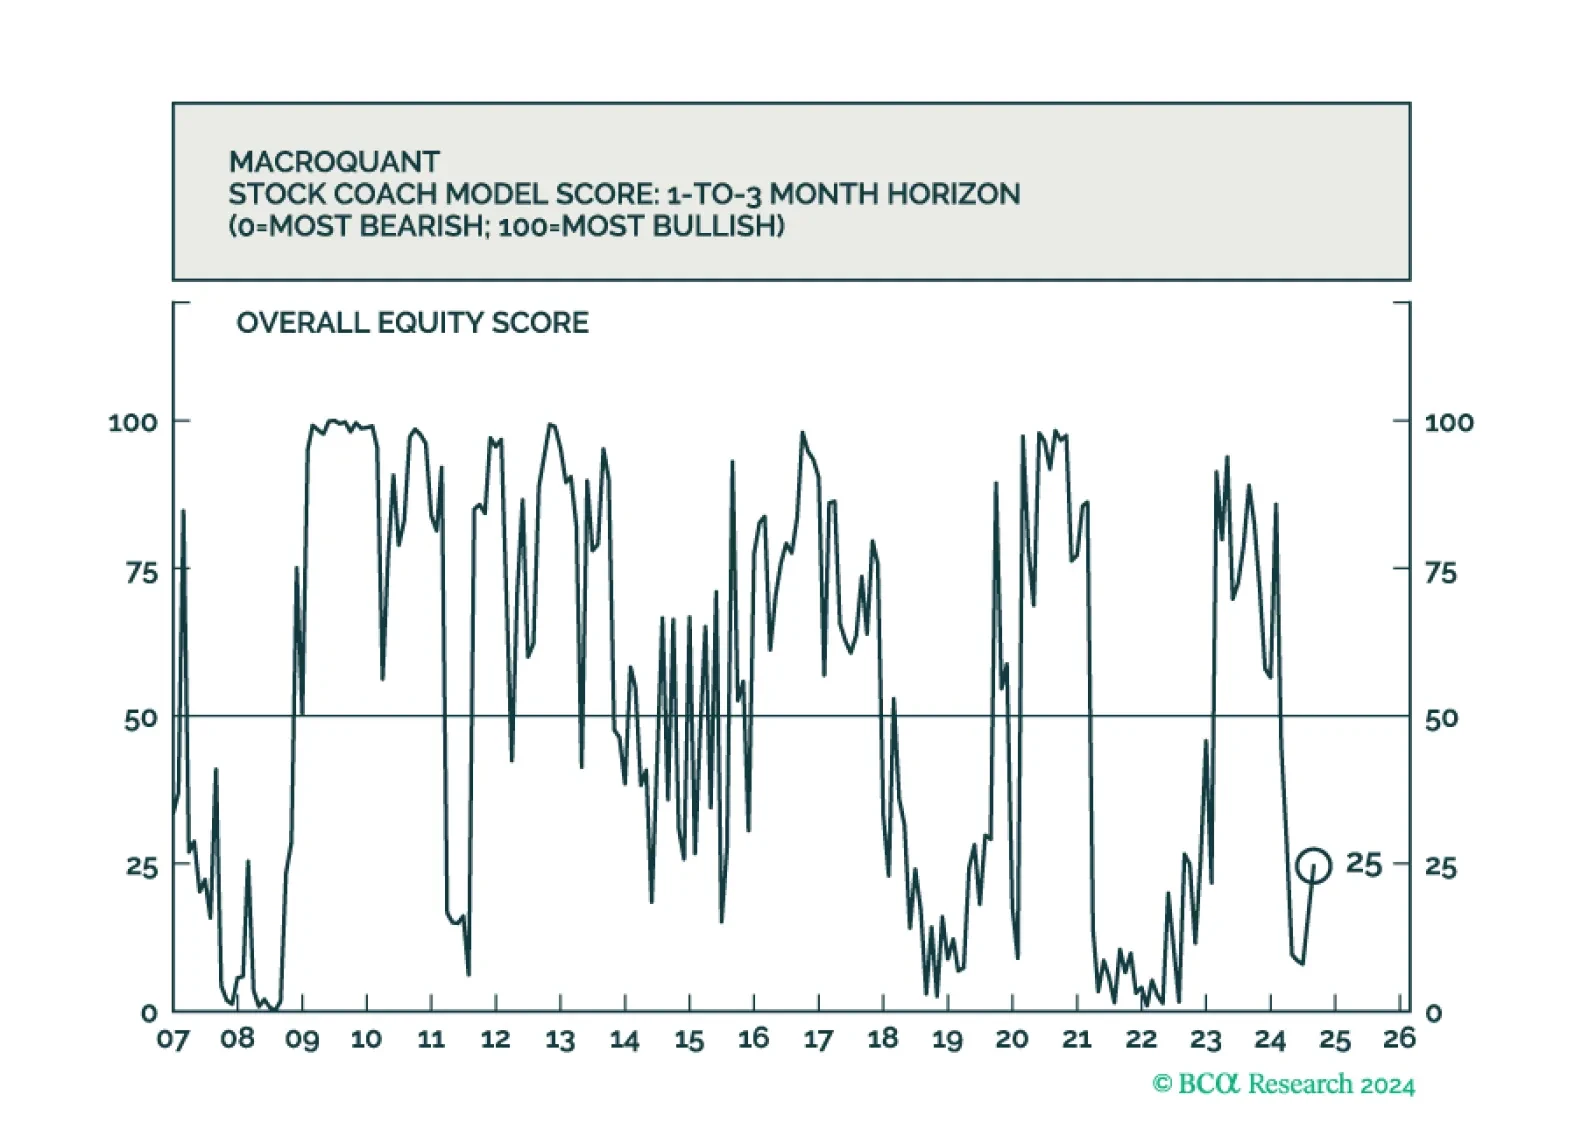
Despite the recent easing in financial conditions and hopes around Chinese stimulus, MacroQuant sees a heightened risk that the US will fall into a recession over the next 12 months. As such, it recommends an underweight to stocks, counterbalanced by an overweight to bonds.