 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
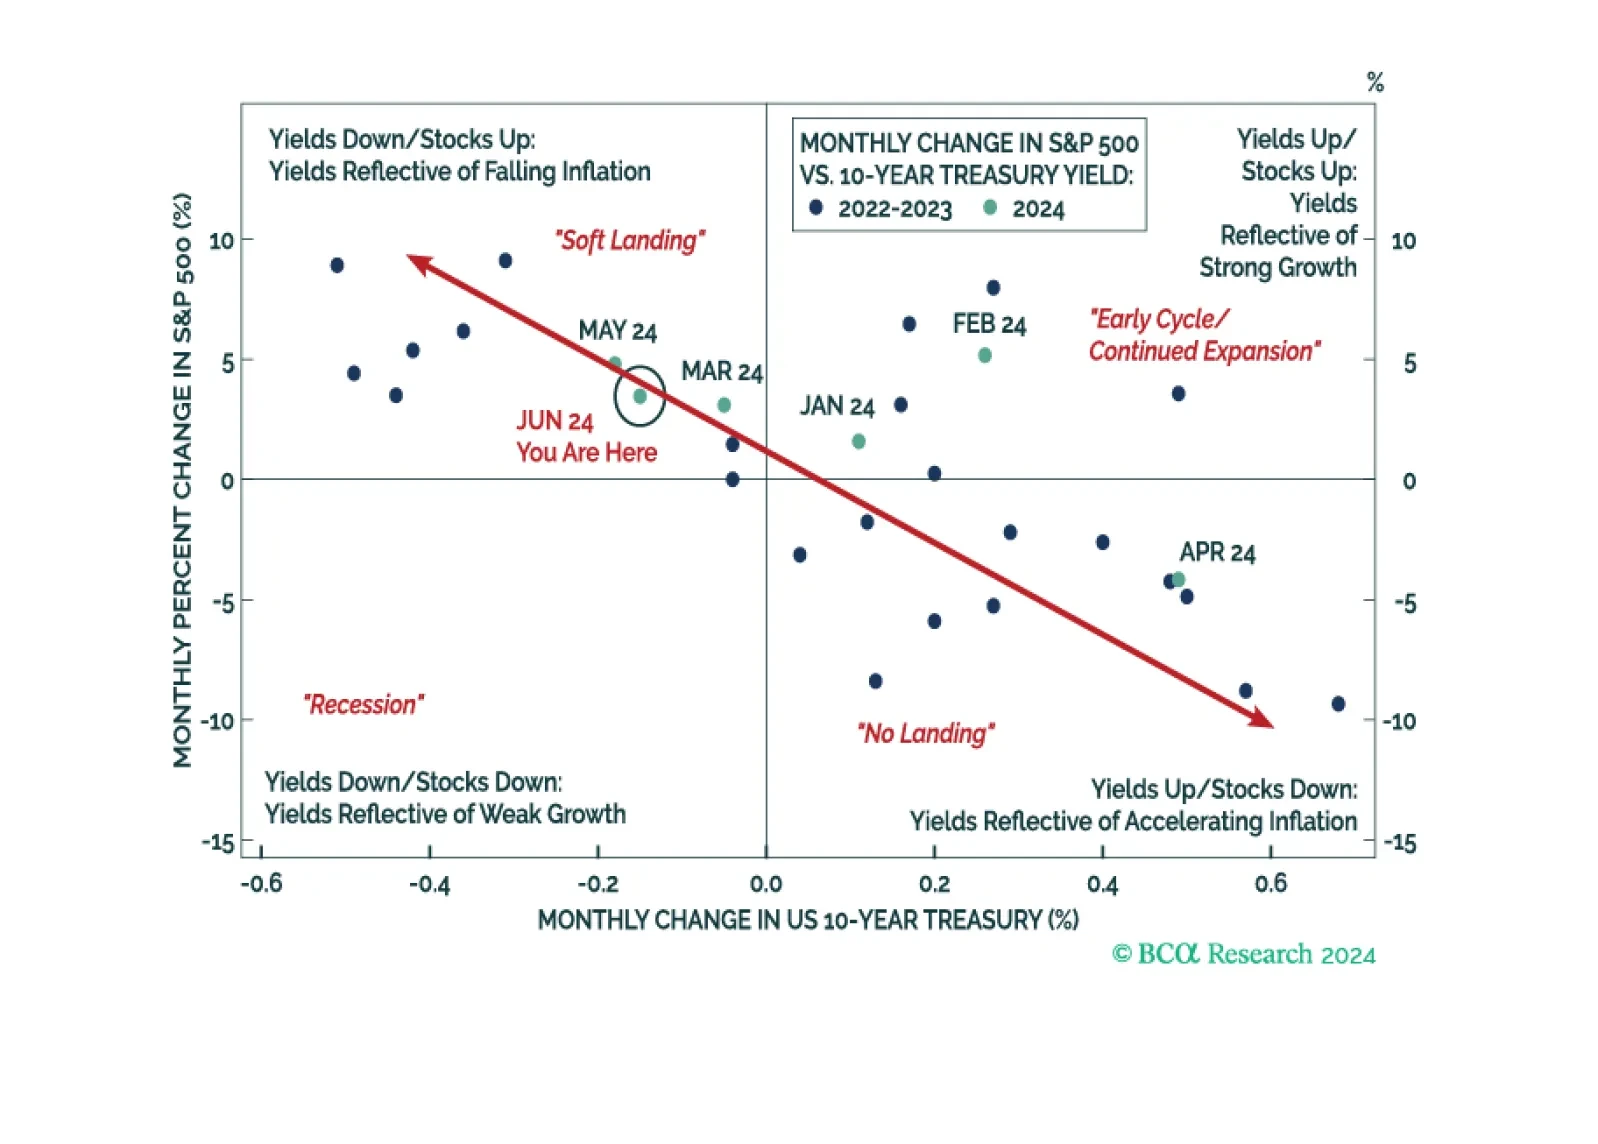
We have turned cautious on equities for the first time since August 2022. Our end-of-the-year target for 2024, 5,500 on the S&P 500, has been reached. From here on out, any upside is gravy. However, we worry about US – not European – politics. In fact, we think investors could profit from the recent selloff in France. The real risks are in the US.

At first glance, France has moved to the far left. However, this coalition is fragile, and Macron’s allies still hold the balance of power. What are the assets that will benefit from this new political setup, and those that will not?
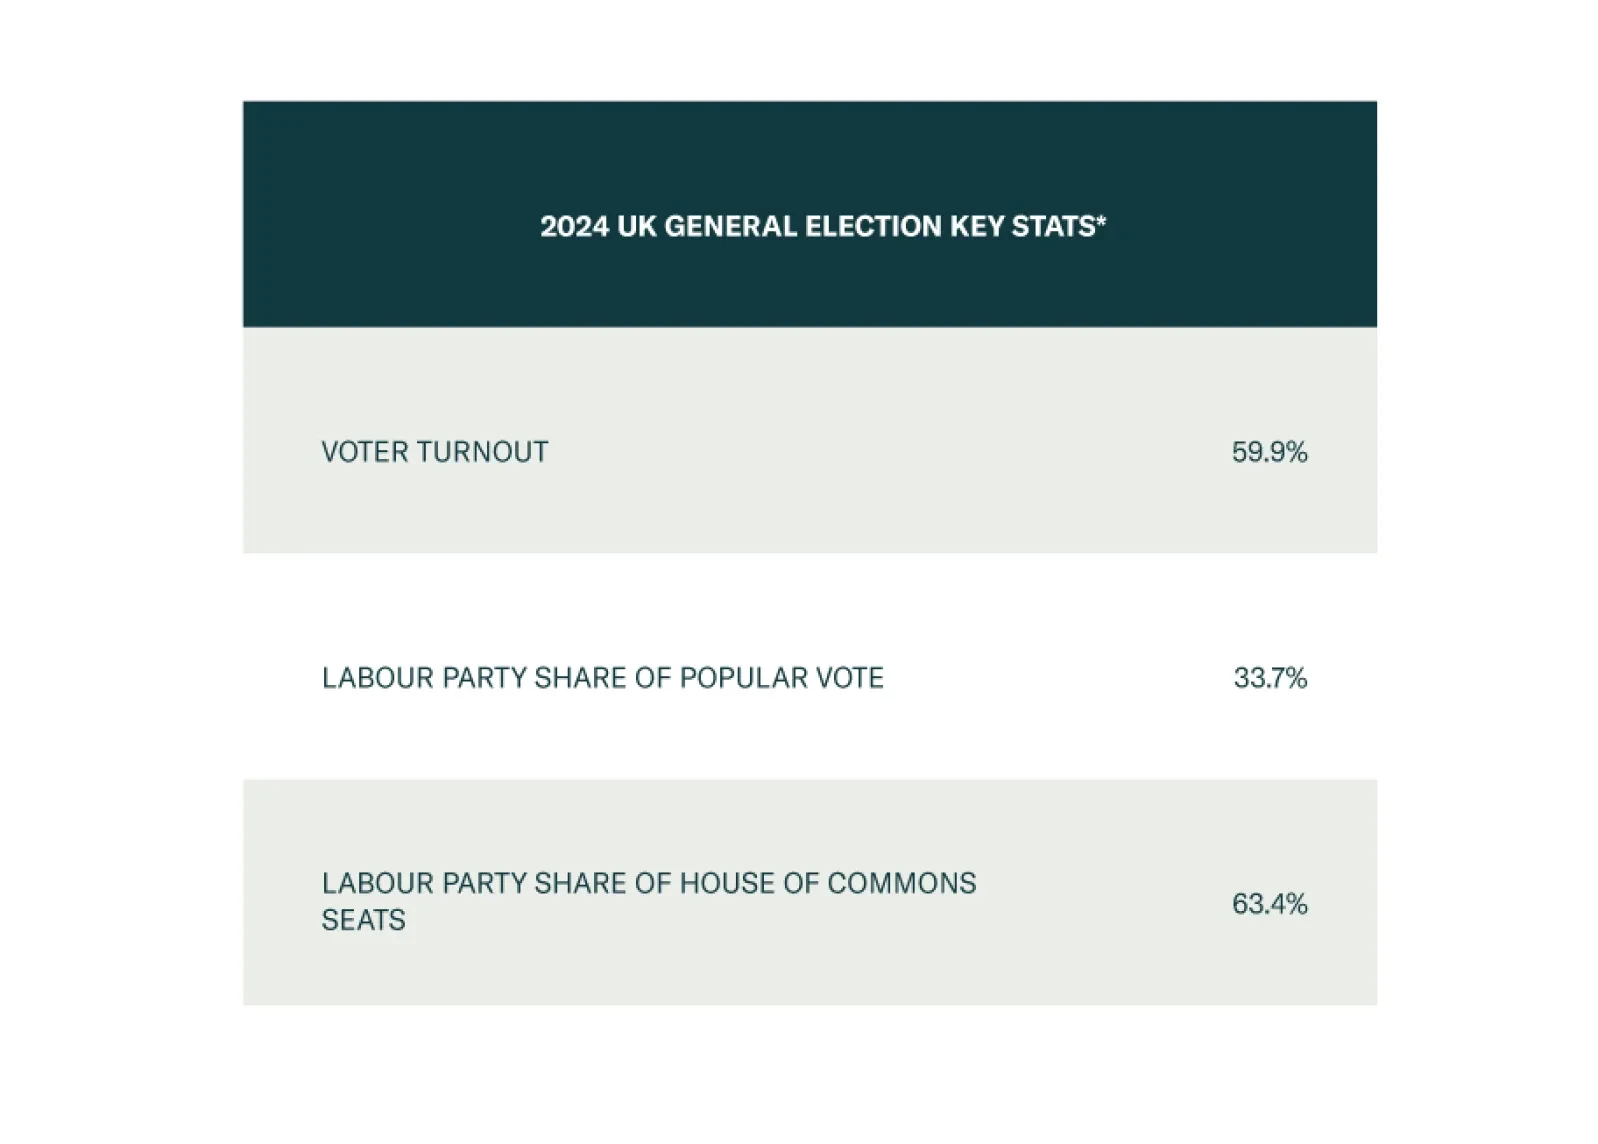
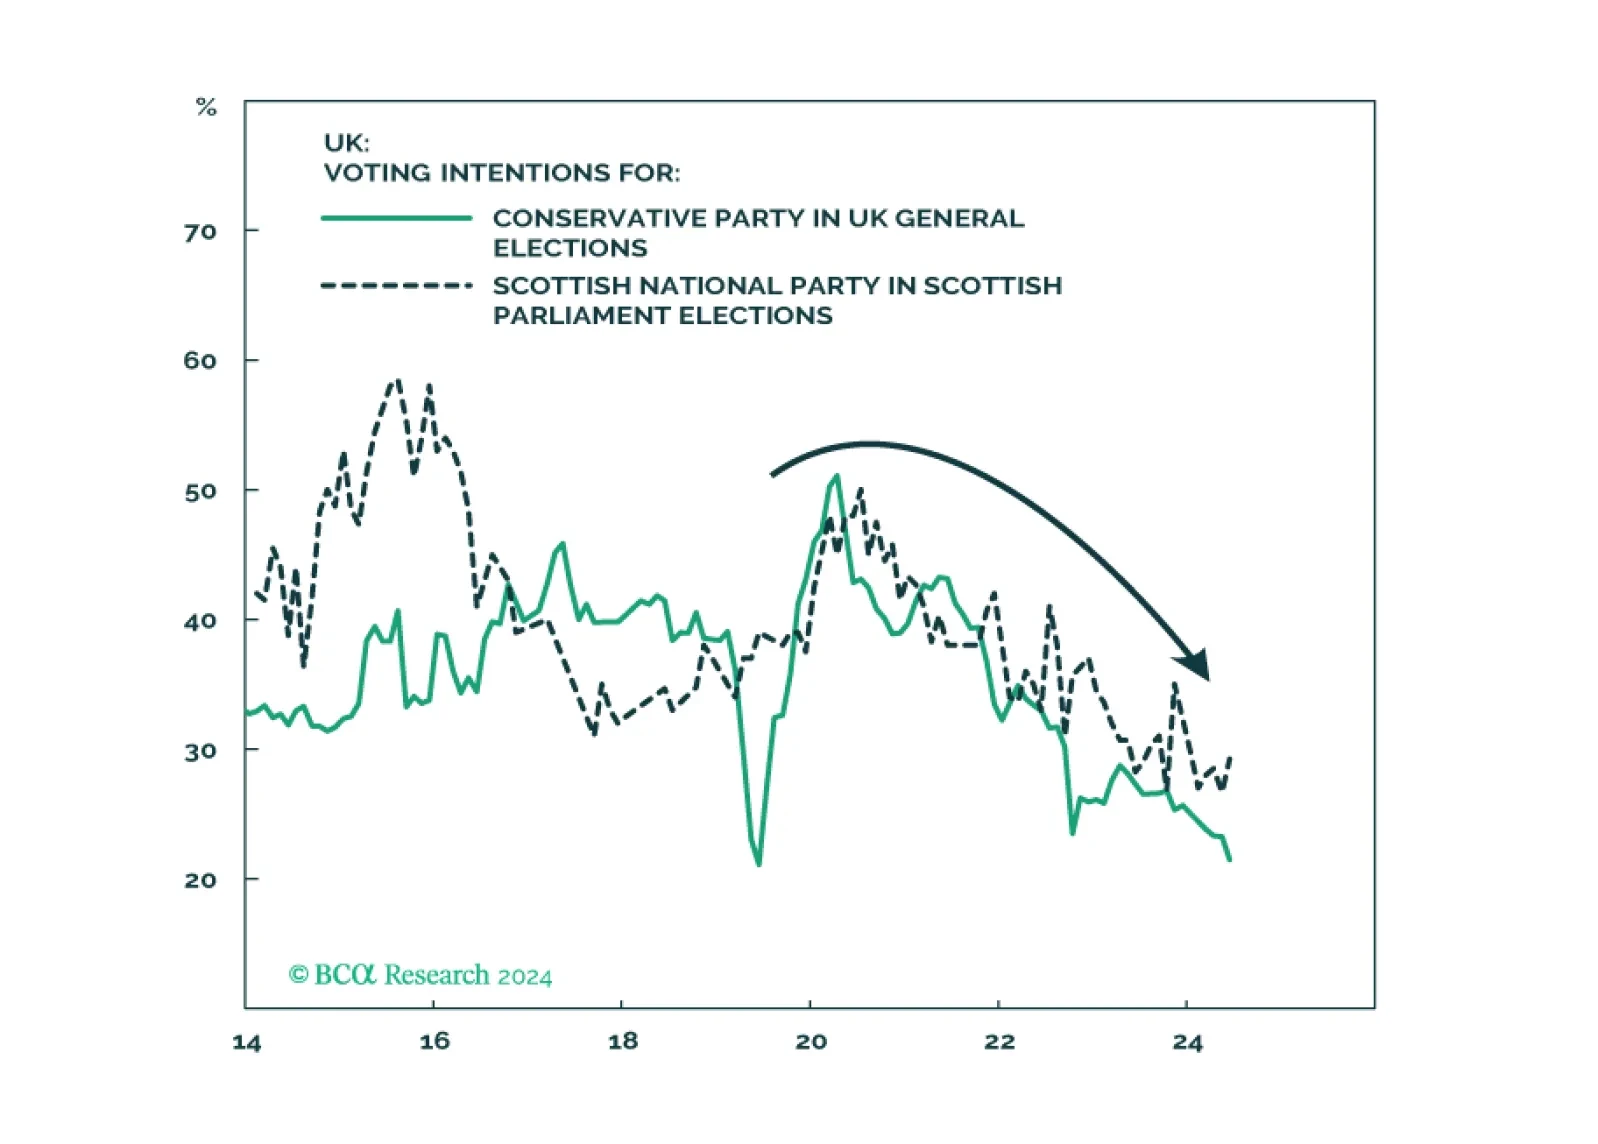
The new Labour government will have flexibility to respond to macro shocks, which is positive for the UK in general, namely GBP-EUR, and also gilts in absolute terms. But over the long run, tax hikes will likely surprise to the upside, which poses a risk to corporate earnings.
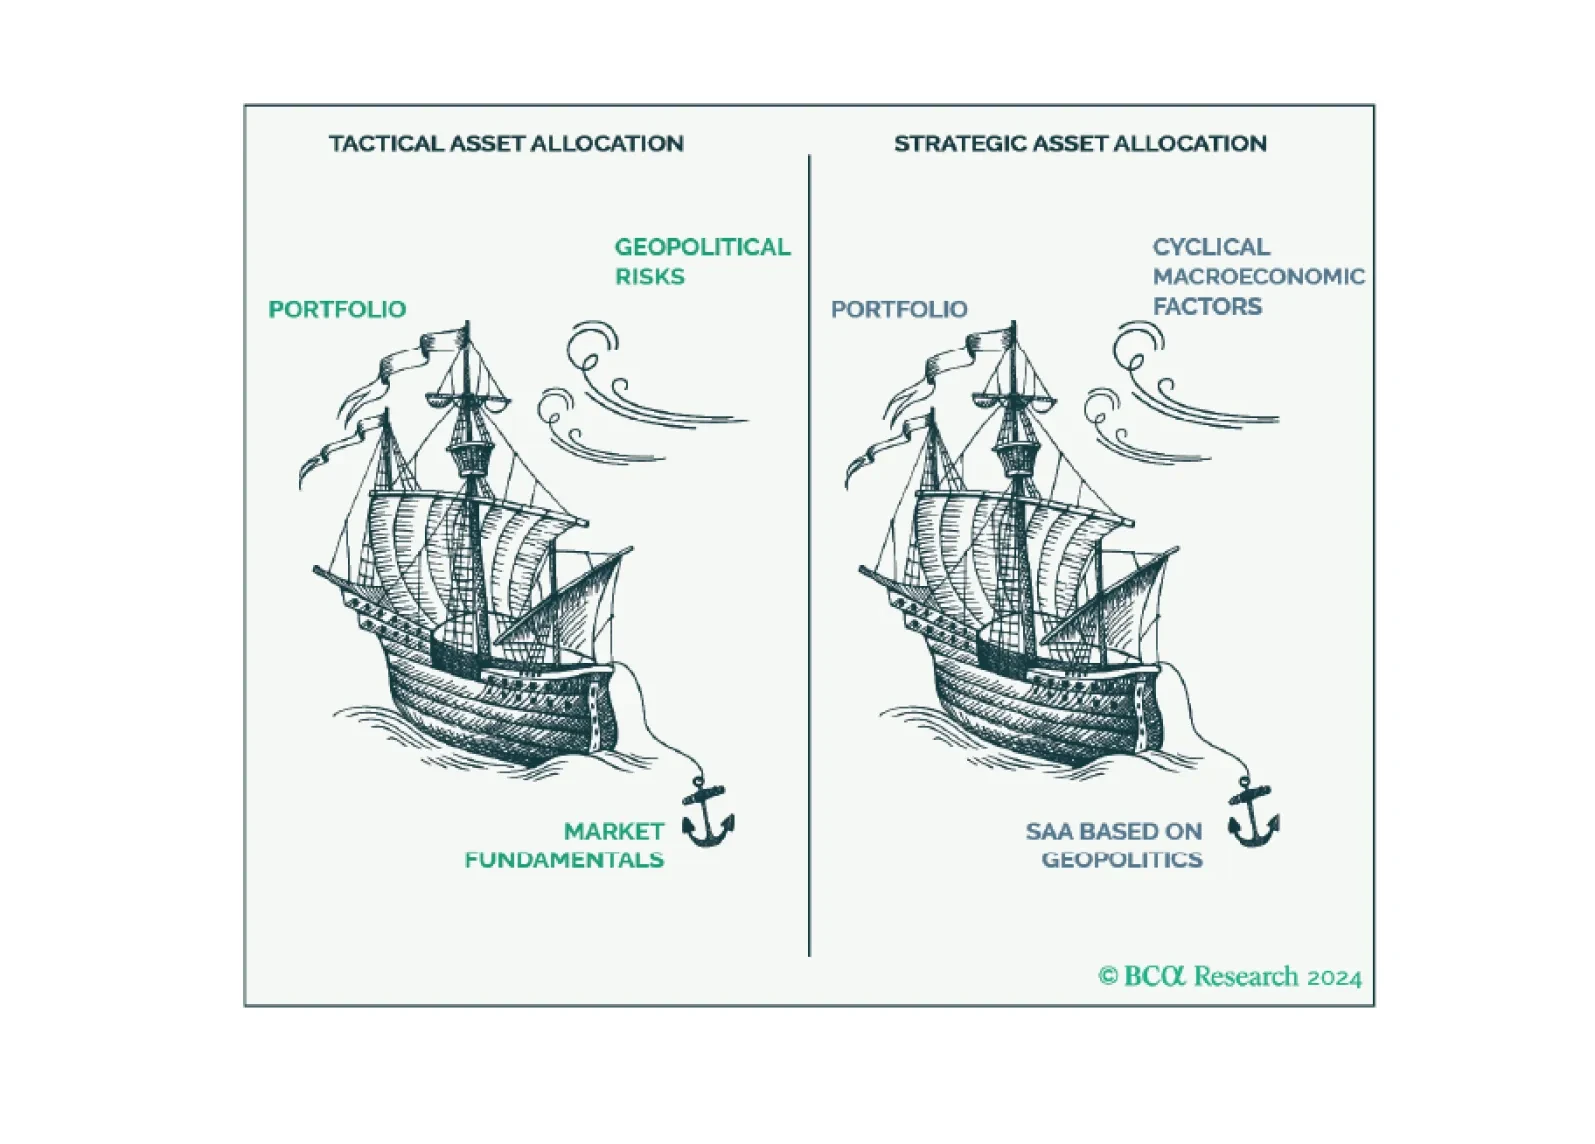
There are many different paths to macro investing. In our Volume II – The Beta Report – we present our own, which we have dubbed GeoMacro. We are very confident that we are “on to something,” but are humbled constantly by the markets, brilliant applications of different frameworks, and the confidence that, at BCA Research specifically, GeoMacro Strategy is housed in a collective of other approaches and methodologies that will greatly enhance our own capabilities. Our conclusion is simple: When it comes to searching for beta, nothing but geopolitics and politics matters. When it comes to searching for alpha, the macro fundamentals far outweigh geopolitics and politics.
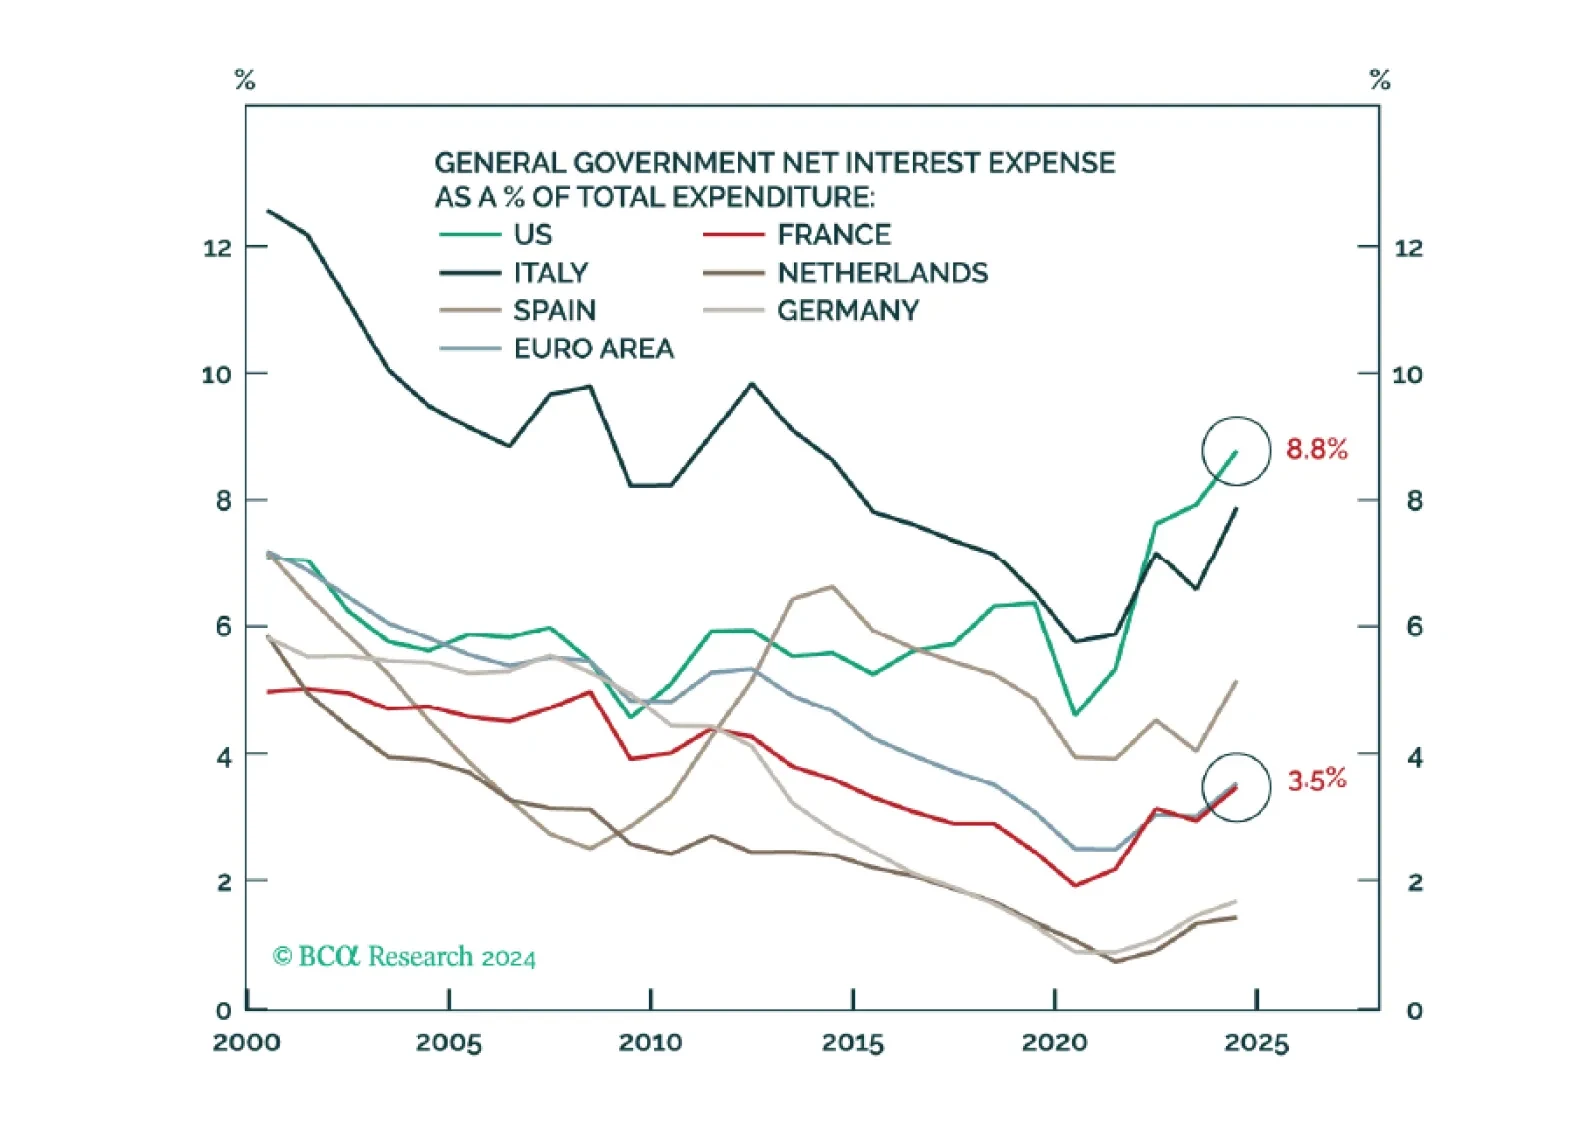
In our Volume I – The Alpha Report – we posit that the French bond market reaction is a mere amuse bouche for what is coming to the US. All year, we have warned investors that US politics could induce a bond market riot. This moment is nigh. Act accordingly!
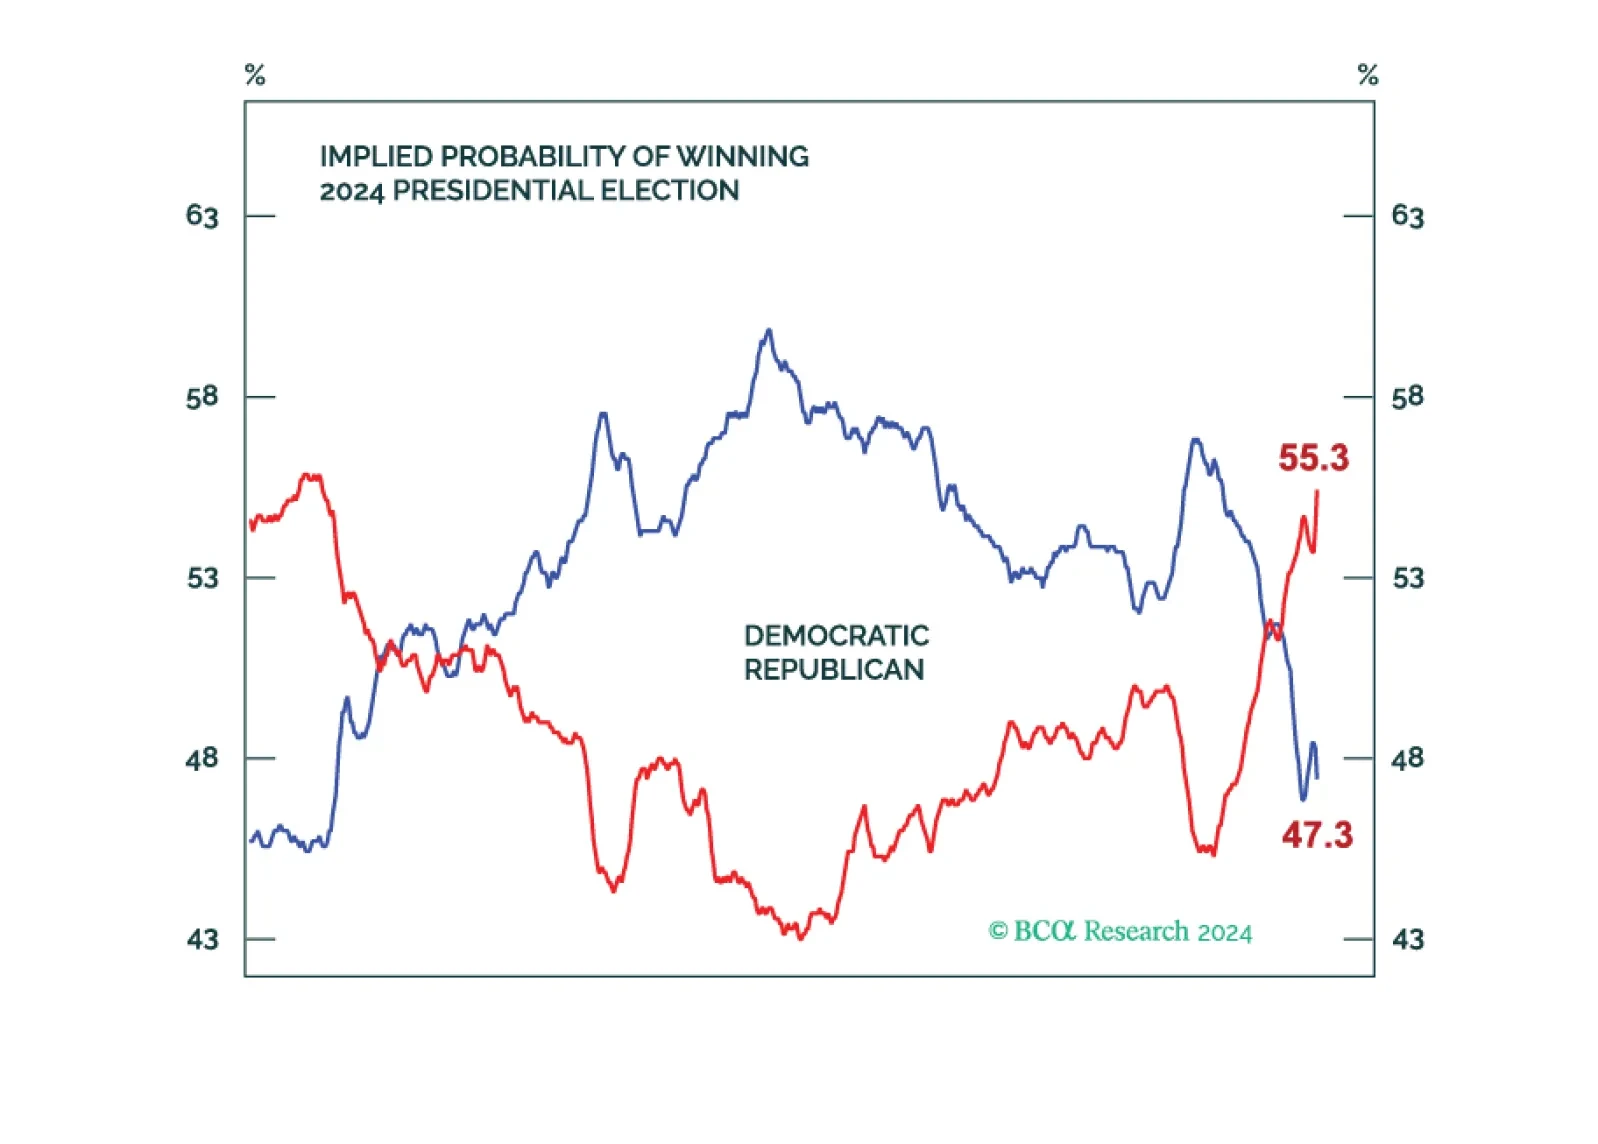
The bond market should sell off and drag stocks down on higher odds of a single-party sweep, policy uncertainty, unorthodox Trump presidency, aggressive tariffs, large tax cuts, large budget deficits, labor shortages, a fired Fed chair, and higher inflation.
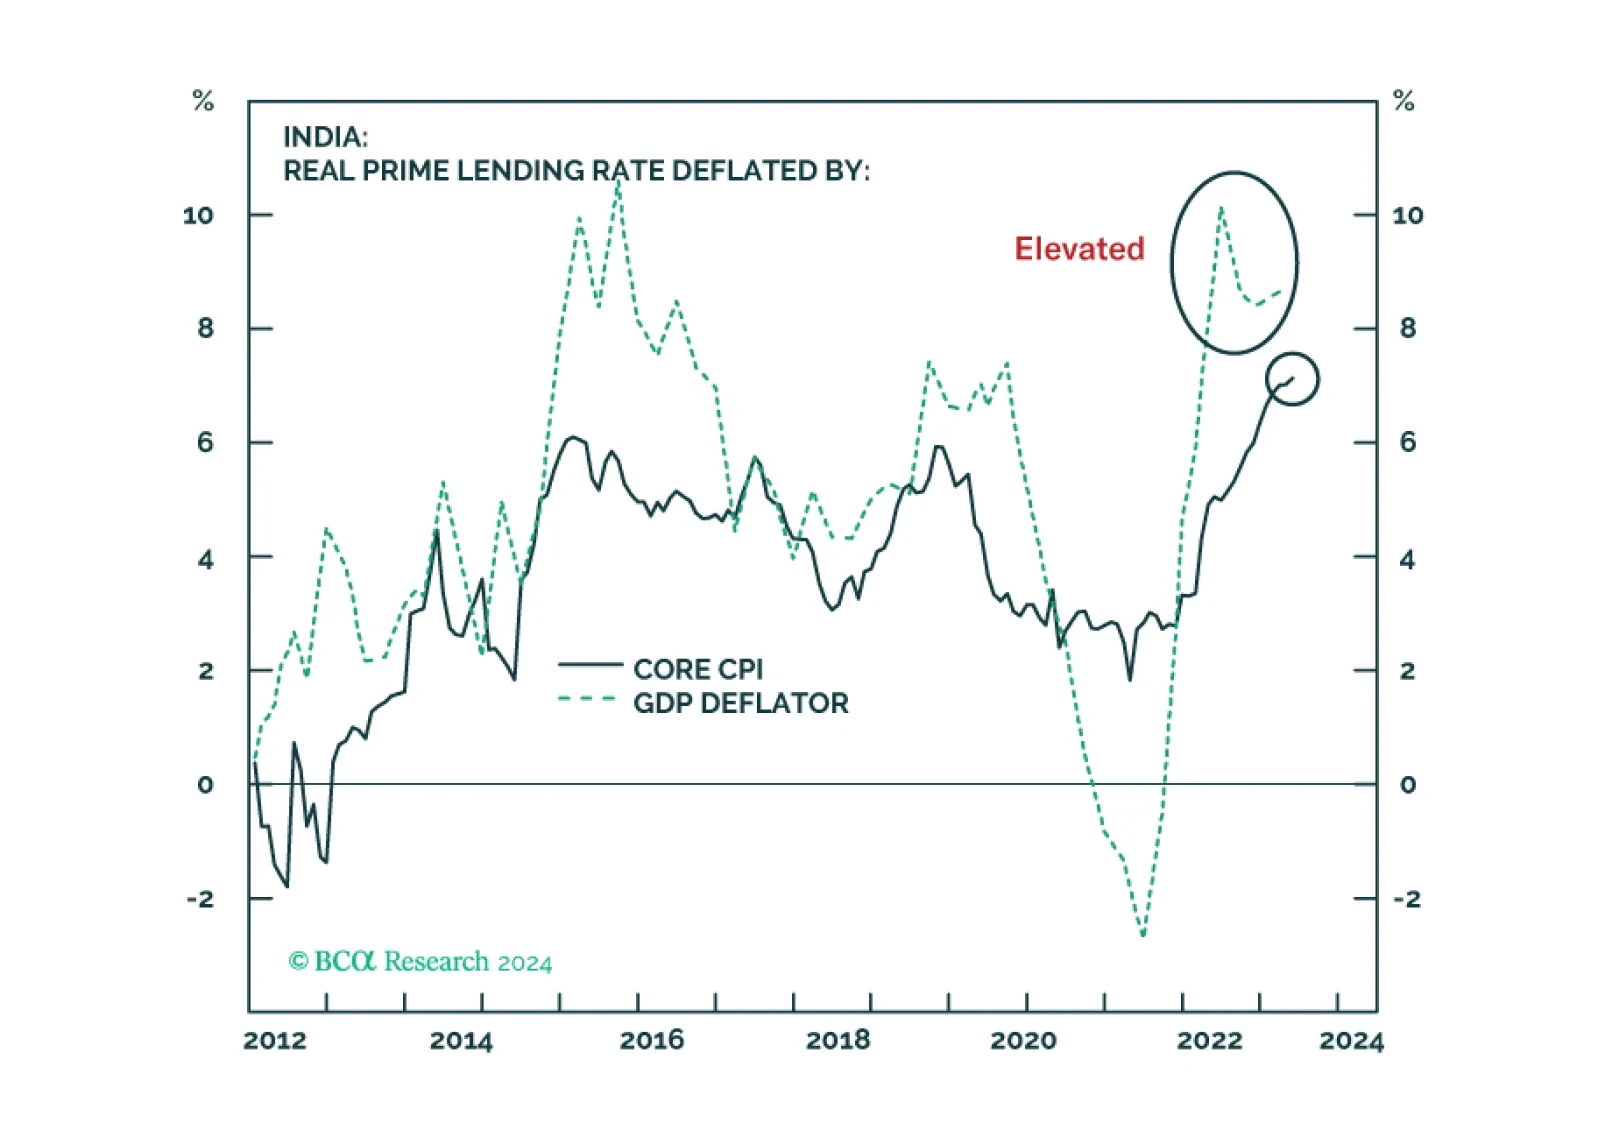
The Indian election outcome is a positive development for the country’s long-term socio-economic outlook. Indian stocks, however, remain vulnerable in the near term due to sharply slowing nominal sales and surging real borrowing costs. Indian domestic bonds, on the other hand, are a buy.
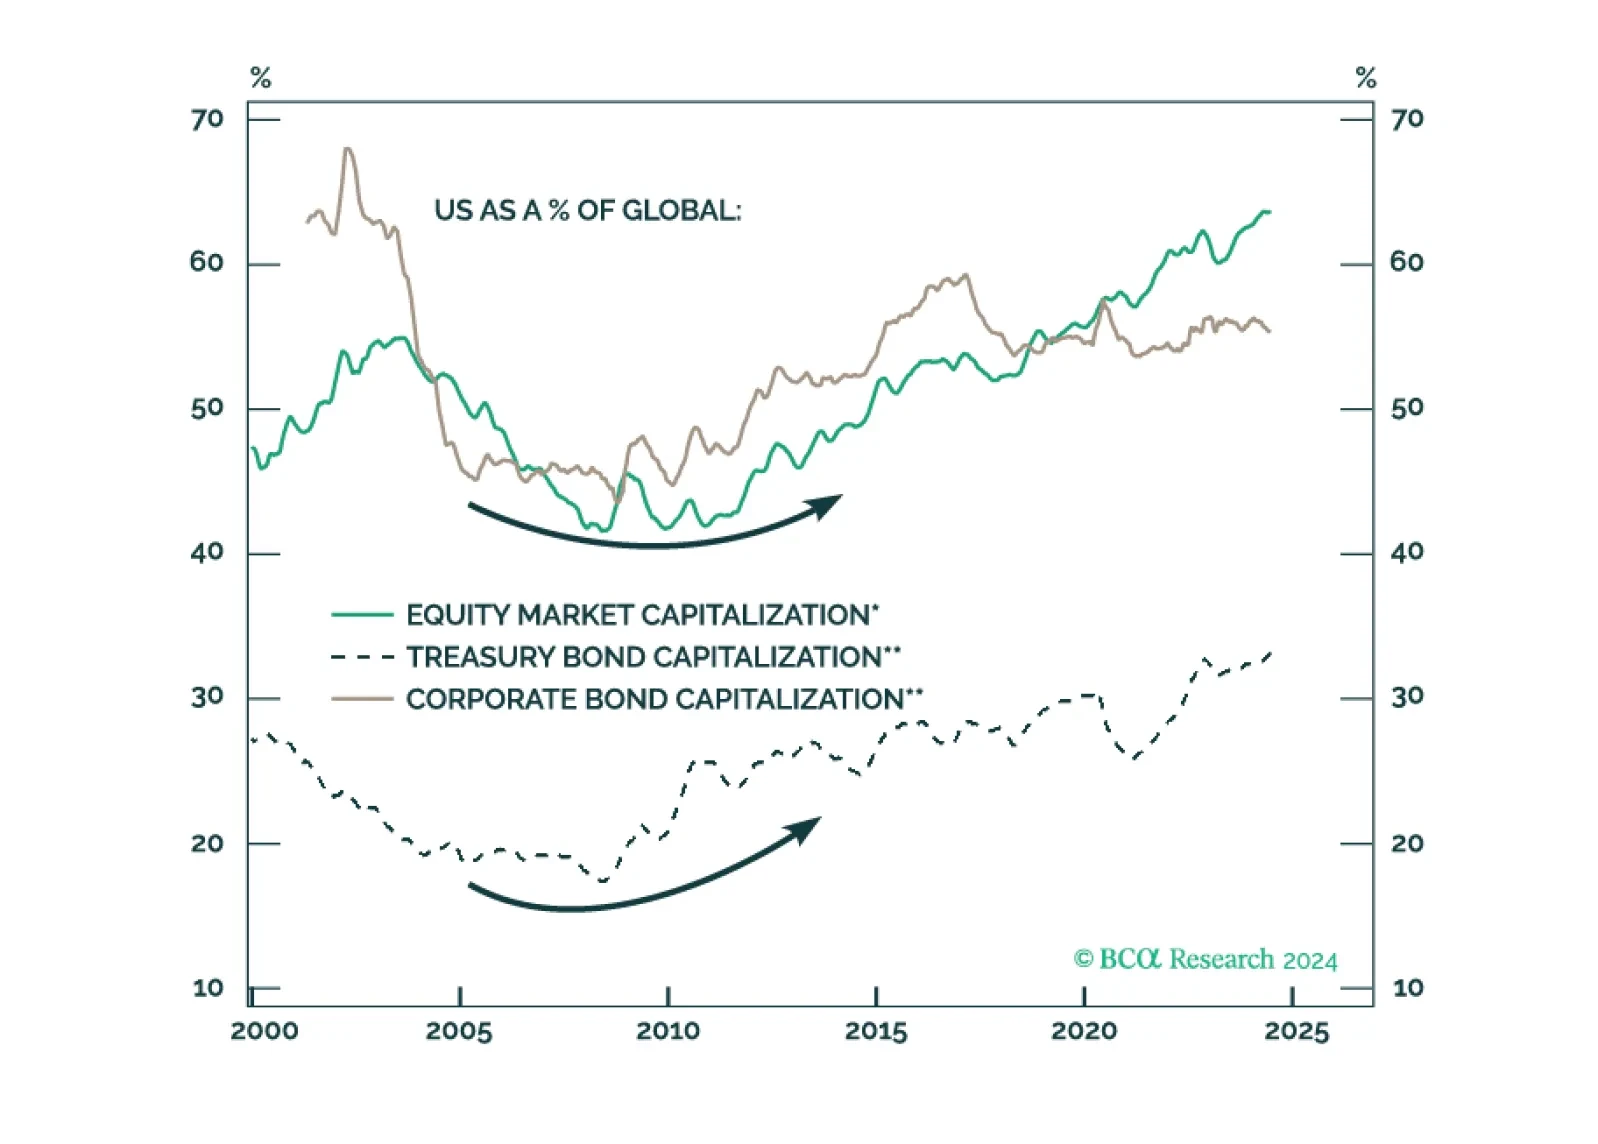
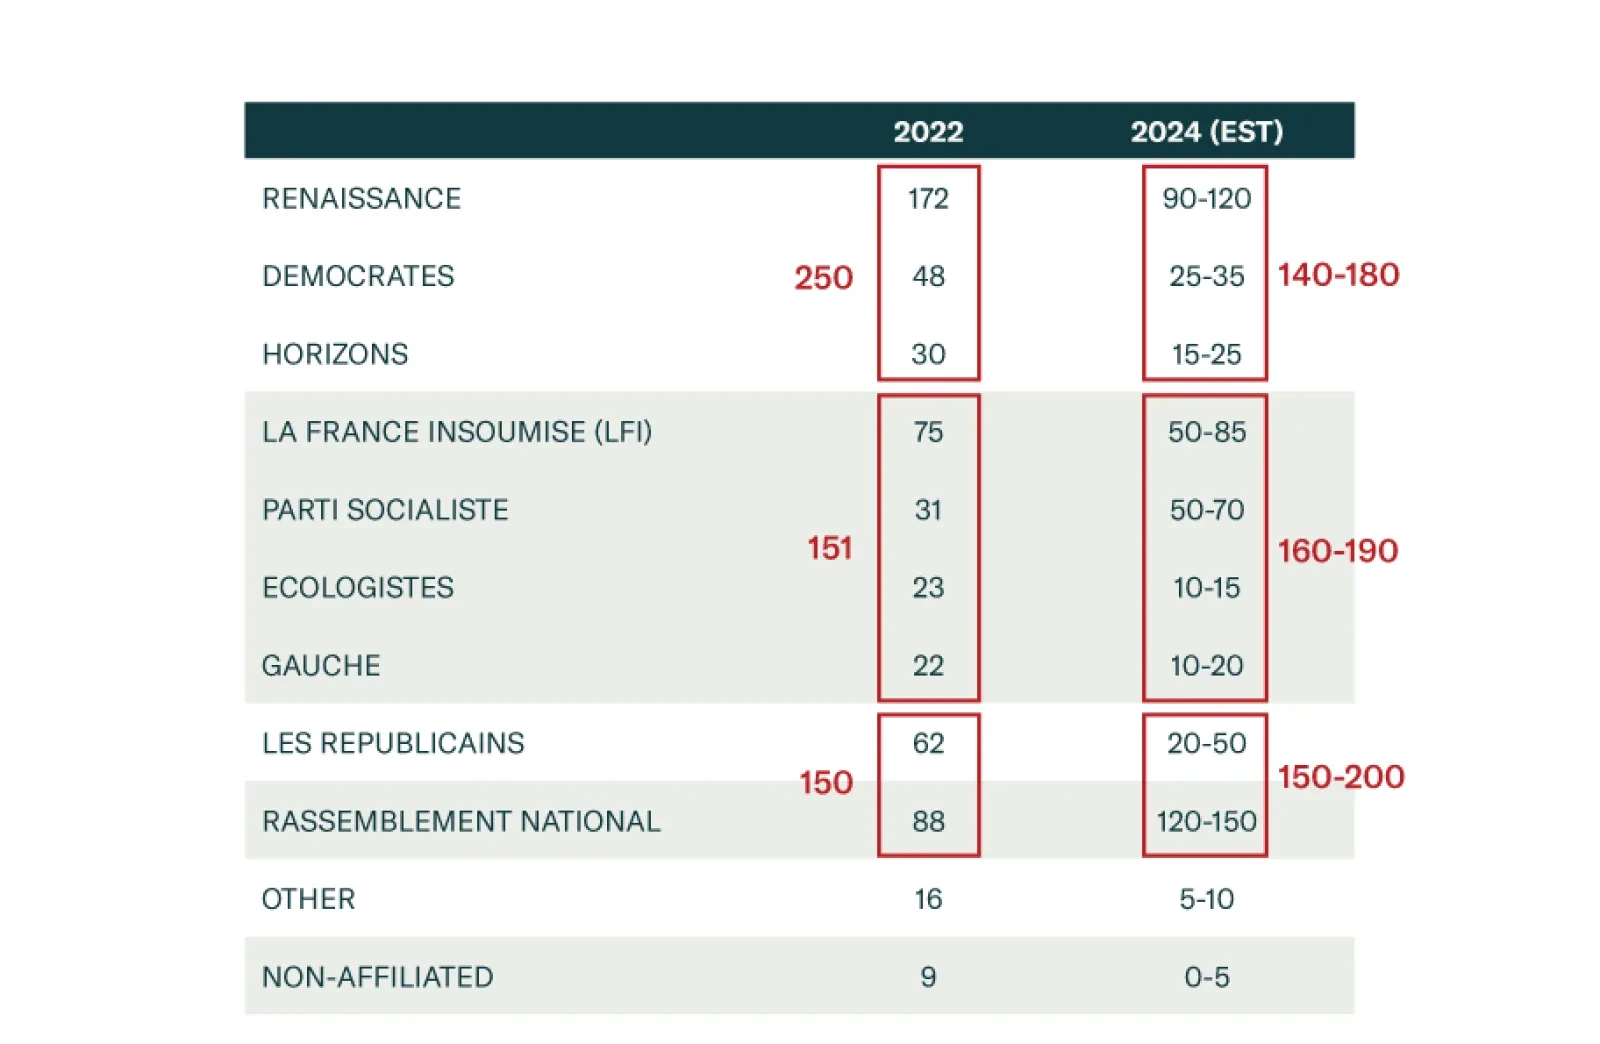
European assets are selling off as investors panic about the upcoming French election. Is this panic justified, and if so, for how long?