Inflation/Deflation

To the extent that US small businesses are typically more exposed to domestic economic conditions than larger firms, results of the NFIB Small Business Economic Trends survey are instructive. One important trend is that the October survey results corroborate…
The ZEW survey of investor sentiment continues to send an optimistic signal. German sentiment jumped from -1.1 to +9.8 in November – its highest level since March and beating expectations of a smaller improvement to 5.0. Similarly, expectations for the Euro…
BCA Research’s Global Fixed Income Strategy service remains long 10-year German bunds vs short 10-year Japanese government bonds (JGBs) as a tactical trade. This trade mirrors the team's two highest conviction strategic views in government bond space,…
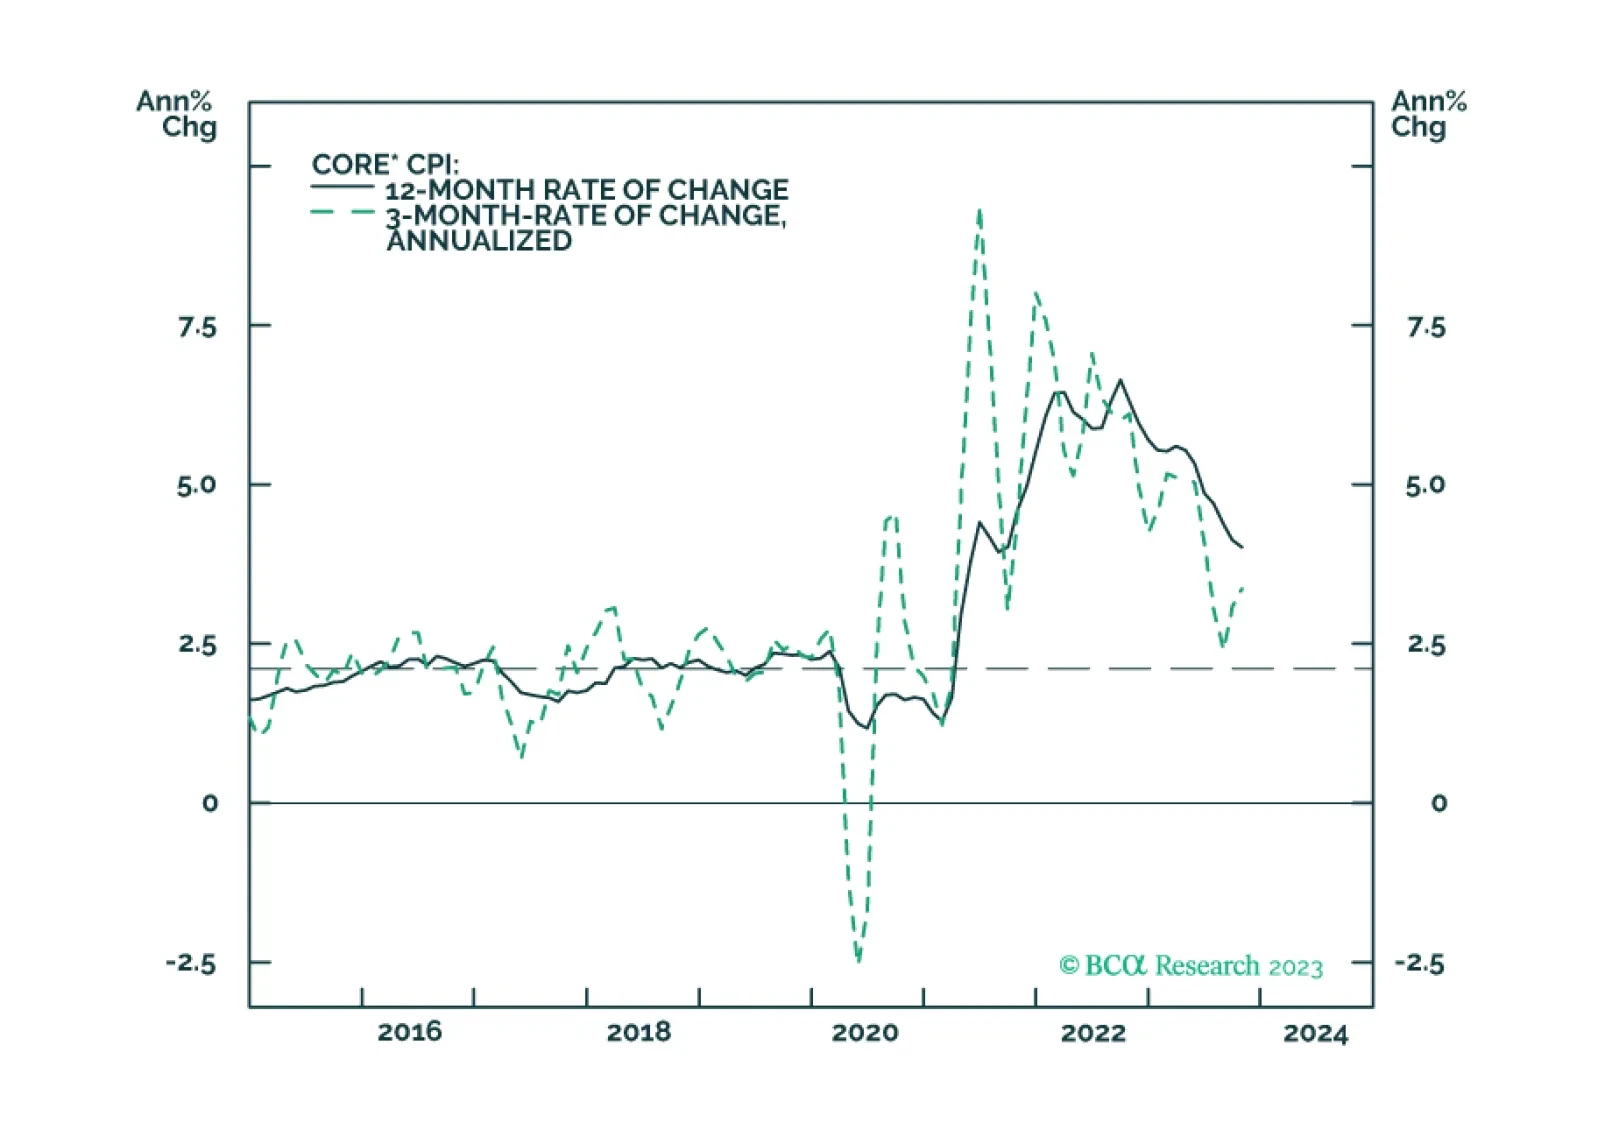
Our thoughts on this morning’s CPI print and the bond market’s reaction.
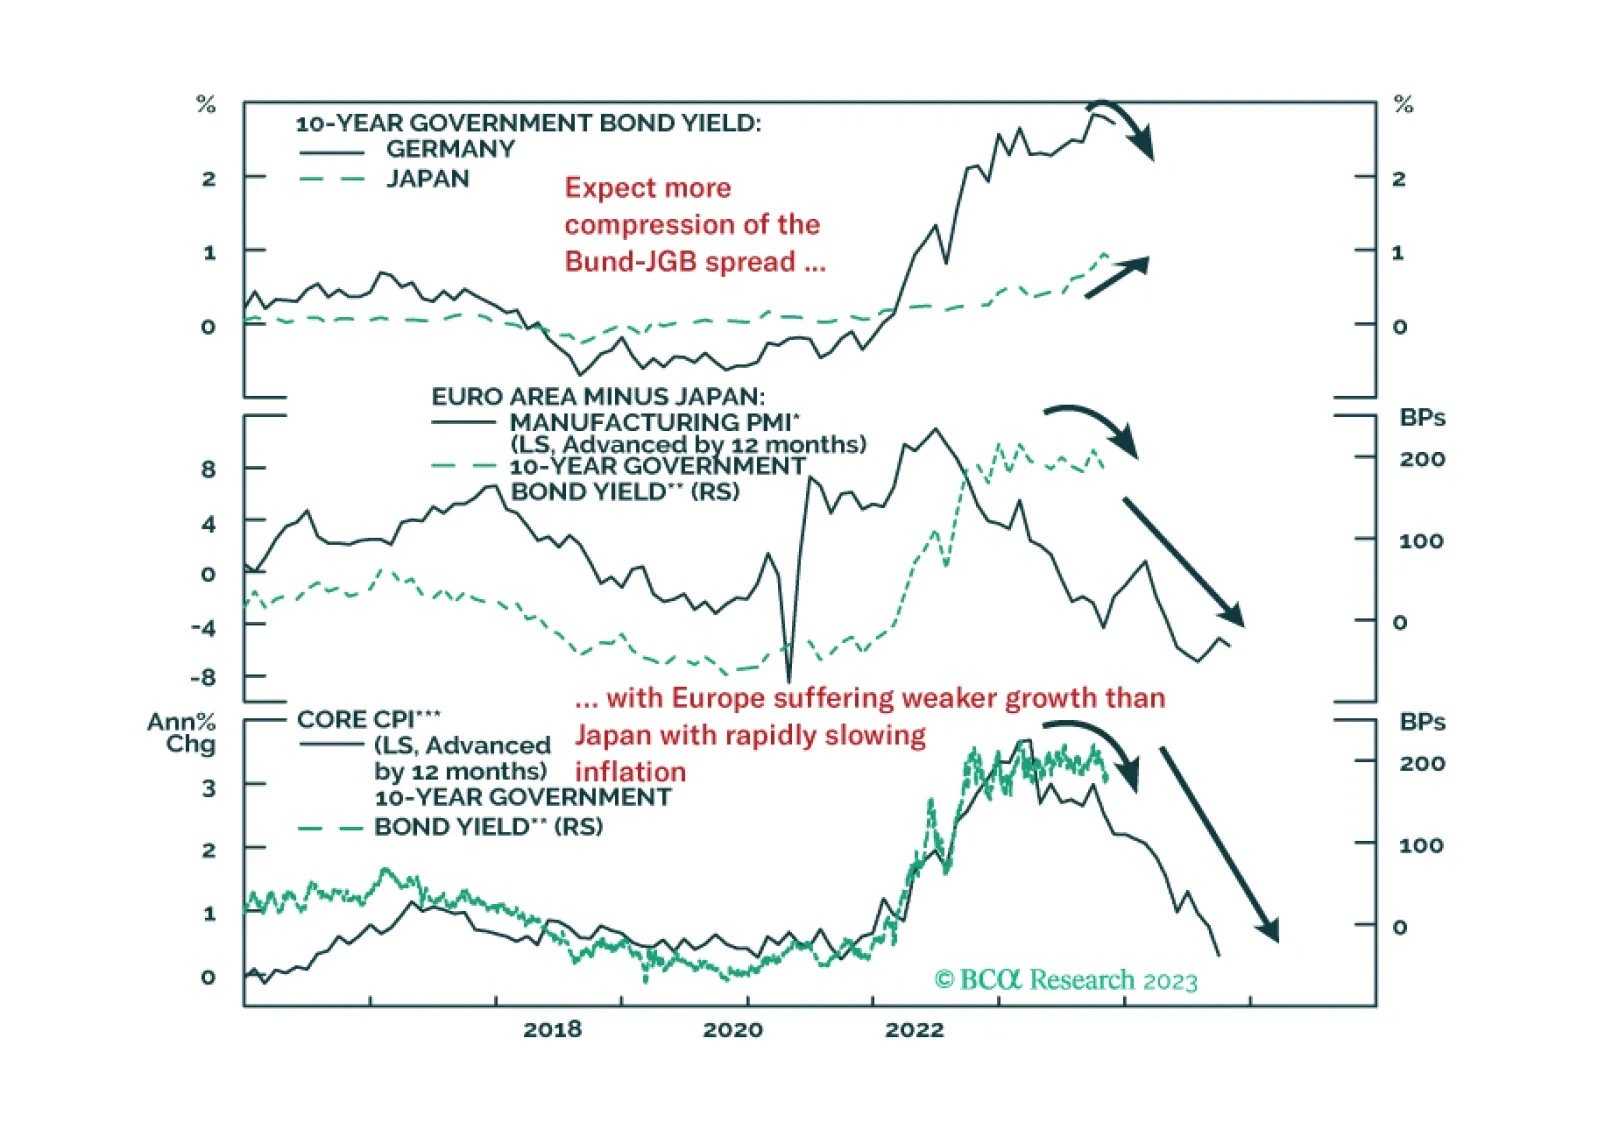
In this Insight, we review the performance and rationale for our current set of tactical fixed income trade recommendations. Our highest conviction positions also happen to be our most successful trades: positioning for a narrowing of the German bund-JGB spread and wider Japanese inflation breakevens.
The preliminary release for the University of Michigan’s Consumer Survey sent a pessimistic signal about consumer sentiment on Friday. The headline index fell from 63.8 to 60.4 in November, below expectations of a marginal decrease to 63.7. Declines in both…
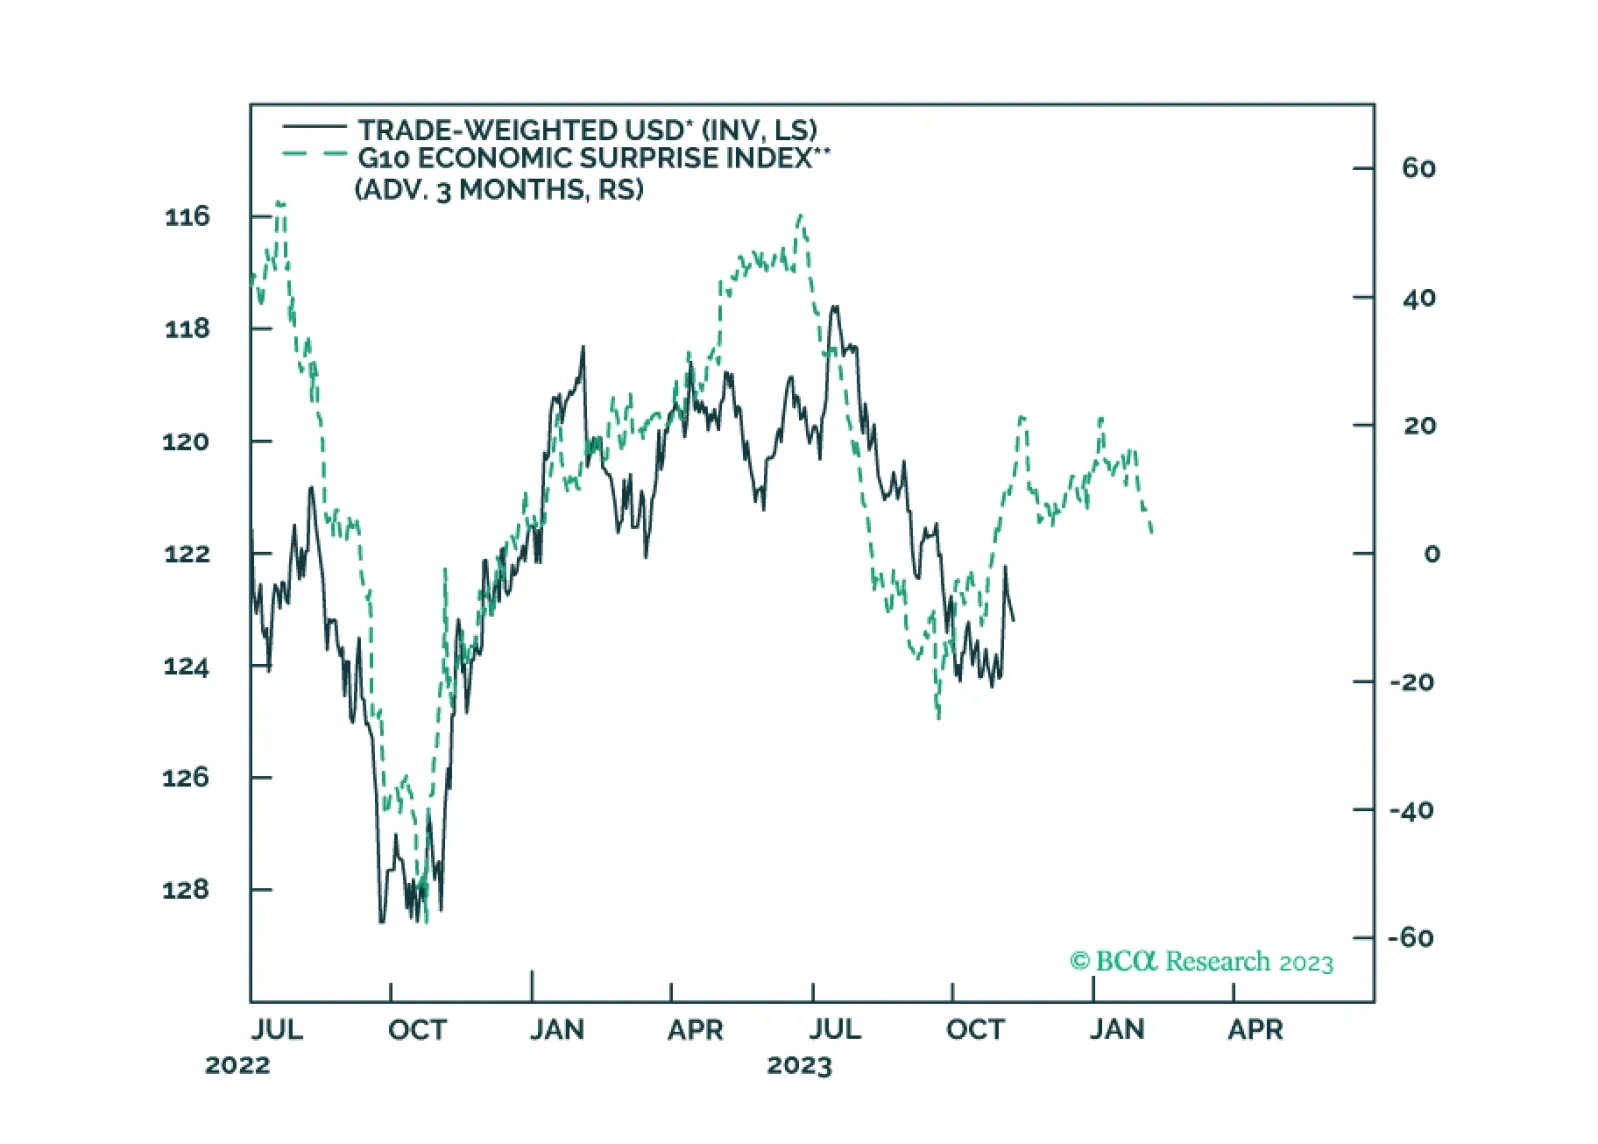
In this report, we go around the globe and survey the near-term outlook for G10 currencies. Our longer-term view on the dollar has been clear, we are sellers. In this report, we review if a tactical sell is also warranted given incoming data and the message from our models.
China's CPI and PPI inflation release for October indicates that deflationary pressures continue to dominate the domestic economy. After remaining unchanged in September, consumer prices declined by 0.2% y/y last month, falling below consensus estimates of a…
According to BCA Research’s Counterpoint service, the ECB is the central bank that poses the lowest risk of repeating the mistakes of the 1970s and letting inflation expectations unanchor. One reason is the ECB’s inherited Germanic anti-inflation DNA. Even in…
The US disinflationary trend remains intact. The core PCE deflator continued its downtrend in September, falling to 3.7% y/y from a peak of 5.6% in February 2022. Alternative measures of underlying price pressures such as the trimmed mean and median PCE…