Latest from BCA Research
MacroQuant is bearish on equities, overweight bonds, and overweight cash. Within equities, the model favors Europe over the US and is underweight on EM.
The risk-reward of the US dollar is currently positive. If a US recession is not imminent, then US bond yields will move higher, thus supporting the greenback. If the US enters a recession soon, the US dollar will benefit because it is counter-cyclical. Besides, the US dollar has not been as weak as the DXY index suggests.
Pent-up demand for services is keeping the global economy going, but we still expect recession over the next 12 months. Investors should keep a cautious portfolio stance.
This week we present our Portfolio Allocation Summary for May 2023.
EUR/USD is trying to breach above 1.10. What is the balance of positive versus negative factors that would allow the euro to breakout?
Yen bulls need patience. The near-term narrative remains bearish on the back of interest-rate differentials. Longer term, it is the most attractive currency the G10, on valuation grounds.
Yen bulls need patience. The near-term narrative remains bearish on the back of interest-rate differentials. Longer term, it is the most attractive currency the G10, on valuation grounds.
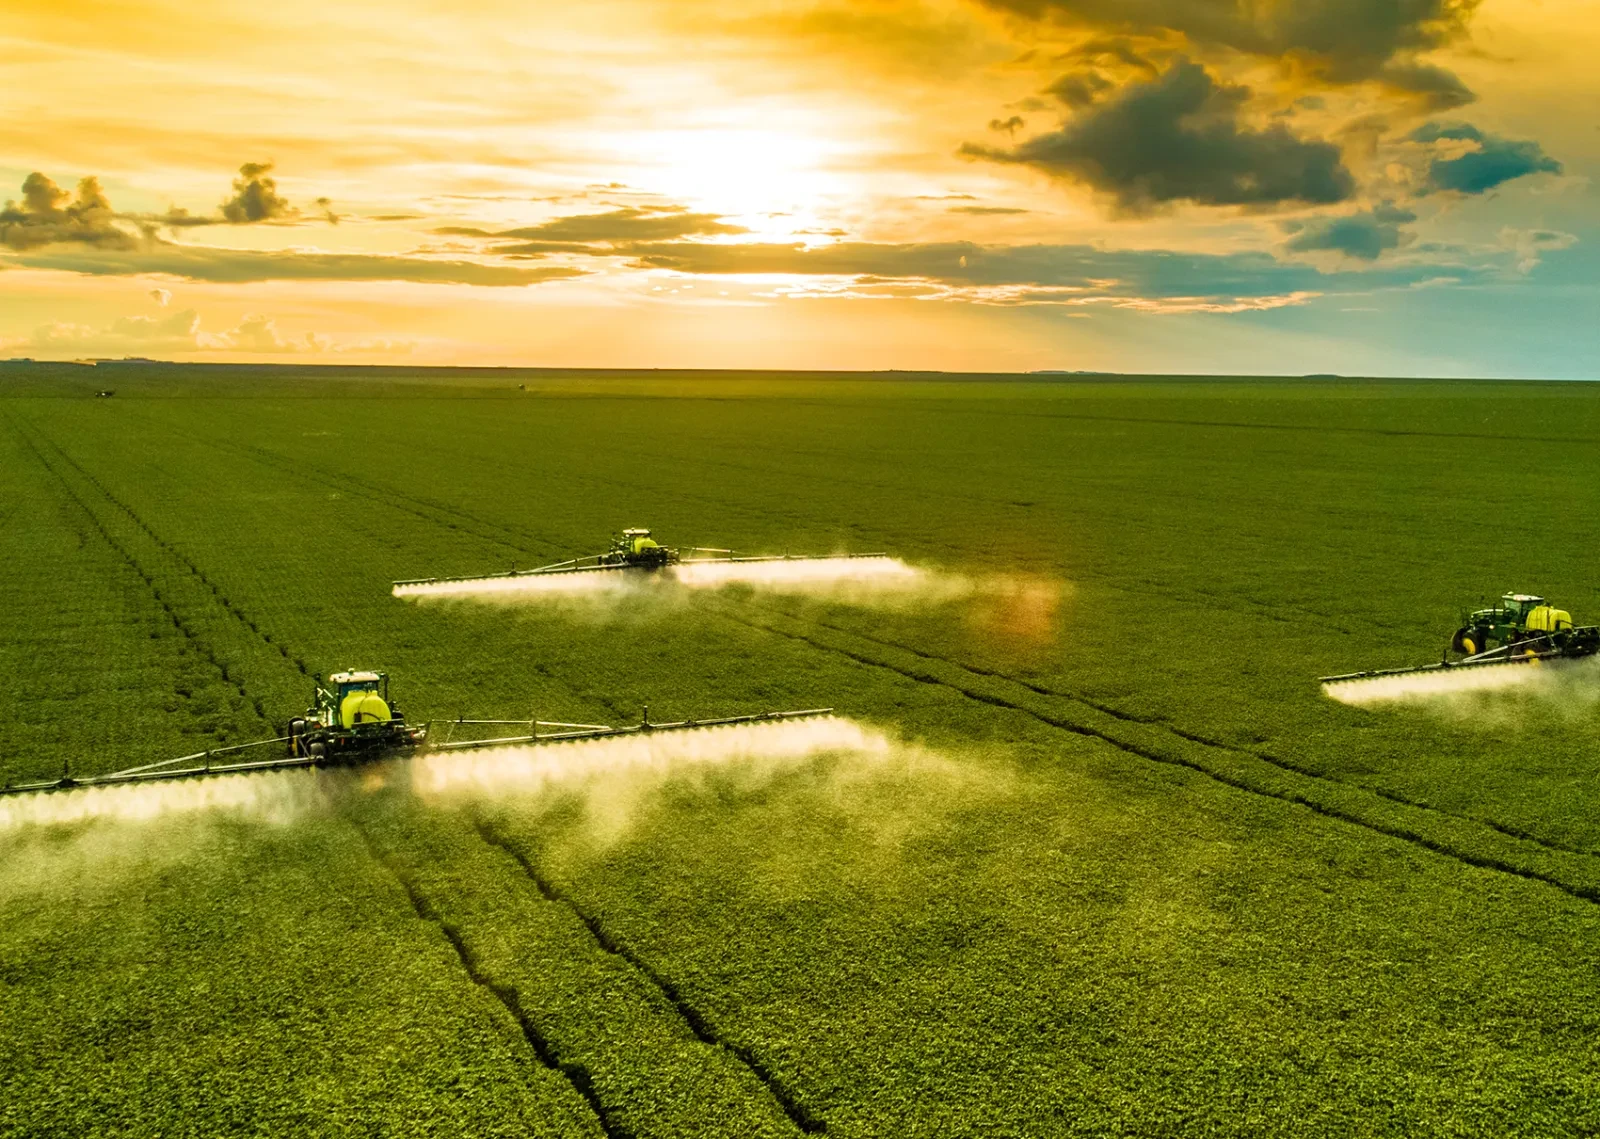
Fertilizer prices will continue to move lower as the natgas price shock touched off by the Russian invasion of Ukraine dissipates. As a result, we expect grain prices to soften another 10% this year. Food-price inflation will move lower over the course of the year as grain prices weaken, provided a weather- or geopolitical shock does not once again send natgas prices higher.
The new fiscal framework will fail to prevent the rise of the public debt-to-GDP ratio as it relies on overly optimistic revenue growth. A rising public debt-to-GDP ratio will lead to a widening fiscal risk premium in Brazilian financial markets. We are making two new recommendations: downgrade Brazilian sovereign credit from neutral to underweight, and go long Brazilian CDS / short Mexican CDS.