Latest from BCA Research
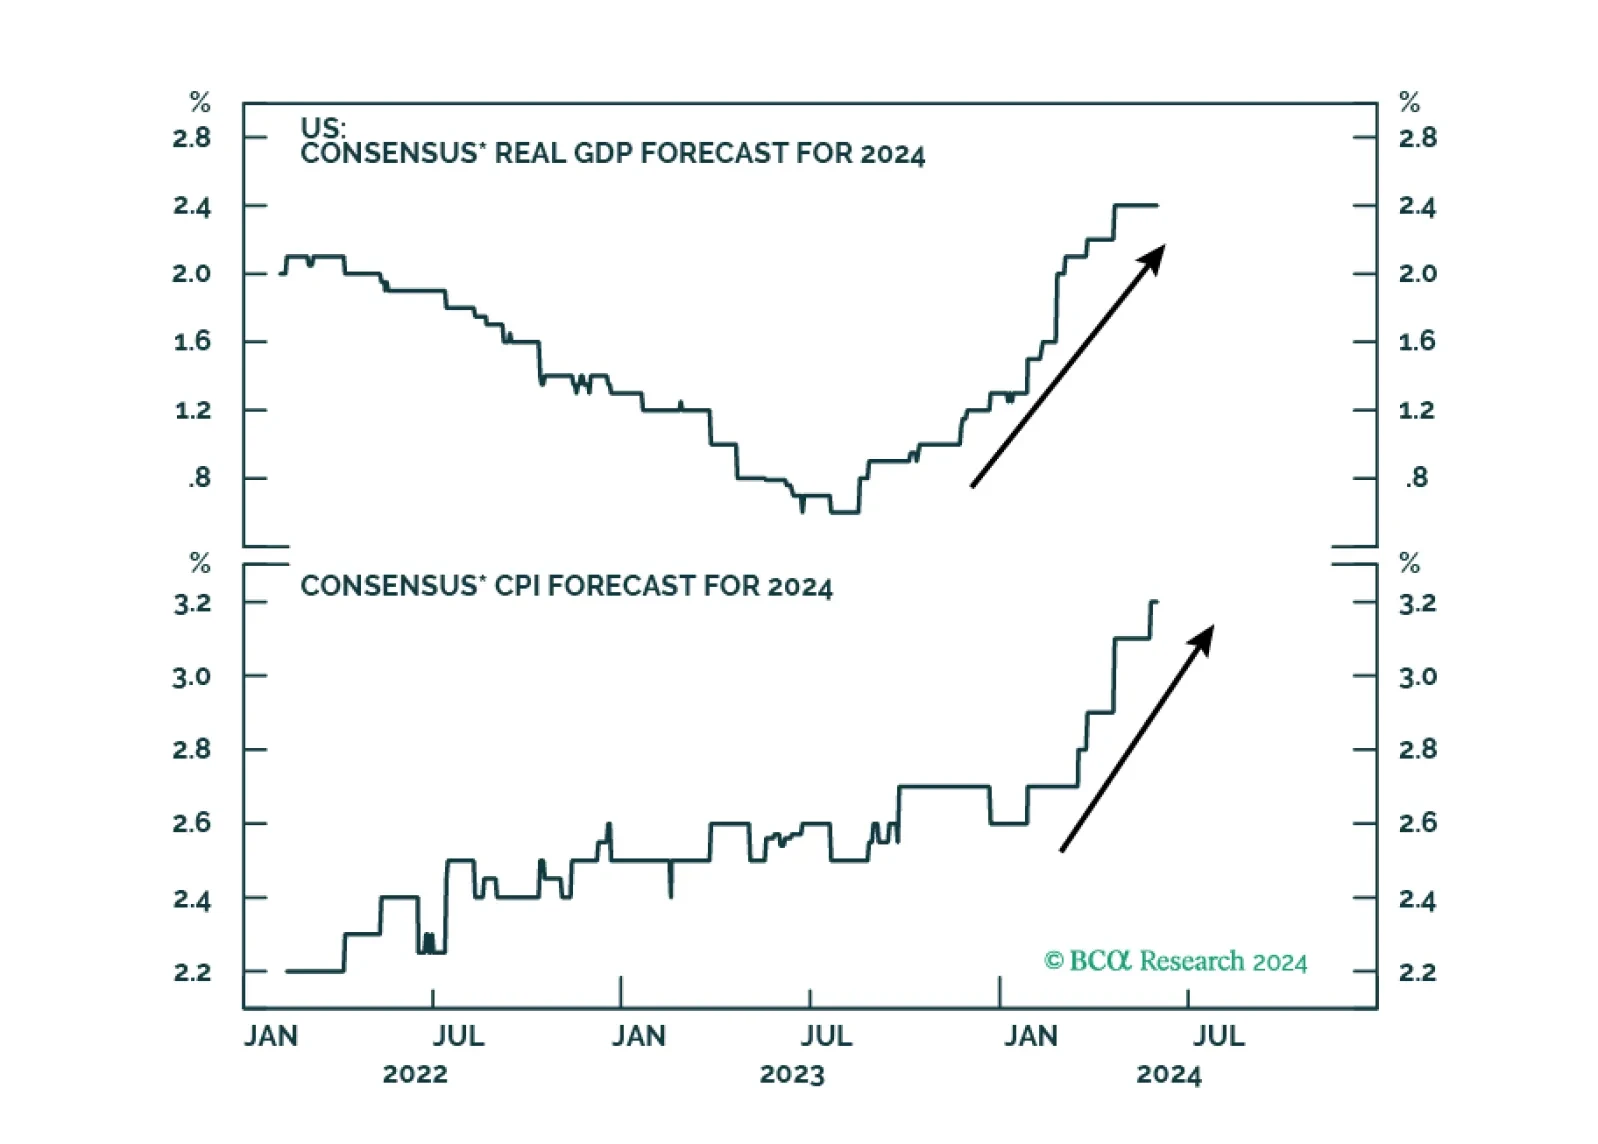
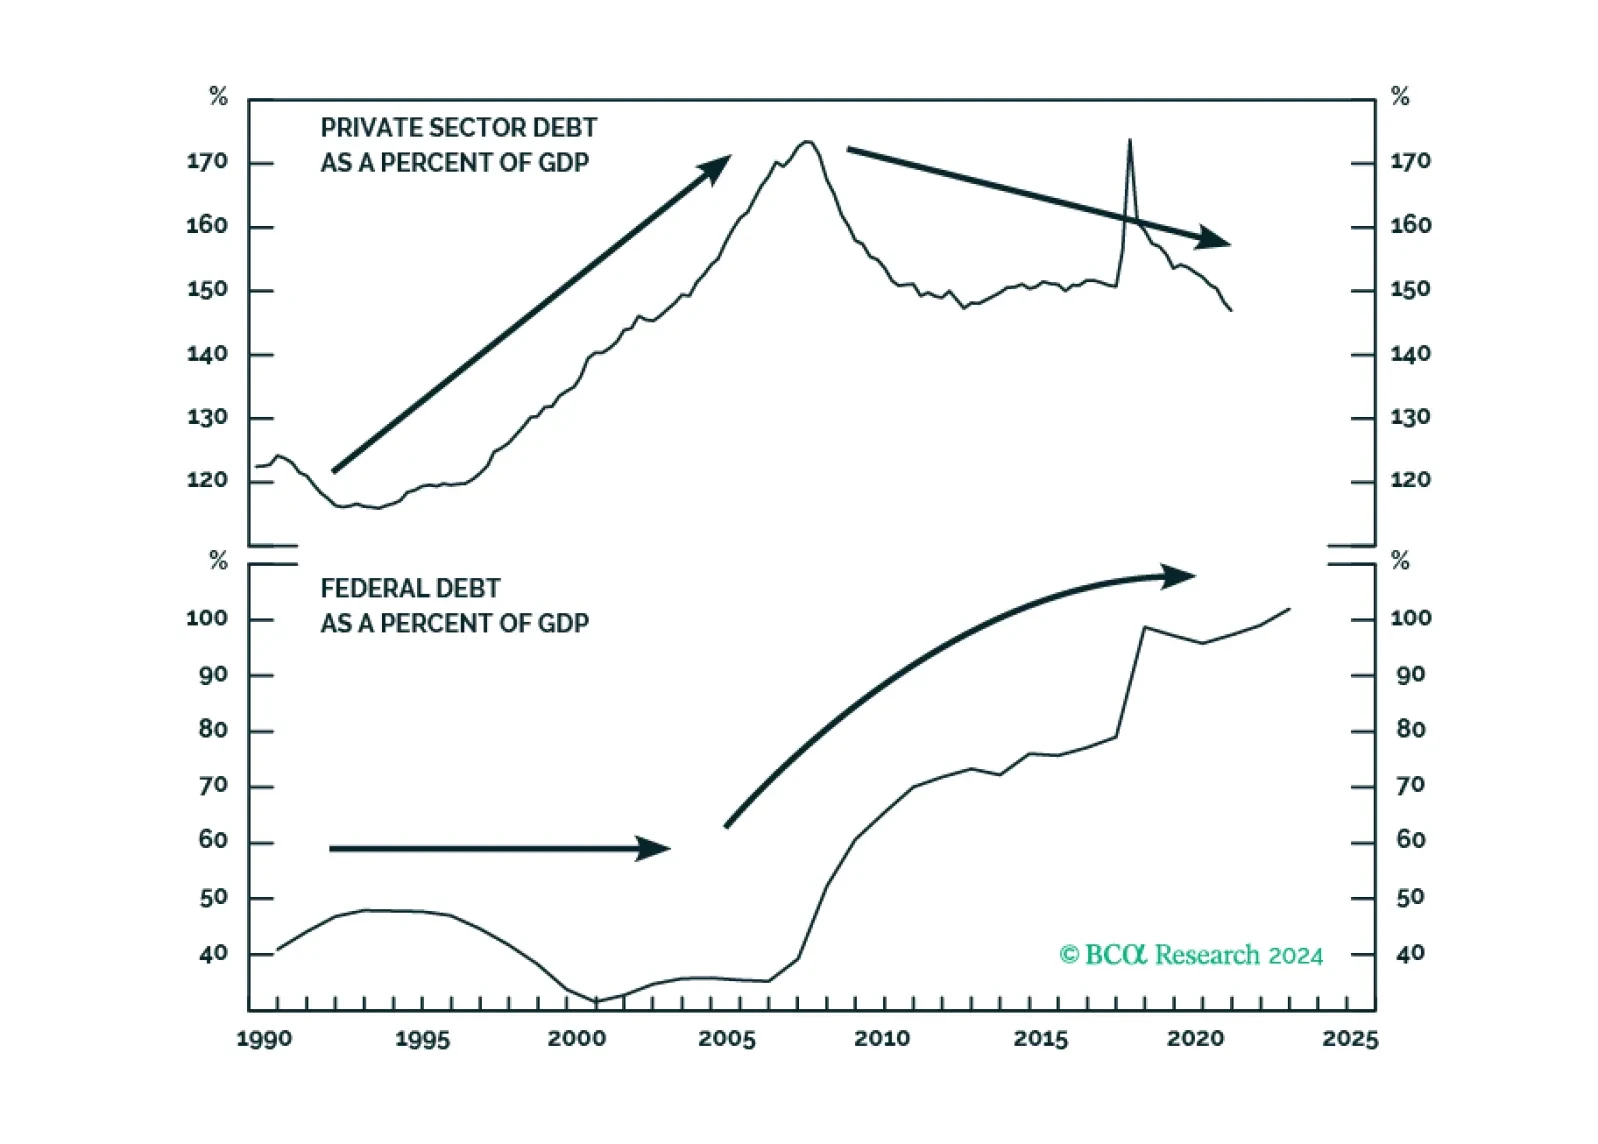
The US economy is in the “Overheating” phase, so stronger growth brings higher inflation. Tight monetary policy means recession is still likely over the next 12 months. Stay defensive.
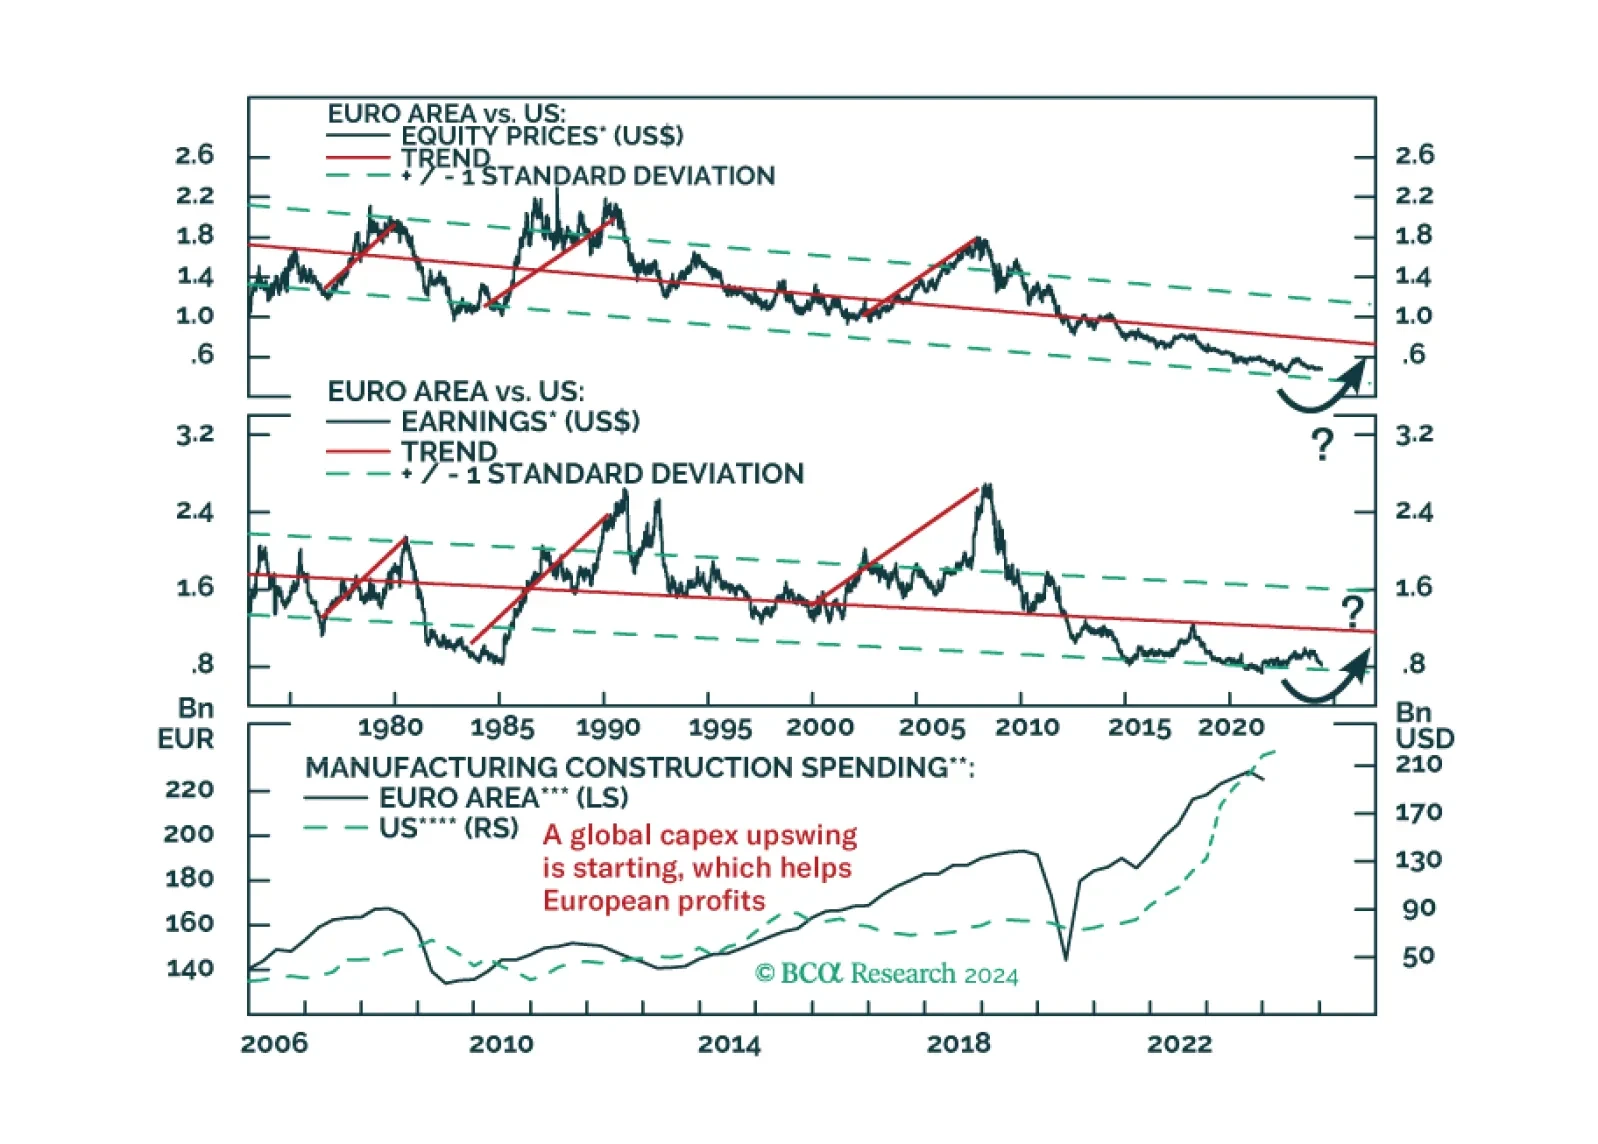
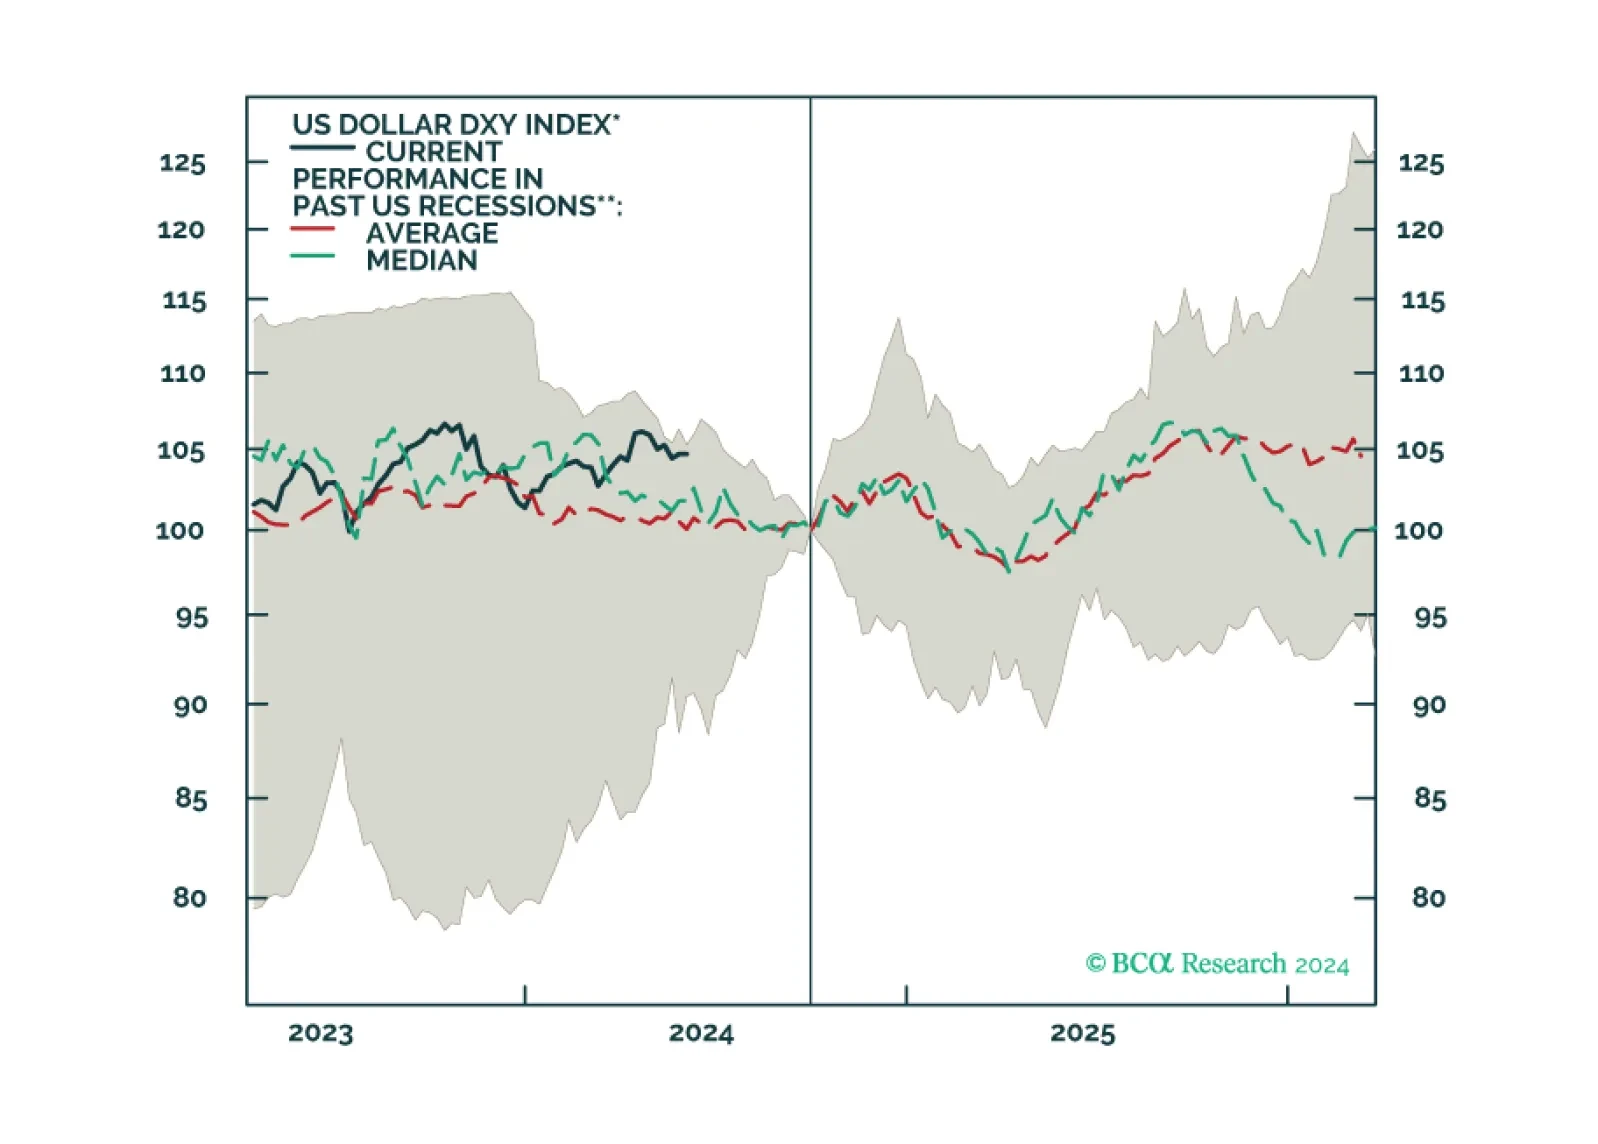
In this report, we gauge the outlook for the dollar given client visits in Africa.
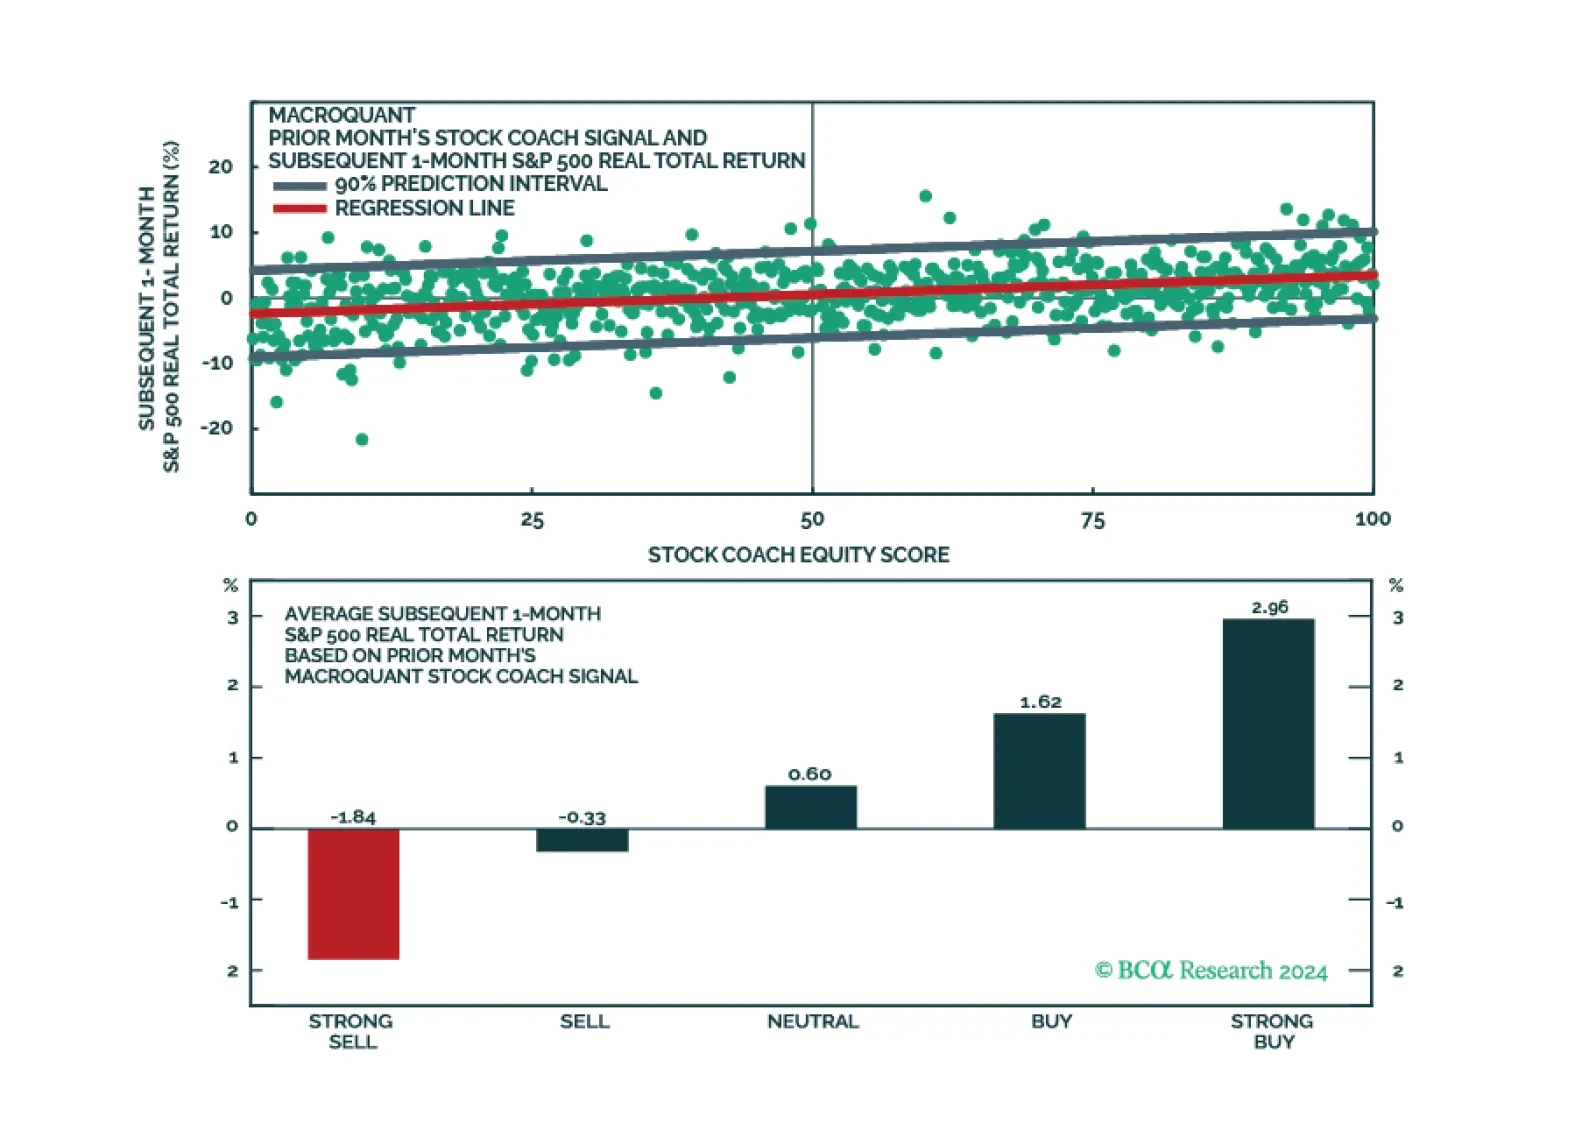
MacroQuant sees significant downside risks to stocks over a 1-to-3 month horizon and suggests increasing allocation to long-term bonds. The model favours defensive equity sectors but is also hedging its bets by overweighting materials.
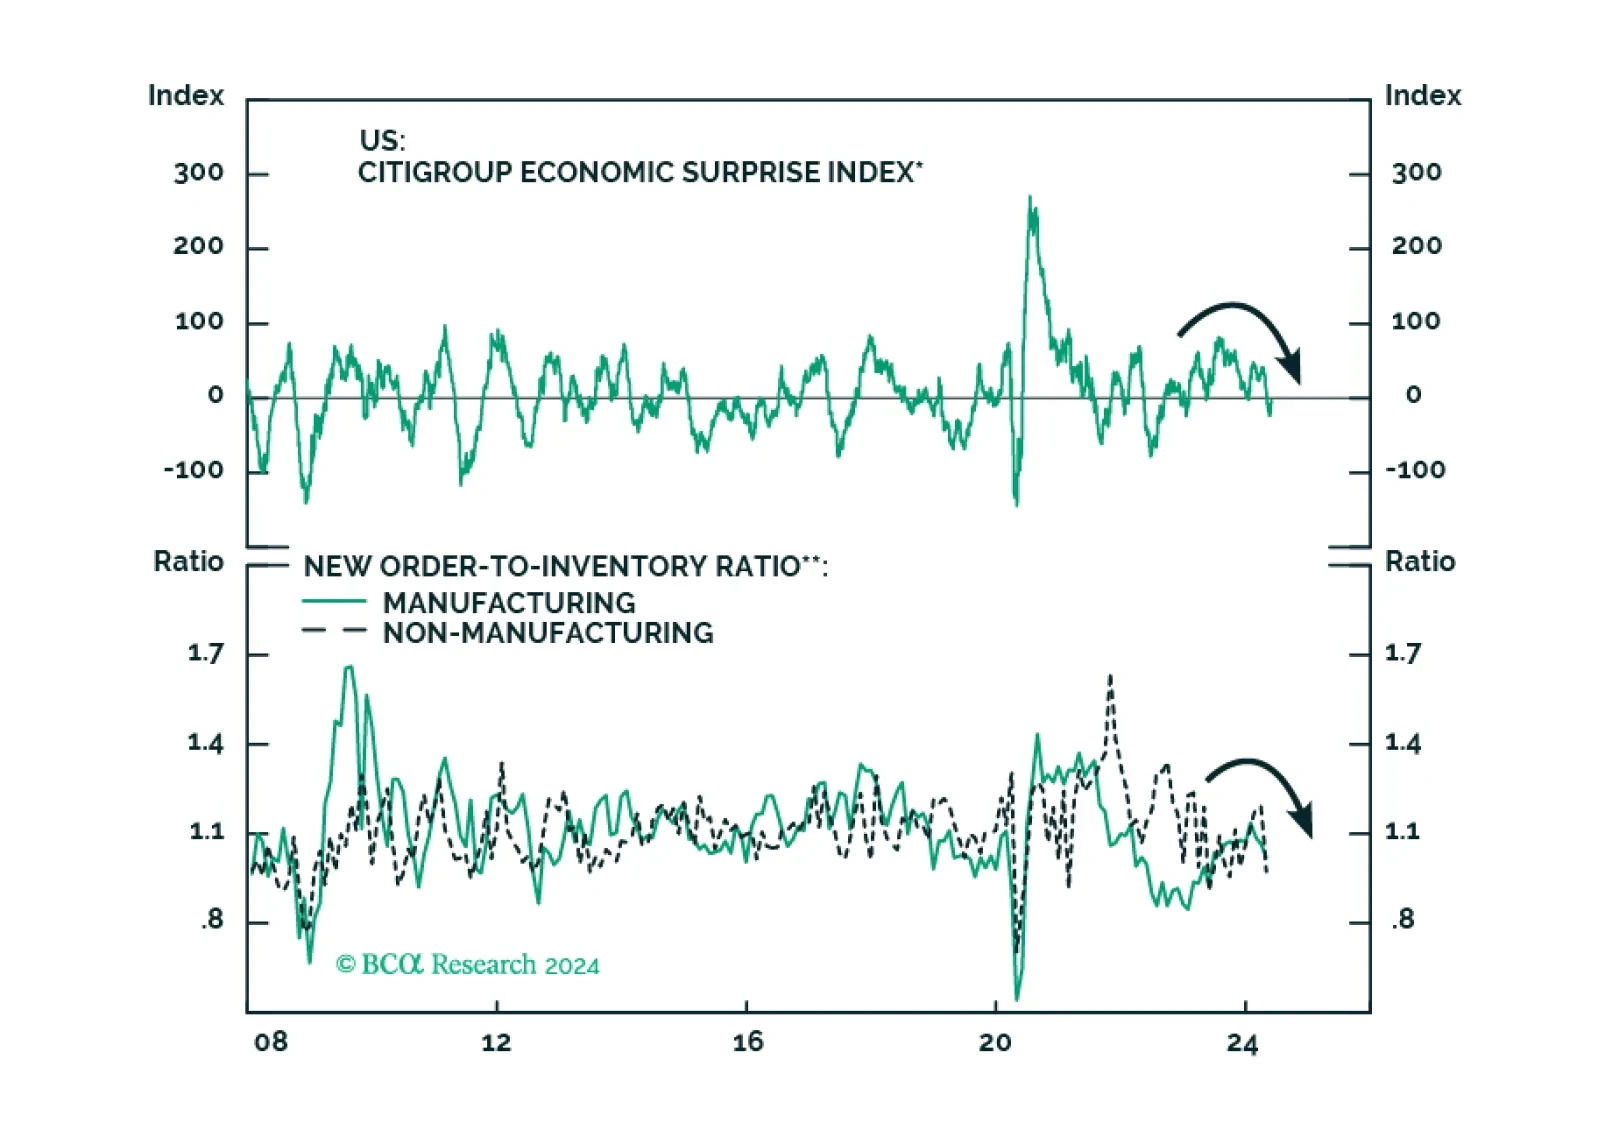
Democrats remain slightly favored for the White House because they are the four-year incumbent presidential party and the economy is not in recession. But if the unemployment rate rises in the lead up to November, then Biden and Democrats will become disfavored regardless of Trump’s convictions.
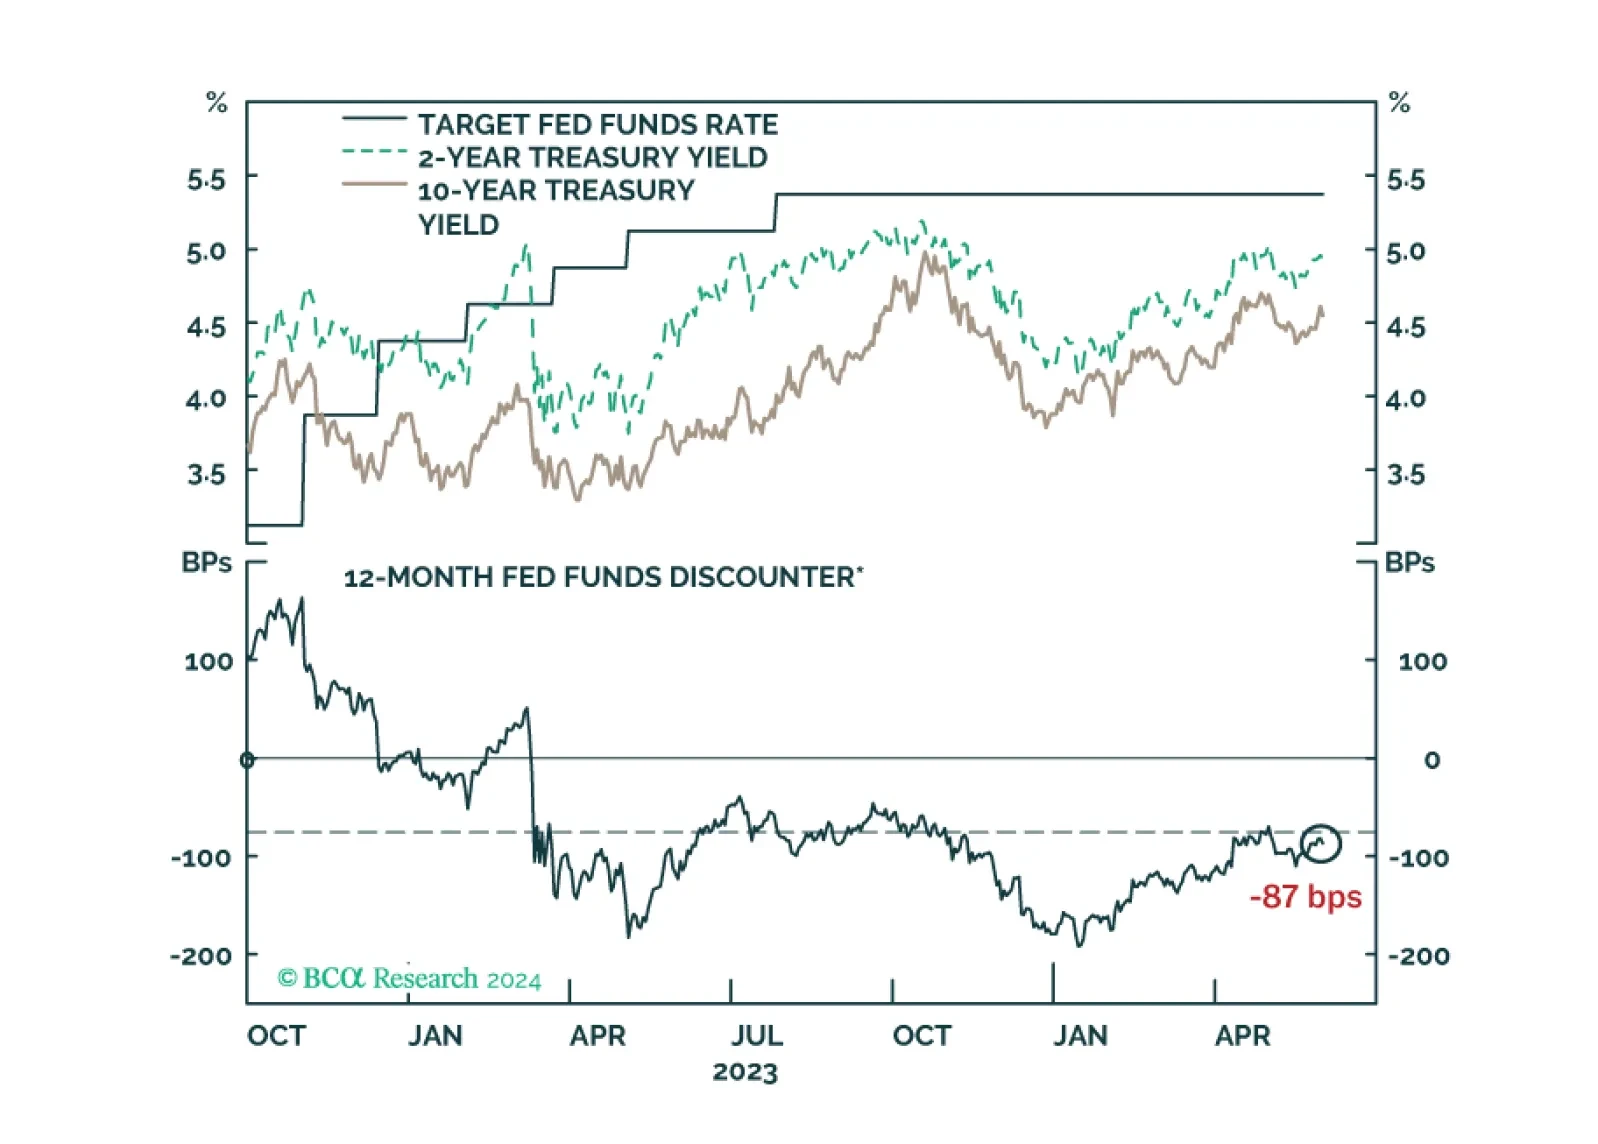
We comment on whether Treasury market valuation is sufficiently attractive to get long bonds and consider some of the common arguments for why yields may yet make new highs.
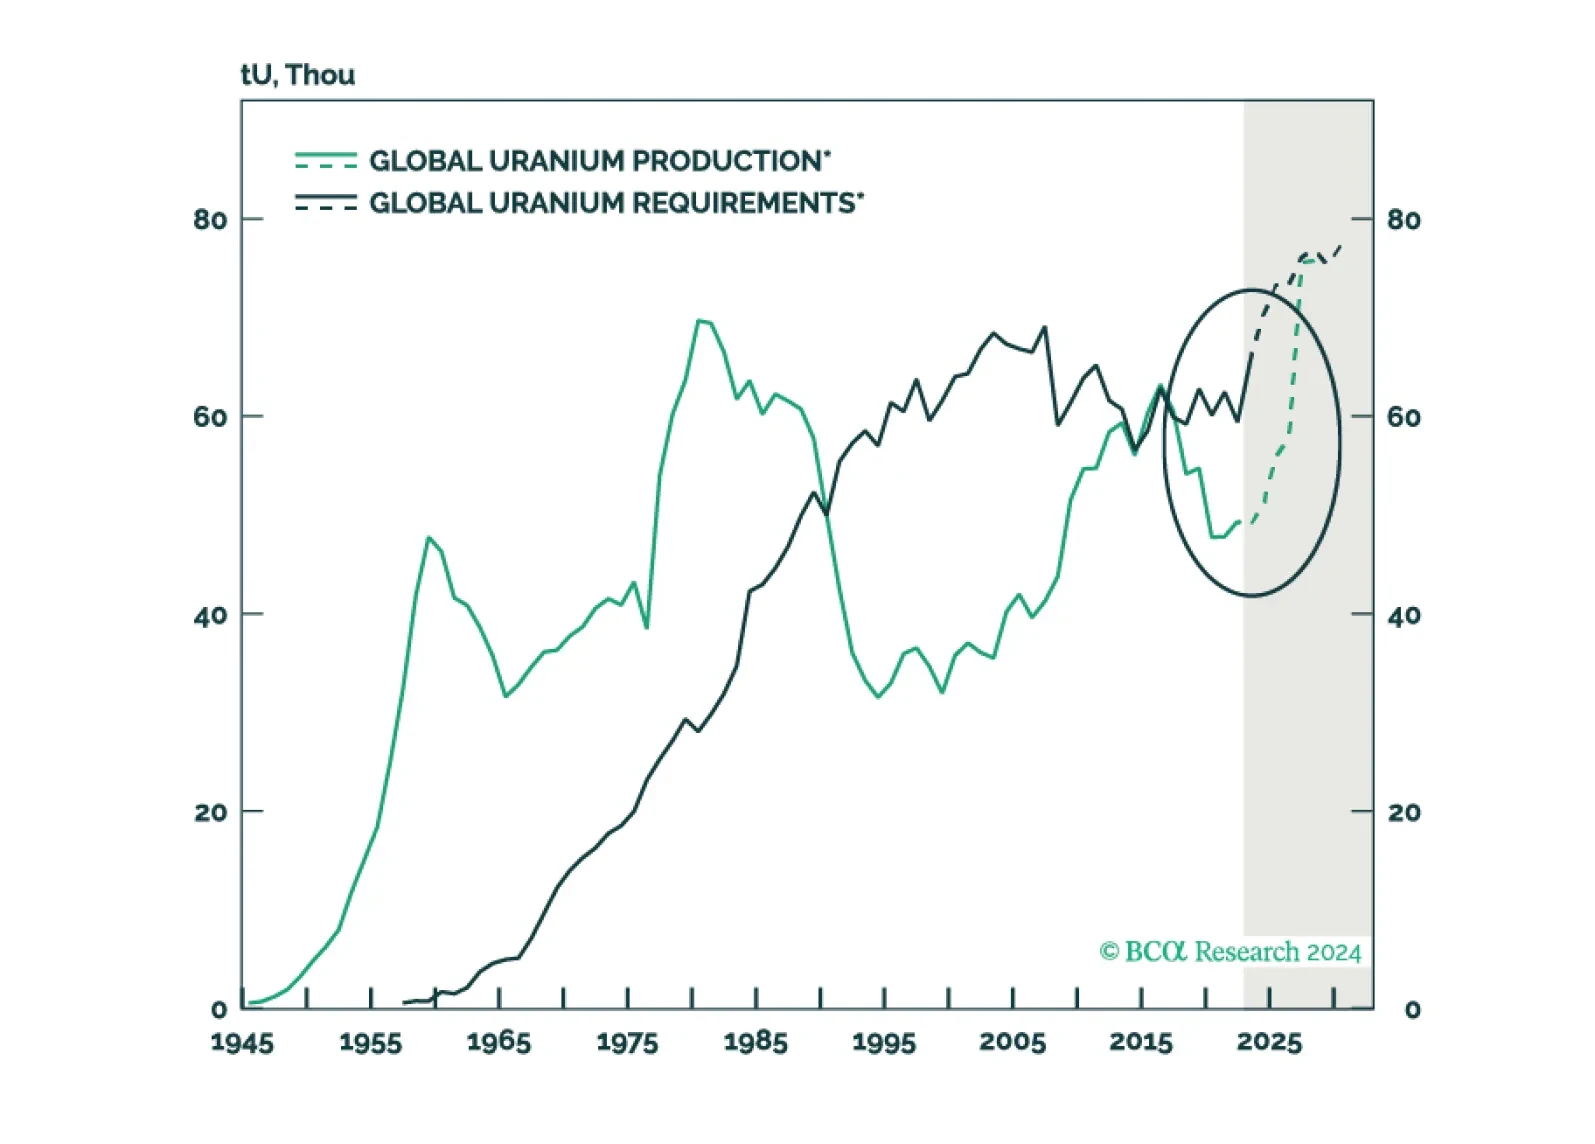
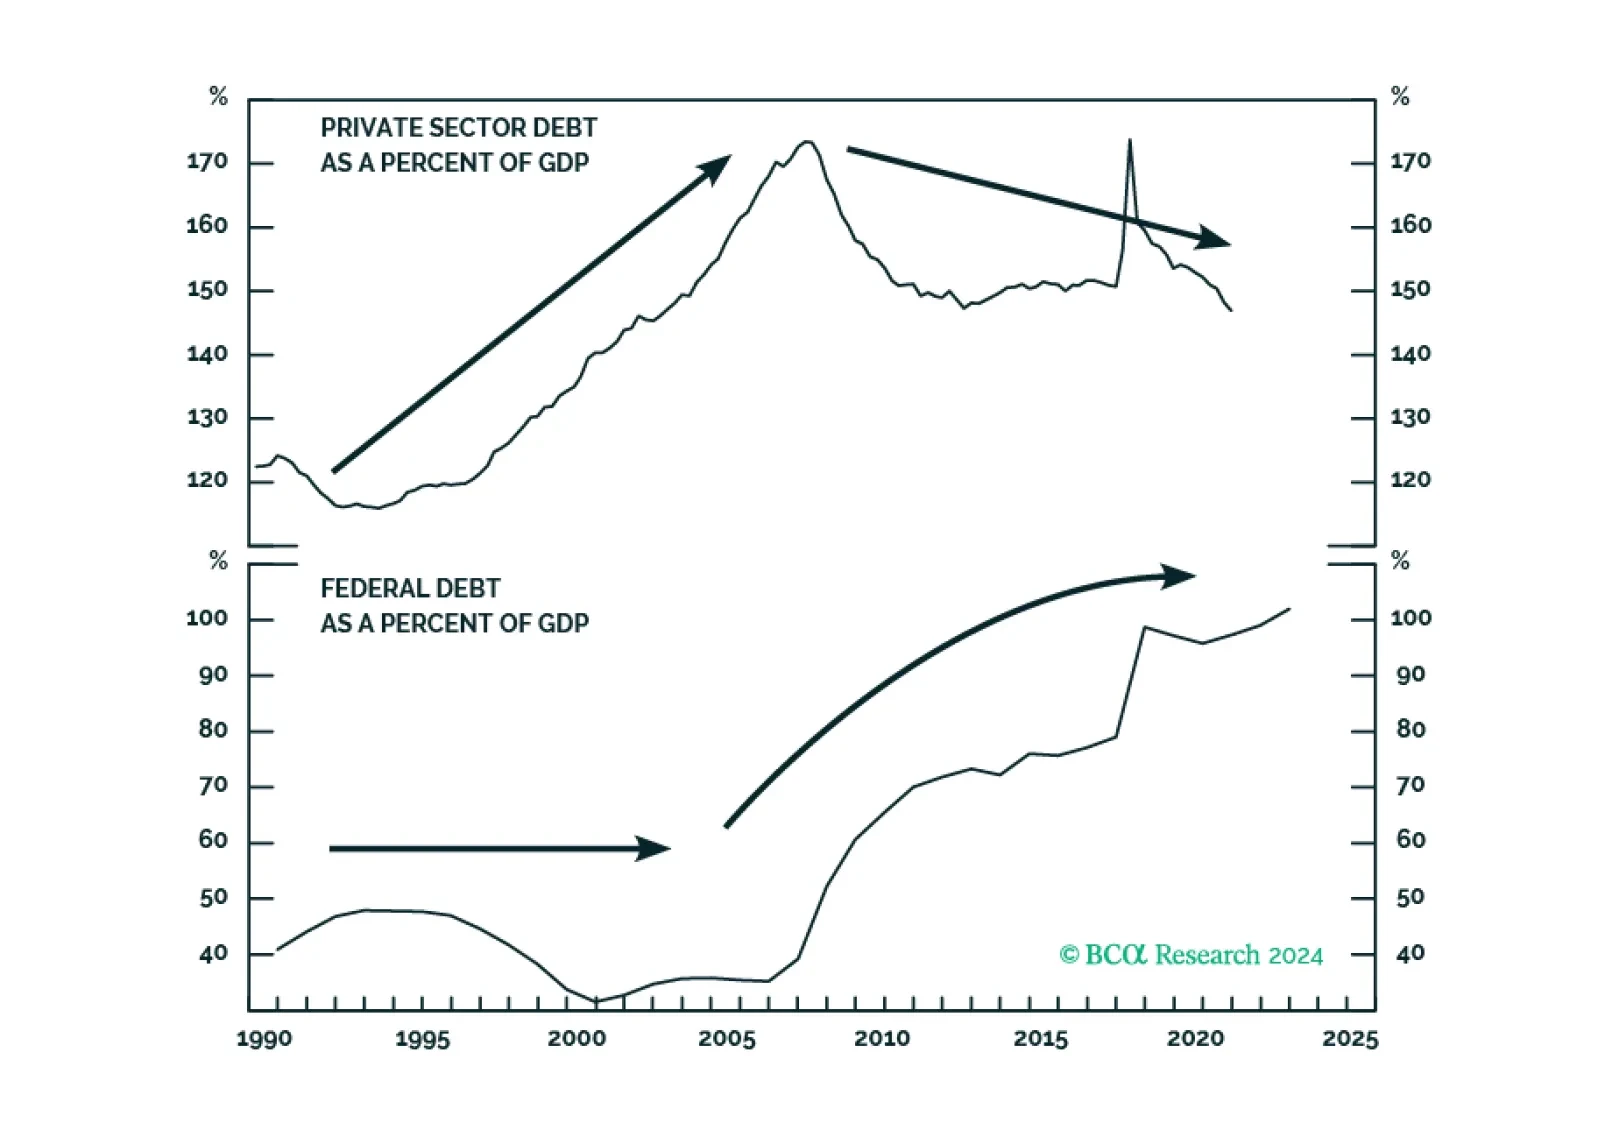
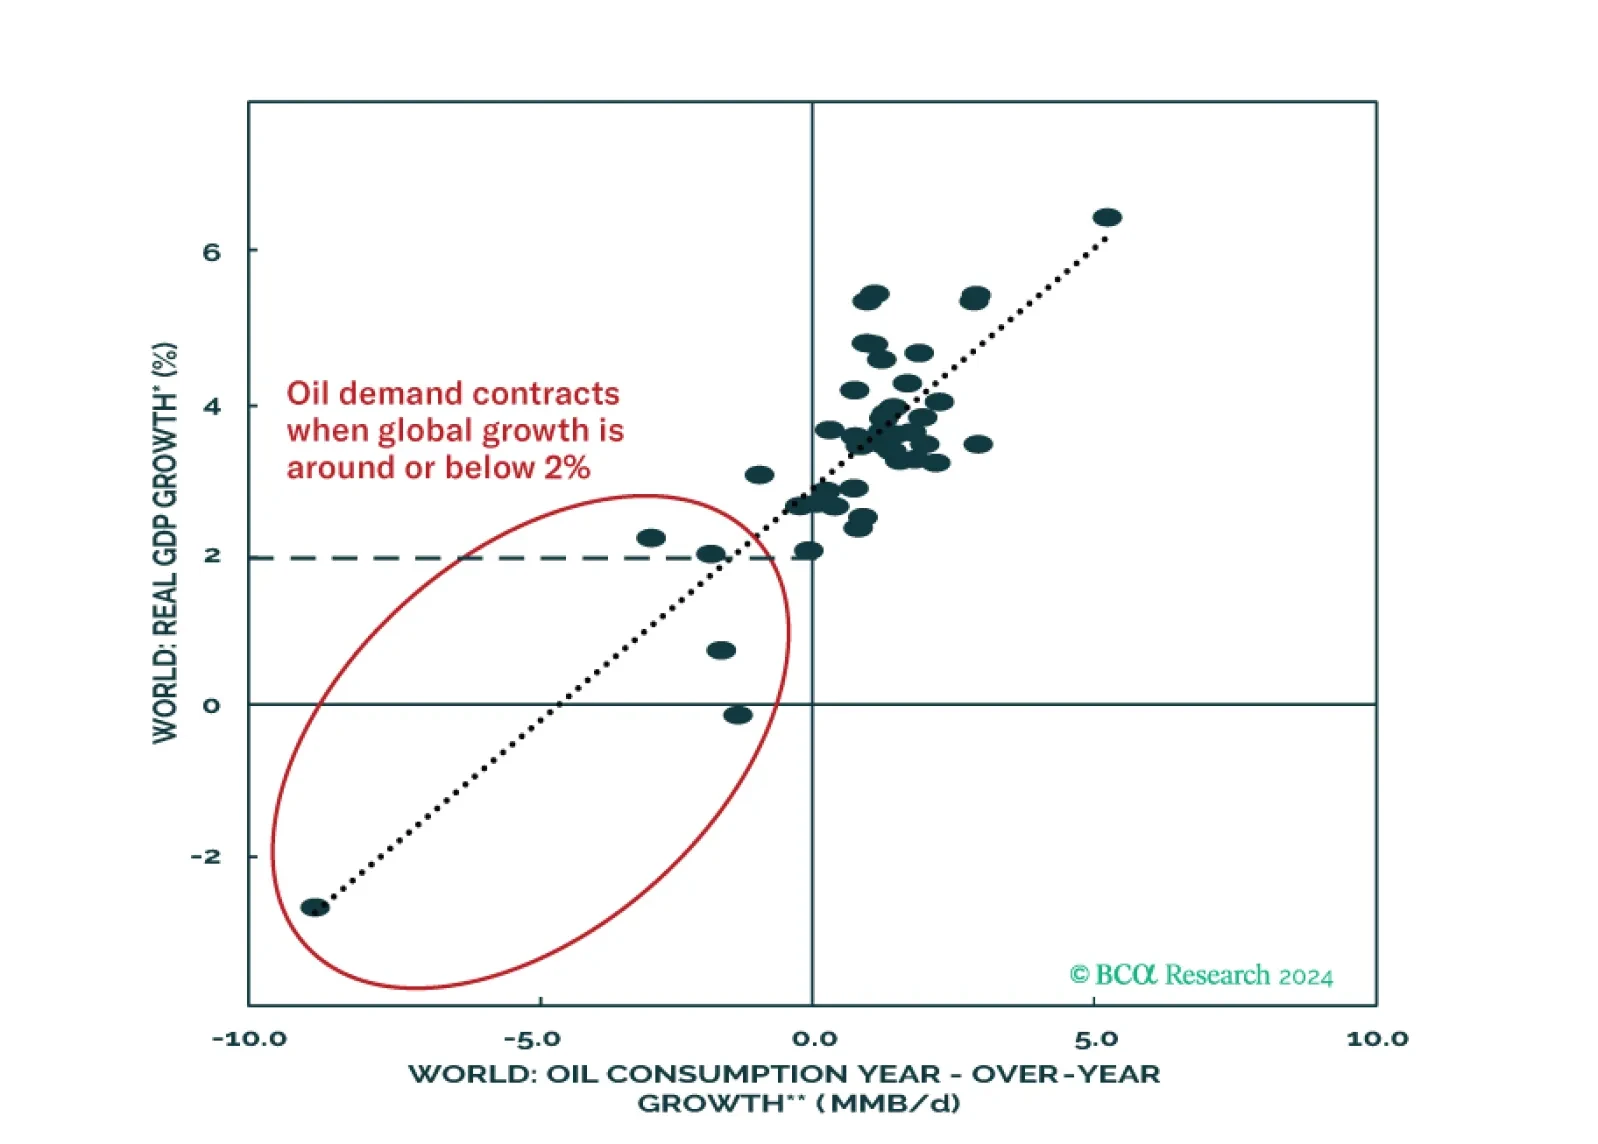
The three major oil forecasters – IEA, EIA, and OPEC – are forecasting oil demand growth until 2025 to be broadly in line with its range over the past four decades. On a cyclical horizon, we give high odds that a recession will begin within the coming 6-12 months, disappointing these oil demand forecasts. On a strategic horizon, the IEA projects EVs will displace 9% of global oil demand by 2035, serving as a long-term demand headwind.