Latest from BCA Research
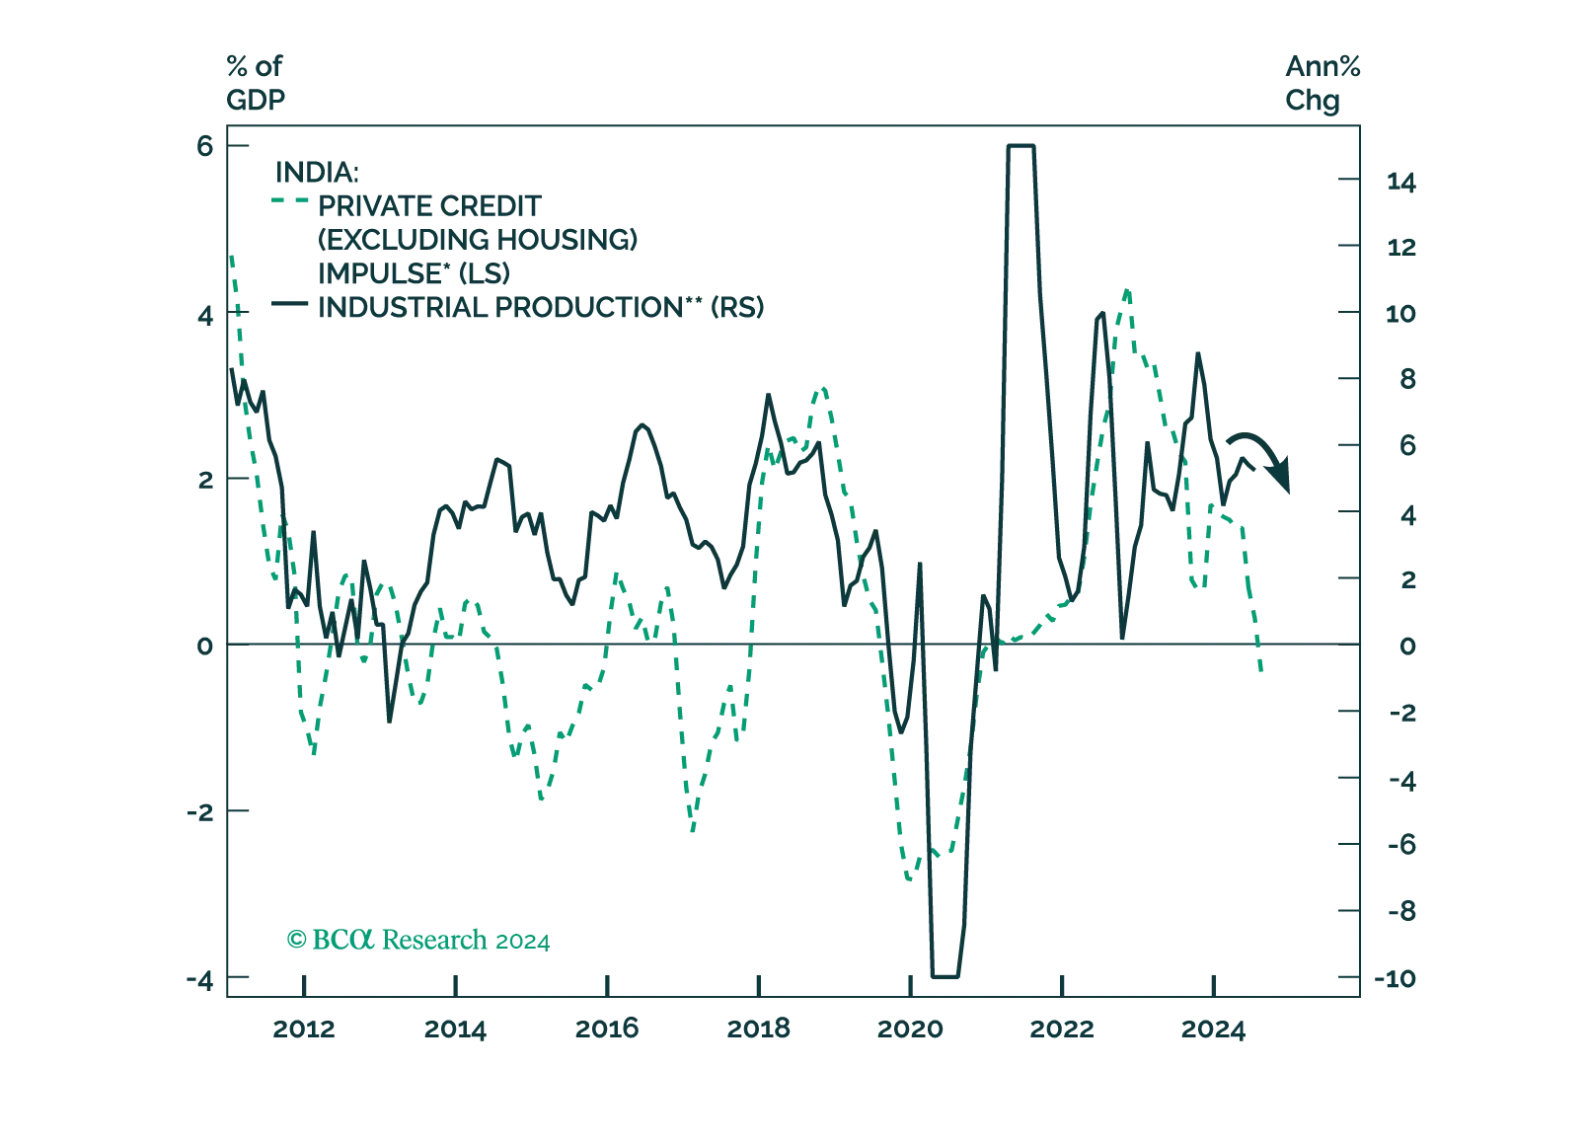
India’s credit impulse has turned negative. Government spending is contracting. The country’s growth will remain subdued; and both drivers of stock prices – profits and multiples – are headed lower at a time when equity valuations are at a record high.
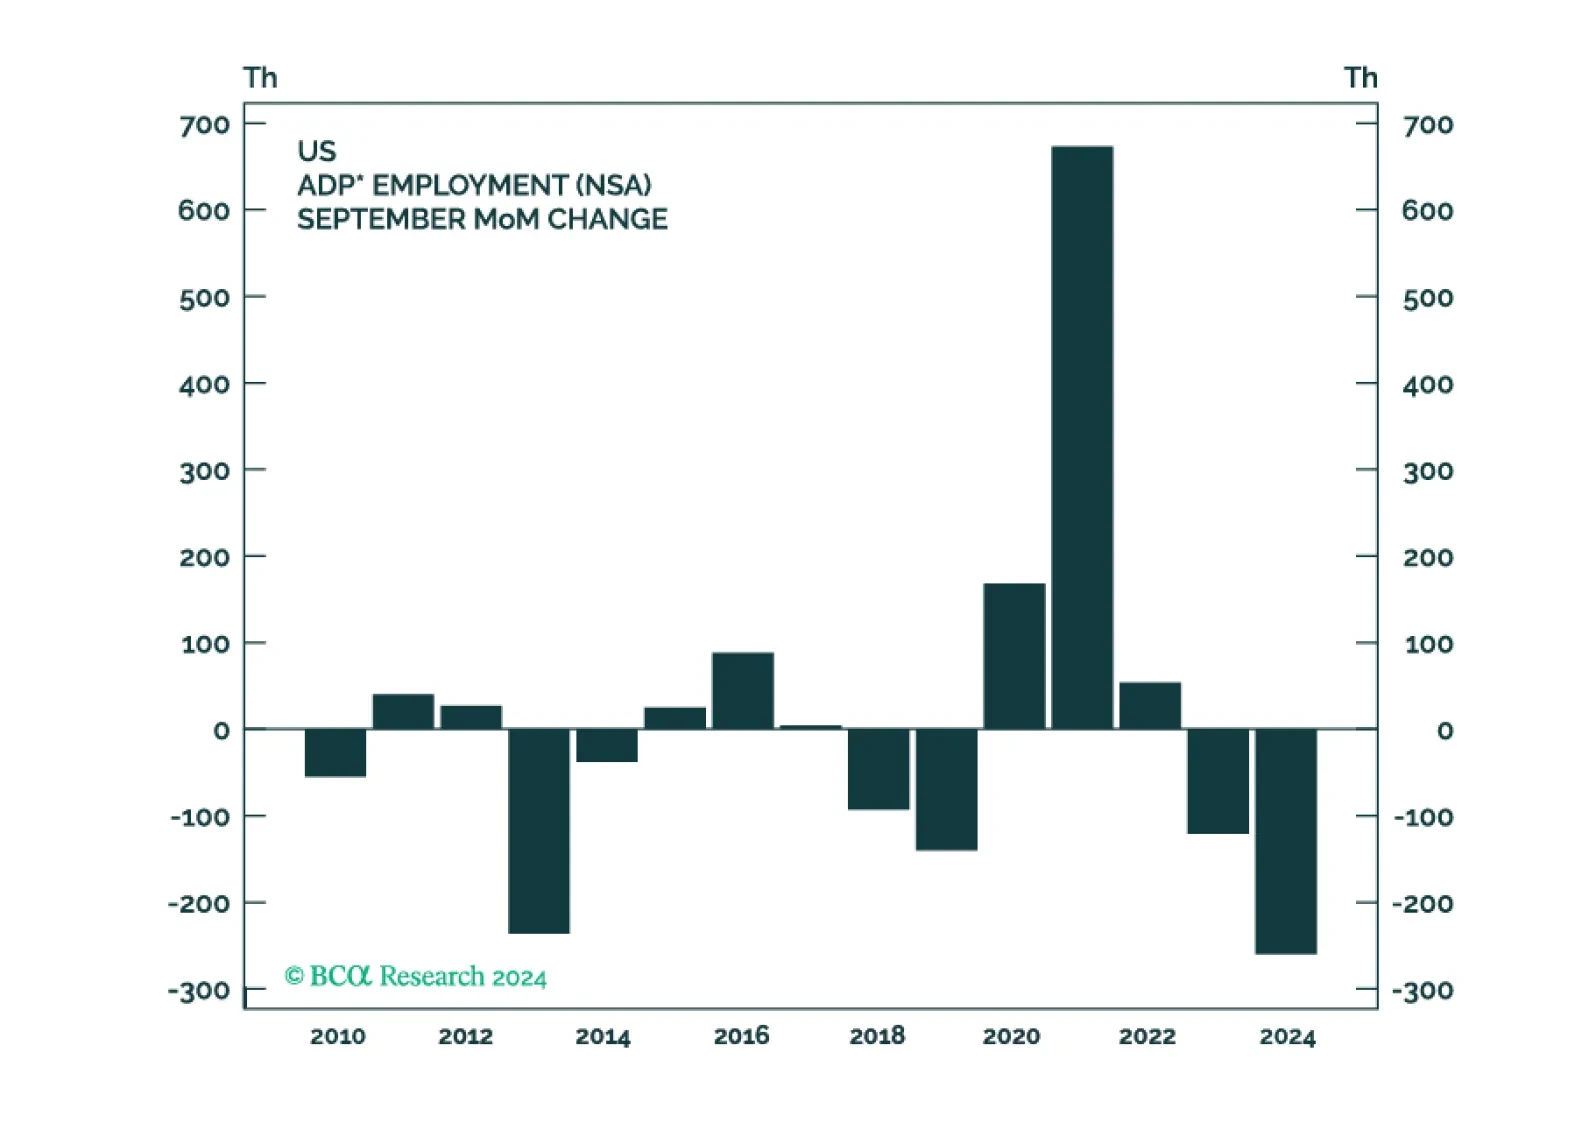
I am not one to dismiss the ADP report. Unlike the establishment survey, the ADP numbers are based on hard data. If the ADP is not a reliable guide to the government’s payrolls estimates, maybe that is because the government’s payroll estimates are not a reliable guide to actual payrolls.
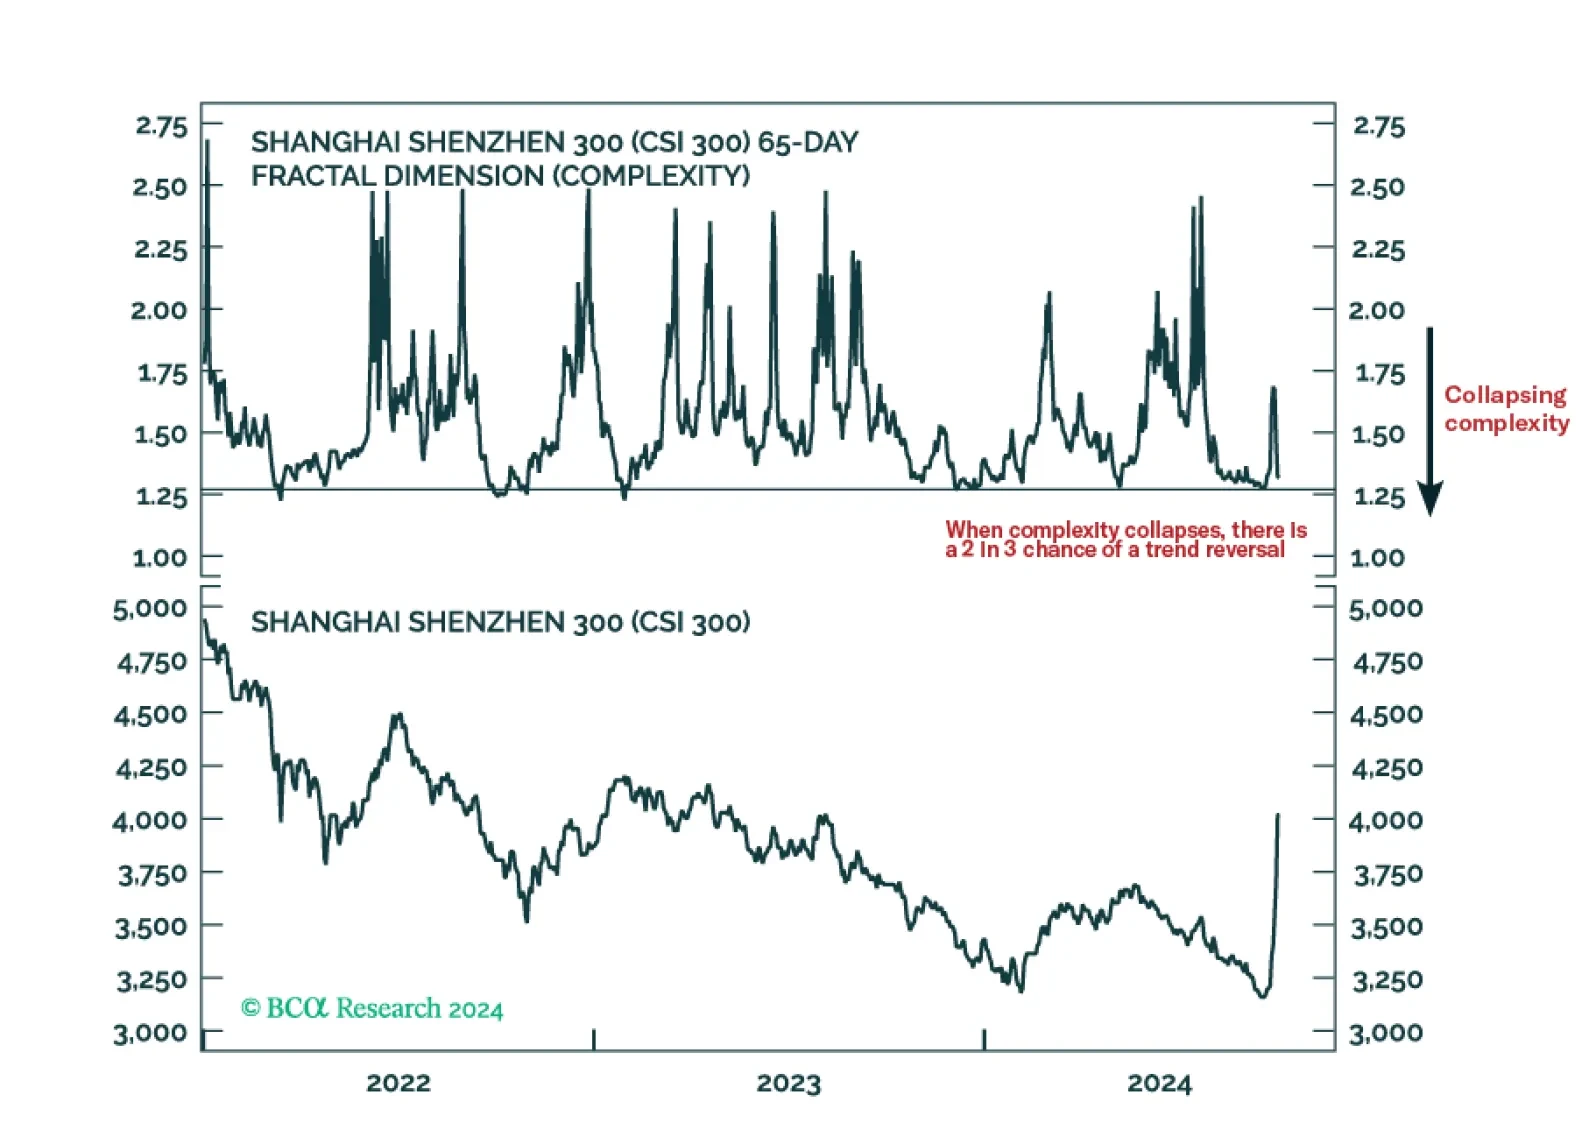
Absent the multi-decade housing and construction boom, China will be unable to generate the monster credit impulses that it did through 2000-20. Hence, the recent melt-up in Chinese stocks and China plays may last a few weeks more but is unlikely to be a rerun of the 2015 episode either in magnitude or in duration. We go through the tactical and longer-term investment implications. Plus, a new recommendation on a 6-month horizon is to go long USD/GBP.
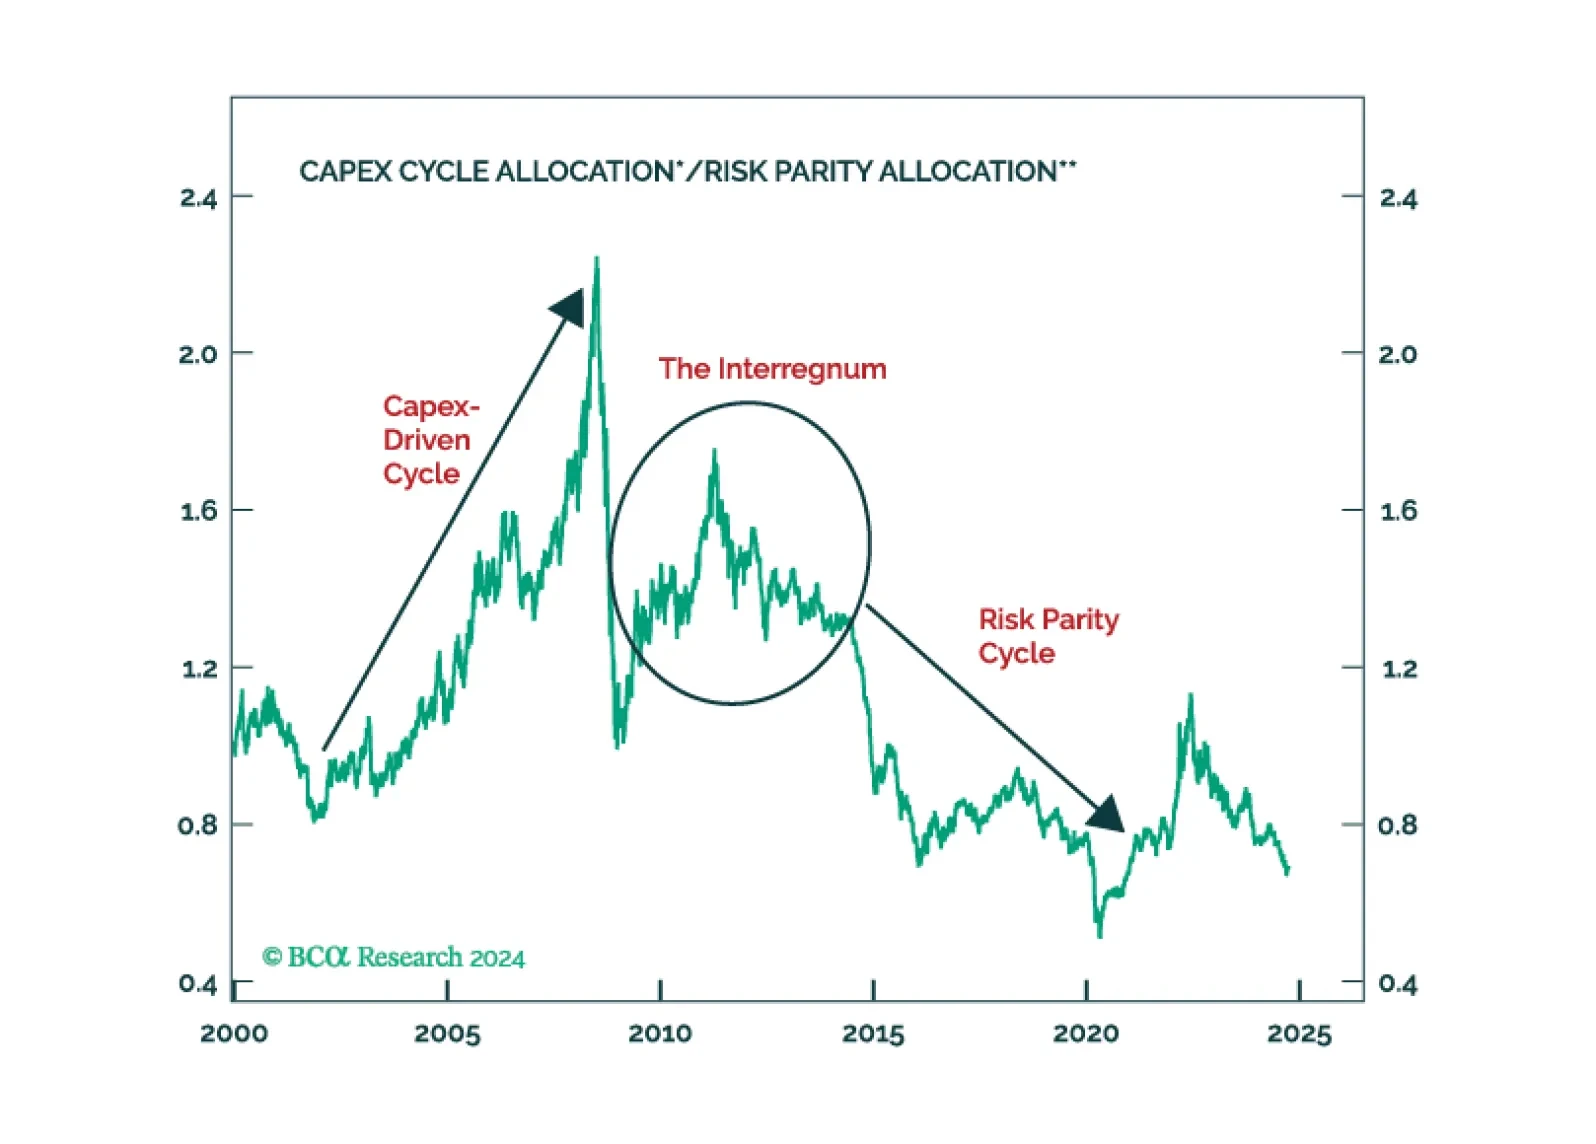
Western policymakers are pursuing three capital “T” Truths: China is evil, climate change is a major risk, and Russia is… also evil. Pursuing all three priorities at the same time presents a version of the classic “impossible trinity.”
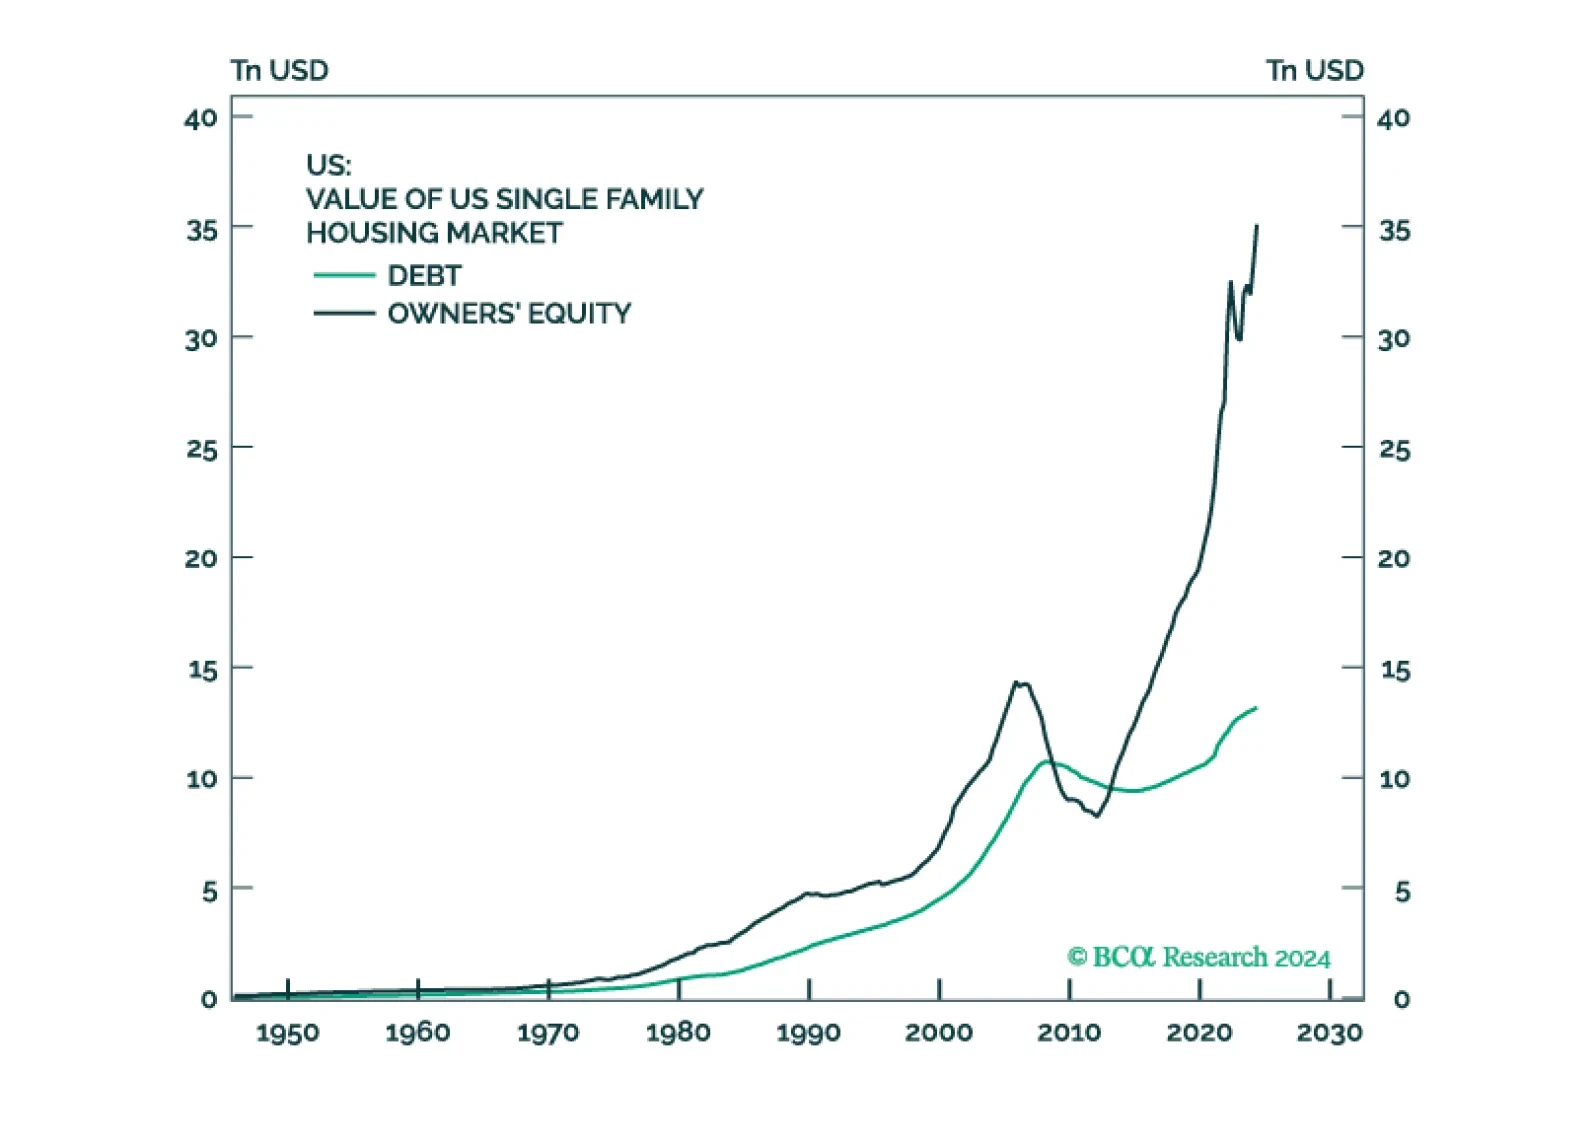
October seasonality tends to be negative for stocks in an election year. That is the only thing that has stayed our hand from shifting out of our tactical underweight on US equities, initiated – poorly – in July. But the big macro news from September has not been bearish. The Fed has signaled jumbo cuts. Within seven weeks, the US central bank intends to cut by 100bps! Meanwhile, China appears to have reached a “policy bottom,” with its September 26 Politburo meeting signaling an extraordinary rhetorical shift towards fiscal policy. As such, we are starting to sniff out global reflation, akin to the 2015-2016 mid-cycle slowdown. The labor market data still worries us. It is clearly deteriorating, on paper. Is it because of an imminent recession or “normalization?” It is difficult to say. We are open minded. Finally, the Middle East tensions are again on the horizon. If Iran stays its hand against Saudi energy facilities – which we expect it to continue to do – the Iran-Israel conflict is a sideshow. Nonetheless, with global reflation afoot, we went long oil last week, on September 26. As such, geopolitics is a neat tailwind to that call.

Our Portfolio Allocation Summary for October 2024.

The politically induced selloff in Mexican markets has gone too far. In our view, investor fears about the constitutional changes are largely unwarranted. These reforms will have little to no ramifications for the economy in the foreseeable future, and it is not clear to what extent they can undermine Mexican democracy. Moreover, the market riot is not justified by the country’s decent macro shape. All in all, Mexican markets will resume their outperformance versus their EM peers sooner rather than later.
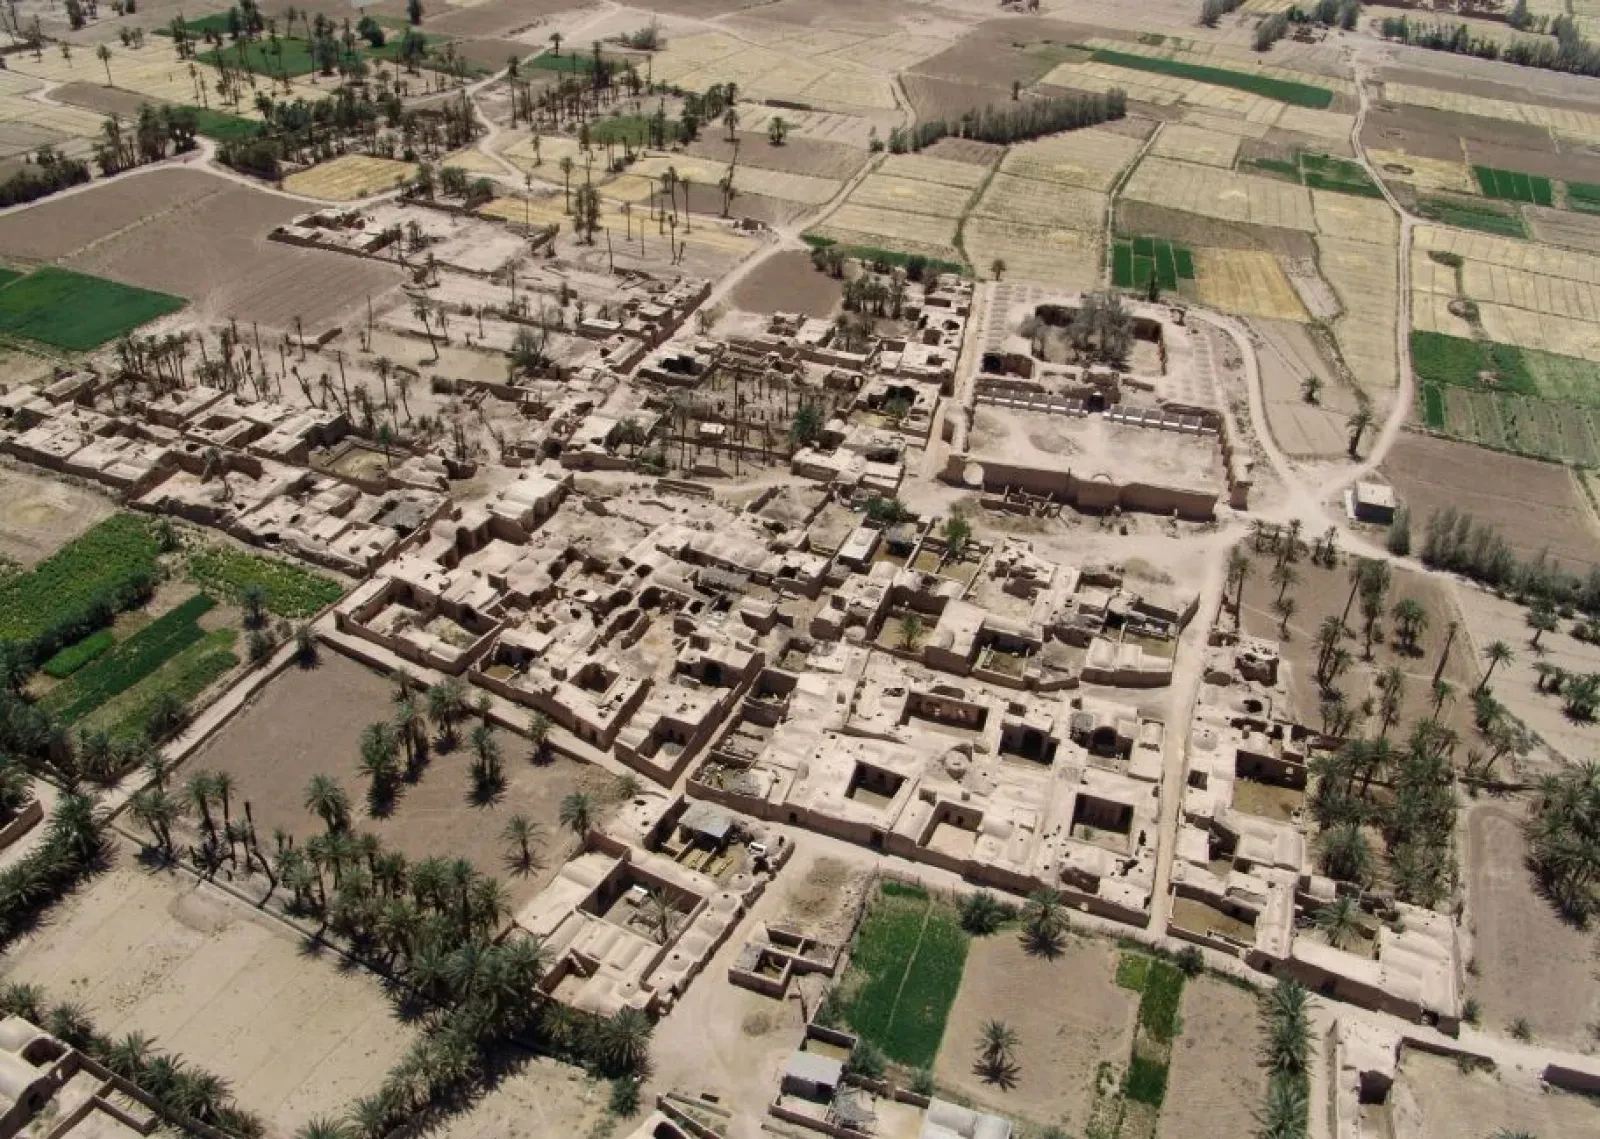
Iran has launched a salvo of ballistic missiles towards Israel on October 1 in retaliation for Israeli ground invasion against Lebanon. Thus far, the attack looks to be a bit different from the attack in April, with ballistic missiles making up the bulk of the reported projectiles. This means that the emphasis on drones, which were highly unsuccessful, has been replaced with an emphasis on missiles.
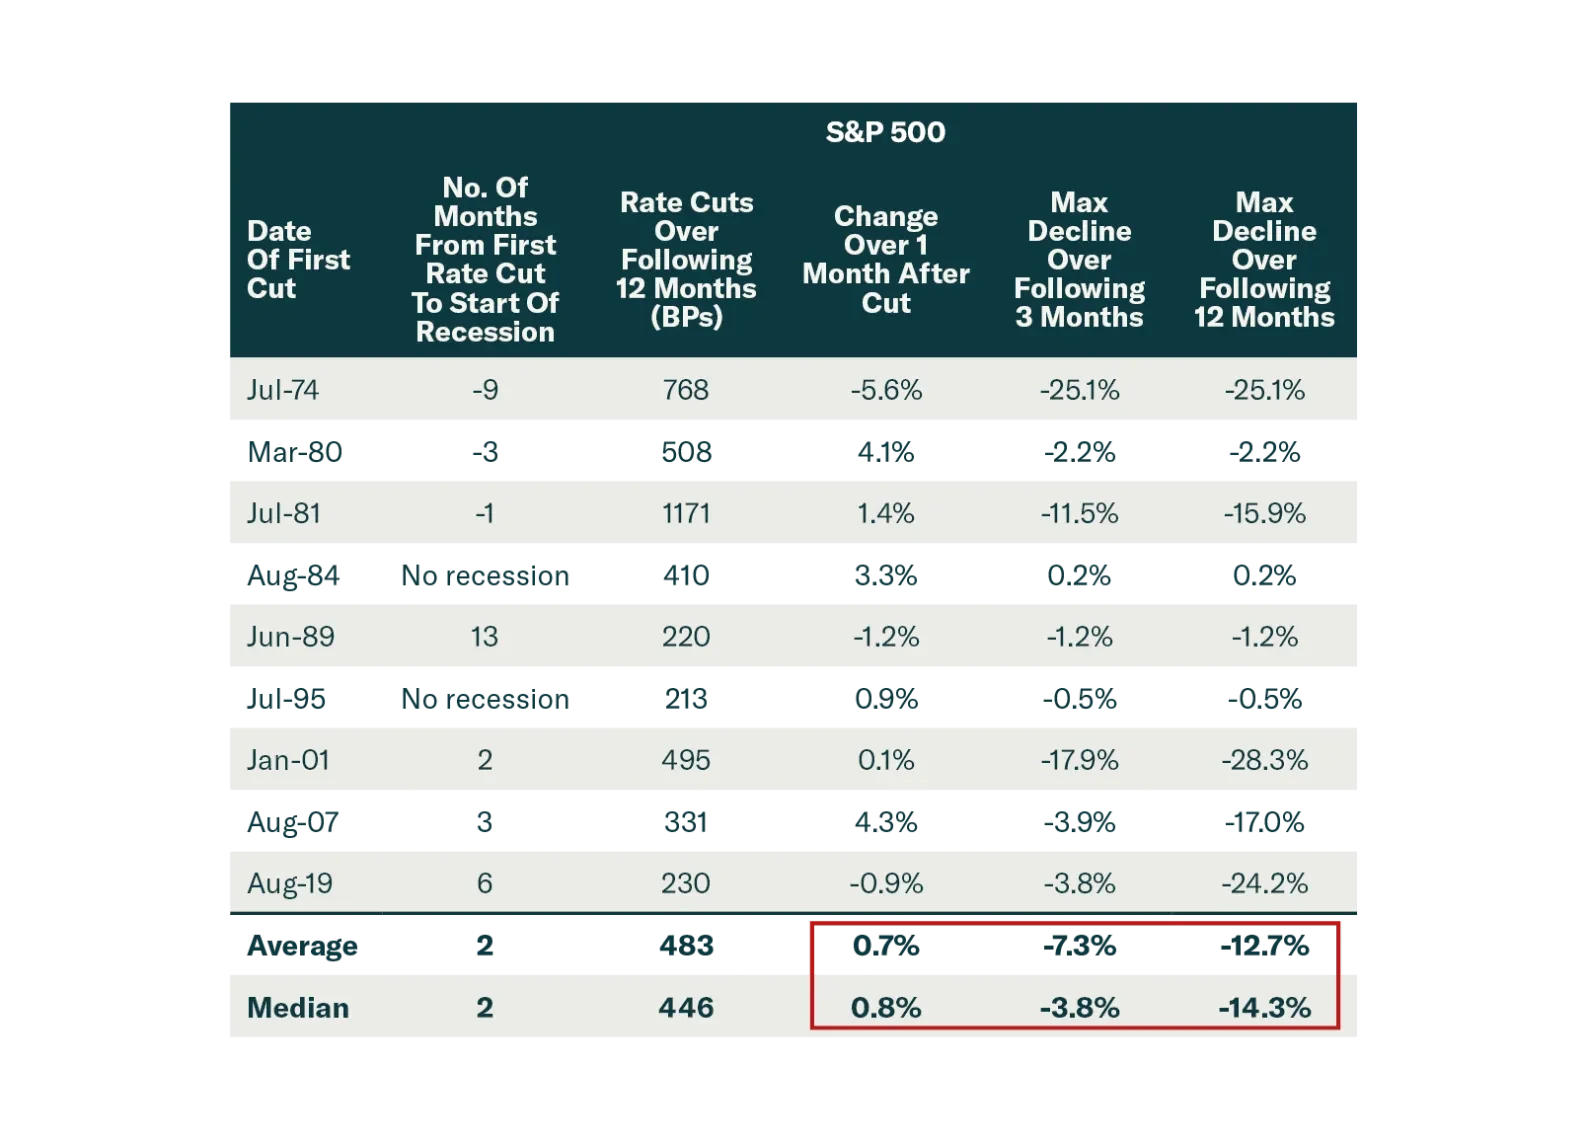
The market got excited by the 50 bps Fed cut and China stimulus. But these are a recognition that economies are slowing significantly. Stocks often rally after the first Fed cut, before falling sharply. Investors should stay defensive.