Skip to main content

Developed Countries

The UK unemployment rate surprised to the upside in the 3-month period ending in April, ticking up to 4.4% against expectations it would remain stable at March’s originally reported 4.3%. Concurrently, wage growth remains elevated. The 3-month measure of…
The Eurozone Sentix Economic index improved from -3.6 to 0.3 in June, easily surpassing expectations of a more muted improvement to -1.7. Notably, the Expectation and Current Situation subindices rose to 28-month and 13-month highs of 10 and -9, respectively.…
The NFIB’s Small Business Optimism (SBO) Index came in at 90.5 in May, above expectations that it would remain flat at 89.7. Despite the upside surprise, the Russell 2000 index closed down 40 basis points on Tuesday while the S&P 500 gained 30 bps to notch…
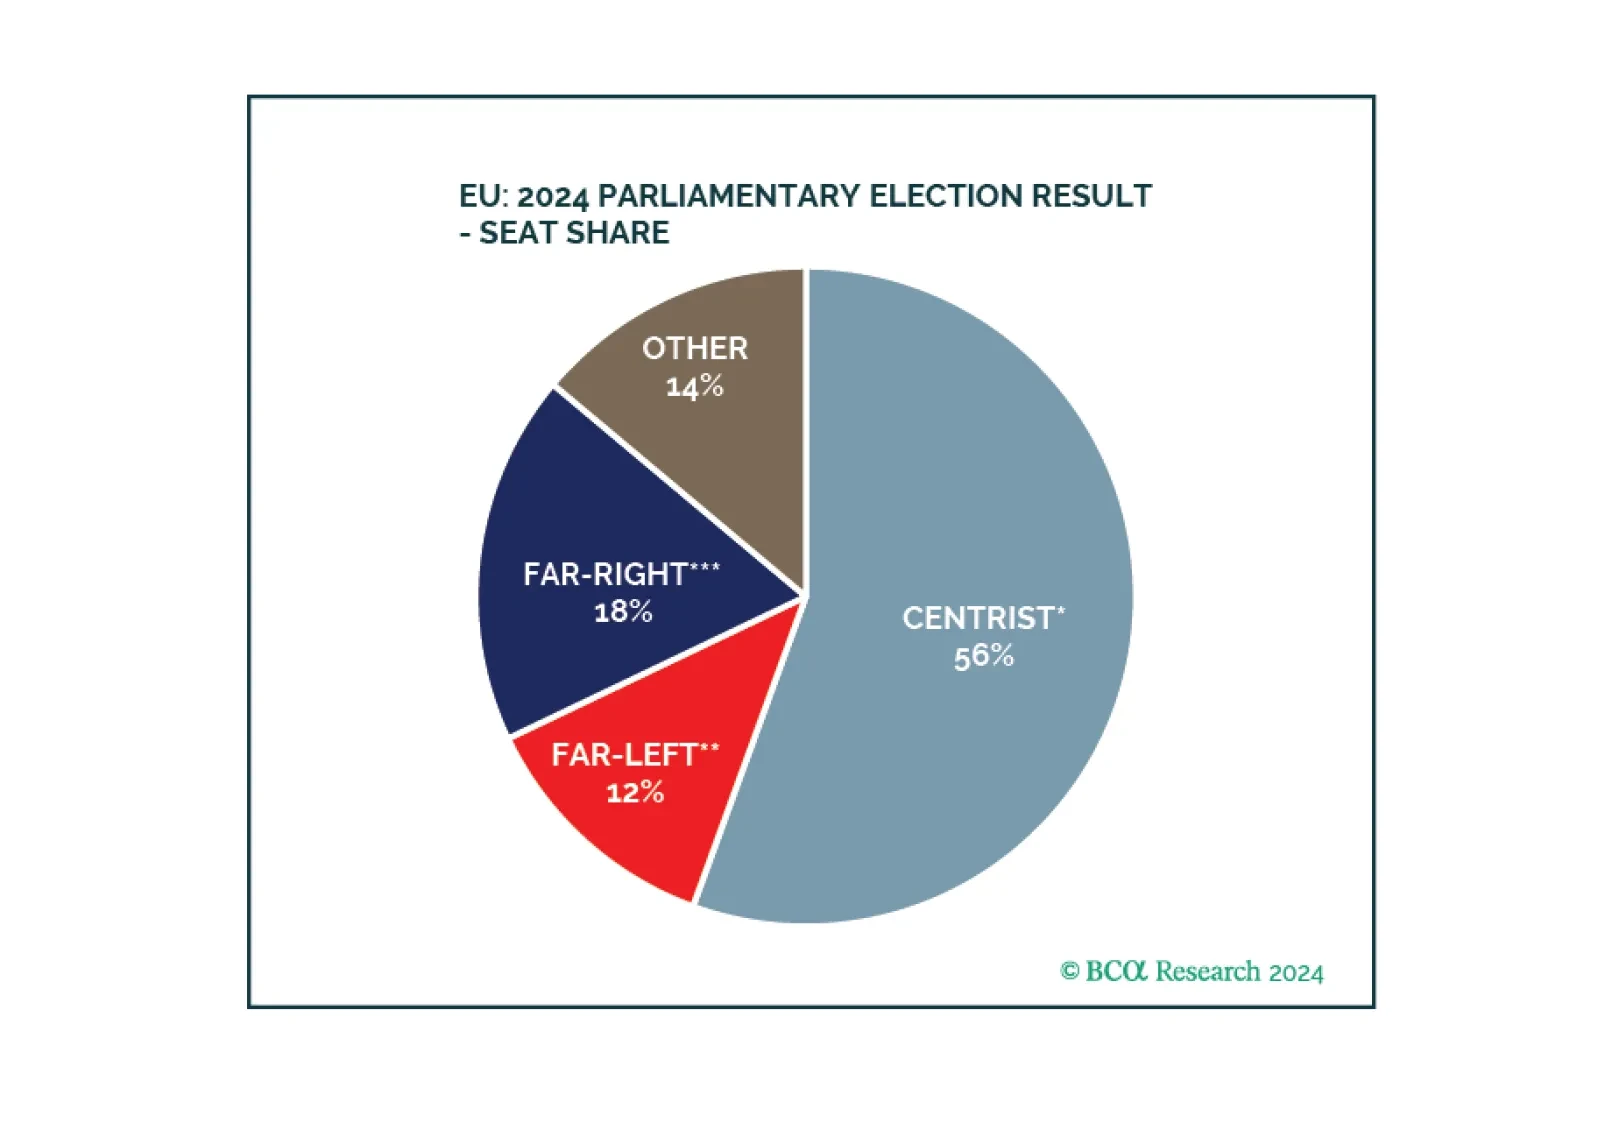
According to BCA Research’s Geopolitical Strategy service, the European parliamentary election was not an earthquake. It saw an improvement in right-leaning political groups and a deterioration in both centrist and left-leaning groups, as expected. European…

Europe did not witness a major policy reversal. Inflationary pressures are coming down, enabling the ECB to cut rates and European states to maintain soft budgets. Geopolitical challenges ensure that European parties continue to cooperate on national defense, economic security, and energy security.
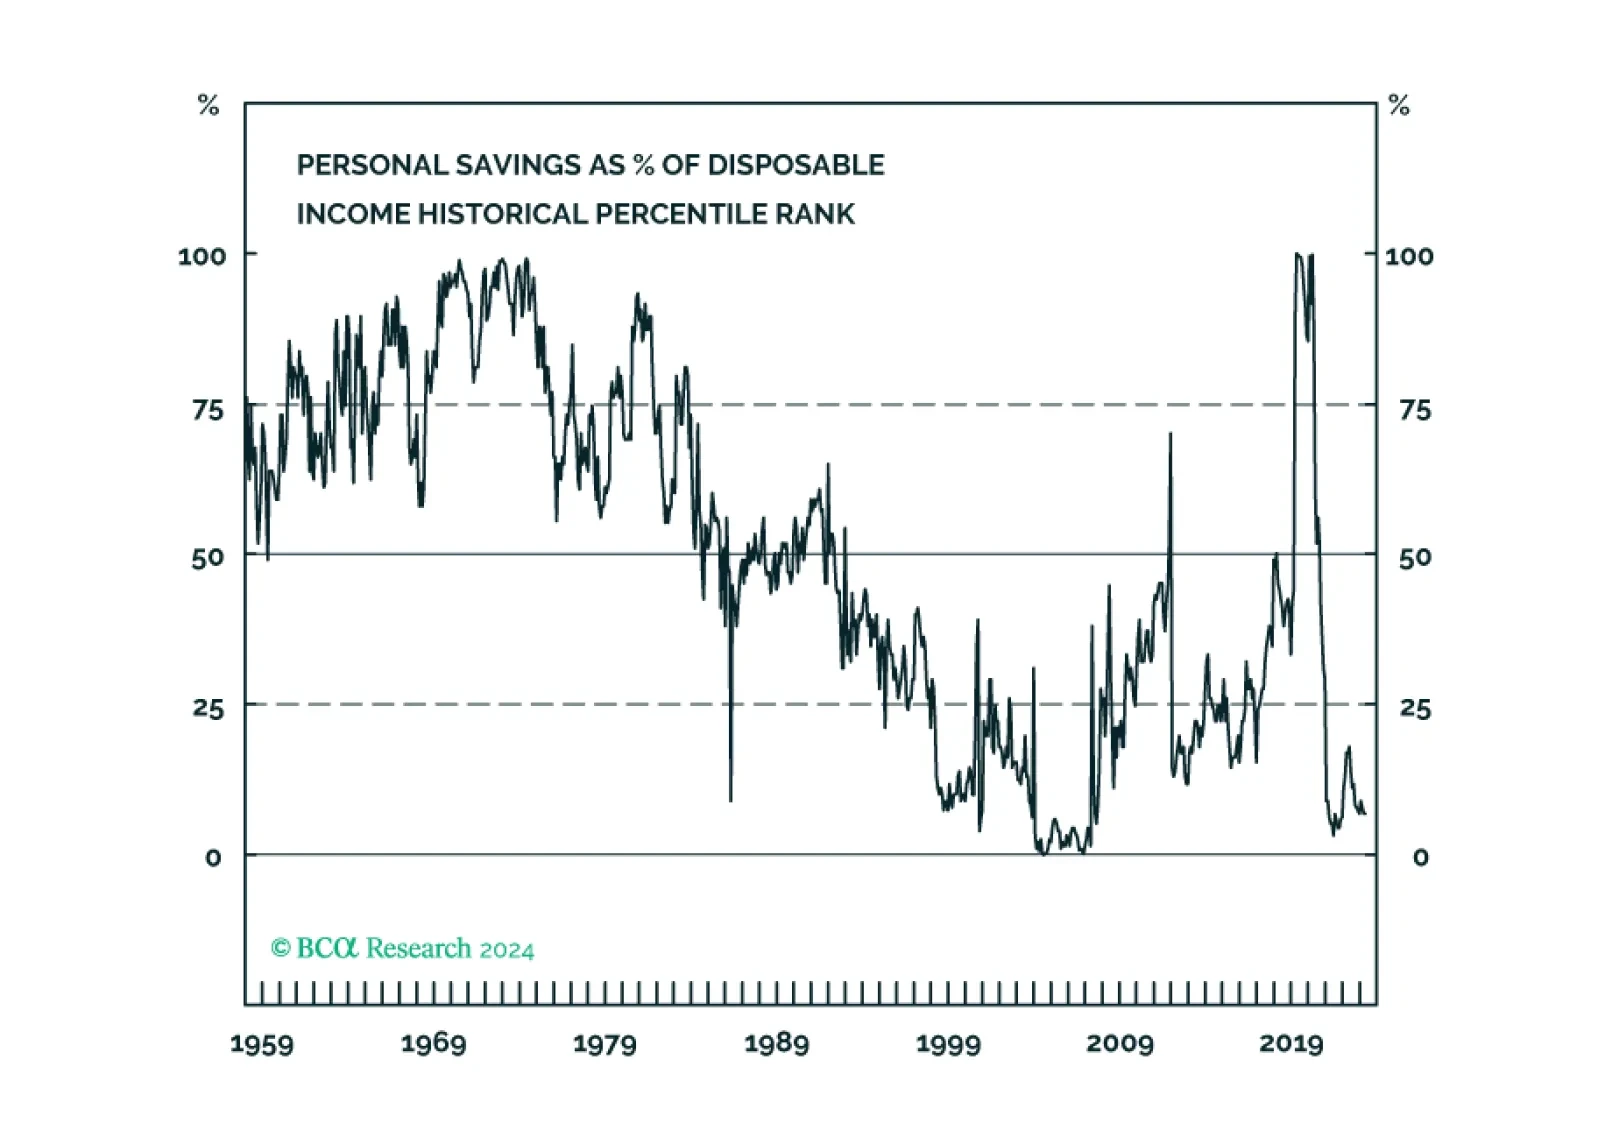
Total consumer credit rose by USD 6.4 billion in April (to USD 5,053 billion outstanding), from a USD 1.1 billion decrease in March (a large downward revision to the USD 6.3 billion rise initially reported) and significantly shy of expectations for a USD 10…
Sweden is a small export-oriented economy and its high sensitivity to global trade makes it a good bellwether of global growth developments. The headwinds from high borrowing costs are relatively more pronounced in Sweden where a large share of households…
A decade of Canadian equity underperformance has led to a historical discount relative to the S&P 500. Sector composition largely explains this underperformance. Banks and natural resources stocks are overrepresented in the TSX while the US stock market is…

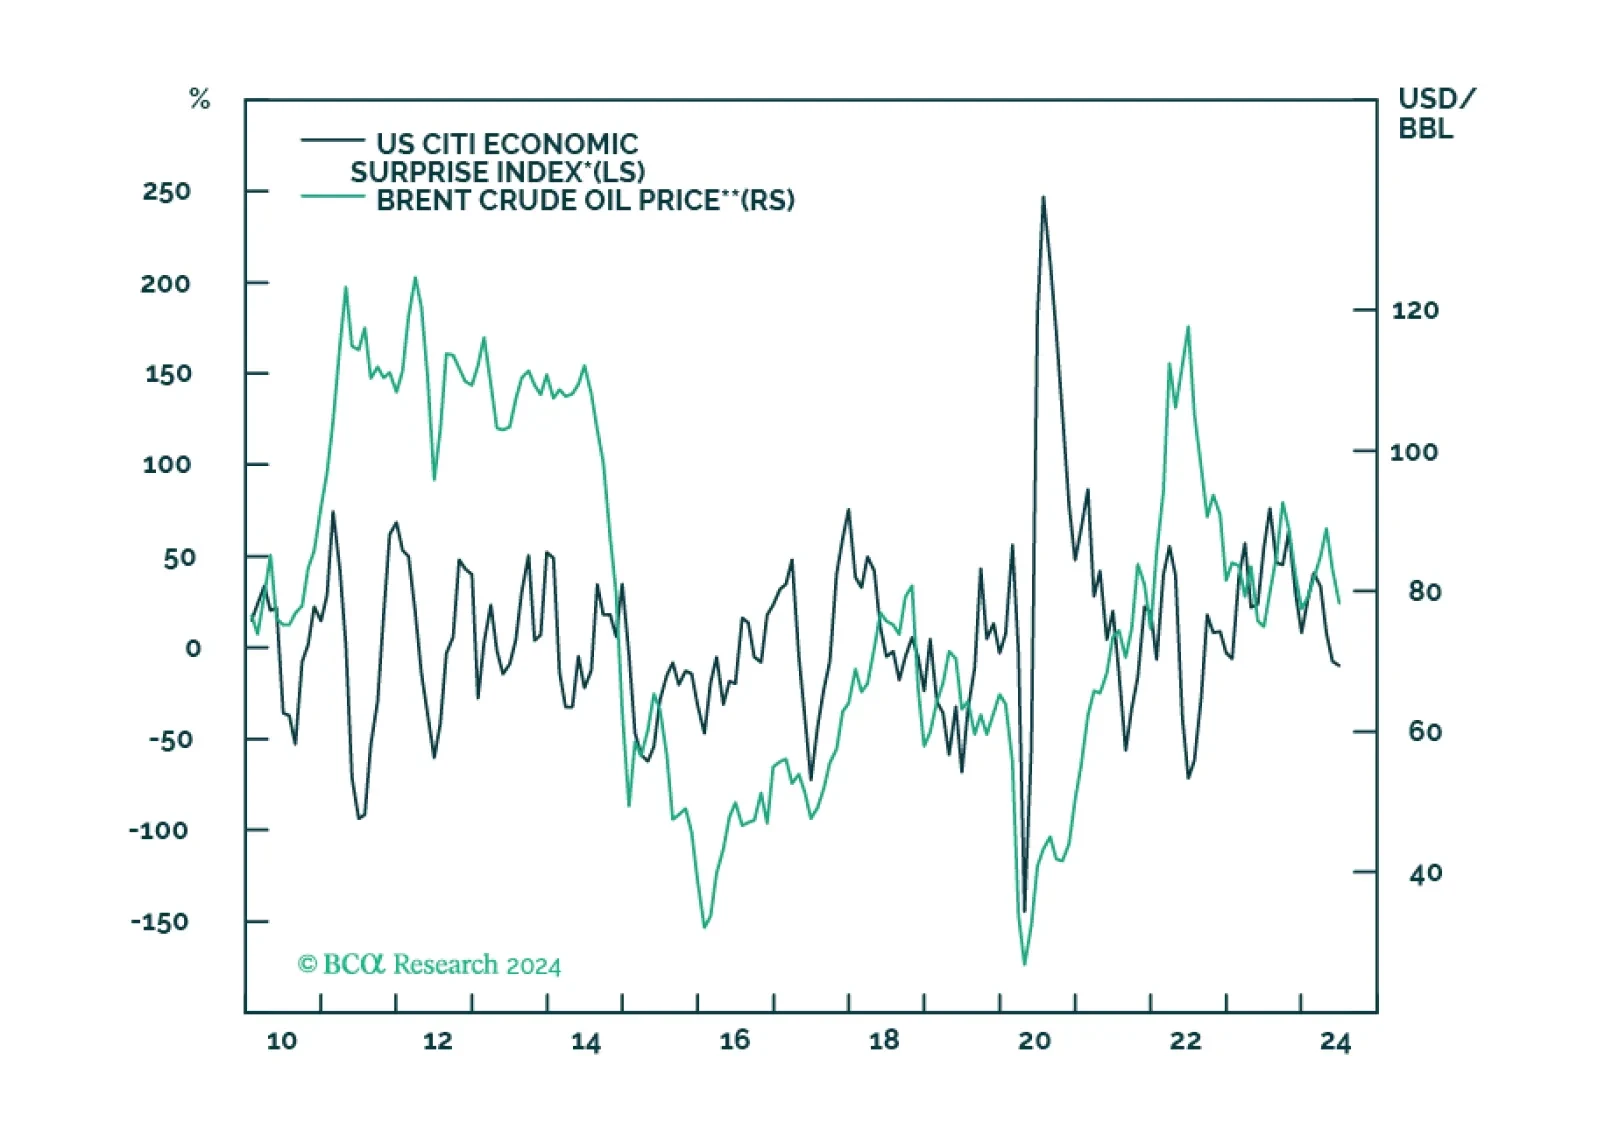
We close our overweights to Energy and Aerospace & Defense. The macroeconomic backdrop is deteriorating for Energy. As for A&D, the good news is already priced in.
Although the comprehensive economic surprise indexes continued weakening in May, the metrics in our equity downgrade checklist haven’t softened enough to check more boxes now. While we continue to expect the US economy will enter a recession before year end, it is not yet certain and we remain tactically neutral.