Productos de construcción
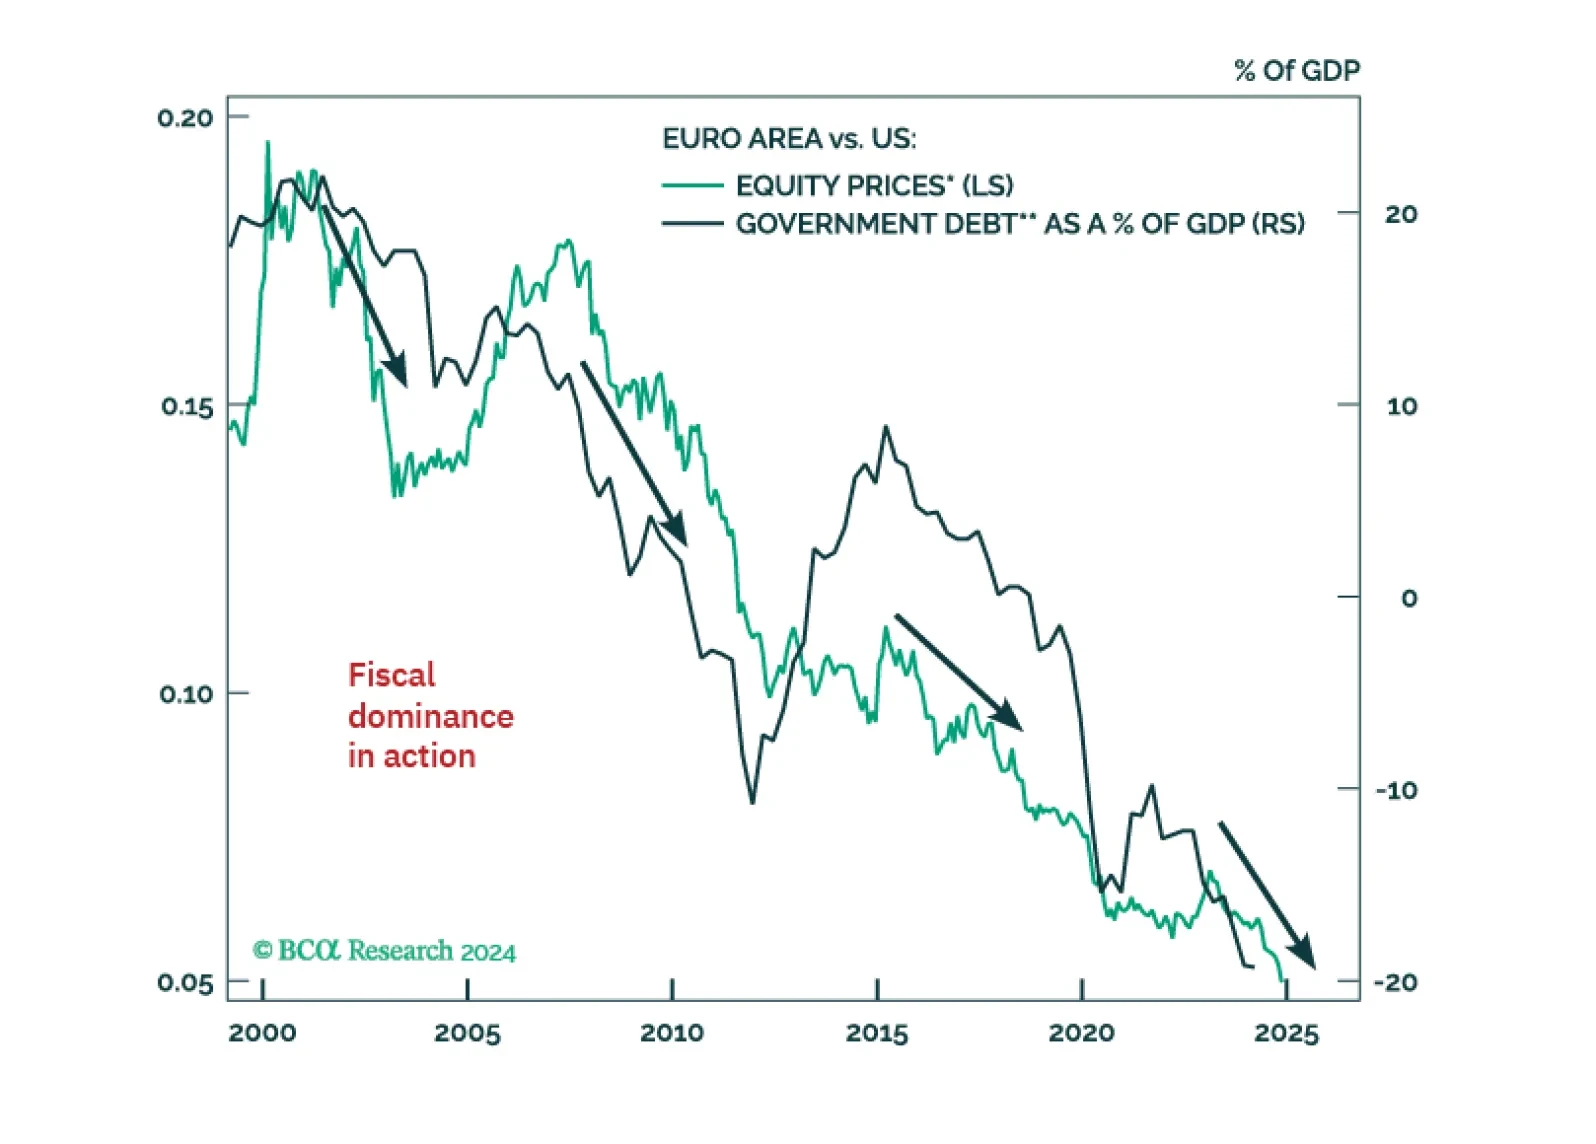
Los inversores han renunciado a los activos europeos, que ahora cotizan con descuentos excepcionales respecto a los activos estadounidenses. Sin embargo, una política fiscal estadounidense más restrictiva, el fin de la austeridad y del desapalancamiento en Europa, el tsunami de GNL a punto de golpear las costas europeas y el capex global impulsado por la Tríada Geopolítica Imposible significan que el momento de gloria de Europa pronto volverá.
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
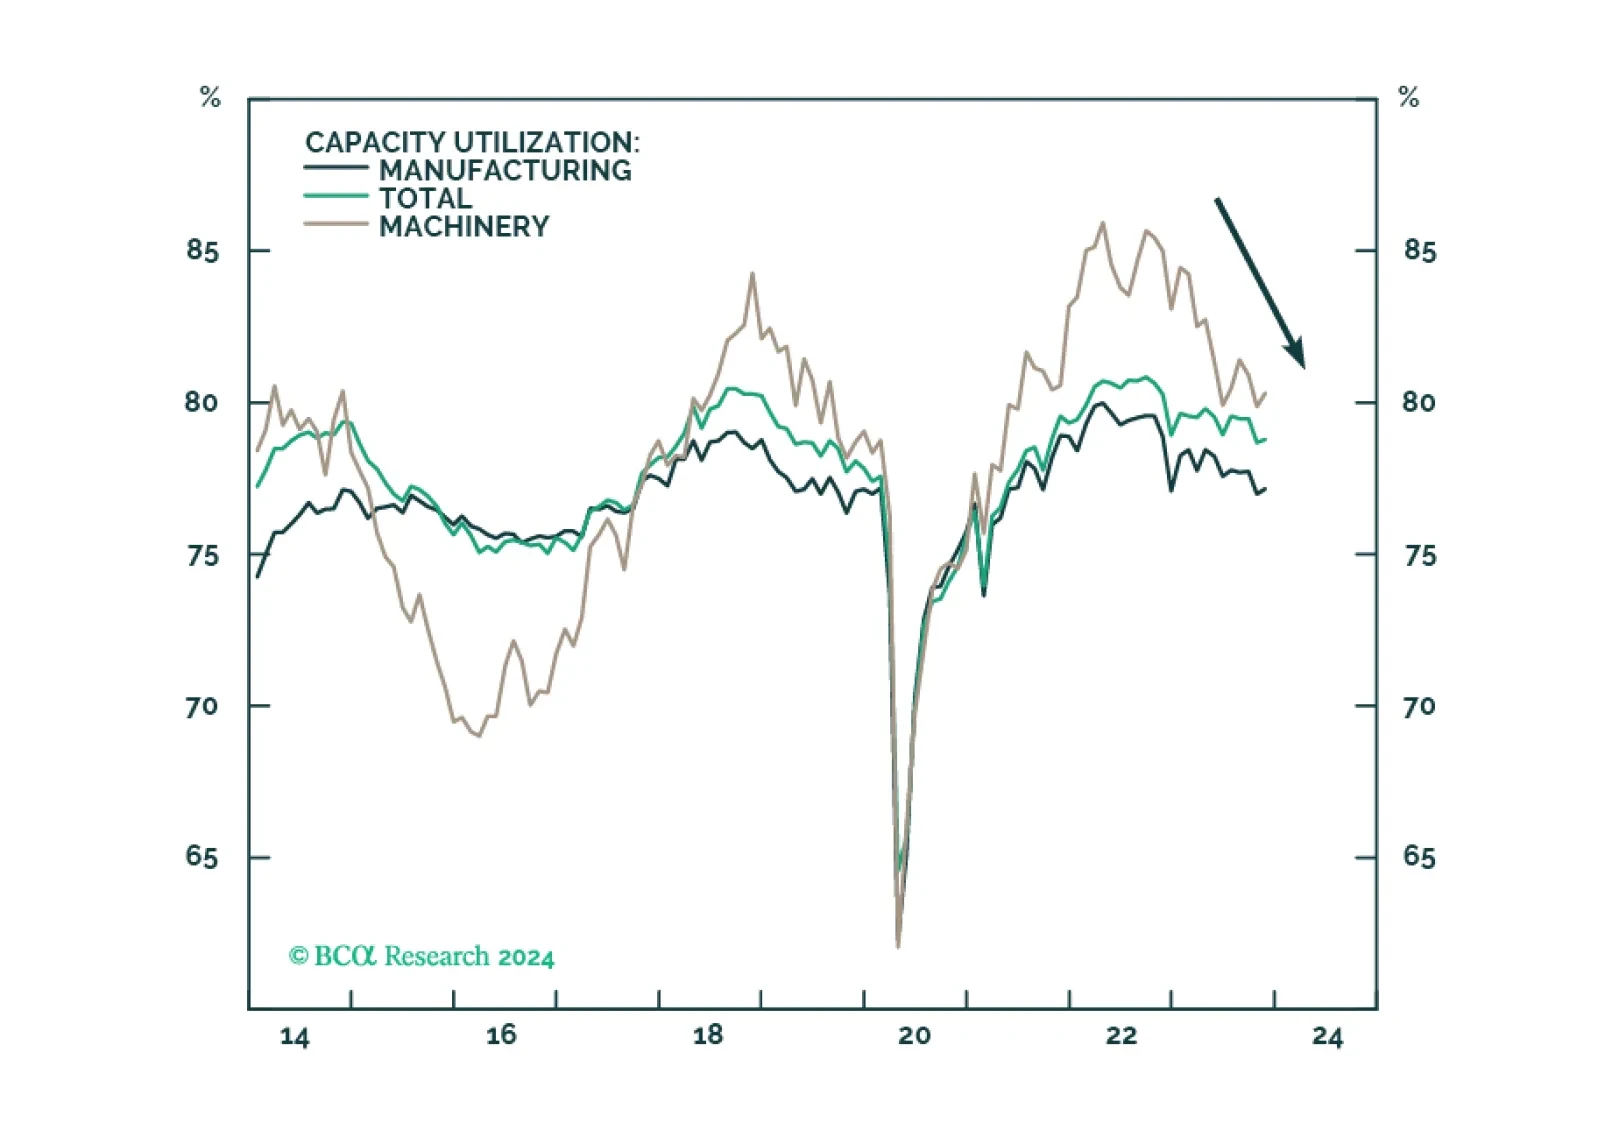
The US manufacturing renaissance, spurred on by reshoring, automation, and government spending, is running its course but progress has slowed on the back of tight monetary conditions and the manufacturing recession. The deceleration of these positive trends weighs on the outlook for the Capital Goods industry group, impeding its performance over the short term. However, we reiterate that positive long-term trends for the industry remain intact. We downgrade Capital Goods to a tactical underweight. It remains a strategic overweight.
