Mercados Emergentes

East Asian exports reveal the global economy keeps decelerating. Singaporean non-oil domestic exports (NODX) missed expectations and decelerated in October, falling 7.4% m/m (-4.6% y/y). Electronics exports grew 2.6% y/y, slowing down from 4.0% in September.…
Chinese activity indicators showed resilience in October, with retail sales jumping from 3.2% to 4.8% y/y. Industrial production growth was roughly unchanged at 5.3% y/y. New and used home prices keep falling, albeit at a slower pace. We would fade this…
The flipside of the recent US dollar rally has been weakness across both DM and EM FX. The USD rally has legs and will have cross-asset reverberations. EM equities will be affected. A key determinant of EM returns is the currency, as investors cannot benefit…
Our China Investment Strategy team assessed the country’s outlook in a context of underwhelming stimulus and rising trade tensions. Trump’s re-election raises the likelihood of tariff hikes on Chinese exports. China’s recent stimulus announcements…
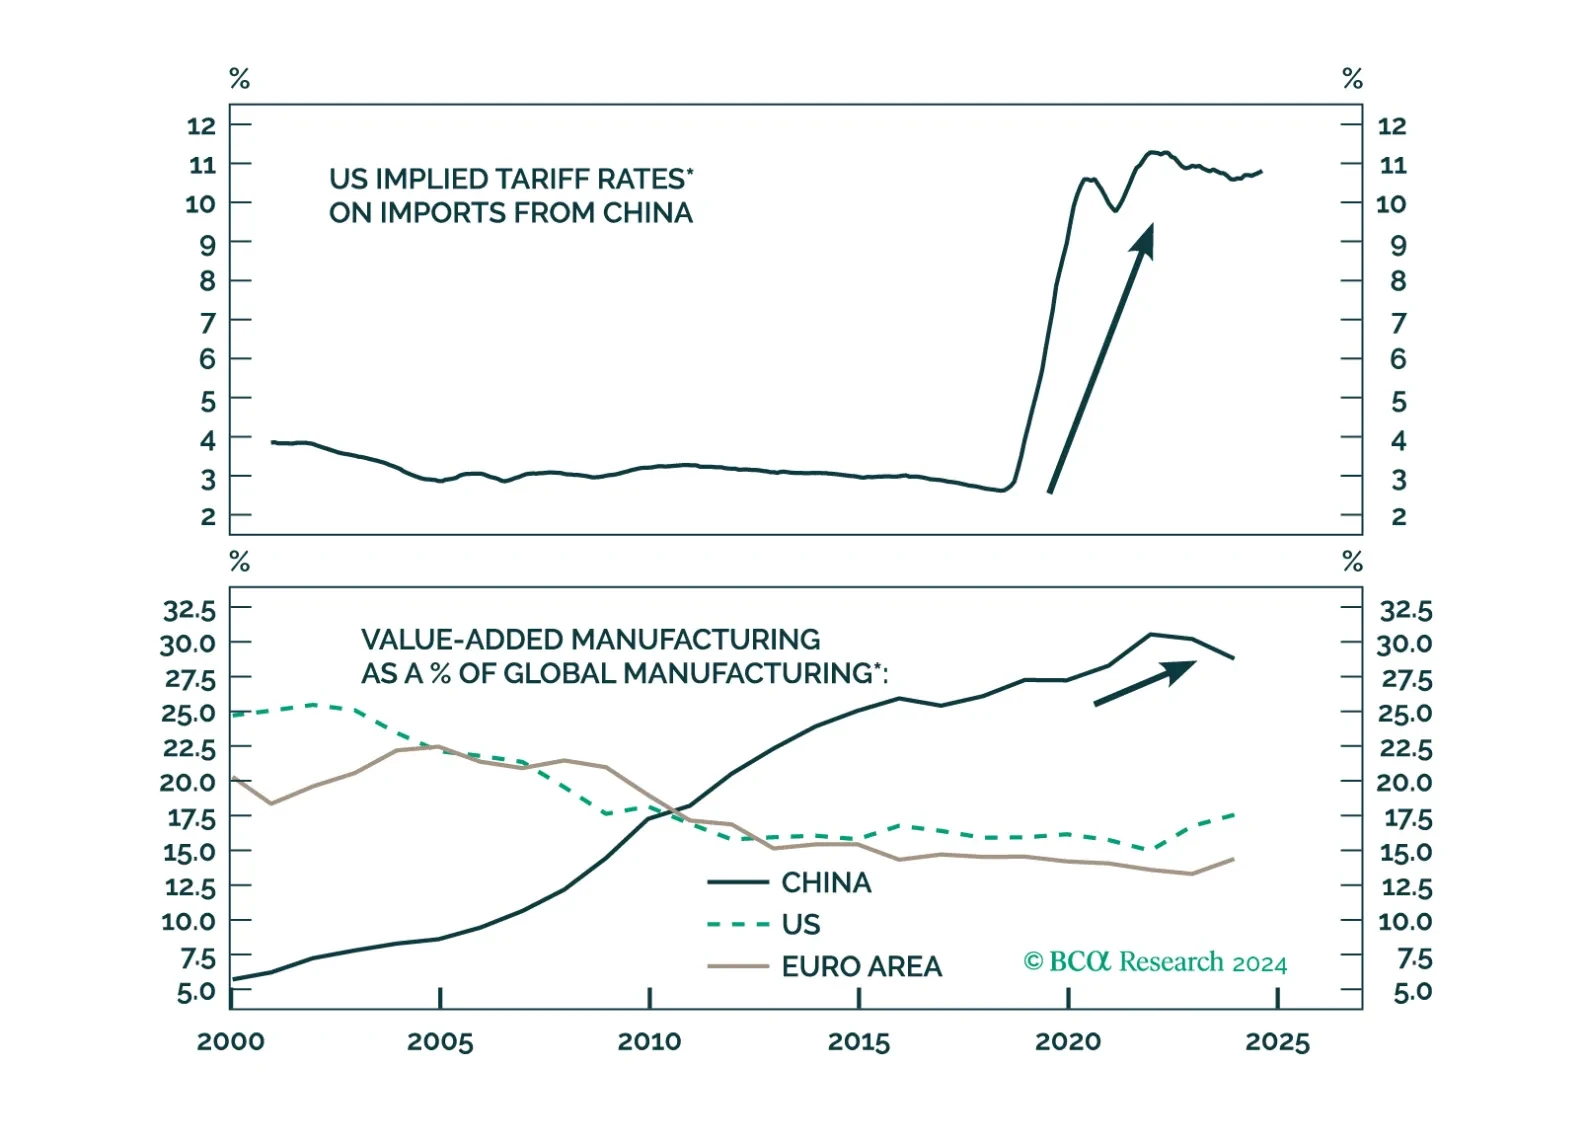
La reelección presidencial de Trump convierte los aumentos de aranceles de EE. UU. sobre las exportaciones chinas en una amenaza inminente. Beijing ha realizado amplios esfuerzos para reducir la exposición al riesgo de la economía doméstica y diversificar el comercio alejándolo de EE. UU. Sin embargo, China no está hoy mejor posicionada que en 2018 para soportar el impacto de una guerra comercial renovada.
Resumen de la asignación de nuestra cartera para noviembre de 2024.
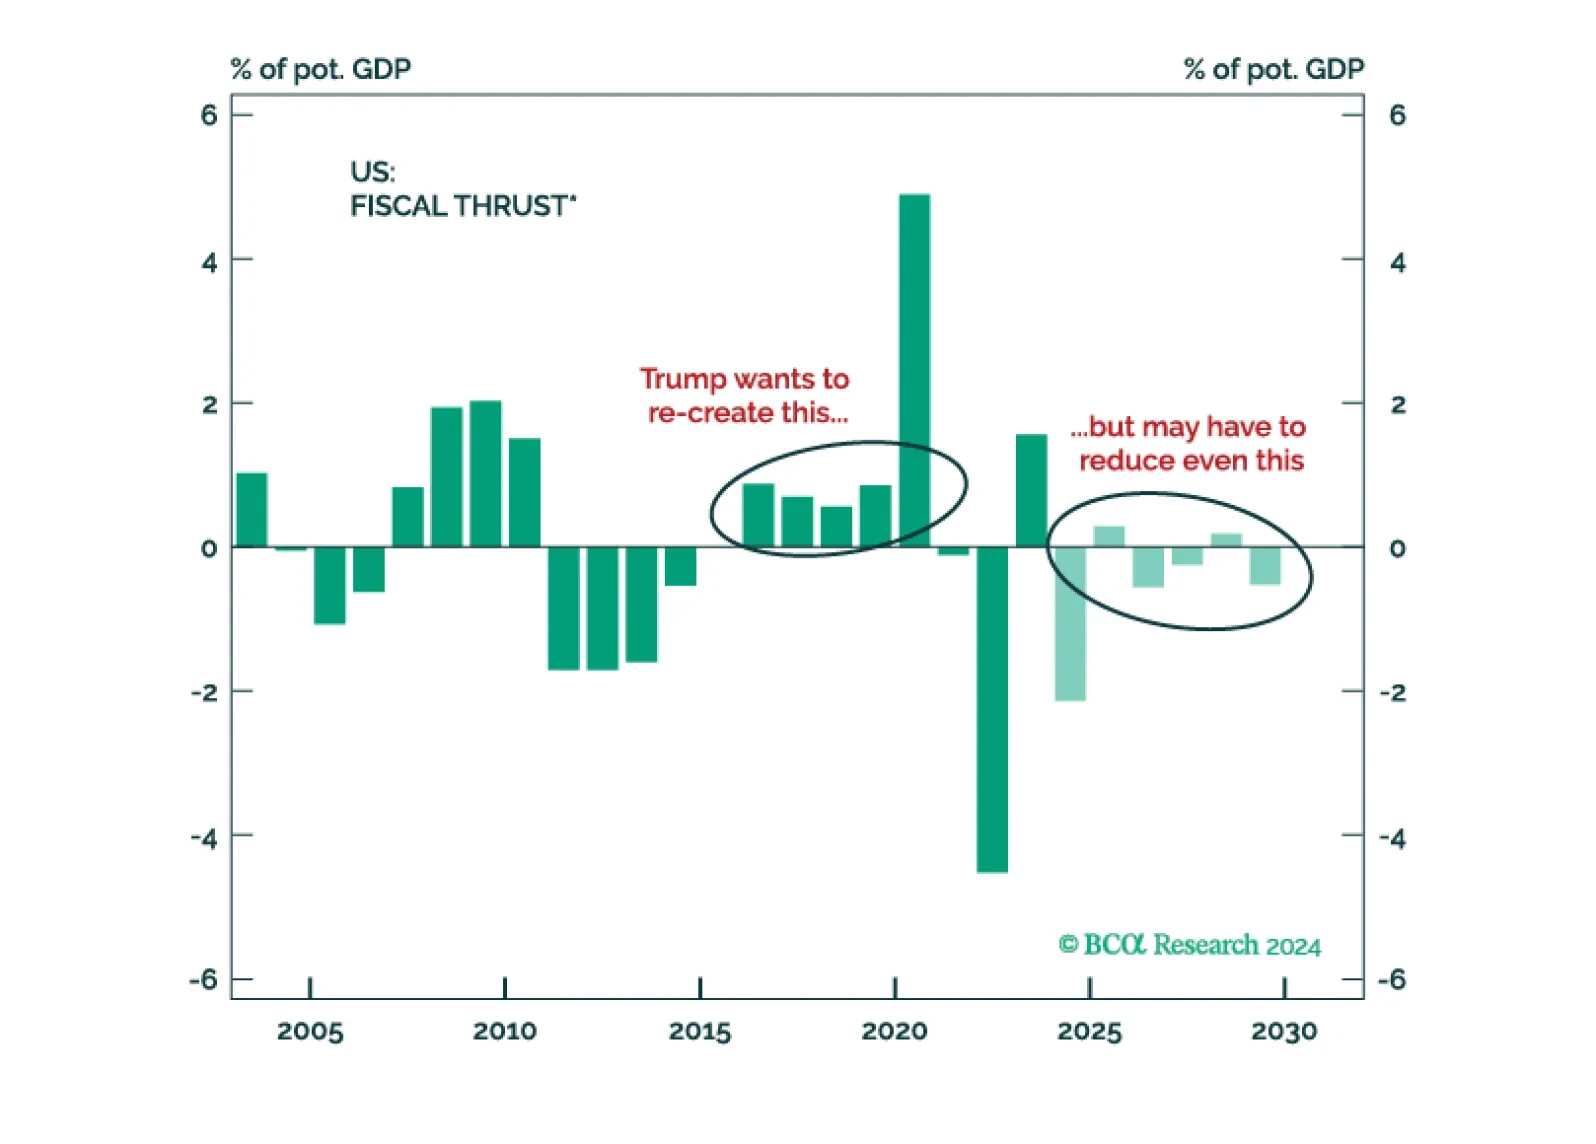
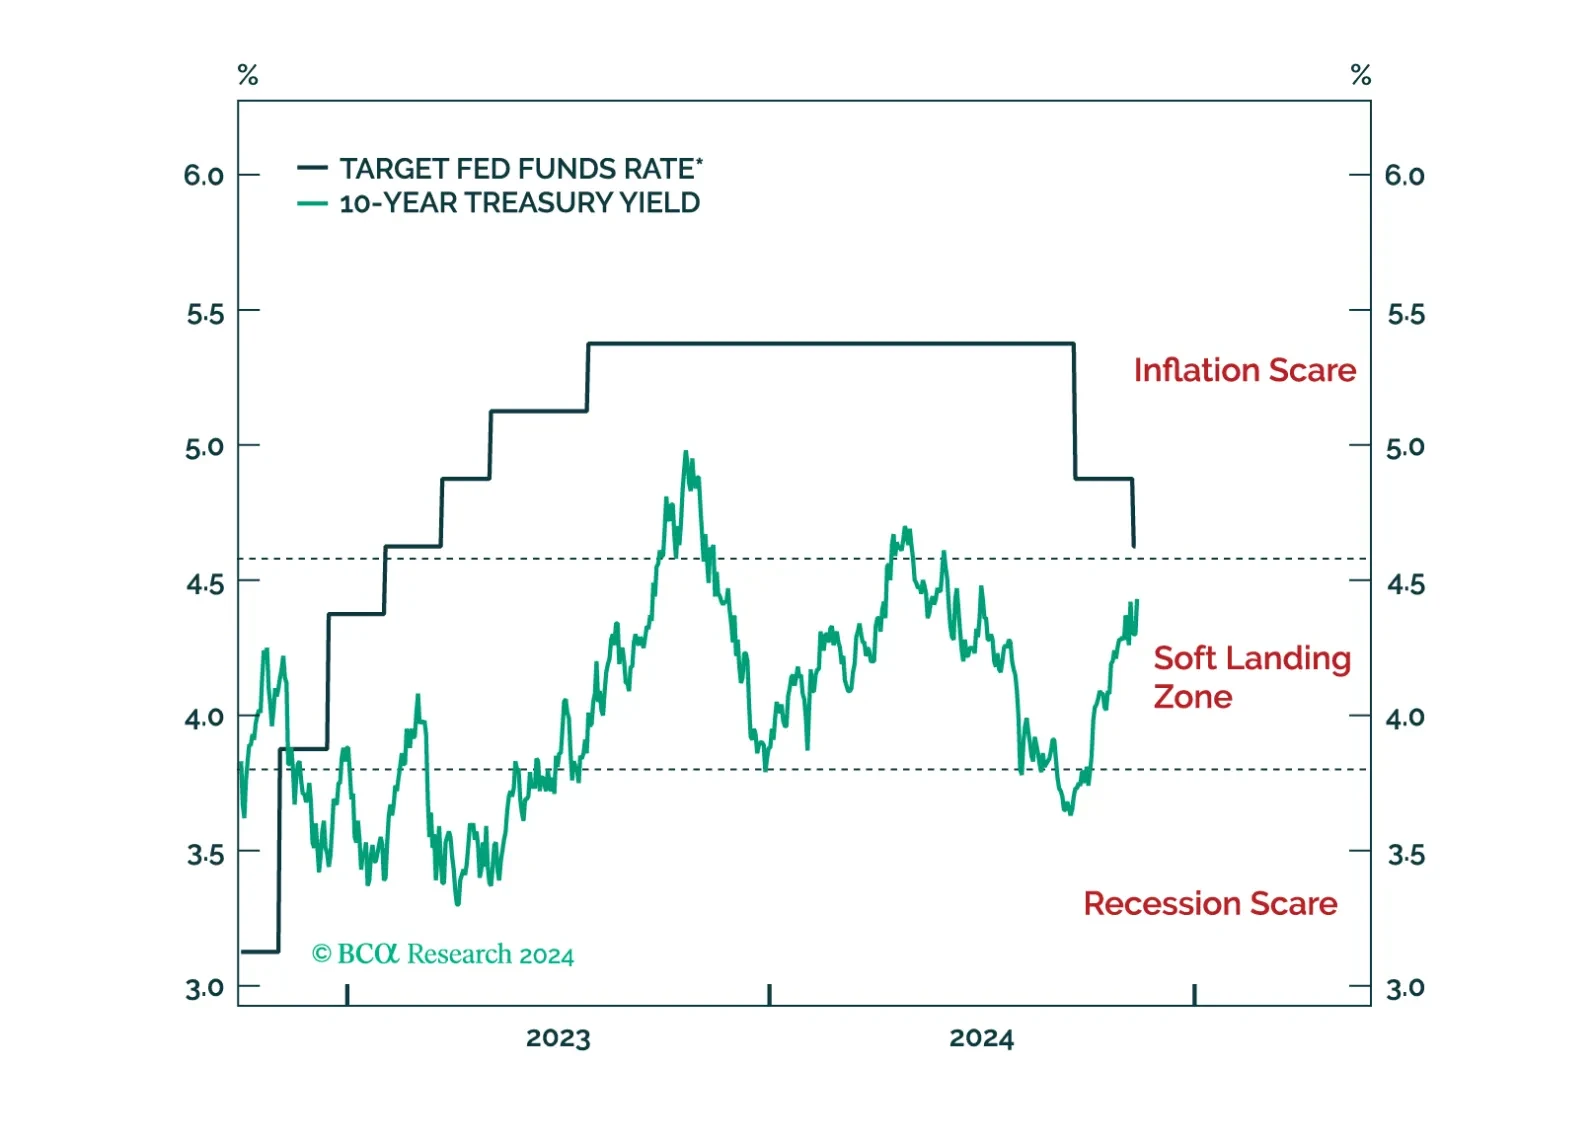
¡El mes de noviembre nos ha traído S&P 6,000! El presidente Trump ha ganado una “Red Sweep” (como esperábamos todo el año) y ha dado paso a un cambio de régimen en Estados Unidos. Por ahora, estamos abiertos a aprovechar el impulso. Sin embargo, el mayor riesgo para el mercado son los rendimientos de los bonos, que deberían subir a medida que los inversores empiecen a valorar las políticas del presidente Trump y su impacto en los déficits.
China’s October data for inflation and money disappointed. Headline CPI decelerated to 0.3% year-over-year from 0.4% in September, and PPI deflation worsened at -2.9% vs. -2.8% a month prior. While broad measures such as M2 accelerated, new loan growth has…
As highlighted recently, we do not think China’s announced stimulus measures will be enough to stave off deflation (see Today’s Pick). To lift China’s economy, Beijing must unveil large fiscal transfers to households and some initiatives to lift property…
Our China Investment Strategy team recently met with clients in China to assess investor sentiment and discuss the outlook as Beijing unveils new stimulus measures. China’s economic recovery faces headwinds and is unlikely to stabilize until mid-2025.…