Demografía
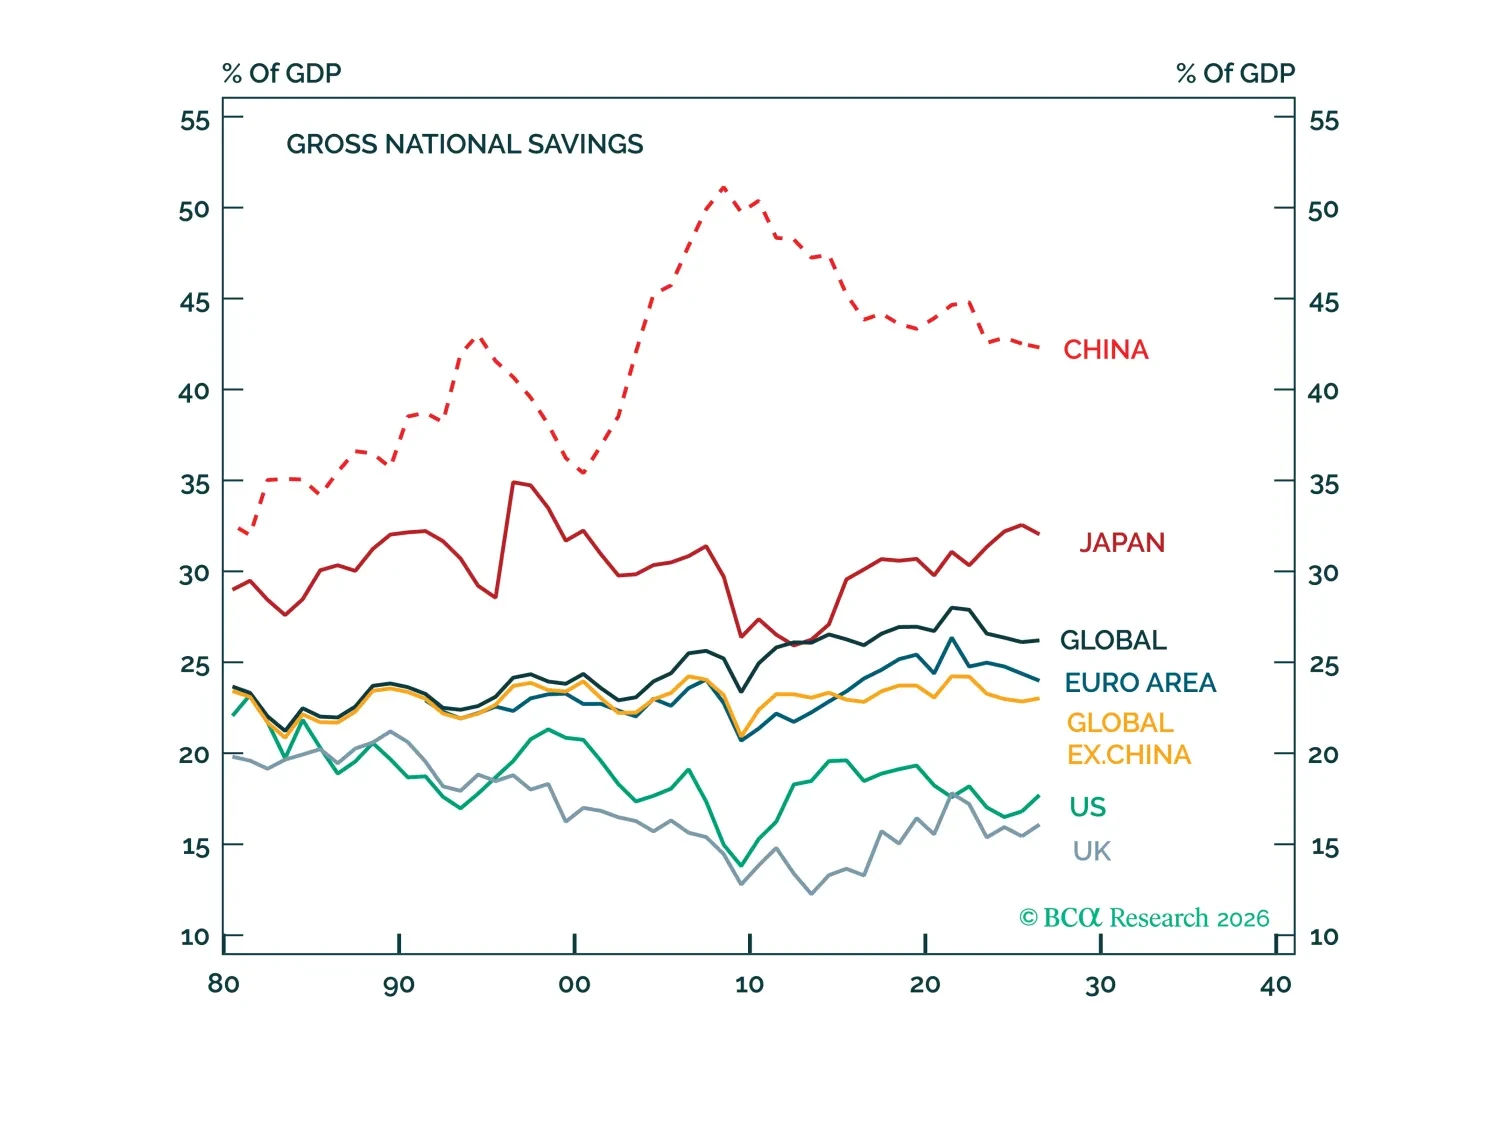
China no produce demasiado. Gasta demasiado poco. La única manera viable de que China reduzca la inversión sin aumentar el desempleo es reduciendo el ahorro nacional. Sin embargo, hacerlo probablemente será políticamente complicado. Esto sugiere que China sufrirá un crecimiento por debajo de lo esperado y presiones deflacionarias en el futuro previsible.
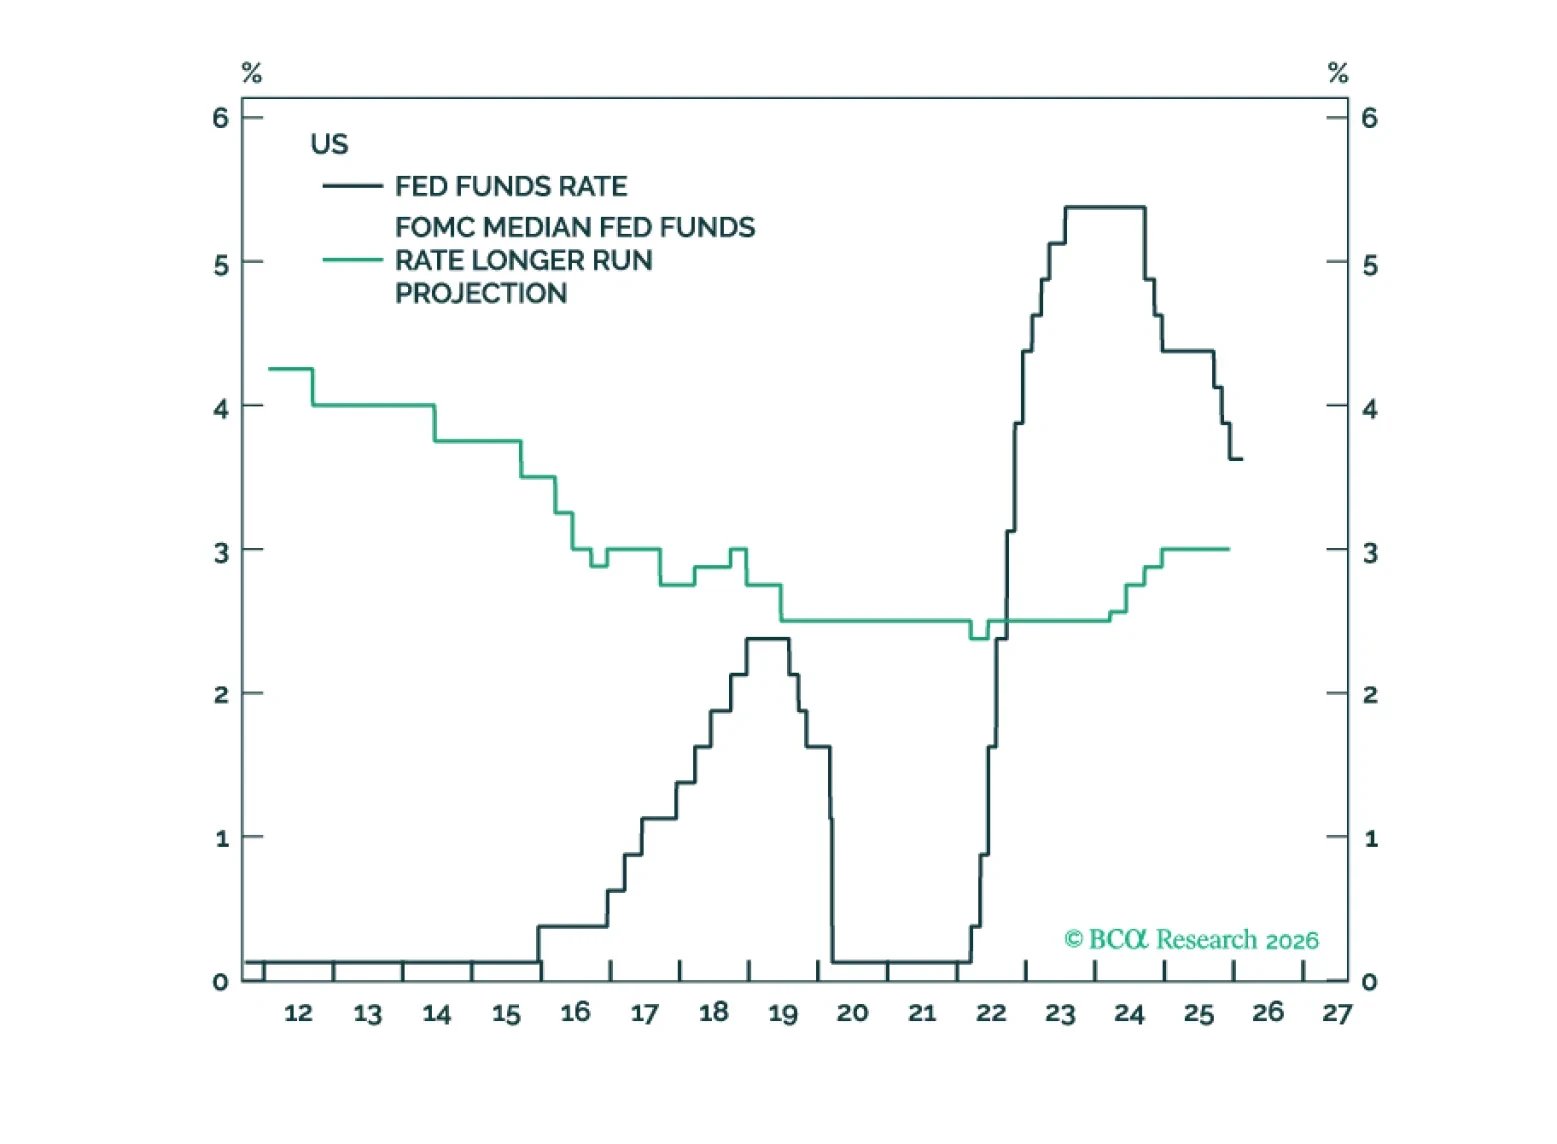
La tasa neutral en Estados Unidos se está sosteniendo gracias a una variedad de fuerzas que corren el riesgo de revertirse. Entre ellas se encuentran el auge de la inversión de capital en IA, los grandes déficits presupuestarios y el nivel extraordinariamente alto de la riqueza de los hogares. Por tanto, es probable que las tasas de interés sorprendan a la baja en los próximos años.

La inteligencia artificial desestabilizará la política doméstica y la seguridad internacional. Los estados intentarán adoptar políticas fiscales más creativas, incluyendo el aumento de impuestos a las grandes tecnologías.
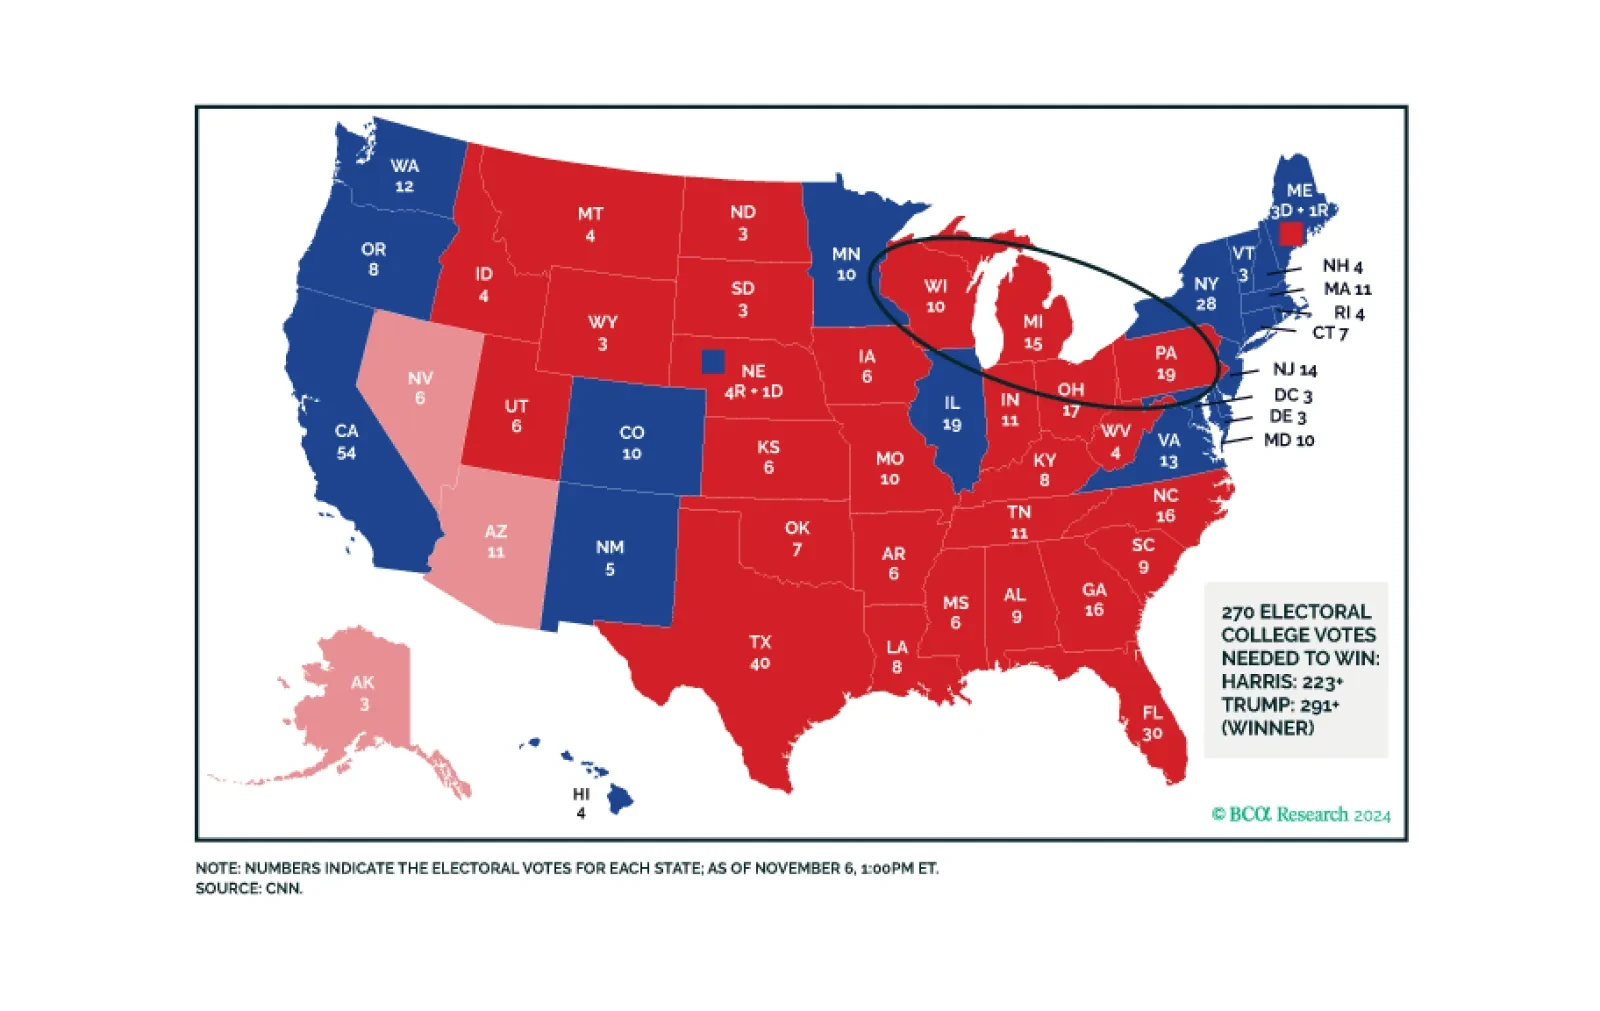
Trump’s resounding victory brings a popular mandate that ensures deregulation and higher trade tariffs. Higher budget deficit and immigration reform are also in the cards as the Republicans look like they may squeak a thin margin in the House of Representatives. Foreign policy will become more unilateral, with US assets outperforming initially.
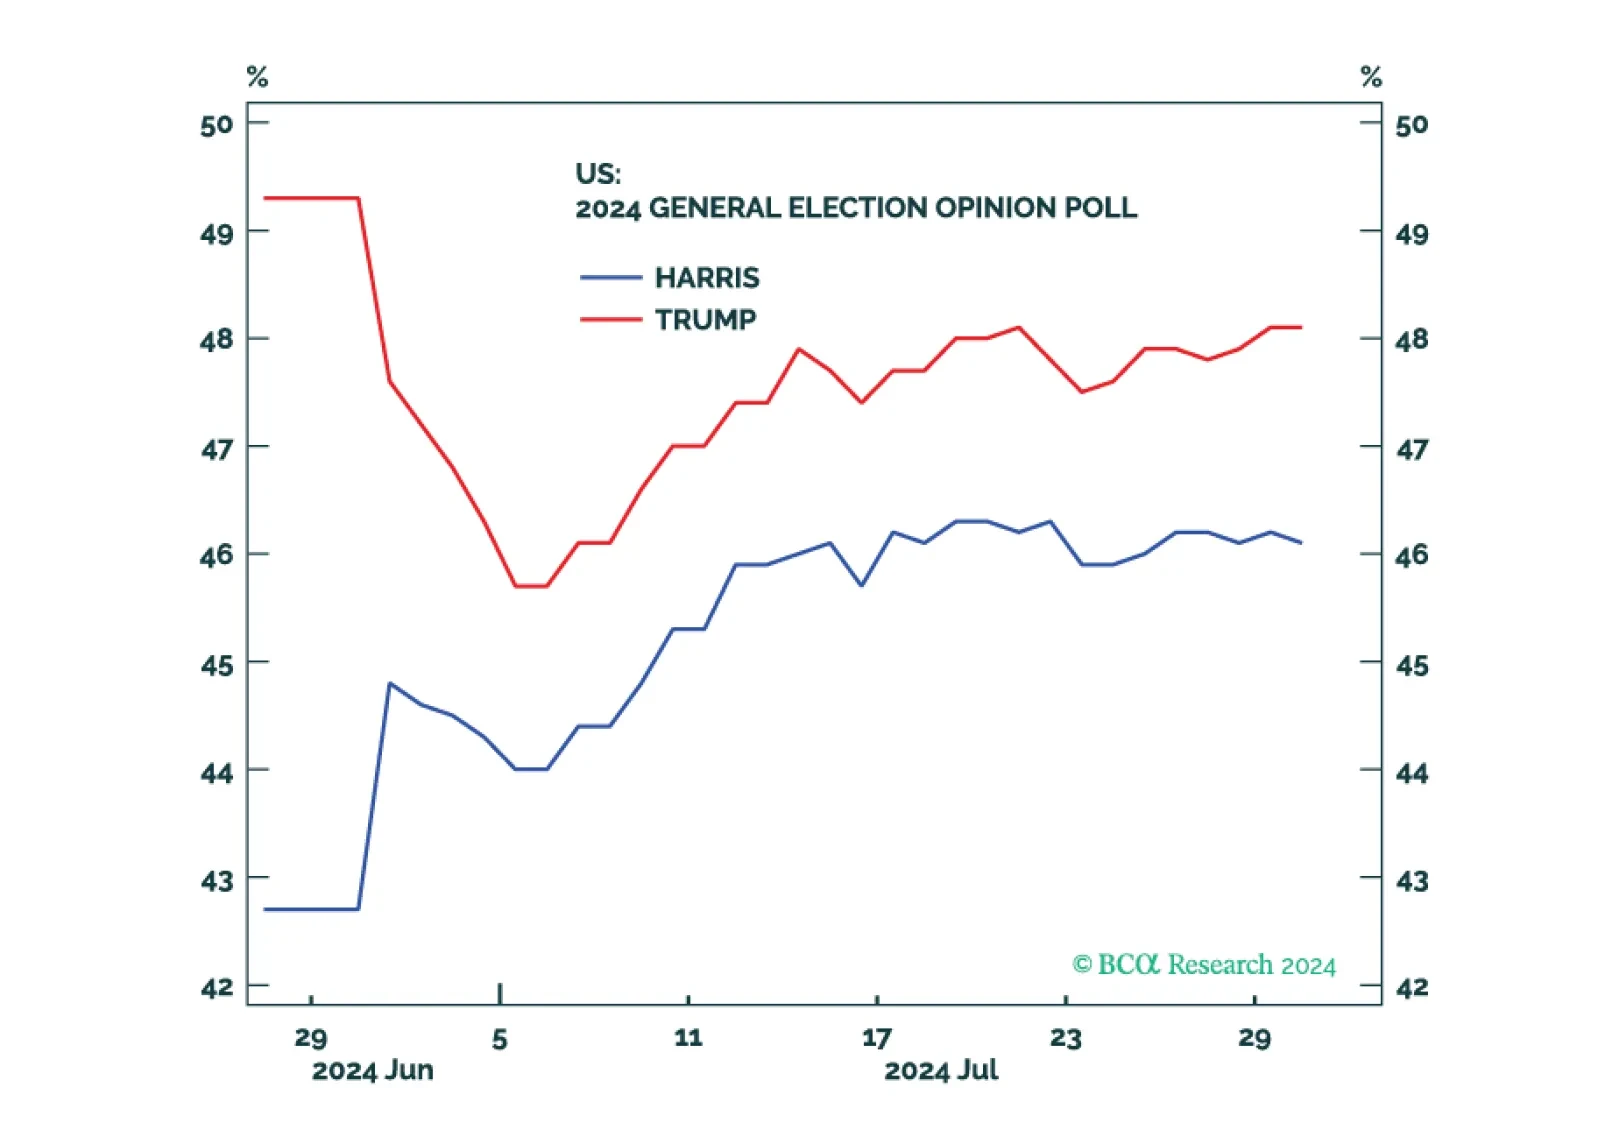
Republicans are favored but the election is still competitive. Equities, corporate credit, and cyclical sectors will fall until policy uncertainty is reduced.
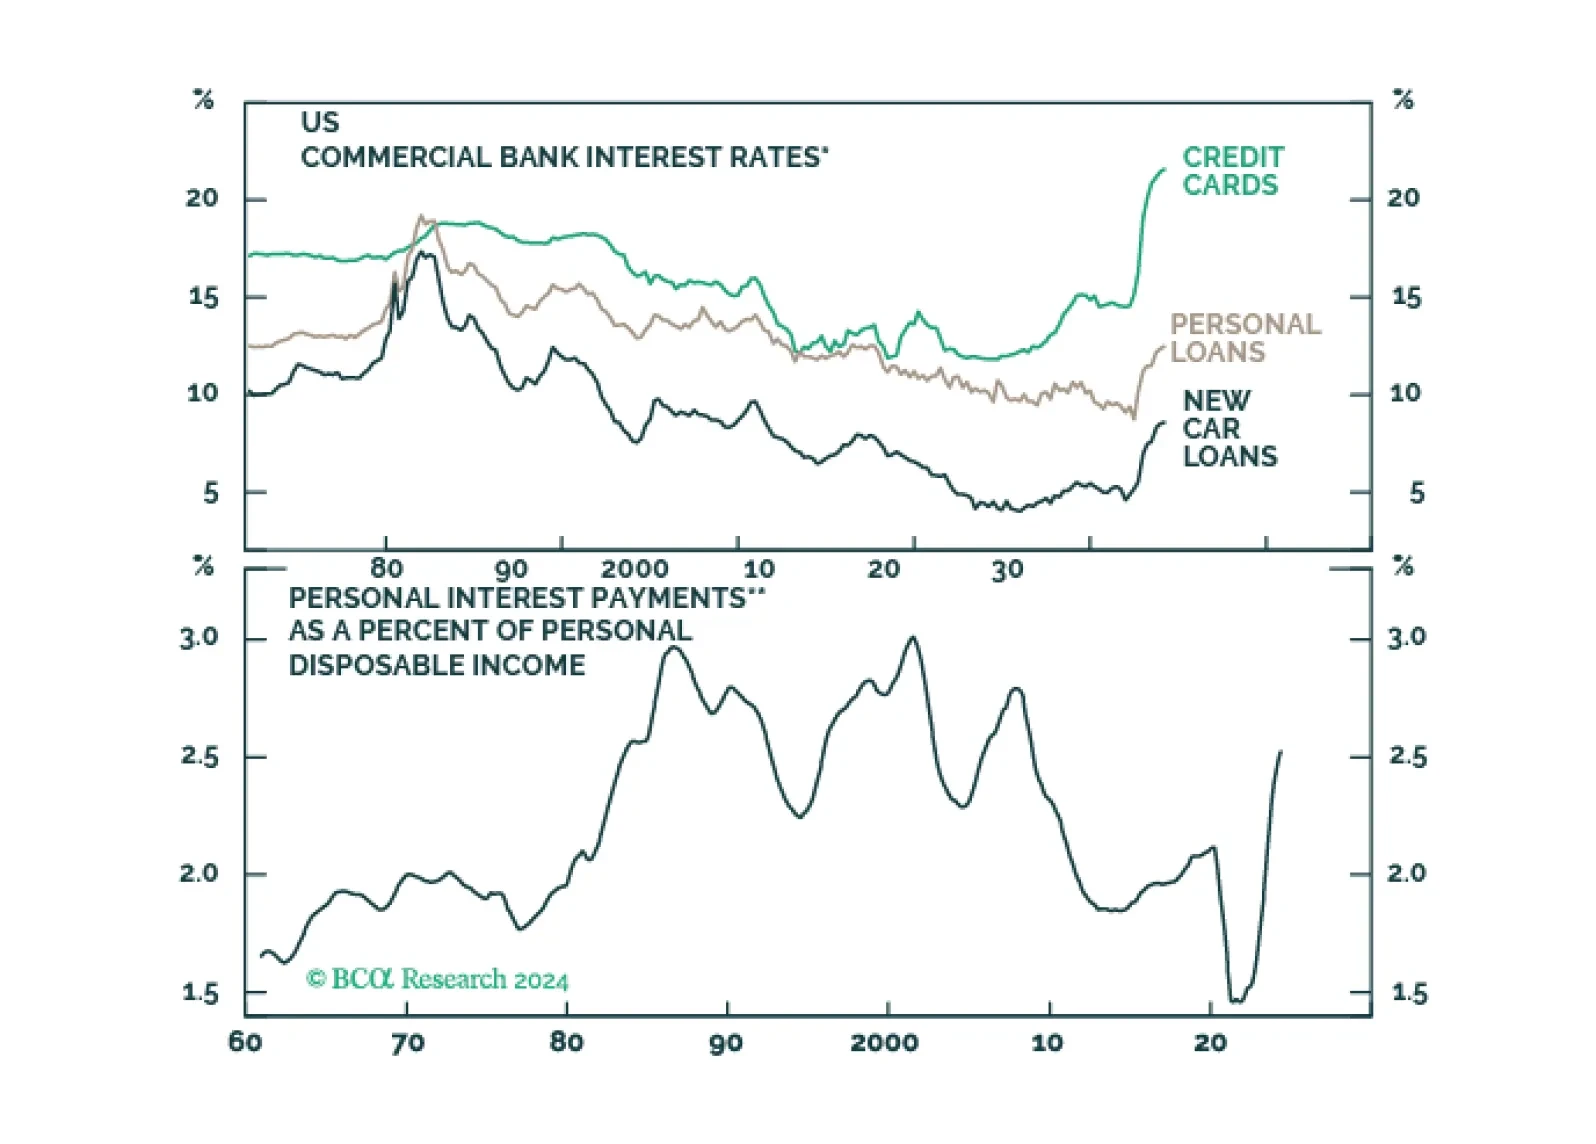
Global consumer spending is likely to slow over the coming quarters, culminating in a major economic downturn in late 2024 or early 2025. Investors should maintain benchmark exposure to equities for now but look to turn more defensive by the end of this summer.
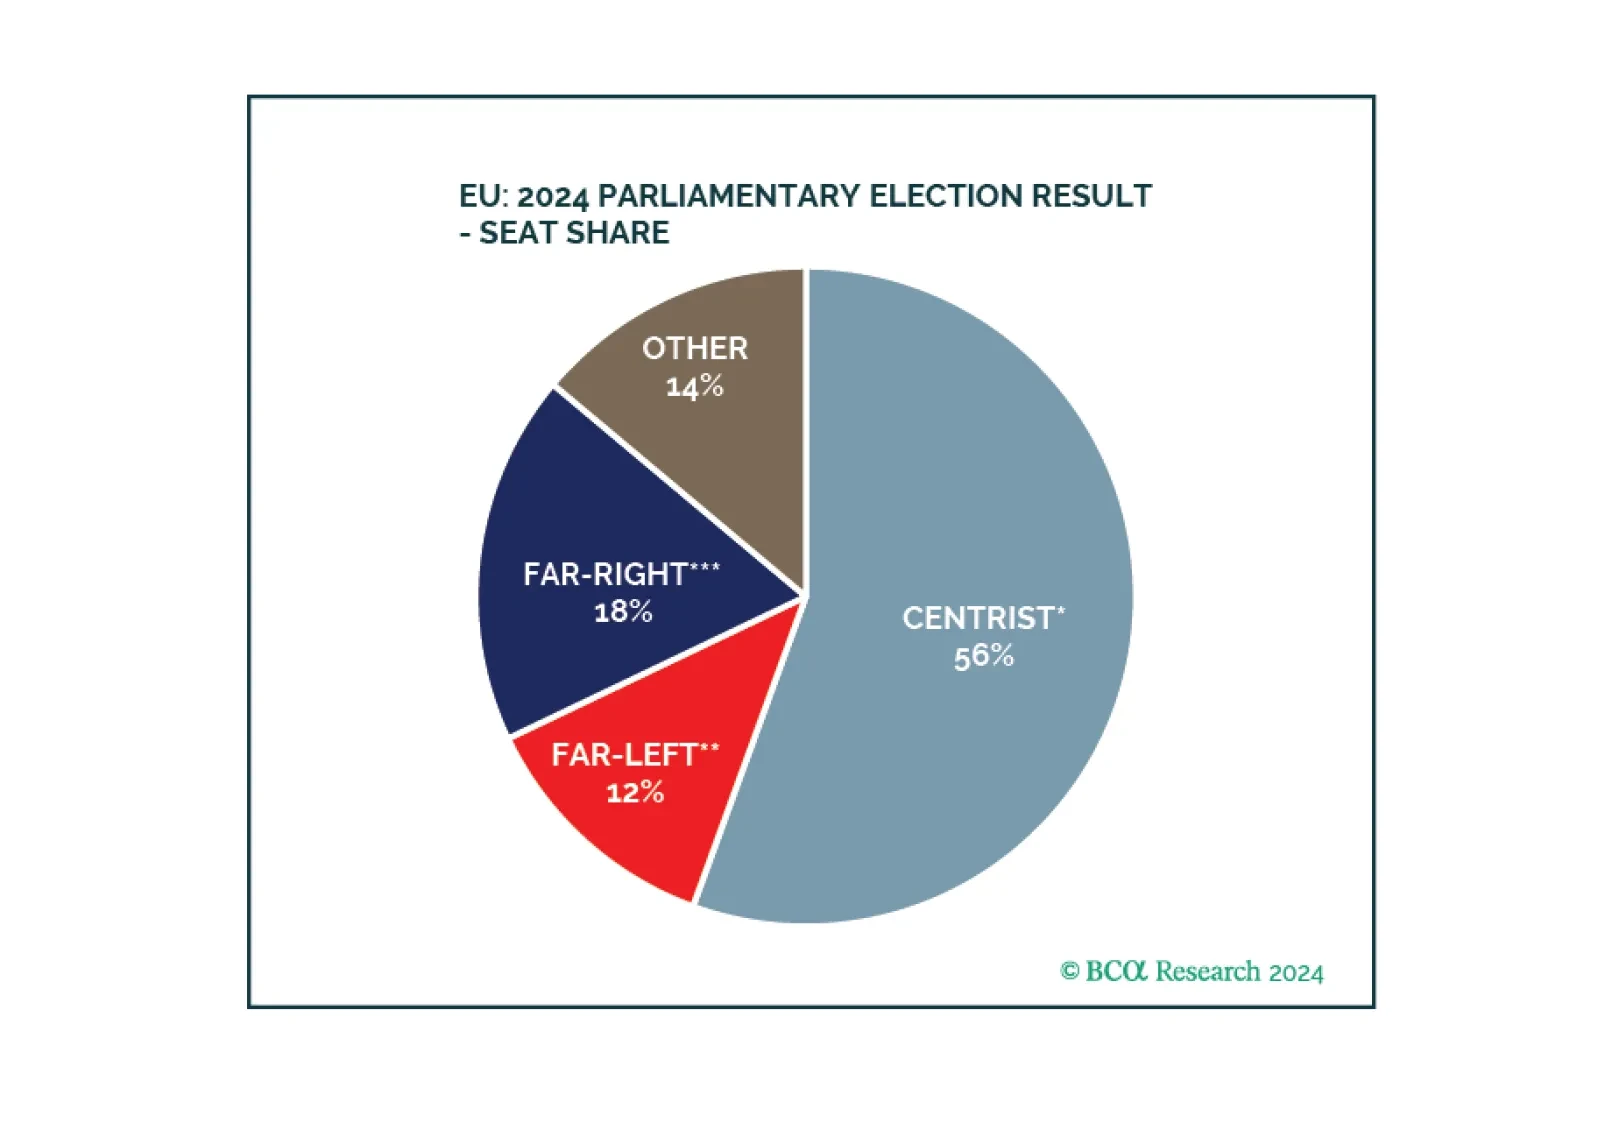
Europe did not witness a major policy reversal. Inflationary pressures are coming down, enabling the ECB to cut rates and European states to maintain soft budgets. Geopolitical challenges ensure that European parties continue to cooperate on national defense, economic security, and energy security.
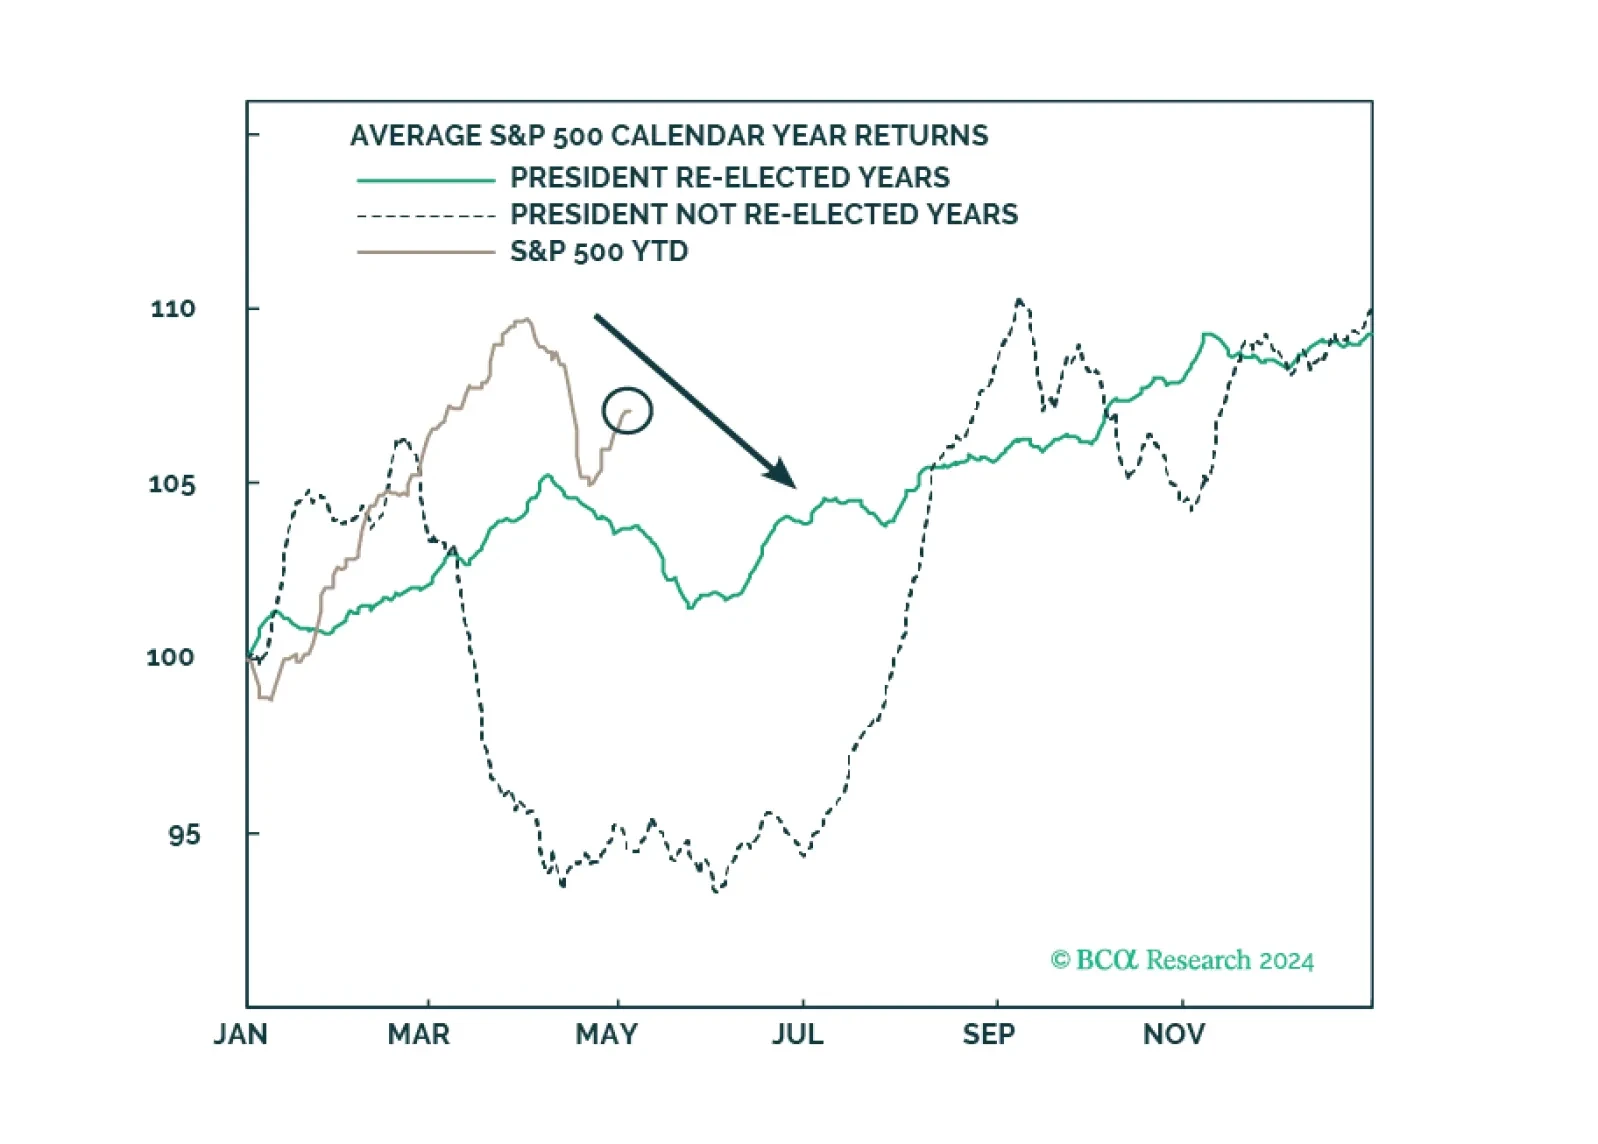
Investors should prepare for economic data to weaken even as policy uncertainty and geopolitical risk skyrocket ahead of the US election.
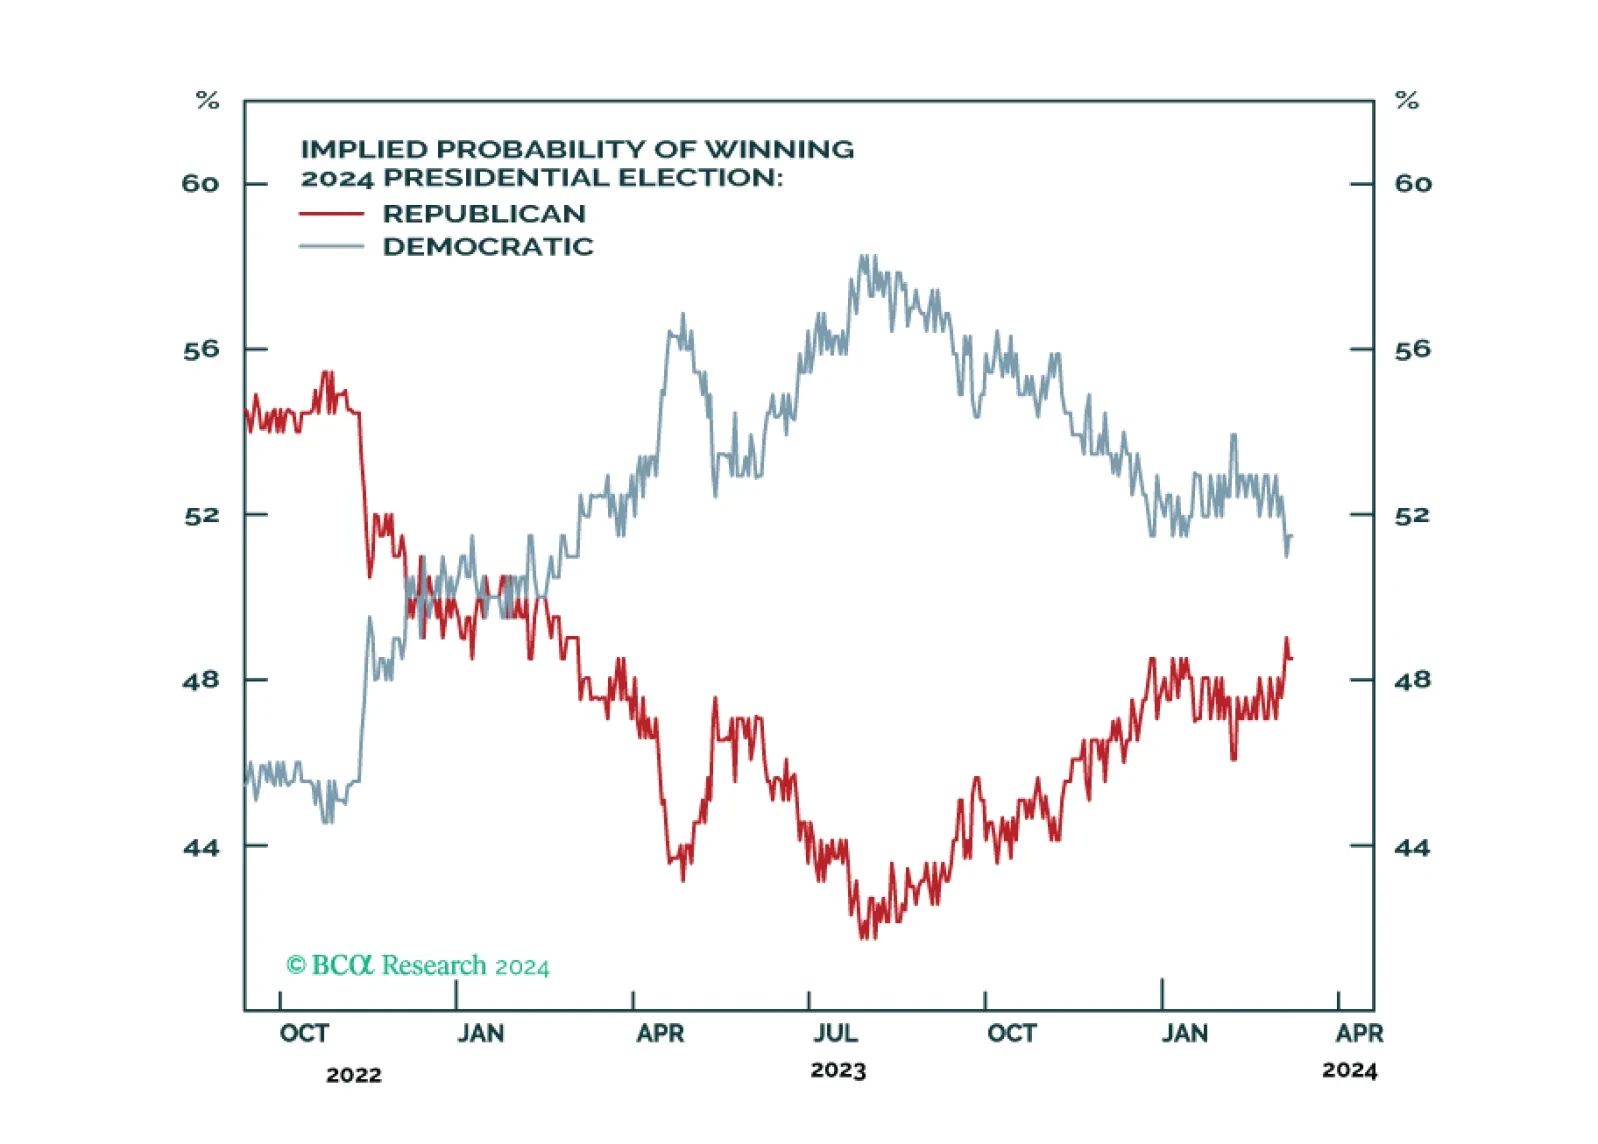
Democrats are still slightly favored for reelection as the incumbent party is presiding over a growing economy. However, Biden’s strong showing in the primary election is not lifting his popular approval yet, and that is a worrying sign. Policy uncertainty should rise sharply, which is marginally negative for the stock market.
Middle East conflict, extreme US policy uncertainty, Chinese economic slowdown, US-Russian proxy war, and Asian military conflicts do not create a stable investment backdrop for 2024. Our top five “black swan” risks may be highly improbable, but they stem from these underlying trends.