Skip to main content

Economy

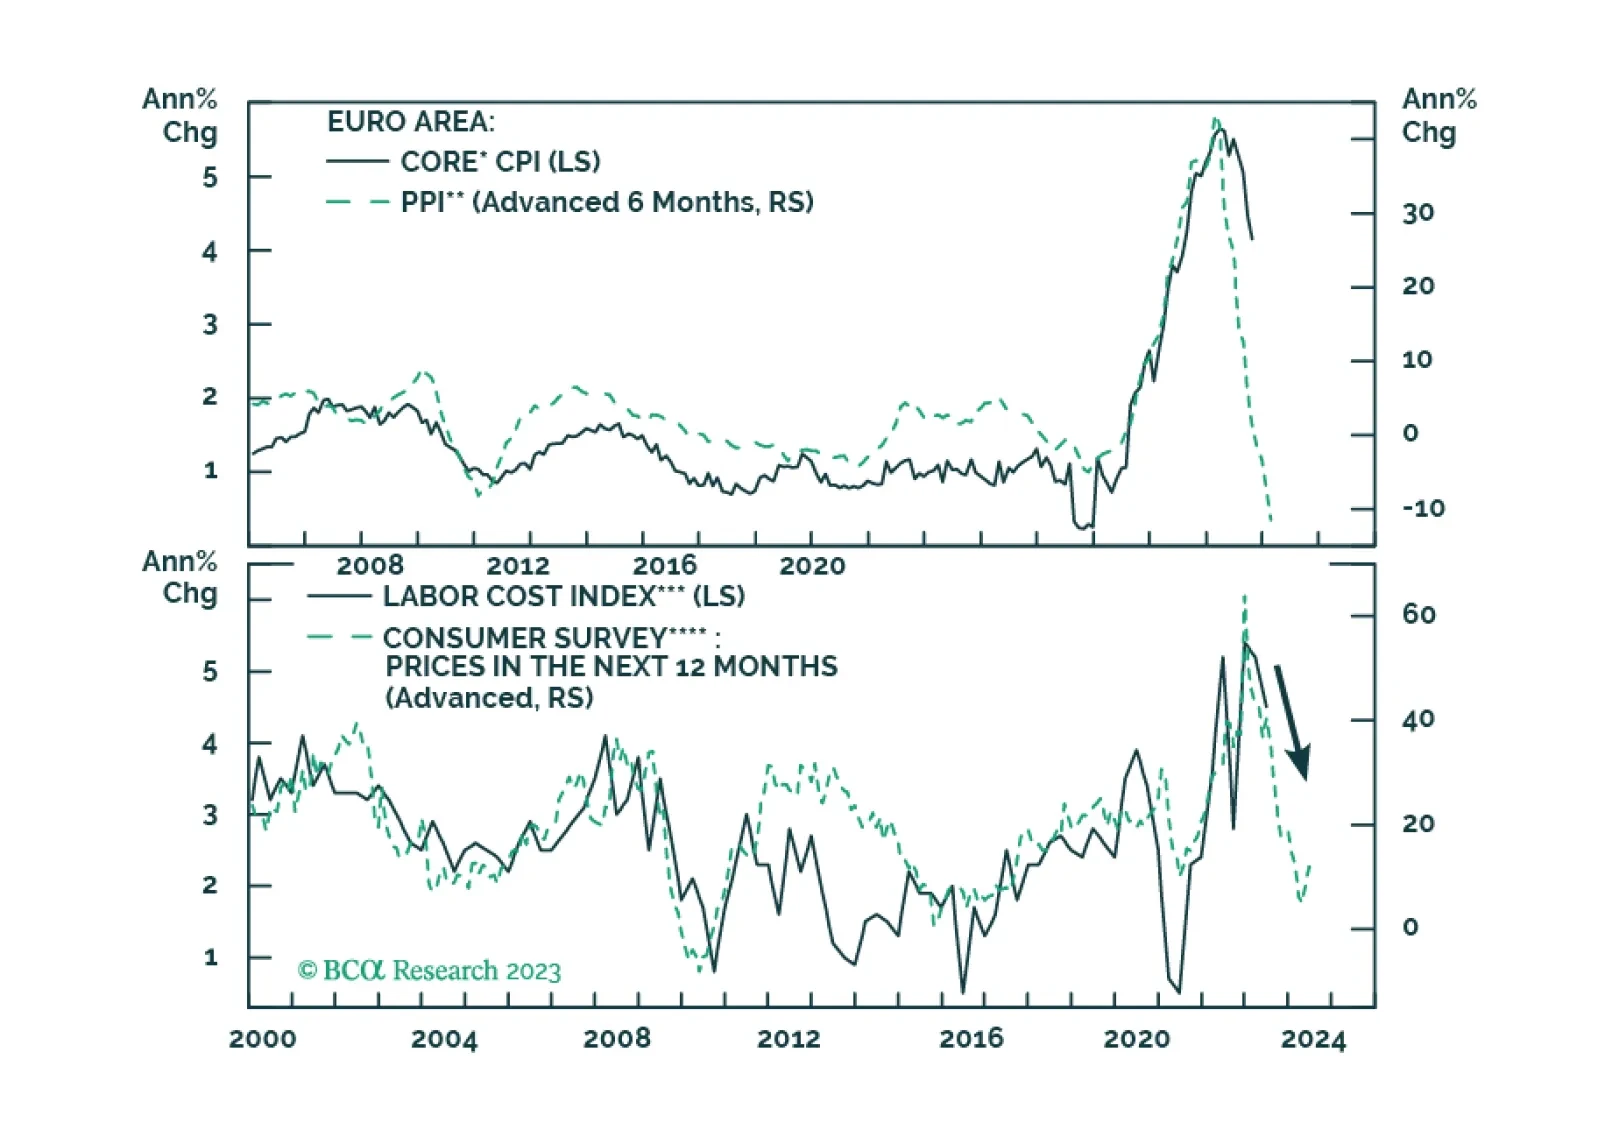
According to BCA Research’s European Investment Strategy service, German yields will fall toward 2% as market-based inflation expectations dip. For now, the deceleration in Eurozone core CPI can be attributed to the effect of the pass-through of energy prices…
The US Federal Reserve Senior Loan Officer Opinion Survey (SLOOS) reveals that US banks continued to tighten lending standards for commercial and industrial (C&I), commercial real estate (CRE), residential real estate (RRE) except government residential…

The Eurozone’s inflation will continue to slow over the coming months. While this trend will help Bund prices, will it boost the appeal of European equities?
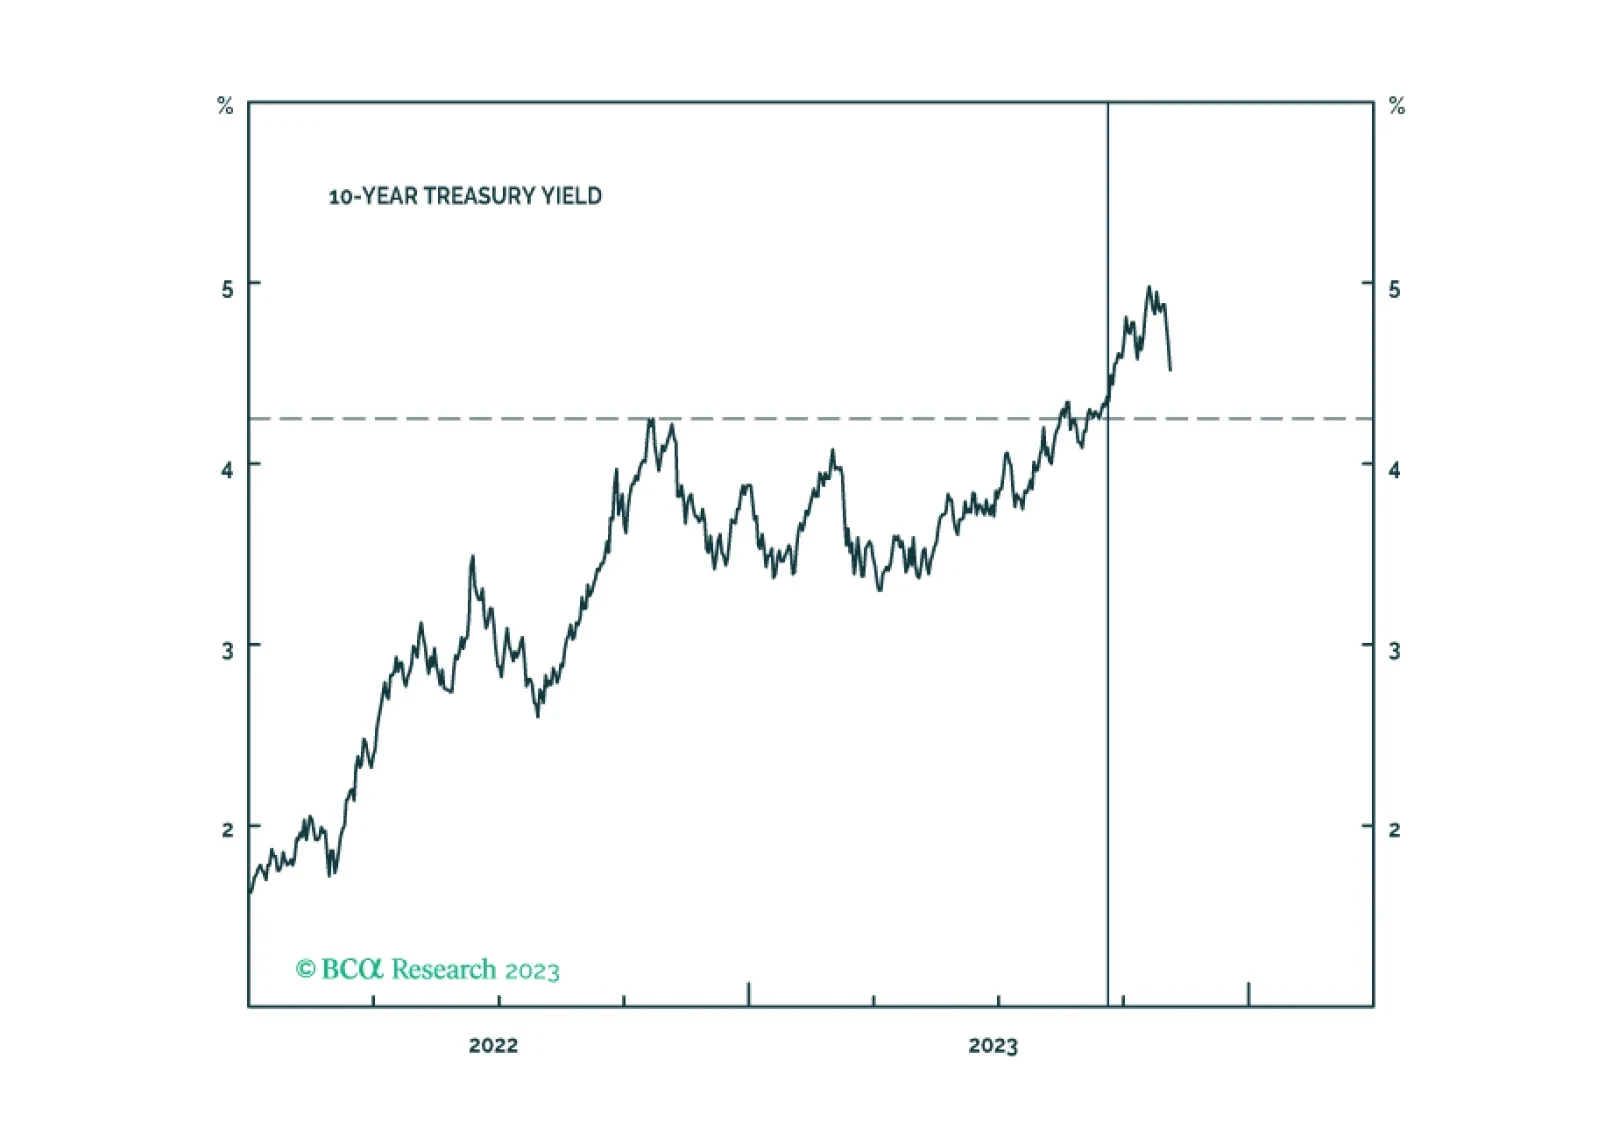
We consider several uncertainties in this week’s report, from the interest rate outlook to the source of the mountain of cash households have amassed since the pandemic began. We have not adjusted our tactical asset-allocation recommendations but will do so soon to align with the defensive cast of our cyclical recommendations.
Special Report

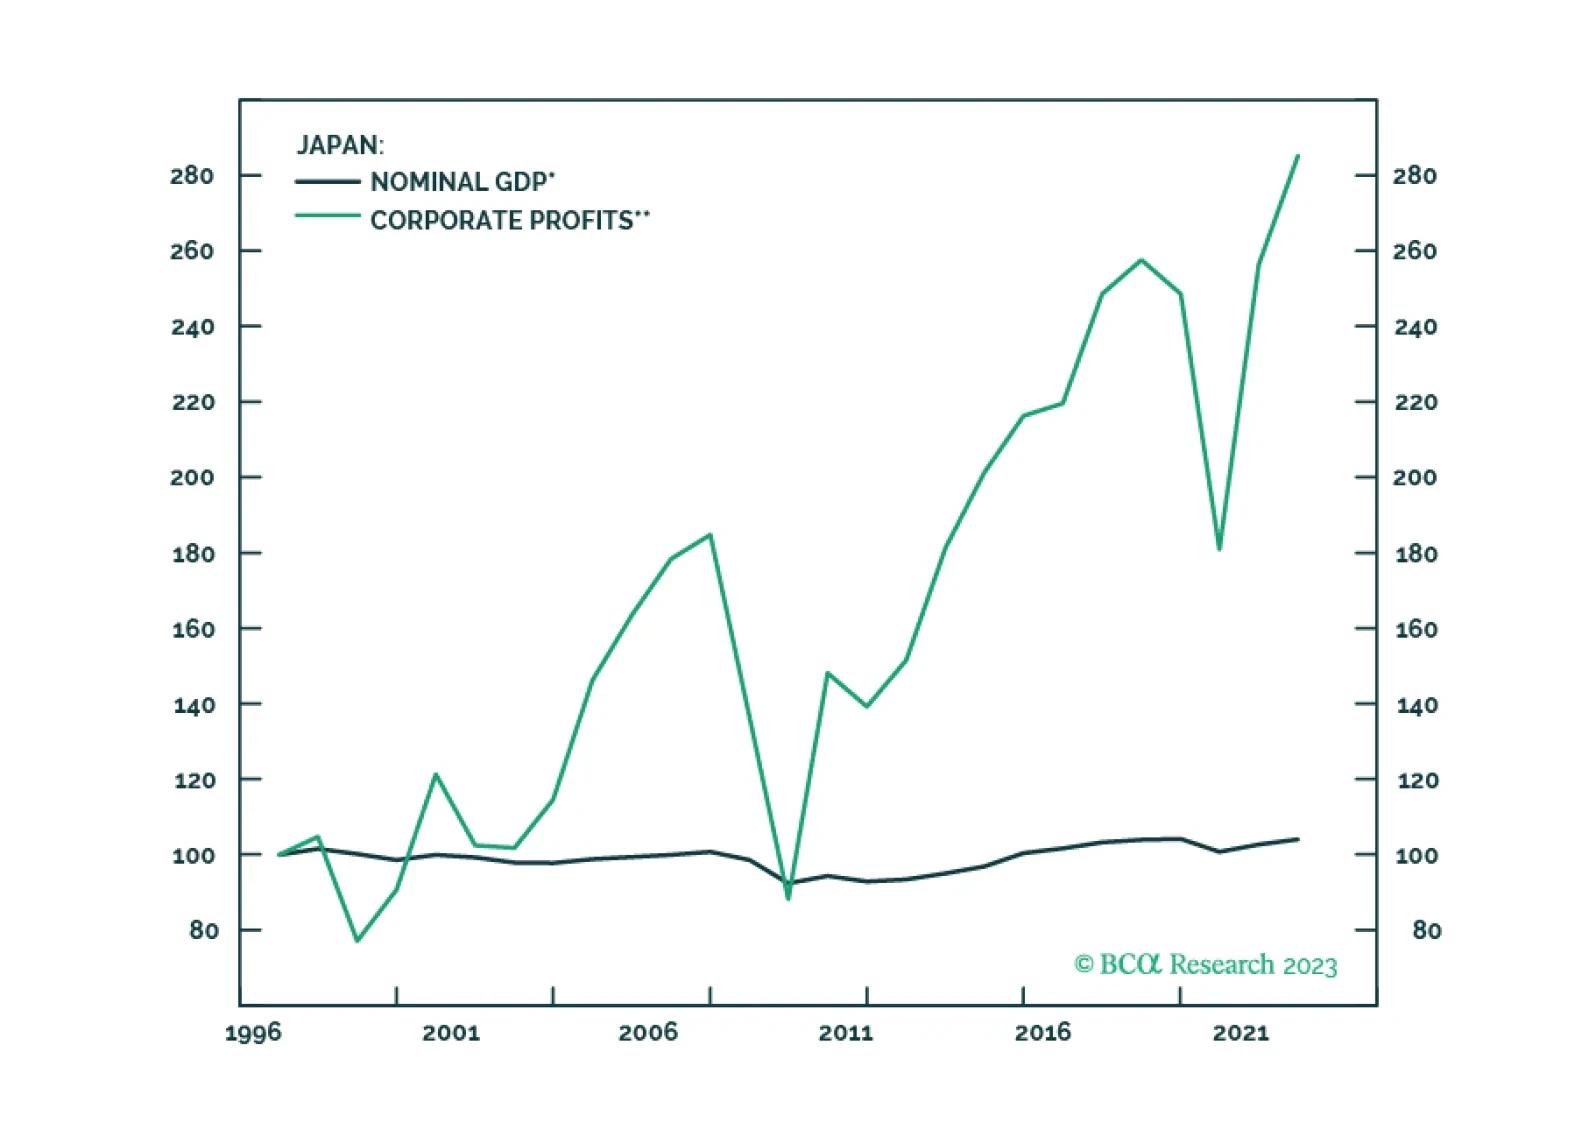
Economic growth has little to no relationship with long-term country returns. But if GDP doesn’t drive long-term equity returns, then what does? To find out, we break down equity total returns of 33 countries from 1997 to 2022 into seven components. In line with other academic research, we find that, over our sample, net buybacks were a crucial factor for long-term country performance. Our research suggests that equity issuance is an underestimated driver of returns that investors should pay more attention to.

The US Nonfarm Payroll report indicates that labor market conditions cooled in October. The 150 thousand increase in payroll employment fell below expectations of 180 thousand and marks a slowdown from the 297 thousand increase in September. Moreover, the…
The US ISM PMI delivered a disappointing signal about service sector activity in October. The headline index fell from 53.6 to 51.8 – marking a sharp slowdown in activity and falling below expectations of a much more muted decline to 53.0. The index is now at…
The South African rand is the best performing major currency since the DXY peaked on October 3. Considering that the rand acts as a proxy for global sentiment towards emerging markets, its recent strength raises the question whether investors are becoming…
The FX G10 attractiveness model continues to favor the US dollar, but the tide could shift in the coming weeks. Currencies such as the NOK, CHF and even CAD have been rising in rankings in recent months. Using an aggregate of economic and financial variables,…
The October update of the Global Manufacturing PMI sent a pessimistic signal about the industrial cycle. The headline index declined from 49.2 to 48.8, indicating a faster pace of deterioration. In particular, the Output, Employment, and New Export Orders…