Economy

The US Conference Board's Leading Economic Indicator (LEI) continues to send a poor signal about the economic outlook. The monthly pace of contraction quickened to -0.8% m/m in October from -0.7% m/m in September. In terms of the drivers of the monthly…
To the extent that Taiwanese export orders act as a bellwether for global trade dynamics, we often monitor the release to gain a sense of the state of the manufacturing cycle. On this front, the October update provided a positive signal. The pace of decline…
As we anticipated in an Insight we published in May, palladium continues to underperform platinum. Last week, platinum's discount to palladium shrunk to its smallest since August 2018. While the prices of both metals have fallen so far this year, palladium's…
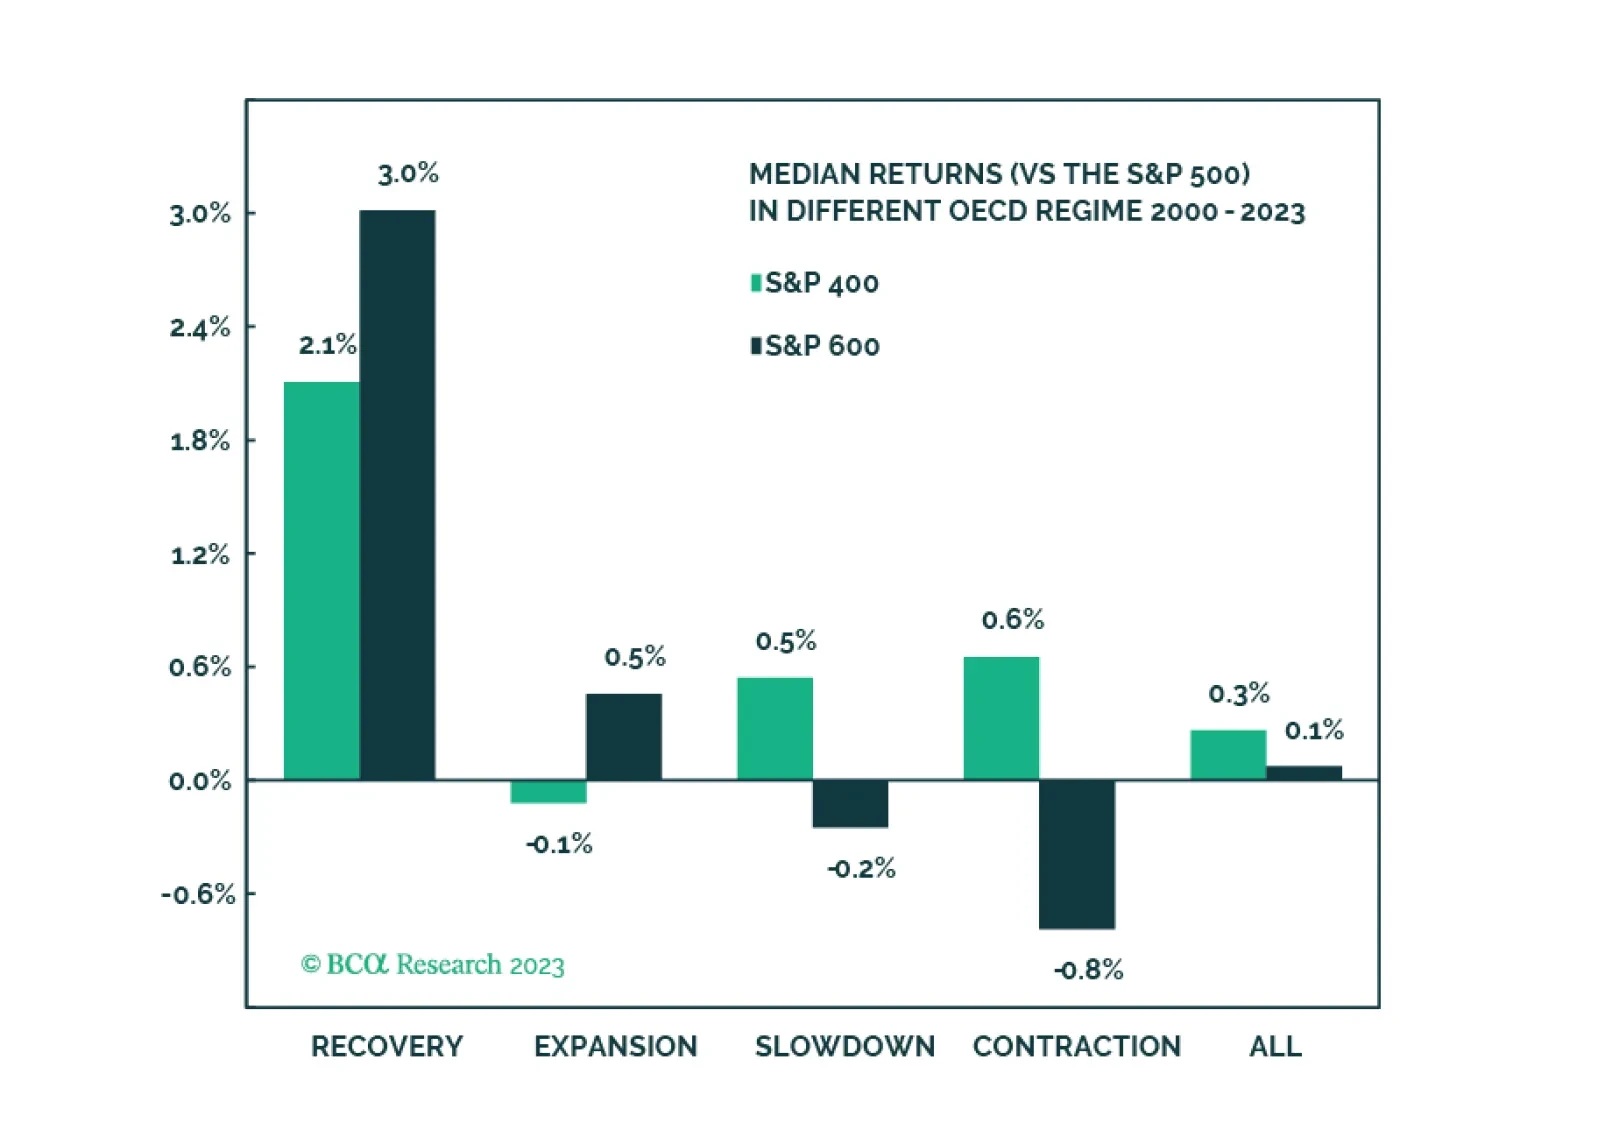
Mid-caps are the best of both worlds and are an excellent strategic overweight thanks to their size premium, but also better financial quality and higher dividend yield than Small. We are bullish on Mid near term and believe that this may be a great trade. We will initiate a position in the S&P 400 as a tactical overweight but will monitor it very closely.
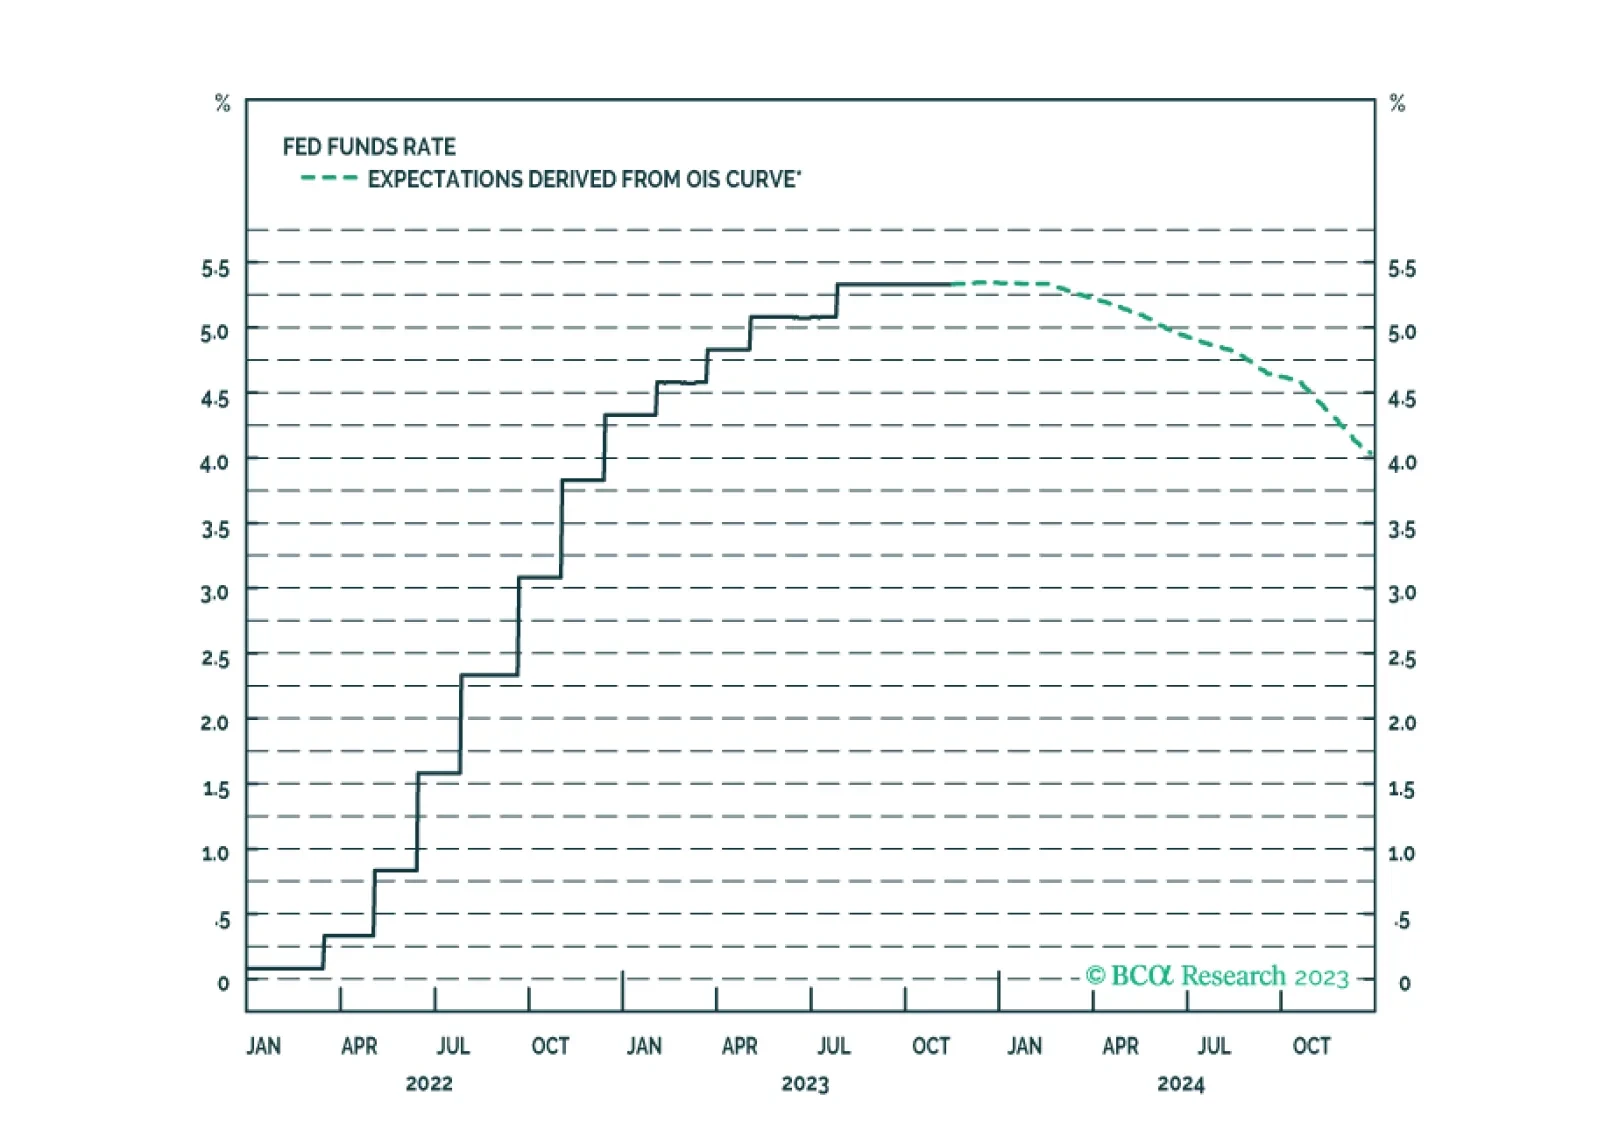
The soft-landing narrative has gotten nowhere at BCA but appears to be making some headway with broker-dealers and investors. We are preparing to lean against it once it pushes equity prices a little higher.
Singapore is a small open economy that is highly sensitive to fluctuations in the global manufacturing activity. As such, Singapore’s non-oil domestic exports (NODX) are a bellwether for global growth. Singapore’s NODX delivered an upside surprise on Friday.…
Recent data releases have painted a mixed picture of US housing market dynamics. On the one hand, housing starts and building permits unexpectedly increased on a month-on-month basis in October. After falling in 2022, housing starts have somewhat stabilized…
Global market sentiment has improved notably since late-October. In the equity space, DM and EM stocks have gained 8.5% and 7.8% respectively since October 26. Regarding currencies, the counter-cyclical DXY index has lost 2.2% so far in November. And as we…
Oil prices have relapsed despite the supply cuts and the geopolitical volatility stemming from the Middle East. Odds are that global oil demand is downshifting. The chart above illustrates that there is a tight relationship between crude oil prices and the…
BCA Research's US Bond Strategy service continues to recommend a neutral allocation to TIPS for now, but with a bias to turn underweight. The team calculates a forecasted range for headline CPI inflation of 0.9% to 2.9% over the next 12 months. For core CPI…