Skip to main content

Economy

We rank the US spread sectors in terms of risk versus reward.

The US Conference Board’s Leading Economic Index (LEI) fell by 0.4% m/m in January, following a 0.1% m/m drop in December – disappointing expectations of a milder decline. This marks the 23rd consecutive monthly decrease and has pushed down the index to its…
Chinese policymakers surprised on Tuesday with greater-than-anticipated easing for the troubled property market. Although the 1-year loan prime rate (LPR) – the benchmark for most household and corporate loans – was kept unchanged at 3.45%, the 5-year LPR –…
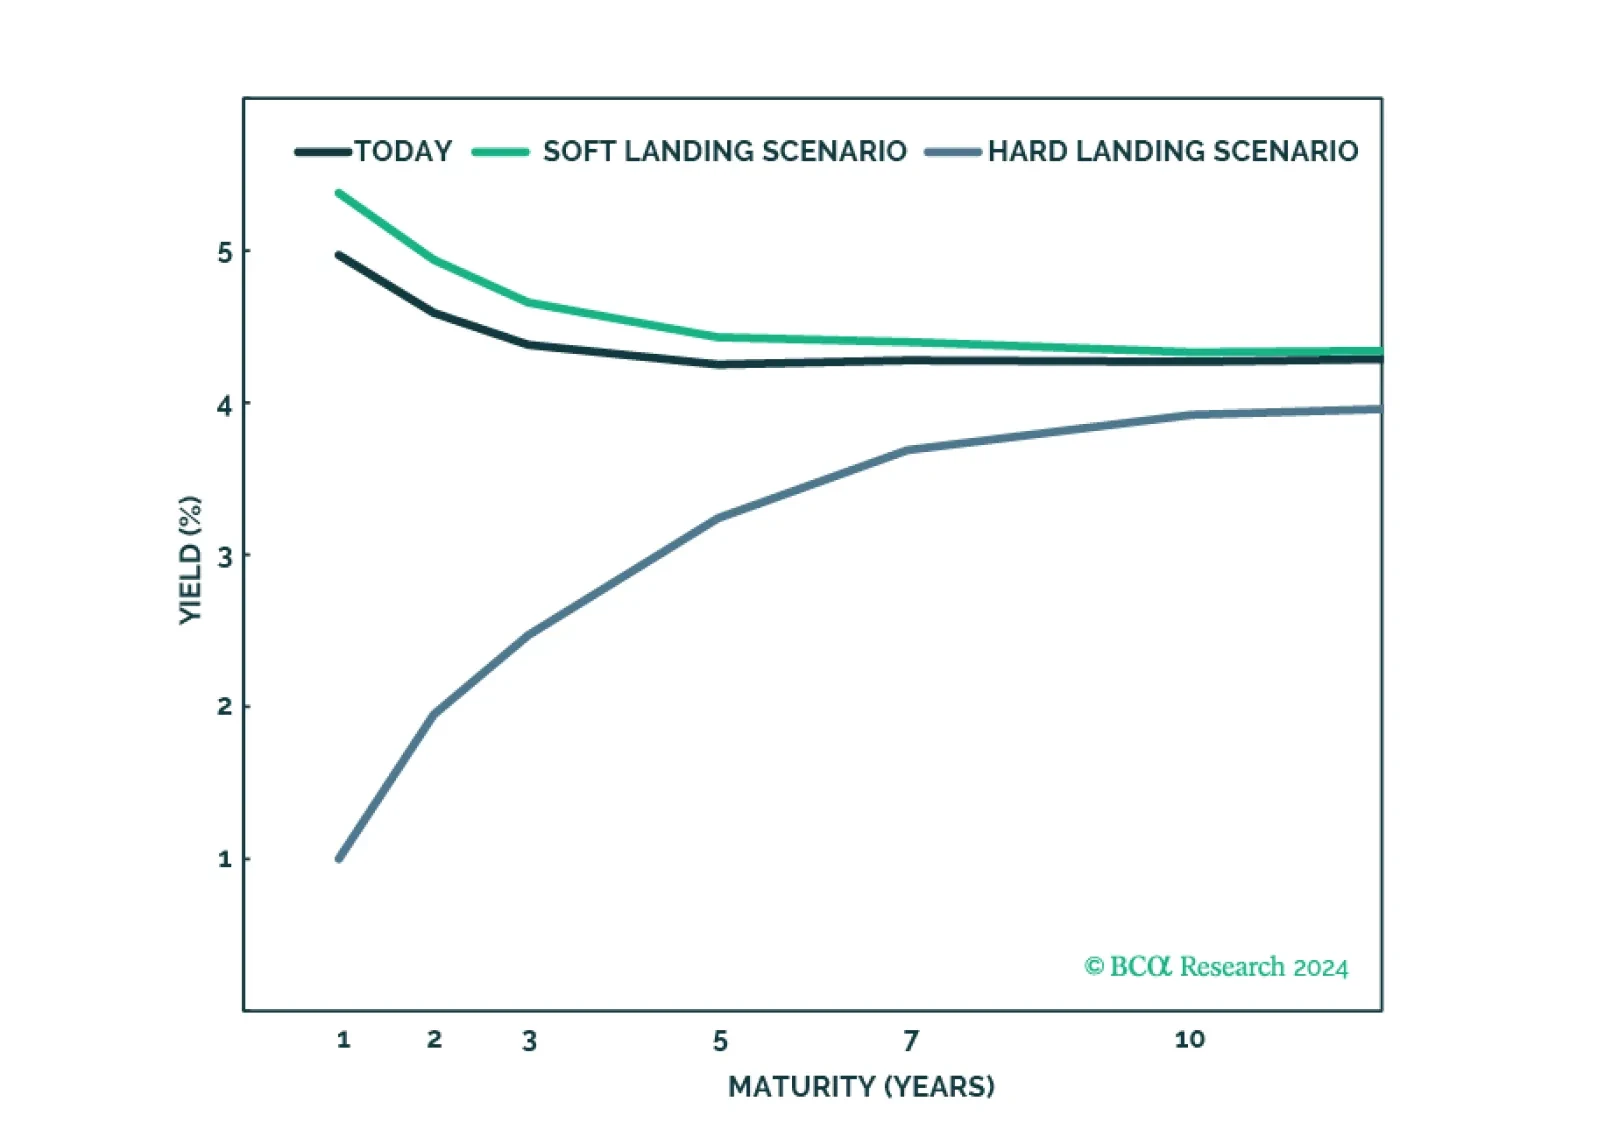
US Treasuries have been selling off over the past two months as investors downgrade the odds of an imminent start to the Fed’s easing cycle. Naturally, a question facing investors is whether current levels constitute a good opportunity to increase duration…
The Health Care sector is among the best performing US equity sectors so far this year. Its 6.2% year-to-date price gain exceeds the S&P 500’s 4.3% increase and is second only to Communication Services. This marks a shift in dynamics from the earlier part of…

Democrats remain favored for reelection in 2024, which implies gridlock and policy status quo in 2025. That is not negative for stocks in the near term. However, economic, political, and geopolitical risks will escalate from here, causing volatility.

The stronger-than-anticipated acceleration in Sweden’s headline CPI inflation is unlikely to derail the Riksbank’s plan to pivot to policy easing this year. In particular, base effects from lower energy prices a year ago are behind the 1-point increase in…
The S&P 500 forged a new all-time high last Thursday and ended the week with a 4.9% year-to-date gain, extending the rally that started in late-October. Interestingly, the recent increase comes even though investors have priced out a Fed rate cut in March and…
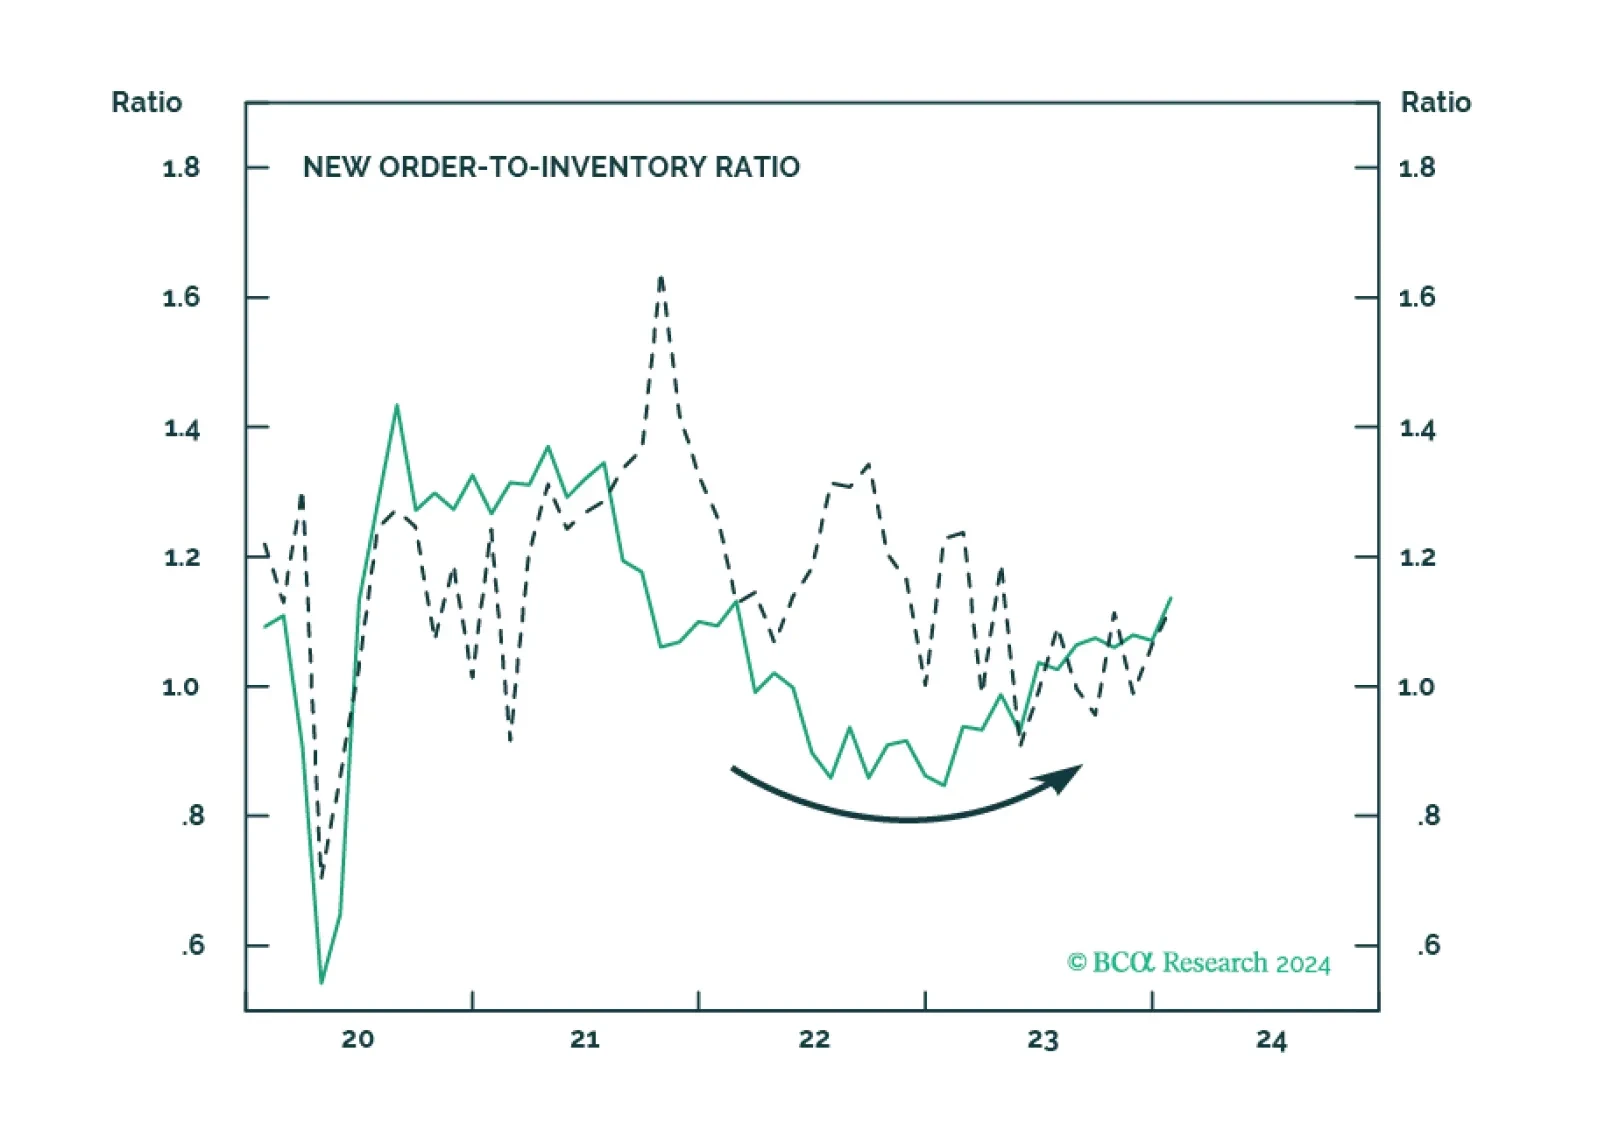
Much of the focus of investors concerned about lingering price pressures has been on services prices. There is good reason for that. Even though core CPI inflation remains relatively elevated at 3.9% y/y in January, core goods prices fell by 0.3% y/y and are…

Reported earnings for Q4-2023 were rather underwhelming and prone to issues that we have identified over the past few months: Growth is concentrated in just a few sectors and companies, while the profitability of a broad swath of the equity market is under pressure from disinflation and sticky wages. Consumers are still spending, but less enthusiastically than before, while a switch from spending on services to spending on goods is in its very early innings. Downgrade Consumer Staples to neutral.