Economy

Swiss annual inflation continued to decelerate in February, with headline CPI now at 1.2% and core at 1.1%. This is remarkable since inflation continues to track well below the 1.8% forecast by the Swiss National Bank (SNB) for the first quarter. Import and…
Economic sentiment has improved since the December FOMC meeting, with positive momentum extending into February. The chart above neatly summarizes the impact that the Fed’s projected easing has had on sentiment, both on “Wall Street” and “Main Street”. The…
The JPM Global Manufacturing PMI improved from 50.0 to 50.3 in February, indicating that global manufacturing activity is growing again after having contracted for 18 months. Notably, new orders expanded from previously contracting levels (from 49.8 to 50.4)…
According to BCA Research’s European Investment Strategy service, the underperformance of European assets relative to the US is due its lagging productivity, even after adjusting for sectoral compositions in their stock markets. Structurally, European goods…
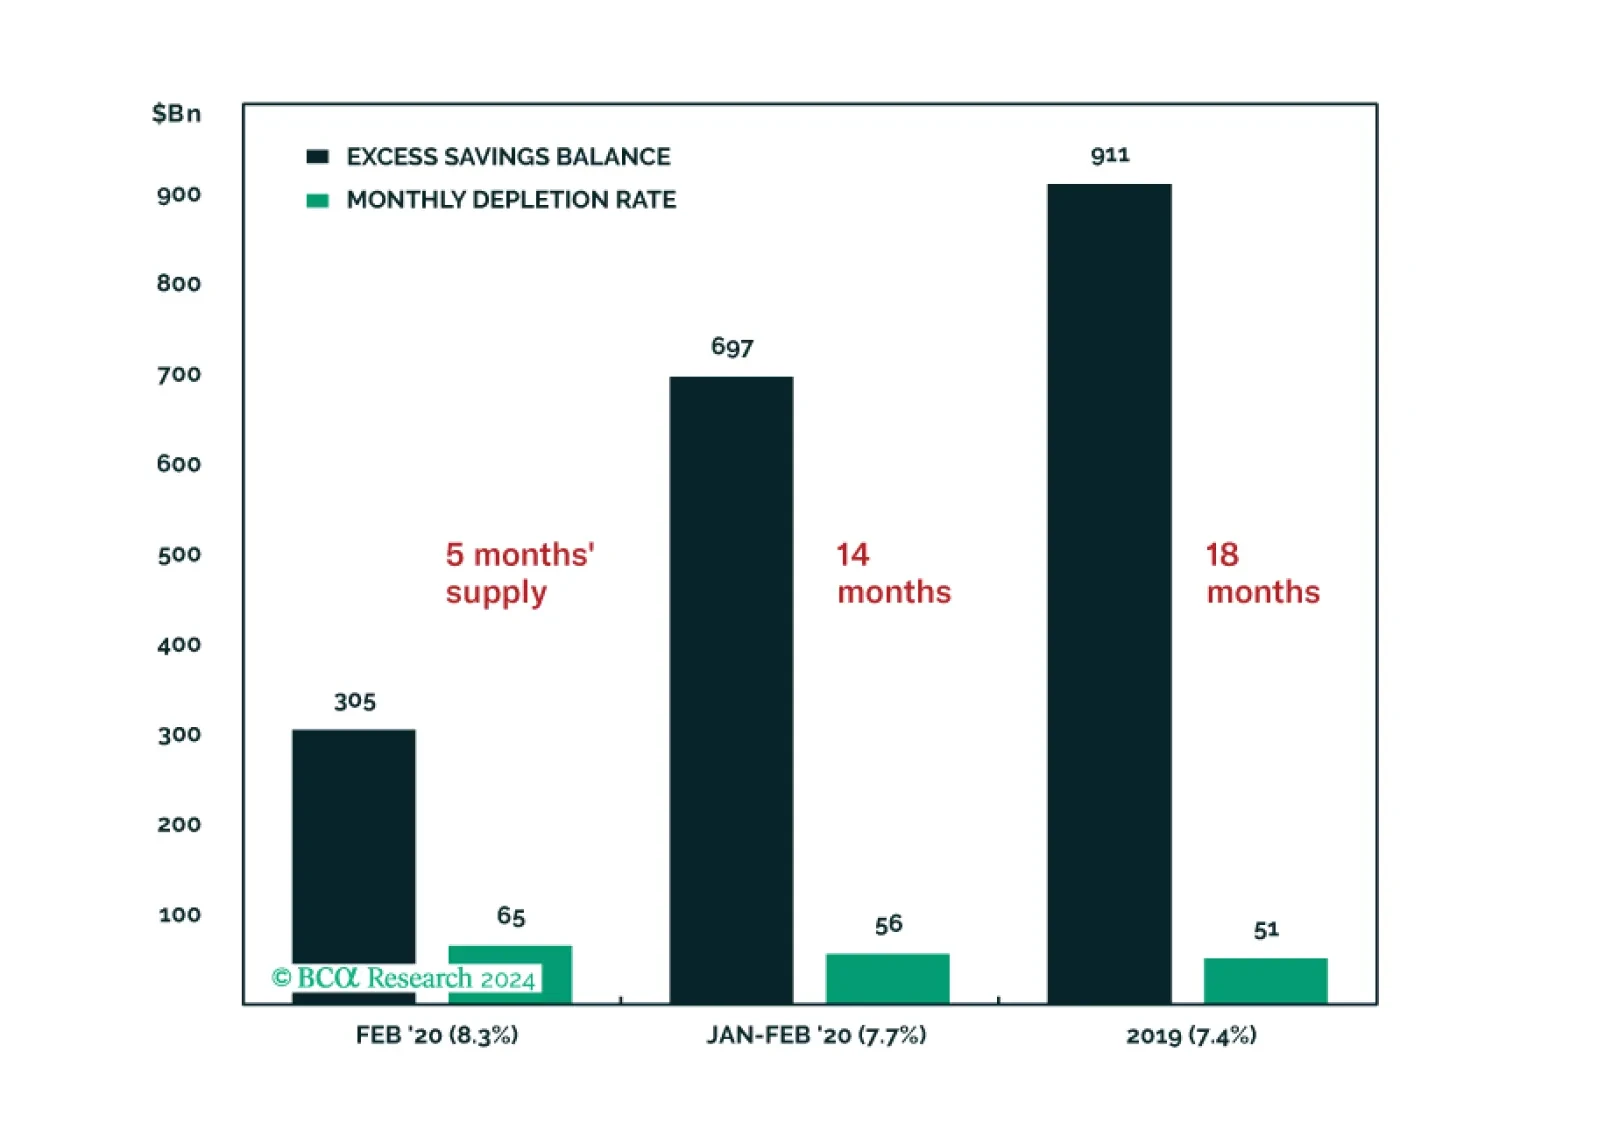
We feel as good about spurning the soft-landing narrative today as we did about spurning the recession narrative a year ago, but we are not giving into complacency. This week’s report looks at two key ways that we may be getting it wrong: by underestimating households’ asset support and the labor market’s durability. We remain tactically neutral but continue to look for opportunities to turn defensive.
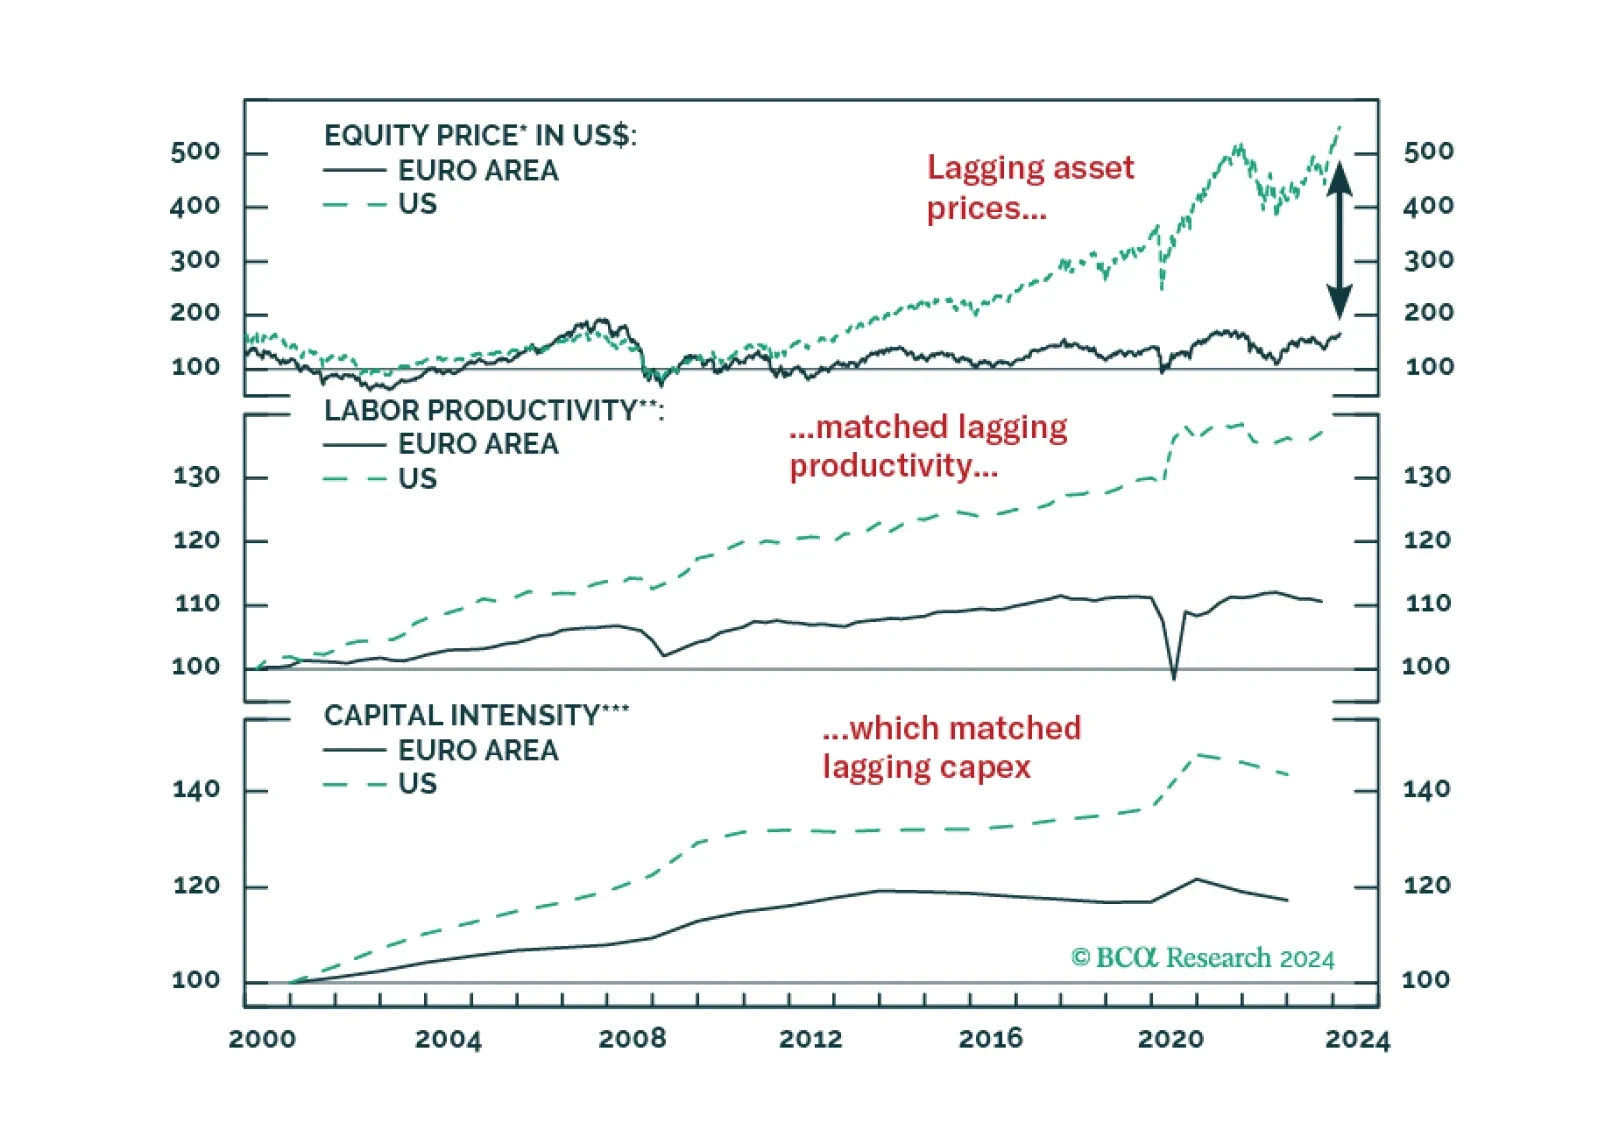
Europe’s productivity growth lags that of the US. While structural factors contribute to Europe’s lower productivity level, the region’s recent lost decade plays an even greater role.
The US ISM manufacturing PMI release for February disappointed consensus expectations. The headline index relapsed to 47.8 after climbing to a 15-month high of 49.1 in January, falling below expectations of a continued slowdown in the pace of contraction to…
The preliminary Eurozone inflation release suggests that price pressures eased by less than anticipated in February. Headline CPI inflation slowed from 2.8% y/y to 2.6% y/y (slightly above expectations of 2.5% y/y. Similarly, although the core inflation gauge…
As we highlighted in a previous Insight, the breadth of the US equity rally has been relatively narrow, led by extremely strong gains among Big Tech stocks. Tech is still the best performing sector, with the S&P IT price index up 12% year-to-date on top of a…
The global equity rally – which fizzled at the start of the year – picked up steam again in February with nearly all major regions posting above average returns. After having underperformed last year, Chinese stocks led their global counterparts in terms of…