Economy

We assign high odds that the US will tip into a recession by year-end or early 2025. Given it has been the largest driver of global demand in this cycle, a US recession will morph into a global downturn. The procyclical Eurozone economy is particularly…
BCA’s composite sentiment indicator, compiled from surveys of advisors, individual investors and traders, surged over the past three months from already very optimistic levels. It reached 63% last week, a six-and-half-year high and the third highest point in…
UK’s CPI growth stands right on the Bank of England’s (BoE) 2% target. However, services inflation remains sticky, growing at a constant 5.7% y/y in June. Moreover, the deceleration in wage growth remains insufficient to temper inflationary pressures in the…
The US economy has clearly cooled from its above-trend pace of growth in 2023. The consensus view among BCA Research’s strategists project that this deceleration will eventually culminate in a recession by year-end or early 2025. Our US Investment strategists…
Total consumer credit rose by USD 11.4 billion in May (to USD 5,065 billion outstanding) from a slightly upwardly revised USD 6.5 billion increase in April, surpassing expectations of a smaller increase. Notably, revolving credit (which includes credit cards)…
The S&P 600 and Russell 2000 have outperformed the S&P 500 by close to 10% since July 9. Small caps typically outperform in the early stages of economic expansions when growth is accelerating, demand-driven inflation is rising and lending standards are…
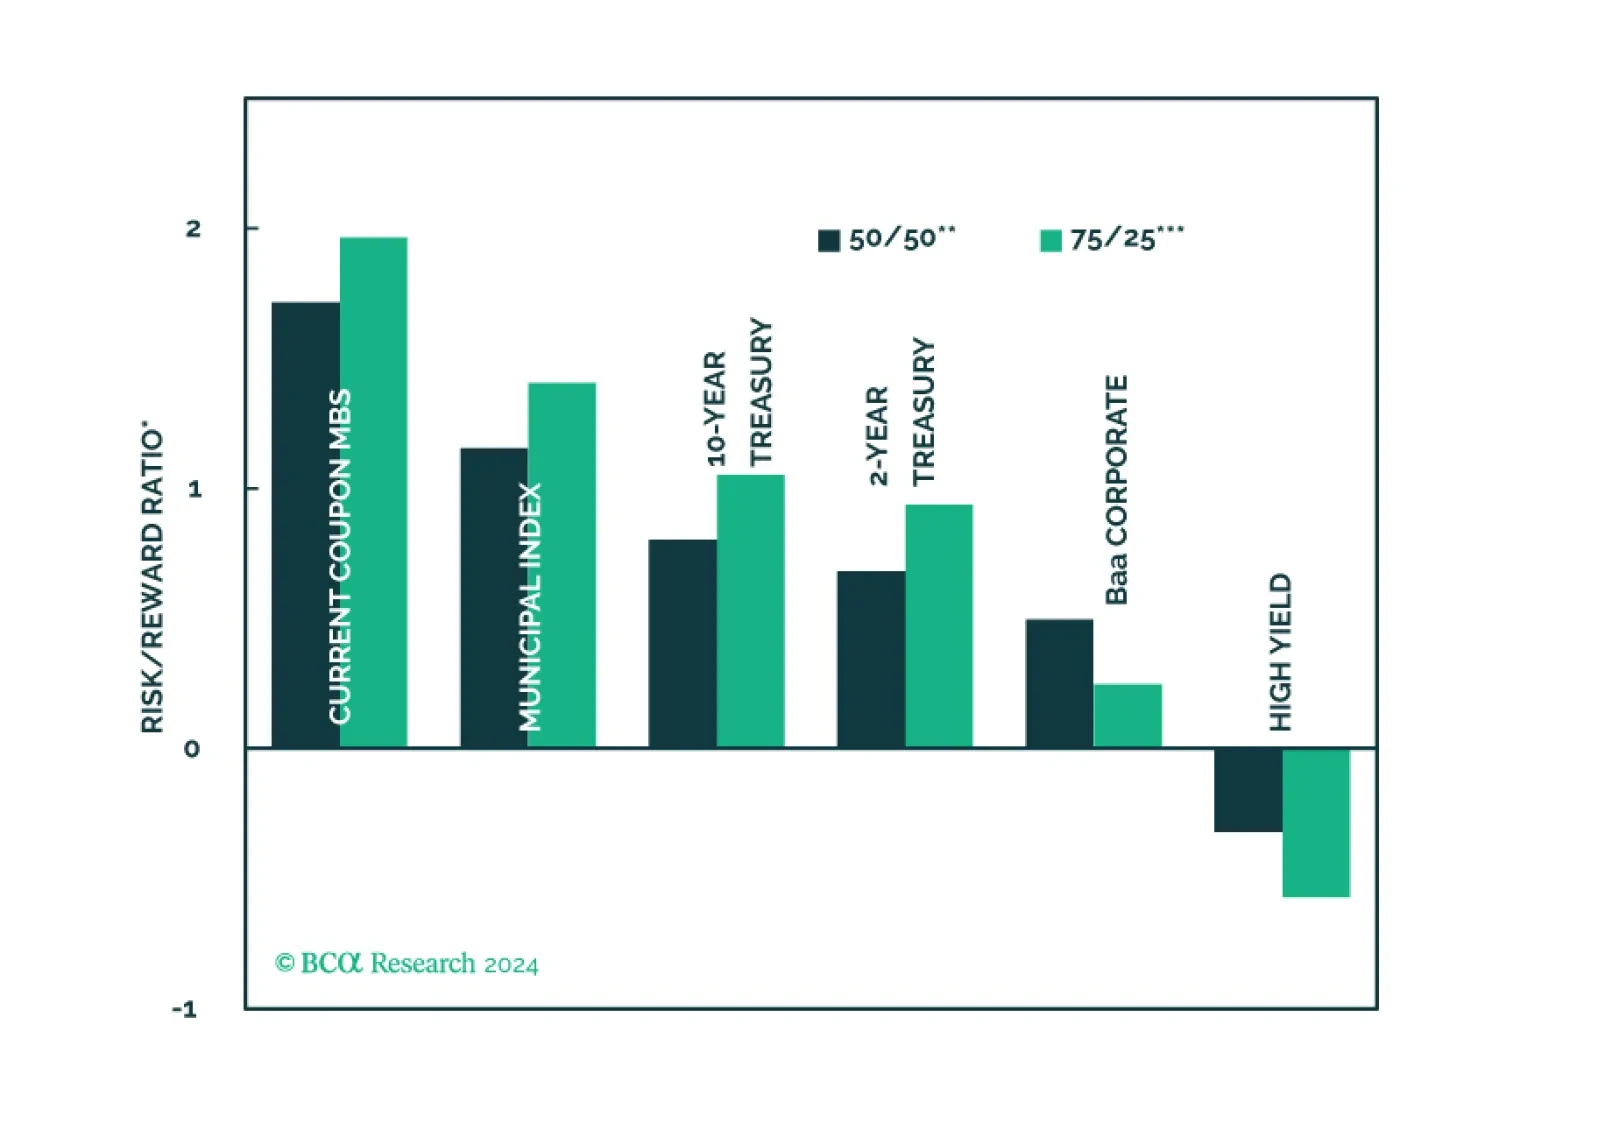
We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
Export dynamics from small open economies are a good bellwether for global growth conditions. Taiwan export orders decelerated from 7.0% y/y to 3.1% in June, badly disappointing expectations of a double-digit growth rate and following two consecutive months…
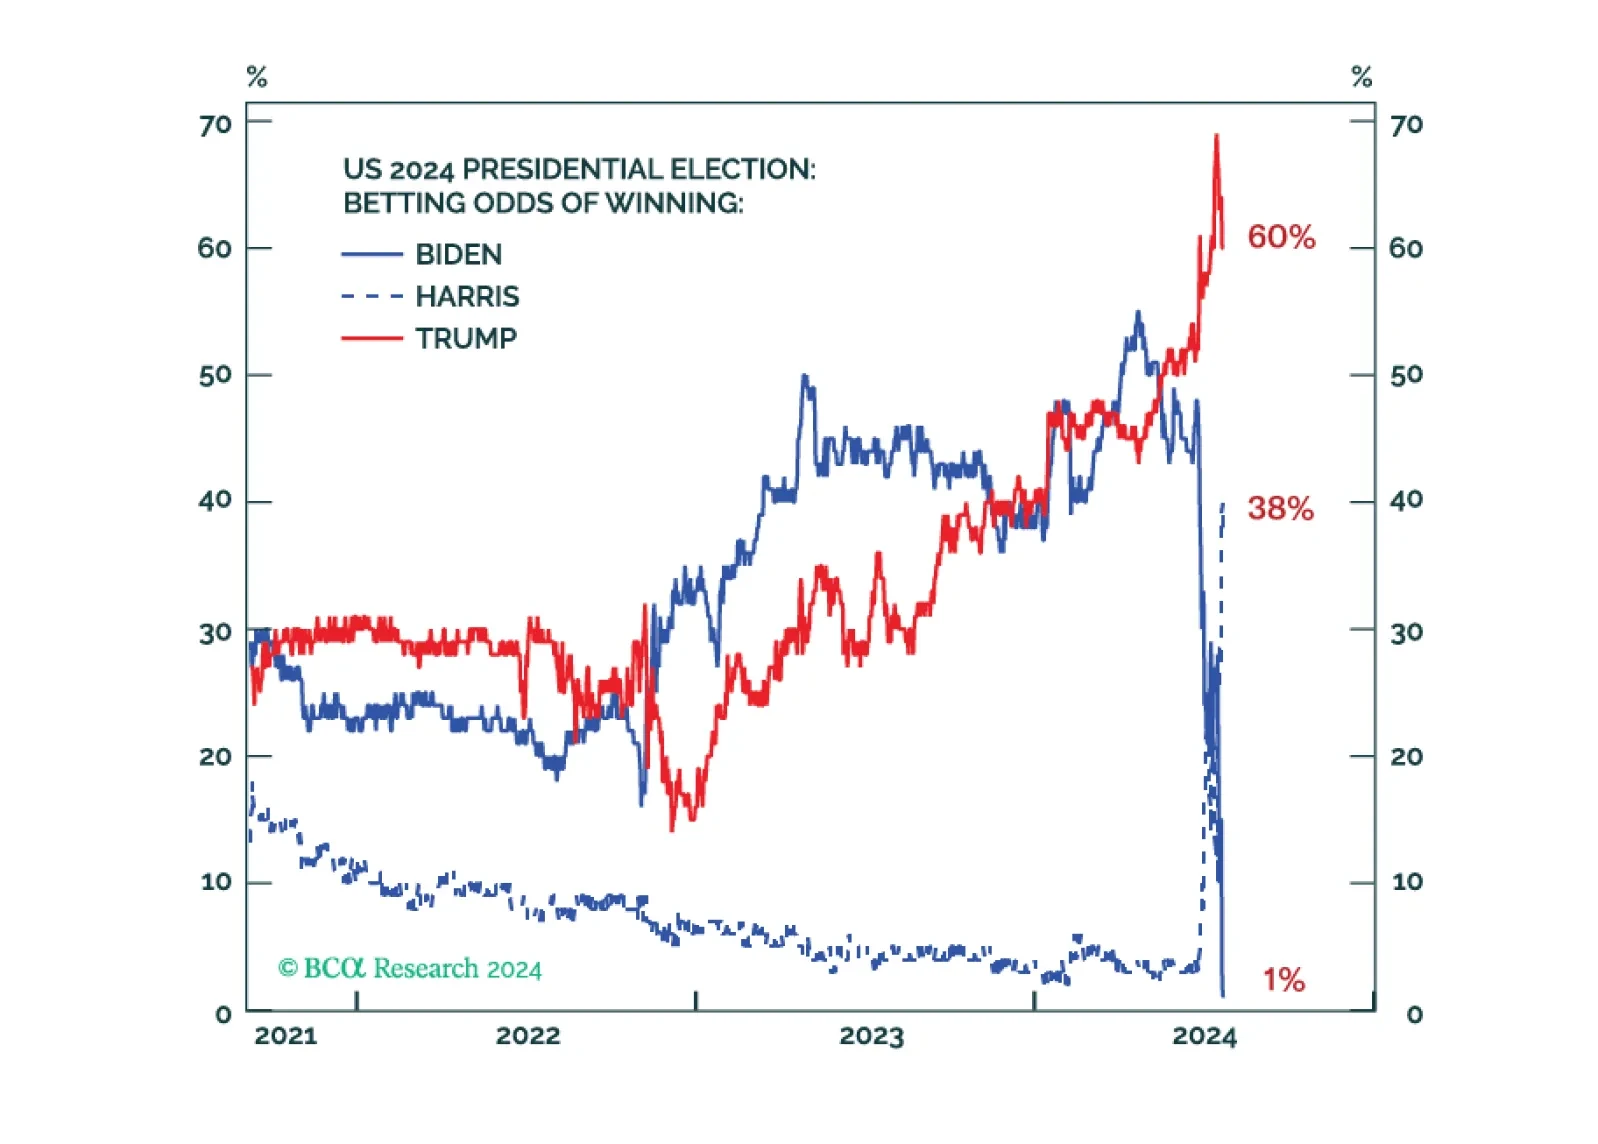
Investors should focus on growth concerns rather than the “Trump trade.” Bond yields will fall in the short run due to cyclically disinflationary economic slowdown, rather than rise in anticipation of a Republican full sweep and inflationary policies, which are likely but not yet a done deal.
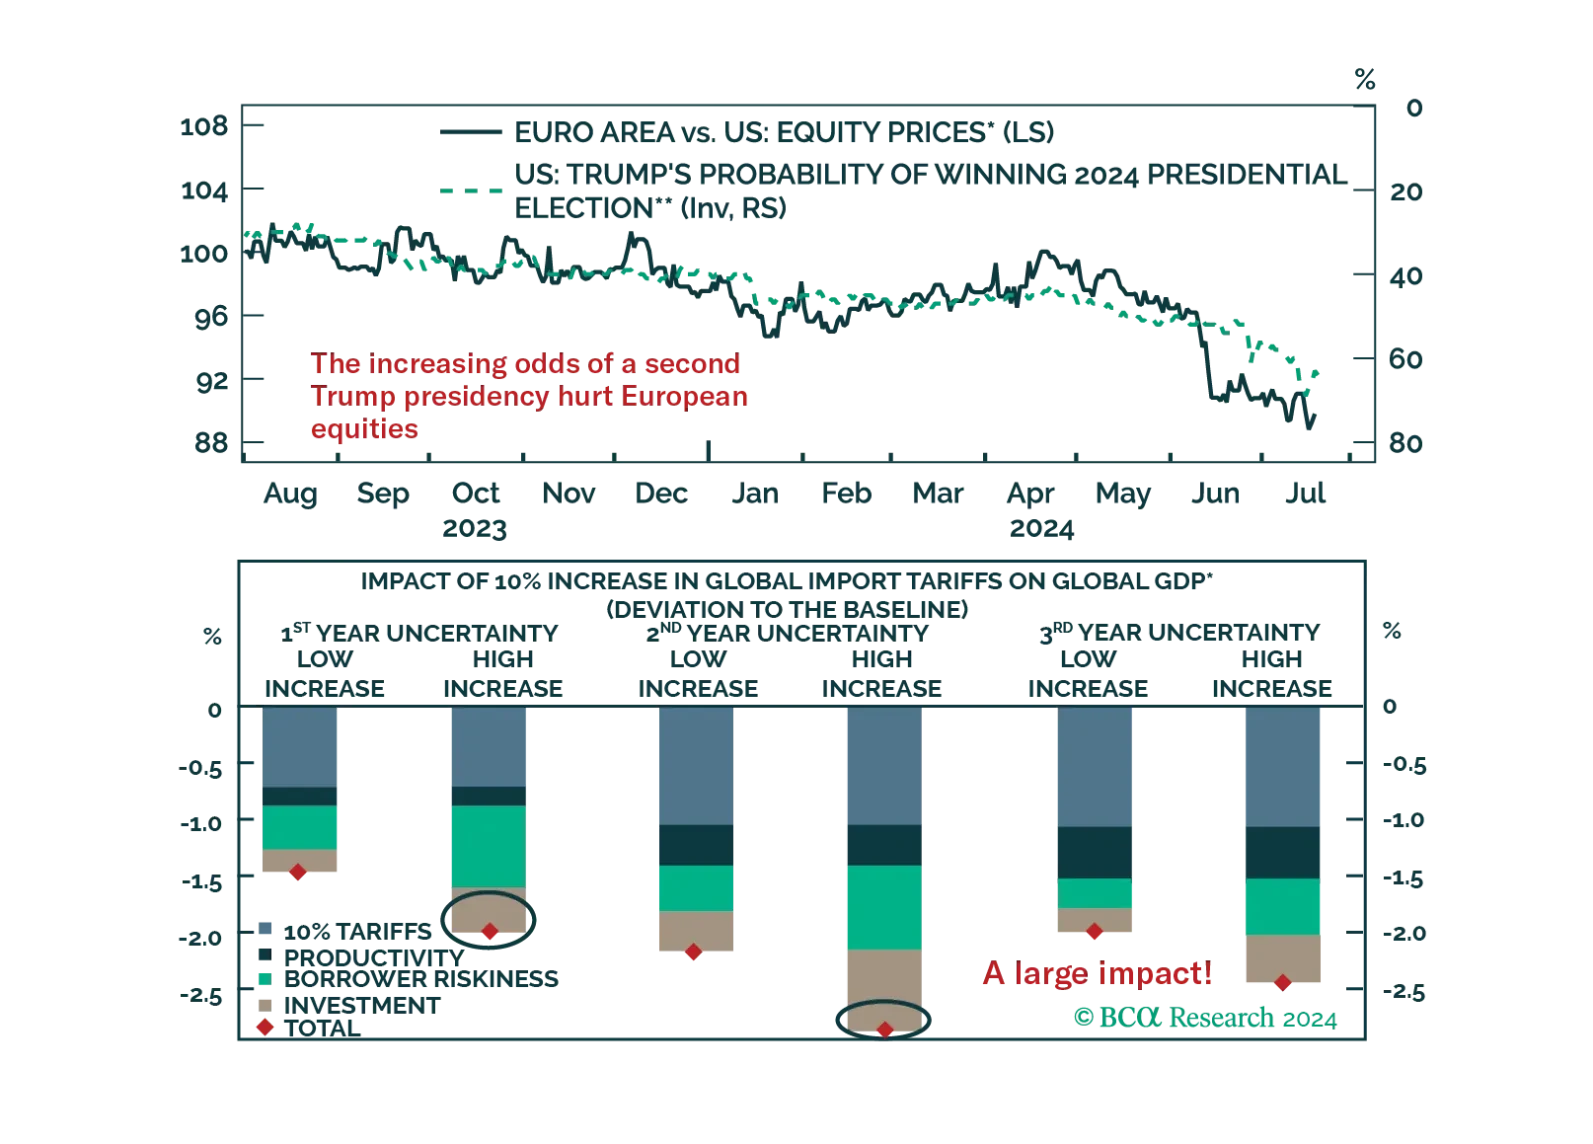
As Trump’s victory odds rise, the underperformance of European equities deepens. How negative would a global trade war be for European assets?