Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Japanese Yen

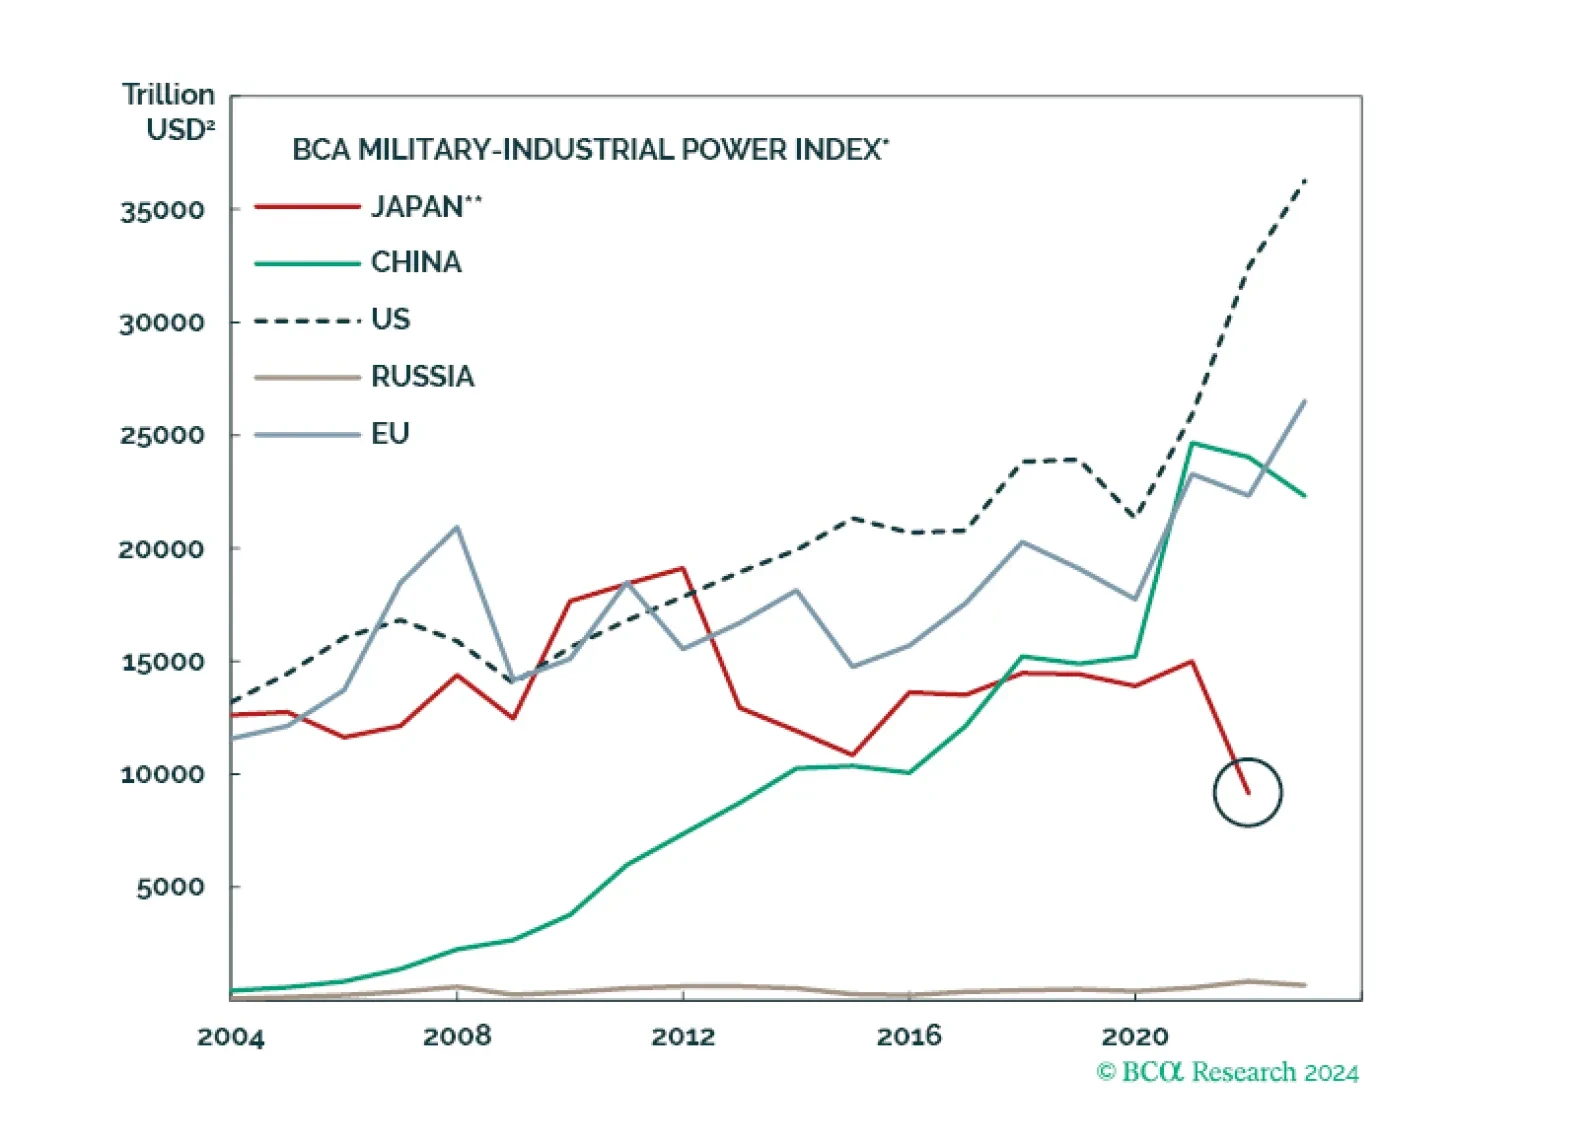
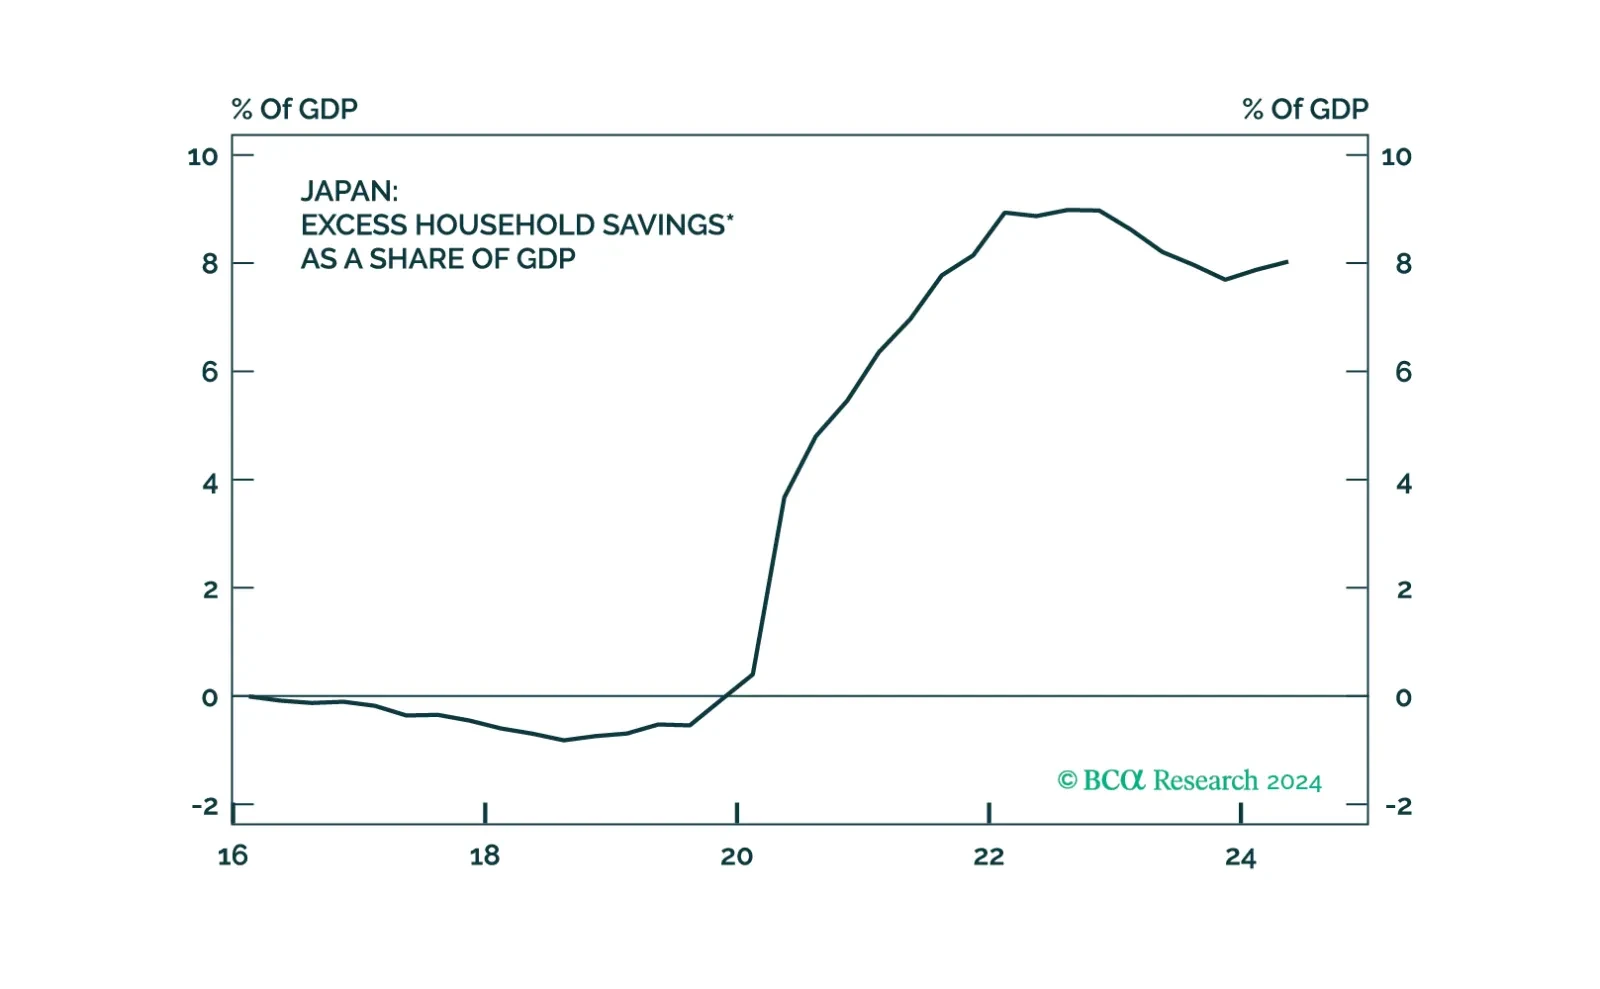
En los próximos meses, el nuevo gobierno de Japón relajará la política fiscal, lo que mejorará la demanda interna marginalmente. La política monetaria puede endurecerse más a corto plazo, pero no demasiado a largo plazo. El contexto geopolítico empuja a Japón hacia una política económica acomodaticia.

La última reunión del Banco de Japón no alteró nuestras firmes convicciones de mantener una posición larga en el yen y una infraponderación en los JGBs.
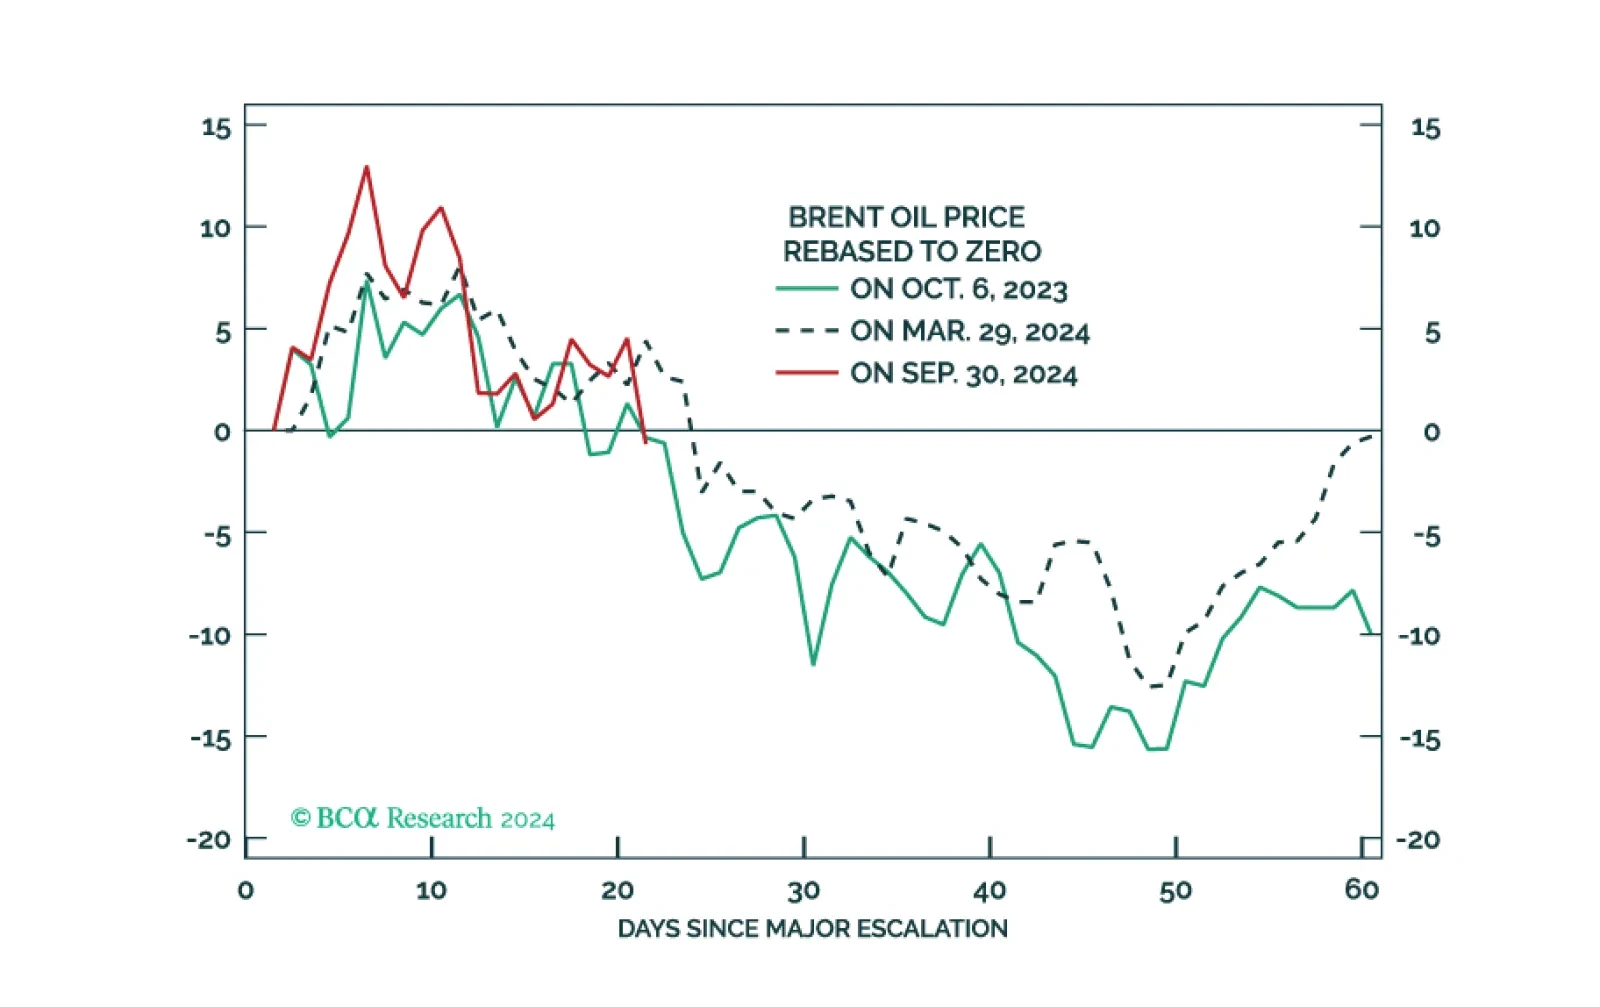
El sistema político mundial se está desestabilizando y Estados Unidos adoptará una postura más agresiva en política exterior, política comercial o en ambas, independientemente del resultado electoral. Tácticamente, apueste por el dólar.
Our Counterpoint Strategy team believes the equity bull market’s biggest risk is the reversal of the divergence between Japanese and US real yields. Japan’s real policy interest rate differential versus the US stands at an unprecedented and unsustainable…

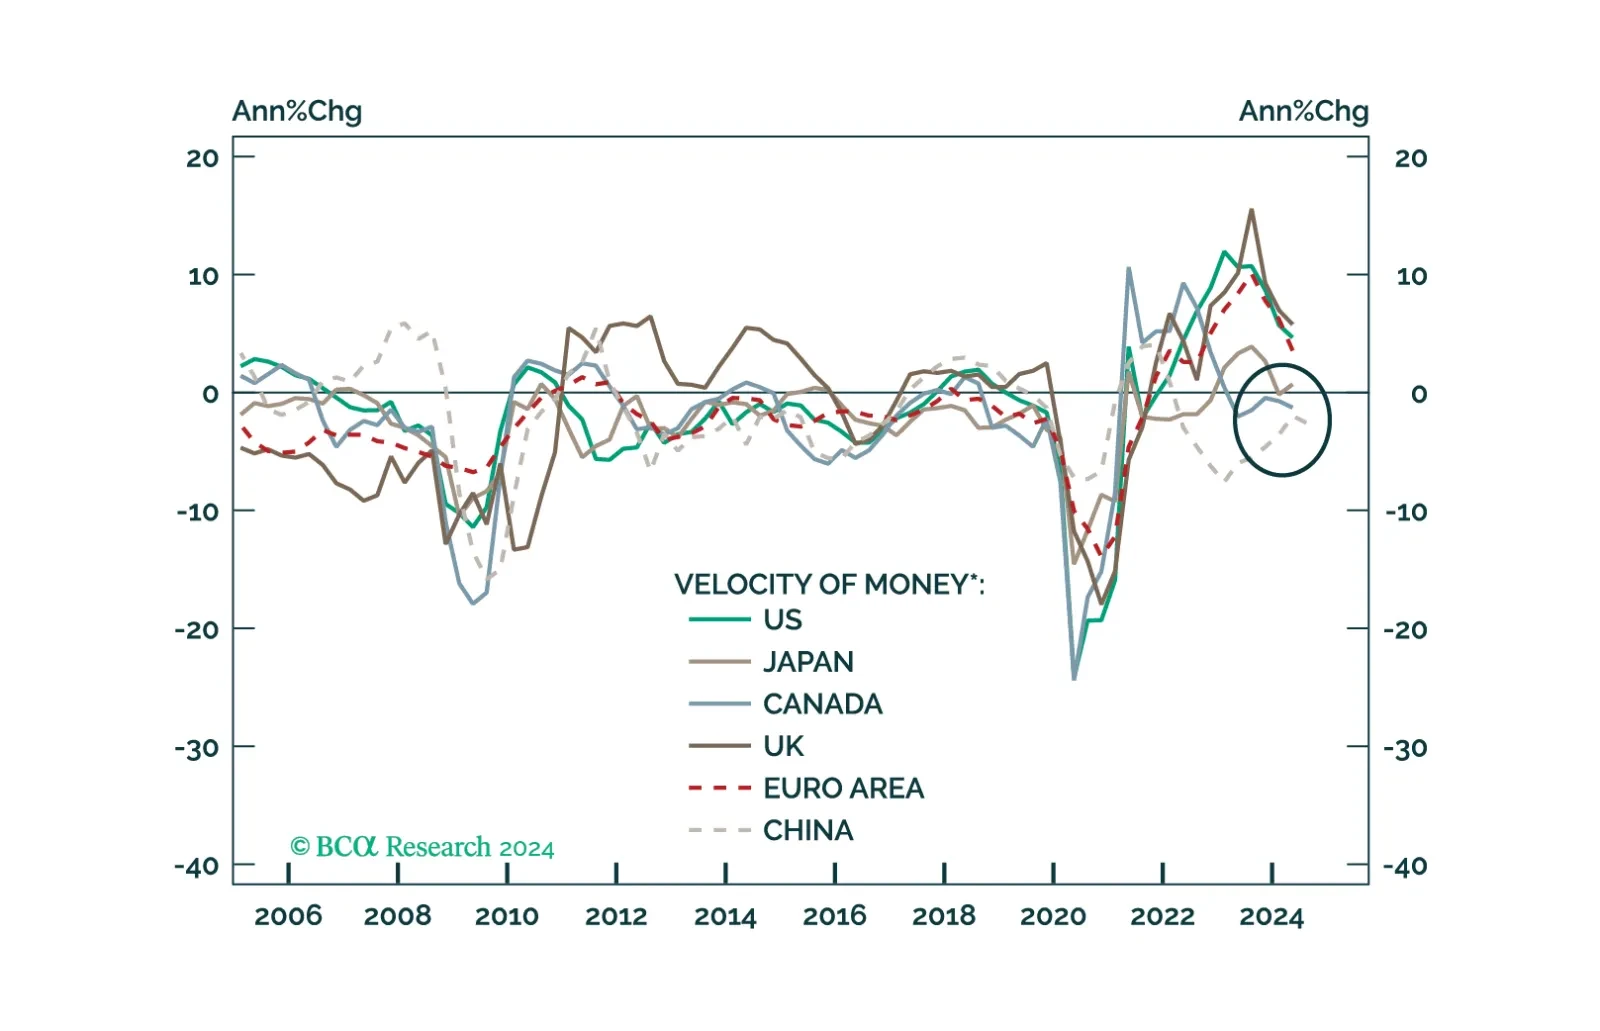
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
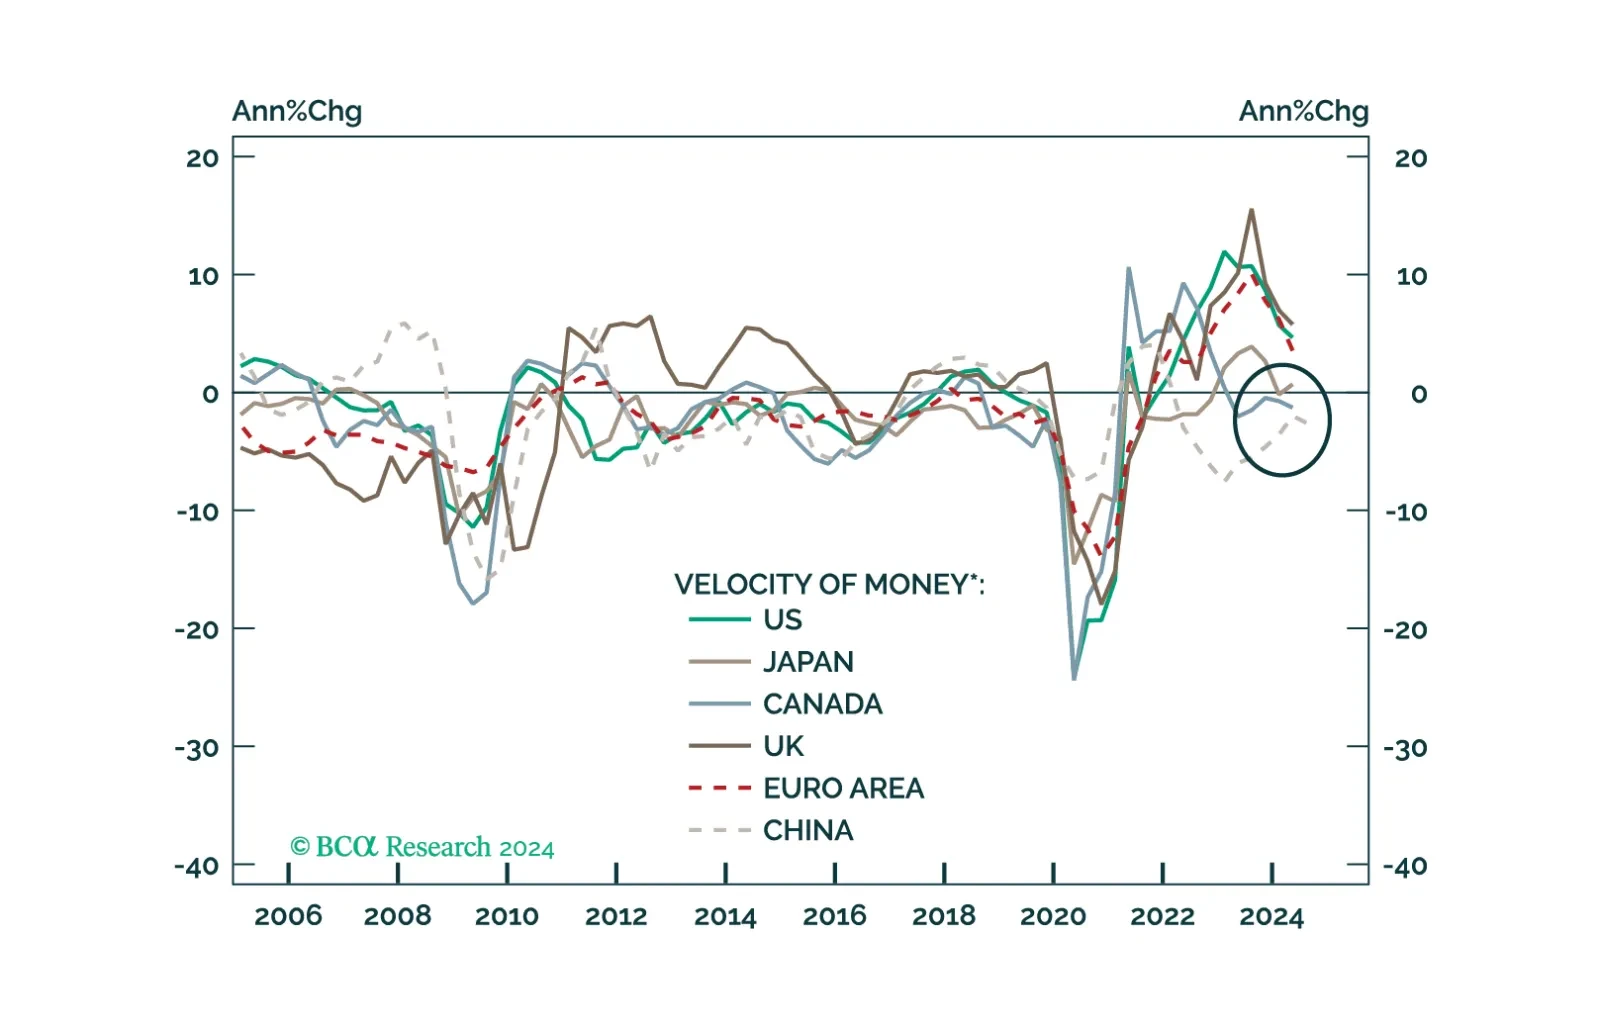
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.

This report looks at the likely path for the dollar and bond yields over the next 6-to-12 months.
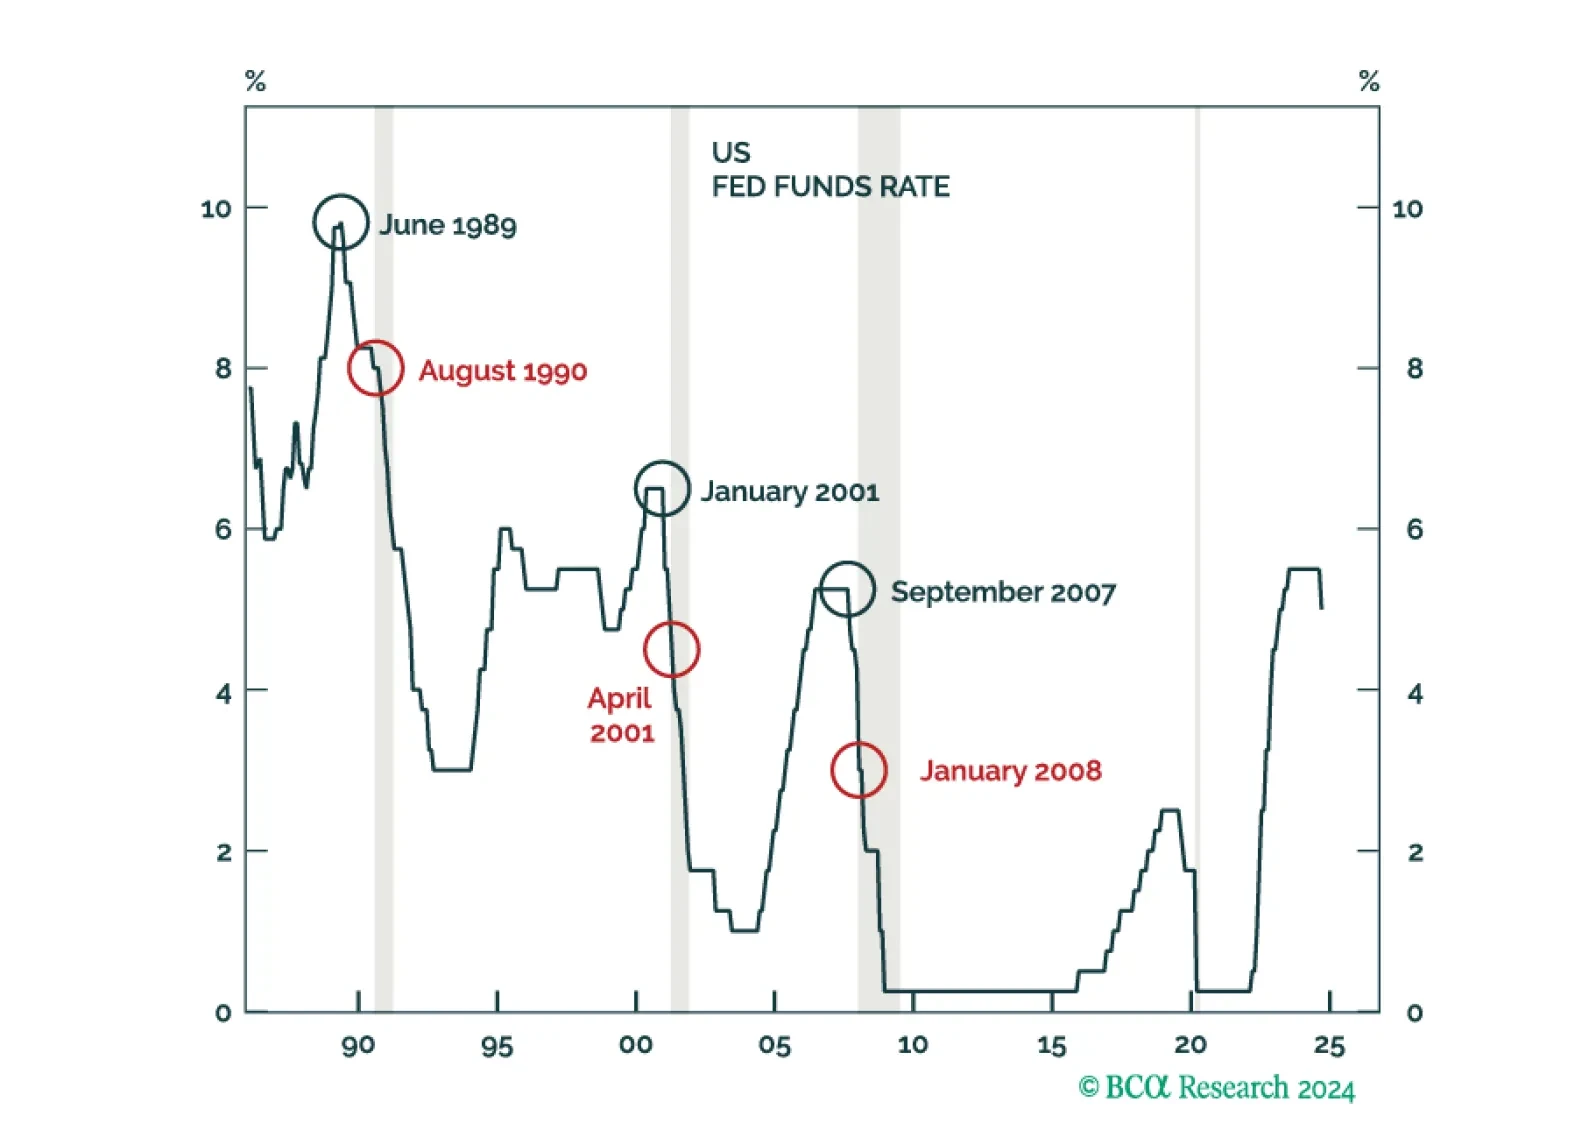
After resisting the consensus narrative in 2022 that a US recession was imminent, and then predicting an immaculate disinflation for 2023, the Global Investment Strategy team has joined the dark side and is now expecting a recession to start in the US within the next six months. Accordingly, we recommend that investors underweight stocks and overweight government bonds.

The Bank of Japan kept its policy rate unchanged at 0.25% in September and signaled it was in no rush to lift rates further. This move follows two hikes this year, one of them unanticipated. The signaling is consistent with dovish comments in August that the…
The Bank of Japan’s policy normalization has been accompanied by exceptional outperformance by Japanese banks. Japanese banks have outperformed both the country’s broader market as well as the MSCI ACW Banks index by 10.3% and 2.6%, respectively, so far this…