Saltar al contenido principal

Estados Unidos

The 10-year US Treasury yield briefly moved above 5% earlier this week before dipping back down. While we can’t rule out another jump back above 5% in the coming weeks, the recent bond selloff has created a good deal of long-run value in US Treasuries. In the…
This year's rally in US equities has for the most part been narrow in breadth. The 19.5% increase in the S&P 500's price index in the first seven months of the year exceeds the equal weighted index's 9.5% gain over the same period. Since then, the S&P 500's…
BCA Research’s US Investment Strategy service studied the SIFIs’ earnings calls for insights into borrower performance, lender willingness, liquidity and the actions and intentions of households and businesses. Nothing in the banks’ commentary suggested that…

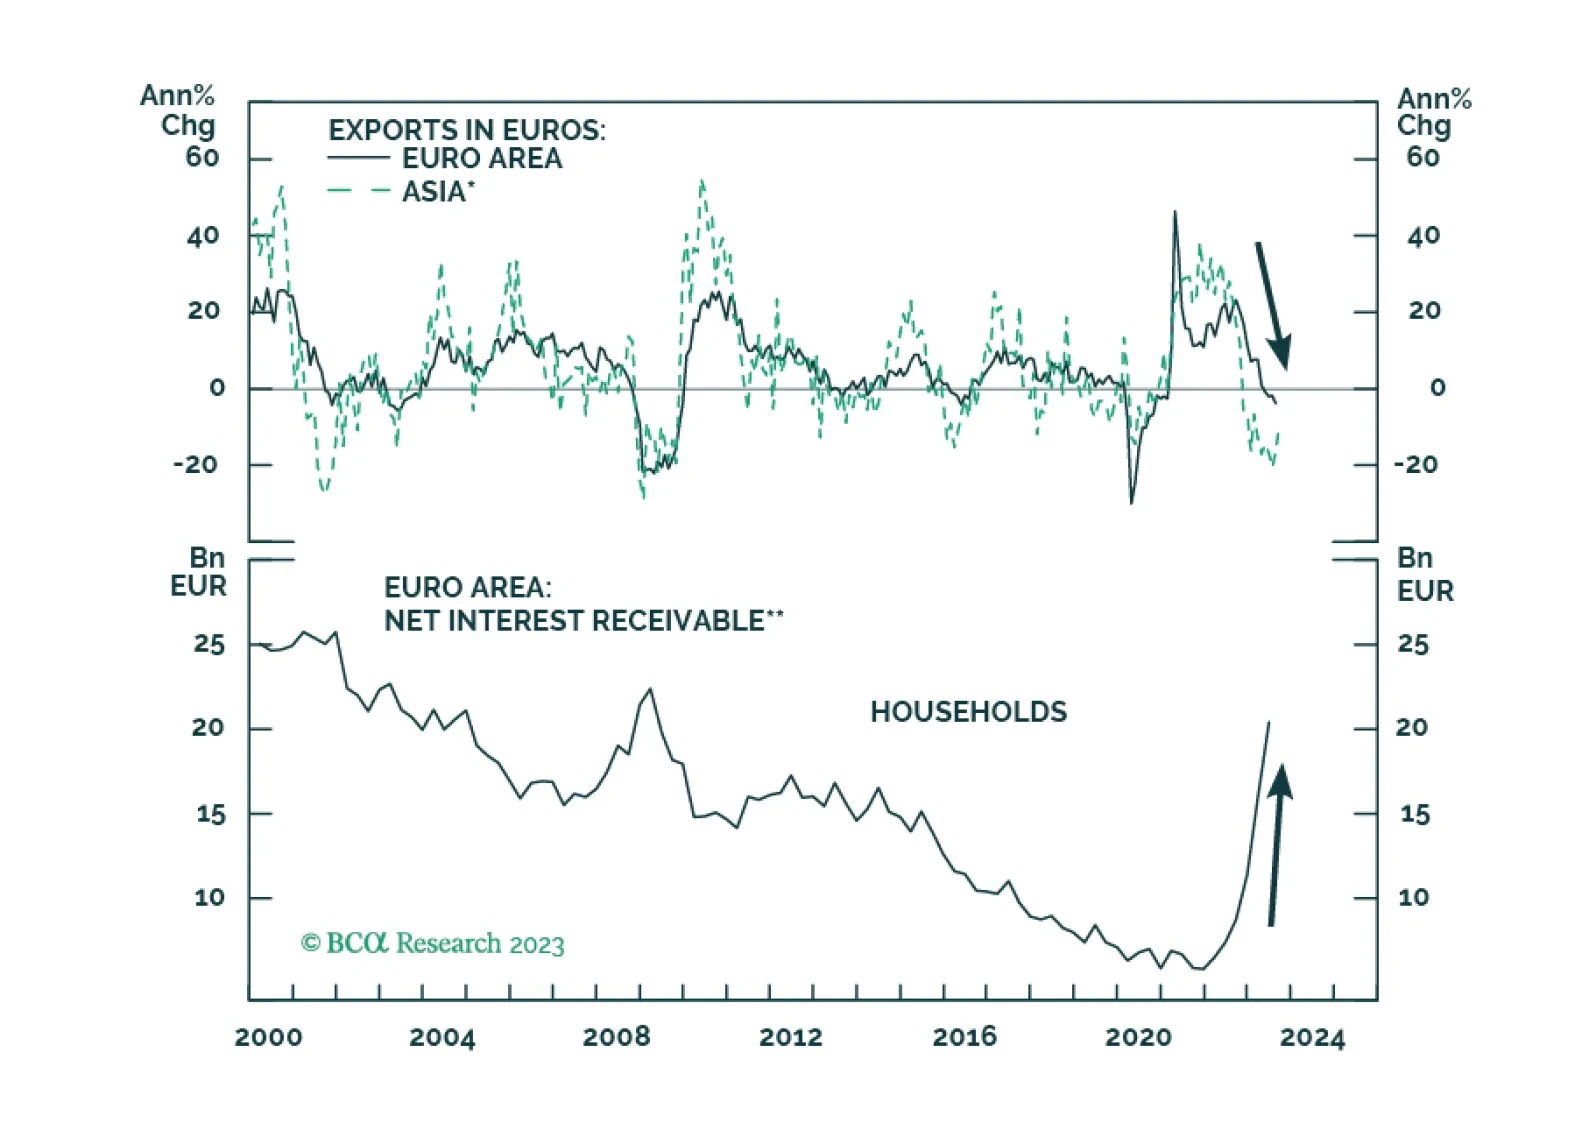
Europe’s weak patch is not about the ECB’s policy tightening, at least not yet. 2024 is another story, and the ECB’s policy will prompt a Eurozone’s recession around the summer.
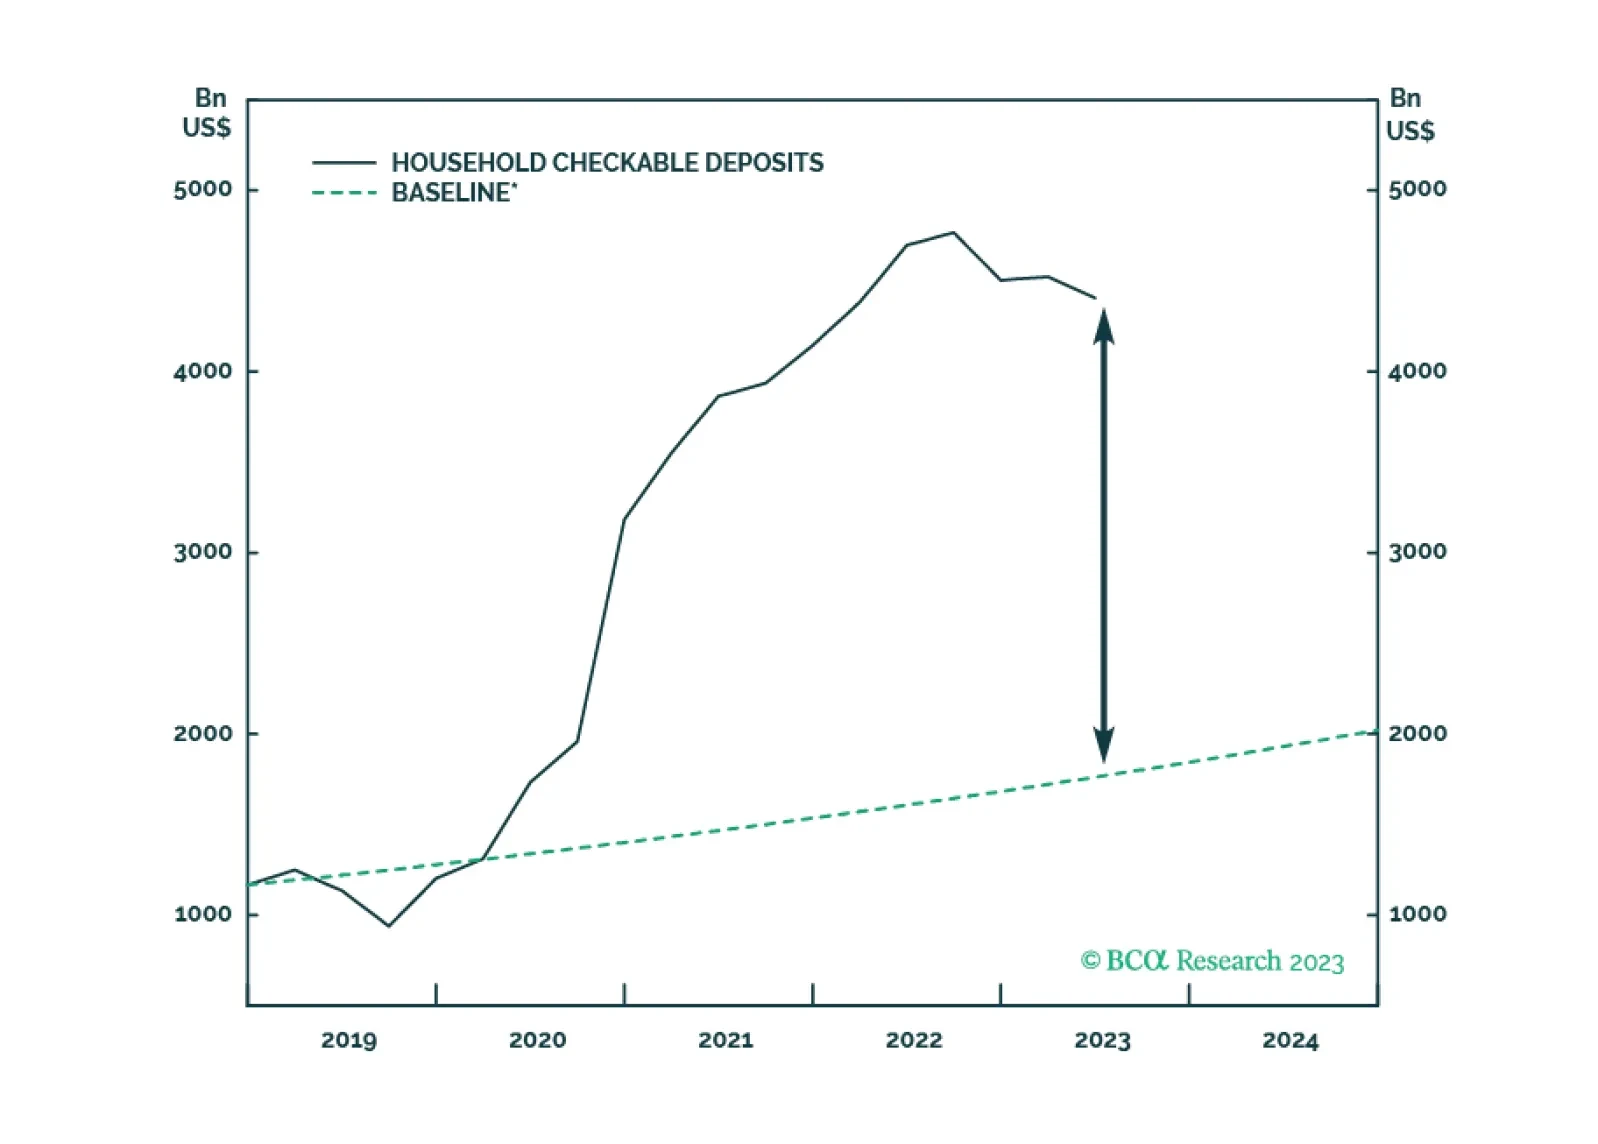
The biggest banks report that consumer credit card delinquencies still have yet to get back to pre-COVID levels and other credit performance indicators, leading and lagging, remain solid. There is still a great deal of cash sloshing around the banking system, though consumption has clearly slowed. We reiterate our view that a recession is coming, but not before the year is out.
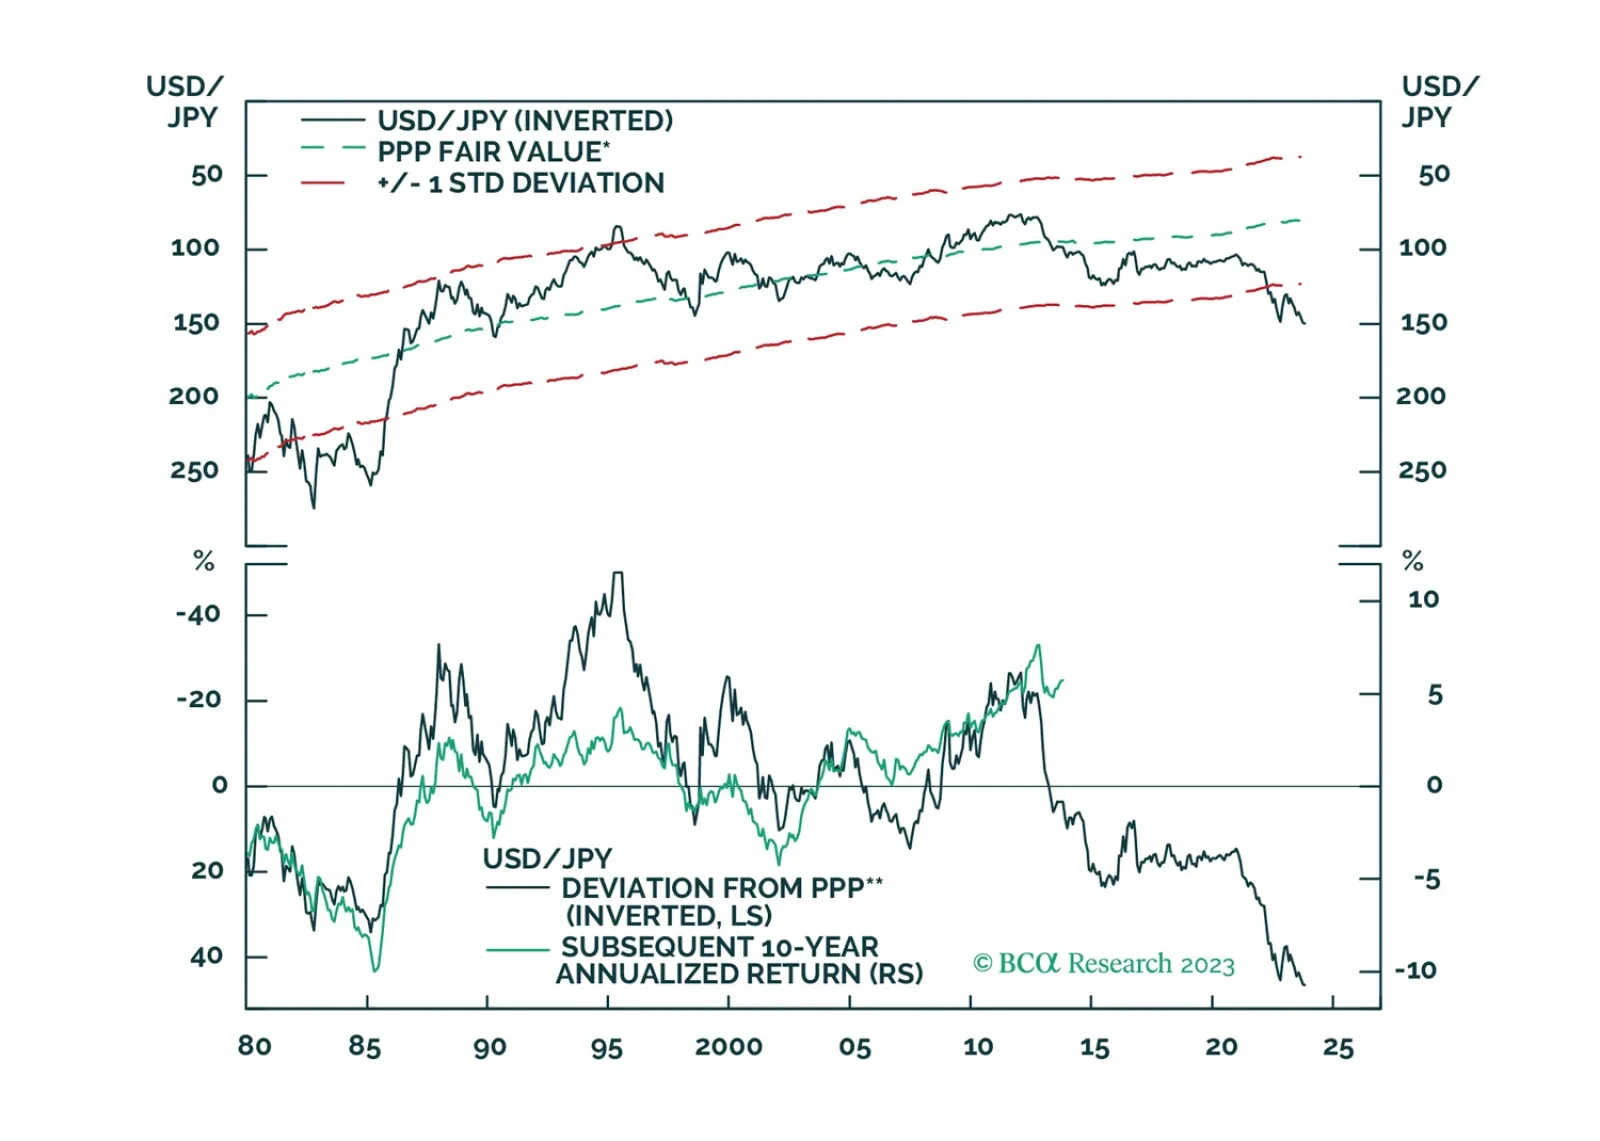
According to BCA Research's Global Investment Strategy service, the global economy will stay buoyant over the next few quarters but will then sour as the lagged effects of higher interest rates and tighter bank lending standards work their way through the…

There is a high probability that the global economy will tip into recession in the second half of 2024. A long yen position is an excellent hedge against that risk.
The Conference Board's Leading Economic Index's 0.7% m/m decline in September sent a weaker-than-anticipated signal about the outlook for the US economy. It fell below anticipations that the pace of decline would remain unchanged at -0.4% m/m and marks the…
Fed Chair Jay Powell's speech at the Economic Club of New York on Thursday corroborates the signal from other recent Fedspeak that policymakers may not need to hike rates again. He highlighted that although inflation is still too high, price pressures are…

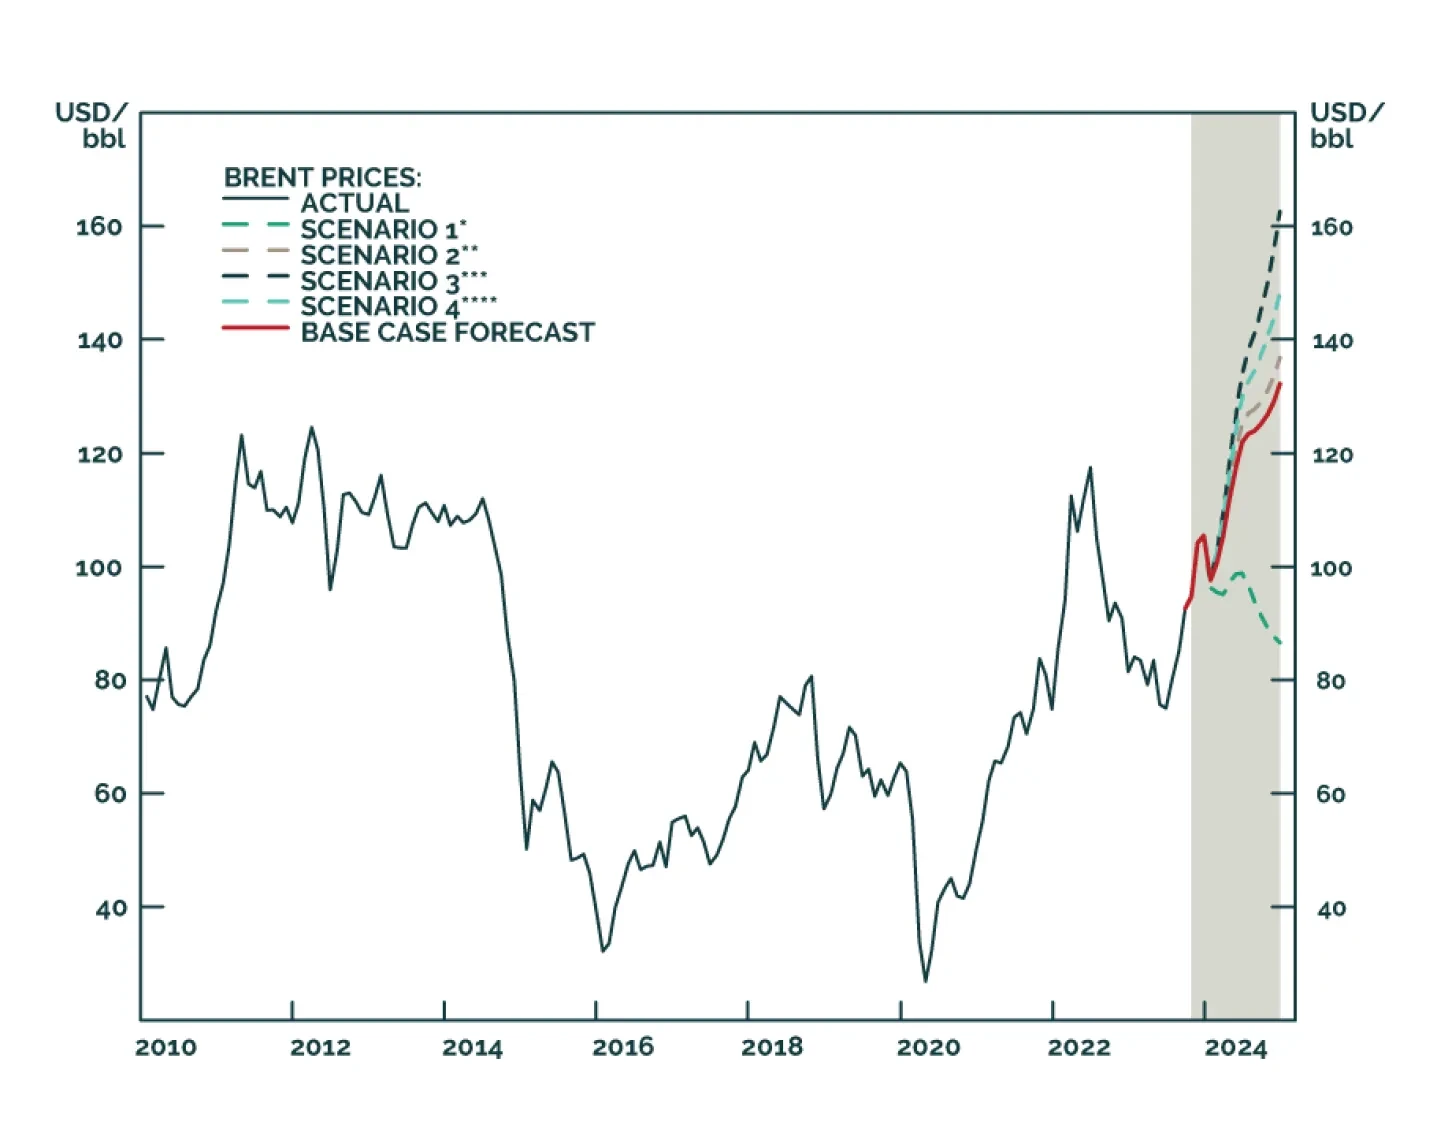
Despite higher uncertainty, our Brent price forecasts remain unchanged at just over $101/bbl for 4Q23 and $118/bbl for next year. We remain long equity exposure to oil and gas producers via the XOP ETF, and commodity exposure via the COMT ETF. We also remain long $100 Dec24 Brent calls and long 1Q24 Brent futures vs. short 1Q25 Brent futures in anticipation of stronger backwardation.