Saltar al contenido principal

Estados Unidos

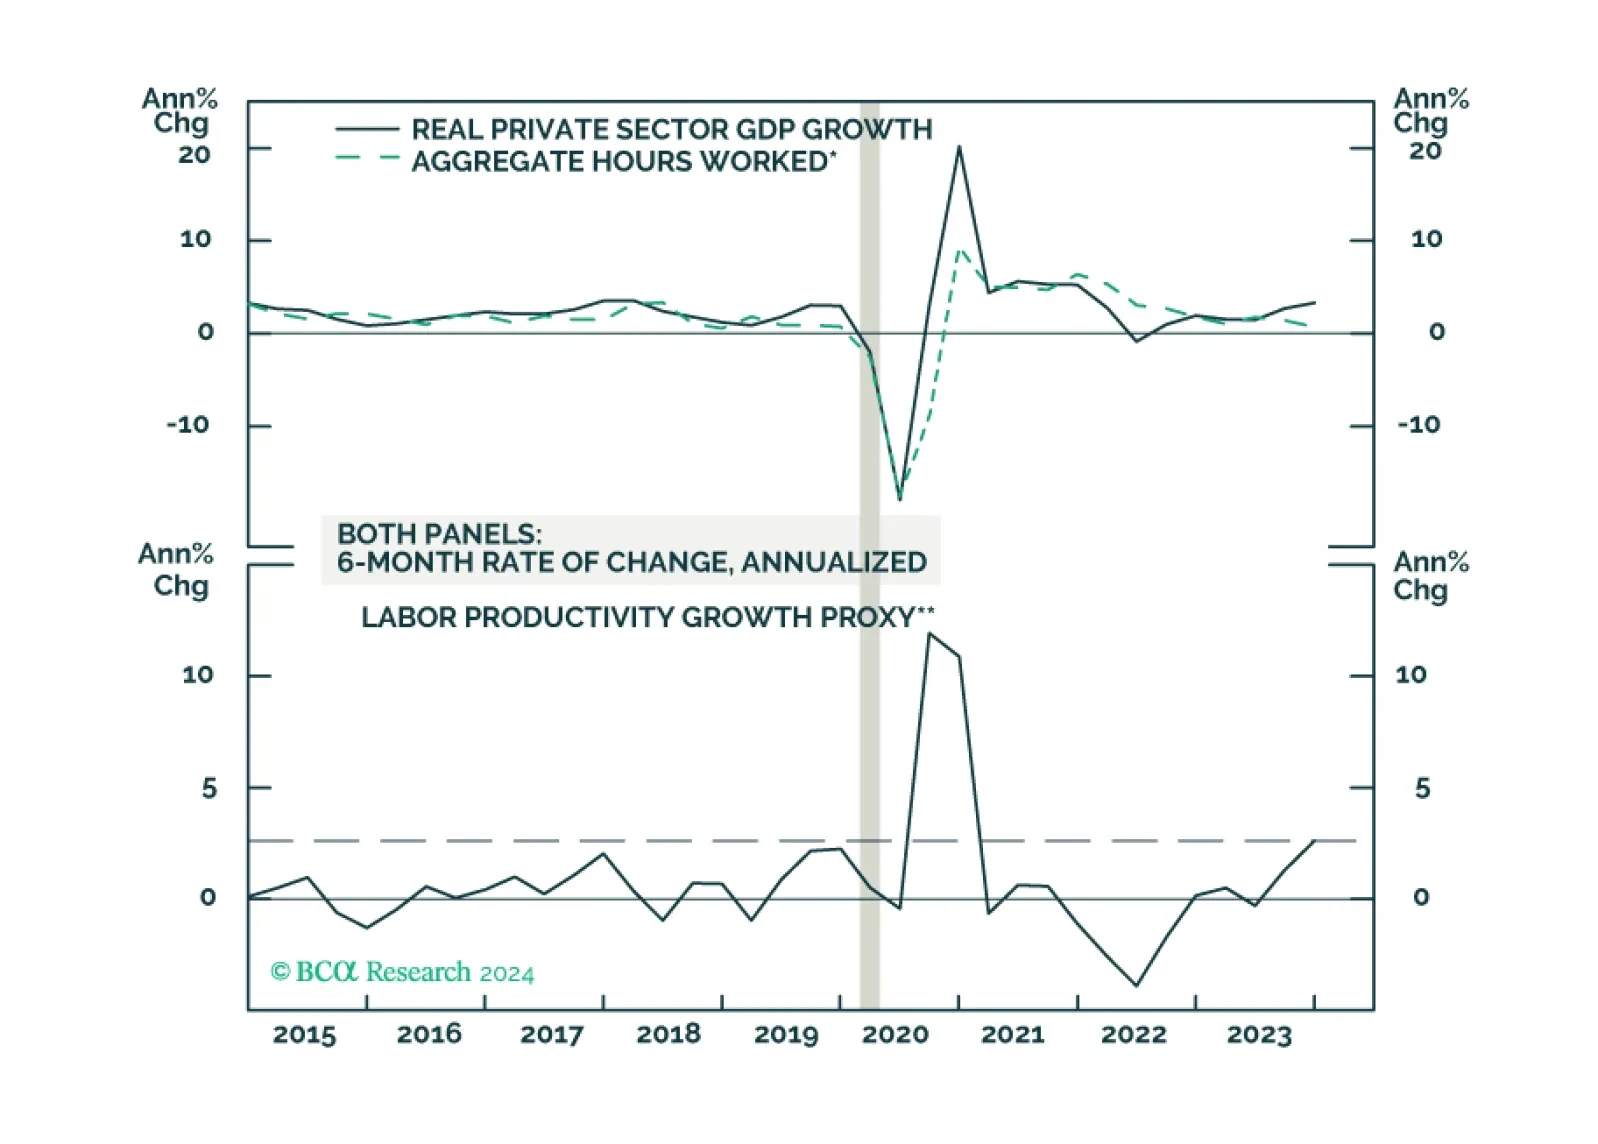
Friday’s US Personal Income and Outlays report for December delivered a positive update on the US economy. On the growth side, the data confirm the signal from the Q4 GDP release that consumer spending continues to power the US economy. The robust 0.5%…
With the latest PCE release confirming that the disinflation process is intact (see The Numbers), a key question facing investors is around the timing of the Fed’s pivot to rate cuts. Indeed, the US inflation surprise index has collapsed from its mid-2021…
While balance of payments (BoP) do not really matter for day-to-day FX considerations, they do matter over the long term. According to BCA’s Foreign Exchange Strategists, at high levels of US dollar valuation like today, the current account balance tends to…
According to BCA Research’s The Bank Credit Analyst service, there are two important flaws in the market’s “Goldilocks” narrative. First, investors are assuming inflation will fully return to target this year because core inflation ex-housing is already at…

Low inflation argues for the Fed to move relatively quickly toward rate cuts. Continued above-trend GDP growth poses a risk to this view, but leading indicators point to slower growth in the coming quarters.
Informe especial

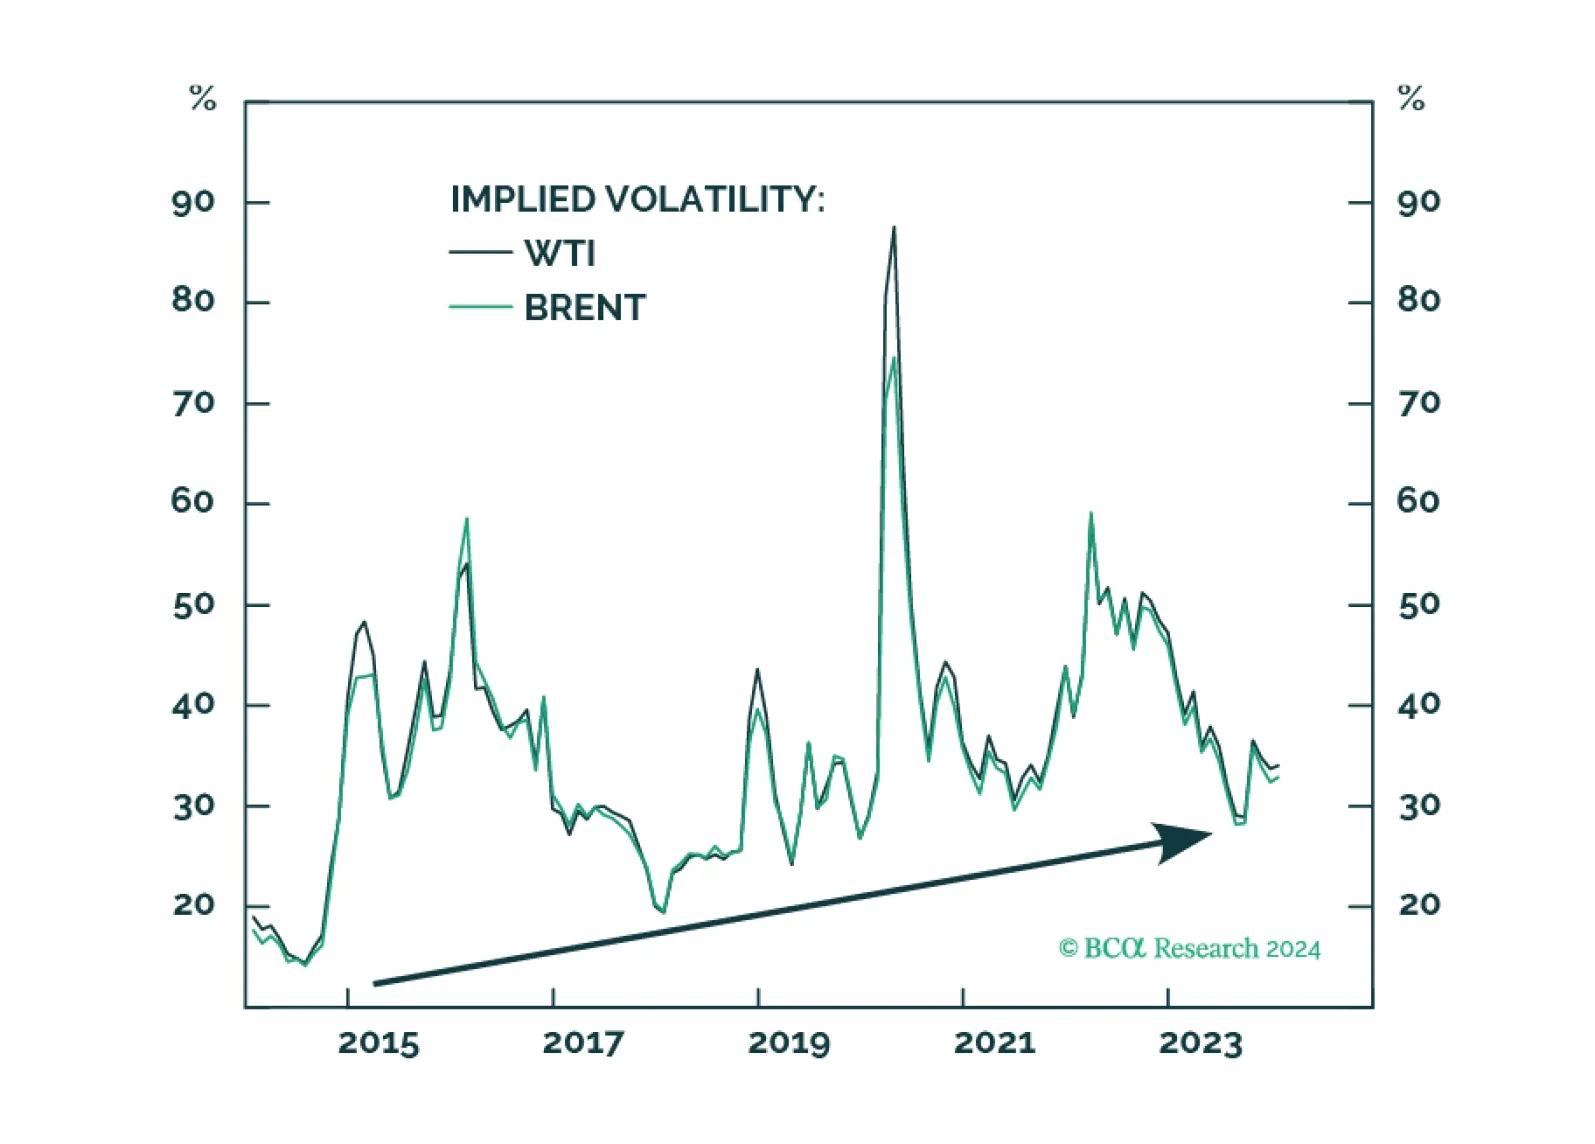
Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.
The Q4 2023 US GDP print delivered a positive message on economic conditions. Although real GDP growth decelerated from 4.9% to 3.3%, it came in well above consensus expectations of 2.0% and the Atlanta Fed’s GDPNow estimate of 2.4%. Consumers once again…

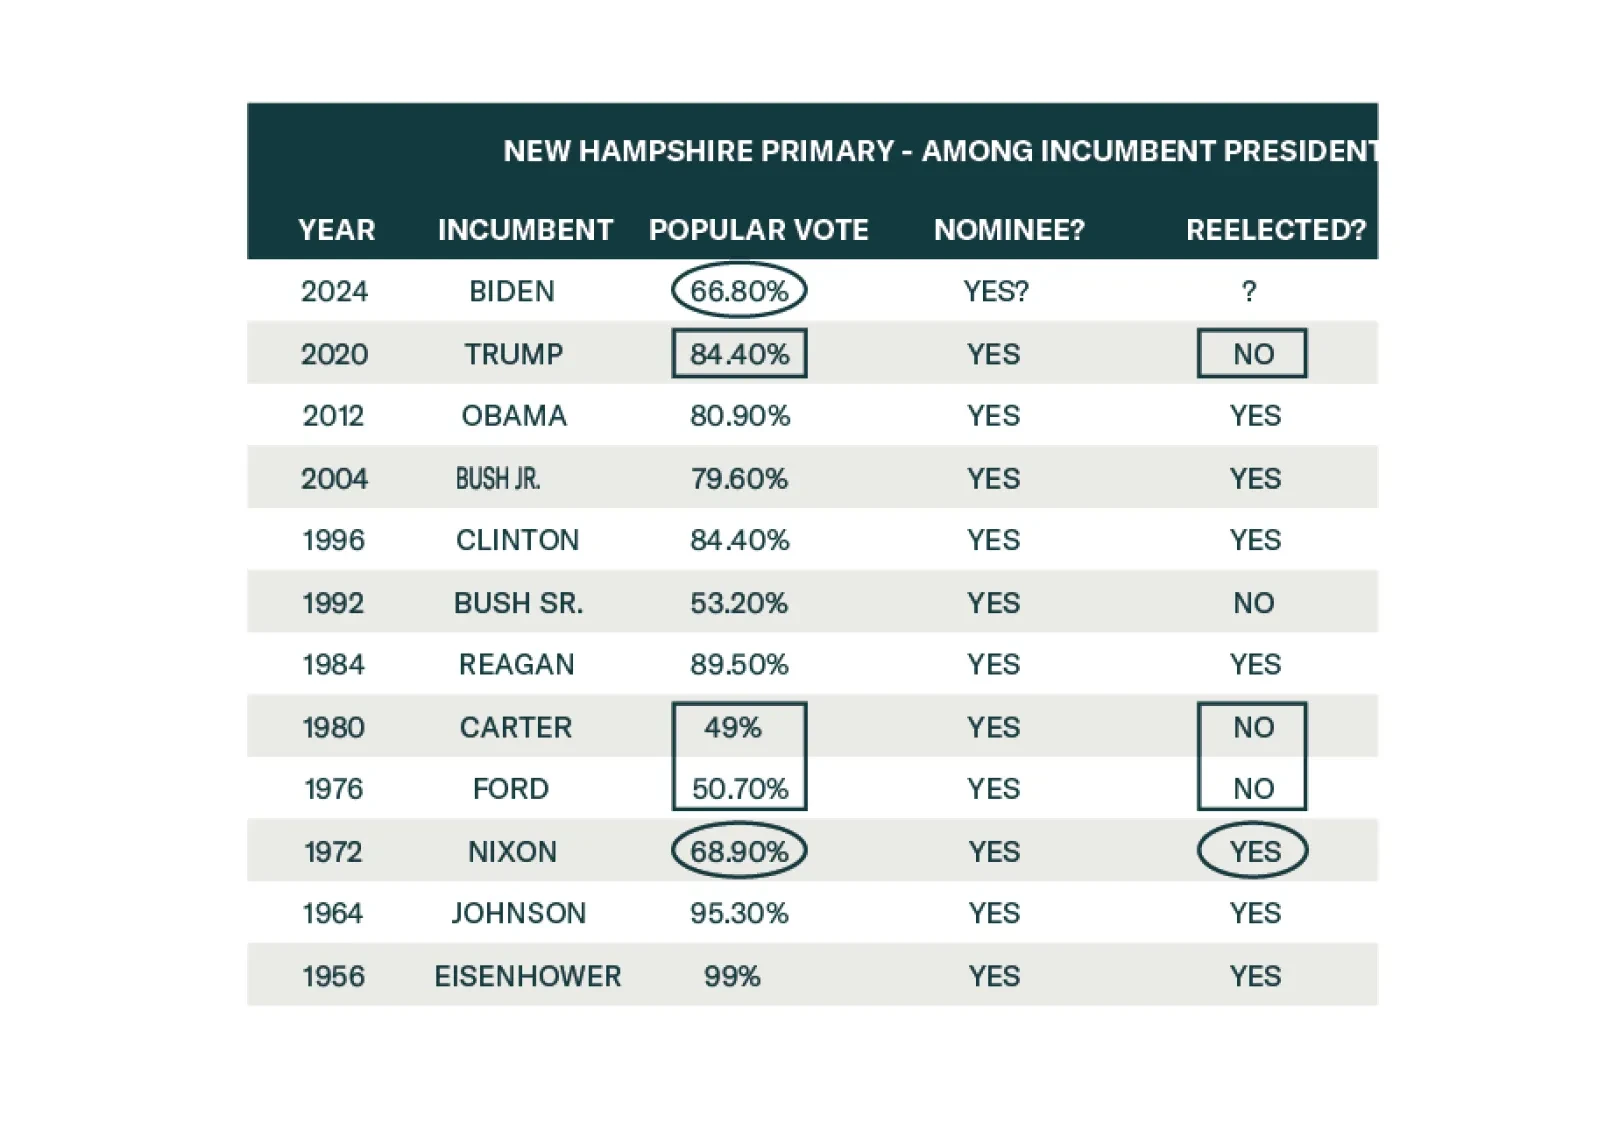
The US primary election is effectively over. The Biden-Trump rematch – our base case since 2022 – is all but set in stone. Only a health issue or freak incident could change that now.
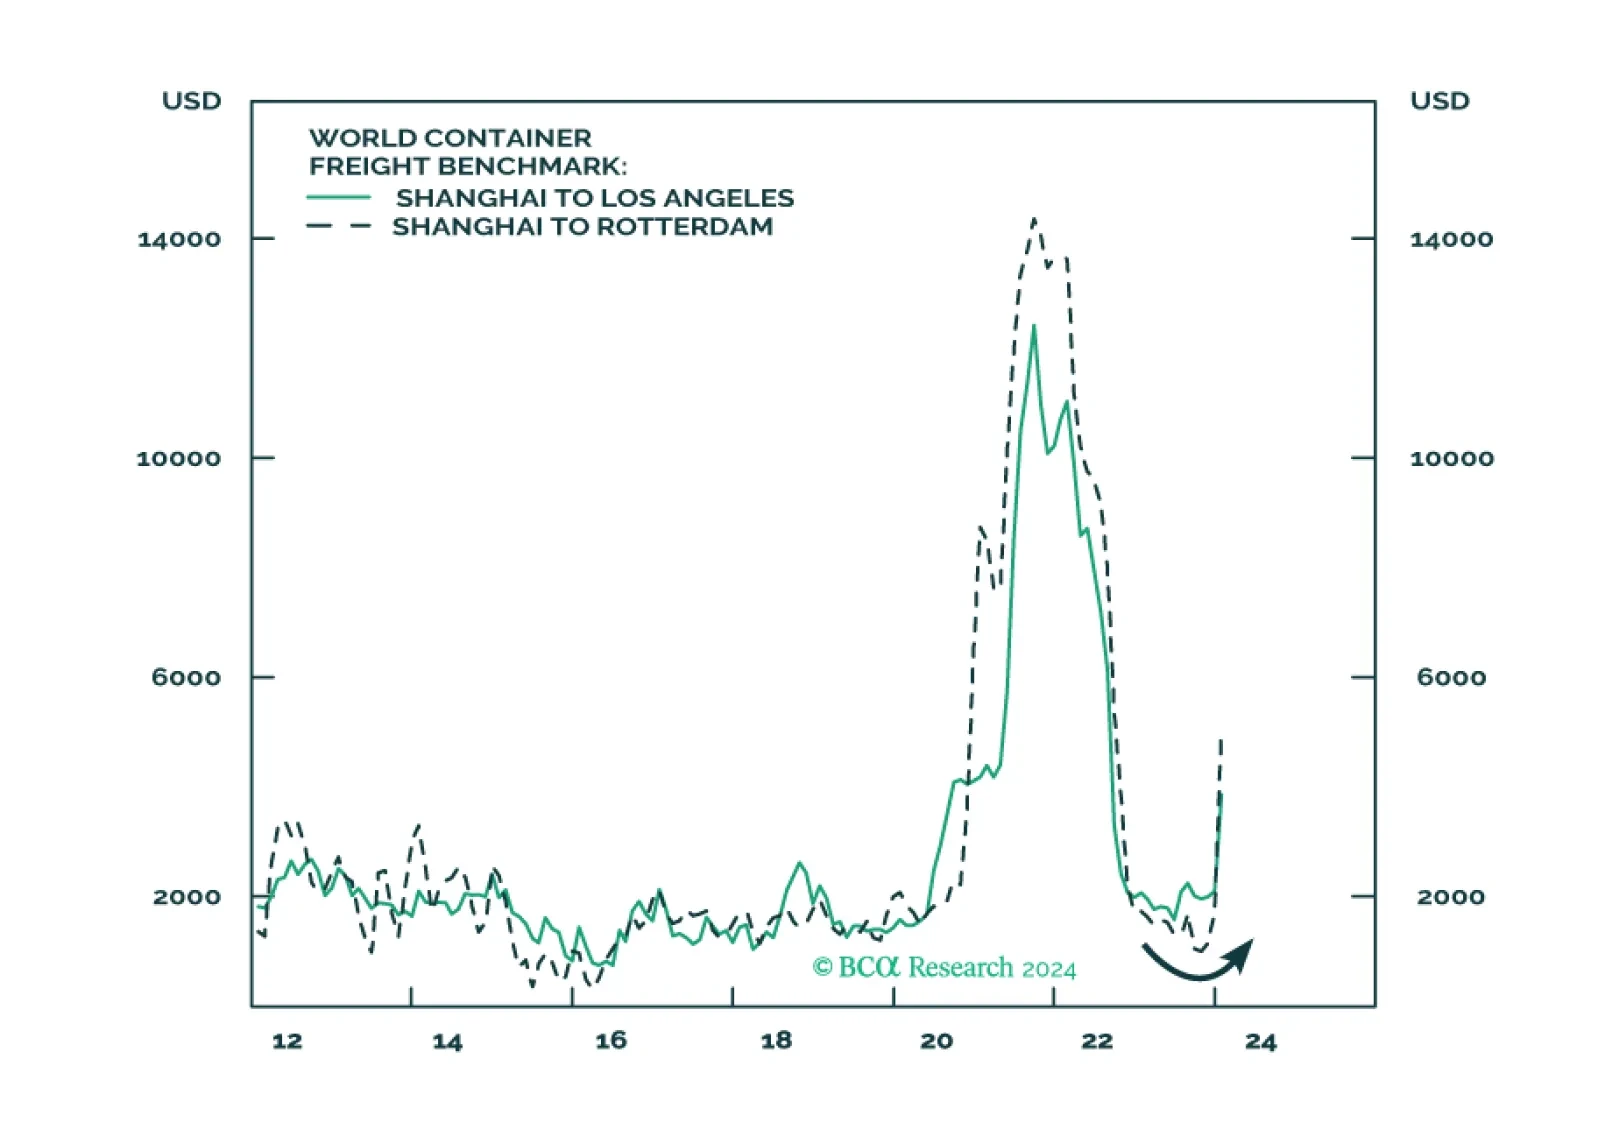
Middle East conflict, extreme US policy uncertainty, Chinese economic slowdown, US-Russian proxy war, and Asian military conflicts do not create a stable investment backdrop for 2024. Our top five “black swan” risks may be highly improbable, but they stem from these underlying trends.

Flash PMIs sent a generally positive update on economic activity across major DM economies in January – particularly in the case of manufacturing. In the US, the composite index rose to a 7-month high of 52.3, beating expectations it would remain broadly…