Estados Unidos
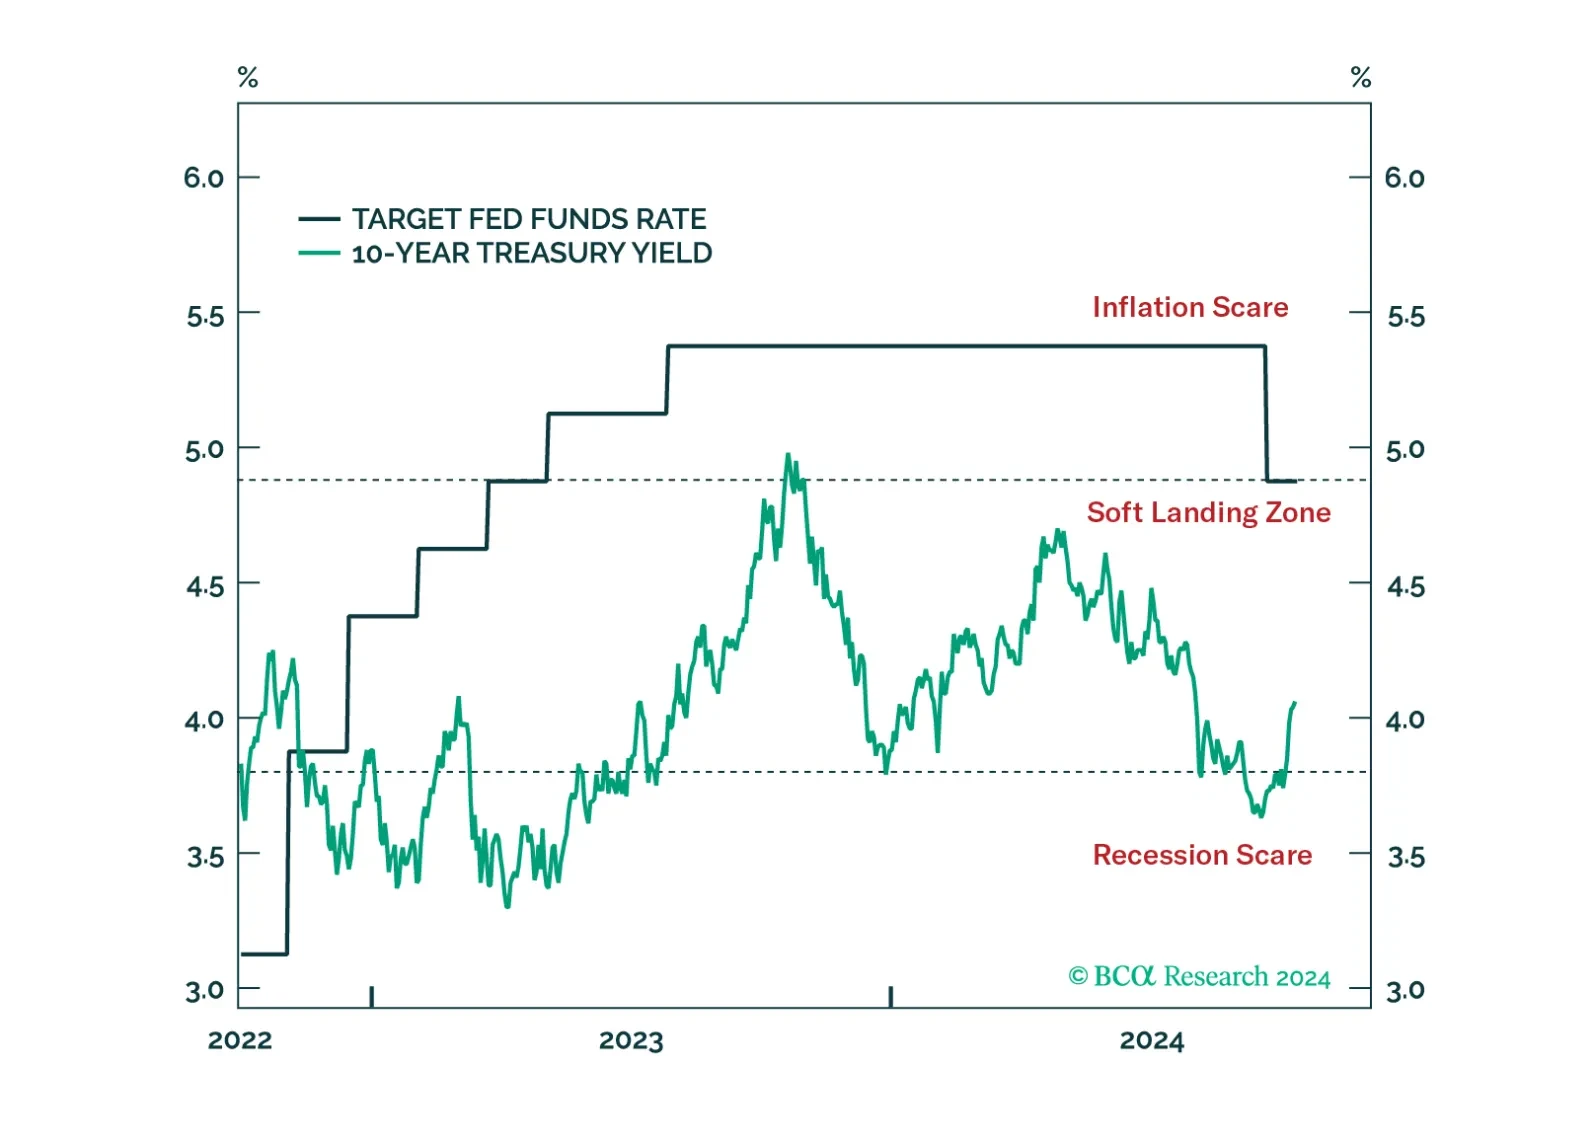
We give our thoughts on this morning’s CPI release and (lack of) market reaction. We also close our short position in January 2025 fed funds futures.

The Chicago Fed National Activity Index (CFNAI) – a summary statistic of US economic data releases – increased to 0.12 from -0.42, suggesting that the US economy improved in August. Details, however, do not point to a broad-based acceleration since…
According to BCA Research’s US Political Strategy service, the important election takeaway for investment strategy comes from the Senate. The Senate is highly likely to fall to Republicans. They are nearly certain to win West Virginia and very likely to win…
The NFIB Small Business Optimism index was mostly flat in September, ticking a mere 0.3 points higher to 91.5 in September, below expectations of a more meaningful improvement to 92.0. The NFIB Small Business Optimism has oscillated in a tight range since…
Consumer credit growth slowed in August, rising by USD 8.9 bn (to USD 5,097.6 bn outstanding) from USD 26.6 bn, disappointing expectations of a USD 12 bn monthly increase. Notably, revolving credit (which includes credit cards) declined by USD 1.4 bn over the…
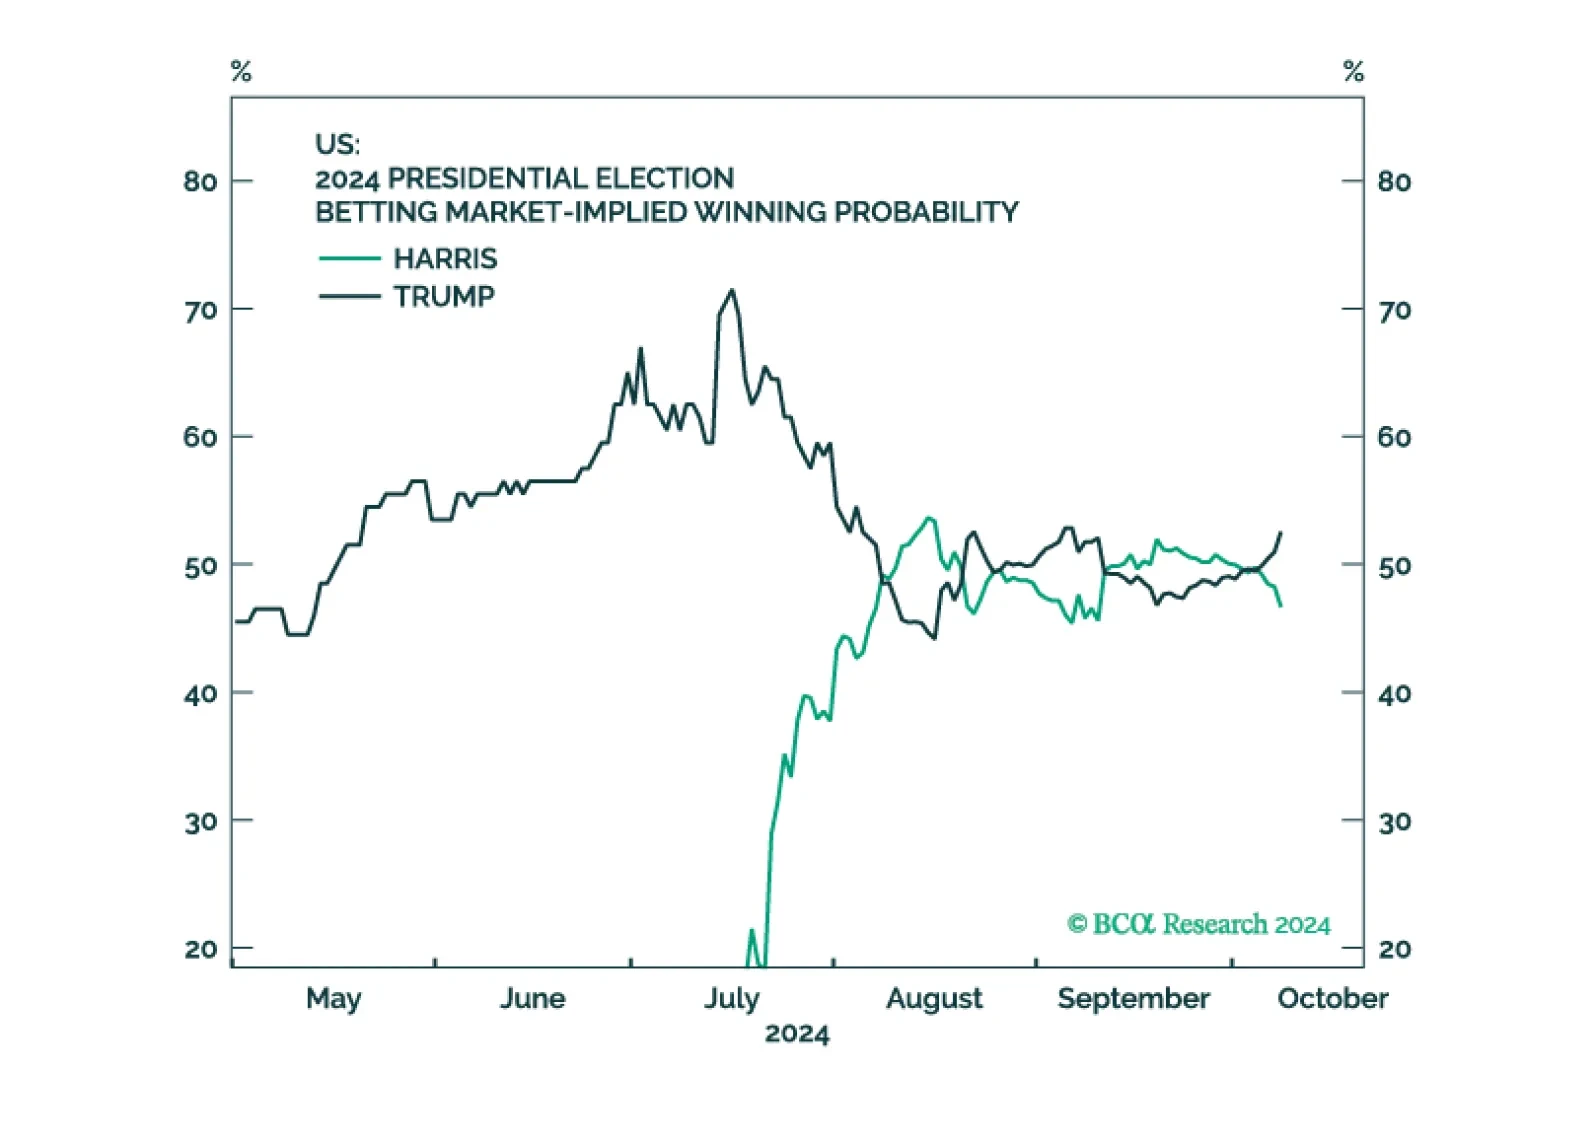
The month of October ahead of a US general election tends to be a volatile month with negative outcome for equities. As such, it is prudent to remain on the sidelines until after the election.

The US election underscores three long-term trends of Generational Change, Peak Polarization, and Limited Big Government. Investors should expect more volatility around the election and should assess the results before adding more risk. While we predicted the October surprise from the Middle East, more surprises are coming before the final vote is cast.
The dollar had erased all of its 2024 gains going into the fall, as markets prepared for Fed rate cuts. After a nearly 6% drawdown over the spring and summer, last week’s DXY rally brought the dollar back into the black YTD. Can these gains continue now that…
In response to the Chinese stimulus announced in late September, our Emerging Market strategists upgraded EM equities to no more than neutral. Indeed, while these measures have triggered a sentiment-fueled rally from depressed valuation levels, conditions are…
September nonfarm payrolls grew by 254 thousand, from 155 thousand in August, handily exceeding expectations of 150 thousand. Pro-cyclical manufacturing jobs declined by a lower-than-anticipated 7 thousand, while leisure and hospitality, as well as…