Saltar al contenido principal

Economy

On the surface, the acceleration in Chinese retail sales and industrial production growth in October suggests that the economy is holding up. Retail sales expanded by 7.6% y/y last month – beating expectations of 7.0% y/y following a 5.5% y/y increase in…
The New York Fed's Empire Manufacturing Index unexpectedly returned to positive territory in November, climbing 14 points to its highest level since April. The headline index suggests that manufacturing activity is expanding in New York State – a positive…
Informe especial

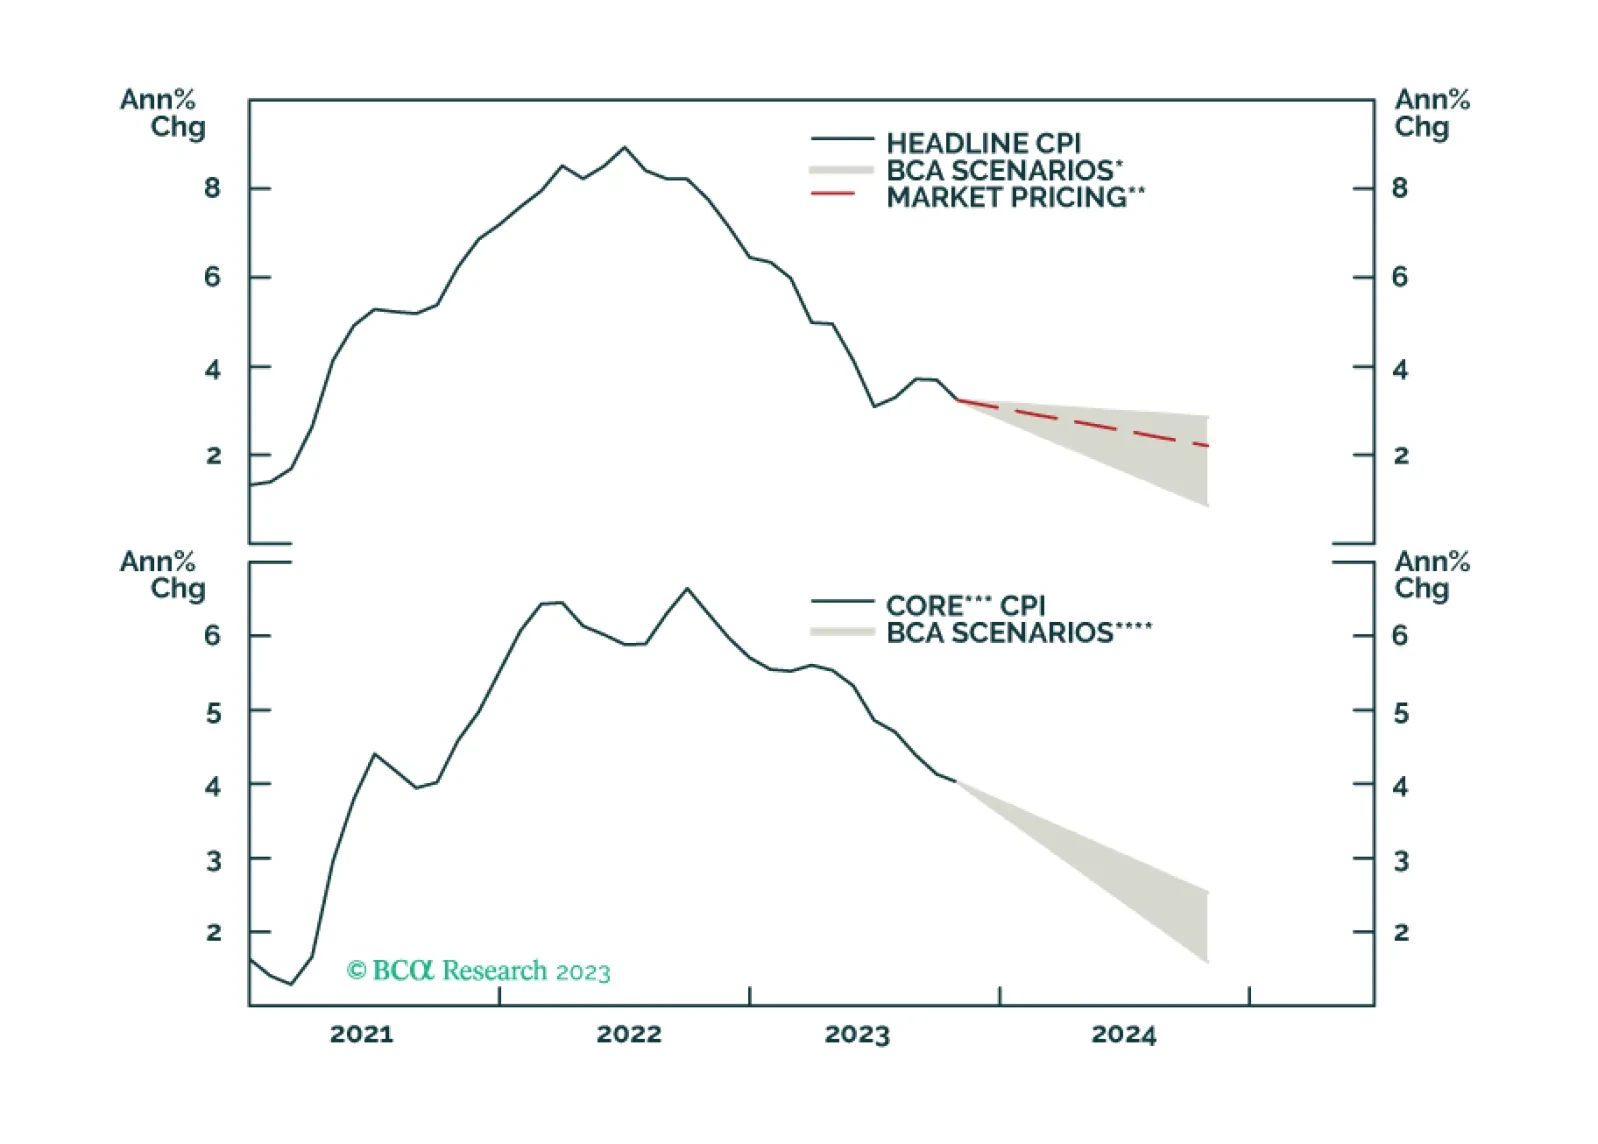
This week’s Special report revisits our TIPS Golden Rule. We provide a 12-month inflation forecast and discuss how it impacts our TIPS view.
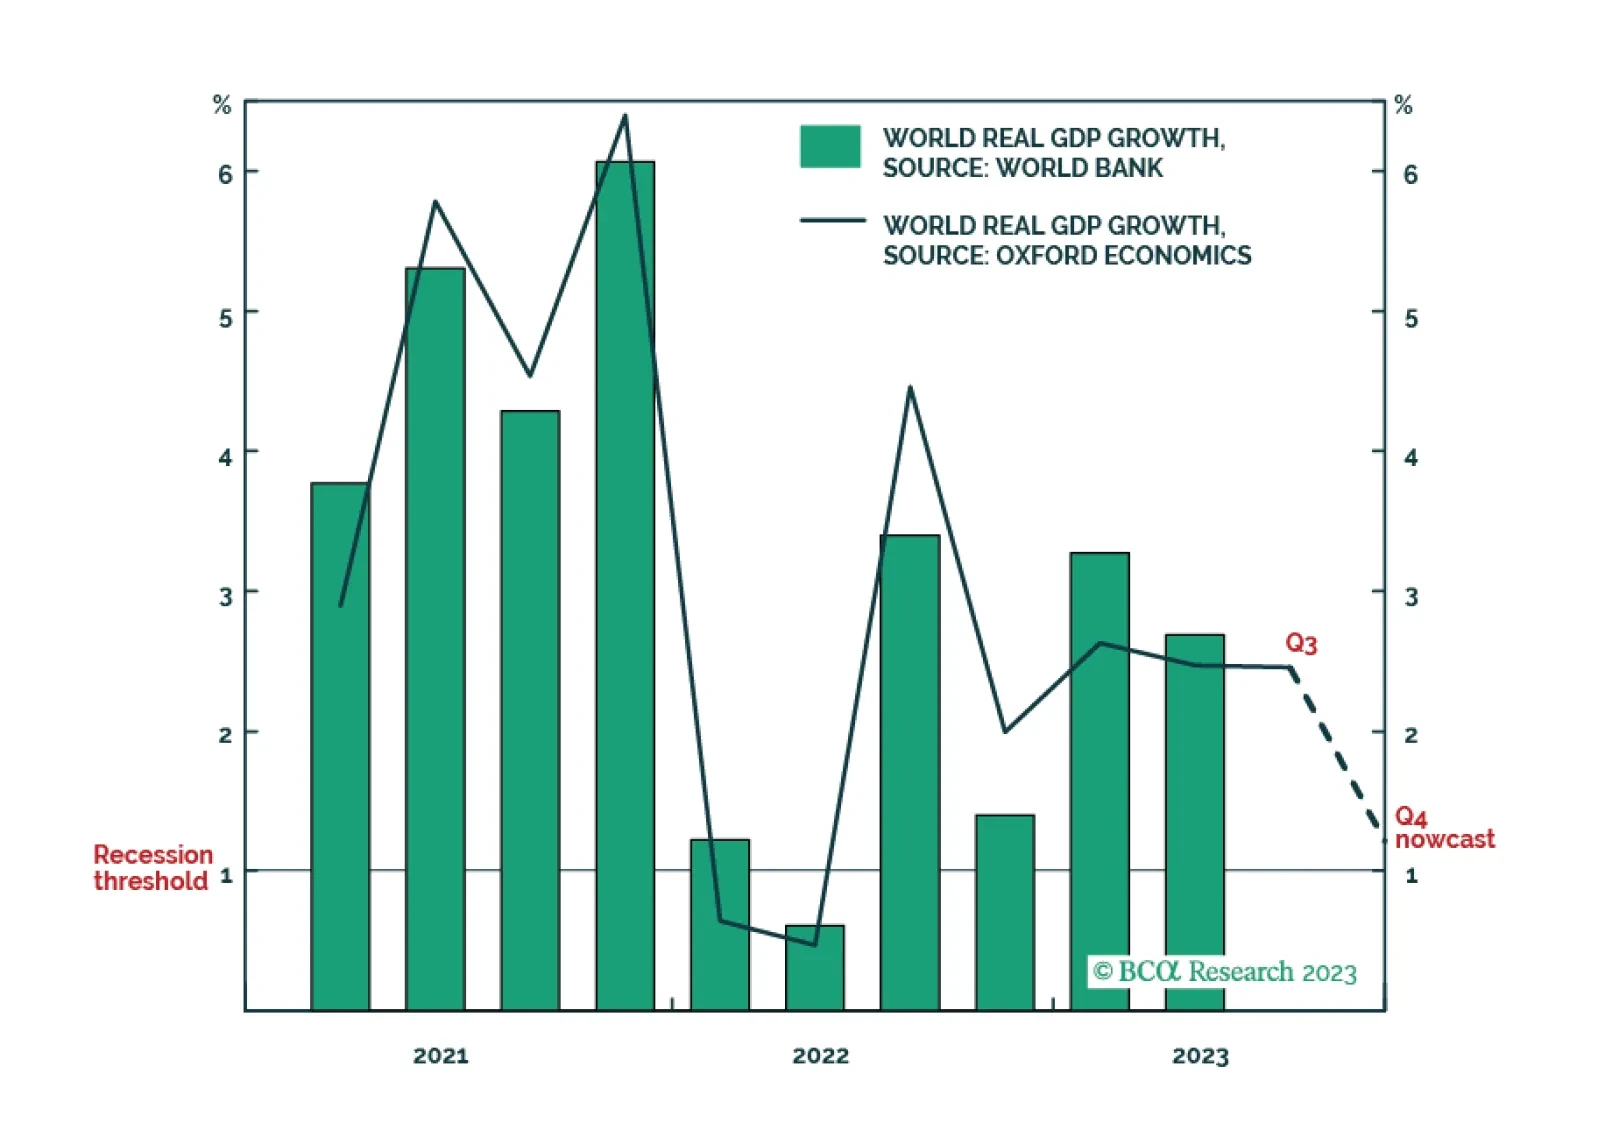
The latest ‘nowcast’ for world economic growth in the fourth quarter has plunged to just 1.2 percent, marking the cusp of another world recession. One important implication is that expectations for oil demand growth and industrial metal demand growth are way too optimistic.
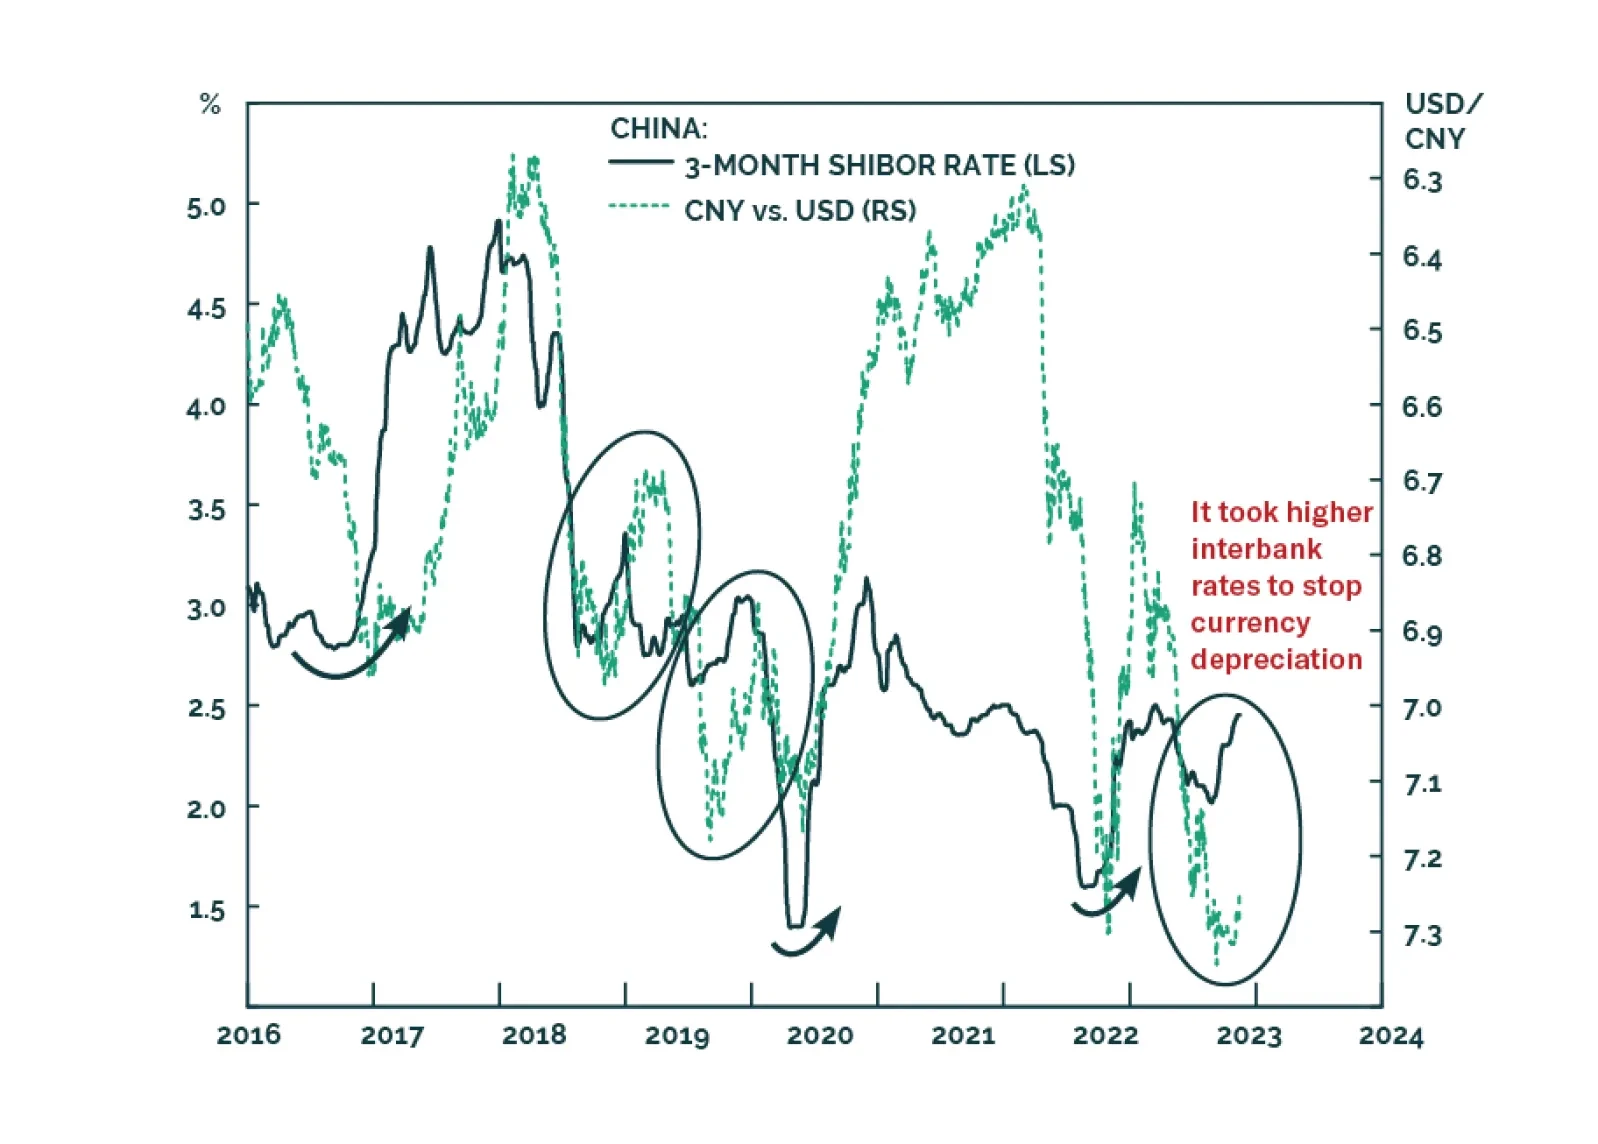
Many commentators have attributed the latest increase in Chinese interest rates to an improving economy, the large issuance of government bonds, the tax payments season, and other technical factors. Yet, these explanations are missing the key point: the PBoC has steered interbank rates higher to defend the currency. Higher borrowing costs are the last thing the mainland economy now needs.

US Treasury yields fell sharply following yesterday’s soft October CPI report, and investors have now officially priced out all remaining rate hikes from the yield curve. In fact, the fed funds futures curve is priced for a 25 basis point rate cut by next…
To the extent that US small businesses are typically more exposed to domestic economic conditions than larger firms, results of the NFIB Small Business Economic Trends survey are instructive. One important trend is that the October survey results corroborate…
The ZEW survey of investor sentiment continues to send an optimistic signal. German sentiment jumped from -1.1 to +9.8 in November – its highest level since March and beating expectations of a smaller improvement to 5.0. Similarly, expectations for the Euro…
The DXY collapsed to a 2 ½ month low on Tuesday following the softer than anticipated CPI inflation release which prompted investors to bring forward their Fed rate cut expectations (see The Numbers). This marks an acceleration of a budding downtrend since…
BCA Research’s Global Fixed Income Strategy service remains long 10-year German bunds vs short 10-year Japanese government bonds (JGBs) as a tactical trade. This trade mirrors the team's two highest conviction strategic views in government bond space,…