Saltar al contenido principal

Developed Countries

As talks of a market “meltup” abound, we used last Friday’s edition of our BCA Live & Unfiltered meeting to assess our asset allocation recommendations. Our House View has been underweight equities since March, a recommendation reinforced by two of our most…
Our Global Investment Strategy team examined the risk of a fiscal crisis amid rising global debt levels. Stabilizing the US debt-to-GDP ratio would require a nearly 4% GDP improvement in the primary budget balance at current Treasury yields. Reducing deficits…
October retail sales beat expectations, printing 0.4% m/m on top of positive revisions for September. However, the numbers were weaker when adjusting for autos or other volatile components, with the control group declining 0.1% from 0.7% growth in September.…
The flipside of the recent US dollar rally has been weakness across both DM and EM FX. The USD rally has legs and will have cross-asset reverberations. EM equities will be affected. A key determinant of EM returns is the currency, as investors cannot benefit…
Informe especial

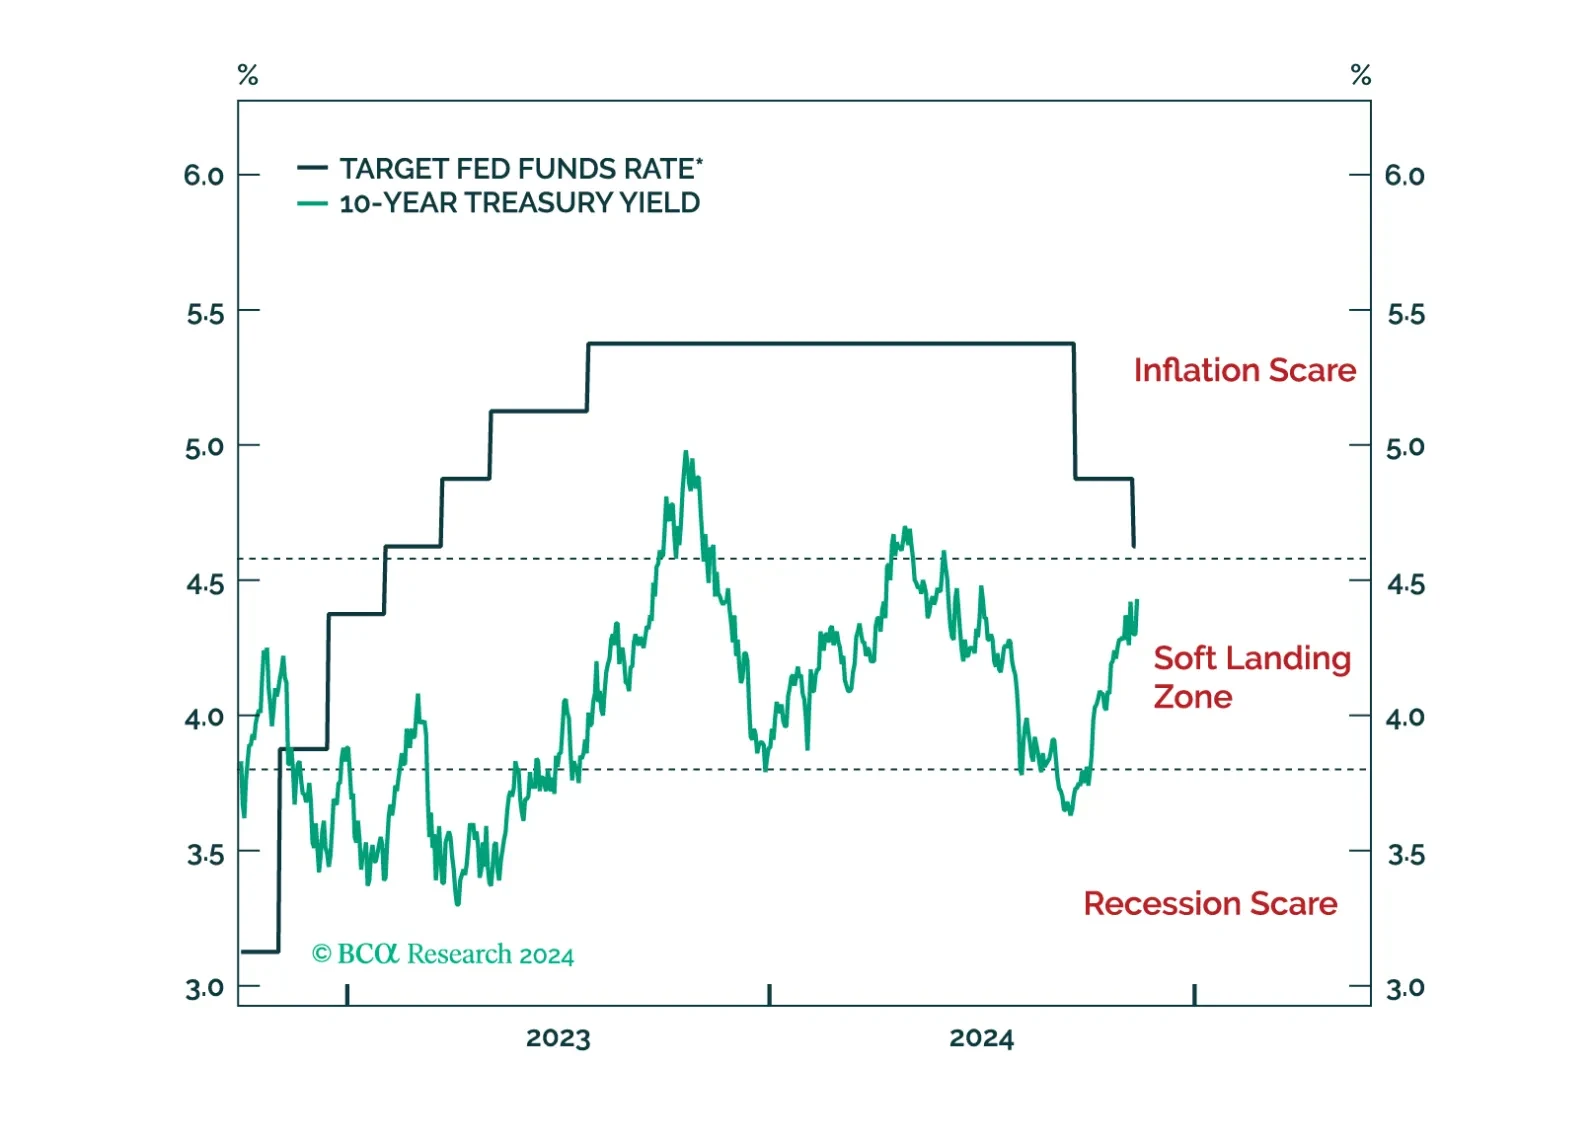
Investors are overstating the positive fiscal impact of the Trump presidency. The bond market will have something to say about the scope for further deficit expansion via tax cuts. As such, the trade after the trade of the Trump 2.0 administration may involve less growth out of the US, not more. In the interim, however, investors should continue to expect higher yields and increased equity volatility. There are plenty of risks ahead, including geopolitics, trade, and uncertainty surrounding fiscal policy.

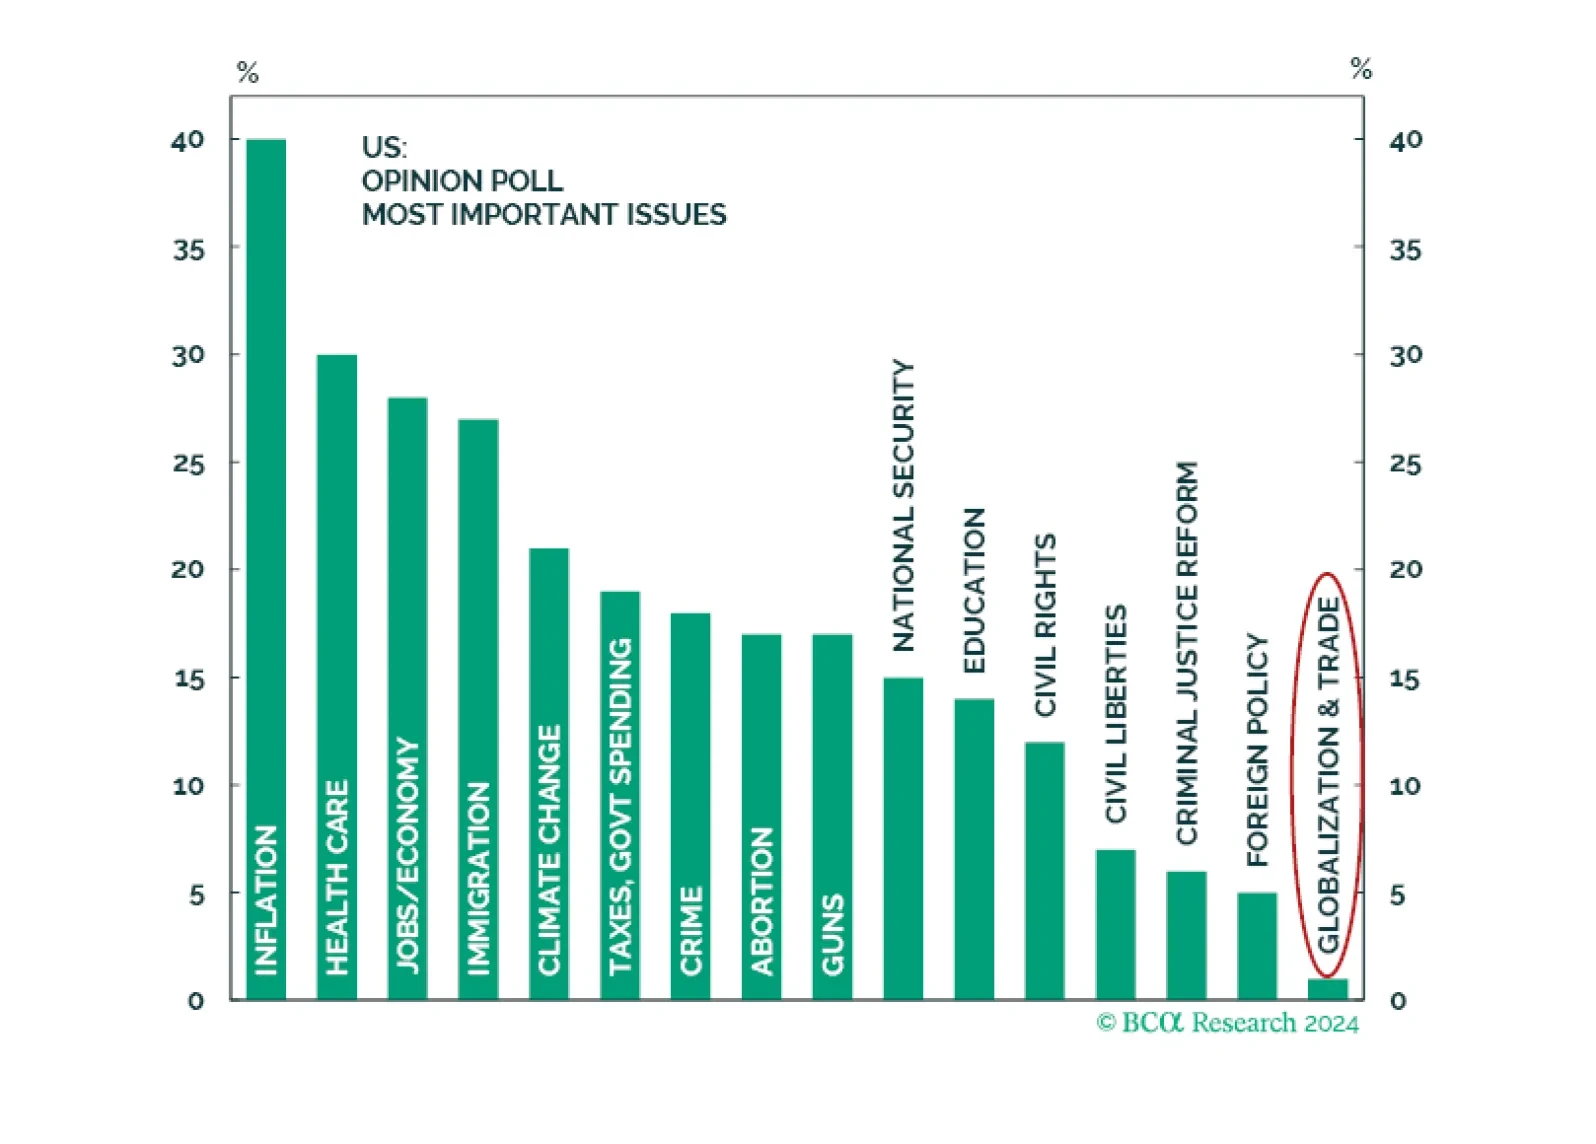
Ultimately, 2024 is not 2016 — a seemingly obvious point, but one with market relevance. In 2016, voters gave Trump a strong mandate for nominal GDP growth. It is not clear if this is the case today. Inflation is the most important issue, least relevant is trade and globalization. As such, Trump’s renewed mandate is for supply side reforms, not more populism and protectionism.

US CPI inflation for October printed in line with expectations and was unchanged from September, with headline at 0.2% month-over-month and core at 0.3%. Headline re-accelerated to 2.6% from 2.4% on an annual basis, and core stayed steady at 3.3%. This report…
Resumen de la asignación de nuestra cartera para noviembre de 2024.
The NFIB Small Business Optimism Index beat expectations in October, increasing to 93.7 from 91.5. Although improvements were broad-based, the increase was led by a brightened outlook. Given that the survey was conducted before the US election, uncertainty…
Economic expectations for Germany and the Eurozone disappointed, with the November ZEW decreasing to 12.5 from 20.1. The assessment of current conditions also worsened, implying the sentiment rebound from September will not be sustained. The outlook remains…