Saltar al contenido principal

Developed Countries

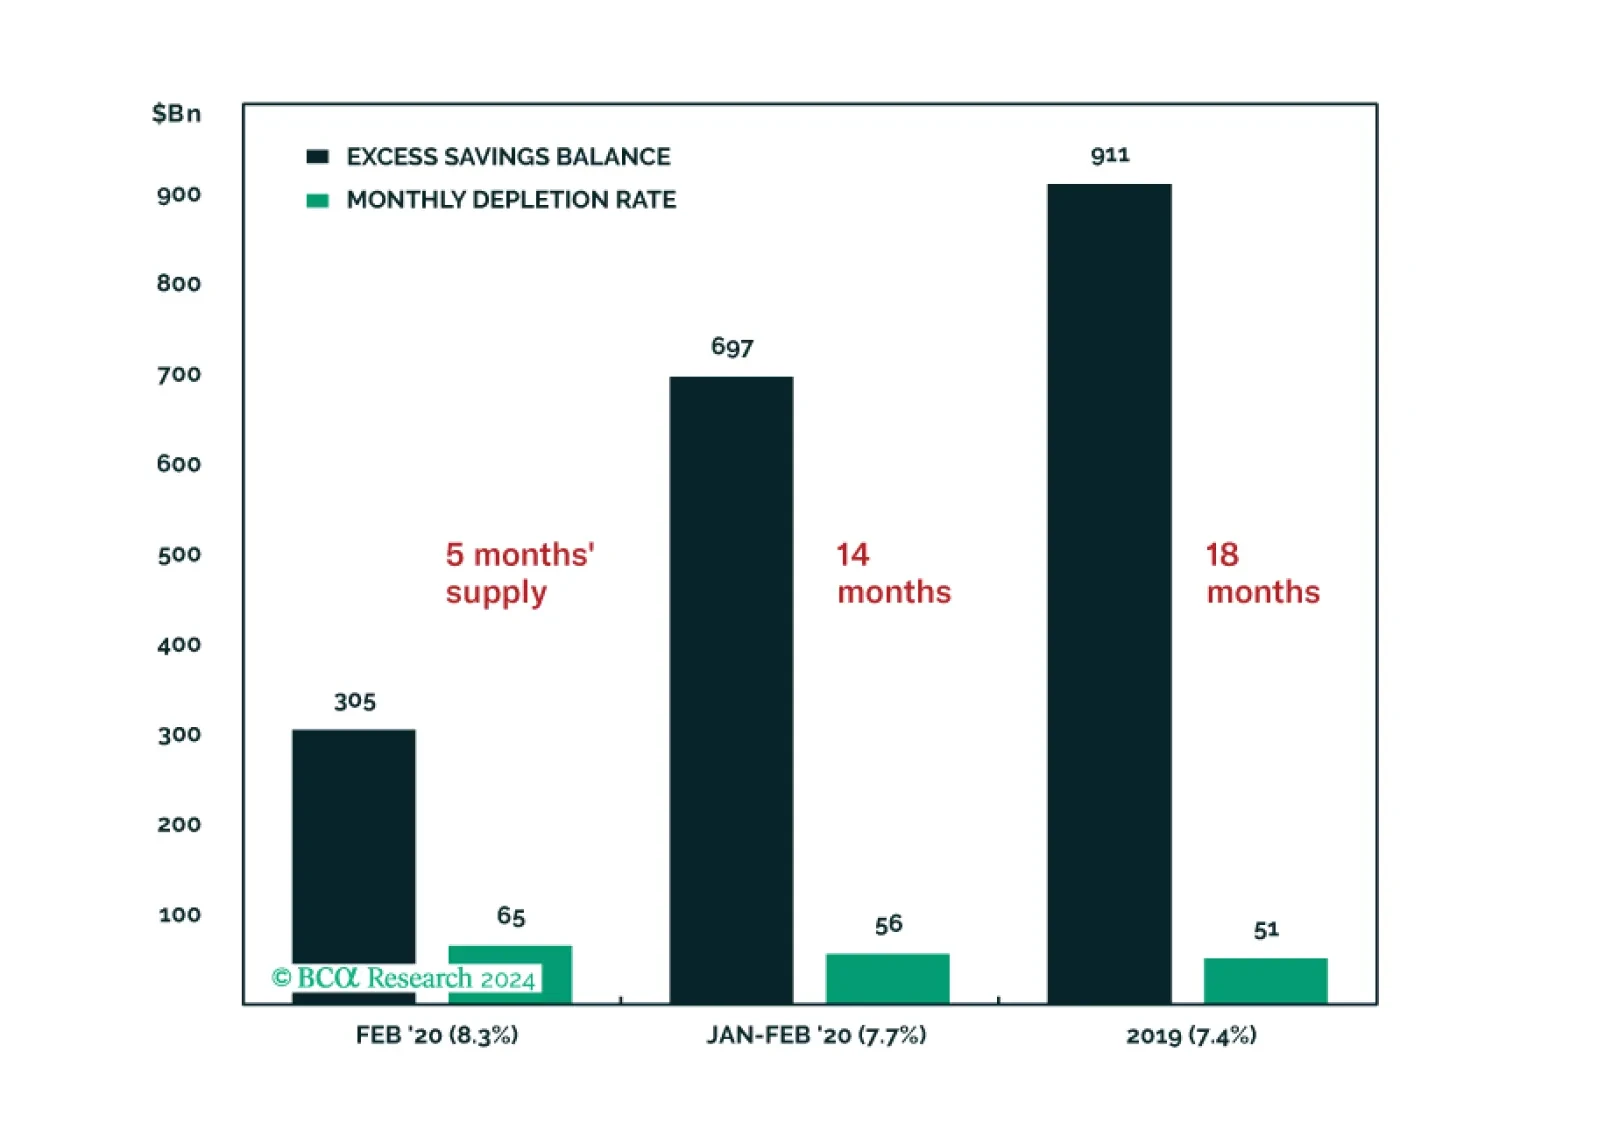
Our US Investment Strategy service examines the state of consumer finances in the context of their view that a recession will materialize this year with a double-digit peak-to-trough decline in S&P 500 earnings expectations. They expect the pandemic-era…
The US ISM Services PMI declined slightly to 52.6 in February, just below expectations of 53. Overall, the service sector continues to expand, however, the recent ISM suggests that growth is slowing down. In fact, most of the components of the ISM worsened,…
Data out of Norway is becoming increasingly positive, and there is a strong investment case to be made for the country, with bullish implications for both equities and the currency: Retail sales remain robust and are catching up to the improvement we have…

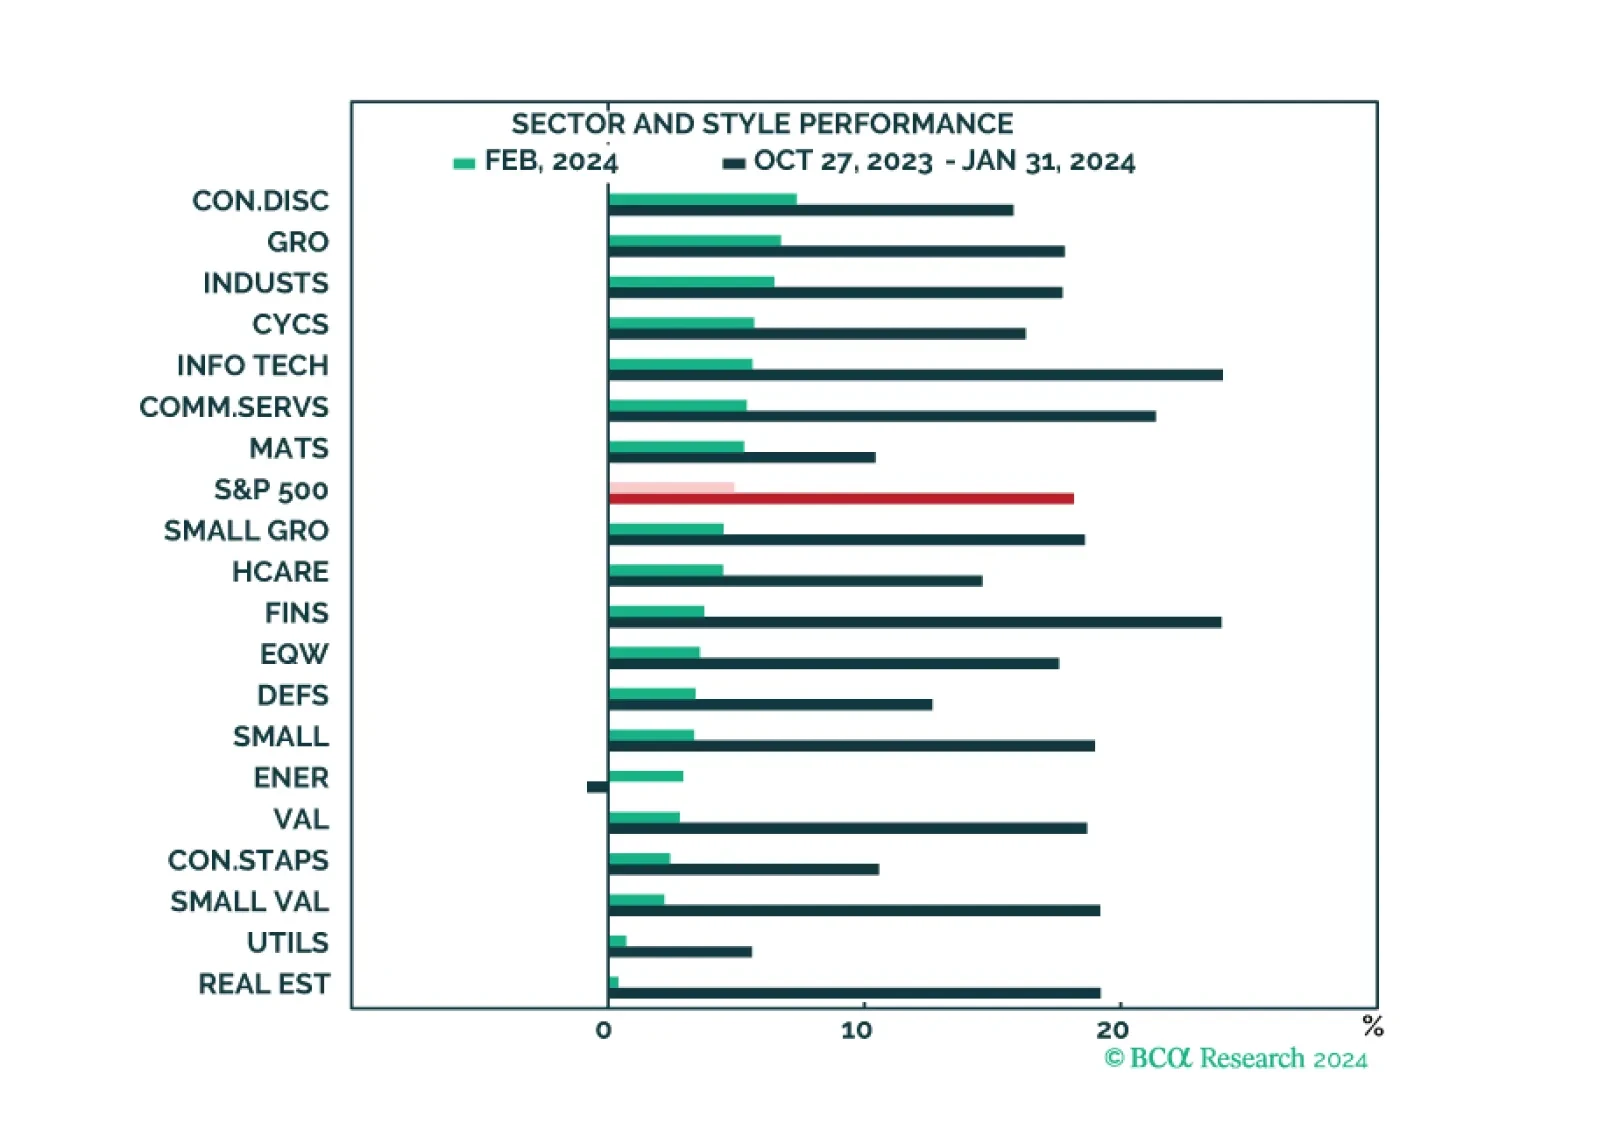
The market narrative continues to be dominated by the Magnificent Six, which drove both market performance and strong Q4 earnings results. While all sectors and styles have recently turned green, the rally is still mostly narrow. Earnings growth appears to be strong, but outside of the Magnificent Six, many companies are struggling. The market appears expensive and overbought, but that is mostly down to the high valuations and the popularity of the Magnificent Six.
Swiss annual inflation continued to decelerate in February, with headline CPI now at 1.2% and core at 1.1%. This is remarkable since inflation continues to track well below the 1.8% forecast by the Swiss National Bank (SNB) for the first quarter. Import and…
Economic sentiment has improved since the December FOMC meeting, with positive momentum extending into February. The chart above neatly summarizes the impact that the Fed’s projected easing has had on sentiment, both on “Wall Street” and “Main Street”. The…
According to BCA Research’s European Investment Strategy service, the underperformance of European assets relative to the US is due its lagging productivity, even after adjusting for sectoral compositions in their stock markets. Structurally, European goods…

We feel as good about spurning the soft-landing narrative today as we did about spurning the recession narrative a year ago, but we are not giving into complacency. This week’s report looks at two key ways that we may be getting it wrong: by underestimating households’ asset support and the labor market’s durability. We remain tactically neutral but continue to look for opportunities to turn defensive.

The US ISM manufacturing PMI release for February disappointed consensus expectations. The headline index relapsed to 47.8 after climbing to a 15-month high of 49.1 in January, falling below expectations of a continued slowdown in the pace of contraction to…
The preliminary Eurozone inflation release suggests that price pressures eased by less than anticipated in February. Headline CPI inflation slowed from 2.8% y/y to 2.6% y/y (slightly above expectations of 2.5% y/y. Similarly, although the core inflation gauge…