Aterrizaje Duro/Suave de la Recesión
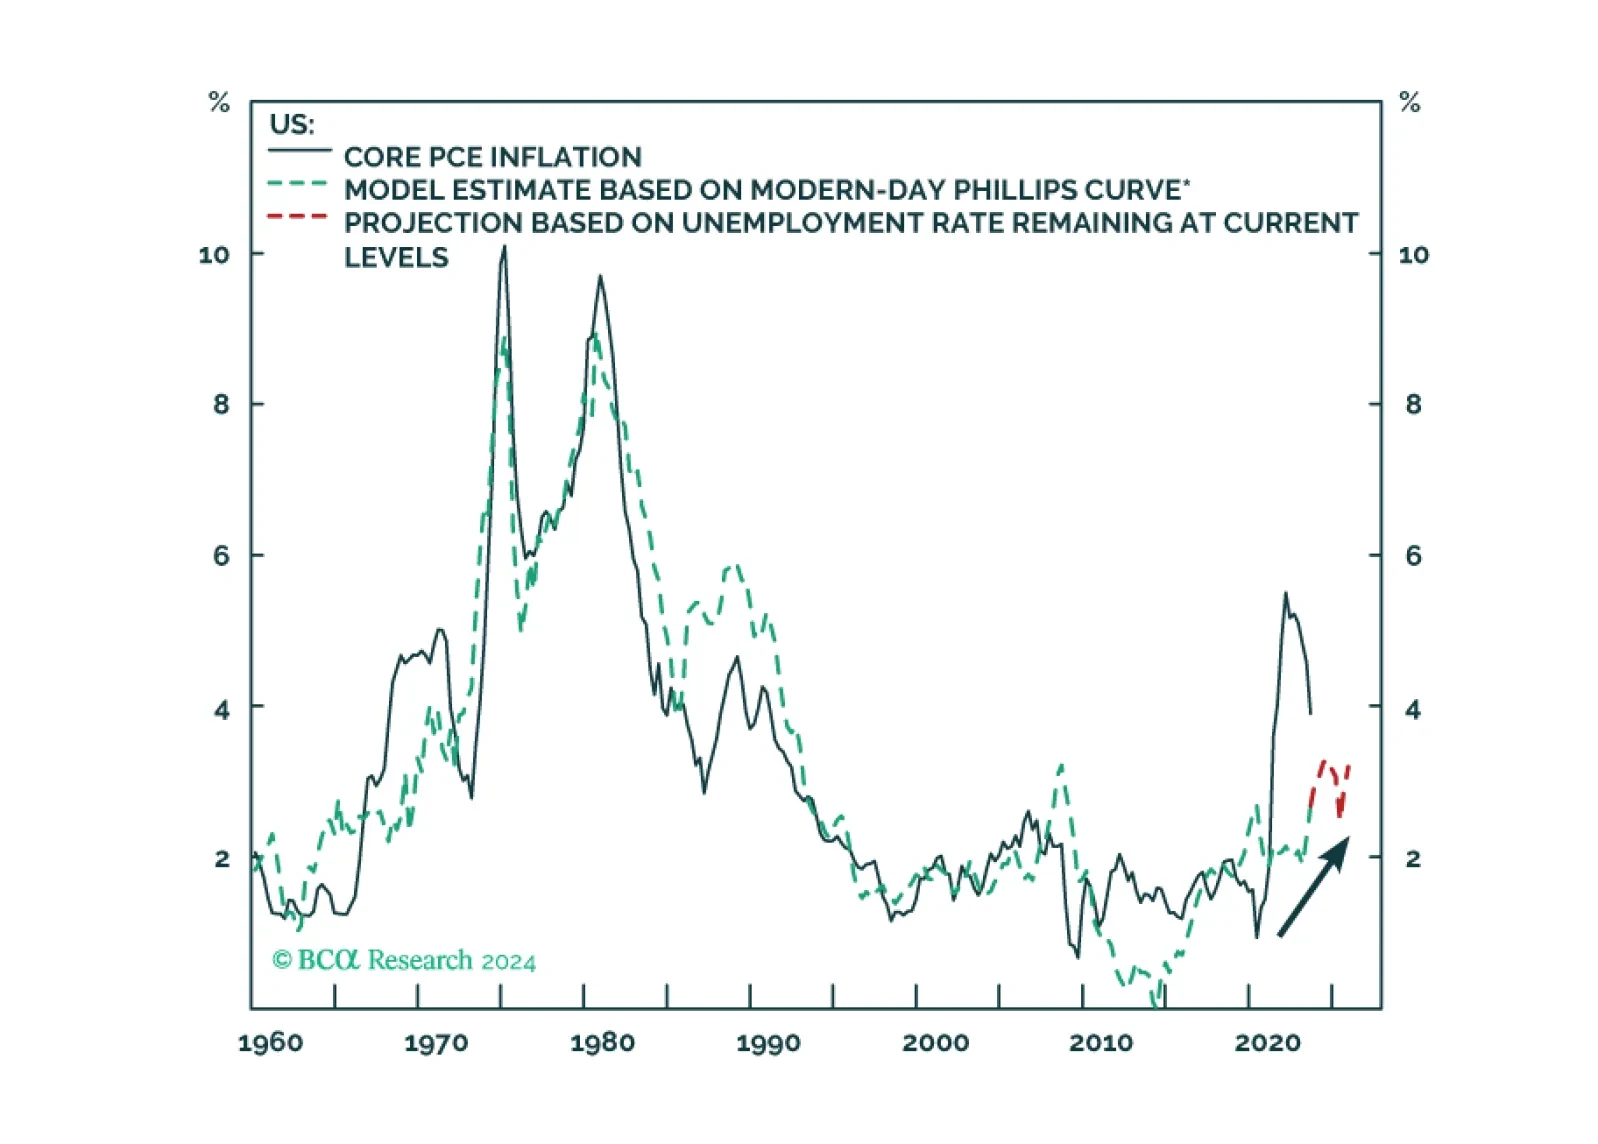
In Section I, we discuss the implications and potential risks of the Fed’s recent pivot. The near-term implications of the Fed's dovish pivot are likely to continue to be bullish for risky asset prices, and a new high in global stock prices cannot be ruled out. The Fed has not effectively countered market expectations that monetary policy will cease to be tight in a year’s time, which has eased financial conditions and will work counter to the Fed’s economic forecasts. However, we would expect this, at most, to delay rather than to prevent a recession. Developed economies remain on a recessionary path so long as monetary policy in the US and euro area remains actually tight. As such, we do not see the December meeting as a truly bullish catalyst for risky assets on a 12-month time horizon. In Section II, my colleague Ryan Swift of BCA’s US Bond Strategy service reviews the outlook for the Fed’s interest rate and balance sheet policies for next year.
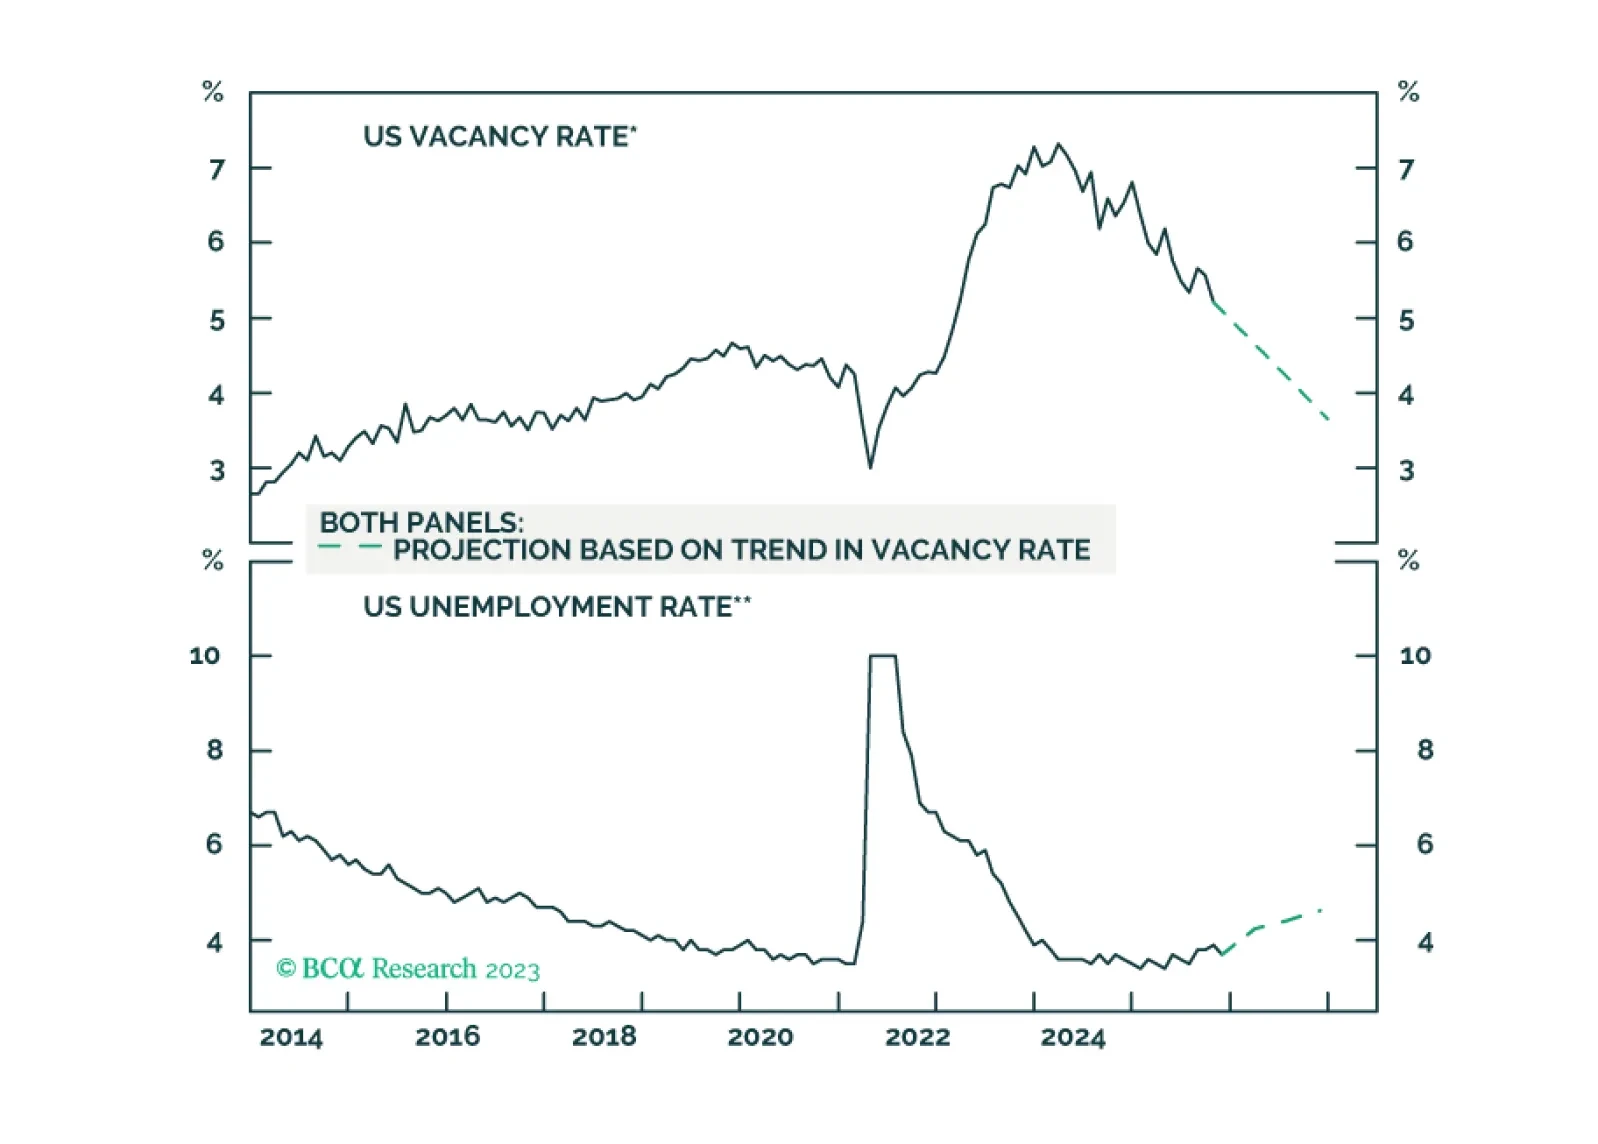
Our outlook for the Fed’s interest rate and balance sheet policies in 2024.
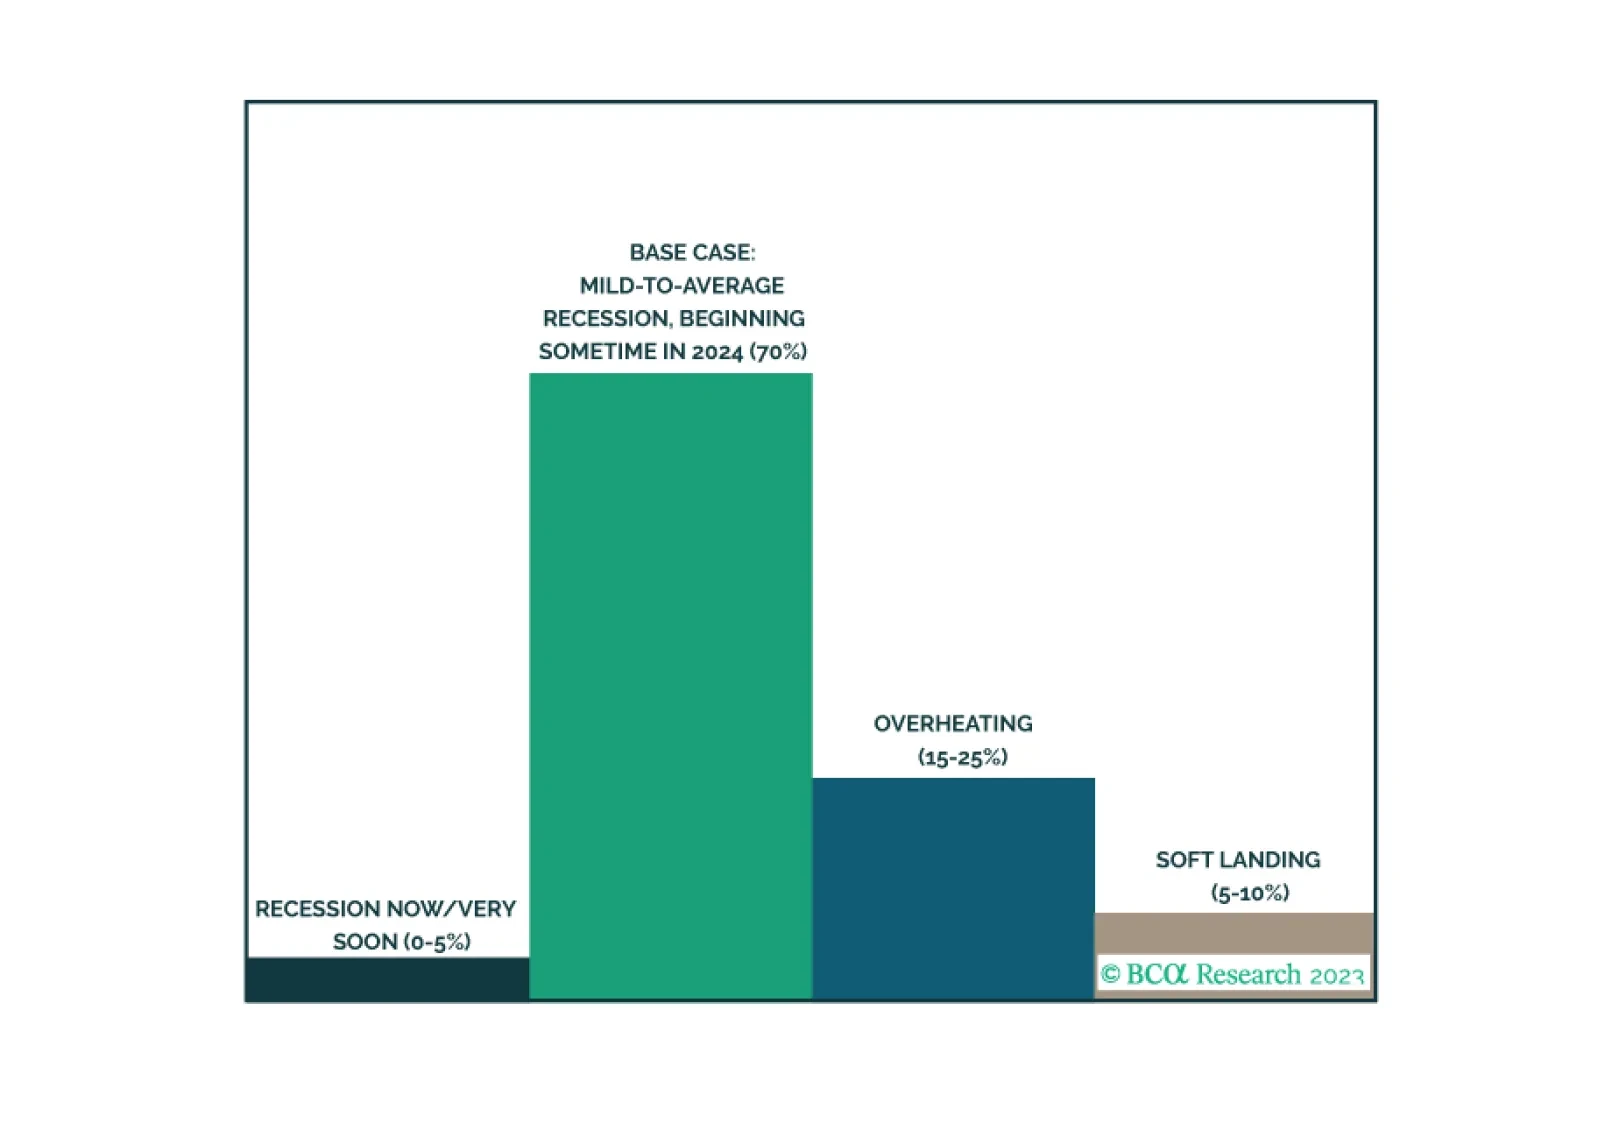
Our last publication of 2023 is an illustrated guide to our view that the economy will enter a recession around midyear. We expect equities will underperform Treasuries and cash over much of 2024, but we are waiting to turn tactically defensive until more investors are drawn into the soft-landing camp, capping the equity rally.
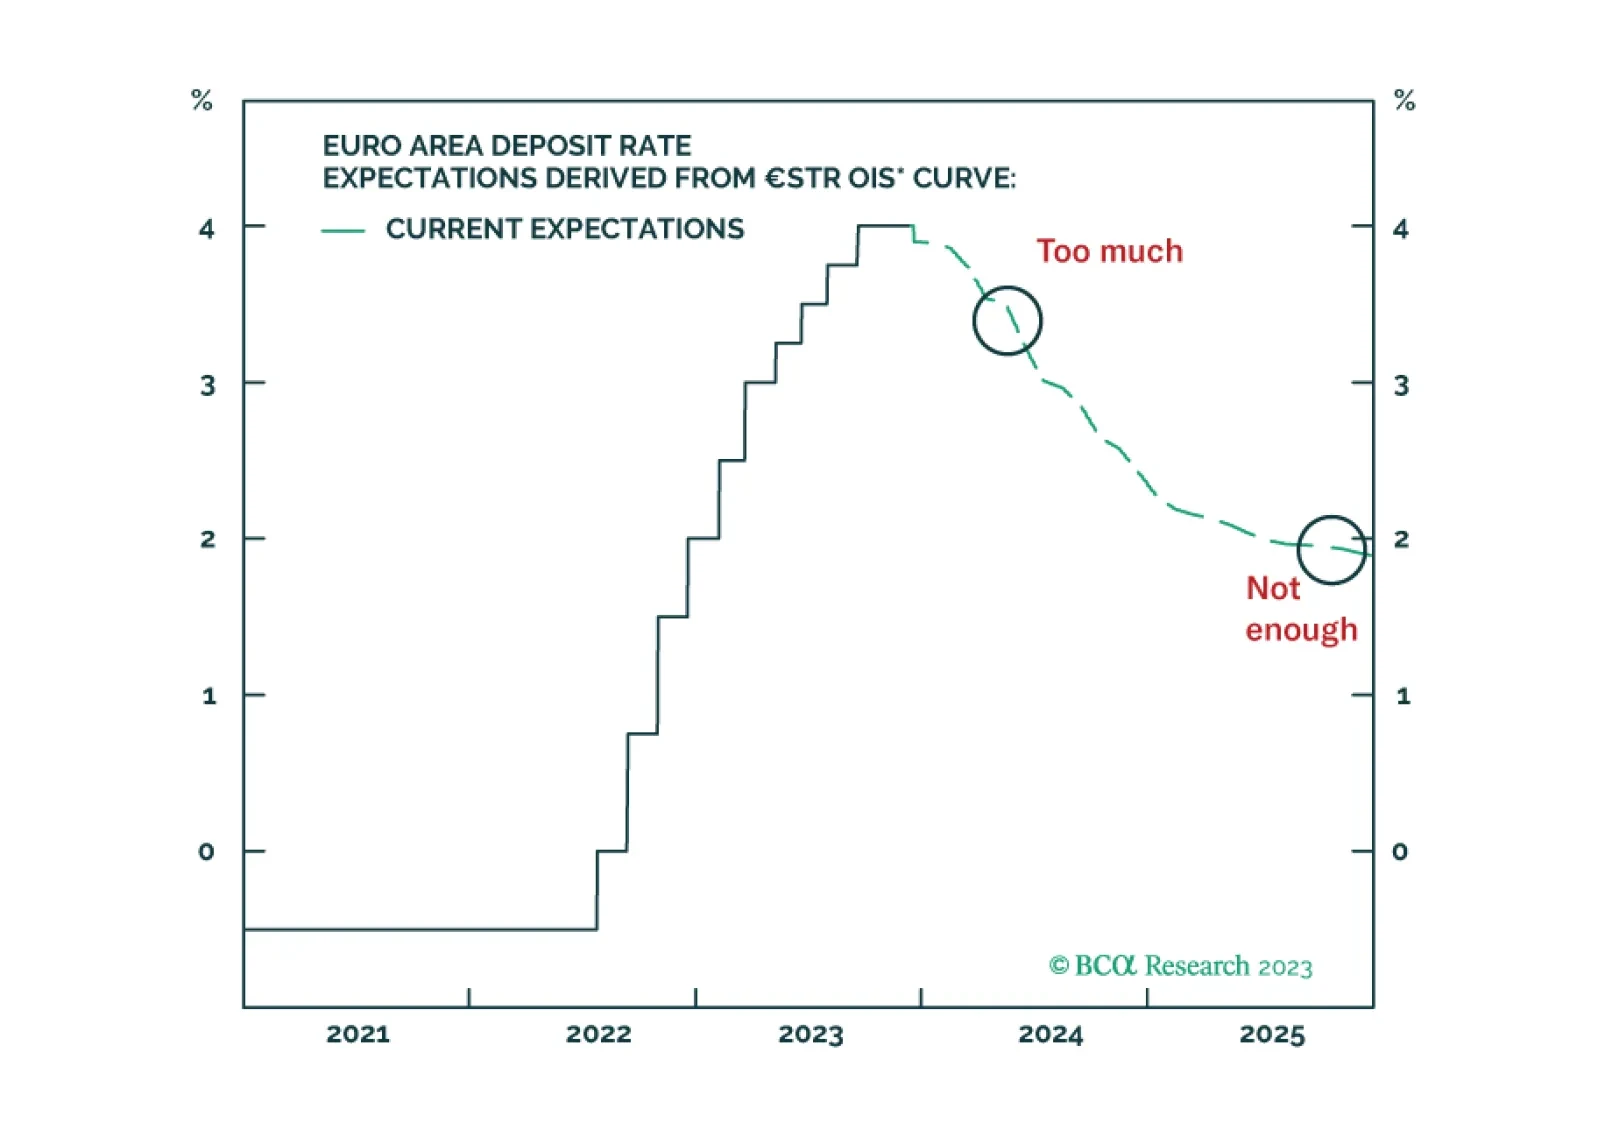
Explore the eight main themes that will drive the returns of European assets in 2024.
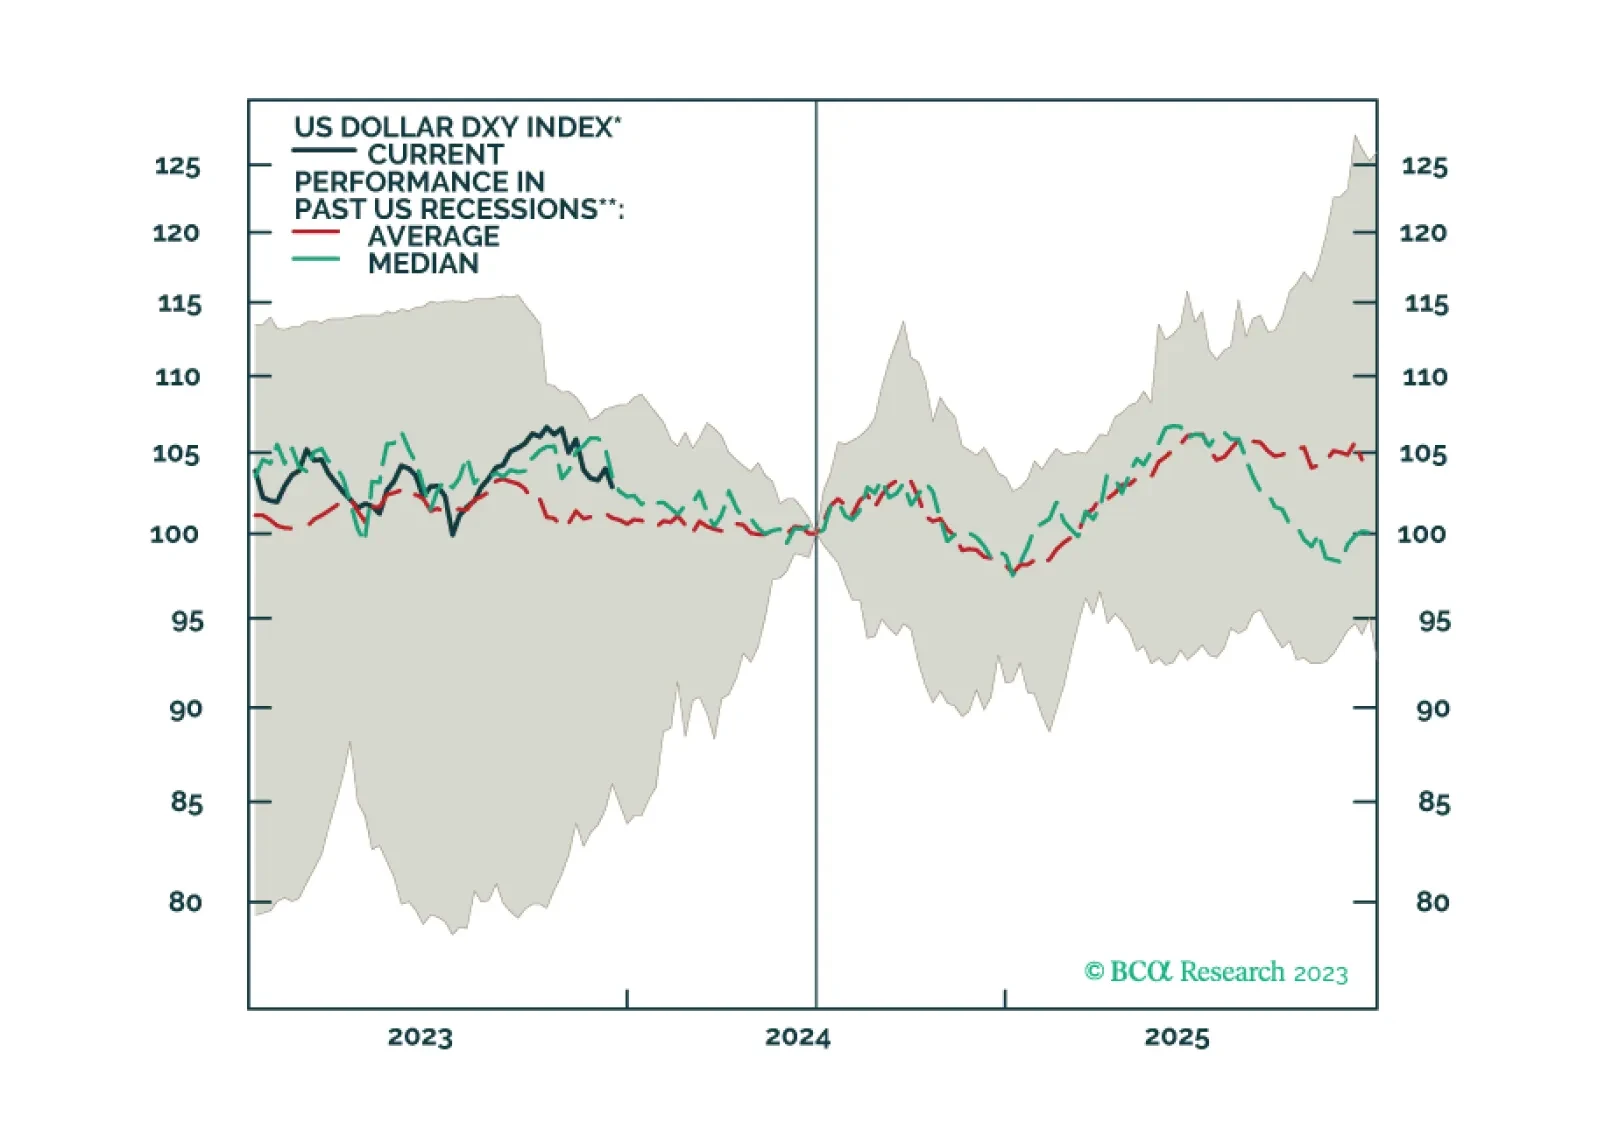
In this week’s report, we present our dollar view for 2024 and beyond, with a few trade ideas.
