Saltar al contenido principal

Essentials

Concise macro insight that cuts through daily noise, helping clients stay informed on what matters in markets, why it matters, and how to talk about it, without spending hours reading research.

Explore Essentials
Bank Credit Analyst In this BCA Special Report, we ask what policies investors should expect if Donald Trump wins the 2024 Presidential election. The answer is that a second Trump term would be much less positive for risky assets than the first. While the US will remain democratic and geopolitically preeminent no matter the outcome of the 2024 election, a second term Trump administration would likely oversee large budget deficits, continued wealth inequality, labor shortages, high import prices, and an erosion of checks and balances, possibly including at the Federal Reserve. Trade policy under a second Trump presidency represents the greatest cyclical risk to investors, and the sequencing of policies in general will be important to monitor. An early legislative priority of immigration over tax cuts, alongside the rapid imposition of new tariffs, would be the worst alignment for risky assets.
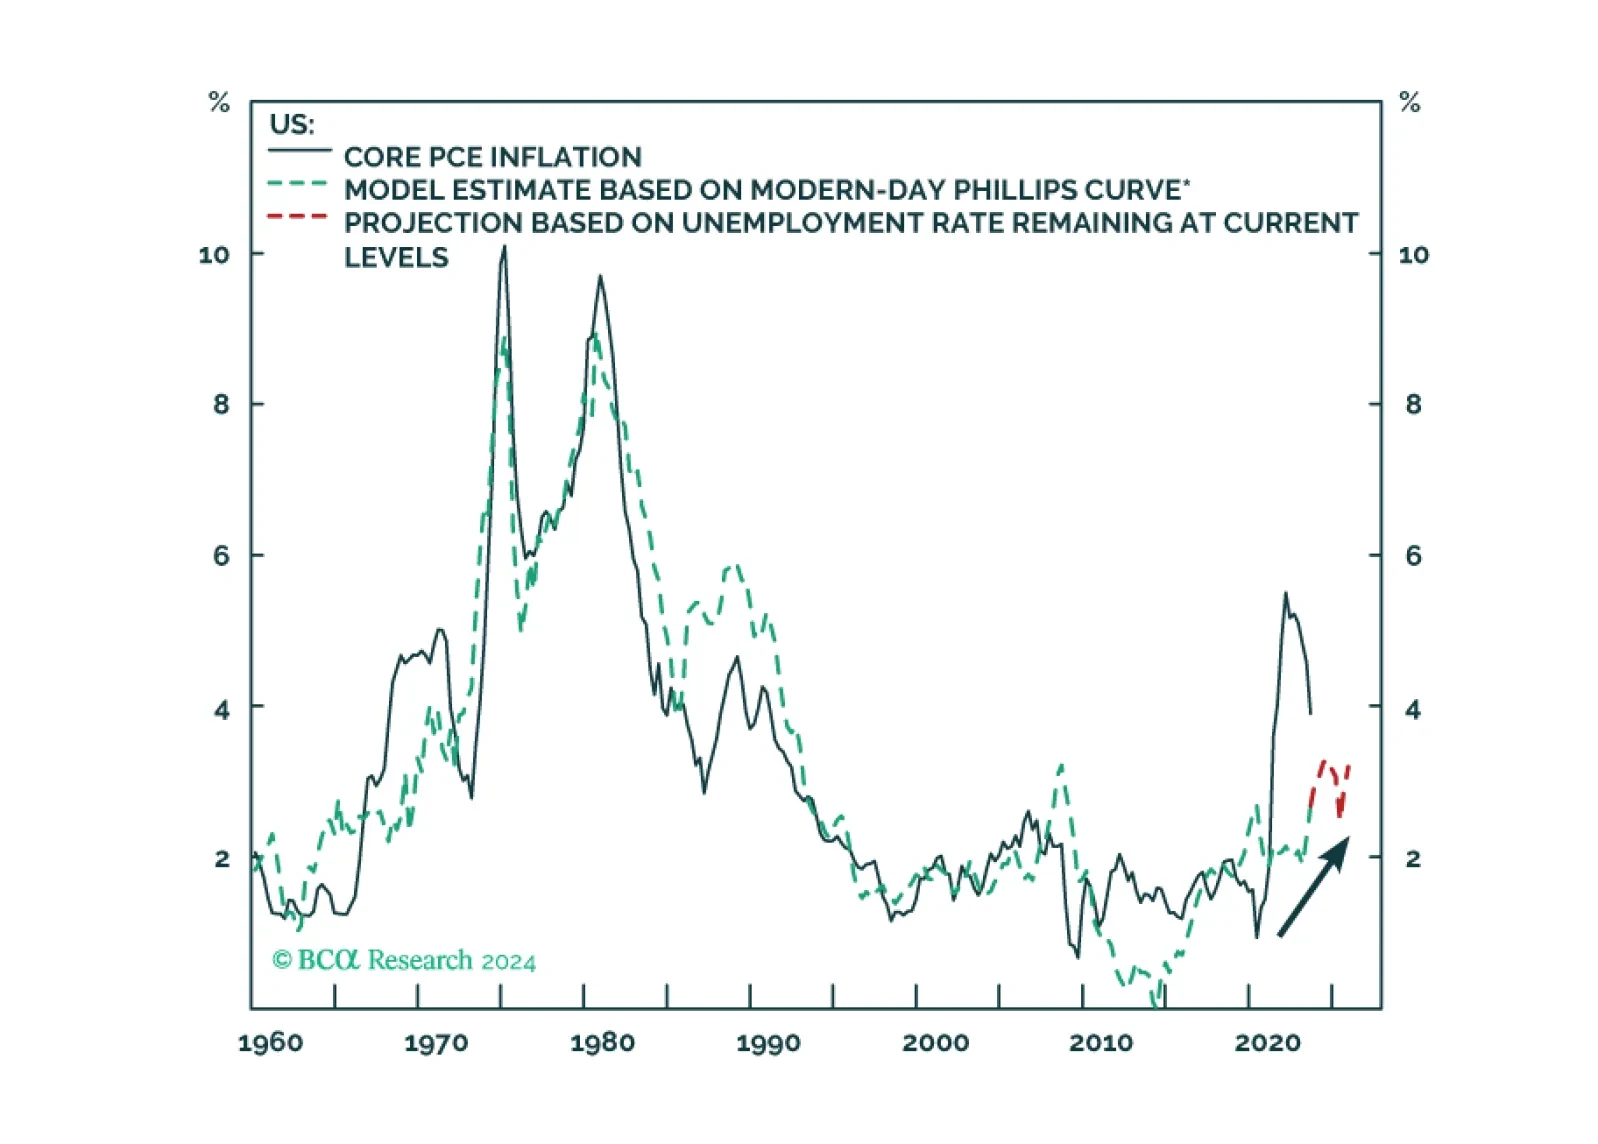
Bank Credit Analyst In Section I, we argue that the December FOMC meeting has caused the “soft landing” narrative to penetrate the psyche of “Main Street”, which is now impacting the real economy. But if a pickup in sentiment and growth works against the pace of disinflation on which expectations of rate cuts were predicated, then the economy has a “circular reference” problem. A true “no landing” scenario would likely prevent Fed rate cuts, which would cause a large hawkish shock. That would put pressure on equity multiples via both a higher risk-free rate and equity risk premium. In Section II, we ask what policies investors should expect if Donald Trump wins the 2024 Presidential election. The answer is that a second Trump term would be much less positive for risky assets than the first.
Bank Credit Analyst In this BCA Special Report, we ask what policies investors should expect if Donald Trump wins the 2024 Presidential election. The answer is that a second Trump term would be much less positive for risky assets than the first. While the US will remain democratic and geopolitically preeminent no matter the outcome of the 2024 election, a second term Trump administration would likely oversee large budget deficits, continued wealth inequality, labor shortages, high import prices, and an erosion of checks and balances, possibly including at the Federal Reserve. Trade policy under a second Trump presidency represents the greatest cyclical risk to investors, and the sequencing of policies in general will be important to monitor. An early legislative priority of immigration over tax cuts, alongside the rapid imposition of new tariffs, would be the worst alignment for risky assets.
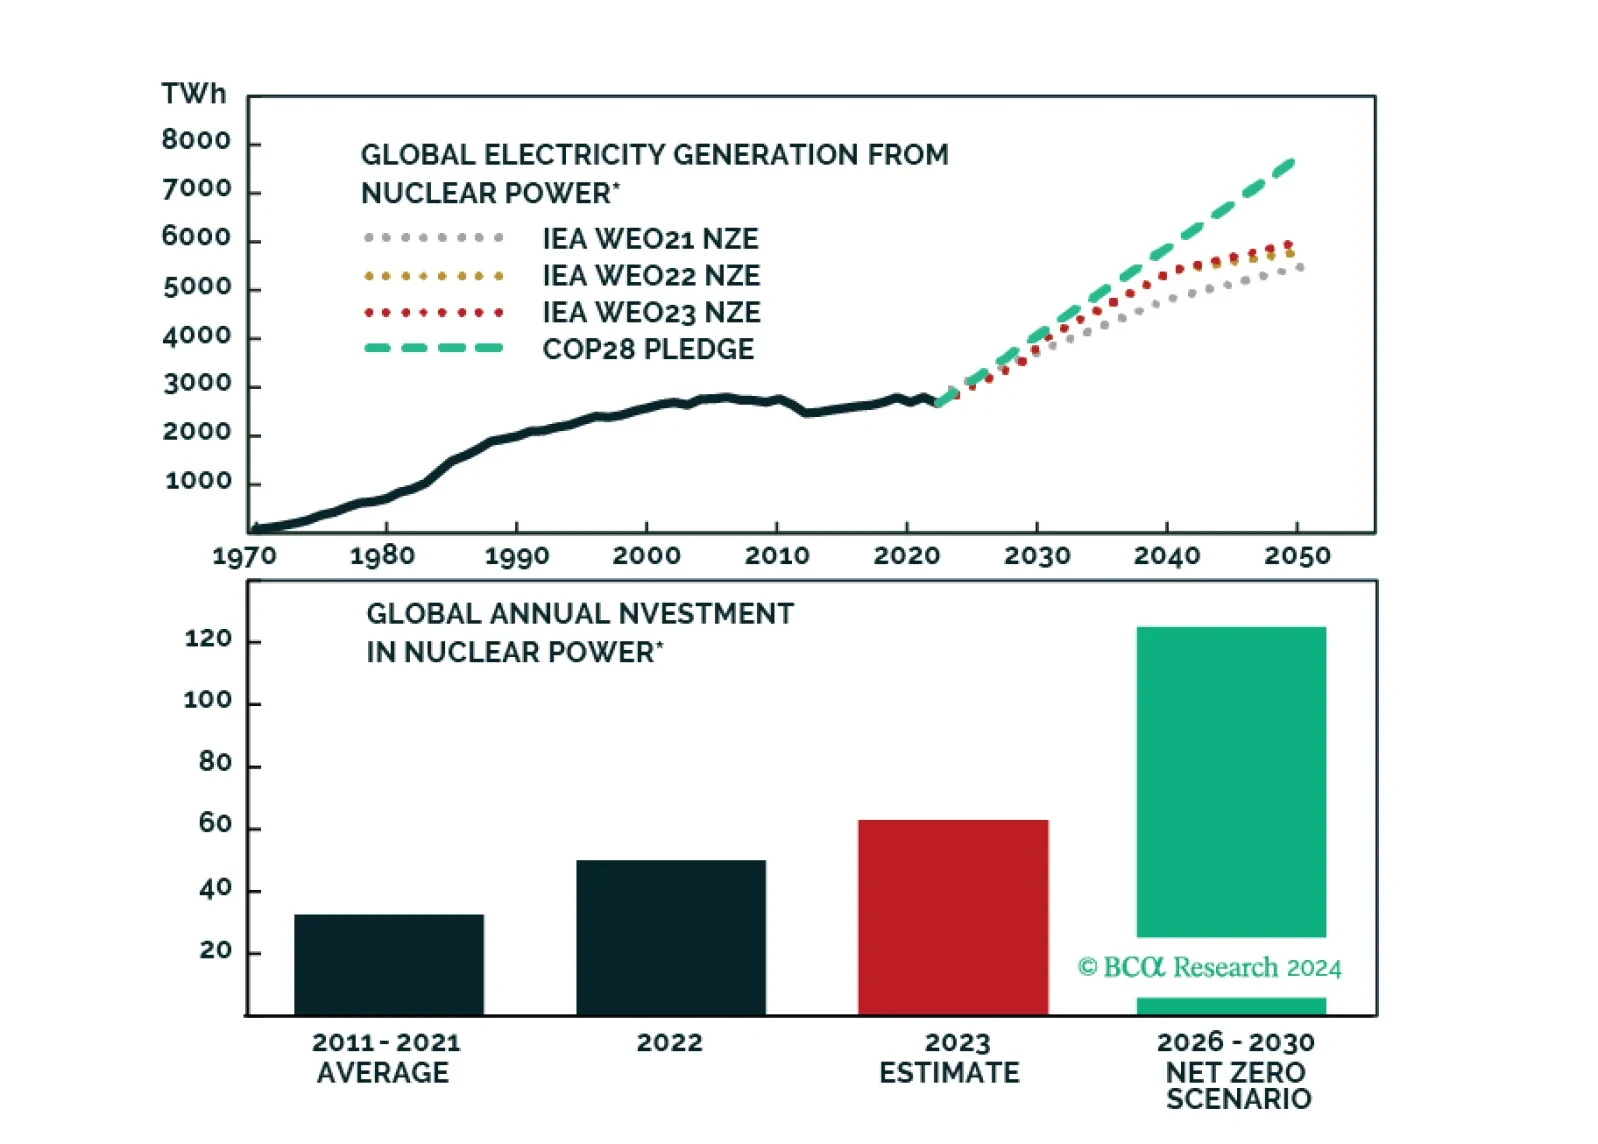
Bank Credit Analyst This report presents the main ways to invest in the Nuclear Renaissance; from exposure to physical uranium to equity plays alongside or outside the nuclear fuel cycle.
Bank Credit Analyst BCA Research presents a limited monthly special series about the Nuclear Renaissance.
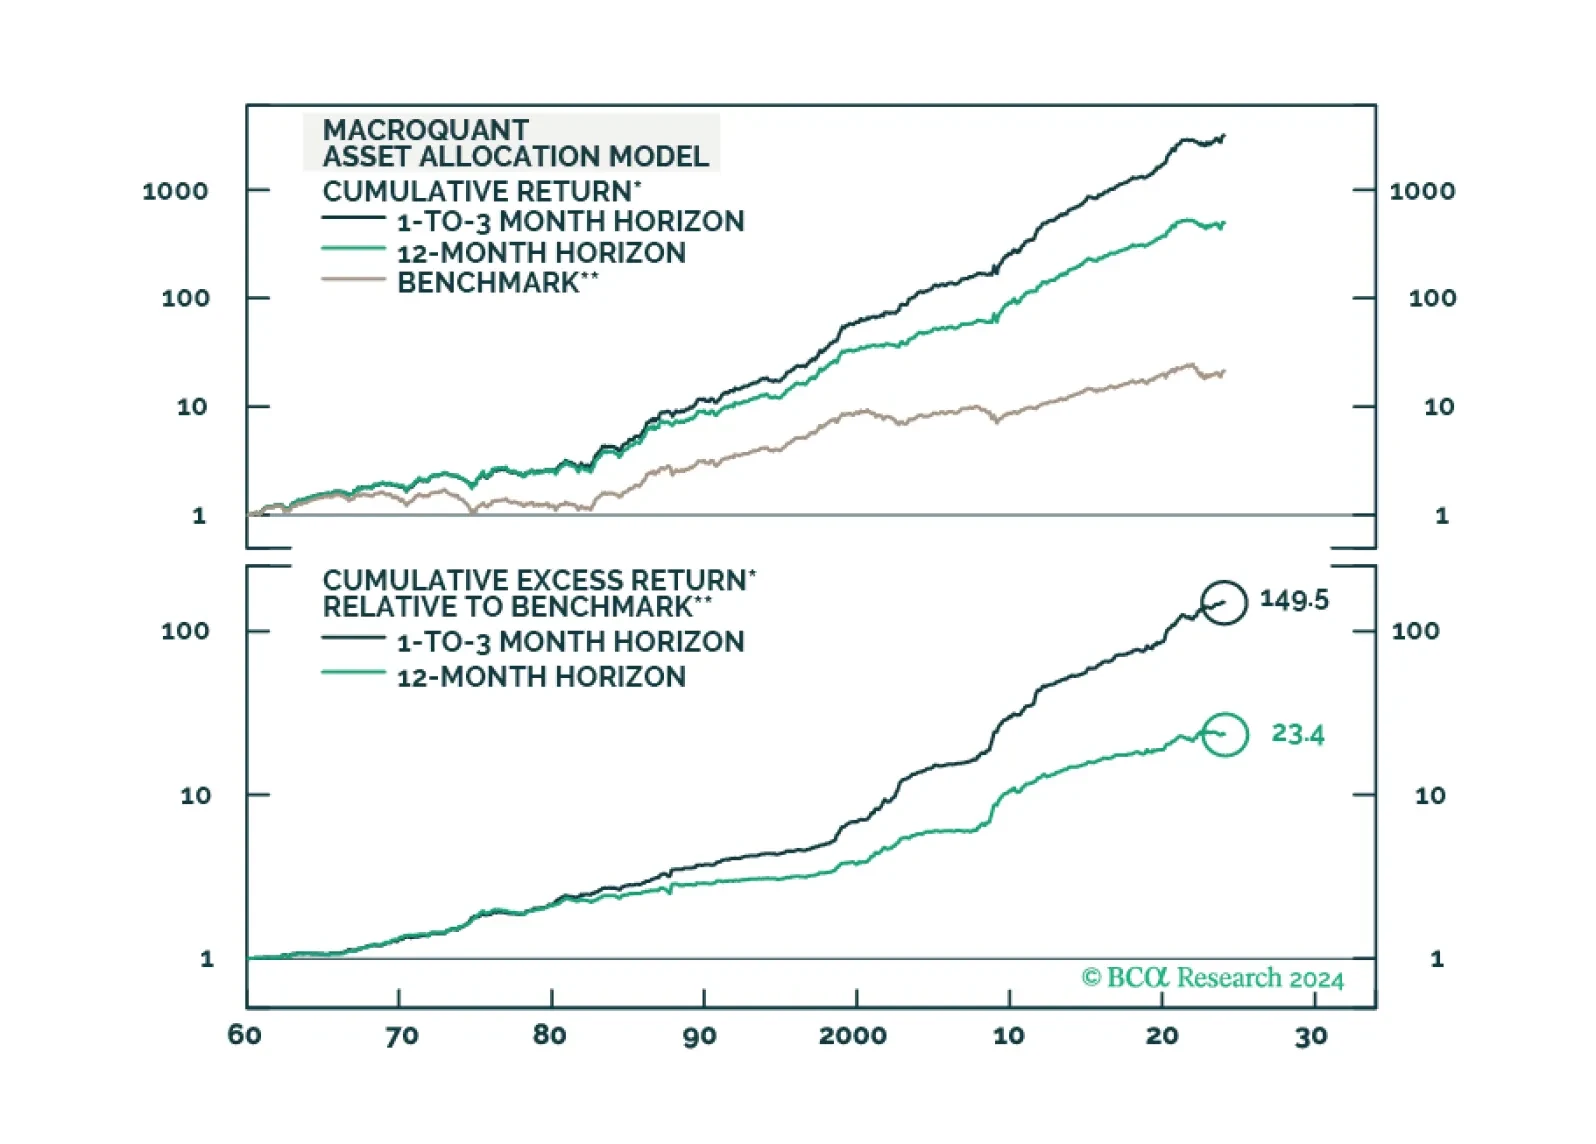
Bank Credit Analyst Today we are sending you the white paper introducing our next-generation MacroQuant 2.0 model. Two years in the making, this model distills everything I have learned about economics and financial markets over the past 30 years into simple buy and sell signals.
Bank Credit Analyst
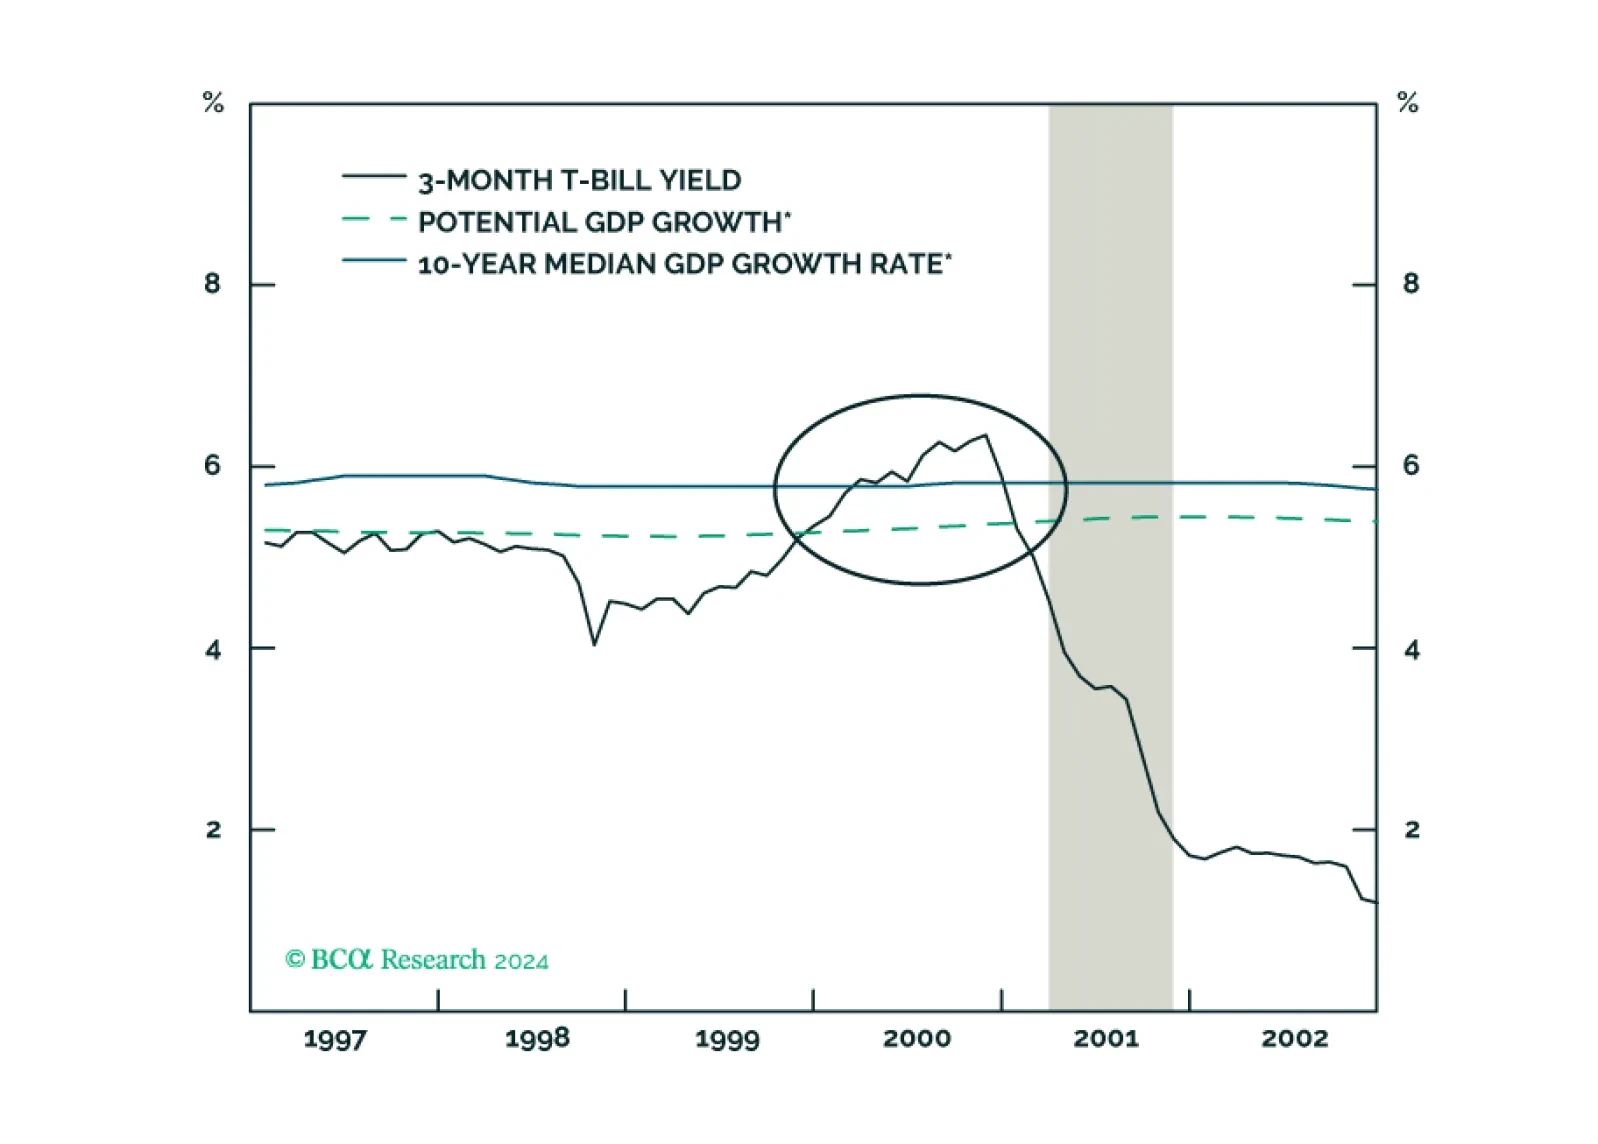
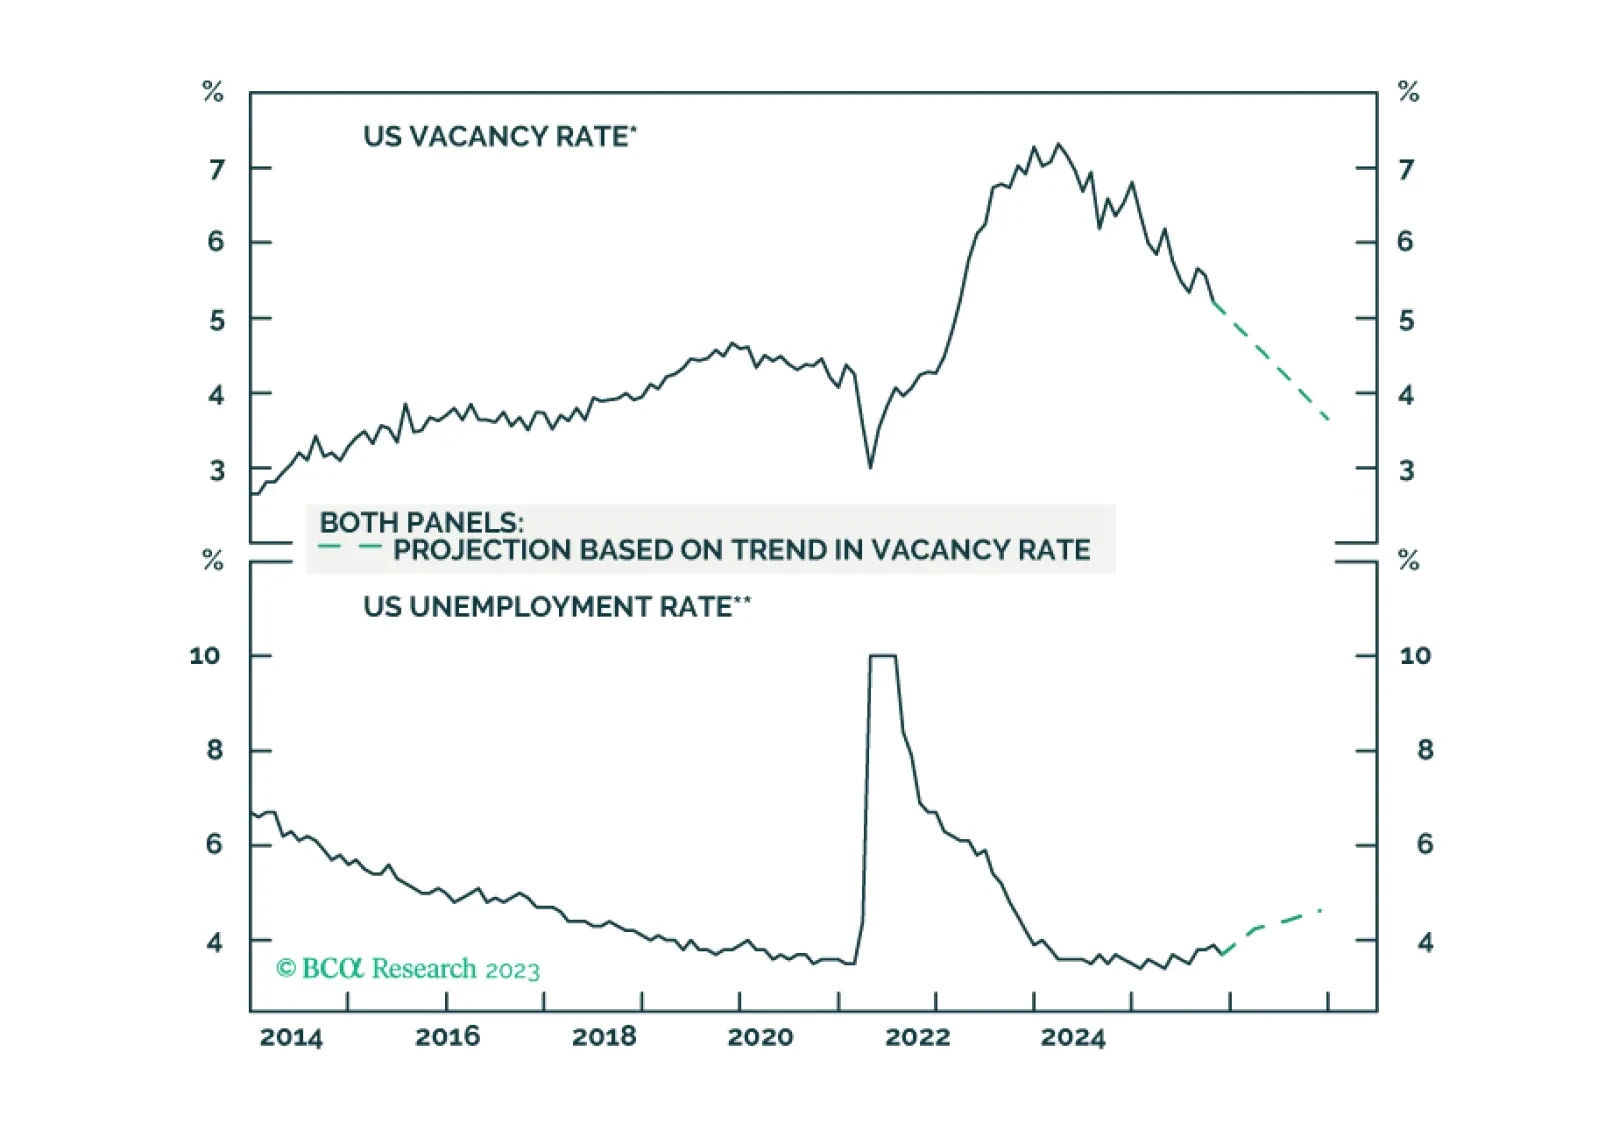
Bank Credit Analyst In Section I, we discuss the important flaws in the market’s “Goldilocks” economic narrative. Forward-looking measures of labor demand are heralding an eventual rise in the unemployment rate, and it is unlikely that this will occur in a benign fashion. This underscores that the US economy remains on a recessionary trajectory so long as monetary policy remains tight. Over the very near term, the Fed's December policy shift will remain a bullish factor for risky asset prices. But over a 6-12 month time horizon, investors should still be underweight risky assets and long fixed-income duration. In Section II, we review the post-World War II recessions to understand their causes and to see what indicators have been the most successful at signaling the end of recessionary selloffs in equity markets. We present an early draft “economic recovery checklist” for investors to monitor as a guide to determining when to increase one’s allocation to equities and other risky assets in the middle of a recession.
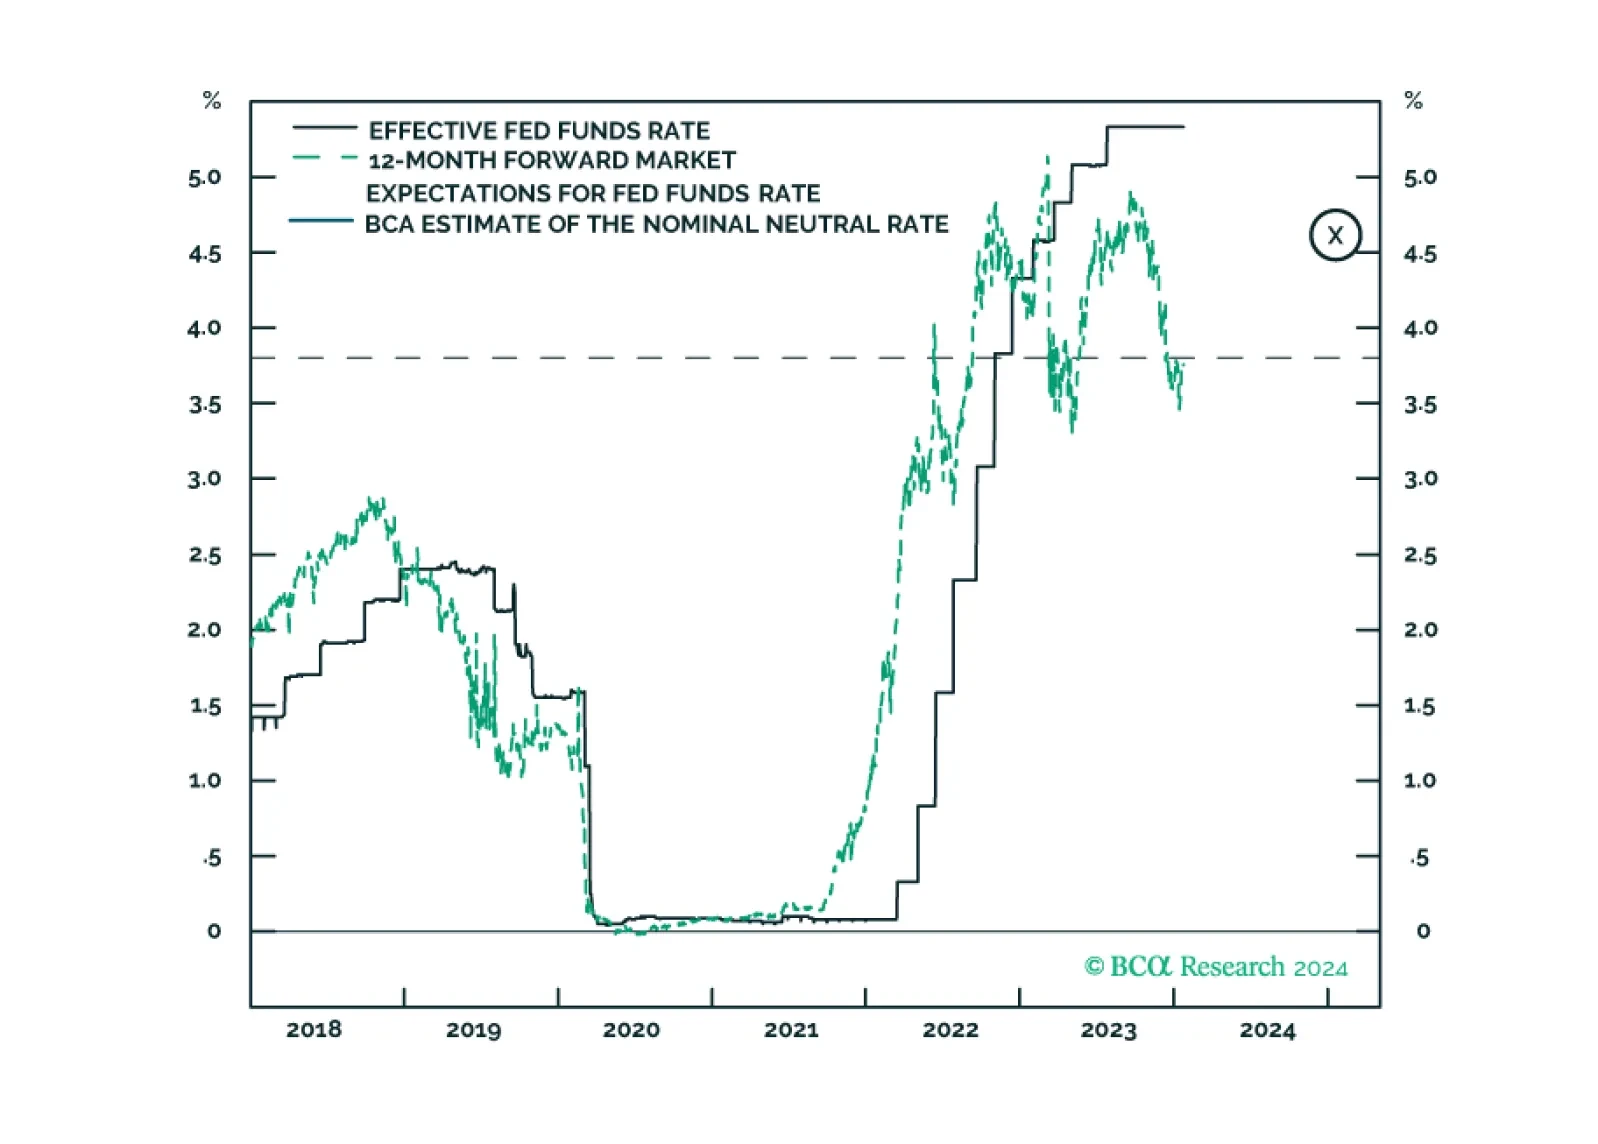
Bank Credit Analyst Our outlook for the Fed’s interest rate and balance sheet policies in 2024.
Bank Credit Analyst In Section I, we discuss the implications and potential risks of the Fed’s recent pivot. The near-term implications of the Fed's dovish pivot are likely to continue to be bullish for risky asset prices, and a new high in global stock prices cannot be ruled out. The Fed has not effectively countered market expectations that monetary policy will cease to be tight in a year’s time, which has eased financial conditions and will work counter to the Fed’s economic forecasts. However, we would expect this, at most, to delay rather than to prevent a recession. Developed economies remain on a recessionary path so long as monetary policy in the US and euro area remains actually tight. As such, we do not see the December meeting as a truly bullish catalyst for risky assets on a 12-month time horizon. In Section II, my colleague Ryan Swift of BCA’s US Bond Strategy service reviews the outlook for the Fed’s interest rate and balance sheet policies for next year.