 Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
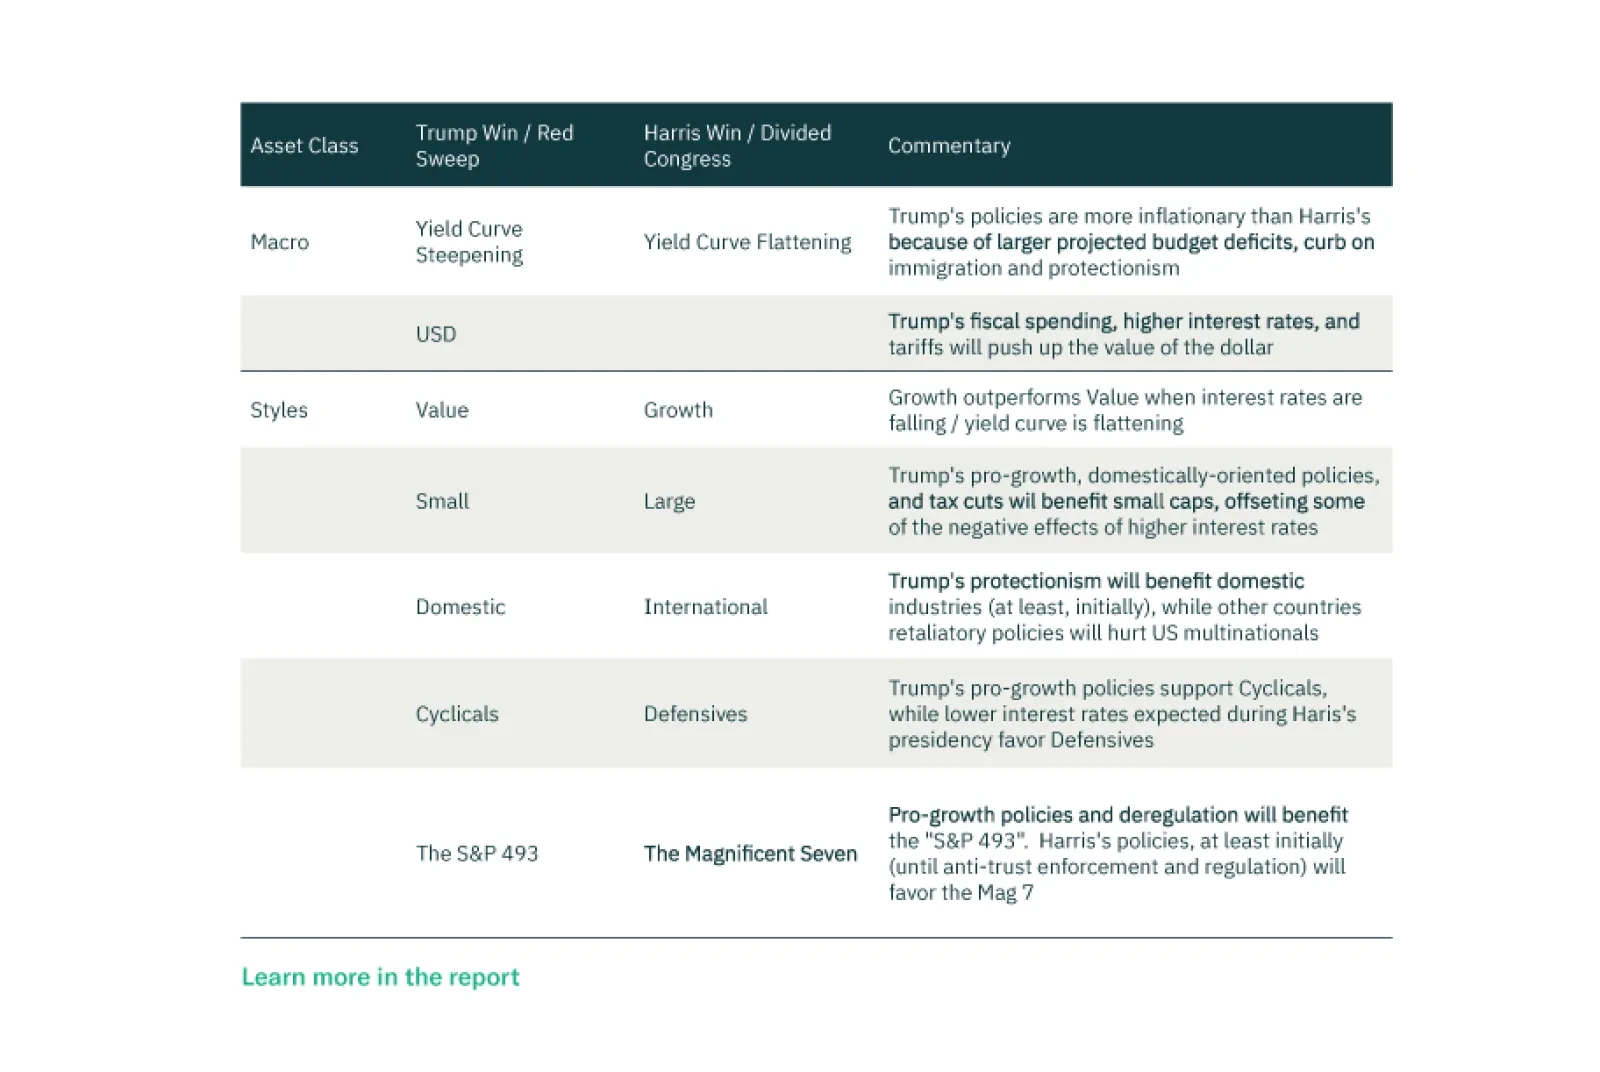
The most likely outcomes for the US elections are a “Red Sweep” and a “Blue Gridlock.” The following is a brief discussion of likely policies associated with each election outcome. We also present a post-election US Equities Cheat Sheet, in which we summarize winning trades for each scenario over the tactical investment horizon.
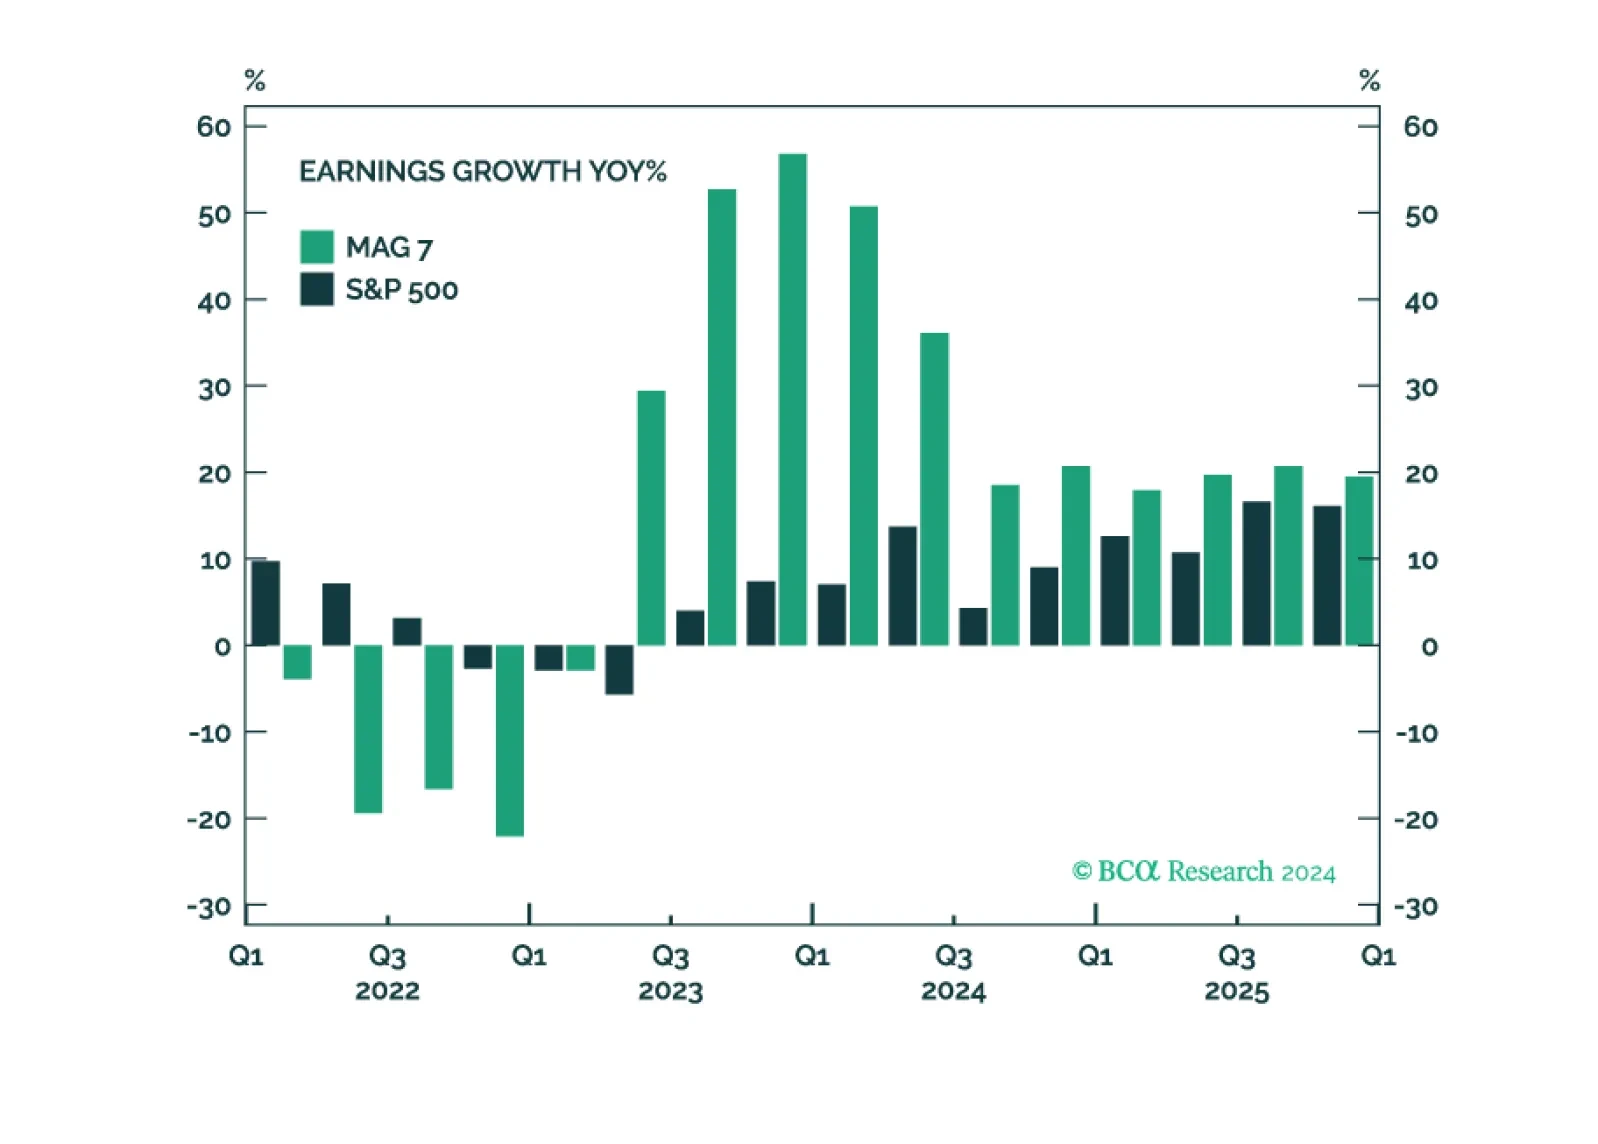
This week, we are sending you a sector chart pack. In the front section of this publication, we briefly review October's performance and then switch our attention to the earnings season and outlook for the Magnificent Seven.
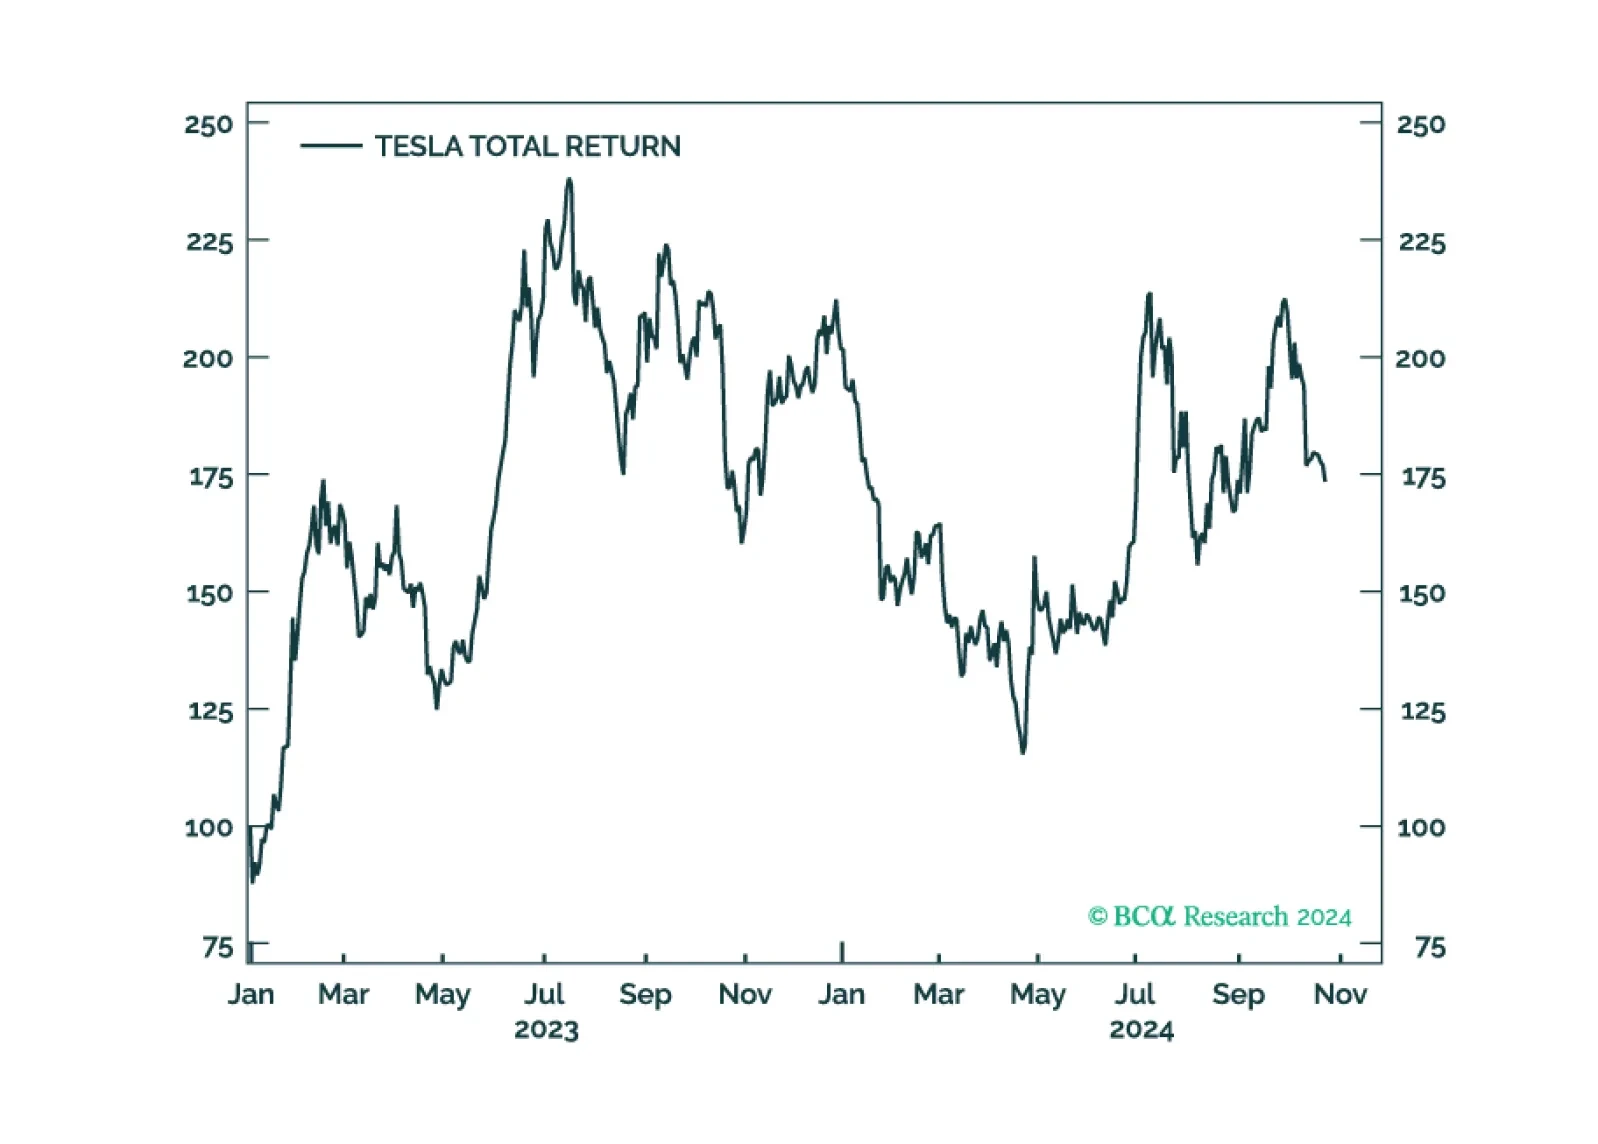
Upgrade Auto & Components Industry Group from an underweight to an overweight as it is dominated by Tesla, whose outlook has brightened.
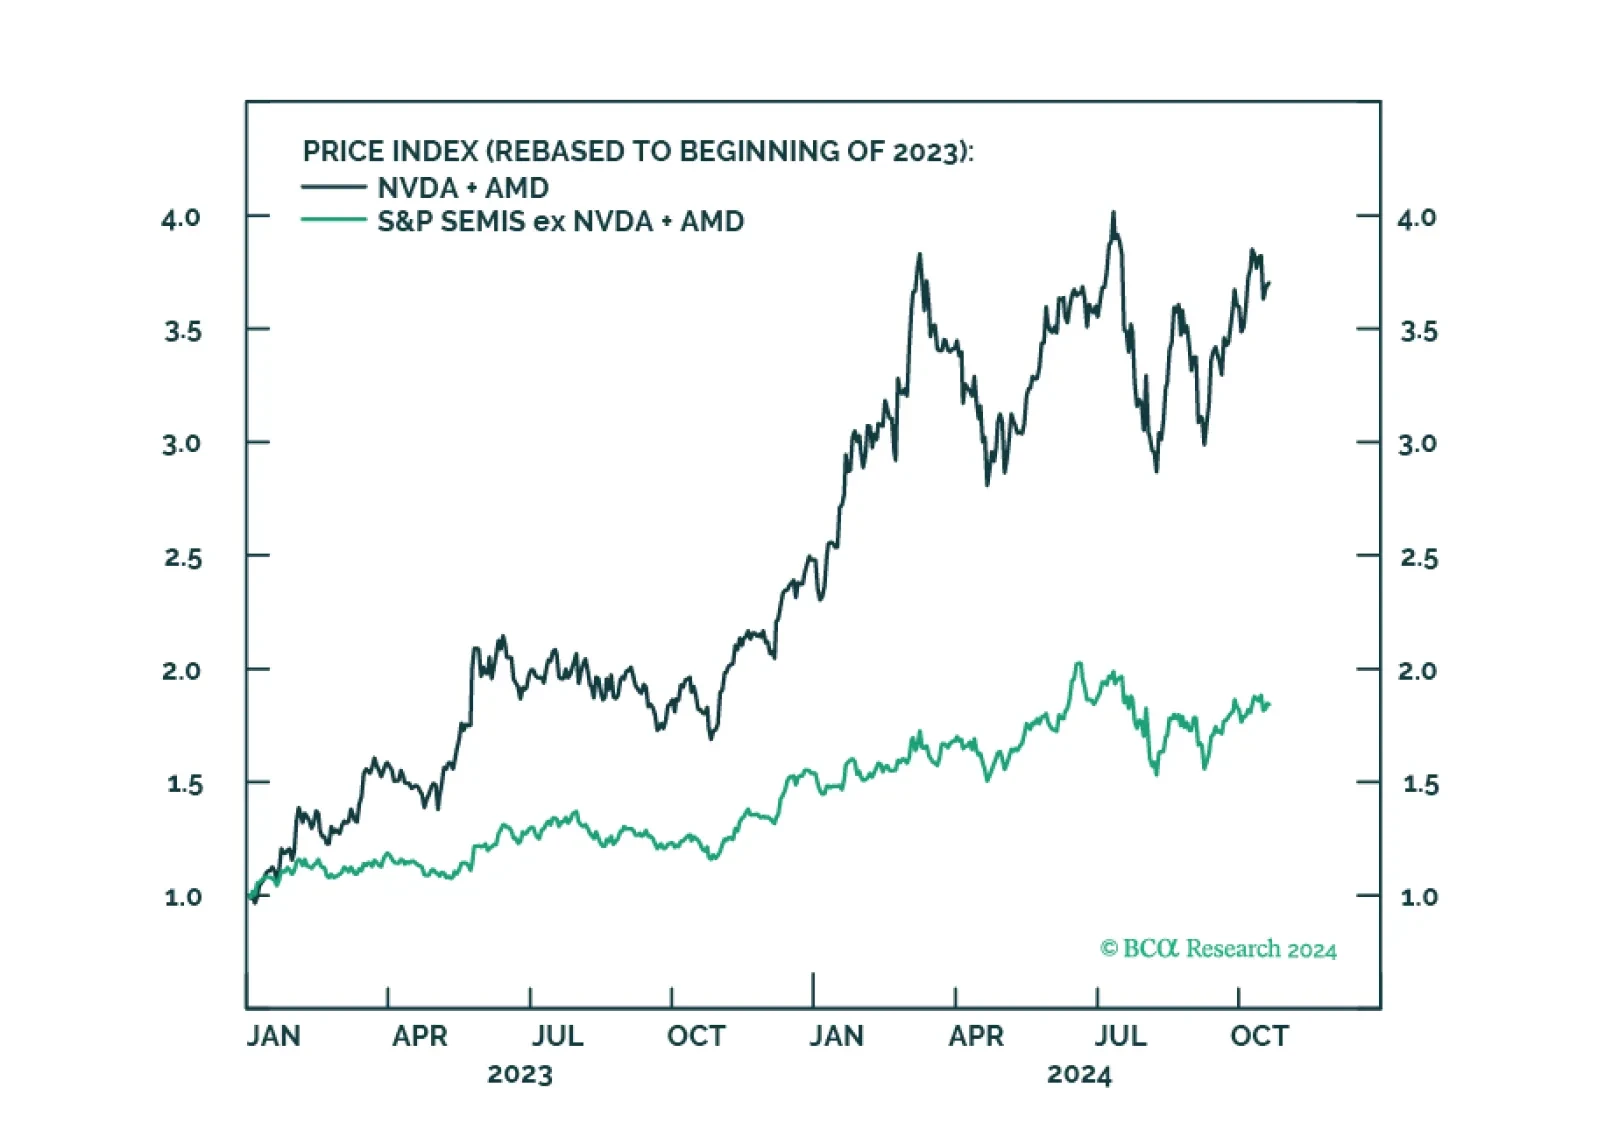
The semiconductor industry has decoupled: Demand for AI and advanced chips is booming, while the outlook for legacy and non-AI semiconductors is downbeat. We upgrade the US semiconductors to overweight on a tactical investment horizon as Nvidia’s good fortunes will drive the performance of the entire industry. We also reiterate overweight in Diversified Financials and Capital Markets as the resurgence in capital market activity is still in its early innings and will continue to drive the outperformance of the nation’s largest investment banks.
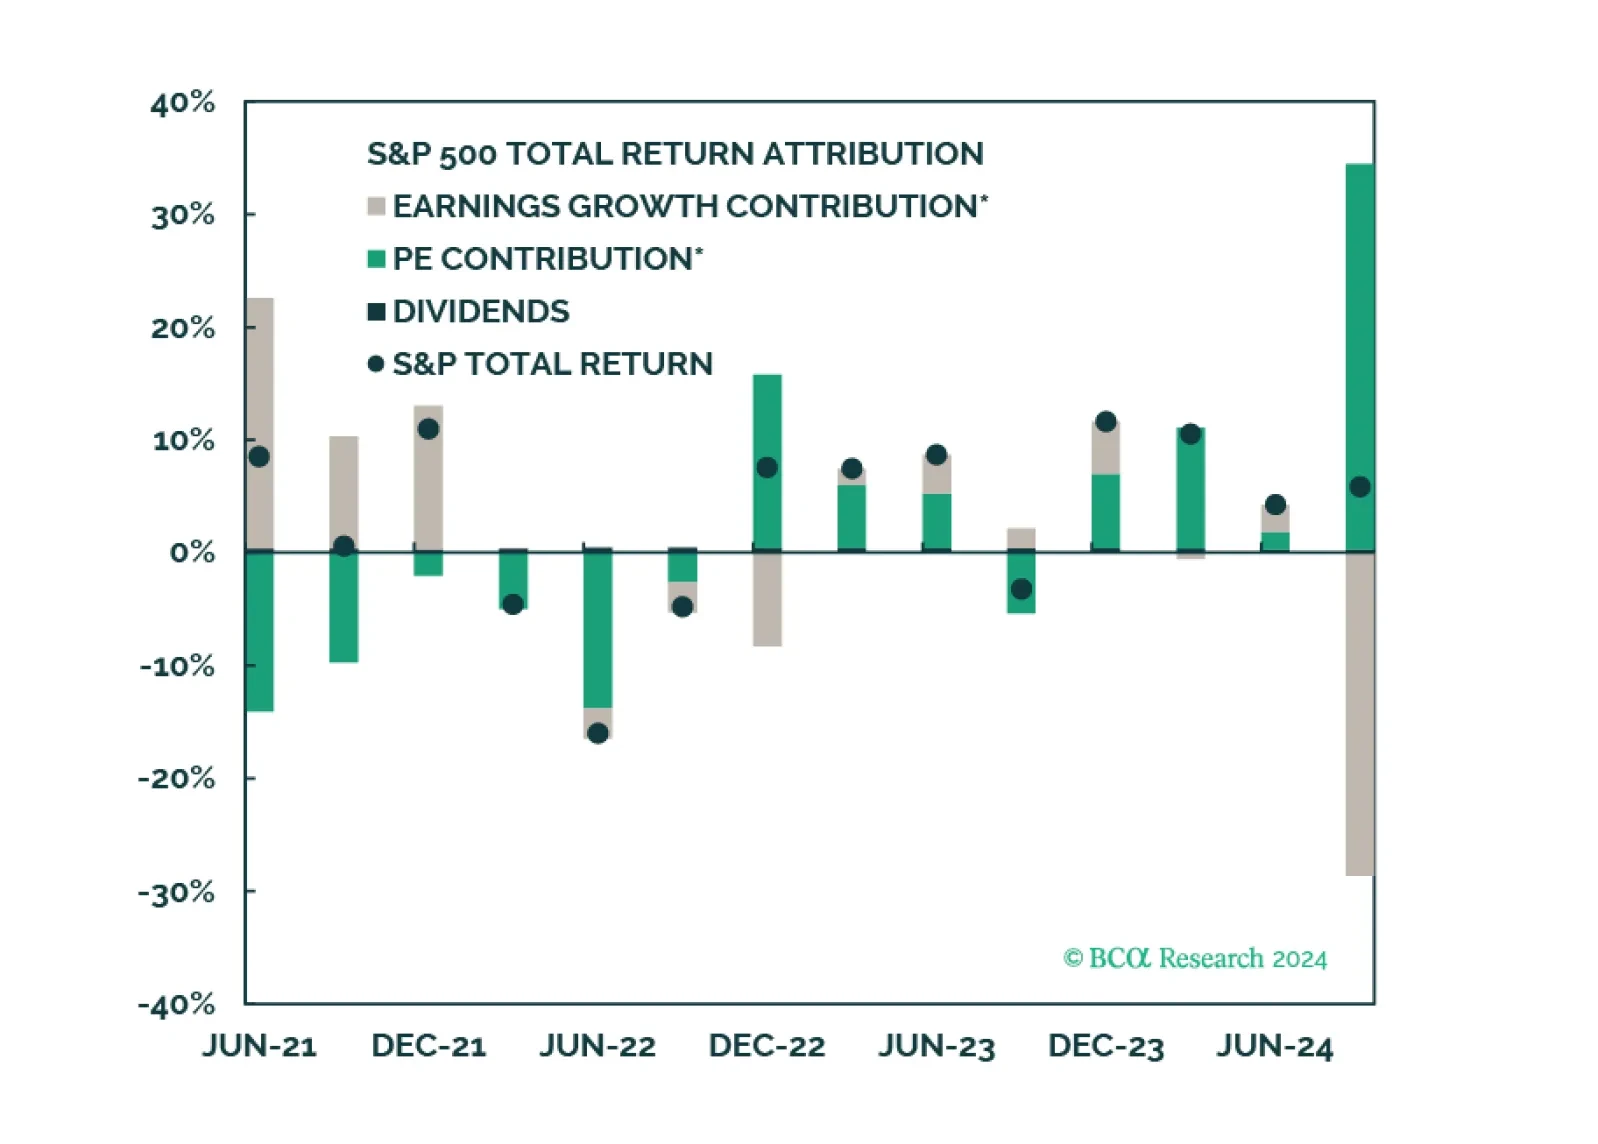
Earnings growth is expected to be strong enough to assuage investors' fears that recession is not yet imminent. Q3 earnings expectations have been revised downward over the past three months, and the bar for the beats has been lowered. Operating margins are also expected to expand.
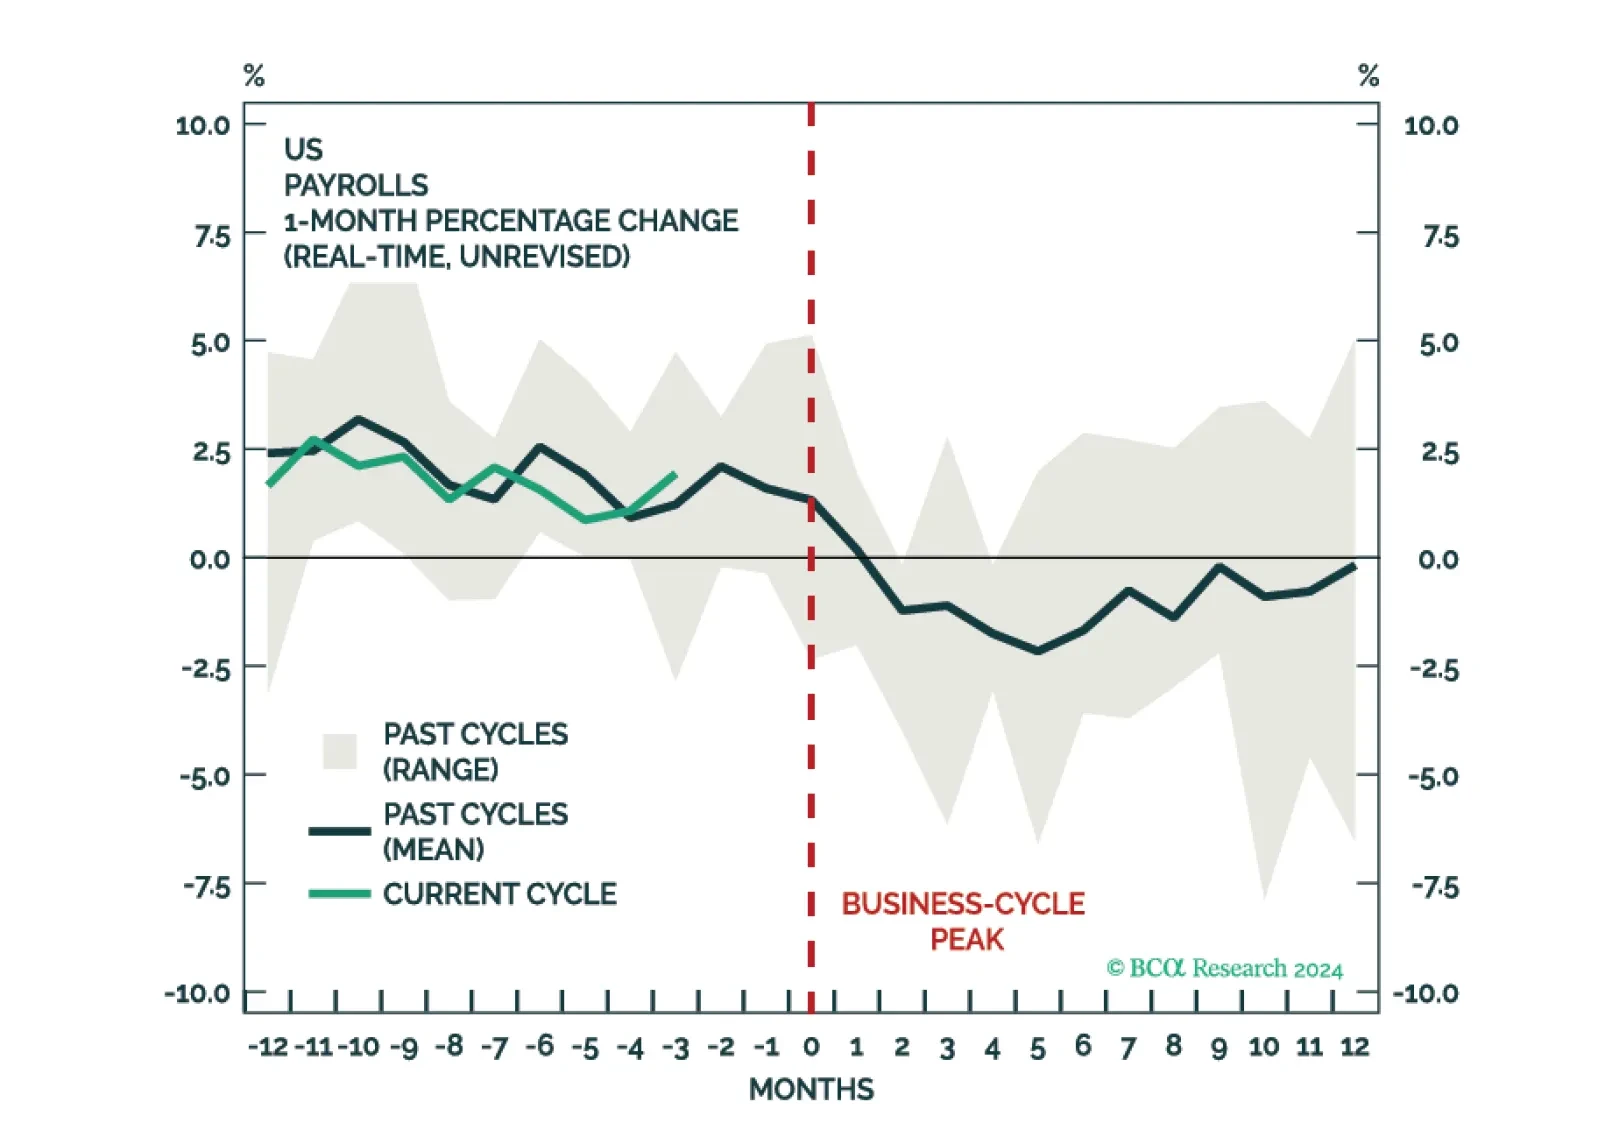
It is too early to say that the US labor market has turned the corner. We assign a 60% chance that the US will enter a recession over the next 12 months, with the downturn likely to begin in the first half of 2025. Accordingly, investors should underweight equities.
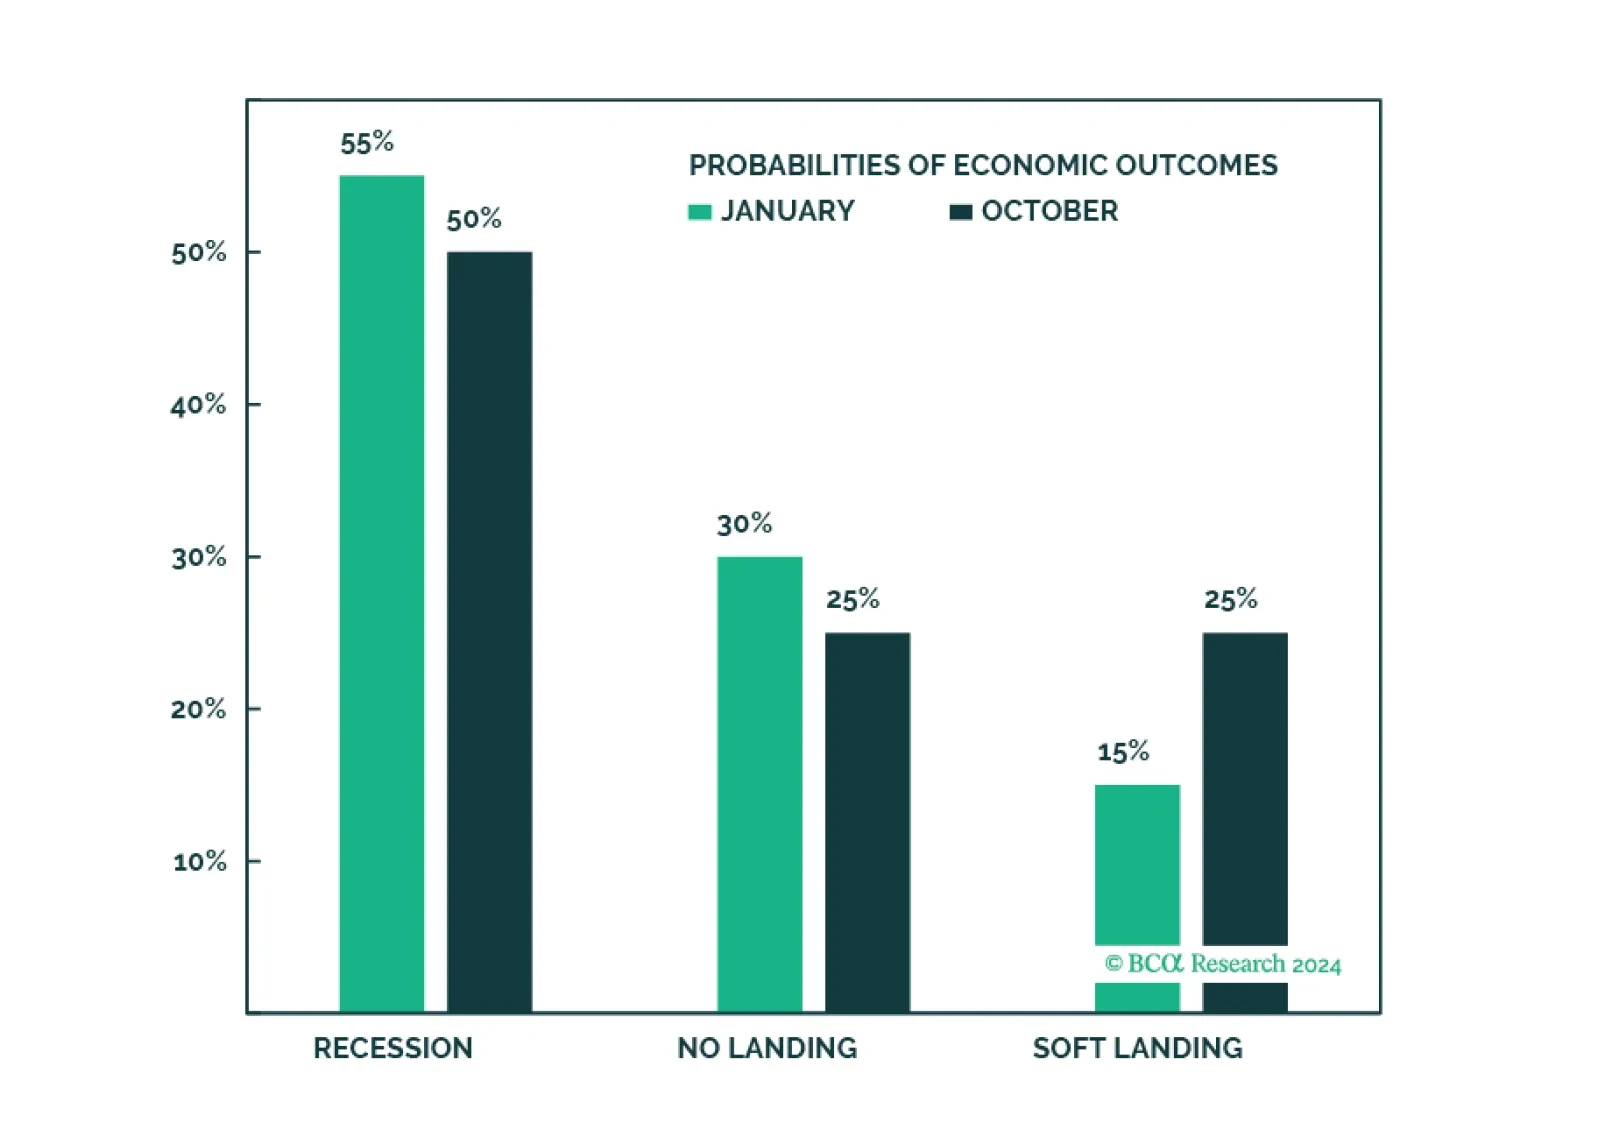
Recent data releases and revisions indicate that the US economy is stronger than initially reported, reducing the odds of a recession. While we harbor concerns about the reliability of the data, for now, it appears that aggressive monetary easing is taking place against the backdrop of a strong economy. If that is indeed the case, the economy may overheat again. This warrants portfolio rebalancing away from sectors that offer downside protection in a downturn, such as Telecom and Utilities, to sectors that outperform in a no-landing scenario, such as Energy.
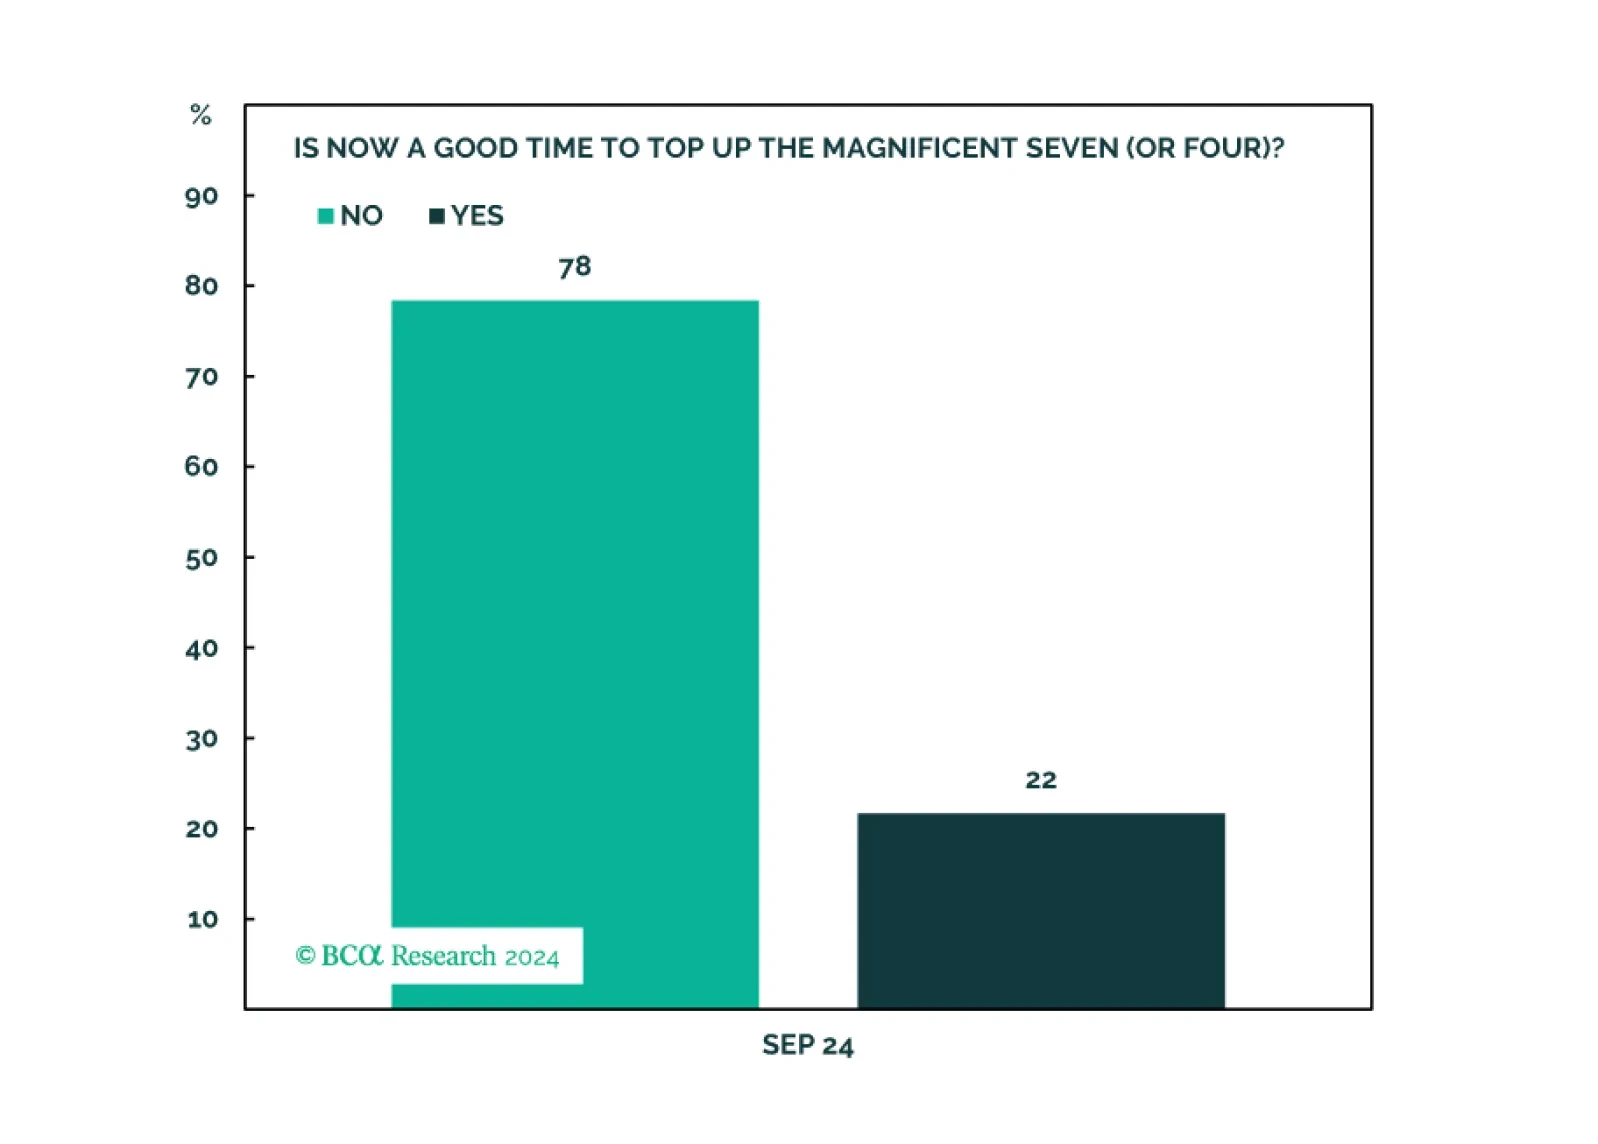
In this report, we follow up on the Roundtable that we hosted on September 11. We summarize the results of the client polls and answer a few questions on top of investors’ minds.