Fixed Income
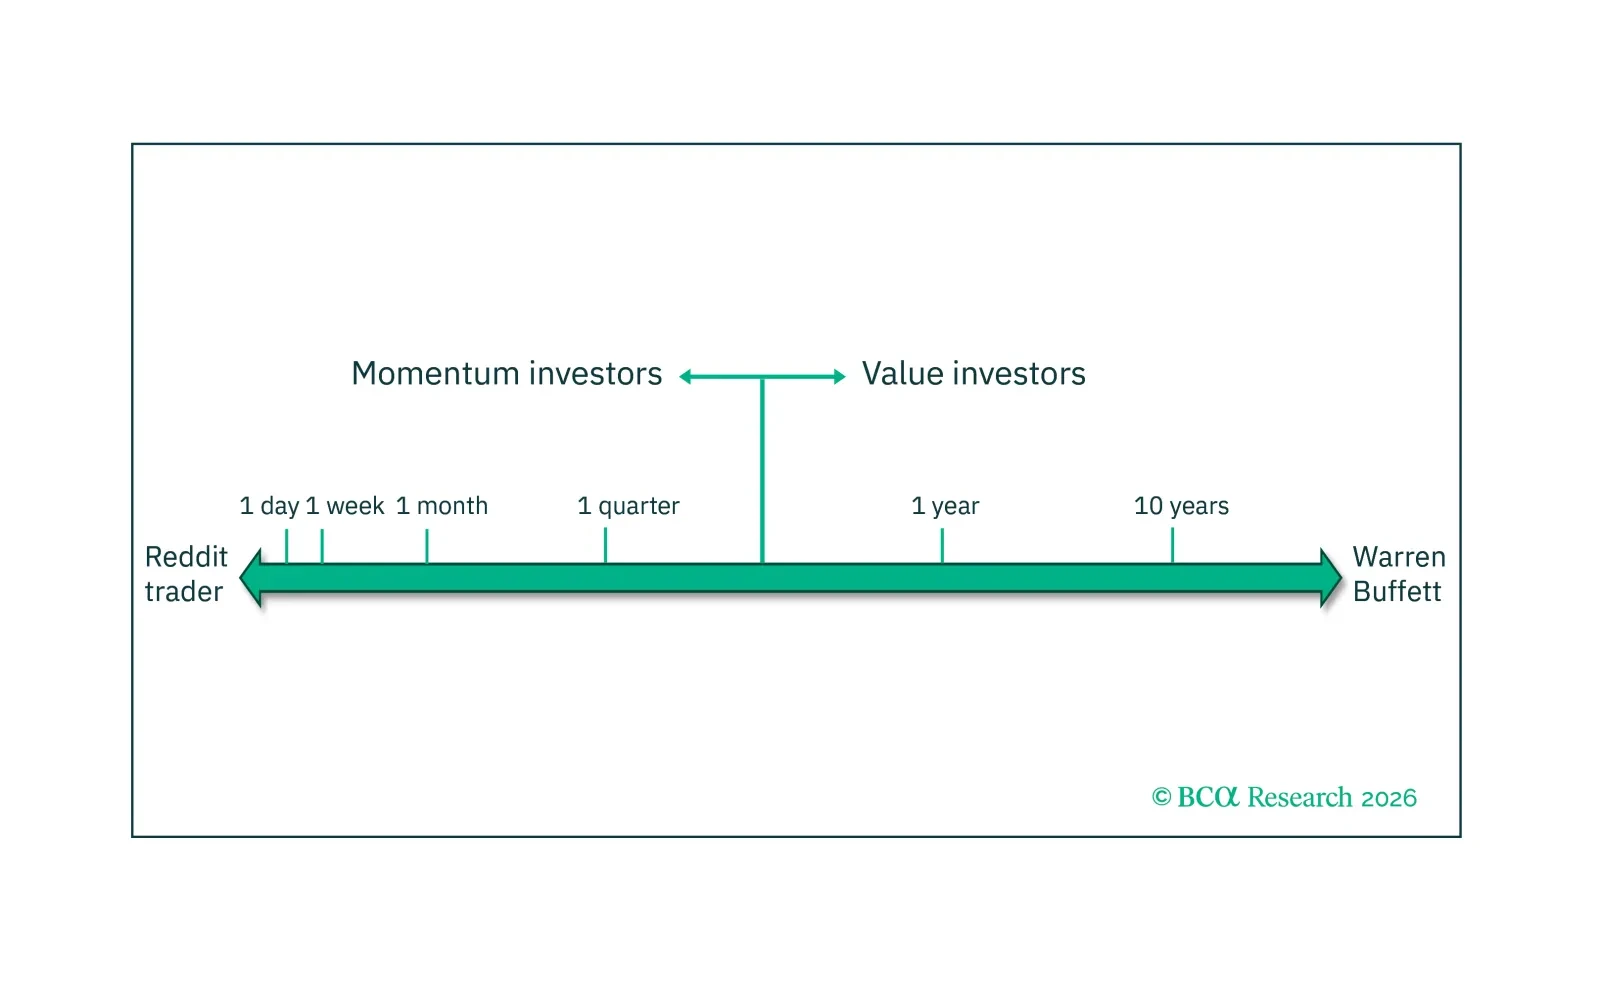
市場は「群衆の英知」が「群衆の狂気」に転じると、非効率で流動性が低く、相転移に脆弱になる。市場の英知から市場の狂気へのこの切り替わりは、アクティブ・ファンド運用における最も重要な繰り返し発生する行動に基づく投資機会であり、市場の複雑性を測定することでリアルタイムに活用できる。
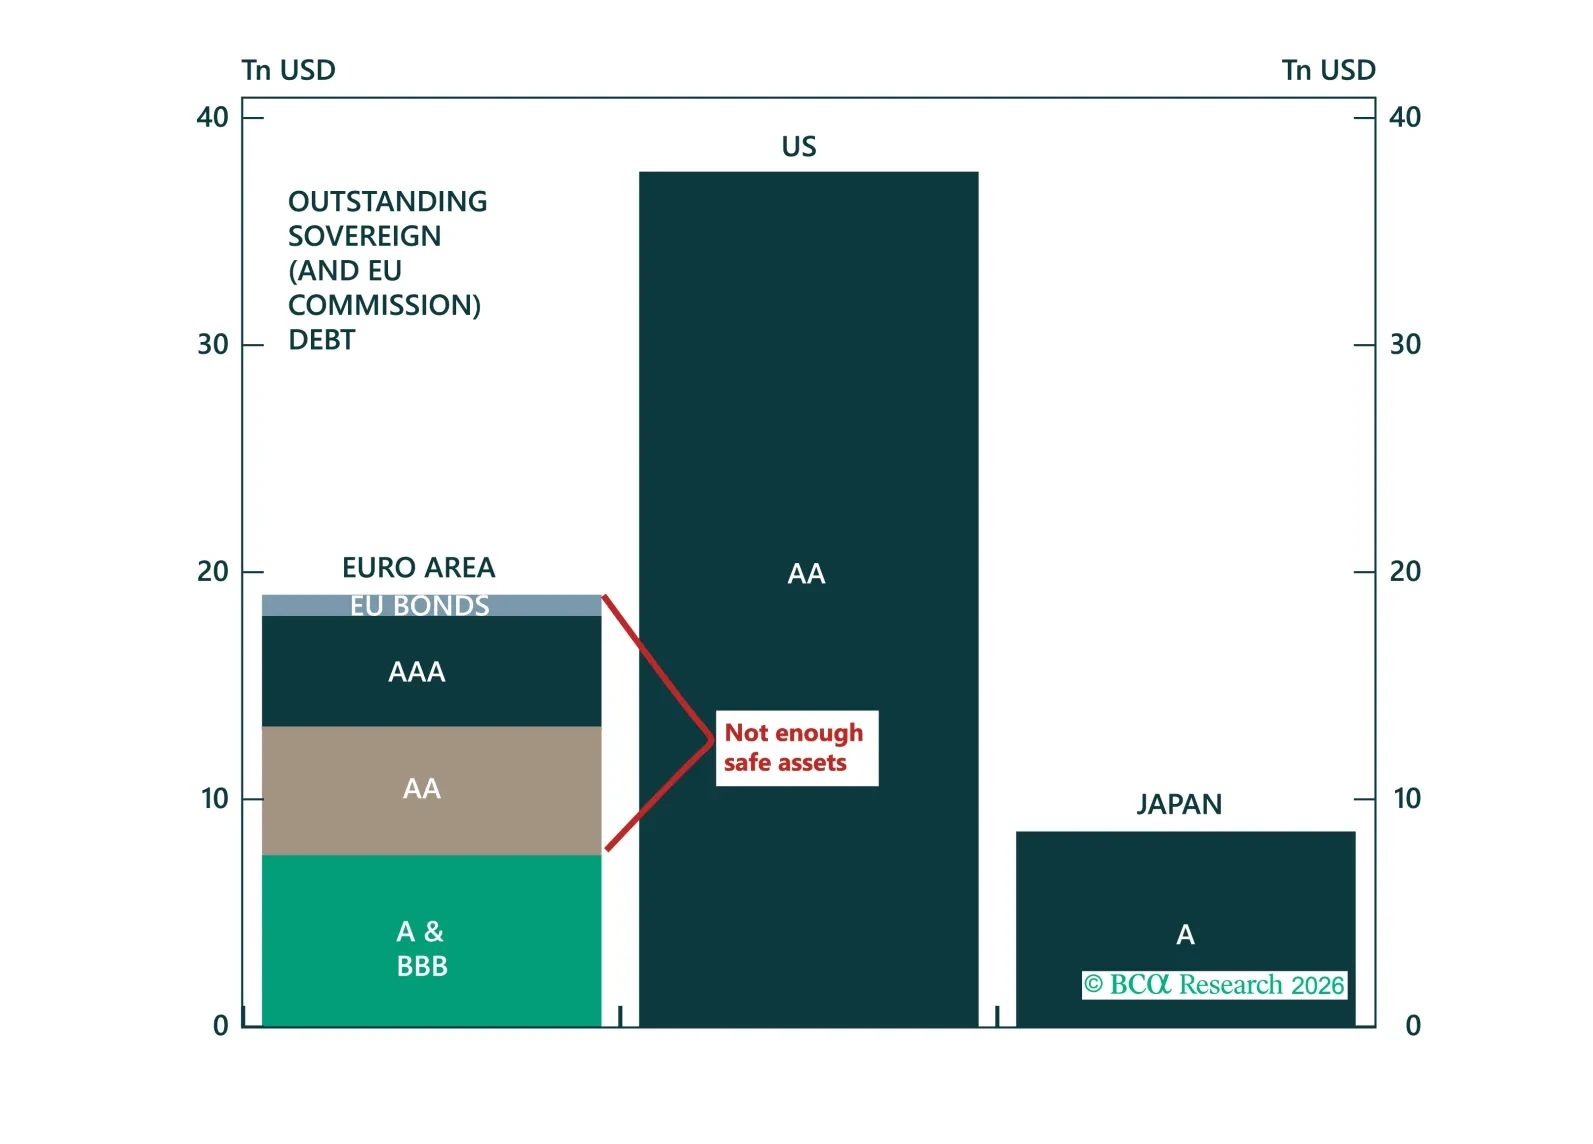
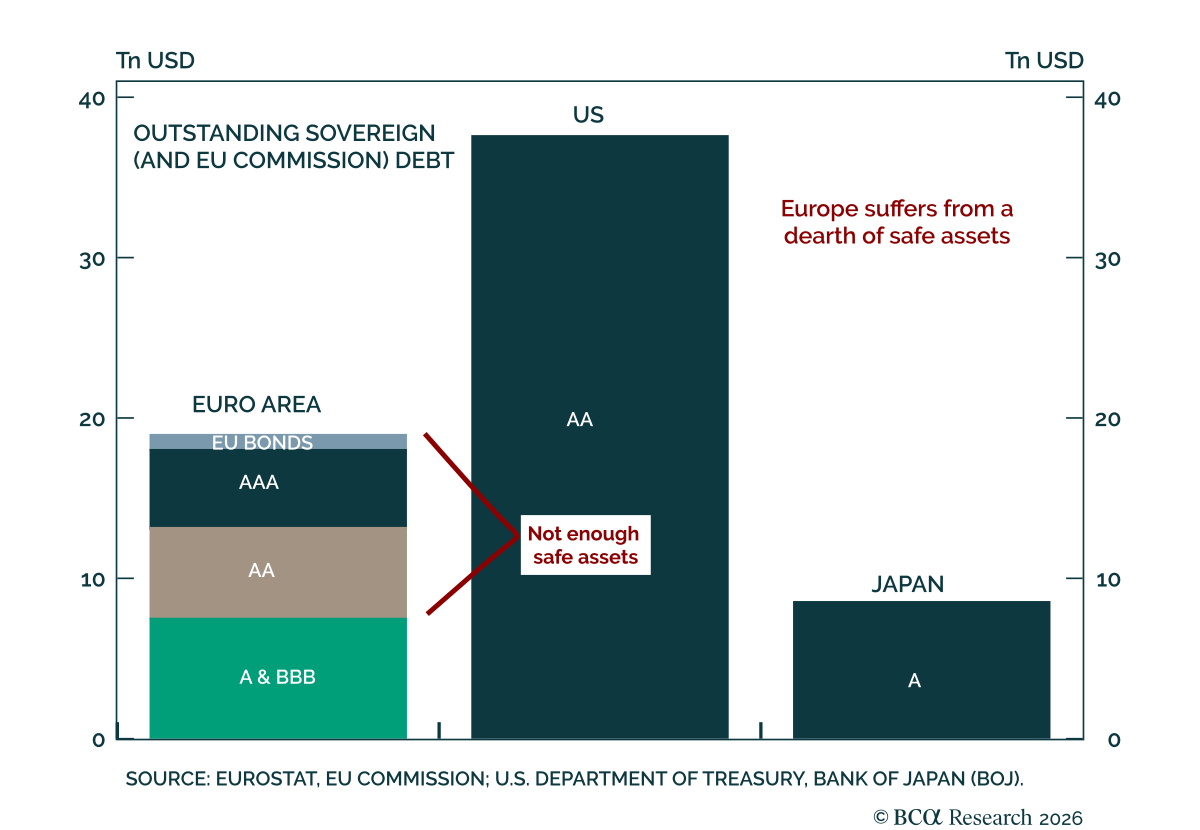
The dollar's retreat is creating the most compelling window for euro internationalisation since Maastricht, but Europe is missing the one instrument that would make it real. In this report, we make the case for the Eurobond, assess which model is most likely to prevail, and explain why the trade is long euro on dips and overweight Central and Eastern European sovereign spreads.
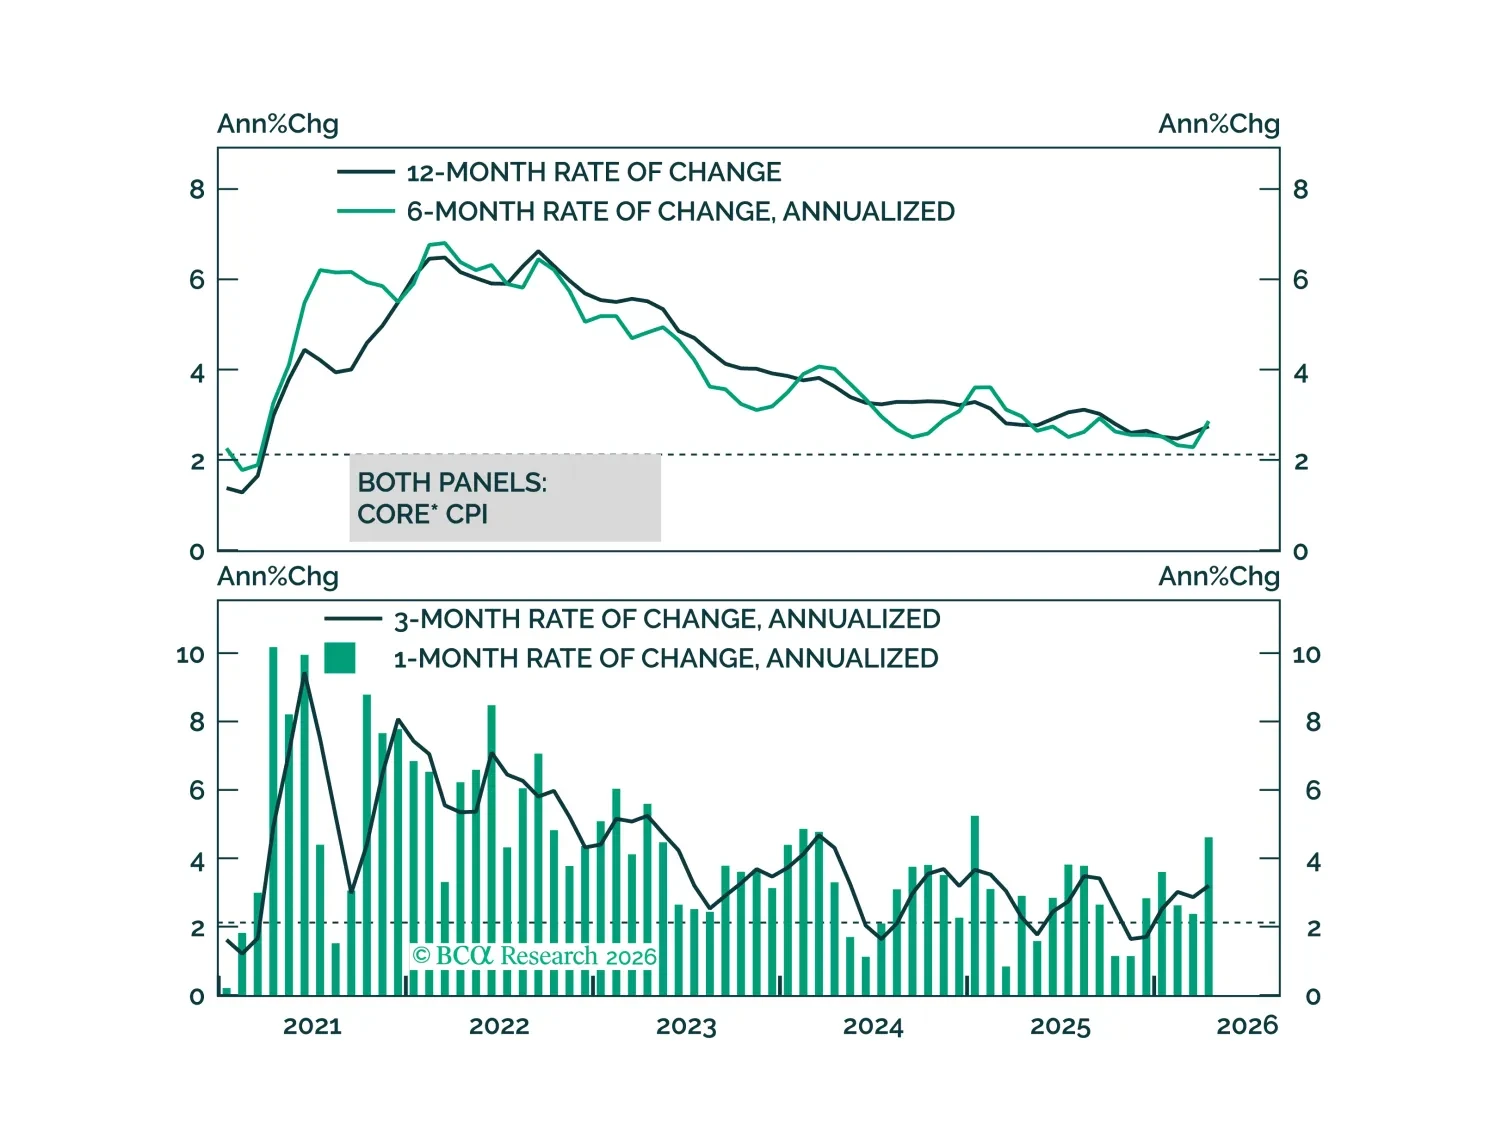
The April CPI report showed clear evidence of the direct effect of higher oil prices on inflation but, so far, limited evidence of passthrough to core.
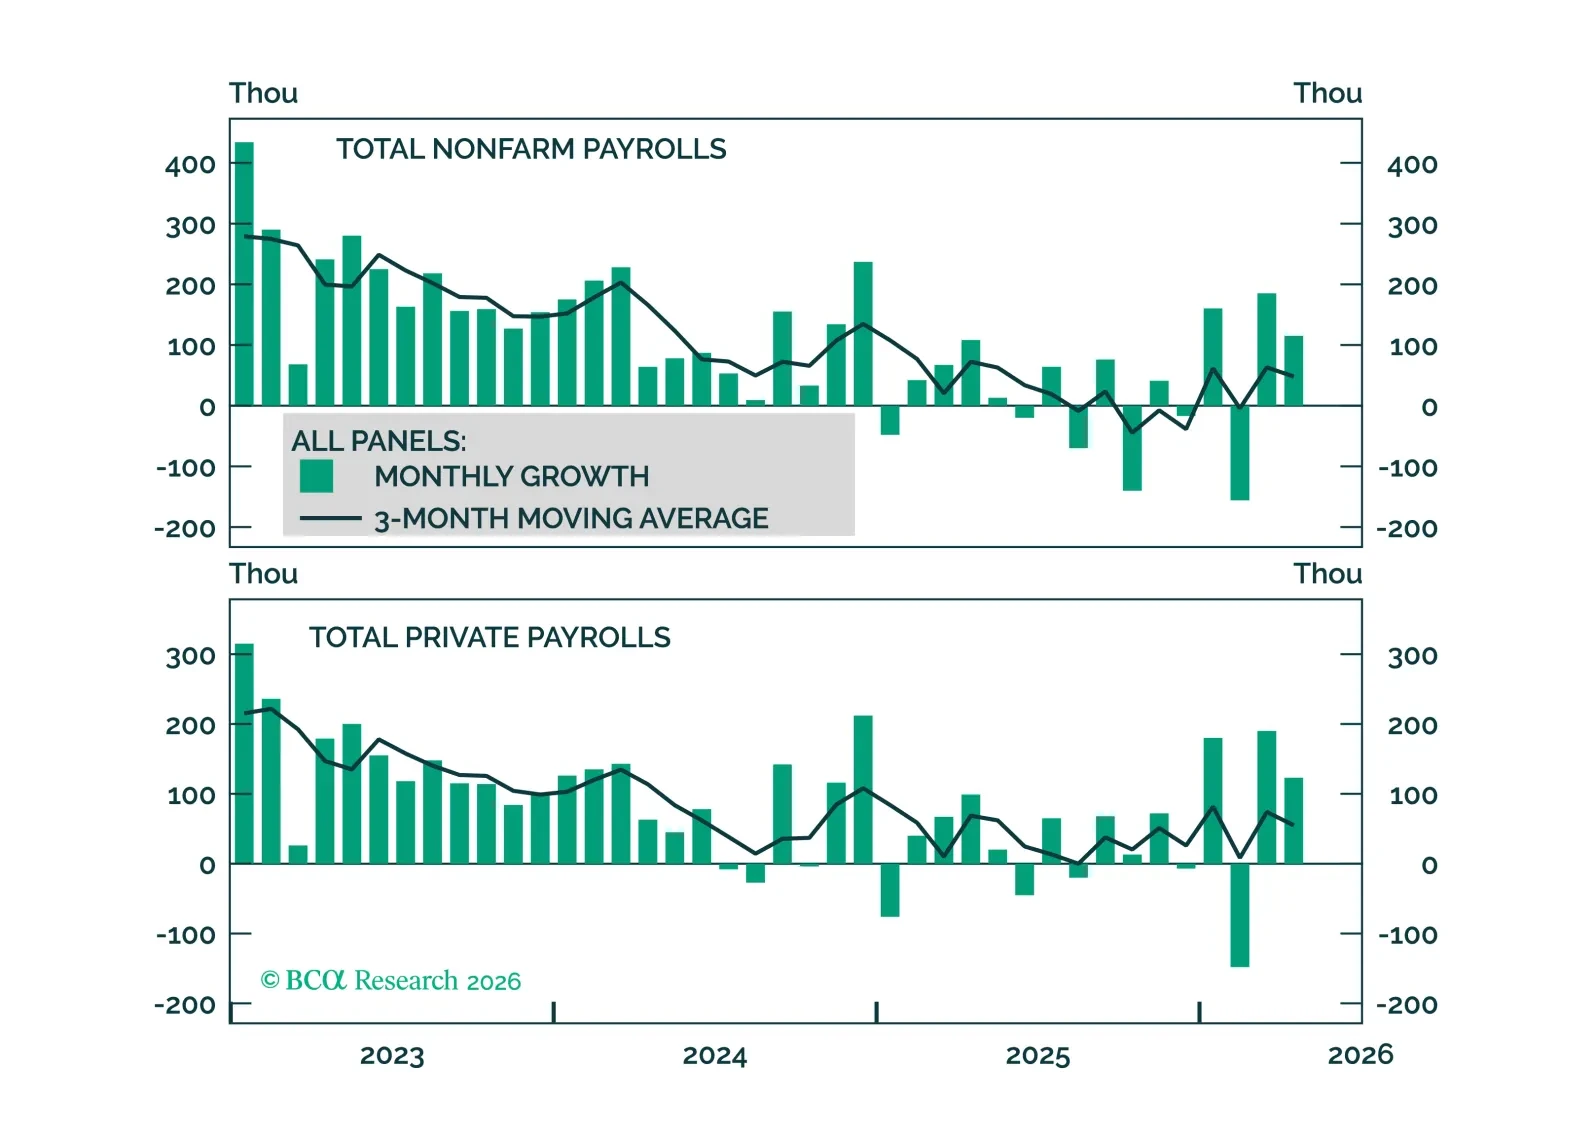
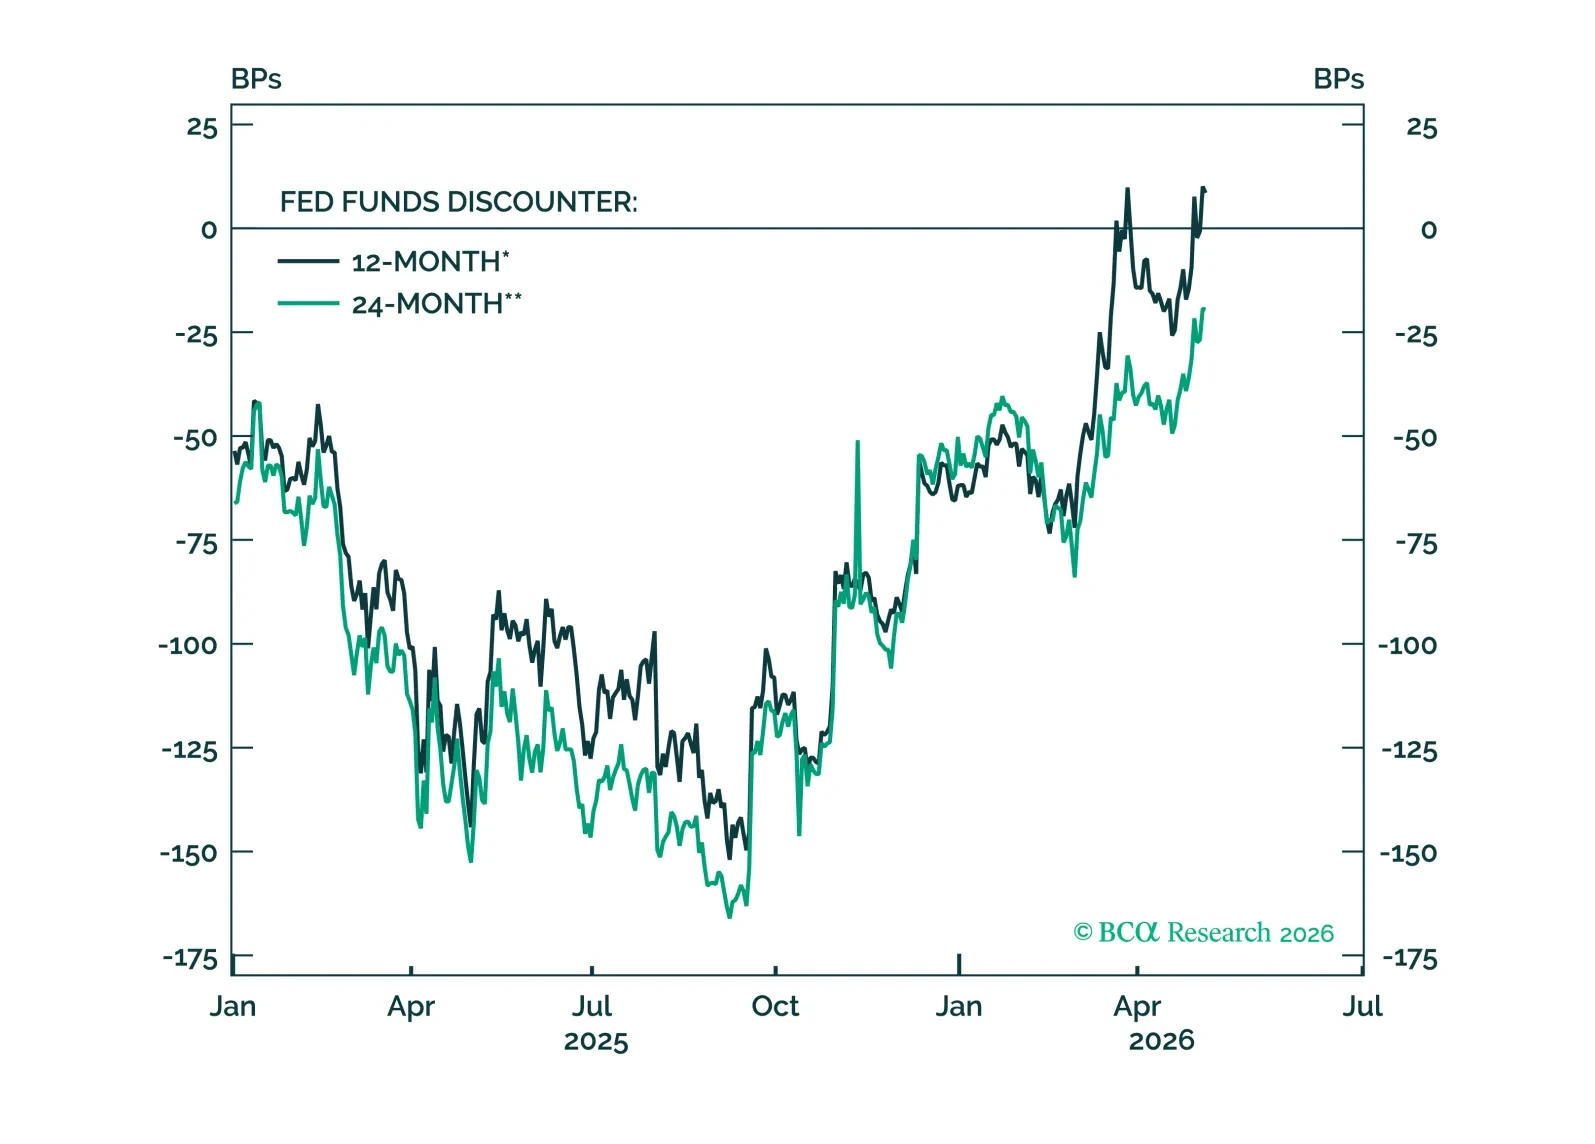
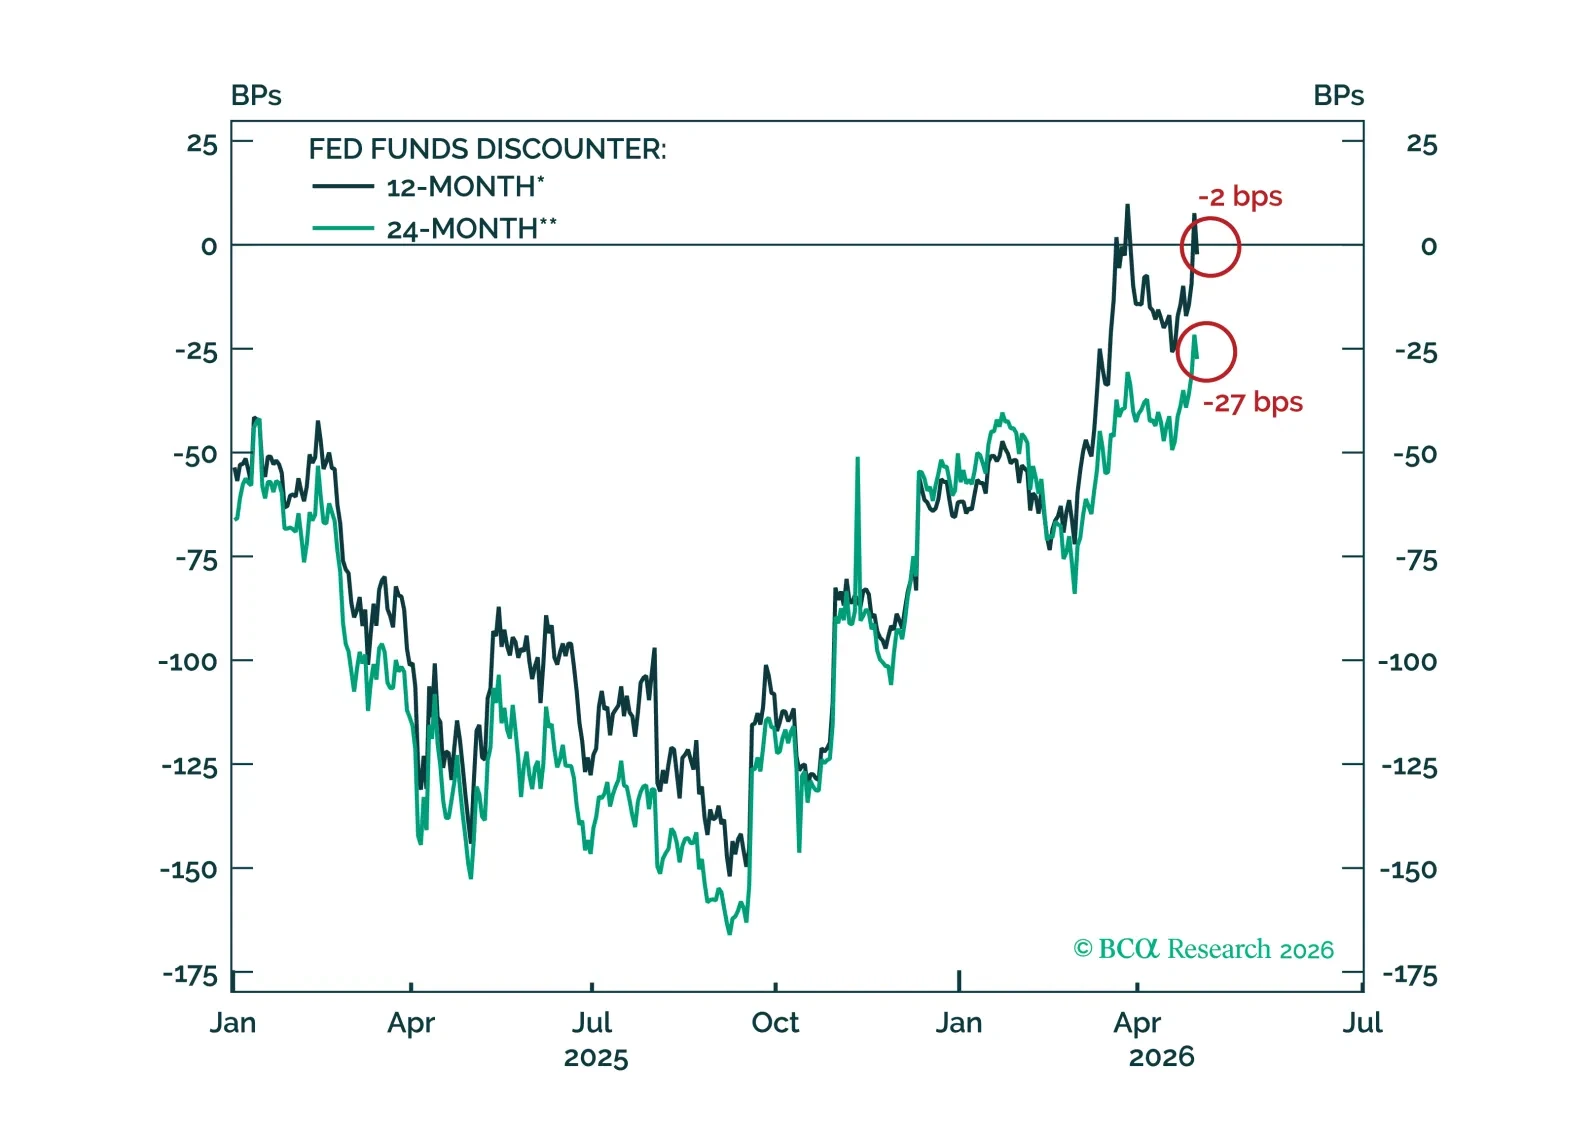
Improving job growth keeps Fed rate cuts off the table, but evidence of labor market tightening will be required before rate hikes become part of the discussion.

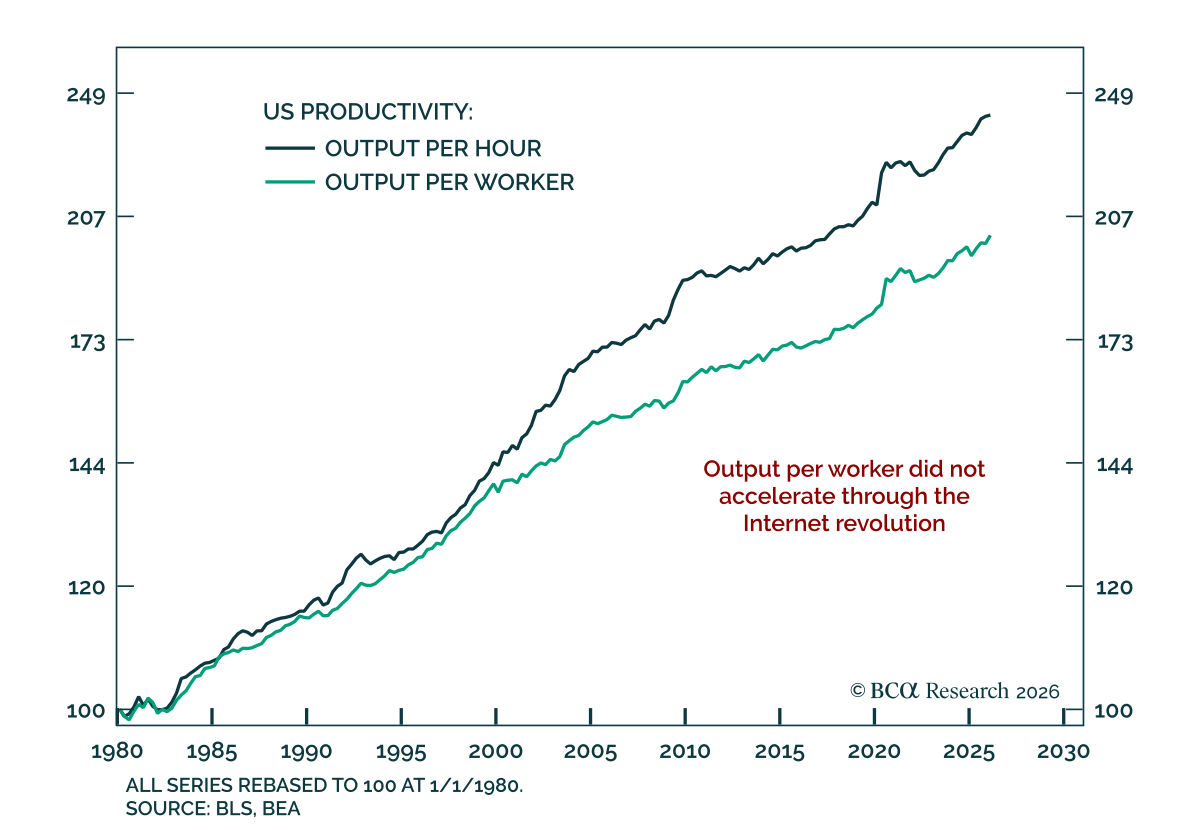
新任のFRB議長ケビン・ワーシュは、AI主導の生産性加速がFRBをインフレ率2%の目標を継続的に達成できなかったことの責任追及から救うと賭けている。しかし歴史は、新技術の普及は指数関数的に進む一方で、全体としての生産性成長はそうではないことを教えている。したがって、ワーシュの賭けが(その可能性は高いが)外れれば、米国のインフレの上振れは持続するだろう。投資への含意を論じる。さらに、新たなトレードはコットンのショートだ。