経済

Eurozone economic data sent a positive signal on Monday. Preliminary CPI releases from Germany and Spain show price pressures continue to moderate. In Germany, the harmonized index declined by 0.2% m/m while the annual rate of change eased from 4.3% y/y to…
China's industrial profits delivered a positive signal over the past couple months. Total profits expanded on a year-on-year basis in both August (+17.2% y/y) and September (+11.9% y/y). Rebounding industrial profits is typically a favorable development for…
In a recent Insight we highlighted that the S&P 500's year-to-date rally is narrow in breadth and that the equal weighted index has erased all its year-to-date gains. This is also true in the case of the Euro Area where the MSCI price index is still up by…
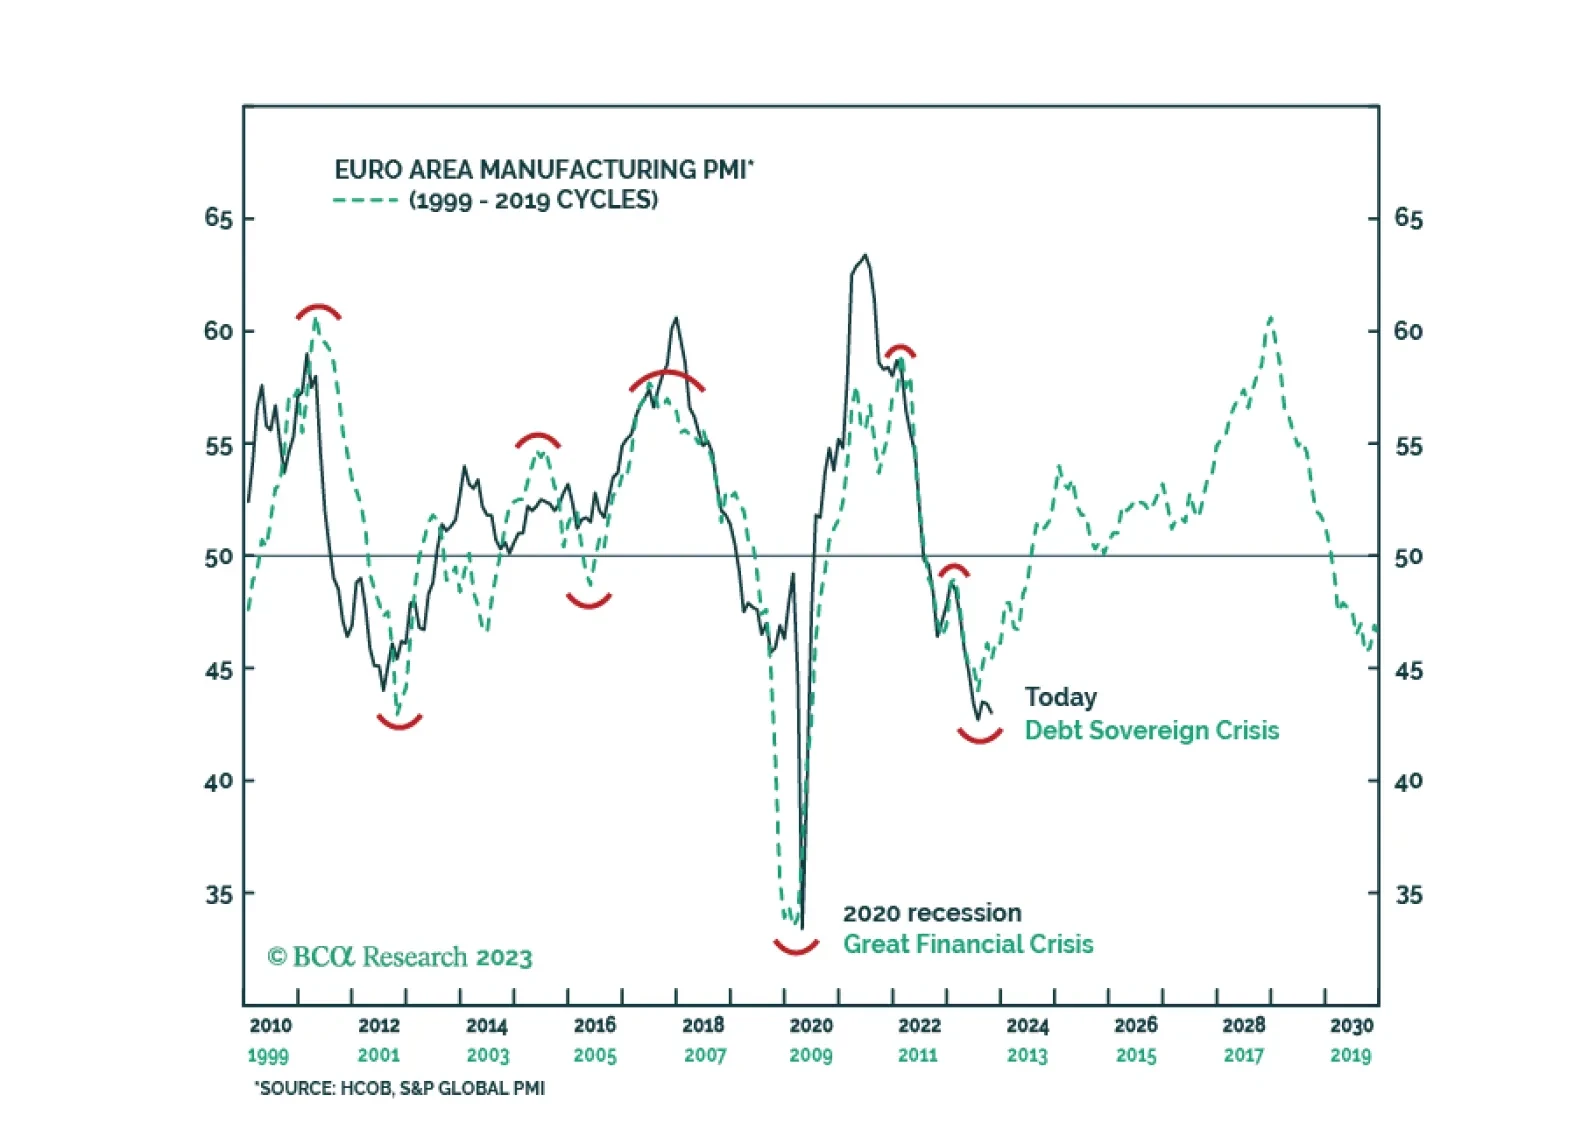
What will the next manufacturing cycle look like in Europe and how will risk assets perform? Lessons from the recent past.
The US PCE report confirmed the signal from Thursday's preliminary GDP release that consumer spending was resilient in Q3. Although personal income growth unexpectedly slowed, both nominal and real spending growth accelerated and beat expectations in…
Friday's Tokyo CPI release suggests that inflationary pressures are picking back up again in Japan. Headline inflation accelerated to 3.3% y/y – surprising expectations it would remain unchanged at 2.8% y/y. The ex-fresh food component also unexpectedly rose…
Recent US data reveals that consumer spending has been extremely robust in the US (see The Numbers). Personal consumption expanded by 4.0% q/q annualized in Q3, helping lift aggregate economic growth. Nevertheless, Consumer Discretionary is the second worst…
The US House of Representatives finally got a Speaker, but according to BCA Research’s US Political Strategy service, his voting record indicates that he will be a populist hardliner, which increases the chance that there will be a government shutdown.…
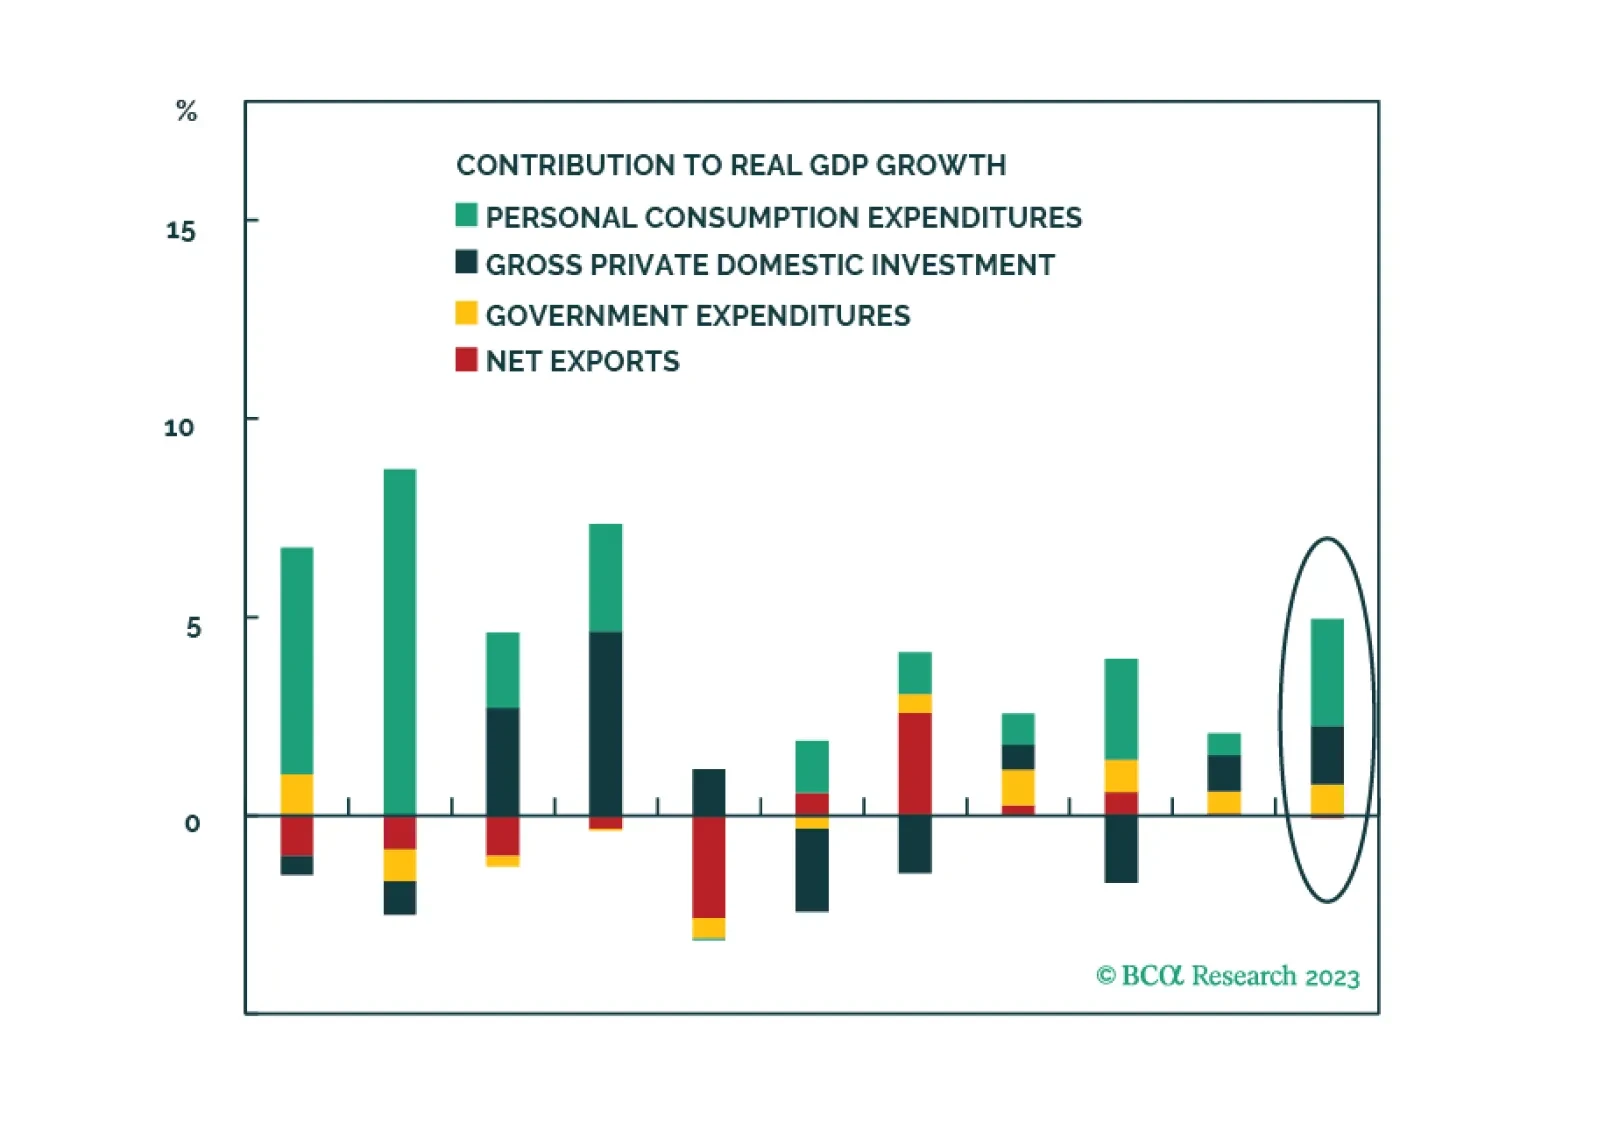
Stronger US growth elicits a response from the House Republicans. But a government shutdown is not devastating to the economy. What is more devastating would be a crisis in the Middle East, Europe, and Asia. Stay long US defense, energy, and large caps stocks.
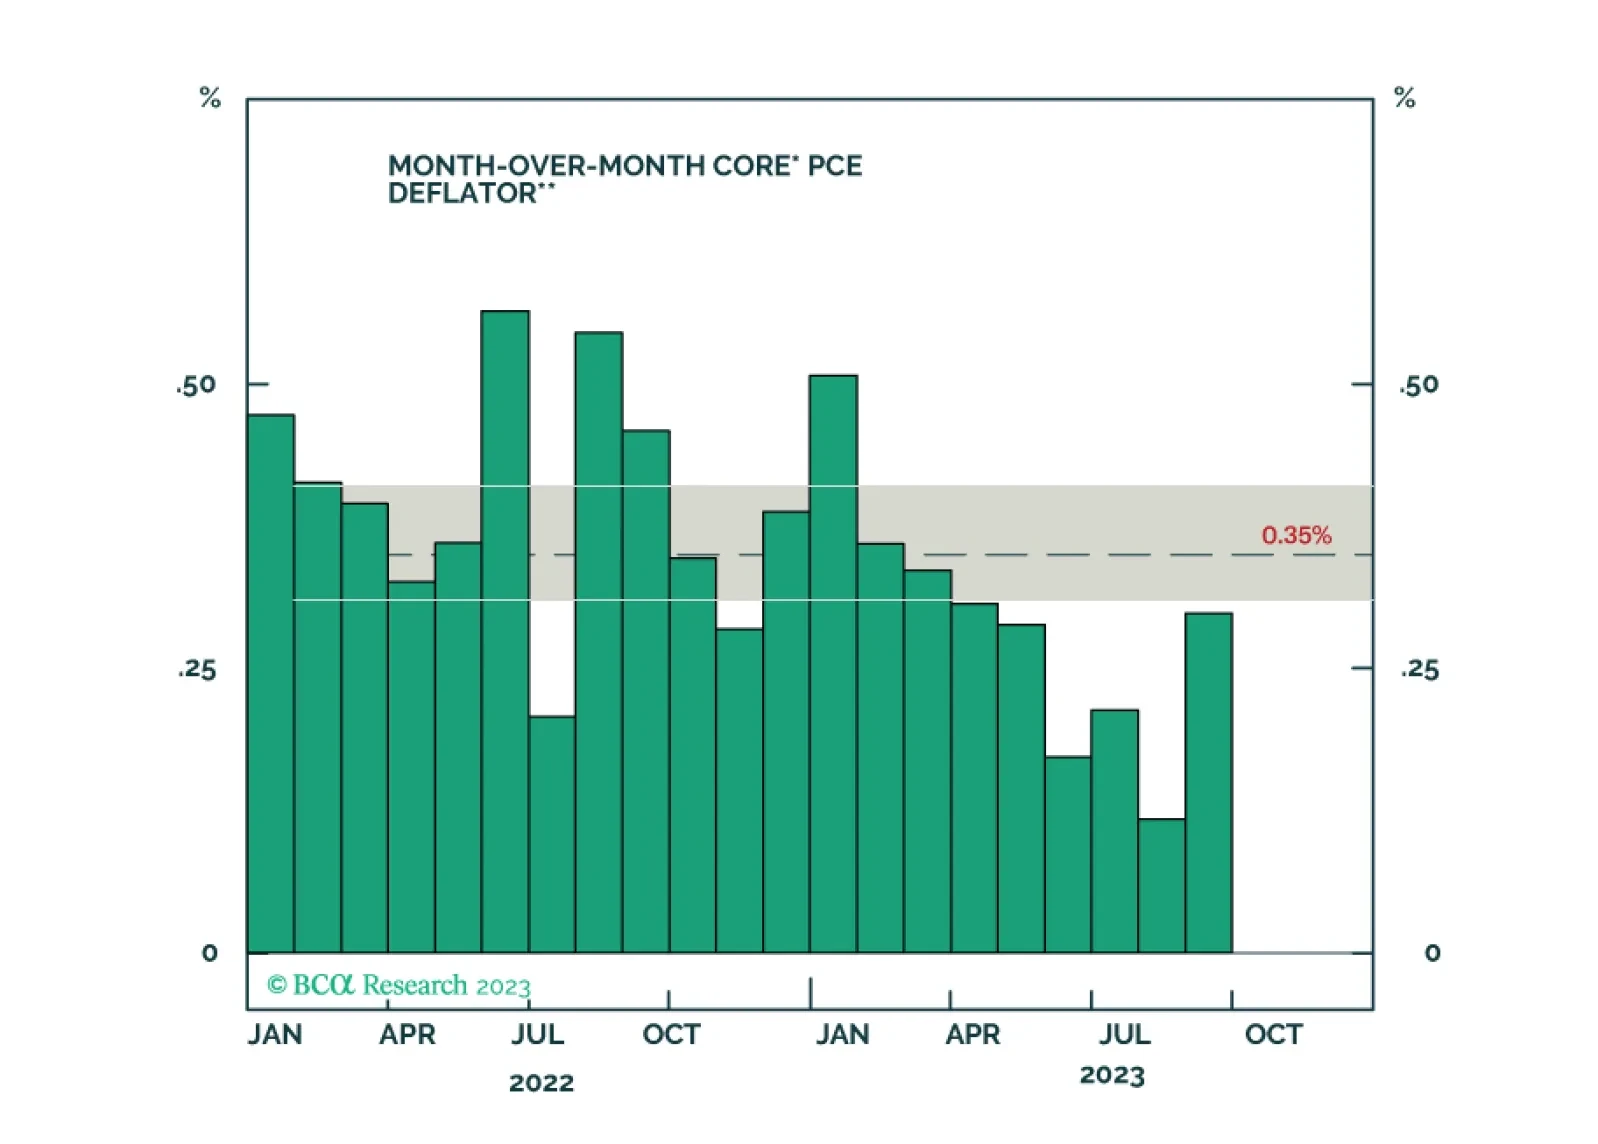
A look at recent data on economic growth, inflation and the labor market, and a discussion of the implications for Fed policy and bond strategy.