ポリシー

今週、当社のセントラル・バンク・モニターズ(CBMs)を更新しました。これらは先進国経済における金融政策をどのように調整すべきかを見極めるのに役立ちます。結論としては、全体としてより緩和的な金融政策が求められるものの、G10諸国間のシグナルの乖離から生じるいくつかのトレード・アイデアがあります。
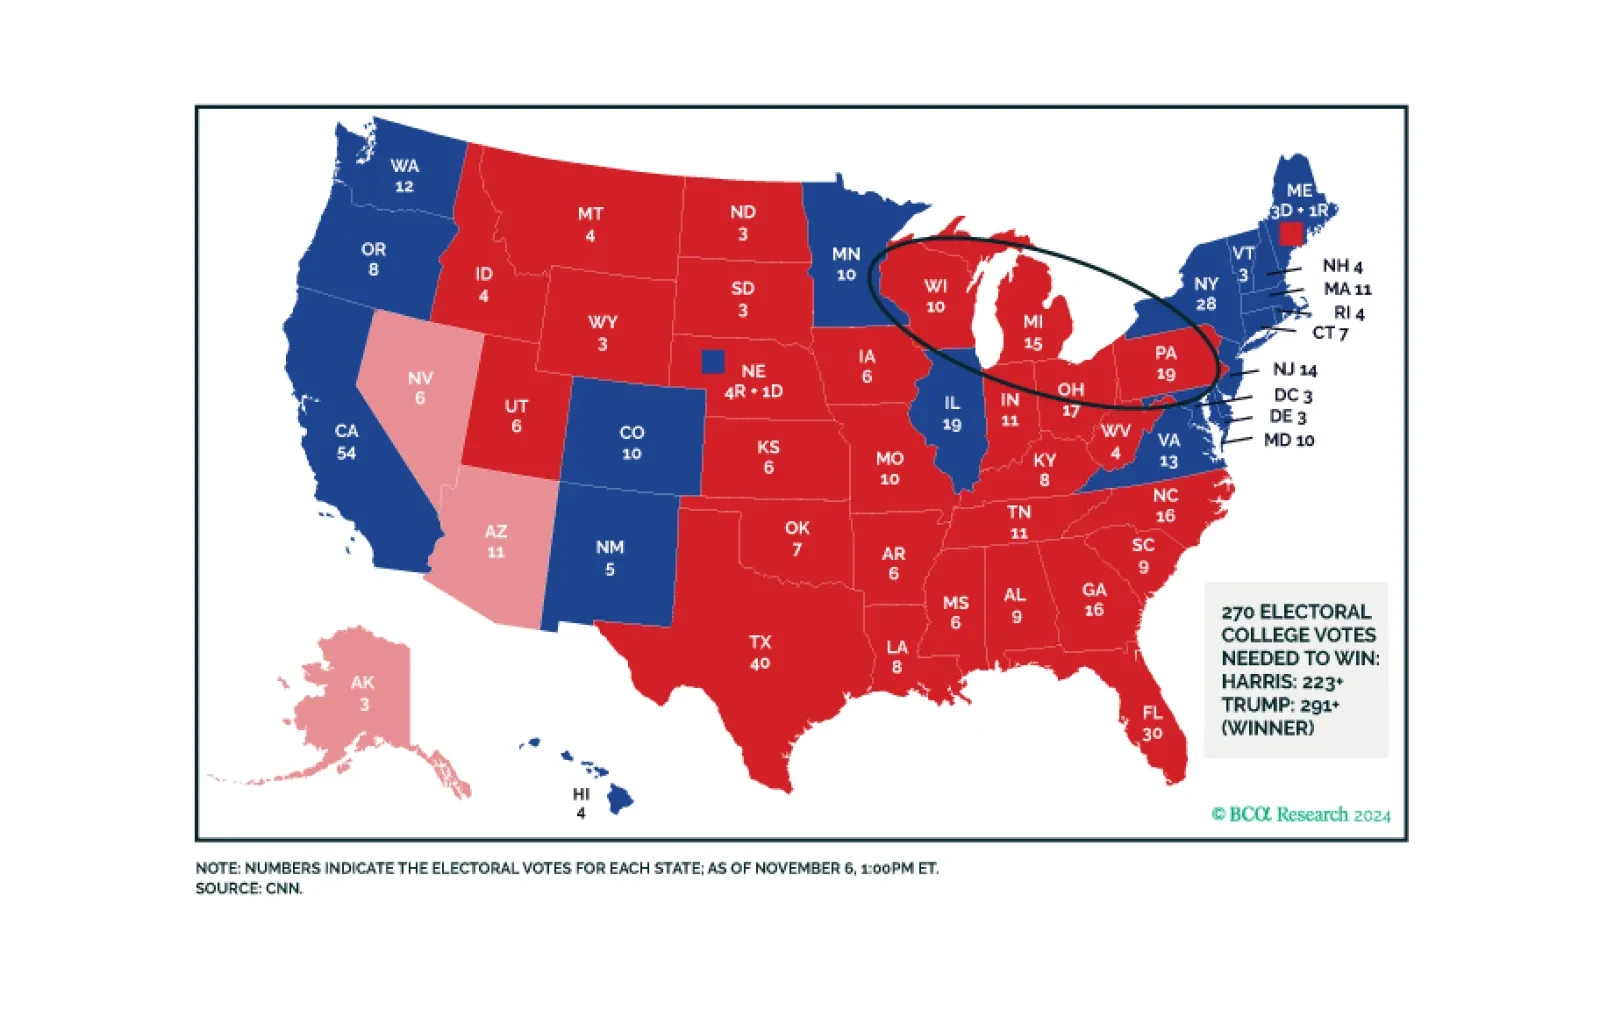
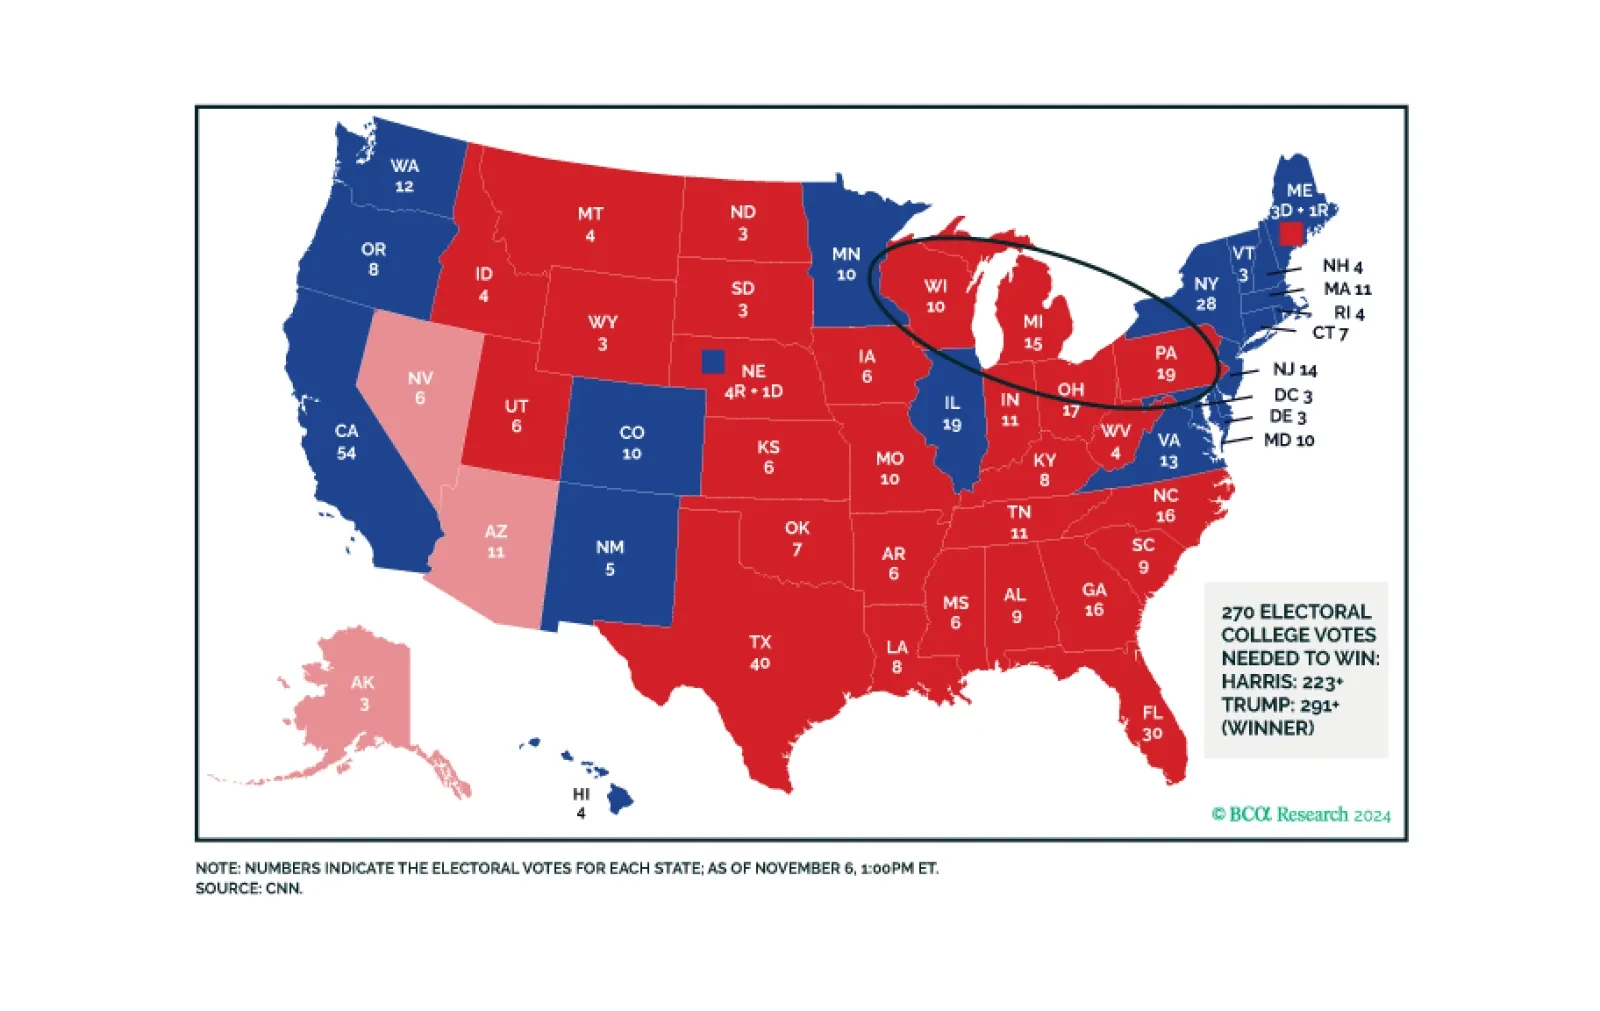
トランプの圧勝は規制緩和と貿易関税の引き上げを確実にする民意の支持をもたらす。財政赤字の拡大や移民改革も見込まれ、共和党は下院でかろうじて僅差を確保するかもしれない。外交はより一方的になり、当初は米国資産が上回るだろう。

The US dollar steamrolled its peers since early October. After breaking out above its 200-day moving average, it is now fast approaching recent highs. Multiple factors drove this rally, among them are the stronger-than-expected US economic data, weaker data…
The preliminary November University of Michigan Consumer Sentiment Index beat expectations, rising to 73 from 70.5 a month prior. Expectations drove the increase, jumping to 78.5 from 74.1, while current conditions worsened by 0.5 points to 64.4, missing…
Our China Investment Strategy team recently met with clients in China to assess investor sentiment and discuss the outlook as Beijing unveils new stimulus measures. China’s economic recovery faces headwinds and is unlikely to stabilize until mid-2025.…
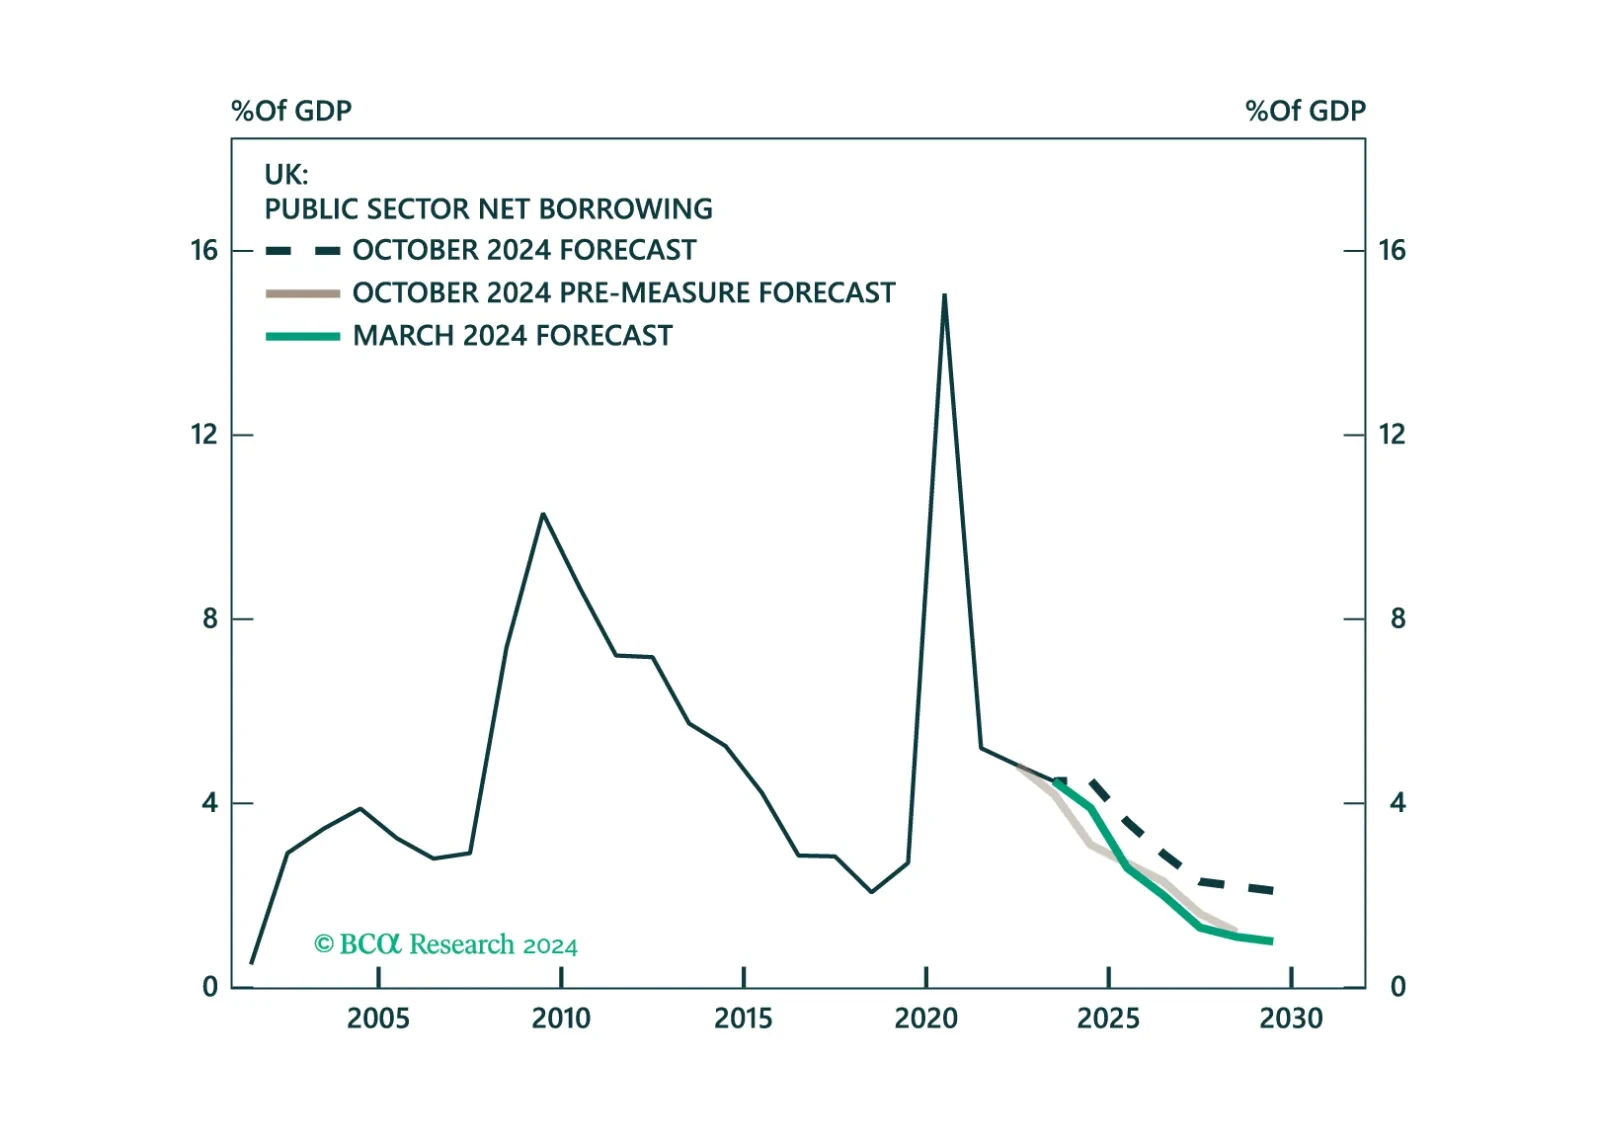
本ストラテジー・インサイトは、イングランド銀行の本日の利下げおよび先週英国政府が発表した予算案に関する当社の見解を示します。
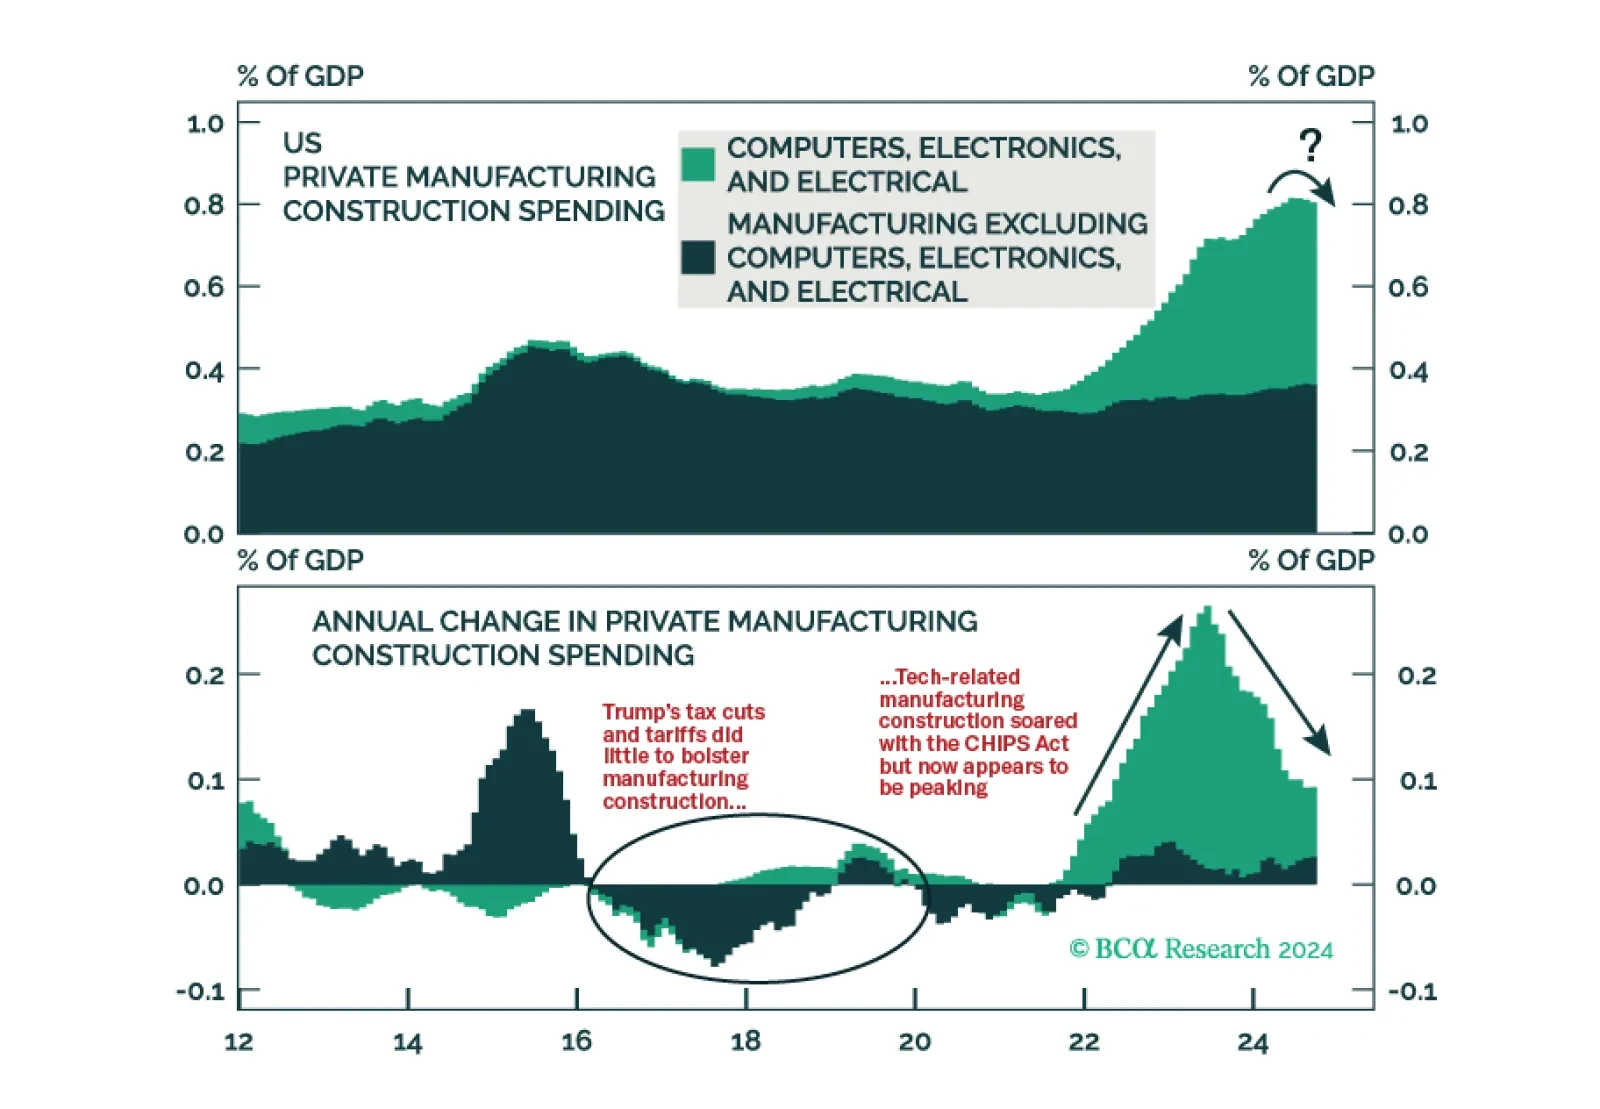
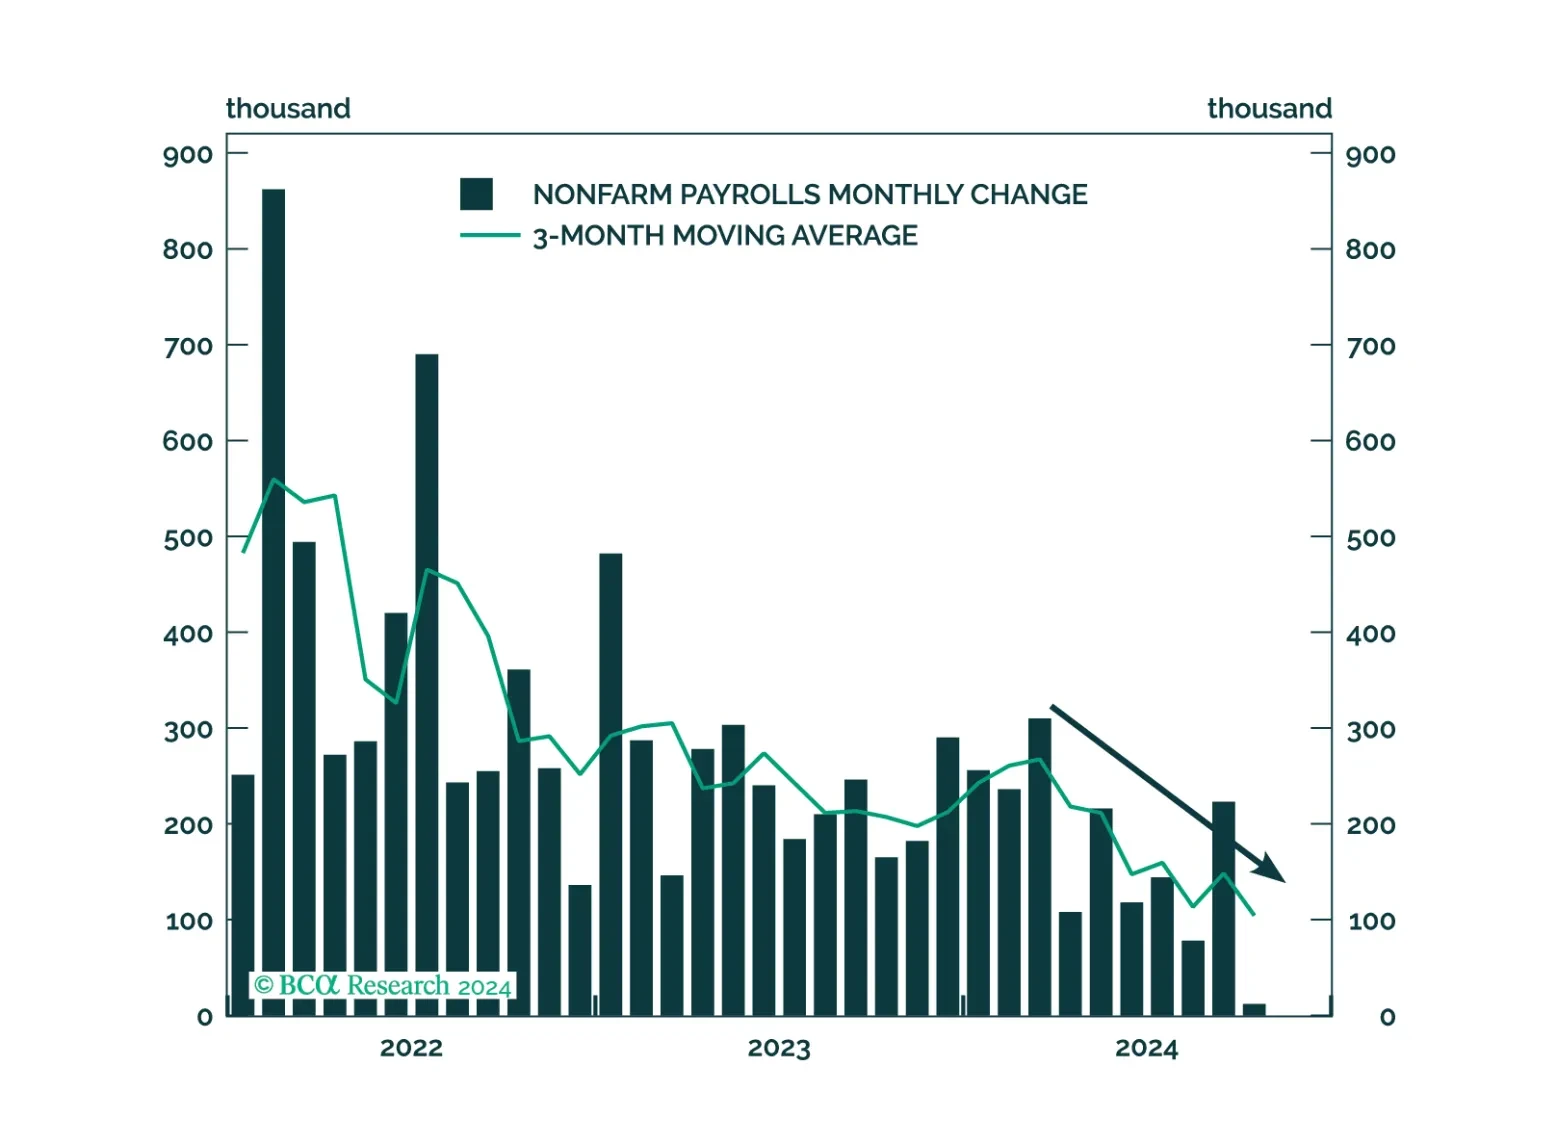
新たな貿易戦争の見通しは、トランプの政策の他の親企業的な側面の効果をそれ以上に相殺します。選挙に向けて労働市場がすでに弱まっていることから、当社は今後12か月の米国景気後退確率を65%から75%に引き上げます。
