Fixed Income

Our 2025 Outlook was just published. We revisit this year’s calls and discuss what we think is ahead for the global economy and markets for the next 12 months and beyond. The recent US election has significantly shifted our economic and market outlook. A…
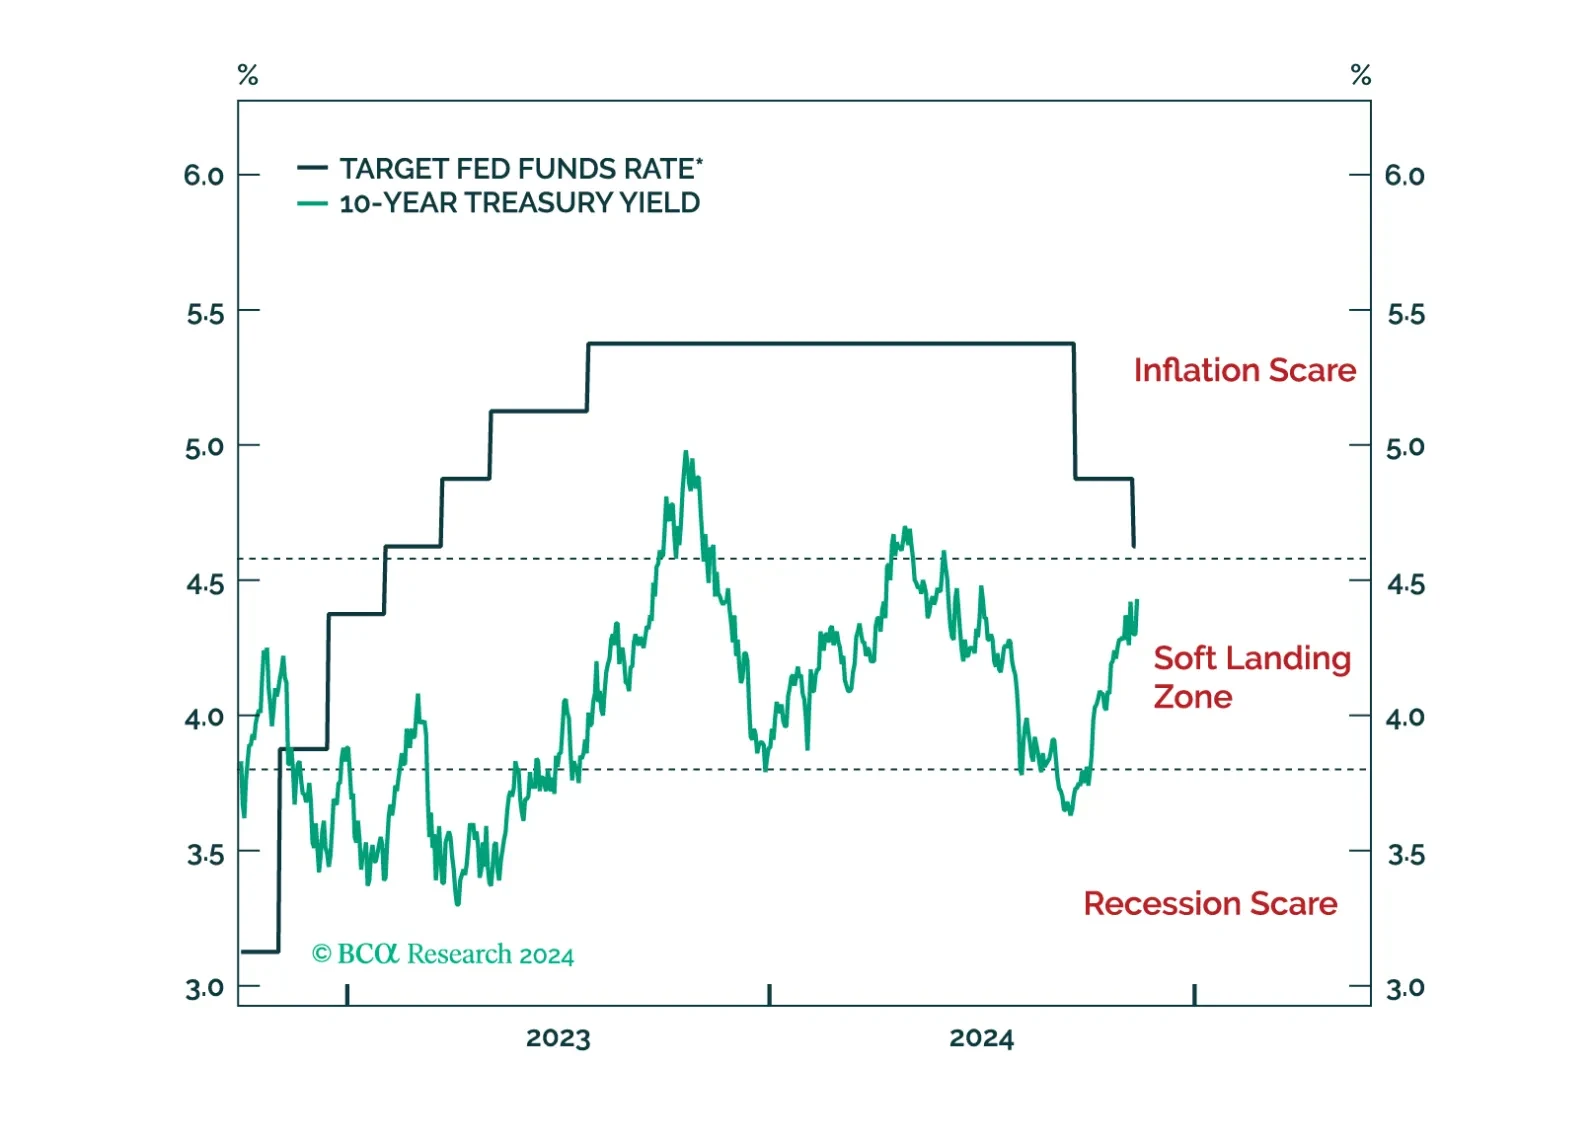
Our US bond strategists expect yields to remain volatile, and do not have confidence that yields have peaked yet. The transition period to a new US administration introduces headline risks on where fiscal policy is headed. At about 4.4%, the 10-year Treasury…
Our Global Asset Allocation team analyzed the performance and allocation strategies of 79 US public pension funds, providing insights across governance, scale, and liquidity. Strategic Asset Allocation (SAA) is the most significant driver of fund performance,…
Chinese activity indicators showed resilience in October, with retail sales jumping from 3.2% to 4.8% y/y. Industrial production growth was roughly unchanged at 5.3% y/y. New and used home prices keep falling, albeit at a slower pace. We would fade this…
According to the latest update of the Central Bank Monitors from BCA’s Global Fixed Income strategists, economic weakness and diminishing inflation pressures warrant a shift towards easier global monetary conditions. The most hawkish signals come from the UK,…
US CPI inflation for October printed in line with expectations and was unchanged from September, with headline at 0.2% month-over-month and core at 0.3%. Headline re-accelerated to 2.6% from 2.4% on an annual basis, and core stayed steady at 3.3%. This report…

Resumen de la asignación de nuestra cartera para noviembre de 2024.

Esta semana actualizamos nuestros Monitores de Bancos Centrales (CBMs), que nos ayudan a calibrar cómo debe ajustarse la política monetaria en las economías de mercados desarrollados. Nuestra conclusión es que, si bien en términos generales se requieren condiciones monetarias más acomodaticias, surgen algunas ideas de trading a partir de las divergencias en las señales entre los países del G10.
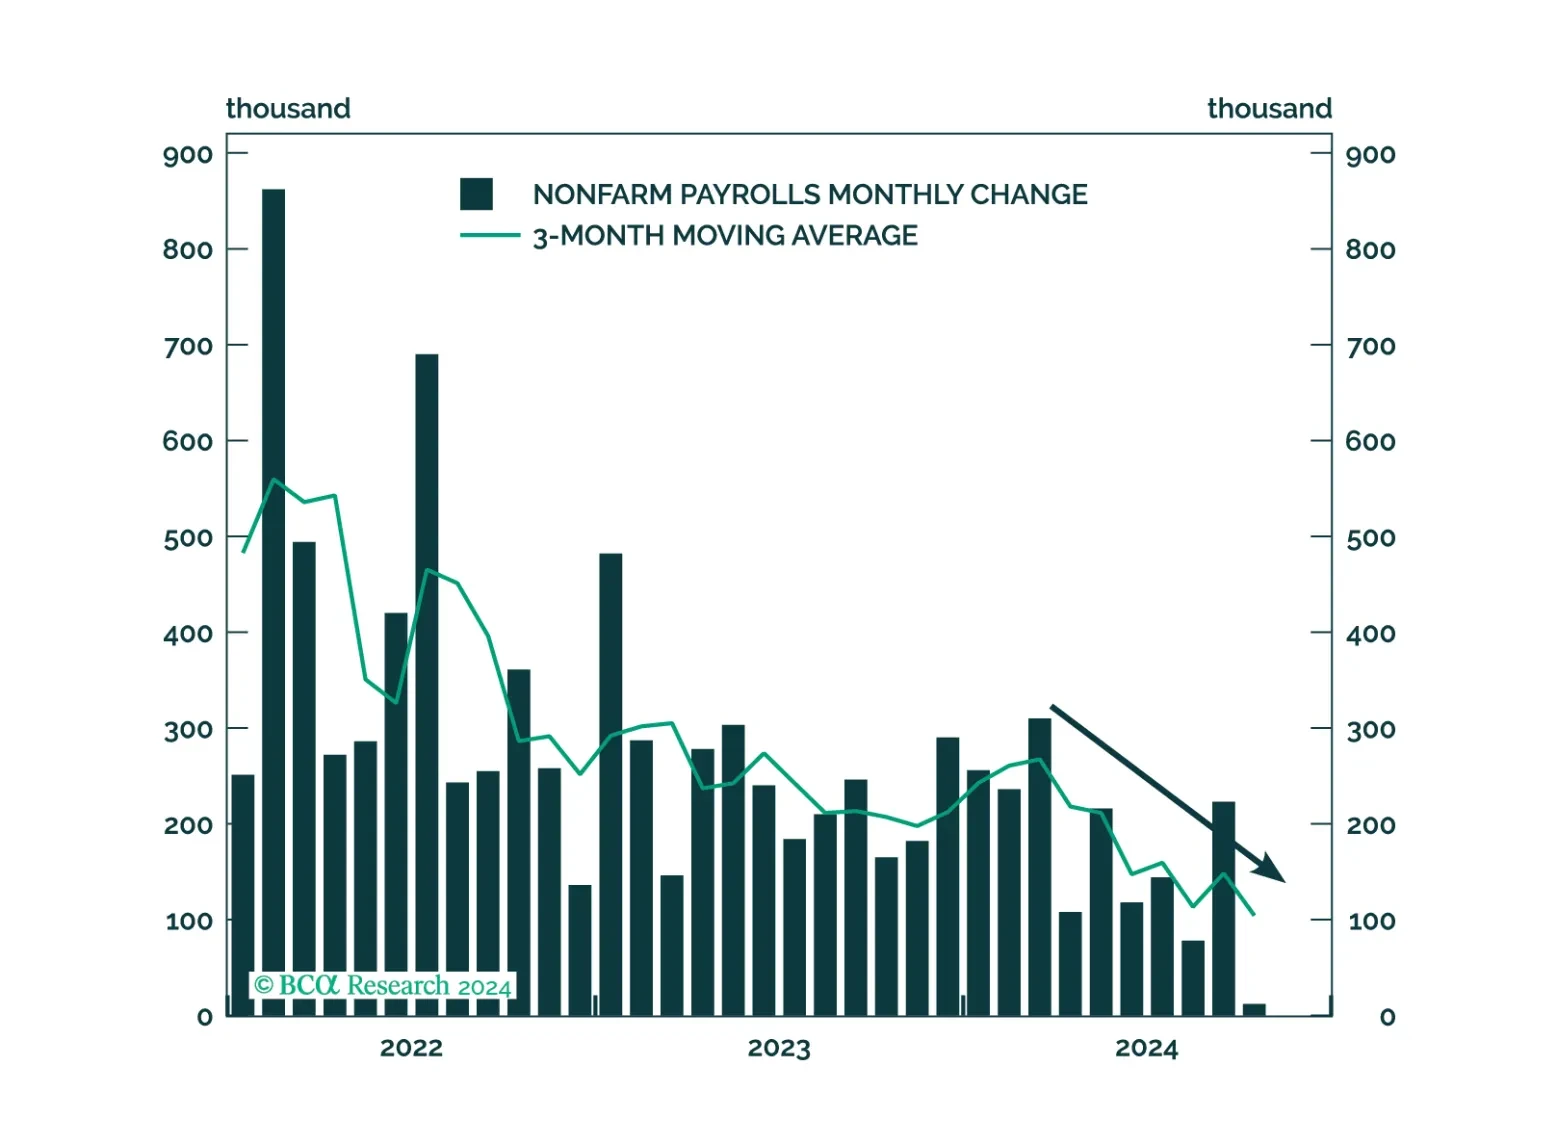
El impulso postelectoral nos lleva a creer que podríamos vernos obligados a salir de nuestra posición defensiva antes de que termine la semana, pero seguimos creyendo en nuestro pronóstico de recesión. Si finalmente somos obligados a salir, buscaremos un punto de entrada más oportuno para apostar contra los activos de riesgo una vez que la fiebre electoral haya pasado.