Saltar al contenido principal

Estados Unidos

According to BCA Research’s Emerging Markets Strategy Service, China has been accumulating high-value memory semiconductors in anticipation of further US restrictions. Since October 2022, the US has been tightening rules that would limit China’s progress in…
US job openings declined from a downwardly revised 7.91 million to 7.67 million in July, the lowest level since 2021 and well short of expectations of 8.1 million. The downward revision indicates that labor demand actually declined in June, when it was…
The Q2 2024 earnings season is drawing to a close with 93% of S&P 500 companies having reported results as we go to press. Nearly 80% (60%) of companies have topped earnings (sales) expectations in Q2, according to Factset. Excluding Materials and Real Estate…
According to BCA Research’s GeoMacro Strategy service, there are two main pressure points that the US can utilize against China. First, the US consumer market is the largest in the world. Despite having diversified away from the US, it remains a very…
The ISM manufacturing PMI improved in August, from 46.8 to 47.2, but remained below expectations of 47.5 and extended a five-month contraction streak. Production declined at a faster pace (45.9 to 44.8) and both new orders and new export orders contracted…
The 2Y/10Y segment of the yield curve is flirting with un-inversion. Aggressive rate cut expectations have largely driven its steepening, with the 2-year Treasury yields falling nearly 100 bps over the past couple of months. Our colleagues at the Bank Credit…
Significantly stronger-than-expected consumer spending growth led to an upward revision to US GDP growth in Q2. That said, gross domestic income (GDI) has been lagging behind GDP. It increased 1.3% q/q in Q2, at the same rate as in Q1, and well below Q2’s…

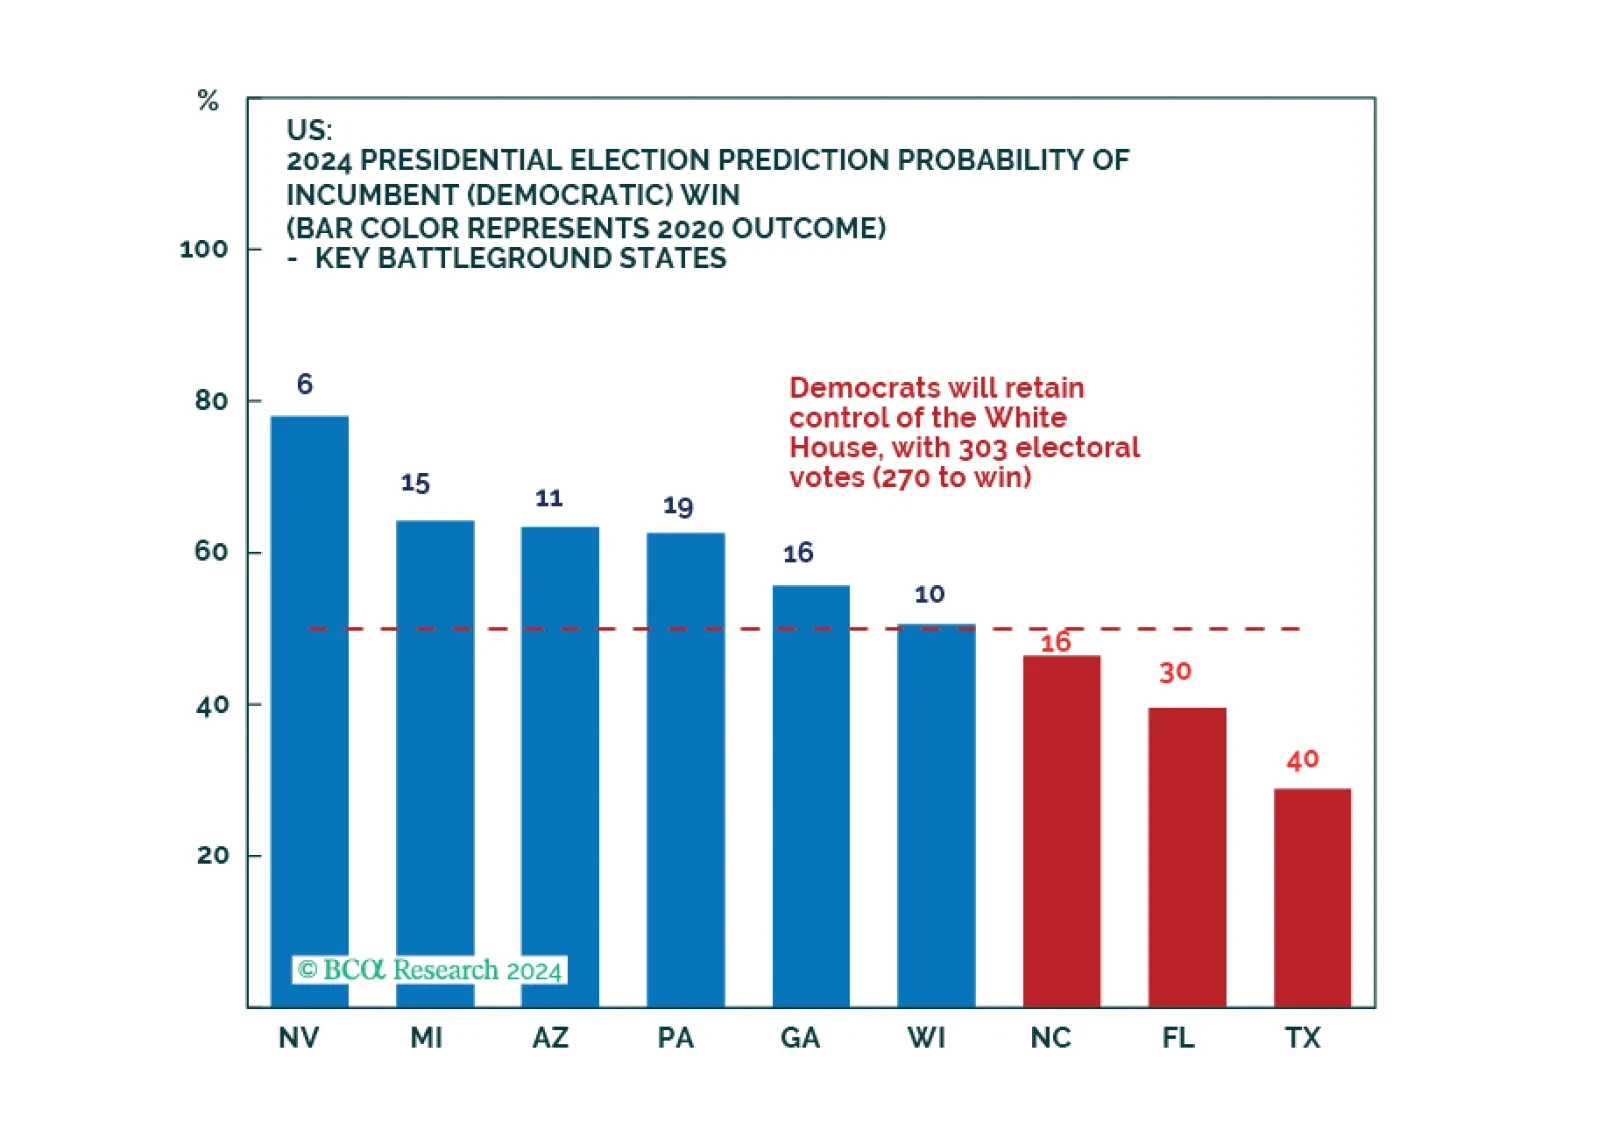
Democrats will not win a full sweep and implement drastic new tax hikes. However, our quant model still favors them to win the White House and just upgraded their odds. While we expect equity volatility around the election, investors do not need to worry about corporate tax hikes.
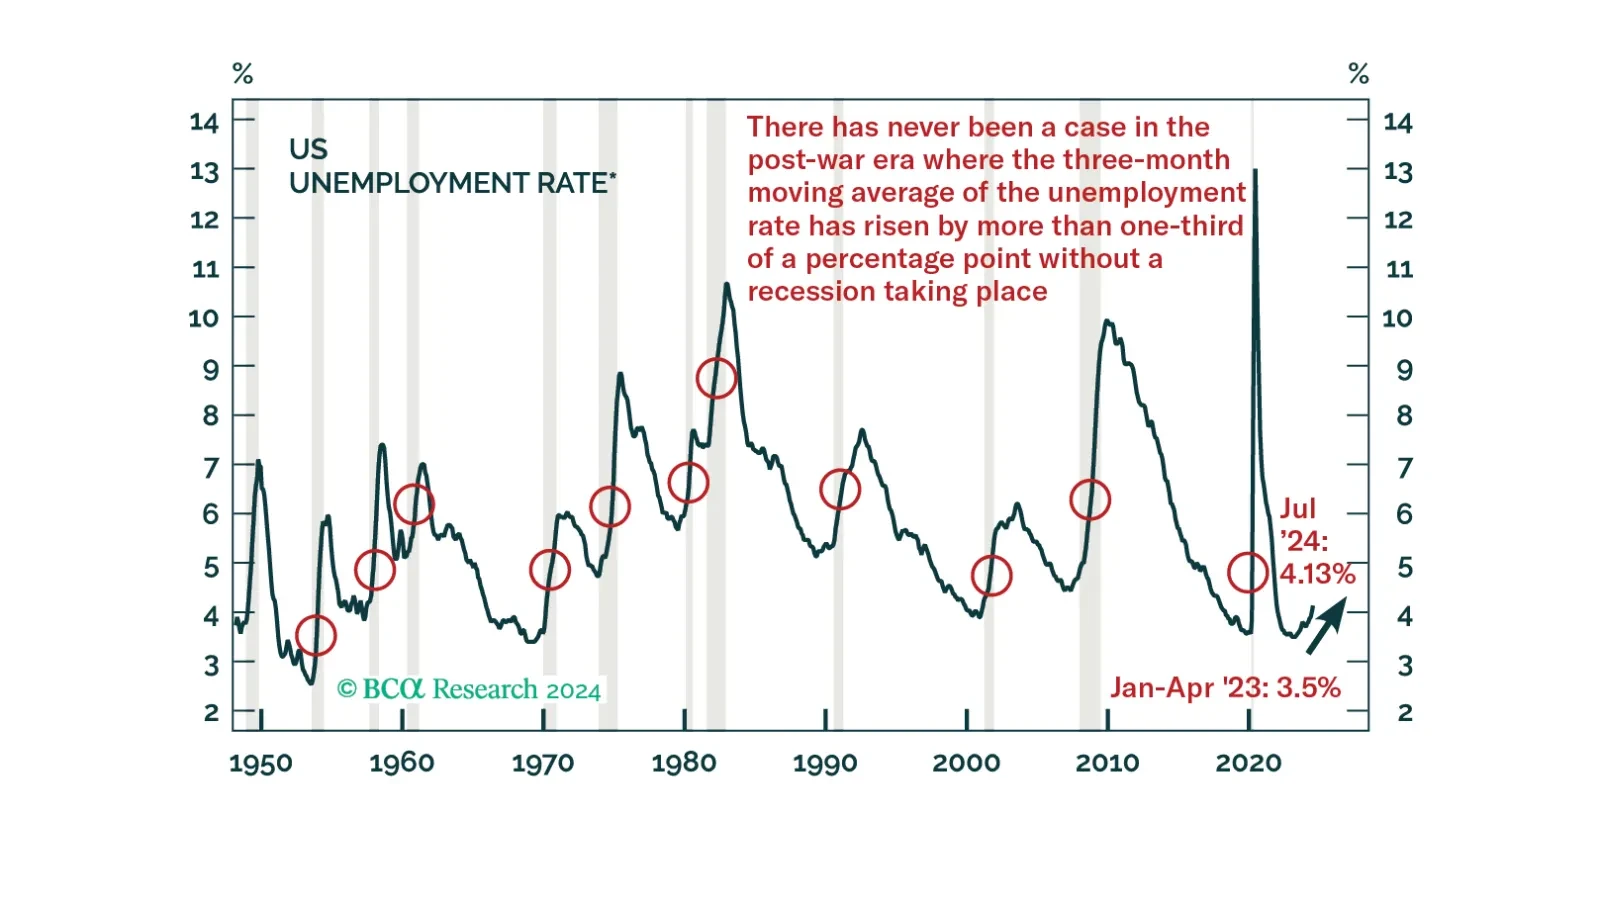
Our annual end-of-summer chartbook report traces the labor market deterioration that led us to downgrade equities at the beginning of August. It also highlights the soft-landing expectations that the credit and equity markets are discounting. We like the risk-reward profile of our newly defensive stance.
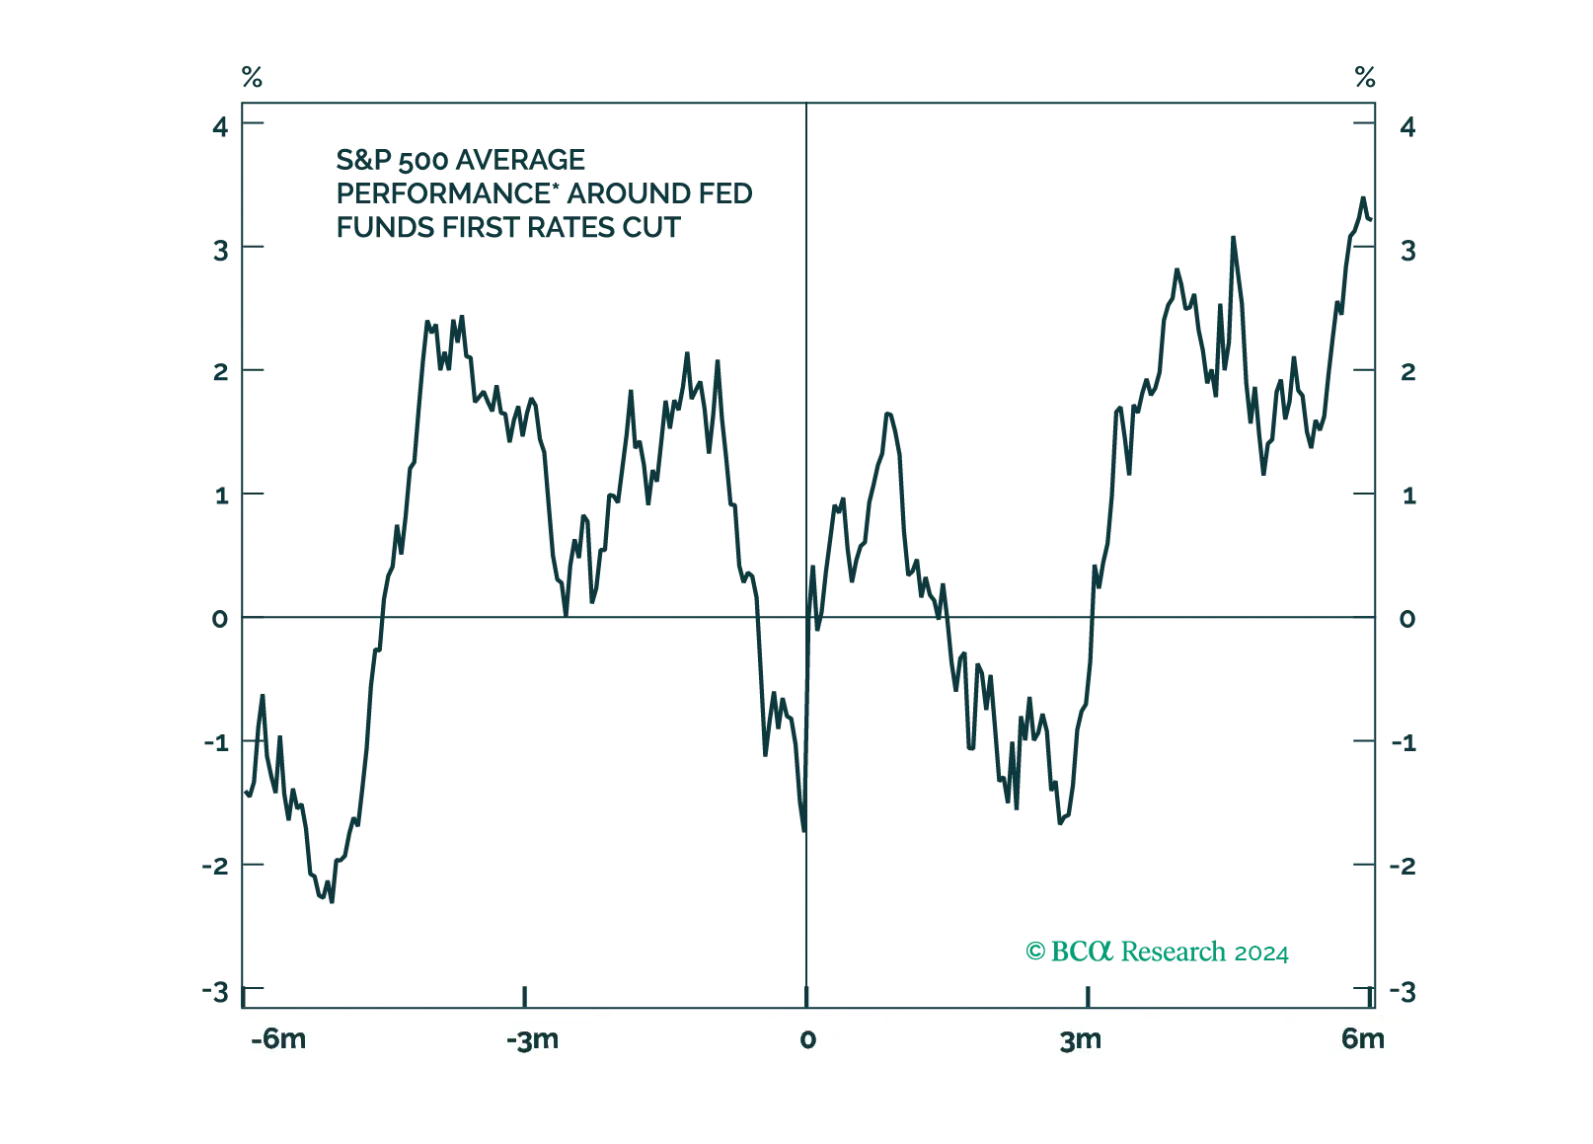
Even after the Fed cuts rates, policy will remain restrictive for some time. Moreover, in history, stocks have tended to fall around the first rate cut. We remain cautious on the outlook for the economy and risk assets.