Economía

Chinese industrial profits rose by 4.0% y/y in April, from a 3.5% y/y contraction in March. They grew by 4.3% in the first four months of the year, compared to the same period in 2023. In March, the central government pledged funds to incentivize businesses…
The greenback typically moves in the opposite direction of global growth. The US economy is indeed more highly geared towards services than manufacturing, compared with the rest of the world. Therefore, when global growth reaccelerates, capital typically…
The US manufacturing cycle has followed a surprisingly stable pattern for over seven decades. History suggests that this cycle tends to last for about 36 months, with a down leg spanning 18 months, followed by an up leg approximately spanning another 18…
According to BCA Research’s Global Investment Strategy service, there is only a narrow path to a soft landing. Our colleagues estimate a mere 20% chance that the US will avoid a recession before the end of 2025. The US unemployment rate is a highly…
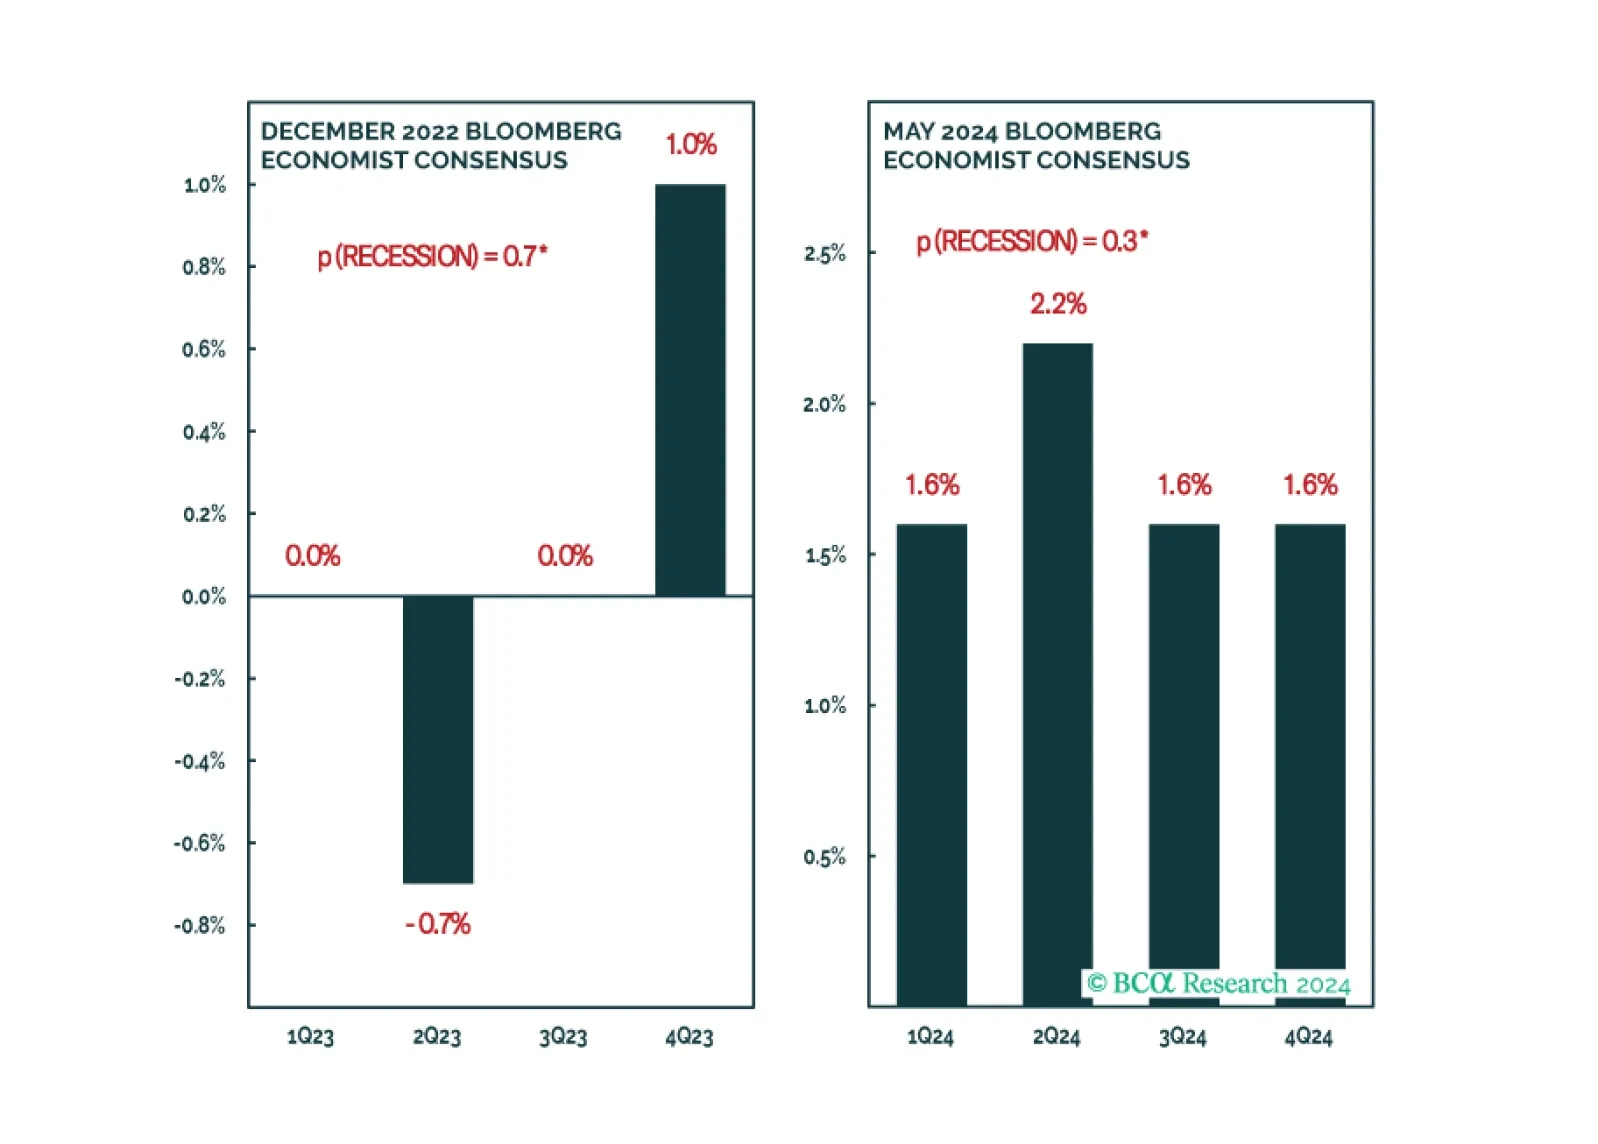
The signs of an approaching recession are starting to emerge. We will turn tactically defensive once they all fall into place.
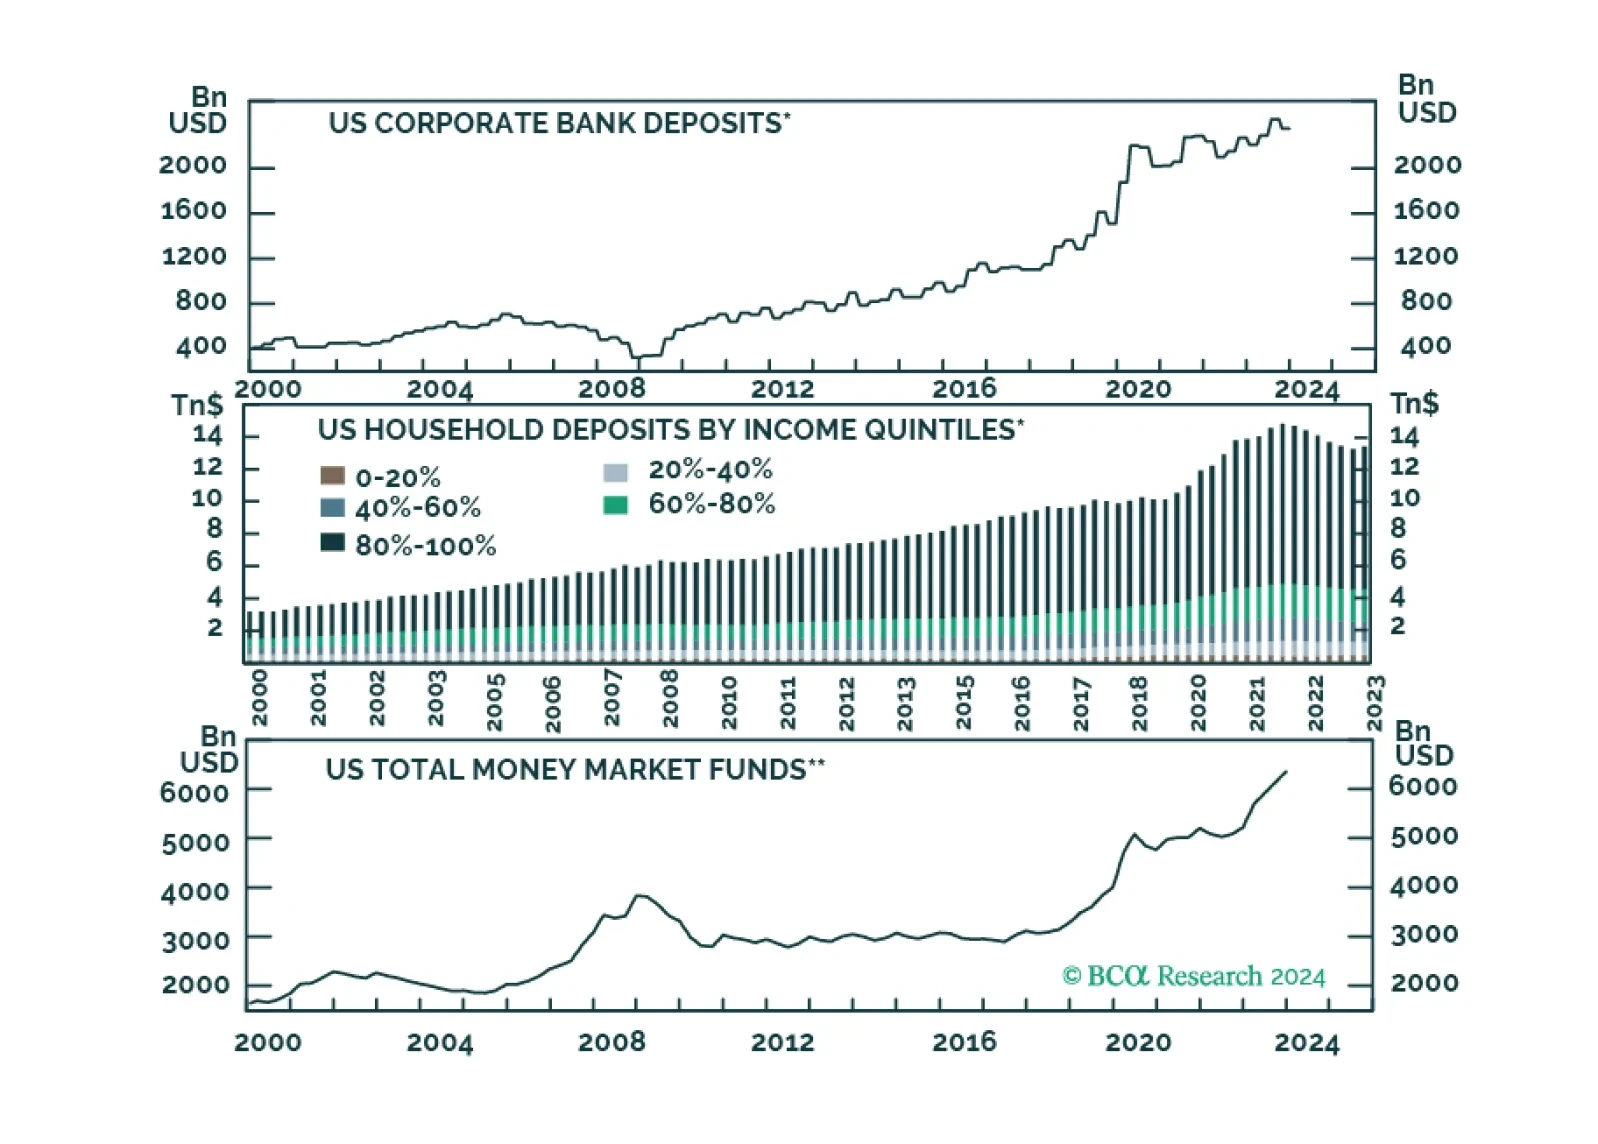
Si miramos la actividad económica, la política monetaria global parece restrictiva; sin embargo, el comportamiento de los mercados financieros cuenta otra historia. ¿Qué pasa?
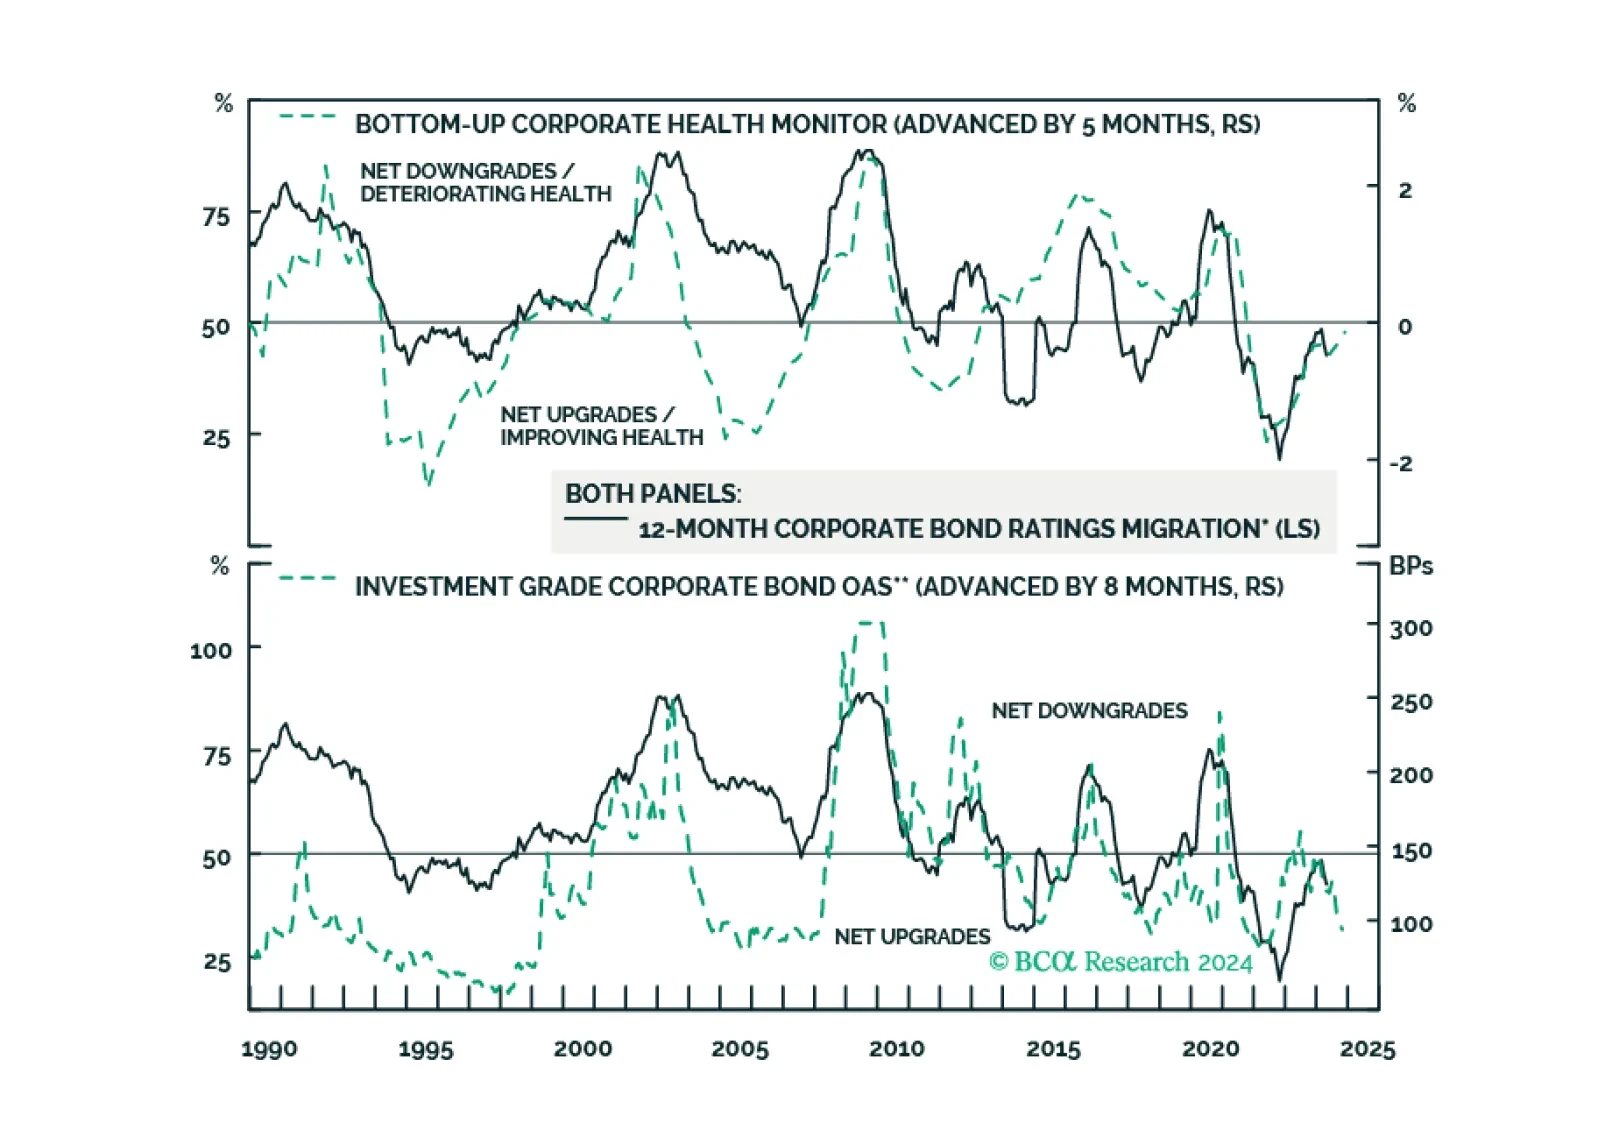
Nonfinancial corporate balance sheets are generally in good shape, but there are signs of deterioration at the bottom-end of the credit spectrum. We present evidence showing that credit deterioration at the bottom-end of the credit spectrum has a habit of migrating upwards.
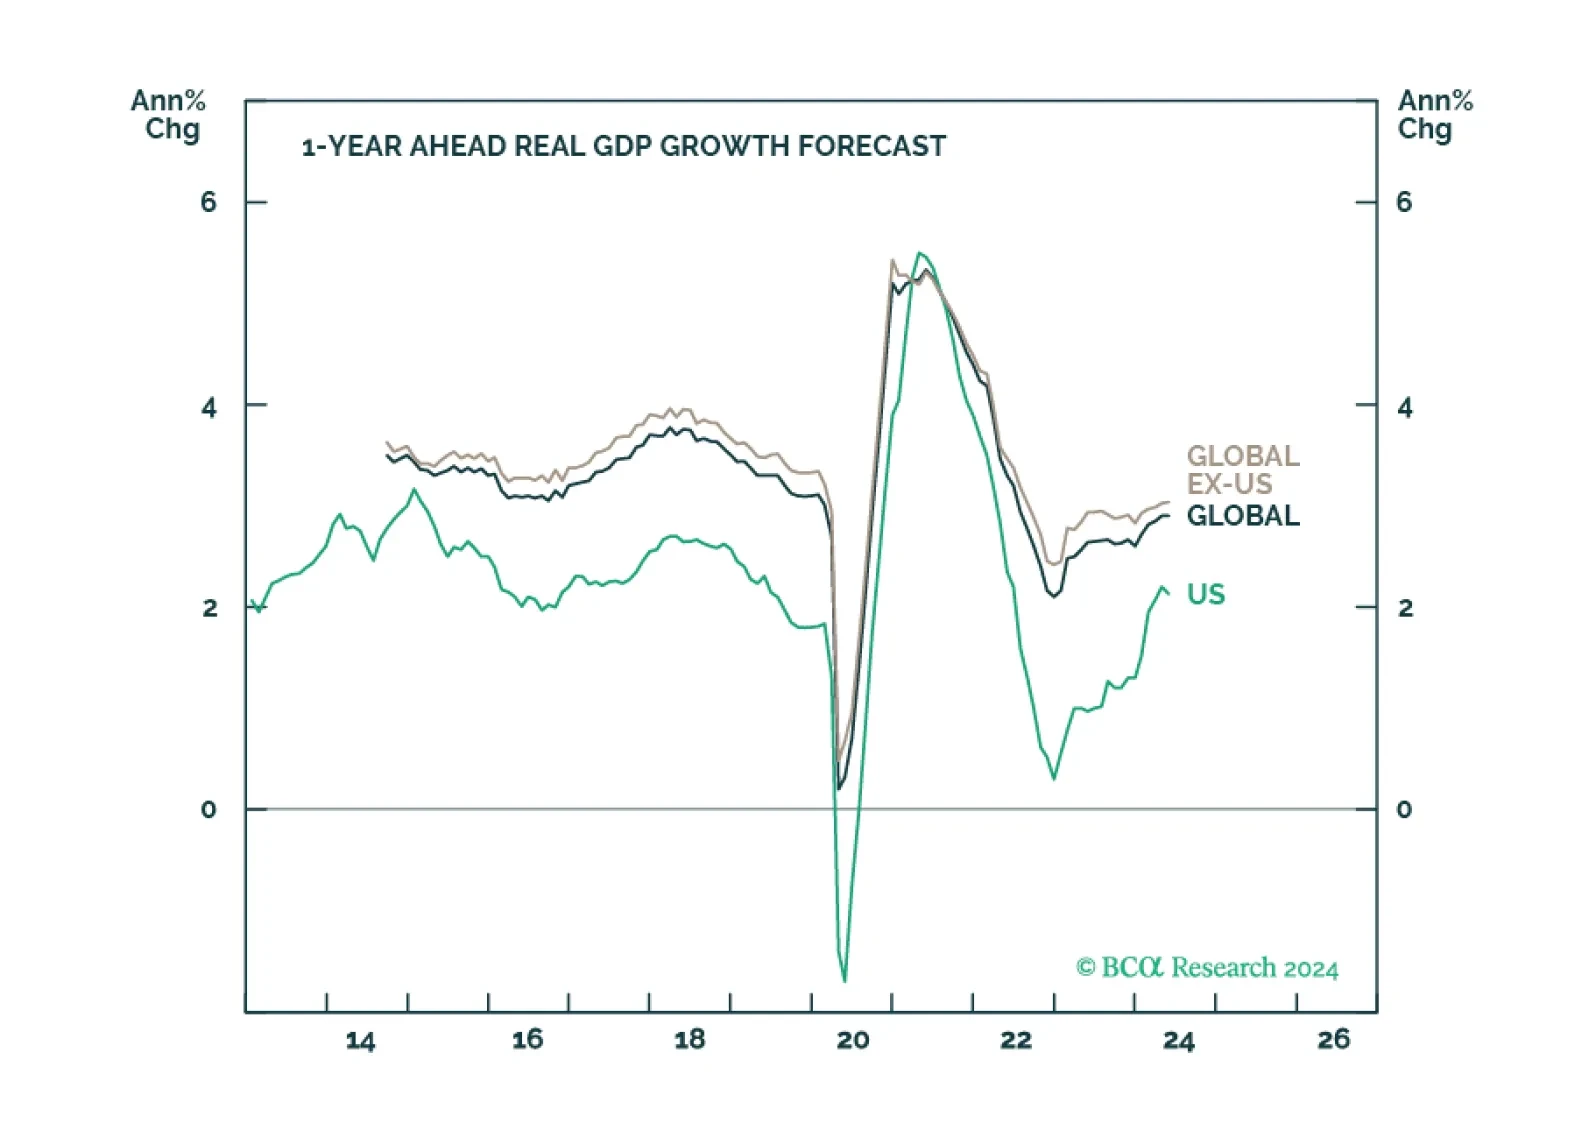
There is a path to a soft landing, but it is a narrow one. We estimate that there is only a 20% chance that the US will avoid a recession before the end of 2025. We are currently neutral on global equities, but expect to downgrade stocks to underweight during the summer.
Negotiated wages rose 4.7% y/y in Q1, from 4.5% y/y in Q4 in the Eurozone. Meanwhile, preliminary estimates for the Eurozone Composite PMI surprised to the upside in May. Although wage growth is the main driver of services inflation and Euro Area economic…
According to BCA Research’s Counterpoint service, the non-US developed economy is “demand-constrained” whereas the US economy is “supply-constrained”. This schism will continue but in reverse. The team has highlighted that following the surge in…