Ciclos Económicos

The preliminary Eurozone inflation release suggests that price pressures eased by less than anticipated in February. Headline CPI inflation slowed from 2.8% y/y to 2.6% y/y (slightly above expectations of 2.5% y/y. Similarly, although the core inflation gauge…
As we highlighted in a previous Insight, the breadth of the US equity rally has been relatively narrow, led by extremely strong gains among Big Tech stocks. Tech is still the best performing sector, with the S&P IT price index up 12% year-to-date on top of a…
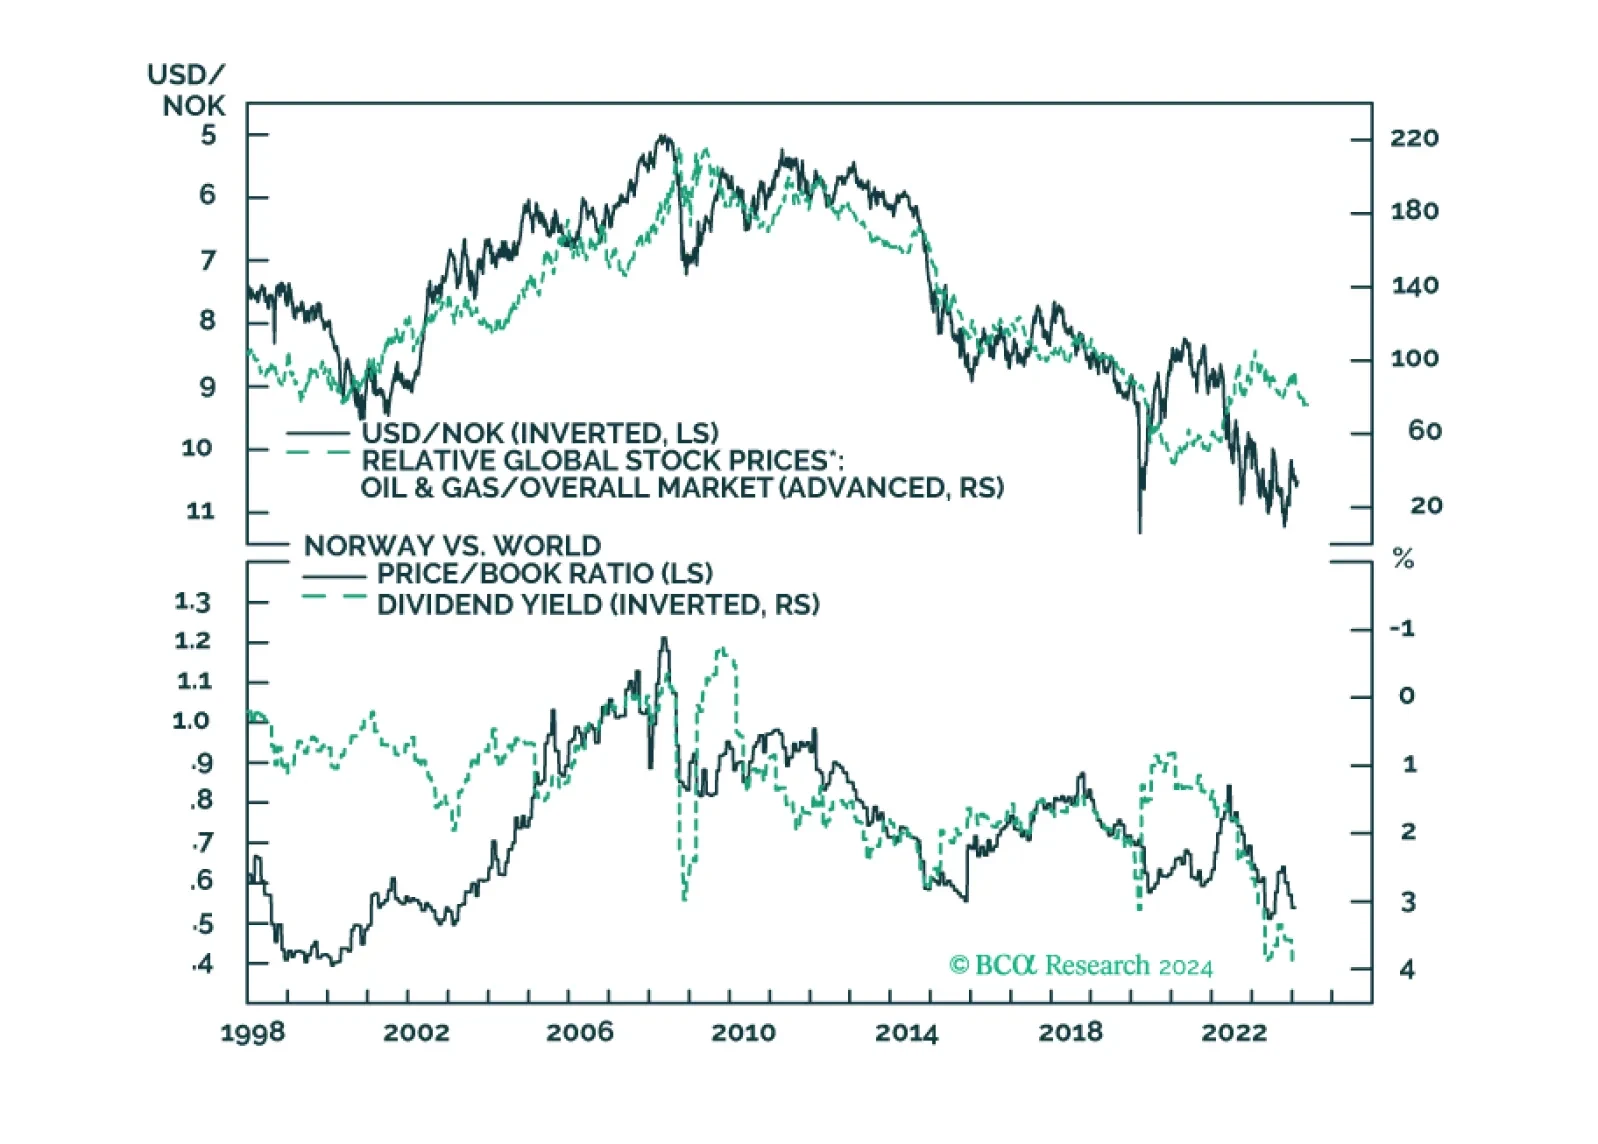
In this insight, we provide an update on the Norwegian krone, with attractive trade ideas over a long-term horizon. Shorter-term, our neutral-to-positive view on the dollar keeps us on the sidelines for USD/NOK.
Aside from the 1.0% m/m jump in personal income – which beat expectations of a 0.4% m/m rise – the US January Personal Income and Outlays report was broadly in line with consensus estimates. Nominal personal spending growth decelerated from 0.7% m/m to 0.2%…
In a recent report, our US Bond strategists argued that while the year-to-date increase in yields has made Treasures more attractive, conditions are not yet in place to extend duration. Instead, they expect that there will be a better opportunity later this…
BCA Research’s Global Investment Strategy service’s US equity model, Stock Coach, has become more bullish on the near-term prospects for the S&P 500. The model’s short-term (1-to-3 month) equity score improved over the course of February, finishing the month…
US GDP growth for Q4 was revised lower from 3.3% to 3.2% annualized, driven by a downward revision to private inventory investments (now detracting 0.27 points from a previous 0.07 contribution to GDP). However, consumer spending grew at a faster pace than…
New Zealand government bonds rallied, and the NZD was the worst performing major currency on Wednesday following the Reserve Bank of New Zealand’s (RBNZ) policy announcement. Although the central bank’s decision to keep its official cash rate (OCR) unchanged…
On the surface, the latest Taiwanese export orders release delivered a positive signal on the global trade cycle. The 1.9% y/y expansion in January marks a significant improvement from the 16.0% contraction in December. Moreover, a 28% surge in orders from…
Earlier this year it looked like the spread between the rate of 10-year and 2-year Treasury notes was heading toward positive territory. Yet the 2s/10s spread peaked at -16 bps on January 16 and the inversion has been deepening since. This peak in the yield…