Brazil
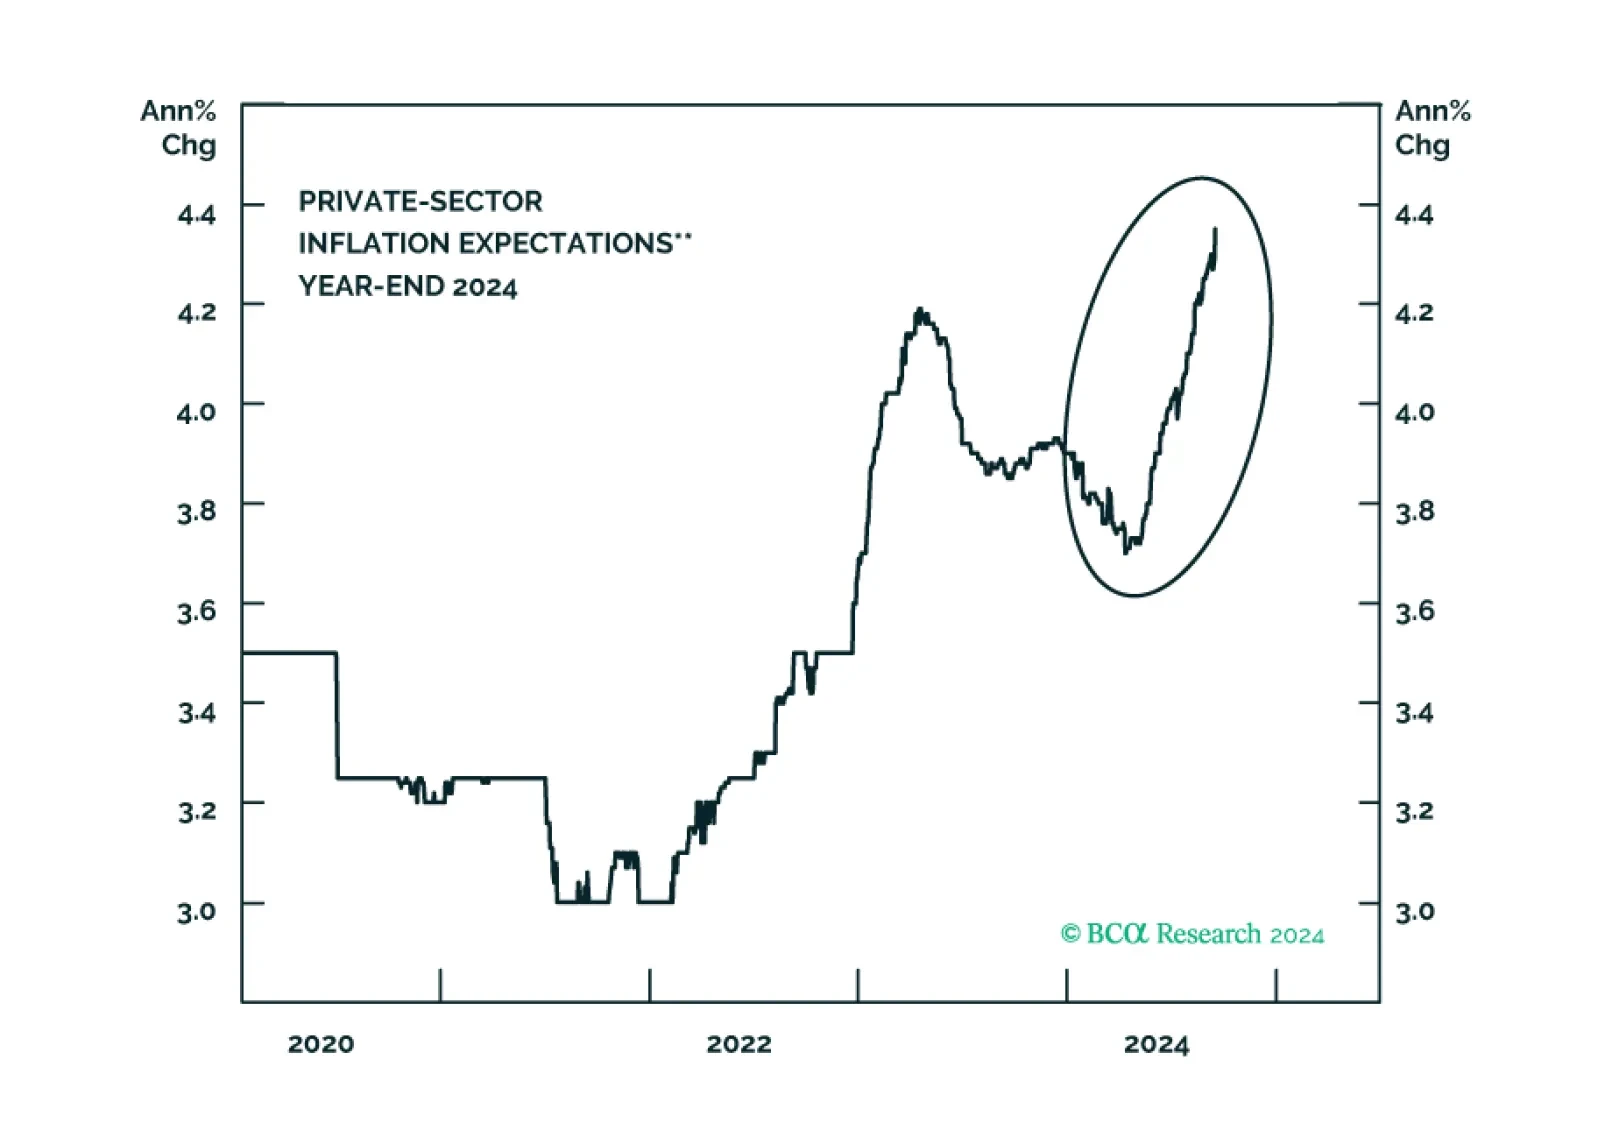
The Central Bank of Brazil (BCB) raised interest rates last week. Is this the commencement of a major tightening cycle that will persist well into next year? Despite this move, we maintain that the BCB will cut interest rates substantially next year. We believe the Lula-nominated board members are playing the long game: voting to hike rates until year-end to establish credibility with financial markets in order to get a pass at easing monetary policy in early 2025.

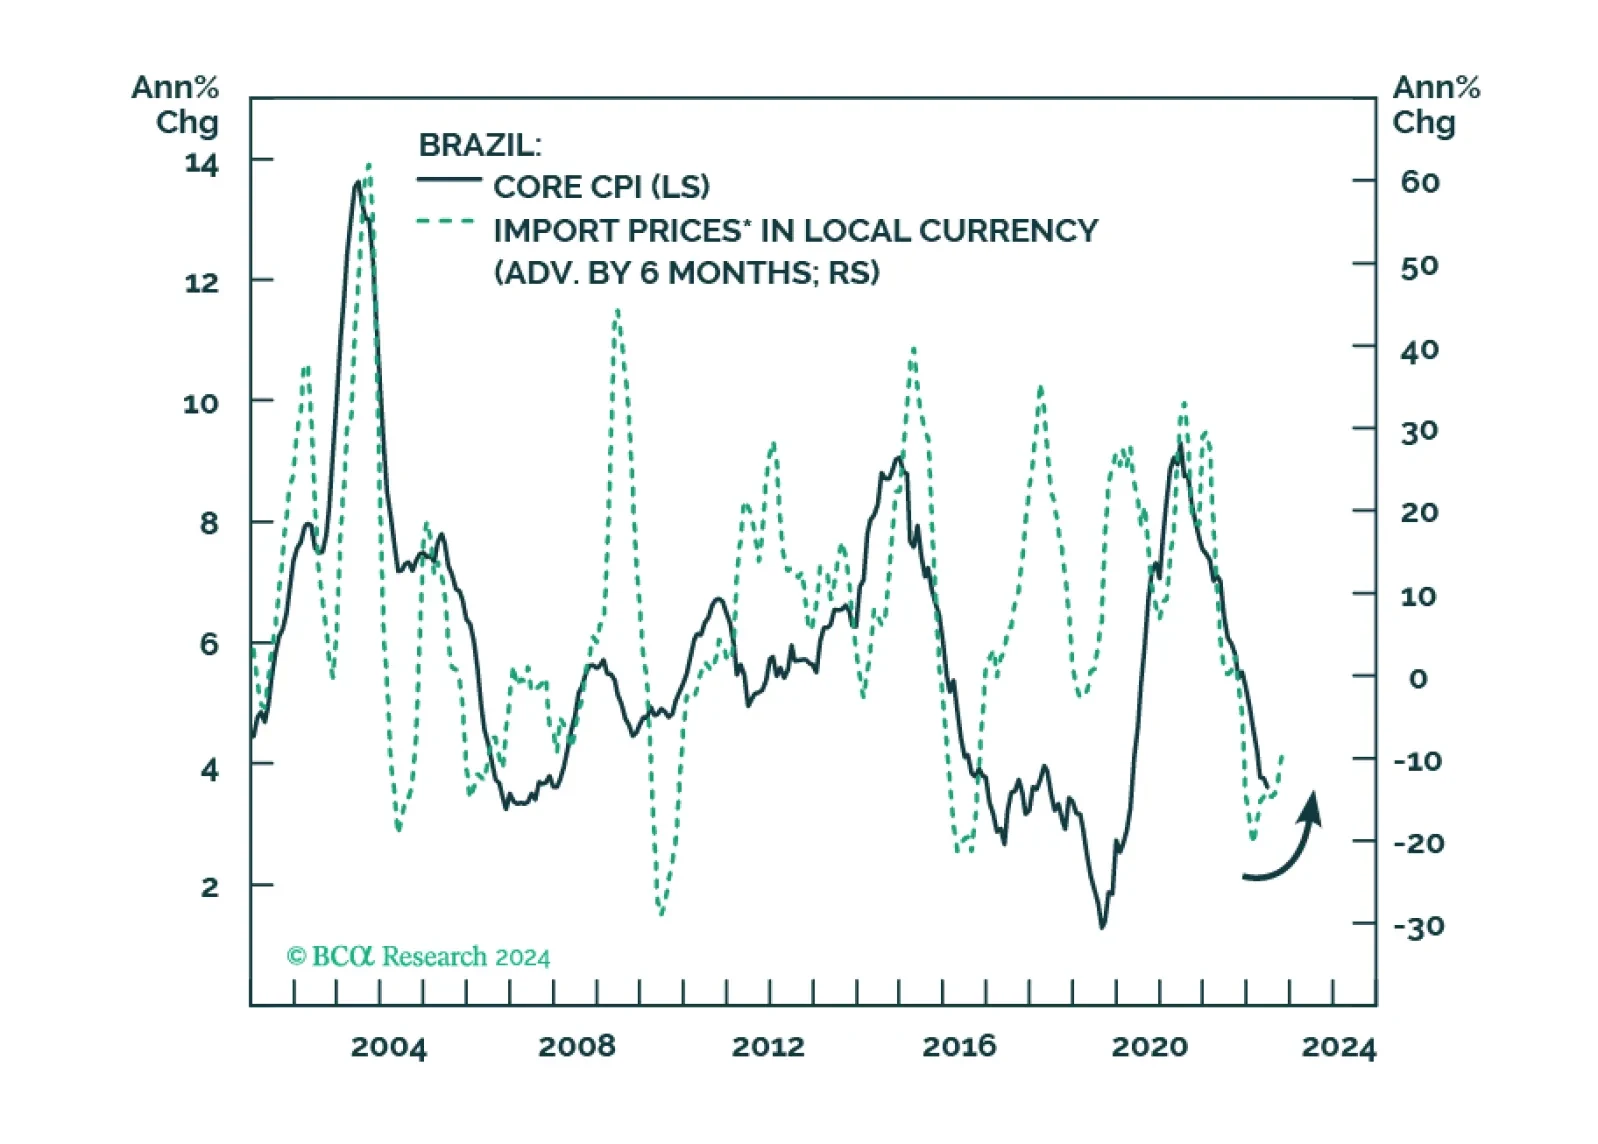
Brazil’s two macro demons – a rising public debt-to-GDP ratio and inflation – have resurfaced and will worsen over the coming months. Yet, President Lula will pay lip service to fiscal concerns without enacting meaningful cutbacks. In addition, a politicized COPOM will cut rates aggressively next year and fall behind the inflation curve. All in all, the selloff in Brazilian markets still has legs.
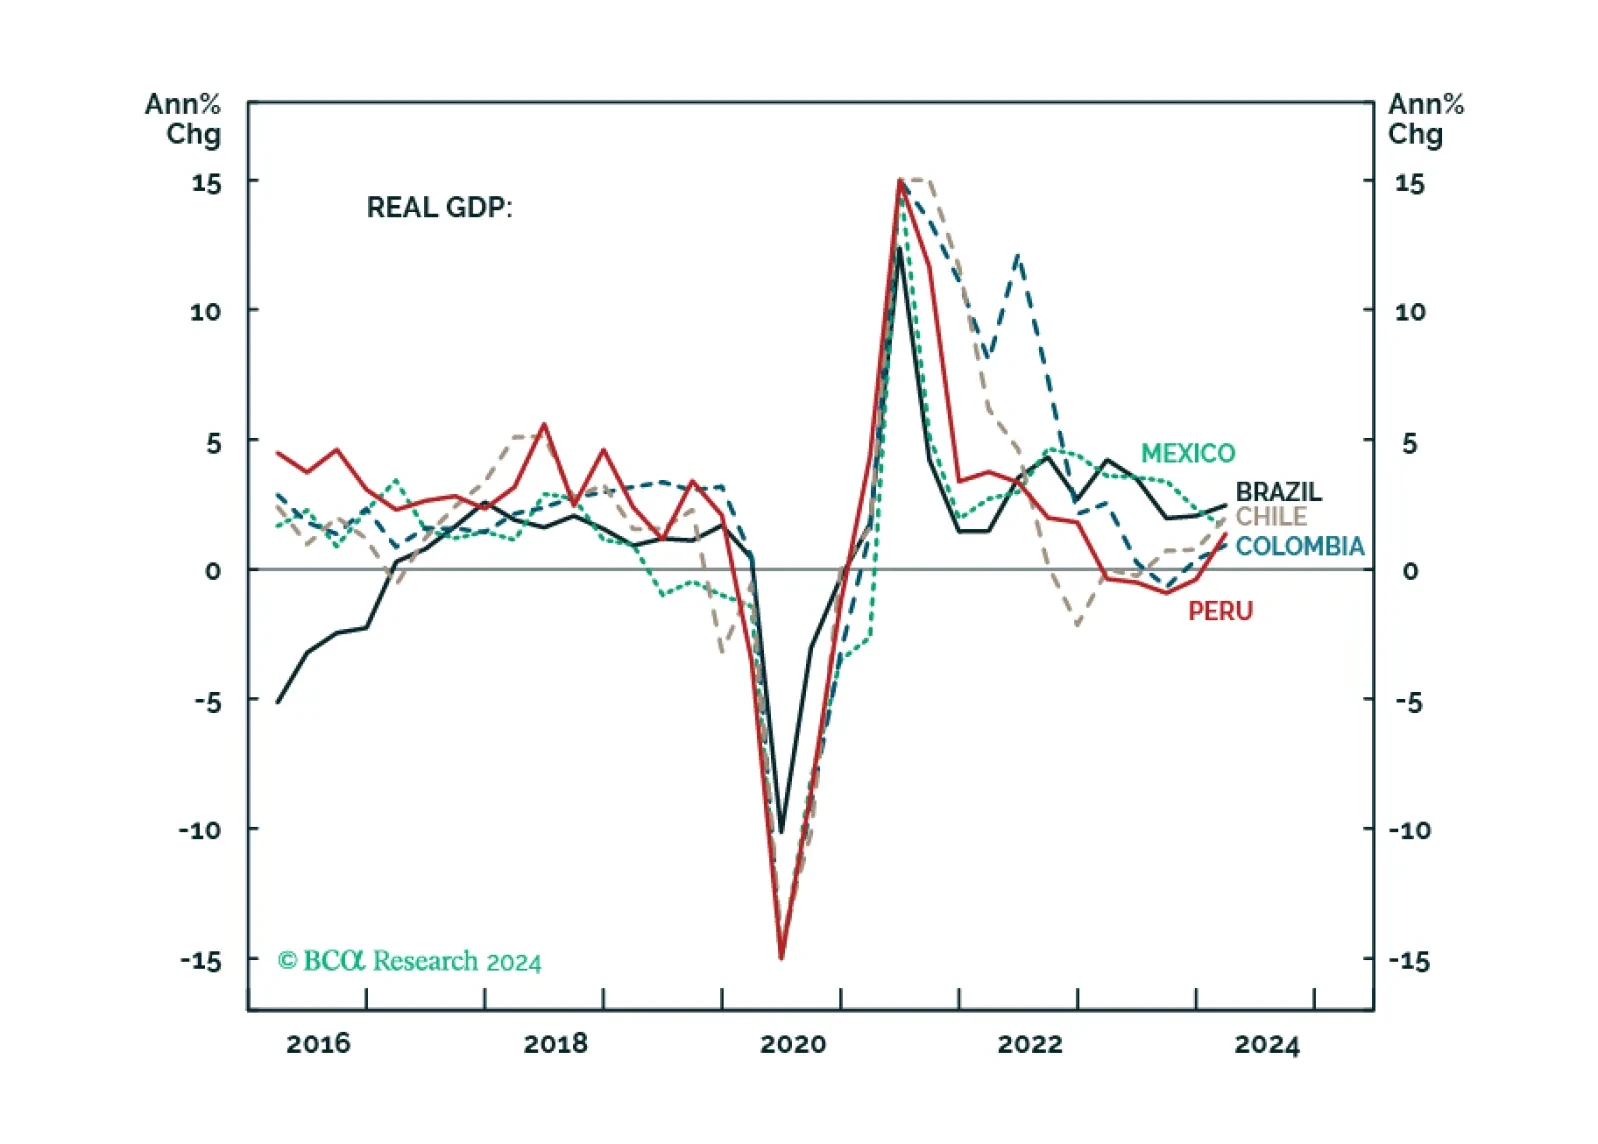
Non-trivial macro divergences have emerged between mainstream LATAM economies. This report compares and ranks Brazil, Mexico, Colombia, Chile, and Peru based on their business cycle outlook, macro policy stance, external accounts, and structural fundamentals. All in all, LATAM risk assets will fall in absolute terms given a strengthening US dollar and a global risk-off move in the coming months. Within LATAM, we favor Mexico, Chile and Peru, are neutral on Brazil, and bearish on Colombia.
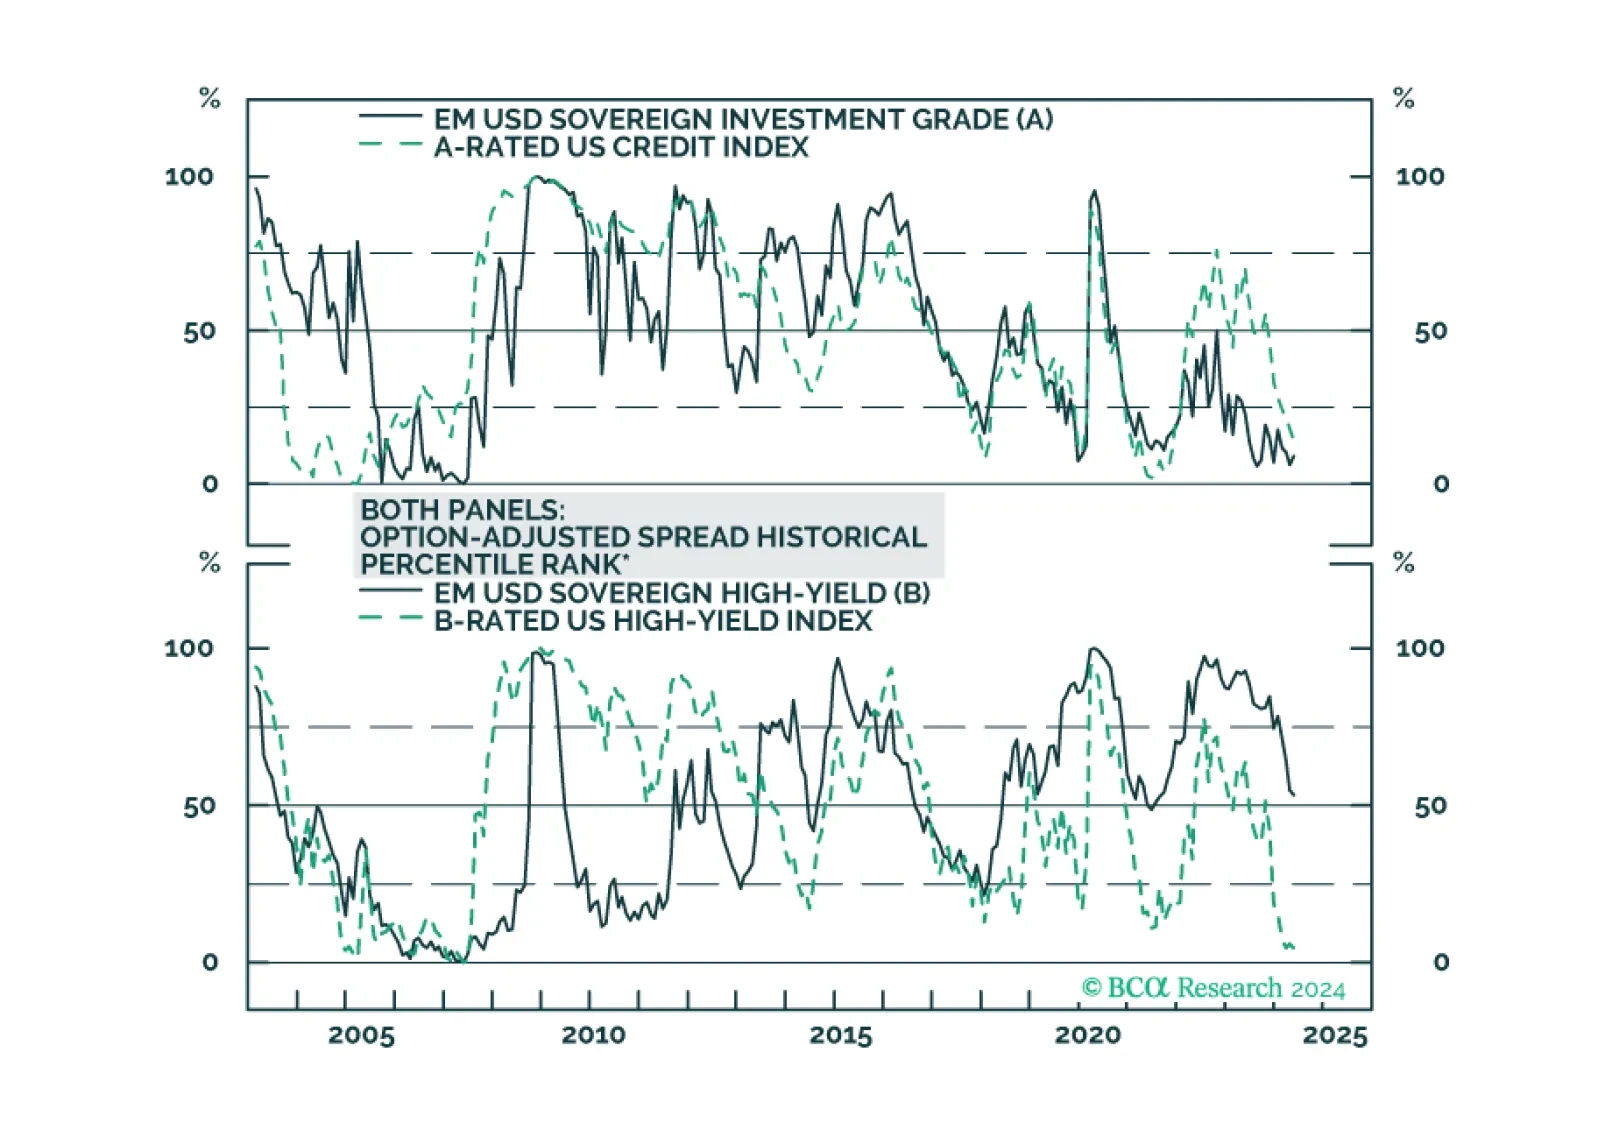
We dig into the USD-denominated Emerging Market Sovereign Index to see which credit tiers and countries offer value relative to US Credit.
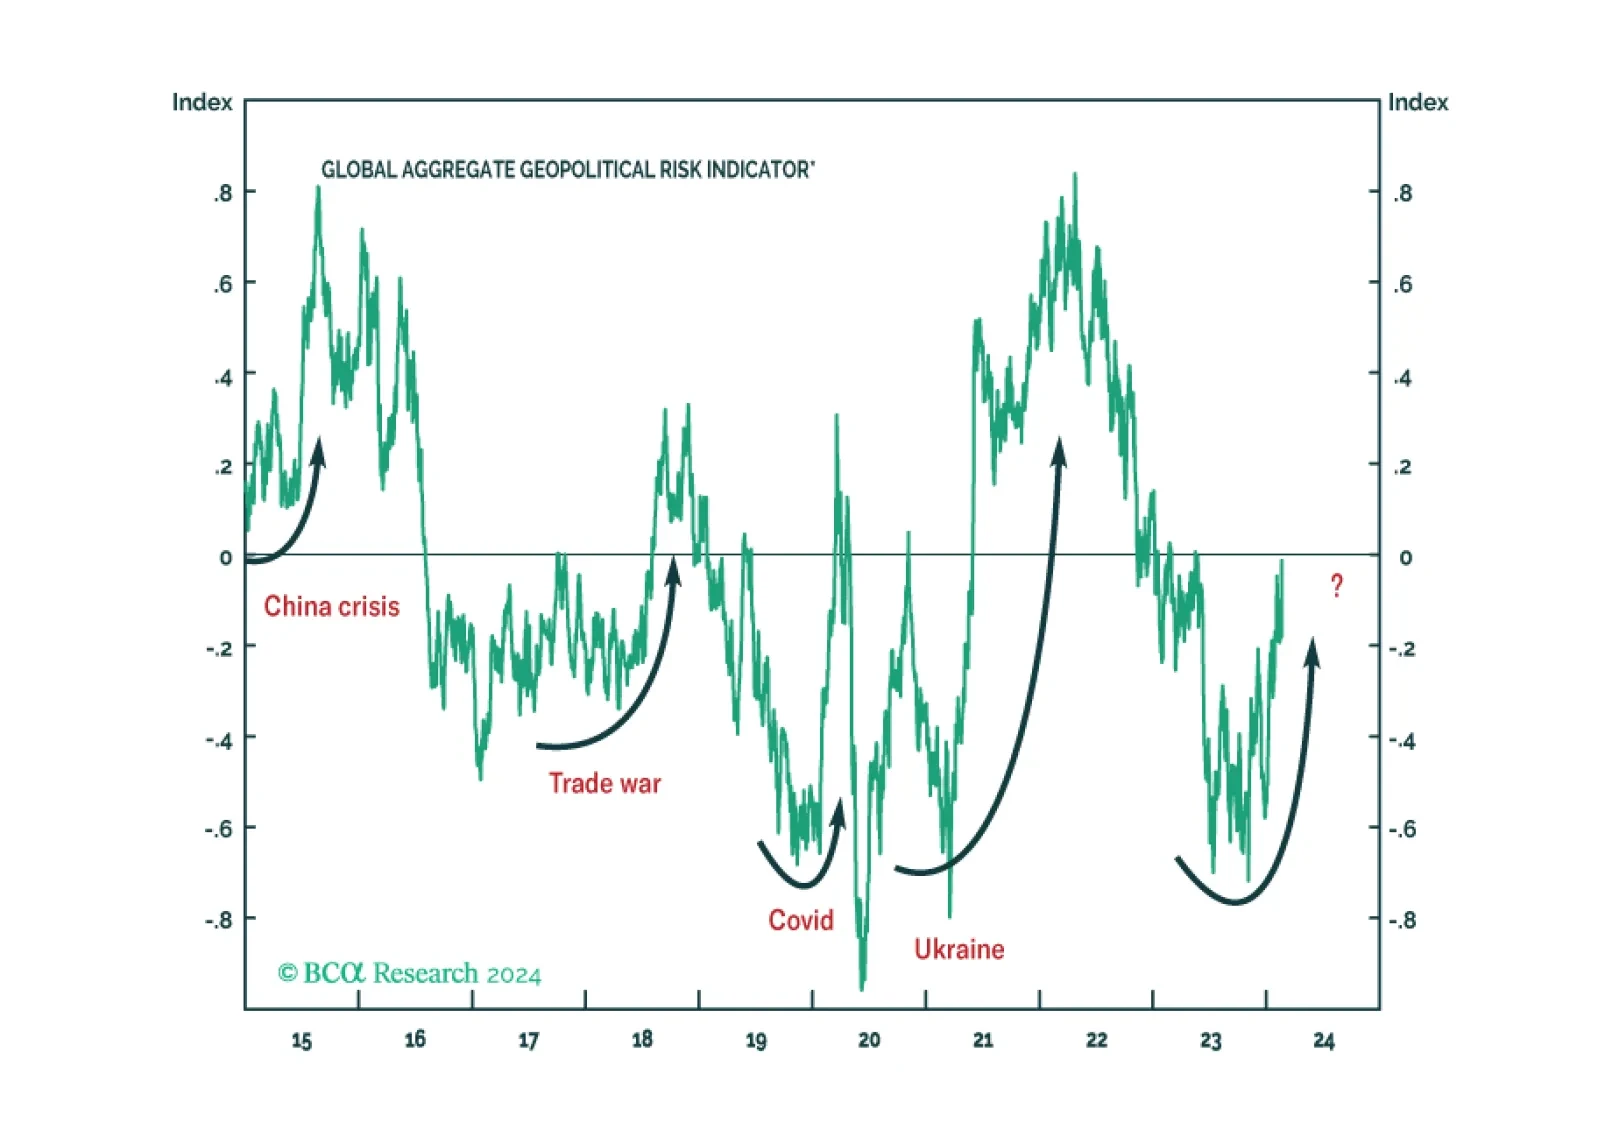
While 2024 will see various election risks, global geopolitical uncertainty is driven by the US election and its struggle with Russia, China, and Iran. The stock market can manage local domestic political risk. But it will correct upon a major outbreak of geopolitical uncertainty.
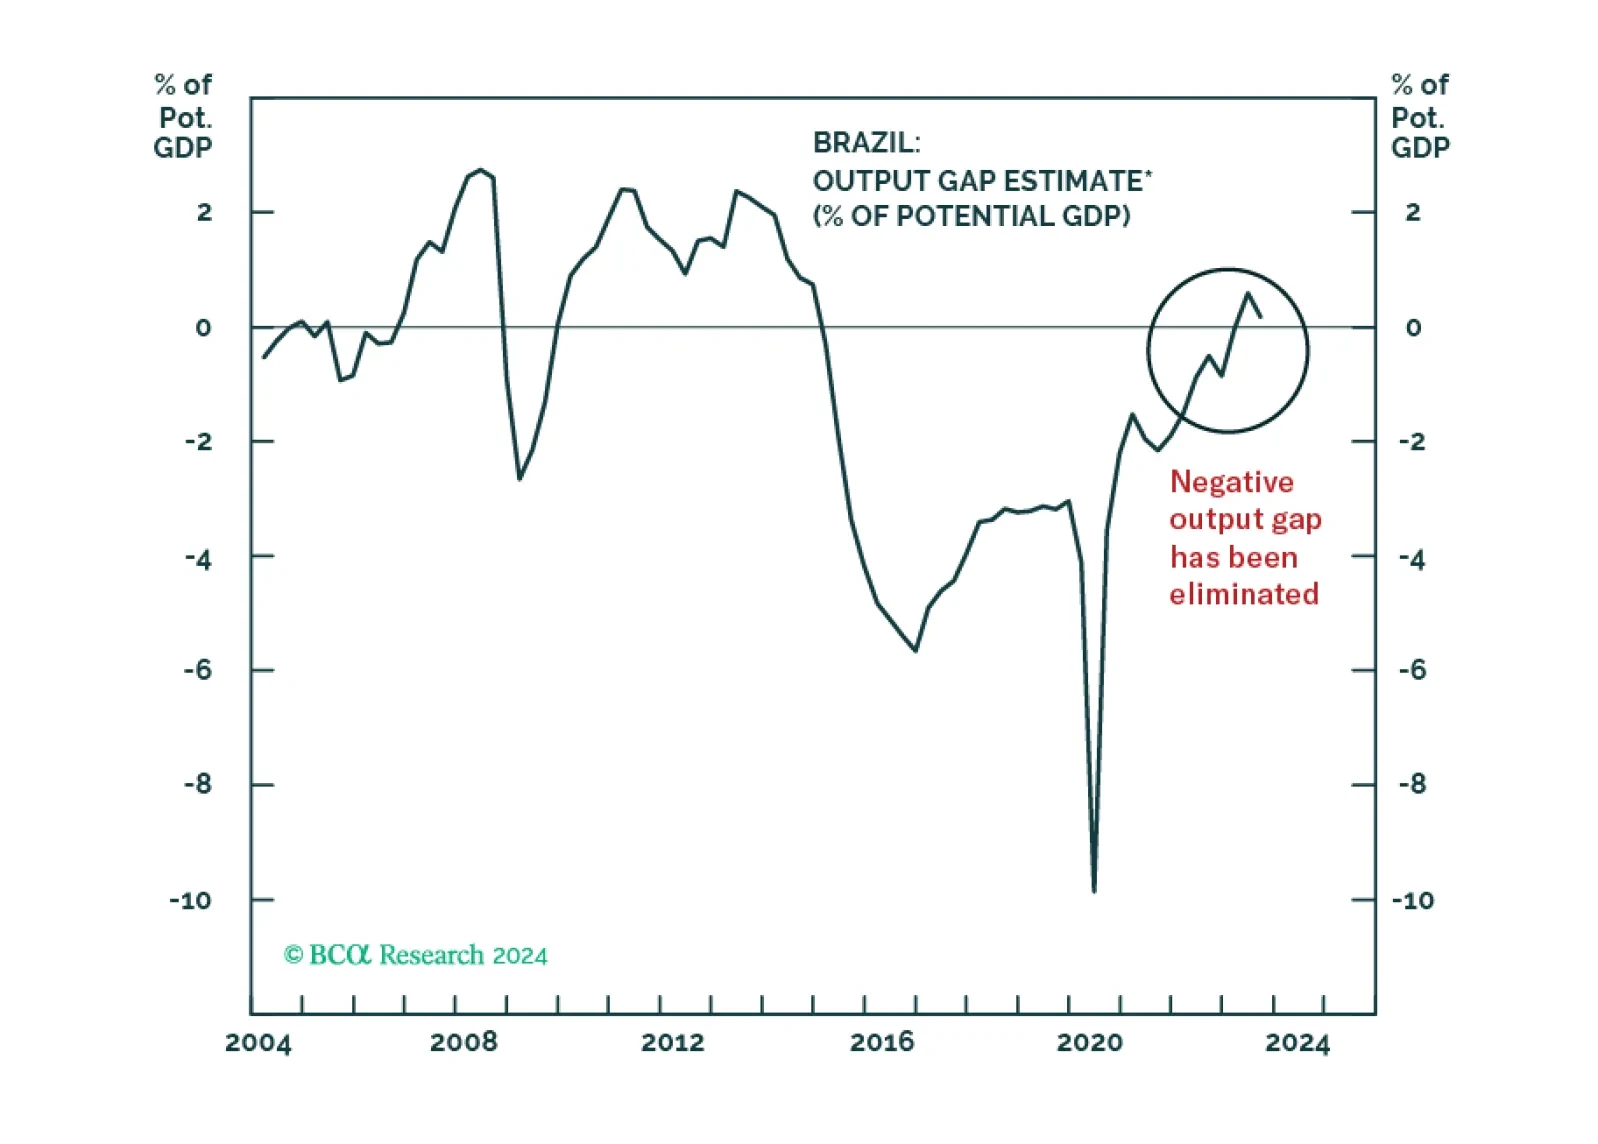
The Brazilian government and the central bank will be prioritizing growth over curbing the fiscal deficit and inflation. The outcome of an easy policy mix is that growth and inflation will be higher relative to market expectations, and real interest rates will drop considerably. We recommend that investors go long mid- and small-cap stocks on a pullback and inflation-linked bonds. However, foreign investors should hedge the currency risk.